
 Ultra-Large Volume Wearable Injectors Market | 2026-2036
Ultra-Large Volume Wearable Injectors Market Size, Share, and Industry Trends Forecast 2026-2036
Ultra-Large Volume Wearable Injectors Market Analytics
Glass is decoupling from ultra-large volume wearable injector housings as polymer-based drug-contact surfaces reduce weight and breakage risk. Becton, Dickinson and Company leverages its integrated manufacturing scale to control supply chains for high-volume disposable components. Ypsomed Holding AG anchors European production capacity for electromechanical patch platforms. Enable Injections, Inc. differentiates through its patient-administered bolus technology designed for biologics exceeding 10 mL volumes.
Ultra-large volume wearable injectors are ambulatory drug delivery systems designed to administer therapeutic doses typically ranging from 5 mL to 50 mL subcutaneously over extended periods, incorporating pressure sensors, flow restrictors, and prefilled reservoir technologies to ensure controlled release without clinical supervision. Their primary purpose centers on enabling self-administration of viscous biologics for chronic conditions that previously required intravenous infusion. Insulin delivery devices lead product type adoption given the established reimbursement framework and patient familiarity with wearable pumps. Electromechanical systems dominate technology deployment, though smart sensors represent the fastest-growing segment as real-time dose verification and connectivity integration become standard expectations. Chronic disease management commands the largest application share, while home care settings absorb disproportionate volume growth as payors shift reimbursement toward lower-acuity sites.
FDA combination product regulations, EU MDR requirements for active implantable devices, and ISO 11608 standardization for needle-based injection systems collectively determine market access timelines and clinical evidence burdens for manufacturers. These frameworks elevate barrier-to-entry costs while simultaneously validating device reliability for risk-averse biopharma partners seeking delivery platform collaborations. Stakeholders must monitor how evolving pharmacovigilance obligations for connected devices reshape post-market surveillance investments and partnership structures.
Market Dynamics
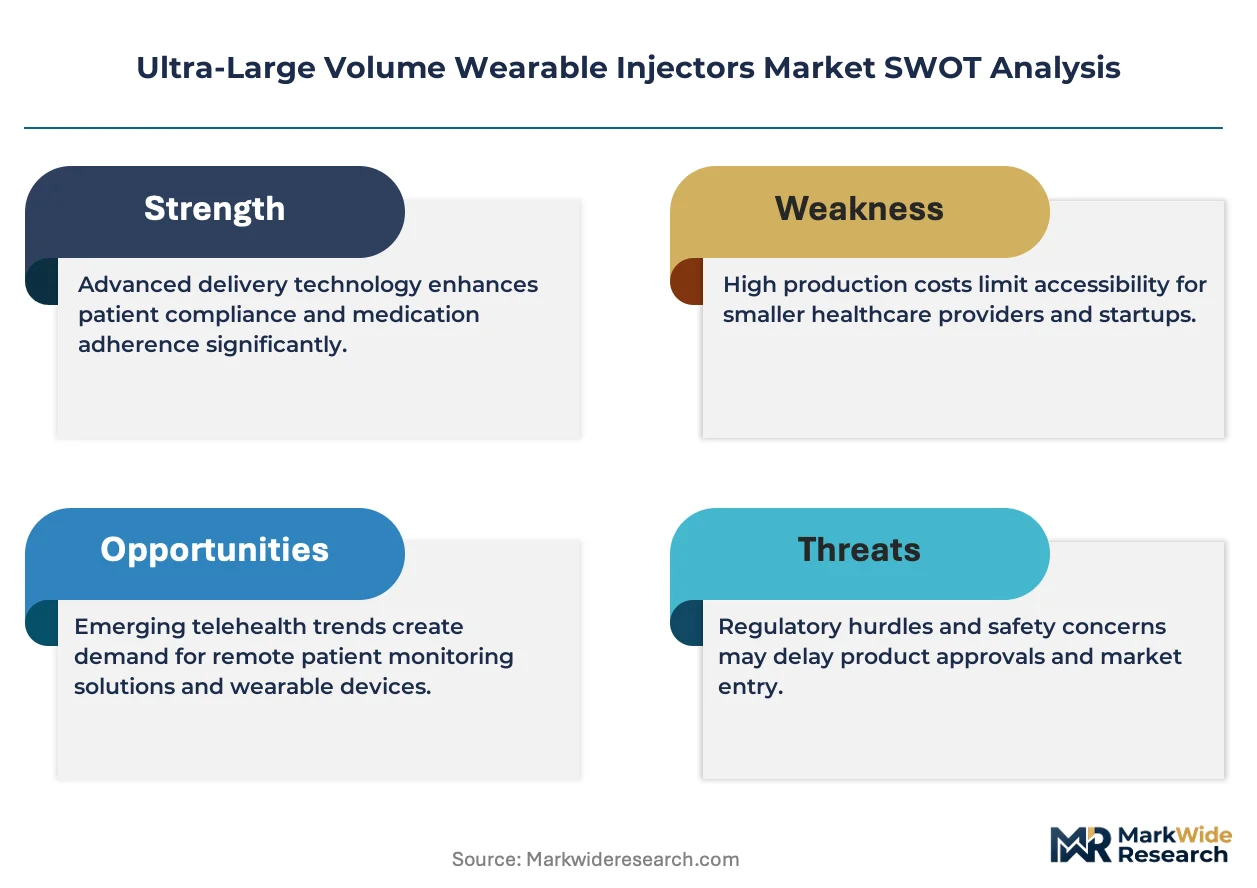
Biopharma outsourcing of delivery platform development to specialized device manufacturers is consolidating procurement decisions around integrated electromechanical systems rather than standalone components. This structural shift elevates vendor selection criteria toward full-stack capabilities spanning reservoir engineering, sensor integration, and regulatory dossier preparation.
Growth Catalysts
- EU MDR device classification harmonization:Streamlined conformity assessment pathways for active implantable devices accelerate partnership timelines between drug sponsors and platform developers.
- Home care reimbursement expansion:CMS and commercial payors in the United States now cover ambulatory infusion alternatives, shifting site-of-care economics toward patient-administered delivery.
- Prefilled reservoir standardization:ISO 11608-1 needle-based injection system specifications enable interchangeability across biologics portfolios, reducing validation overhead for multi-product platforms.
Market Restraints
- Specialized polymer supply concentration:Cyclic olefin polymer and high-performance thermoplastic elastomer feedstocks concentrate among three Japanese and German chemical suppliers, creating input cost volatility.
- FDA combination product review timelines:Center for Drug Evaluation and Research and Center for Devices and Radiological Health jurisdictional determinations extend pre-market approval durations for novel platform submissions.
- Intravenous infusion substitution persistence:Hospital-based infusion centers retain clinical preference for certain monoclonal antibody therapies where subcutaneous bioequivalence remains unestablished.
Strategic Opportunities
- Brazil chronic disease burden:ANVISA's accelerated pathway for innovative medical devices targets diabetes and autoimmune condition management, opening Latin America's largest patient population to wearable delivery.
- Connected device pharmacovigilance mandates:FDA draft guidance on real-world evidence generation from digital health technologies creates revenue streams for data-analytics-integrated platform offerings.
- Pharmacy channel direct distribution:Specialty pharmacy networks in the United States are building cold-chain capabilities for large-volume biologics, bypassing traditional wholesale intermediaries.
Industry Challenges
- Electromechanical systems engineering talent scarcity:Firmware development for pressure-sensor feedback loops and Bluetooth Low Energy connectivity requires specialized skill sets concentrated among medical device hubs in Massachusetts and Switzerland.
- Biocompatibility testing backlog:ISO 10993 cytotoxicity and sensitization study queues at contract research organizations extend preclinical timelines for new drug-contact materials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultra-Large Volume Wearable Injectors Market |
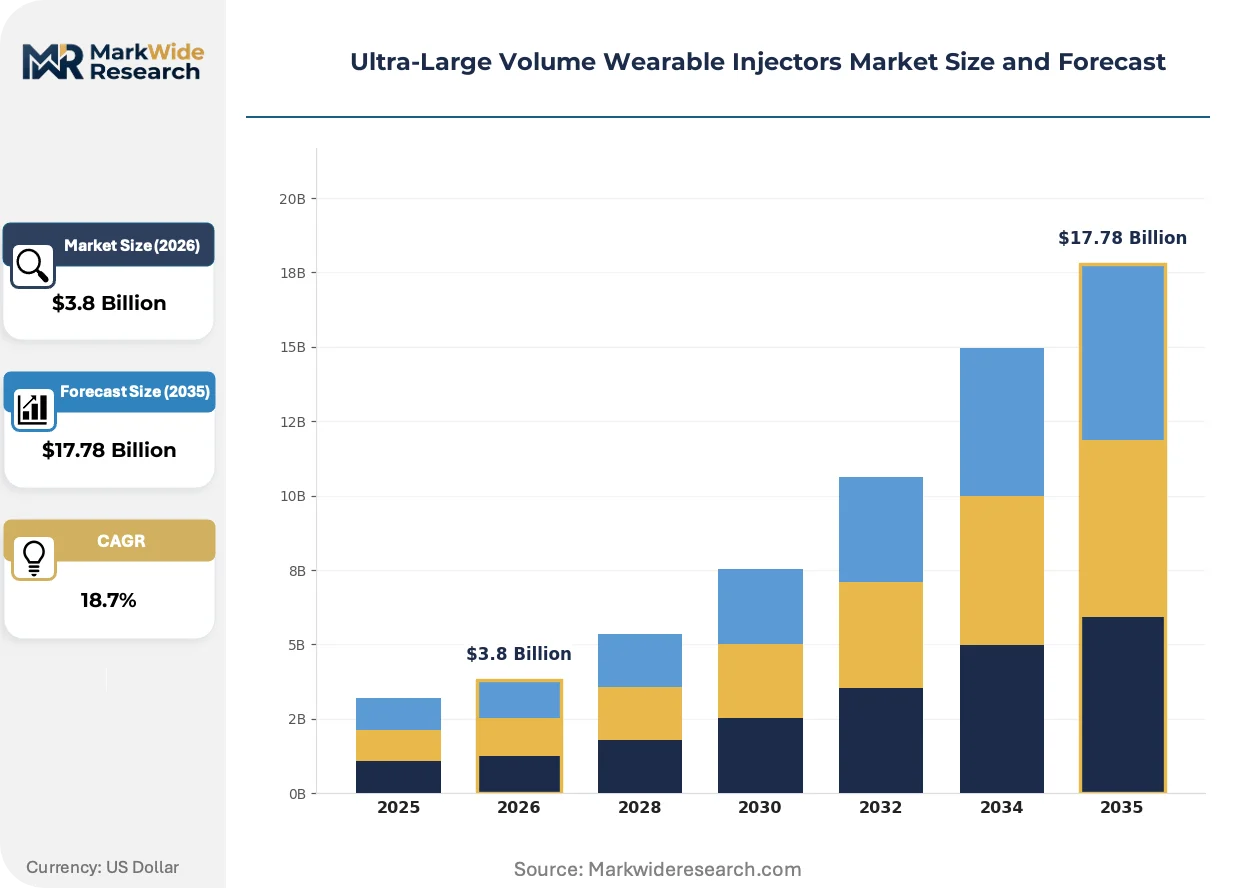
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.78 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin Delivery Devices, Hormone Replacement Systems, Vaccination Solutions, Pain Management Devices Technology: Electromechanical Systems, Wireless Communication, Smart Sensors, Biometric Monitoring End User: Patients, Healthcare Providers, Home Care Settings, Pharmacies Application: Chronic Disease Management, Preventive Care, Acute Therapy, Emergency Treatment |
| Companies Covered | Becton, Dickinson and Company, Ypsomed Holding AG, Insulet Corporation, Enable Injections, Inc., Gerresheimer AG (Sensile Medical AG), Amgen Inc., West Pharmaceutical Services, Inc., Tandem Diabetes Care, Inc., Medtronic plc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultra-Large Volume Wearable Injectors Market Evolving Landscape
Sensor-enabled dose verification and connectivity modules are becoming baseline expectations rather than premium differentiators, compressing development cycles for electromechanical patch platforms. Device architecture is converging around standardized pressure-sensor arrays and cloud-integrated compliance monitoring.
Silicone-free fluid path materials are absorbing market preference as biopharma sponsors seek to eliminate immunogenicity risks associated with traditional elastomer stoppers. Chronic disease management programs in Germany and the Netherlands have adopted these platforms for first-line biologic initiation. The shift is absorbing development resources previously allocated to incremental mechanical reliability improvements.
FDA's evolving guidance on human factors engineering for combination products mandates iterative usability testing with patient cohorts representing varying dexterity levels and visual acuity. Device developers must now embed ethnographic research earlier in design control processes. Insulin delivery platforms face the steepest compliance burden given their broad patient population exposure.
Specialty pharmacy networks are consolidating purchasing influence through centralized formulary committees that evaluate total cost of care rather than device acquisition price alone. This behavioral shift privileges platforms with integrated adherence monitoring and automated refill triggers. The United States exhibits the most pronounced concentration of this procurement model evolution.
Ultra-Large Volume Wearable Injectors Market Segmentation
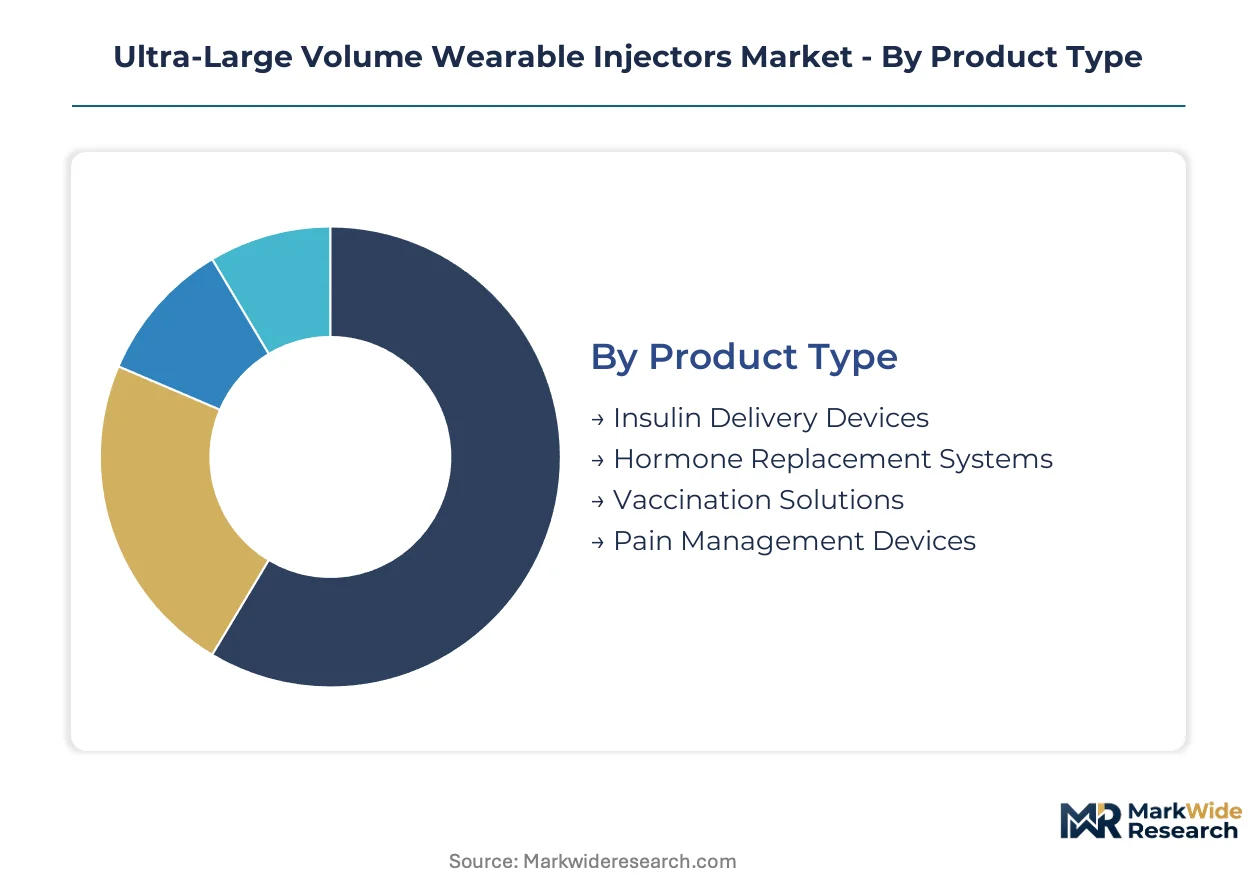
Segmentation in ultra-large volume wearable injectors reveals distinct procurement patterns across therapeutic categories and care settings. Device specifications, connectivity requirements, and reimbursement pathways diverge sharply between diabetes management and acute intervention applications.
Product Type:
Reimbursement tier determines platform selection more than device mechanics, with payor formularies privileging established therapeutic categories over novel indications.
- Insulin Delivery Devices:These systems incorporate continuous glucose monitoring integration and algorithm-driven basal-bolus adjustment. United States Medicare Part D coverage and commercial payor preferred drug lists concentrate procurement volume here, though prior authorization requirements create access friction for next-generation patch pumps.
- Hormone Replacement Systems:Designed for testosterone and growth hormone administration with extended-release reservoir engineering. Germany's statutory health insurance funds and Dutch chronic disease management programs are absorbing disproportionate volume as endocrinology practices shift from intramuscular injection protocols.
- Vaccination Solutions:Prefilled electromechanical platforms for mass immunization campaigns.
- Pain Management Devices:Local anesthetic and opioid antagonist delivery systems for post-surgical ambulatory care.
Insulin delivery devices lead on scale; hormone replacement systems lead on momentum.
Technology:
Platform architecture decisions hinge on whether connectivity serves compliance monitoring or enables therapeutic algorithm adjustment.
- Electromechanical Systems:Pressure-sensor arrays and micro-pump mechanisms constitute the foundational technology layer. Massachusetts device clusters and Swiss precision manufacturing regions concentrate engineering talent for these systems, though firmware validation timelines extend development cycles.
- Smart Sensors:Real-time dose verification, reservoir level detection, and injection site monitoring modules. United States FDA combination product guidance and EU MDR active implantable device classifications are accelerating adoption as standard features rather than premium upgrades.
- Wireless Communication:Bluetooth Low Energy and cellular telemetry for remote monitoring.
- Biometric Monitoring:Integration of physiological parameter sensing with drug delivery.
Electromechanical systems dominate installed base; smart sensors climb the fastest.
End User:
Site-of-care economics are redistributing purchasing authority away from hospital procurement toward patient-directed acquisition channels.
- Home Care Settings:Patient-administered platforms with simplified human factors interfaces and disposable component design. United States CMS home health benefit expansions and commercial payor site-of-care shifting policies are channeling volume here, though training burden and adherence verification remain unresolved.
- Patients:Direct-to-consumer channels for cash-pay wellness and fertility applications.
- Healthcare Providers:Clinic-based initiation and monitoring platforms.
- Pharmacies:Specialty pharmacy networks with cold-chain distribution capabilities.
Home care settings absorb the steepest expansion trajectory; healthcare providers retain the largest current volume.
Application:
Clinical evidence requirements and pharmacovigilance obligations vary dramatically between maintenance therapy and acute intervention contexts.
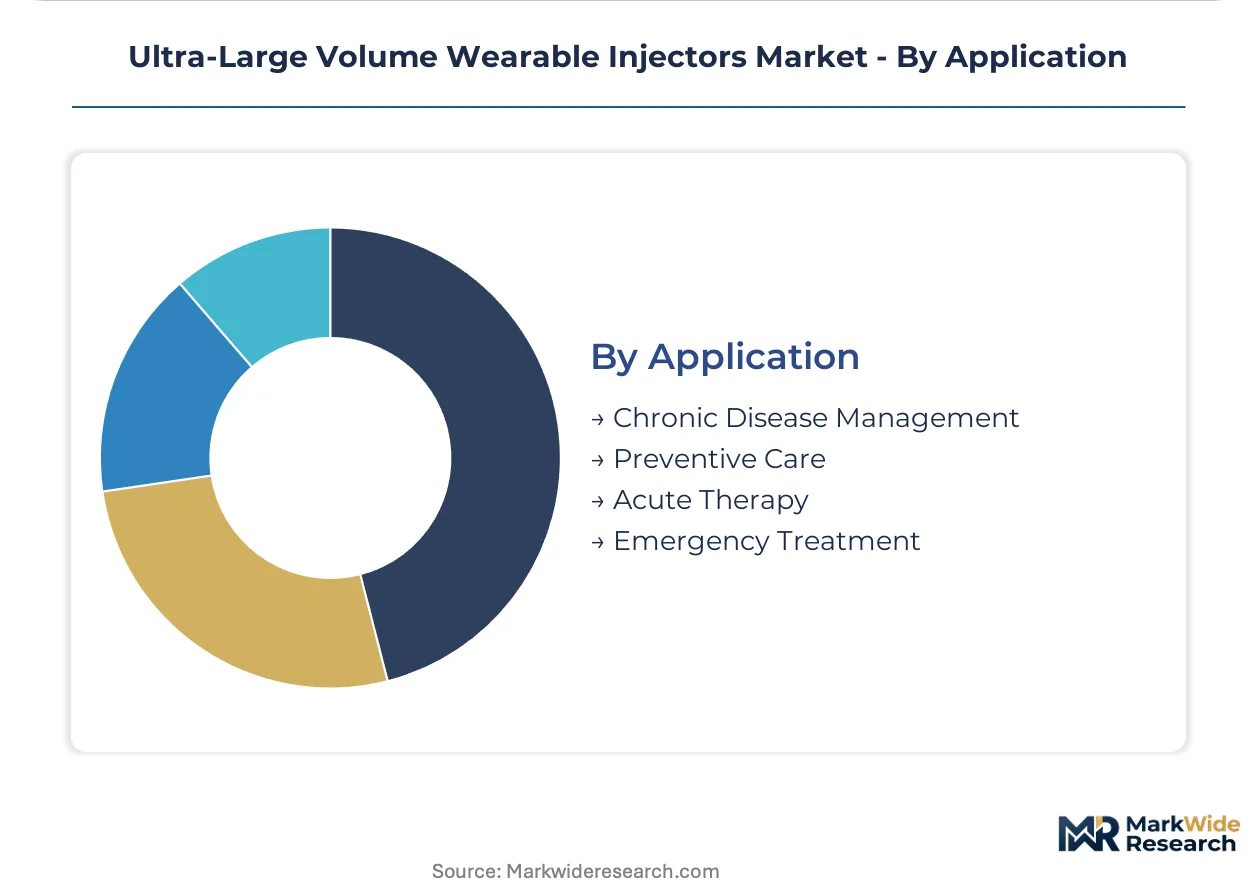
- Chronic Disease Management:Long-term biologic administration for diabetes, autoimmune conditions, and hormonal deficiencies. United States commercial payor step therapy protocols and Germany's disease management program structures concentrate demand here, with real-world evidence generation becoming a competitive requirement.
- Preventive Care:Prophylactic vaccination and pre-exposure prophylaxis delivery.
- Acute Therapy:Time-critical medication administration in non-clinical settings.
- Emergency Treatment:Rescue medications for anaphylaxis and opioid overdose reversal.
Chronic disease management commands the largest revenue pool; preventive care offers the most open competitive terrain.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Massachusetts medical device clusters anchor worldwide development capacity for electromechanical patch platforms, drawing specialized firmware engineering talent from Swiss precision manufacturing regions and German polymer processing centers.
United States
CMS home health benefit expansions and commercial payor site-of-care shifting policies channel procurement volume toward patient-administered delivery systems. FDA combination product regulations govern pre-market approval pathways for novel platform submissions. Greater Boston and San Diego biotech corridors concentrate device developers pursuing integrated sensor arrays.
Germany
Statutory health insurance funds and disease management program structures absorb disproportionate volume for hormone replacement and chronic biologic administration. EU MDR active implantable device classifications streamline conformity assessment for electromechanical systems. Baden-Württemberg and North Rhine-Westphalia host precision manufacturing suppliers serving reservoir engineering requirements.
Switzerland
Swissmedic regulatory frameworks and ISO 11608 standardization leadership validate device reliability for risk-averse biopharma partnerships. Zug and Basel-Land cantons concentrate electromechanical systems engineering talent for pressure-sensor feedback development. Swiss precision manufacturing regions export components to United States and German device integrators.
Japan
PMDA accelerated review pathways for innovative medical devices target diabetes management applications. METI industrial policy supports domestic production capacity for high-performance thermoplastic elastomer feedstocks. Osaka-Kobe manufacturing belt concentrates polymer processing capabilities for drug-contact surface materials.
Brazil
ANVISA accelerated pathway for innovative medical devices opens Latin America's largest patient population to wearable delivery for chronic conditions. National pharmaceutical regulator frameworks align with FDA combination product precedents for platform registration. São Paulo state absorbs distribution infrastructure investment from multinational device sponsors.
Ultra-Large Volume Wearable Injectors Market Competitive Landscape
Global majors compete with regional champions across regulatory dossier preparation and integrated manufacturing scale. The vendor base organizes around three tiers: diversified medical technology conglomerates controlling supply chains for high-volume disposable components; mid-cap electromechanical specialists anchoring European production capacity; and emerging platform developers differentiating through patient-administered bolus technology. Consolidation pressures favor full-stack capabilities spanning reservoir engineering, sensor integration, and pharmacovigilance data analytics.
Within the diversified conglomerate tier, Becton, Dickinson and Company and Medtronic plc exemplify integrated manufacturing scale advantages. Among European electromechanical specialists, Ypsomed Holding AG occupies a position reflecting Swiss precision manufacturing heritage. Enable Injections, Inc. represents the emerging platform developer archetype focused on large-volume biologic delivery. These three anchors illustrate competitive positioning across procurement consolidation trends favoring end-to-end platform partnerships over component sourcing.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Ypsomed Holding AG |
| Insulet Corporation |
| Enable Injections, Inc. |
| Gerresheimer AG (Sensile Medical AG) |
| Amgen Inc. |
| West Pharmaceutical Services, Inc. |
| Tandem Diabetes Care, Inc. |
| Medtronic plc. |
| Others |
Value Network & Pricing Analysis
Specialty pharmacy formulary consolidation in the United States is forcing device manufacturers toward integrated sensor platforms with automated adherence monitoring, compressing margins on standalone mechanical systems while rewarding connectivity-enabled premium tiers. This procurement shift feeds back into polymer selection decisions, with cyclic olefin polymer and high-performance thermoplastic elastomer specifications becoming non-negotiable cost drivers.
Pricing Analysis
Input-cost pass-through from Japanese and German chemical suppliers anchors pricing stratification across premium, standard, and economy tiers. FDA combination product certification and ISO 11608 needle-based injection system compliance create tier separation, with certified platforms commanding substantial premiums. Pricing pressure stems from CMS site-of-care reimbursement compression favoring lower-acuity delivery channels. Home care settings exhibit the highest price sensitivity due to direct patient cost exposure, while hospital procurement committees prioritize total cost of care over device acquisition price.
Supply Chain Analysis
Cyclic olefin polymer and high-performance thermoplastic elastomer feedstocks rest on three Japanese and German chemical suppliers, creating concentrated input dependency for drug-contact surfaces. Massachusetts and Swiss precision manufacturing regions anchor electromechanical systems assembly, with German polymer processing centers serving reservoir engineering requirements. Single-source vulnerability in specialty polymer supply generates cost volatility exposure. Distribution runs through specialty pharmacy networks building cold-chain capabilities for large-volume biologics, bypassing traditional wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story where sensor-enabled dose verification and connectivity modules have transitioned from premium differentiators to baseline procurement requirements. The demand shift toward real-world evidence generation capabilities validates integrated platform investments over component sourcing strategies.
For Market Incumbents: Hedge against emerging platform developers by deepening firmware development capabilities for Bluetooth Low Energy connectivity and pressure-sensor feedback loops. Backward integration into polymer processing reduces exposure to Japanese and German chemical supplier concentration. Prioritize ISO 10993 biocompatibility testing capacity to compress preclinical timelines for new drug-contact materials.
For New Entrants and Emerging Players: Direct-to-patient digital channels for hormone replacement and fertility applications offer the most penetrable white-space opportunity. Brazil's ANVISA accelerated pathway for innovative medical devices provides geographic entry with reduced regulatory friction. Target pharmacy channel partnerships with cold-chain distribution capabilities as the primary go-to-market angle.
For Investors and Strategic Acquirers: Asymmetric upside sits with electromechanical specialists possessing full-stack capabilities spanning reservoir engineering, sensor integration, and regulatory dossier preparation. Long-term viability hinges on pharmacovigilance data analytics integration as FDA connected device mandates mature. Watch for FDA draft guidance finalization on real-world evidence generation as the inflection indicator for platform valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Combination Product Submission | Center for Drug Evaluation and Research jurisdictional determinations govern pre-market approval timelines for novel platforms. |
| EU MDR CE Marking Pathway | Active implantable device classifications streamline conformity assessment for electromechanical patch systems. |
| Specialty Pharmacy Network Partnership | Centralized formulary committees evaluate total cost of care rather than device acquisition price alone. |
| Connected Device Software Development | Real-time dose verification and cloud-integrated compliance monitoring become standard procurement expectations. |
| Reimbursement Strategy Alignment | CMS home health benefit expansions channel volume toward patient-administered delivery systems. |
Research Methodology
Coverage spans the United States, Germany, Switzerland, Japan, and Brazil, with primary inputs from each market cluster. The analysis combines structured interviews with device development executives, regulatory affairs leads at combination product sponsors, specialty pharmacy formulary directors, and hospital biomedical engineers with secondary validation from FDA filings, EU MDR submission databases, ISO 11608 standardization records, and CMS reimbursement policy documents. Bottom-up segmentation modeling and top-down market sizing triangulate volume and value estimates.
Rate-of-change decomposition across the analysis window separates volume expansion from price evolution and mix shift toward connected platforms. Segmentation dimensions include product type, technology architecture, end-user channel, and therapeutic application, with regional regulatory cluster effects modeled explicitly. CAGRs derive from iterative convergence of demand-side procurement forecasts and supply-side capacity constraints, incorporating pharmacovigilance data analytics revenue streams as an emerging value component.
The model assumes a particular technology adoption path for smart sensor integration; alternative pathways for biometric monitoring fusion would alter the outlook. Forecasts reflect assumptions about FDA combination product review timeline stability and EU MDR active implantable device classification continuity. A small set of named triggers warrants ongoing watch: FDA draft guidance finalization on real-world evidence, specialty pharmacy network consolidation pace, and Japanese polymer supplier capacity expansion announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Kidney Stone Management Devices Market
Medical Devices
France Drug Delivery Devices Market
Medical Devices
Transcatheter Pacing System Market
Medical Devices
Peri-Implantitis Market
Medical Devices
Global Cardiopulmonary Bypass Accessory Equipment Market
Medical Devices
Non-Invasive Brain Stimulation System Market
Medical Devices
Intravenous Line Connectors Market
Medical Devices
Corneal Surgery Devices Market
Medical Devices
Spain Respiratory Devices Market
Medical Devices
Anti-Infective Endotracheal Tube Market
Medical Devices
North America Portable Medical and Healthcare Devices Market
Medical Devices
Global Smart Biopsy Devices Market
Medical Devices
US Anti-Blue Ray Myopia Lenses Market
Medical Devices
Peripheral Micro Catheters Market
Medical Devices
Venous Procedure Devices Market
Medical Devices
Knee Braces Market