
 Urometer Market | 2026-2036
Urometer Market Size, Share, and Industry Trends Forecast 2026-2036
Urometer Market Intelligence
The capital-intensity divergence between automated manufacturing lines and manual assembly operations is redrawing competitive boundaries in the urometer landscape. BD sustains one of the broadest infection-prevention portfolios, leveraging its scale across acute-care channels worldwide. B. Braun Melsungen AG anchors its position through deep specialization in urology and continence care, dominating European hospital procurement networks. Medline Industries competes aggressively on private-label distribution, controlling cost-sensitive contracts across North American integrated delivery networks.
A urometer is a calibrated medical device that measures urine volume over time, typically incorporating a graduated collection chamber with drainage ports and anti-reflux valves for closed-system catheterization. Electronic variants integrate load-cell sensors or capacitive elements to deliver continuous digital readouts for critical-care fluid balance protocols. Electronic urometers command the dominant share of value given their integration with EMR systems and alarm thresholds, while portable urometers represent the fastest-expanding category as home-care reimbursement broadens. Pressure-measurement technology retains maturity in cost-constrained settings, though infrared and ultrasonic methods are gaining traction in premium hospital segments where non-contact accuracy reduces contamination risk.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape product development timelines and material biocompatibility standards for all commercially distributed urometers. Japan's PMDA enforces JIS-compliant sterilization validation that adds a distinct regulatory layer for Asia-Pacific market entry. Stakeholders must monitor evolving home-care reimbursement codes and ambulatory surgery center accreditation standards, as these will determine whether portable and digital segments achieve sustained volume expansion or face reimbursement compression.
Market Dynamics
Electronic urometer adoption is fragmenting procurement hierarchies across tertiary care networks, as hospitals in Germany, Japan, and the United States recalibrate capital allocation between integrated EMR systems and standalone fluid-monitoring devices.
Growth Catalysts
- EU MDR compliance deadlines:Class II device re-certification is accelerating replacement cycles for legacy mechanical urometers in European hospital systems.
- Postoperative fluid management protocols:Enhanced recovery after surgery (ERAS) pathways in tertiary care facilities are mandating continuous urine output monitoring.
- Infrared sensing modules:Non-contact measurement technologies are reducing catheter-associated urinary tract infection rates in critical care units.
Market Restraints
- Medical-grade polymer supply concentration:Biocompatible PVC and TPE resin production clusters in Northeast Asia create input cost volatility for chamber manufacturing.
- FDA 510(k) pathway complexity:Substantial equivalence determinations for electronic variants extend product launch timelines by 12-18 months.
- Manual urometer substitution:Cost-constrained ambulatory surgery centers in developing markets retain gravity-based measurement systems.
Strategic Opportunities
- Home-care reimbursement expansion:Portable digital urometers are capturing new volume as Medicare and private insurers broaden remote monitoring codes.
- Load-cell and capacitive convergence:Hybrid sensor architectures are enabling single-device compatibility across pediatric and adult patient populations.
- India's hospital infrastructure buildout:Tier-2 and Tier-3 city medical colleges are procuring calibrated urometers for new critical care departments.
Industry Challenges
- Biocompatibility testing backlog:ISO 10993 cytotoxicity and sensitization studies are creating bottlenecks for manufacturers launching multiple SKUs simultaneously.
- Legacy EMR integration complexity:Proprietary data protocols in established hospital information systems require custom middleware development for seamless digital urometer connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urometer Market |
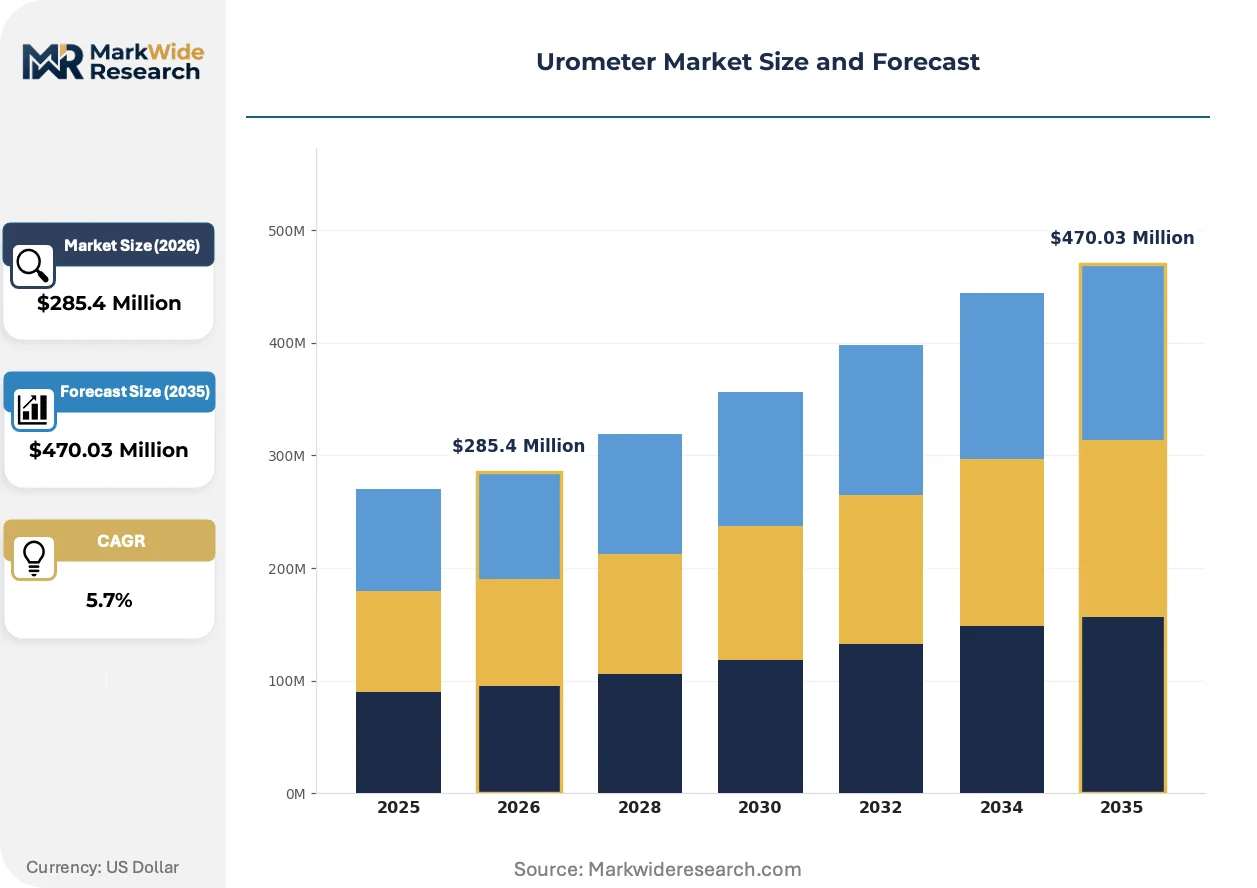
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $470.03 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic Urometers, Mechanical Urometers, Digital Urometers, Portable Urometers End User: Hospitals, Clinics, Home Care, Rehabilitation Centers Technology: Infrared Measurement, Ultrasonic Measurement, Capacitive Measurement, Pressure Measurement Application: Postoperative Monitoring, Dehydration Assessment, Fluid Management, Diagnostic Testing |
| Companies Covered | Medline Industries, Inc., ConvaTec Group Plc, BD (Becton, Dickinson and Company), Cook Medical, B. Braun Melsungen AG, Teleflex Incorporated, Cardinal Health, Laborie, Coloplast, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urometer Market Strategic Shifts & Innovations
Sensor miniaturization and closed-loop catheter system design are redefining performance benchmarks across acute and ambulatory settings. These shifts are compressing traditional equipment replacement cycles and elevating software validation requirements.
Ultrasonic flow measurement is fragmenting the premium hospital segment, replacing contact-based sensors with transcutaneous volume detection. Tertiary care facilities in Germany and Japan are piloting these systems for immunocompromised patient populations. The technology is fragmenting vendor competitive sets by decoupling hardware from disposable revenue models.
Japan's PMDA has tightened JIS-compliant sterilization validation requirements for imported urometers, effective for all new device registrations. Manufacturers must now submit ethylene oxide residual testing protocols alongside standard biocompatibility documentation. European exporters are responding by establishing in-country sterilization partnerships or redesigning for gamma-compatible materials.
Hospital procurement committees are consolidating fluid-management device purchasing under centralized infection-prevention budgets. Group purchasing organizations in the United States are bundling urometers with indwelling catheter contracts, displacing standalone device negotiations. This concentration is most visible in integrated delivery networks across the Midwest and Southeast regions.
Urometer Market Segmentation
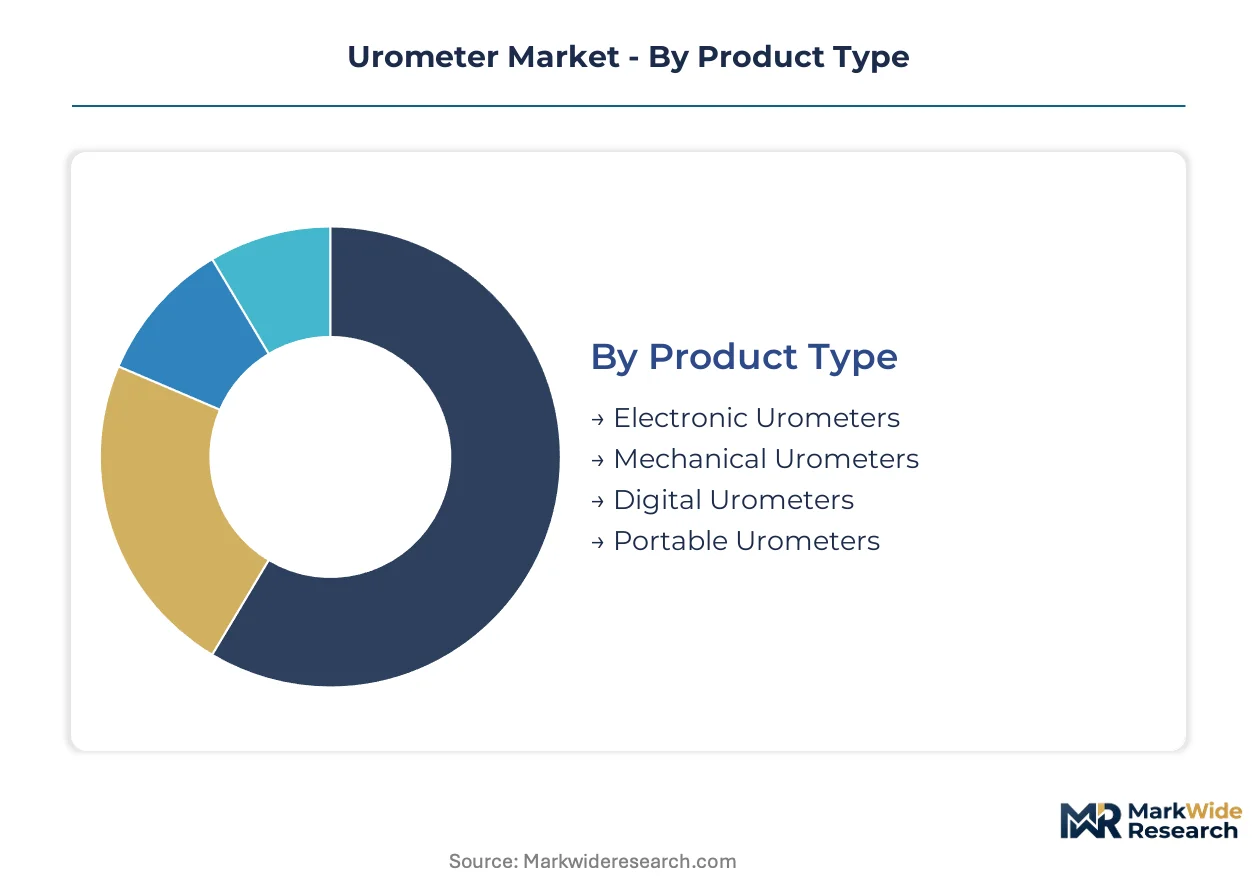
Urometer procurement patterns diverge sharply across care settings, with tertiary hospitals prioritizing EMR-integrated systems while home-care channels favor portable, reimbursement-eligible devices. Technology choices and application intensity vary by clinical workflow, creating distinct margin profiles within each segment cluster.
Product Type:
Electronic variants dominate hospital procurement in Germany, Japan, and the United States, while mechanical systems retain volume in cost-constrained developing markets.
- Electronic Urometers:These systems integrate load-cell sensors with digital displays and EMR connectivity, commanding premium positioning in tertiary care facilities. Demand concentrates in postoperative intensive care units across German university hospitals and Japanese medical centers, driven by ERAS protocol mandates for continuous urine output tracking.
- Portable Urometers:Battery-powered designs with compact chambers and wireless data transmission enable remote patient monitoring. Medicare reimbursement code expansion in the United States and similar private insurer shifts in Germany are accelerating home-care adoption for chronic kidney disease management.
- Mechanical Urometers:Gravity-based graduated chambers with manual reading scales serve cost-sensitive ambulatory surgery centers in India and Southeast Asia.
- Digital Urometers:Hybrid architectures combining electronic sensing with simplified interfaces target mid-tier hospitals seeking upgrade paths from mechanical systems.
Electronic urometers hold the largest share; momentum sits with portable urometers.
End User:
Procurement authority and budget source determine device specification tiers across institutional and consumer channels.
- Hospitals:Tertiary care networks in the United States, Germany, and Japan drive specification intensity, requiring FDA 510(k) or EU MDR Class II certified devices with alarm thresholds and data logging. Infection-prevention committees increasingly bundle urometer procurement with catheter contracts.
- Home Care:Patient-operated devices with simplified interfaces and reimbursement eligibility are gaining traction as remote monitoring codes broaden in North America and Western Europe.
- Clinics:Outpatient facilities favor mid-range electronic or digital systems for procedural fluid monitoring without full critical-care feature sets.
- Rehabilitation Centers:Long-term care settings prioritize durability and ease of cleaning over advanced connectivity, often retaining mechanical or basic digital units.
Hospitals account for dominant procurement volume; home care is climbing the fastest.
Technology:
Sensor architecture selection reflects the trade-off between measurement accuracy, contamination risk, and unit economics.
- Pressure Measurement:Mature, cost-efficient technology using hydrostatic pressure transducers dominates mechanical and entry-electronic segments. Indian Tier-2 hospital buildouts sustain demand for this established approach.
- Capacitive Measurement:Non-contact electrode arrays detect fluid level changes without direct urine exposure, reducing biofilm formation risk. German and Japanese tertiary facilities are piloting these systems for immunocompromised patient populations.
- Infrared Measurement:Optical sensors measure urine volume through chamber walls, eliminating sensor-urine contact. Critical care units in Japan are adopting infrared modules to reduce catheter-associated urinary tract infection rates.
- Ultrasonic Measurement:Transcutaneous flow detection enables completely external volume assessment, fragmenting premium hospital competitive sets by decoupling hardware from disposable revenue models.
Pressure measurement retains the largest installed base; capacitive and ultrasonic methods are gaining share fastest.
Application:
Clinical use case intensity determines feature requirements and replacement frequency across acute and chronic settings.
- Postoperative Monitoring:Continuous urine output tracking in surgical recovery mandates electronic systems with alarm integration. ERAS pathway adoption in United States academic medical centers and German university hospitals drives specification upgrades.
- Fluid Management:Critical-care balancing of intake and output requires calibrated accuracy and EMR documentation, concentrating demand in tertiary hospital intensive care units.
- Dehydration Assessment:Emergency department and ambulatory settings use urometers for rapid hydration status evaluation, favoring portable or mid-tier electronic devices.
- Diagnostic Testing:Timed urine collection for laboratory analysis employs simpler graduated chambers in outpatient and home settings.
Postoperative monitoring commands the largest revenue pool; fluid management applications show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and Southeast Asia exhibit acute price sensitivity, gravitating toward gravity-based mechanical systems, while tertiary hospitals in Germany, Japan, and the United States absorb premium pricing for EMR-integrated electronic units without volume elasticity.
United States
Academic medical centers in the Midwest and Southeast are consolidating urometer procurement under infection-prevention budgets through group purchasing organization bundles. FDA 510(k) clearance timelines for electronic variants extend launch windows by 12-18 months. The Greater Boston cluster anchors telehealth-integrated remote monitoring pilots for home-care reimbursement expansion.
Germany
University hospitals in Bavaria and Baden-Württemberg are mandating continuous urine output tracking under ERAS surgical recovery protocols. EU MDR Class II re-certification deadlines are accelerating replacement cycles for legacy mechanical devices. The Rhine-Ruhr industrial corridor hosts sterilization partnerships serving European exporters facing tightened JIS-compliant validation requirements.
Japan
Tokyo and Osaka medical centers are piloting infrared and capacitive sensing modules to reduce catheter-associated urinary tract infections in immunocompromised populations. PMDA enforcement of JIS-compliant sterilization validation adds distinct regulatory layers for Asia-Pacific market entry. The Nagoya manufacturing hub supplies precision load-cell components for hybrid sensor architectures.
India
Tier-2 and Tier-3 city medical colleges in Maharashtra and Karnataka are procuring calibrated urometers for new critical care departments amid hospital infrastructure buildout. CDSCO medical device registration requirements are tightening for imported electronic variants. The Chennai-Telangana corridor sustains demand for pressure-measurement technology in cost-constrained ambulatory settings.
United Kingdom
NHS trusts in London and the Midlands are evaluating portable digital systems for chronic kidney disease remote monitoring. MHRA post-Brexit regulatory alignment with EU MDR standards is reshaping import certification pathways. The Cambridge-Oxford arc hosts clinical validation studies for ultrasonic flow measurement technologies.
Urometer Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the urometer landscape. Scale-driven multinationals with infection-prevention portfolios dominate premium hospital procurement, while specialized urology-focused manufacturers anchor European supply networks. Private-label distributors control cost-sensitive integrated delivery network contracts. M&A activity concentrates on sensor technology acquisitions, and strategic partnerships with sterilization service providers are proliferating to address JIS and EU MDR compliance requirements.
Among the named participants, BD and B. Braun Melsungen AG occupy positions on the technology-specialist vector, with the latter exemplifying deep regional integration into European hospital procurement hierarchies. Medline Industries represents the private-label distribution archetype, anchoring cost-competitive positioning across North American integrated delivery networks. These three entities collectively illustrate the tripartite competitive structure: scale-specialist, regional-integrated, and distribution-optimized.
| Leading Market Players |
|---|
| Medline Industries, Inc. |
| ConvaTec Group Plc |
| BD (Becton, Dickinson and Company) |
| Cook Medical |
| B. Braun Melsungen AG |
| Teleflex Incorporated |
| Cardinal Health |
| Laborie |
| Coloplast |
| Others |
Cost & Logistics Intelligence
Load-cell sensor substitution for hydrostatic pressure transducers is redrawing procurement economics across the urometer landscape, compressing margins on legacy mechanical assemblies while elevating premium positioning for EMR-integrated electronic systems in German and Japanese tertiary hospitals.
Pricing Analysis
After-sales revenue from calibration services and extended warranty contracts drives lifetime value for electronic urometer manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates FDA 510(k) certified EMR-integrated systems from mid-tier digital units and gravity-based mechanical devices. Cost compression in the mechanical tier is intensifying because Indian Tier-2 hospitals and Southeast Asian ambulatory surgery centers prioritize procurement of lowest-cost calibrated chambers. Price sensitivity concentrates among public hospital procurement committees in developing markets, while private tertiary networks in the United States and Germany absorb premium pricing without volume elasticity.
Supply Chain Analysis
Just-in-time inventory strategies dominate for electronic urometer assembly, though strategic stockpiling of medical-grade polymers persists among Japanese and German manufacturers facing JIS sterilization validation bottlenecks. Biocompatible PVC and TPE resin production clusters in China, South Korea, and Japan feed chamber manufacturing operations. The supply chain rests on precision load-cell components from Nagoya, sterilization service partnerships in the Rhine-Ruhr corridor, and FDA-registered molding facilities in the United States. Single-source vulnerability concentrates in ethylene oxide sterilization capacity for European exporters. Distribution runs through group purchasing organizations bundling urometers with indwelling catheter contracts across North American integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The urometer market is experiencing high-growth disruption as EU MDR Class II re-certification deadlines and ERAS protocol mandates accelerate replacement cycles for legacy mechanical devices across European hospital systems.
For Market Incumbents: Fortify market position by deepening backward integration into load-cell sensor production and establishing captive sterilization partnerships in Japan to satisfy tightened PMDA JIS validation requirements. Defend against ultrasonic flow measurement entrants by accelerating software companion development for seamless EMR connectivity in United States academic medical centers. Prioritize certification investment for hybrid sensor architectures enabling pediatric-to-adult patient population coverage. For New Entrants and Emerging Players: Differentiate on non-contact measurement accuracy by targeting infrared and capacitive sensing modules for immunocompromised critical care units in German university hospitals and Japanese medical centers. Penetrate the home-care reimbursement expansion in North America through portable digital urometers with simplified patient interfaces and wireless data transmission. Pursue go-to-market partnerships with Medicare Advantage plans broadening remote monitoring codes for chronic kidney disease management. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed infection-prevention portfolio companies seeking sensor technology tuck-ins to complement catheter and drainage device franchises. Long-term viability over the next decade hinges on software-enabled recurring revenue models displacing transactional hardware sales. Monitor FDA 510(k) clearance velocity for electronic variants as the primary inflection indicator for premium segment expansion versus reimbursement compression in portable categories.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Class II Re-certification | Accelerates replacement cycles for legacy mechanical urometers in German and French hospital systems. |
| Load-Cell Sensor Backward Integration | Captures margin compression from precision component suppliers in Japan's Nagoya manufacturing hub. |
| Hospital System Partnership | Secures bundled procurement contracts with United States group purchasing organizations in Midwest and Southeast regions. |
| Software Companion Development | Resolves proprietary EMR protocol integration complexity blocking seamless digital urometer connectivity. |
| Reimbursement Strategy | Aligns portable urometer positioning with Medicare remote monitoring code expansion for home-care volume capture. |
Research Approach
Cross-validation between primary interviews with hospital procurement managers, biomedical engineers, and GPO contracts specialists anchors the qualitative findings, while secondary validation draws from FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement contracts, and CMS Medicare reimbursement code updates. Bottom-up demand modeling triangulates against top-down market sizing across the analysis window.
Sensitivity analysis on price elasticity assumptions shapes the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, end user, technology, application, and regional regulatory cluster. CAGRs derive from installed base replacement dynamics and reimbursement code expansion trajectories. Forecast inputs incorporate ERAS protocol adoption rates in tertiary care facilities and JIS sterilization validation timeline variations for Asia-Pacific market entry.
Material uncertainties — regulatory pathway delays, polymer supply disruptions, and reimbursement compression — sit outside the modeled envelope. Forecasts reflect documented assumptions about procurement consolidation and technology substitution rates. Practitioners should keep alternative scenarios live as EU MDR enforcement intensity and home-care reimbursement breadth evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Brazil Aesthetic Devices Market
Medical Devices
Critical Care Devices Market
Medical Devices
Human Anatomical Models Market
Medical Devices
Alexandrite Gemstone Lasers Market
Medical Devices
Seizure Detection Devices Market
Medical Devices
Non-Destructive Medical Technologies Market
Medical Devices
Smart Syringe Pumps Market
Medical Devices
Disposable Lancets Market
Medical Devices
Europe Electric Wheelchair Market
Medical Devices
Global IVF Devices Market
Medical Devices
Embryo Transfer Catheters Market
Medical Devices
Global Intraoperative Neuromonitoring (IONM) Market
Medical Devices
Active Implantable Devices Market
Medical Devices
Heel Incision Devices Market
Medical Devices
Conduction Vaporizers Market
Medical Devices
Europe Micro Invasive Glaucoma Surgery (MIGS) Devices Market