
 Global Injectable Drug Delivery Devices Market | 2026-2036
Global Injectable Drug Delivery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Injectable Drug Delivery Devices Market Outlook
Aftermarket service revenue for device calibration and patient training programs is tilting toward original equipment manufacturers with direct homecare relationships. Becton, Dickinson and Company leverages its integrated sterilization and fill-finish infrastructure to capture recurring service contracts. Gerresheimer AG anchors European glass primary packaging supply for biologics, while West Pharmaceutical Services Inc. competes through elastomer component specialization that reduces extractables risk.
Injectable drug delivery devices are mechanical or electromechanical systems designed to administer therapeutic agents parenterally, typically incorporating ISO 11608-compliant dose accuracy mechanisms and ISO 80369-7 standard luer connections for needle attachment. Their primary commercial purpose centers on enabling self-administration of biologics, vaccines, and chronic disease therapies outside clinical settings. Prefilled syringes and wearable injectors now command the strongest margin pools as biologic viscosity rises and dosing frequency extends. Autoinjectors lead in patient adherence applications for multiple sclerosis and rheumatoid arthritis, while smart injectors with Bluetooth connectivity represent the fastest-growing technology segment despite higher unit costs.
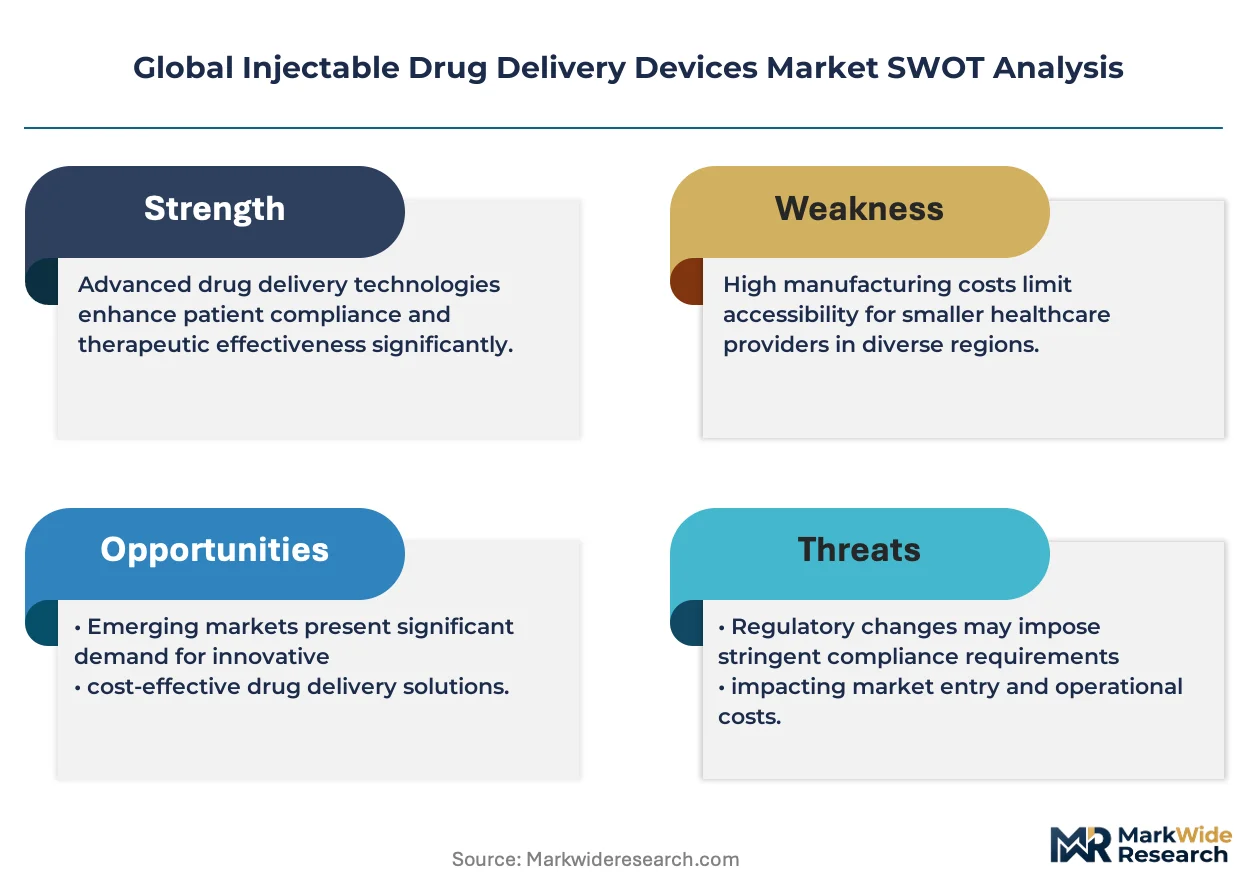
FDA combination product regulations, EU MDR Article 117 requirements for drug-device interfaces, and ISO 13485 quality management standards collectively elevate barrier-to-entry for new device entrants while accelerating incumbent consolidation. The FDA's emerging guidance on human factors engineering for self-injection devices is reshaping design validation timelines and clinical evidence requirements. Stakeholders must monitor evolving interoperability standards between injectors and digital health platforms as payers condition reimbursement on real-world adherence data capture.
Market Dynamics
The EU Medical Device Regulation's sterility assurance mandates for combination products are forcing device manufacturers to consolidate fill-finish and sterilization capabilities under unified quality systems, reshaping competitive boundaries across prefilled syringes and wearable injectors.
Growth Catalysts
- Rising biologic viscosity:Monoclonal antibody formulations exceeding 50 cP are accelerating demand for high-force autoinjectors with enhanced spring mechanisms and lubricated plunger systems.
- Home-based therapy reimbursement:Medicare and commercial payers in the United States now cover self-injection training programs, expanding addressable patient populations for multiple sclerosis and rheumatoid arthritis treatments.
- ISO 80369-7 standardization:Global harmonization of luer connection dimensions is reducing regional SKU complexity and enabling economies of scale in mold fabrication and assembly automation.
Market Restraints
- Borosilicate glass supply concentration:European and Japanese glass tubing manufacturers control 80% of pharmaceutical-grade supply, exposing device makers to input bottlenecks during capacity expansions.
- Extractables testing burden:EMA and FDA requirements for comprehensive elastomer and plastic component characterization extend development timelines by 12-18 months for new drug-device combinations.
- Silicone oil alternatives:Protein aggregation risks from conventional lubricants are driving costly migration to baked-on silicone or polymer coating technologies with unproven long-term stability profiles.
Strategic Opportunities
- Connected device ecosystems:Bluetooth-enabled smart injectors with real-time adherence tracking are opening recurring revenue streams through data licensing to payers and specialty pharmacies.
- Emerging market homecare infrastructure:Brazil and Saudi Arabia are investing in cold chain distribution networks that enable temperature-sensitive biologic self-administration outside hospital settings.
- Prefilled syringe conversion:Vaccine programs in India and Indonesia are transitioning from vial-and-syringe formats to prefilled presentations, reducing medication errors and dosing variability.
Industry Challenges
- Human factors engineering expertise:FDA's enhanced usability validation requirements have created acute shortages of specialists capable of designing intuitive self-injection interfaces for geriatric and pediatric populations.
- Combination product GMP alignment:Device manufacturers must integrate pharmaceutical quality systems (ICH Q10) with ISO 13485 frameworks, requiring redundant documentation and dual-audited facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Injectable Drug Delivery Devices Market |
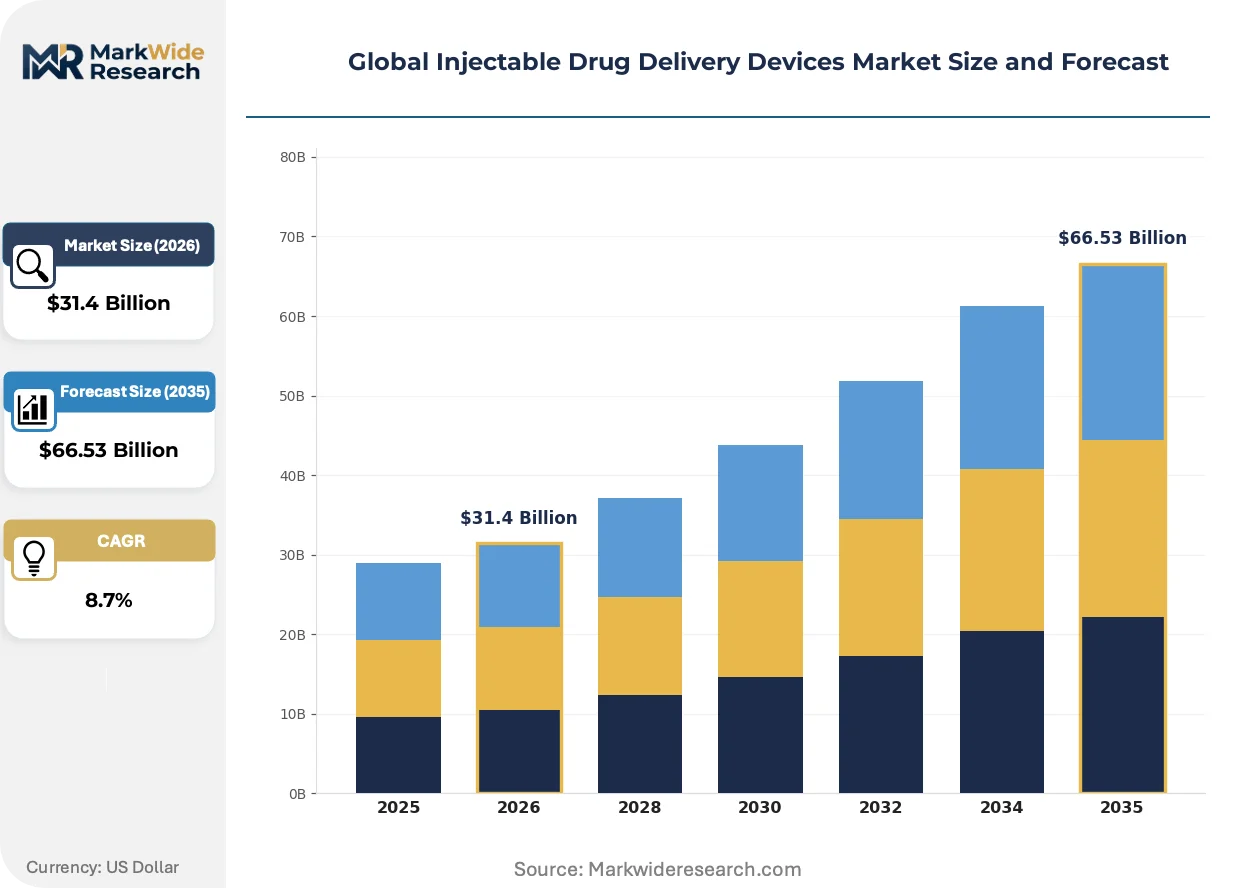
| Market Size in 2026 | $31.4 Billion |
| Market Size in 2035 | $66.53 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prefilled Syringes, Autoinjectors, Pen Injectors, Wearable Injectors Technology: Conventional Injection, Microneedles, Smart Injectors, Needle-Free Devices End User: Hospitals, Homecare Settings, Pharmacies, Clinics Application: Diabetes, Oncology, Vaccination, Chronic Diseases |
| Companies Covered | Becton, Dickinson and Company, Gerresheimer AG, West Pharmaceutical Services Inc., Schott AG, Ypsomed AG, Terumo Corporation, Baxter International Inc., Sanofi, SHL Medical AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Injectable Drug Delivery Devices Market Strategic Shifts
Wearable injector platforms are compressing the distinction between acute and chronic care delivery, enabling subcutaneous administration of large-volume biologics previously restricted to intravenous infusion centers.
Electromechanical large-volume wearable injectors are collapsing the infrastructure requirements for monoclonal antibody administration. Rheumatology and immunology clinics in Germany and Japan are adopting 5-10 mL patch pumps for trastuzumab and vedolizumab delivery. Hospital infusion center utilization rates are falling as patients complete loading doses and maintenance therapy at home.
MDR Article 117's consultation procedure for drug-device interfaces is extending regulatory review timelines for European market entry. Notified bodies must now verify pharmaceutical quality aspects previously assessed only by EMA, creating sequential rather than parallel approval pathways. Combination product sponsors are front-loading clinical evidence packages to preempt interface-specific queries.
Specialty pharmacy networks are capturing patient onboarding and device training functions from traditional distributor models. Accredo and BioPlus in the United States now employ dedicated nurse educators for autoinjector instruction, displacing manufacturer field forces. Device OEMs must credential these intermediaries or risk compromised adherence metrics that jeopardize payer contracts.
Global Injectable Drug Delivery Devices Market Segmentation
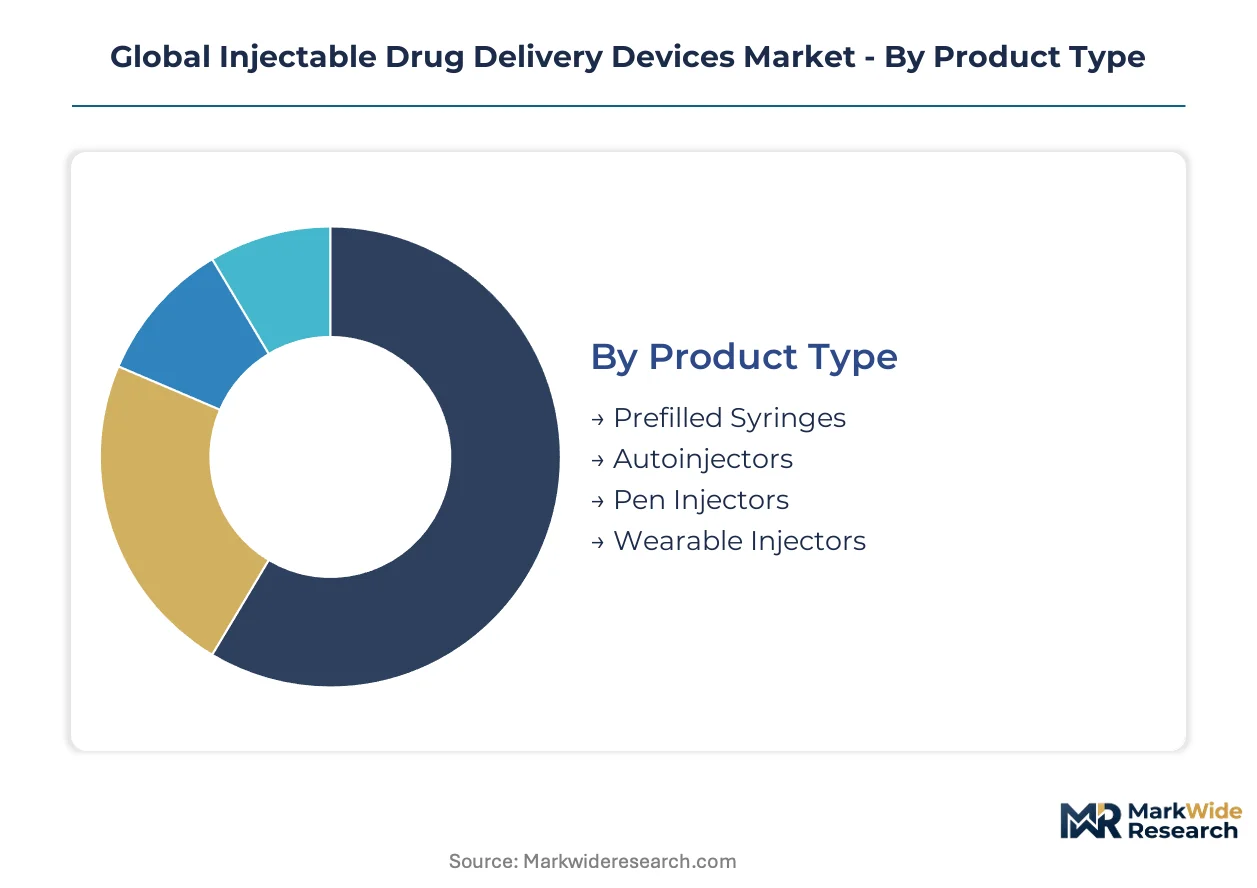
Device segmentation in injectable delivery reflects divergent technical requirements across biologic viscosity classes, patient self-administration capabilities, and regulatory complexity tiers. Each category maps to distinct margin profiles and competitive moats that reshape manufacturer positioning.
Product Type:
Mature formats dominate unit volume while emerging platforms capture premium pricing for high-viscosity biologics.
- Prefilled Syringes:Glass-barrel or polymer-based systems with integrated staked needles, delivering fixed doses of vaccines and anticoagulants. Demand concentrates in Germany and the United States where cold chain infrastructure supports temperature-sensitive biologics; borosilicate glass supply constraints from European manufacturers limit capacity expansion.
- Autoinjectors:Spring-loaded mechanical devices with hidden needles that automate subcutaneous delivery for multiple sclerosis and rheumatoid arthritis therapies. Adoption accelerates in Japan and the United States as Medicare and commercial payers expand home-based therapy reimbursement.
- Pen Injectors:Reusable or disposable dial-dose systems for insulin and GLP-1 agonists.
- Wearable Injectors:Adhesive patch pumps enabling 3-10 mL subcutaneous delivery of monoclonal antibodies.
Prefilled syringes handle the majority of throughput; wearable injectors are expanding most quickly on share.
Technology:
Cost tiers separate legacy mechanical systems from connected and minimally invasive alternatives.
- Conventional Injection:Standard hypodermic syringes and vial-and-needle configurations for clinical administration. Volume concentrates in India and Indonesia vaccination programs transitioning from multi-dose vials to single-use presentations.
- Smart Injectors:Bluetooth-enabled devices with dose tracking, adherence logging, and digital health platform integration. Rheumatology practices in Germany and specialty pharmacies in the United States drive uptake as payers condition contracts on real-world evidence capture.
- Microneedles:Dissolving or hollow microprojection arrays for intradermal delivery.
- Needle-Free Devices:Jet injectors using high-pressure liquid streams to penetrate skin without metal needles.
Conventional injection retains the highest unit volumes; smart injectors command the steepest expansion trajectory.
End User:
Customer type determines regulatory pathway complexity and service revenue attachment rates.
- Homecare Settings:Self-administration environments requiring patient training programs and device support hotlines. Growth accelerates in the United States and Saudi Arabia as cold chain distribution networks mature and reimbursement frameworks shift toward outpatient chronic disease management.
- Hospitals:Acute care facilities with centralized pharmacy compounding and infusion center infrastructure. Demand persists in Japan and Germany for high-volume biologic loading doses before patients transition to home-based maintenance therapy.
- Pharmacies:Retail and specialty pharmacy channels handling patient onboarding and device instruction.
- Clinics:Outpatient rheumatology, endocrinology, and immunology practices.
Hospitals anchor current device procurement volumes; homecare settings are gaining share fastest.
Application:
Margin concentration follows therapy area pricing power and injection frequency requirements.
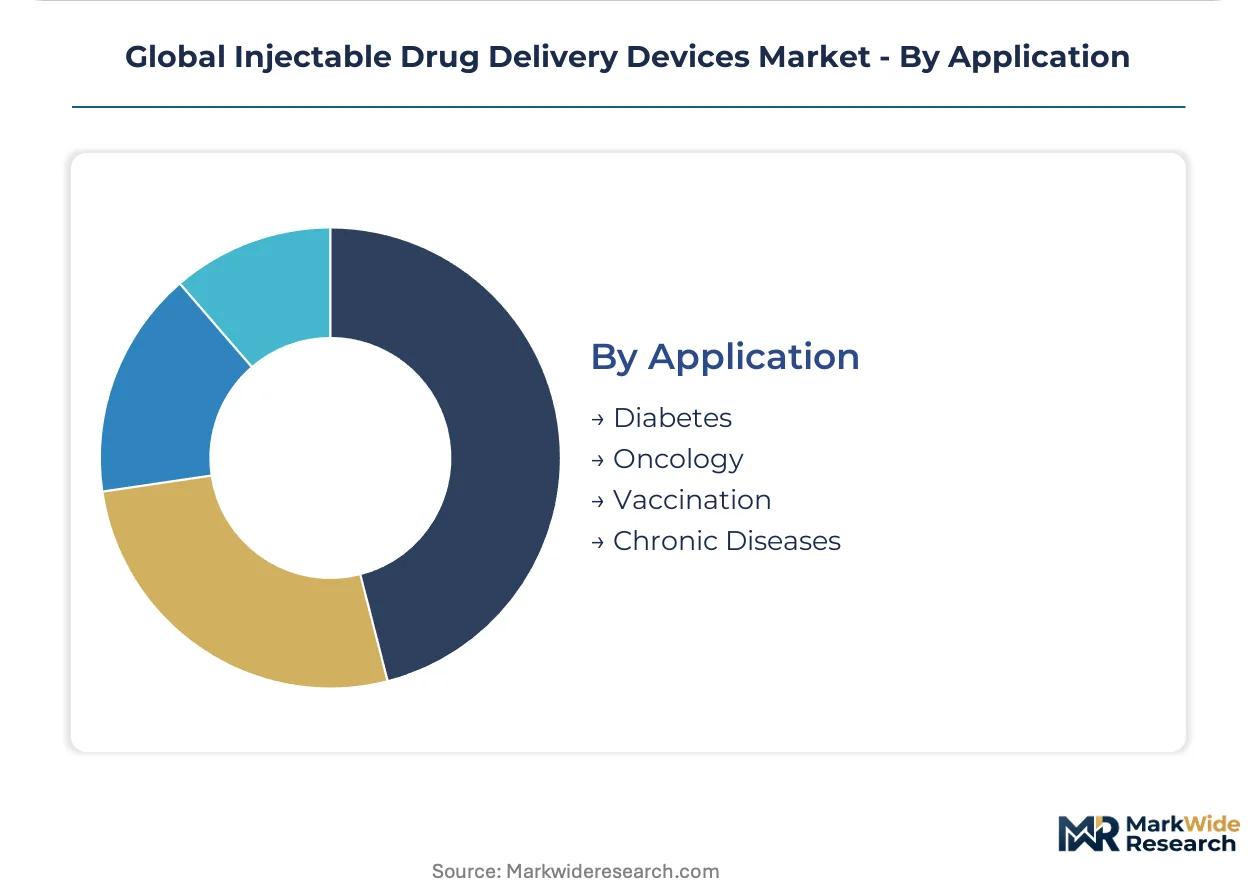
- Diabetes:Insulin and GLP-1 receptor agonist delivery requiring precise dose titration and frequent administration. Pen injectors dominate in the United States and Japan where patient populations exceed 30 million combined; connected device ecosystems emerge as payers demand adherence verification.
- Oncology:Supportive care agents and subcutaneous chemotherapy alternatives reducing infusion center dependency. German and Japanese clinics adopt wearable injectors for trastuzumab and vedolizumab to collapse infrastructure requirements.
- Vaccination:Mass immunization programs and travel medicine.
- Chronic Diseases:Multiple sclerosis, rheumatoid arthritis, and autoimmune conditions.
Diabetes generates the highest absolute device volumes; oncology applications are climbing the fastest on value per unit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major markets. The United States prioritizes connected devices with reimbursement-linked adherence tracking, while Germany and Japan emphasize precision engineering for high-viscosity biologics, and emerging markets in Brazil and Saudi Arabia build cold chain infrastructure to enable home-based therapy expansion.
United States
Medicare and commercial payers now cover self-injection training programs, expanding patient populations for multiple sclerosis and rheumatoid arthritis therapies. FDA combination product regulations and emerging human factors engineering guidance are reshaping design validation timelines. Specialty pharmacy networks in Massachusetts and California capture device training functions, displacing traditional manufacturer field forces with nurse educator models.
Germany
Rheumatology and immunology clinics adopt 5-10 mL wearable injectors for trastuzumab and vedolizumab, collapsing hospital infusion center dependency. EU MDR Article 117 consultation procedures extend regulatory review timelines as notified bodies verify pharmaceutical quality aspects. The Baden-Württemberg medical technology cluster concentrates electromechanical large-volume injector development with integrated sterilization capabilities.
Japan
PMDA streamlines approval pathways for self-administration devices as patient populations for diabetes and autoimmune conditions exceed 30 million combined. METI promotes smart injector adoption through digital health reimbursement frameworks. The Kansai region anchors elastomer component specialization that reduces extractables risk for biologic drug-device combinations.
Brazil
ANVISA accelerates prefilled syringe conversions for national vaccination programs transitioning from multi-dose vials to single-use presentations. Government investments in cold chain distribution networks enable temperature-sensitive biologic self-administration outside hospital settings. São Paulo-based specialty pharmacies build patient onboarding infrastructure for chronic disease management.
Saudi Arabia
SFDA aligns with international standards for combination product sterility assurance as homecare infrastructure expands. National health transformation programs prioritize outpatient chronic disease management with reimbursement for self-injection therapies. The Riyadh cluster develops distribution partnerships for wearable injector platforms serving regional biologic markets.
Global Injectable Drug Delivery Devices Market Competitive Environment
Capability concentration sits with integrated sterilization and fill-finish specialists; scale advantage sits with diversified medical technology conglomerates. The market structures around three tiers: full-service combination product sponsors with unified quality systems, component specialists controlling glass primary packaging or elastomer technology, and regional device assemblers serving emerging markets. Dominant competitive moves include backward integration into sterilization infrastructure and strategic partnerships with specialty pharmacy networks for patient training credentialing.
Within the integrated infrastructure tier, Becton, Dickinson and Company exemplifies unified sterilization and fill-finish capabilities that capture recurring service contracts. Gerresheimer AG and West Pharmaceutical Services Inc. occupy distinct specialist positions—European glass primary packaging supply and elastomer component engineering respectively—each representing archetypes that reduce supply risk for biologic drug-device combinations. These three anchors demonstrate how competitive boundaries reshape around regulatory compliance depth rather than unit volume alone.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Gerresheimer AG |
| West Pharmaceutical Services Inc. |
| Schott AG |
| Ypsomed AG |
| Terumo Corporation |
| Baxter International Inc. |
| Sanofi |
| SHL Medical AG |
| Others |
Value Chain & Pricing Dynamics
Borosilicate glass supply concentration in Germany and Japan determines both pricing tier spreads and supply chain shape, forcing device manufacturers to accept premium input costs or absorb margin compression from polymer alternatives with unproven stability profiles.
Pricing Analysis
Long-term offtake contracts dominate procurement for pharmaceutical-grade glass tubing and elastomer components, insulating incumbent device manufacturers from spot market volatility while locking in volume commitments that strain working capital. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified combination product specialists from regional assemblers serving emerging markets. Pricing pressure stems from EMA and FDA extractables testing requirements that extend development timelines. Hospital procurement committees exhibit lowest price sensitivity due to reimbursement pass-through mechanisms, while emerging market vaccination programs drive aggressive cost compression.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for electromechanical wearable injector components and molded polymer housings. Manufacturing concentrates in Germany for precision glass primary packaging, Switzerland for elastomer formulation expertise, and China for injection molding and electronic subassemblies. Raw material dependencies include pharmaceutical-grade borosilicate glass, medical device silicone elastomers, and stainless steel for spring mechanisms. Single-source vulnerability persists for ISO 80369-7 compliant luer mold fabrication. Distribution runs through specialty pharmacy networks in the United States and hospital procurement consortia in Germany and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Home-based biologic administration represents early-cycle expansion, with Medicare reimbursement for self-injection training programs accelerating patient population access beyond traditional infusion center boundaries.
For Market Incumbents: Entrench sterilization and fill-finish capabilities under unified quality systems to preempt EU MDR Article 117 compliance advantages. Acquire elastomer component specialists in the Kansai region to reduce extractables risk exposure. Consolidate backward integration into borosilicate glass supply through captive European manufacturing partnerships before capacity bottlenecks intensify. For New Entrants and Emerging Players: Brazil's cold chain infrastructure buildout offers the most penetrable geographic entry point for prefilled syringe conversion in national vaccination programs. Target Saudi Arabia's outpatient chronic disease management expansion for wearable injector platform partnerships. Pursue nurse educator credentialing partnerships with Accredo and BioPlus to bypass displaced manufacturer field force channels. For Investors and Strategic Acquirers: FDA's emerging human factors engineering guidance reshapes the acquisition landscape toward usability validation specialists with geriatric and pediatric interface expertise. Five-to-ten year viability favors integrated combination product sponsors over component assemblers exposed to regulatory fragmentation. Monitor notified body capacity constraints for MDR Article 117 consultations as the inflection signal for European market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Unified Sterilization Infrastructure | EU MDR compliance consolidation captures recurring service contracts from fragmented regional assemblers. |
| Specialty Pharmacy Credentialing | Accredo and BioPlus nurse educator partnerships secure adherence metrics for payer contract retention. |
| Human Factors Engineering Investment | FDA usability validation requirements create specialist capability scarcity for geriatric interface design. |
| Elastomer Component Acquisition | Kansai-region formulation expertise reduces extractables risk for high-viscosity biologic combinations. |
| Connected Device Ecosystem Development | Bluetooth adherence tracking opens data licensing revenue streams to Medicare Advantage plans. |
Study Parameters
Initial hypotheses were tested against primary input from regulatory affairs leads at combination product sponsors, biomedical engineers at German rheumatology clinics, GPO contracts managers at US hospital systems, and specialty pharmacy operations directors, then refined against FDA 510(k) filings, EMA consultation procedure records, ISO 13485 audit databases, and CMS Medicare reimbursement policy documents. Bottom-up demand modeling triangulated with top-down market sizing across device category volumes.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeled by device technology, therapeutic application, end-user setting, and regional regulatory cluster. CAGRs derived from patient population epidemiology, biologic pipeline viscosity trends, and reimbursement policy trajectory assumptions. Forecast inputs incorporated cold chain infrastructure investment schedules and notified body capacity expansion timelines.
Practitioners should monitor EU MDR implementation delays, borosilicate glass furnace capacity announcements, and FDA human factors guidance finalization for early signals of forecast revision triggers. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Microcirculation Microscope Market
Medical Devices
Pipetting Systems Market
Medical Devices
Implant Handpiece Market
Medical Devices
US Biomedical Sensors Market
Medical Devices
Japan Aesthetic Devices Market
Medical Devices
Global Lithotripsy Device Market
Medical Devices
Blood Warmers Market
Medical Devices
Electrosurgical Generators Market
Medical Devices
Eye Examination Equipment Market
Medical Devices
Colon Hydrotherapy Units Market
Medical Devices
Next Generation Optical Biometry Devices Market
Medical Devices
Medical Face Shield Market
Medical Devices
Global Surgical Robotics Market
Medical Devices
Global Abutment Implants Market
Medical Devices
Active Humidifier Devices Market
Medical Devices
Wireless Surgical Cameras Market