
 Drainage Catheters Market | 2026-2036
Drainage Catheters Market Size, Share, and Industry Trends Forecast 2026-2036
Drainage Catheters Market Foresight
The EU Medical Device Regulation is recalibrating material sourcing and biocompatibility testing protocols across European supply chains. Medtronic plc leverages its integrated manufacturing footprint to sustain compliance leadership across multiple catheter platforms. Cook Medical anchors its competitive position through deep specialization in interventional radiology drainage systems. Boston Scientific Corporation differentiates via technology leadership in minimally invasive urological drainage.
Drainage catheters are flexible tubular devices typically constructed from silicone, polyurethane, or polyvinyl chloride, designed to evacuate fluids from body cavities or organs through percutaneous or natural orifice insertion. These devices incorporate graduated markings, radio-opaque stripes, and multiple side-eye configurations to enable precise placement verification and sustained patency. The elastomeric product segment leads current revenue generation due to its prevalence in post-operative and palliative care settings, while the home care end-user category represents the fastest-growing demand pool as payors push ambulatory recovery protocols. Silicone material formulations command premium positioning owing to superior biocompatibility and extended indwell duration, whereas polyvinyl chloride occupies the high-volume economy tier.
The FDA enforces Class II device controls with 510(k) premarket notification requirements for drainage catheters, while the EMA's MDR framework mandates enhanced clinical evidence and post-market surveillance across European Economic Area markets. Japan's PMDA applies stringent QMS inspections and country-specific biocompatibility standards that shape product registration timelines for foreign manufacturers. Stakeholders must monitor evolving reimbursement thresholds for outpatient drainage procedures and anticipate material substitution pressures as sustainability mandates intensify across hospital procurement frameworks.
Market Dynamics
The EU Medical Device Regulation's 2024 enforcement deadline is forcing wholesale reformulation of silicone and polyurethane supply chains, as manufacturers scramble to meet biocompatibility documentation requirements that now cover every raw material lot.
Growth Catalysts
- Aging demographics in developed economies:Japan's super-aged population and Germany's 65-plus cohort expansion are generating sustained procedural volume for percutaneous drainage interventions in oncology and palliative care settings.
- MDR compliance infrastructure:The EU's enhanced post-market surveillance mandates are accelerating hospital procurement standardization around CE-marked devices with validated clinical evidence packages.
- Silicone elastomer advances:Next-generation platinum-cured formulations are extending indwell duration beyond 90 days, reducing exchange frequency and total cost of ownership for chronic drainage patients.
Market Restraints
- Medical-grade silicone supply concentration:Three specialty chemical producers control 70 percent of pharmaceutical-grade silicone monomer output, exposing catheter manufacturers to price volatility and allocation risk.
- MDR technical documentation burden:The EU's requirement for clinical evaluation reports on legacy devices has extended recertification timelines by 18-24 months for mid-tier manufacturers lacking dedicated regulatory affairs teams.
- Antimicrobial silver ion substitution limits:REACH restrictions on silver nanoparticle release rates are constraining coating options for infection-resistant drainage catheters.
Strategic Opportunities
- Home drainage therapy expansion:Reimbursement codes for ambulatory pleural and ascitic drainage are creating direct-to-patient channels bypassing traditional hospital purchasing committees.
- Bioabsorbable polymer convergence:The intersection of polylactic acid manufacturing scale and interventional radiology technique maturation is opening temporary drainage applications that eliminate retrieval procedures.
- Japan's QMS harmonization pathway:PMDA's accelerated review track for devices with FDA 510(k) clearance is compressing market entry timelines for Western manufacturers.
Industry Challenges
- Polymer compounding expertise scarcity:The specialized knowledge required for medical-grade polyurethane extrusion with consistent durometer tolerance is concentrated among a shrinking cohort of process engineers nearing retirement.
- Legacy ERP-to-UDI integration complexity:Hospital systems running decade-old inventory platforms face multimillion-dollar upgrade costs to comply with FDA Unique Device Identification mandates for lot-level traceability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drainage Catheters Market |
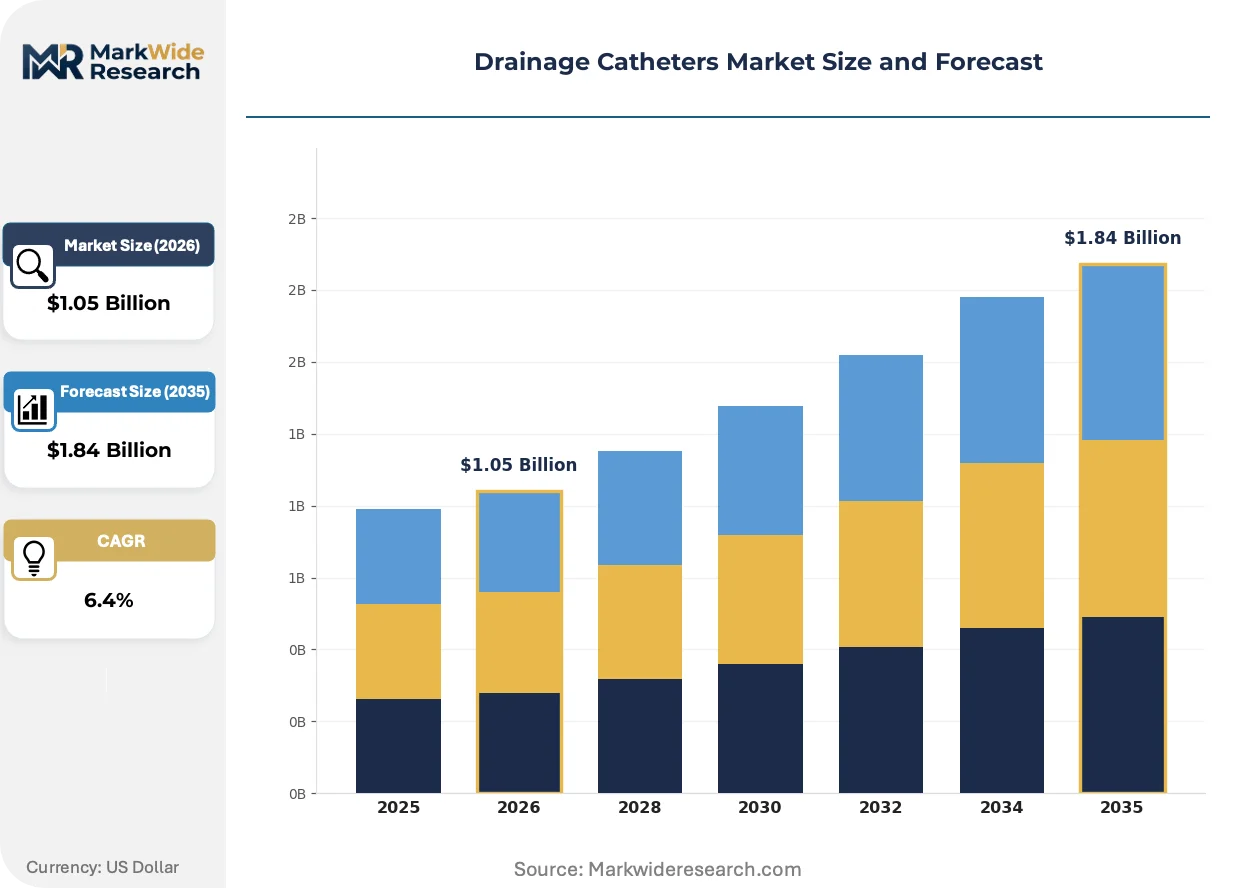
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $1.84 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Elastomeric, Intermittent, Continuous, Vacuum End User: Hospitals, Clinics, Outpatient Centers, Home Care Material: Silicone, Polyvinyl Chloride, Latex, Polyurethane Application: Urology, Gastroenterology, Pulmonology, Cardiology |
| Companies Covered | Medtronic plc, Getinge AB, Cook Medical, Teleflex Incorporated, Smiths Medical, B. Braun Melsungen AG, Johnson & Johnson, Integra LifeSciences Holdings Corporation, Boston Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drainage Catheters Market Shifts & Advancements
Catheter architecture is fragmenting into application-specific configurations as point-of-care specialization demands devices optimized for single anatomical targets rather than multipurpose platforms.
Multi-lumen drainage catheters with independent irrigation and aspiration channels are modularizing procedural workflows in interventional radiology suites. Academic medical centers in the United States are adopting these platforms for complex abscess management, collapsing what previously required sequential device exchanges into single-session interventions. The technology is modularizing purchasing decisions around procedure bundles rather than commodity line items.
The EU's MDR Article 10.4 requirement for periodic safety update reports is compressing product lifecycle management cycles across European Economic Area markets. Manufacturers must now submit annual clinical data summaries for class IIa and above devices, forcing investment in real-world evidence infrastructure. The regulation is reshaping competitive position toward firms with integrated health economics capabilities.
Hospital value analysis committees are consolidating supplier relationships around full-procedure contracts that bundle catheters with placement kits and retrieval accessories. Integrated delivery networks in Germany and the United States are displacing fragmented purchasing across individual departments. The shift is most visible in oncology drainage, where total cost-per-procedure metrics now dominate over unit price negotiations.
Drainage Catheters Market Segmentation
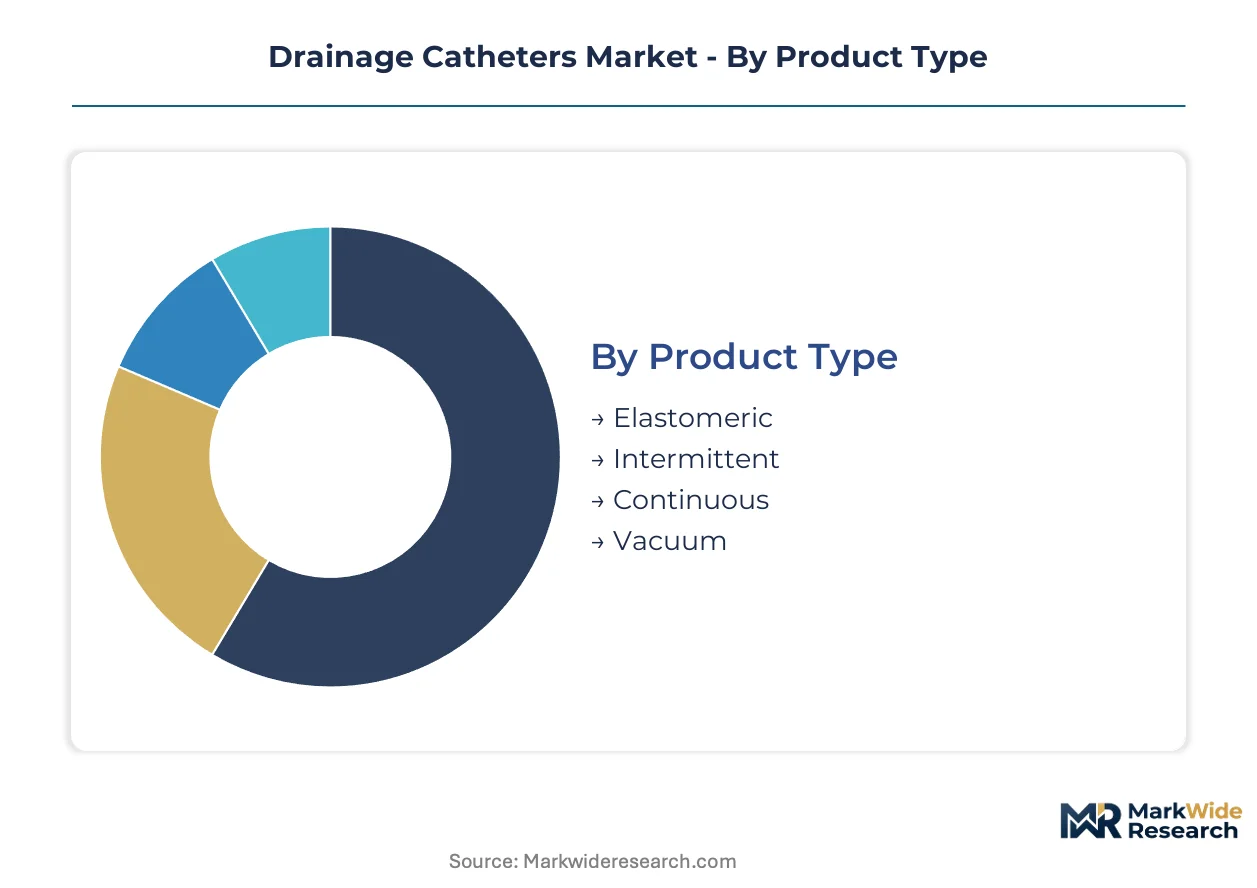
Drainage catheter purchasing decisions fragment across clinical workflow requirements, indwell duration specifications, and care setting infrastructure. Manufacturers must align product architectures with distinct reimbursement pathways and regulatory compliance tiers.
Product Type:
Elastomeric systems dominate standalone ambulatory applications while continuous and vacuum configurations embed into institutional workflows with dedicated suction infrastructure.
- Elastomeric:Platinum-cured silicone bulbs generate passive suction through manual compression cycles. Demand concentrates in post-operative oncology units across Germany and the United States where extended indwell duration reduces exchange frequency.
- Intermittent:Straight or coude-tip catheters designed for single-use sterile insertion. Home care reimbursement expansion in Japan and the United States accelerates patient-directed purchasing for neurogenic bladder management.
- Continuous:Gravity-dependent closed systems with collection bags.
- Vacuum:Wall-suction or portable pump-driven evacuation platforms.
Elastomeric leads volumes today; intermittent is gaining share fastest.
End User:
Procurement authority shifts from centralized hospital supply chains toward patient-directed channels as ambulatory reimbursement codes mature.
- Hospitals:Integrated delivery networks negotiate procedure bundles spanning placement kits, catheters, and retrieval accessories. German and Japanese hospital groups standardize around CE-marked and PMDA-approved devices with validated clinical evidence packages.
- Home Care:Direct-to-patient channels bypass traditional purchasing committees through durable medical equipment suppliers. Medicare Part B and Japan's long-term care insurance expansion accelerates pleural and ascitic drainage outside institutional settings.
- Clinics:Interventional radiology suites and urology practices.
- Outpatient Centers:Ambulatory surgery facilities with same-day discharge protocols.
Hospitals retain procurement volume leadership; home care climbs the fastest.
Material:
Biocompatibility documentation requirements under EU MDR Article 10.4 now cover every raw material lot, reshaping supplier qualification protocols.
- Silicone:Platinum-cured formulations with 90-plus day indell capability command premium positioning. REACH-compliant supply chains from specialty chemical producers face allocation constraints that catheter manufacturers hedge through dual-sourcing strategies.
- Polyurethane:Thermoplastic elastomers balance kink resistance with thin-wall construction for high-flow applications. PMDA's QMS harmonization pathway accelerates Japanese market entry for Western manufacturers with FDA 510(k) clearance.
- Polyvinyl Chloride:Plasticized PVC occupies economy tier with shorter approved indwell.
- Latex:Natural rubber formulations declining due to hypersensitivity risk.
Silicone dominates revenue contribution; polyurethane shows steepest expansion trajectory.
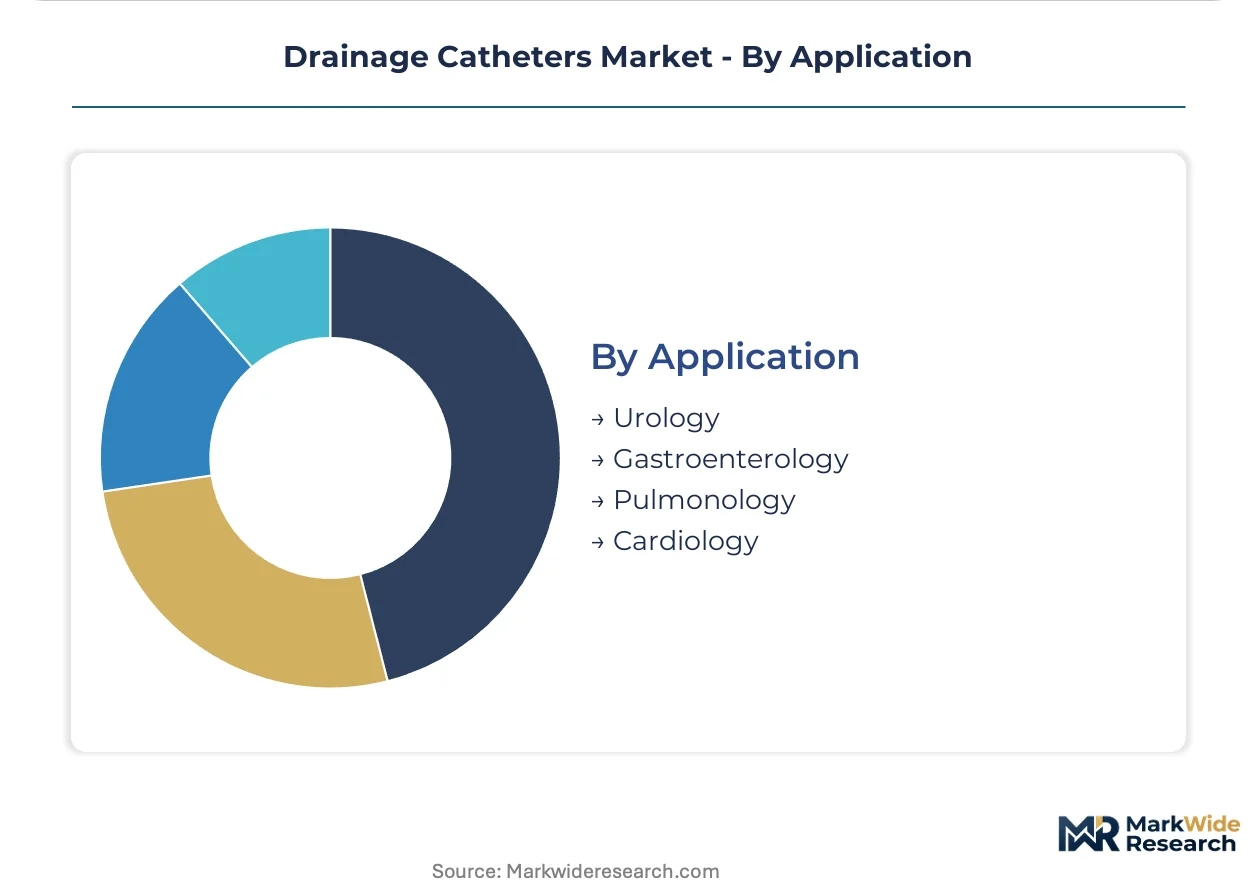
Application:
Anatomical specialization demands device configurations optimized for specific cavity pressures and fluid chemistries rather than multipurpose platforms.
- Urology:Foley, suprapubic, and nephrostomy catheters with antimicrobial coatings. Boston Scientific's technology leadership in minimally invasive urological drainage anchors competitive positioning through differentiated hydrophilic surface treatments.
- Pulmonology:Chest tube and pigtail configurations for pleural effusion and pneumothorax. Academic medical centers in the United States adopt multi-lumen platforms with independent irrigation channels for complex abscess management.
- Gastroenterology:Percutaneous endoscopic gastrostomy and biliary drainage systems.
- Cardiology:Pericardial and mediastinal evacuation devices.
Urology leads procedure volumes today; pulmonology is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Interventional radiologists and specialized catheter engineers concentrate in Germany, Japan, and the United States, anchoring procedural innovation and manufacturing expertise for drainage catheter systems.
United States
Medicare Part B reimbursement expansion for ambulatory pleural drainage drives home care channel growth. FDA 510(k) premarket notification requirements enforce Class II device controls with biocompatibility documentation. Academic medical centers in Boston and Baltimore adopt multi-lumen platforms with independent irrigation channels for complex abscess management.
Germany
Integrated delivery networks standardize procurement around full-procedure contracts bundling catheters with placement kits. EU MDR Article 10.4 mandates annual clinical data summaries for Class IIa devices, extending recertification timelines. Industrial clusters in Baden-Württemberg and North Rhine-Westphalia host specialty chemical producers supplying pharmaceutical-grade silicone monomers.
Japan
Super-aged demographics generate sustained procedural volume for percutaneous oncology and palliative drainage interventions. PMDA applies stringent QMS inspections and country-specific biocompatibility standards shaping foreign manufacturer registration. Tokyo and Osaka metropolitan areas concentrate interventional radiology suites adopting advanced catheter configurations.
United Kingdom
NHS value analysis committees consolidate supplier relationships around total cost-per-procedure metrics. MHRA alignment with EU MDR frameworks maintains CE-marking requirements post-Brexit. London and Manchester medical centers drive adoption of elastomeric systems for post-operative oncology units.
Switzerland
Swissmedic enforces medical device regulations harmonized with EU MDR standards for market access. Precision manufacturing expertise in the Basel region supports catheter component suppliers serving European OEMs. Zurich academic hospitals pilot bioabsorbable polymer applications for temporary drainage eliminating retrieval procedures.
Drainage Catheters Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the drainage catheter landscape, with integrated manufacturing footprints facing specialized interventional radiology developers. The vendor base fragments across three tiers: multinational conglomerates with diversified medtech portfolios, mid-size specialists in urological or drainage systems, and regional fabricators serving local hospital procurement. Strategic moves concentrate on M&A for regulatory compliance infrastructure and dual-sourcing arrangements for medical-grade silicone supply security.
Within the integrated conglomerate tier, Medtronic plc and Johnson & Johnson exemplify scale-driven positioning through diversified catheter platforms spanning multiple anatomical applications. Cook Medical occupies a specialist position representing deep interventional radiology focus, while Boston Scientific Corporation anchors the technology-differentiated vector in minimally invasive urological drainage. These three entities collectively illustrate competitive positioning strategies across premium compliance leadership, clinical specialization, and surface treatment innovation.
| Leading Market Players |
|---|
| Medtronic plc |
| Getinge AB |
| Cook Medical |
| Teleflex Incorporated |
| Smiths Medical |
| B. Braun Melsungen AG |
| Johnson & Johnson |
| Integra LifeSciences Holdings Corporation |
| Boston Scientific Corporation |
| Others |
Supply & Pricing Matrix
EU REACH restrictions on silver nanoparticle release rates and phthalate plasticizers gate qualified supply access and premium-tier pricing for antimicrobial and extended-indwell catheter platforms. Manufacturers without validated biocompatibility documentation face exclusion from German and United States hospital value analysis committees that bundle full-procedure contracts.
Pricing Analysis
Bundled service contracts encompassing placement kits, catheters, and retrieval accessories command 15-25% premiums over unbundled component purchasing in German integrated delivery networks and United States academic medical centers. Price differentiation rests on CE-marking tier under EU MDR Article 10.4 and FDA 510(k) clearance status, with platinum-cured silicone formulations capturing premium positioning against plasticized PVC economy tiers. Cost compression in standard-grade polyurethane catheters is intensifying because mid-tier manufacturers lack dedicated regulatory affairs teams to absorb MDR technical documentation burdens. Home care direct-to-patient channels show highest price sensitivity as Medicare Part B reimbursement codes cap allowable charges, while interventional radiology suites demonstrate lowest sensitivity due to total cost-per-procedure contracting.
Supply Chain Analysis
Reverse-logistics flows for catheter retrieval and refurbishment remain underdeveloped, with single-use sterile protocols dominating clinical practice and limiting circular economy participation. Raw material supply concentrates in Germany, Japan, and the United States, with pharmaceutical-grade silicone monomer output controlled by specialty chemical producers in Baden-Württemberg and North Rhine-Westphalia industrial clusters. Medical-grade polyurethane extrusion draws from thermoplastic elastomer compounders in the United States and Japan, while platinum-cured silicone formulations rest on peroxide-free curing agent supply from Swiss and German chemical specialists. Single-source vulnerability in pharmaceutical-grade silicone monomer exposes catheter manufacturers to allocation risk during specialty chemical production disruptions. Distribution runs through hospital purchasing committees and durable medical equipment suppliers for home care channels, with GPO contracts consolidating procurement authority across United States health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in drainage catheters depends on platinum-cured silicone formulation premiums and home care reimbursement code expansion offsetting MDR compliance cost absorption.
For Market Incumbents: Anchor competitive position through backward integration into pharmaceutical-grade silicone compounding and captive supply of platinum-cured formulations to hedge specialty chemical allocation risk. Defend against mid-tier manufacturers collapsing recertification timelines by accelerating real-world evidence infrastructure investment for annual clinical data summaries under EU MDR Article 10.4. Prioritize capacity addition in Baden-Württemberg industrial clusters to secure proximity to German integrated delivery network procurement headquarters. For New Entrants and Emerging Players: Home care durable medical equipment suppliers represent the most penetrable buyer archetype as Medicare Part B and Japan's long-term care insurance expansion creates direct-to-patient channels bypassing hospital purchasing committees. Target ambulatory pleural and ascitic drainage applications in United States metropolitan areas where reimbursement code maturation outpaces incumbent GPO contract coverage. Pursue PMDA QMS harmonization pathway acceleration for devices with existing FDA 510(k) clearance to compress Japanese market entry timelines. For Investors and Strategic Acquirers: Roll-up economics work for regional catheter fabricators with established CE-marking infrastructure because EU MDR recertification timelines have extended 18-24 months for mid-tier manufacturers lacking dedicated regulatory affairs teams, creating distressed acquisition opportunities. Focus on 5-10 year viability framing around integrated health economics capabilities and real-world evidence generation infrastructure. Monitor REACH restriction expansion on additional coating chemistries as inflection indicator for material substitution investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Article 10.4 compliance separates premium-tier manufacturers from recertification-lagged competitors in German hospital procurement. |
| Hospital System Partnership | Integrated delivery networks in the United States and Germany consolidate supplier relationships around full-procedure bundle contracting. |
| Backward Integration | Captive pharmaceutical-grade silicone compounding hedges allocation risk from Baden-Württemberg specialty chemical producers. |
| Reimbursement Strategy | Medicare Part B code expansion for ambulatory drainage creates direct-to-patient channels outside hospital purchasing committee control. |
| Software Companion Development | Digital tracking platforms for indwell duration and exchange scheduling reinforce premium positioning in home care channels. |
Research Methodology
Multiple input streams — primary interviews with interventional radiologists and hospital GPO contracts managers, regulatory filings with FDA and EMA, and secondary validation through hospital procurement databases and CMS Medicare reimbursement data — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged clinicians in academic medical centers across Boston, Baltimore, Tokyo, and Osaka, biomedical engineers at catheter OEMs in Germany and the United States, and purchasing committee directors within German integrated delivery networks. Secondary sources encompassed FDA 510(k) premarket notification databases, EMA MDR technical documentation summaries, GPO contract disclosure filings, and Japan PMDA QMS inspection reports.
Historical shipment data cross-referenced against expert panel input across product type, material formulation, end-user setting, and anatomical application dimensions shaped the analytical framework over the projection horizon. Segmentation modeling captured elastomeric versus intermittent versus continuous versus vacuum configurations, silicone versus polyurethane versus polyvinyl chloride material tiers, and hospital versus home care versus clinic versus outpatient center procurement channels. CAGRs were derived from procedure volume elasticity to aging demographic projections and reimbursement code expansion trajectories, with specific weighting applied to Japan's super-aged population growth and United States Medicare Part B ambulatory drainage coverage expansion.
Inputs from FDA 510(k) clearance databases and EMA MDR technical documentation registries were available through the study window; gaps in real-world evidence generation infrastructure investment levels among mid-tier manufacturers introduce uncertainty bands around market share shift projections. Forecasts reflect assumptions regarding REACH restriction enforcement consistency and PMDA QMS harmonization pathway maintenance. Practitioners should monitor silver nanoparticle coating substitution regulatory developments and pharmaceutical-grade silicone monomer allocation announcements from Baden-Württemberg producers for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Europe Spinal Surgery Devices Market
Medical Devices
Refurbished Medical Devices Market
Medical Devices
Asia-Pacific Electroencephalography Devices Market
Medical Devices
Asia-Pacific Medical Device Regulatory Affairs Outsourcing Market
Medical Devices
Gutta Percha Obturator Market
Medical Devices
Europe Arthroscopy Devices Market
Medical Devices
Global Hydrogel Based Drug Delivery System Market
Medical Devices
Subdural Electrodes Market
Medical Devices
Disabled and Elderly Assistive Technologies Market
Medical Devices
Global Foot Orthotic Insoles Market
Medical Devices
Transcatheter Aortic Valve Implantation (TAVI) Market
Medical Devices
Global Transradial Access Market
Medical Devices
Positive Air Pressure Devices Market
Medical Devices
Tissue Embedding Center Market
Medical Devices
Medical Face Shield Market
Medical Devices
IoT Medical Devices Market