
 Global Catheter Stabilization Devices Market | 2026-2036
Global Catheter Stabilization Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Catheter Stabilization Devices Market Foresight
ISO 10993 biocompatibility testing is reorganizing competitive access in catheter securement, forcing smaller manufacturers to absorb extended validation timelines. Cardinal Health leverages its hospital distribution network to sustain volume leadership across adhesive anchor categories. BD differentiates through vertical control over hydrocolloid formulation supply, while B. Braun SE anchors its position with specialized neonatal securement portfolios in European tertiary centers.
Catheter stabilization devices are mechanical or adhesive systems engineered to immobilize indwelling catheters, typically incorporating silicone or hydrocolloid interfaces with peel-force ratings between 0.5 and 2.0 N/cm to prevent dislodgement and reduce bloodstream infection risk. Their primary function is maintaining catheter position during patient movement, dressing changes, and transport while minimizing skin trauma at the insertion site. Adhesive anchors dominate current procurement volumes due to universal compatibility with peripheral and central line configurations, though silicone-based fasteners are capturing preference in neonatal care where epidermal integrity demands gentler release profiles. ICU procedures represent the most concentrated application segment, while home healthcare channels are expanding fastest as discharge protocols shift toward ambulatory infusion management.
FDA 510(k) clearance pathways and the EU Medical Device Regulation (MDR) are converging to elevate clinical evidence requirements for securement device substantiation, directly extending product development cycles and favoring manufacturers with dedicated regulatory affairs infrastructure. The EPA's oversight of medical adhesive solvent emissions additionally constrains domestic manufacturing location decisions for US-market suppliers. Stakeholders must monitor how FDA guidance on catheter-related bloodstream infection prevention reshapes hospital purchasing criteria for securement accessories.
Market Dynamics
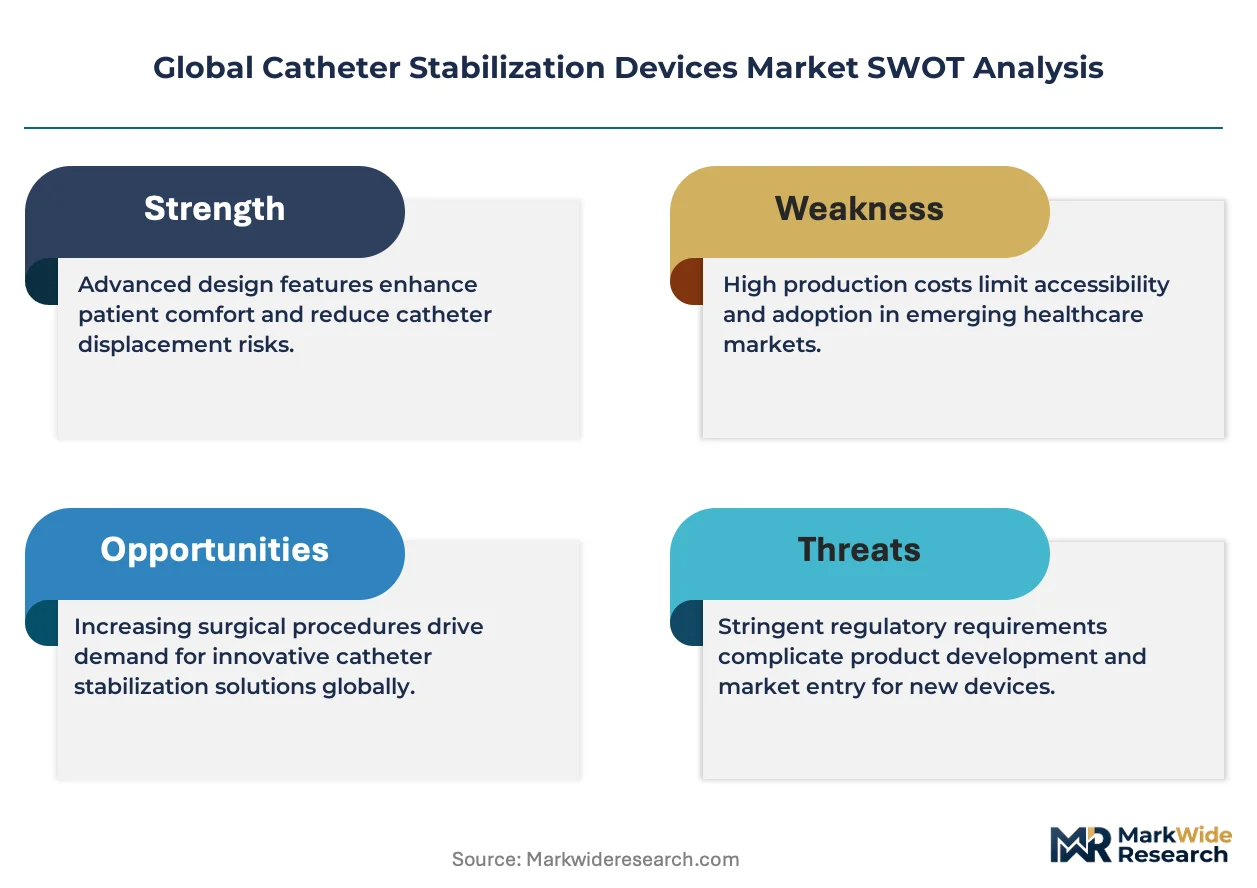
FDA 510(k) clearance pathways and EU MDR convergence are extending product development cycles for adhesive-based securement systems, favoring manufacturers with dedicated regulatory infrastructure while compressing margins for smaller competitors unable to absorb extended validation timelines.
Growth Catalysts
- Catheter-related bloodstream infection prevention protocols:German hospitals are driving replacement cycles for securement devices as national healthcare quality standards mandate enhanced insertion site protection.
- ISO 10993 biocompatibility testing reorganization:Elevated material safety requirements are filtering out subscale suppliers and consolidating procurement toward validated manufacturers.
- Home healthcare discharge acceleration:Ambulatory infusion management protocols in the United States are expanding demand for patient-applied securement solutions outside acute care settings.
Market Restraints
- Medical adhesive solvent emission controls:EPA oversight constrains domestic manufacturing location decisions for US-market suppliers, elevating compliance costs.
- Extended clinical evidence requirements:FDA and EU MDR convergence demands larger safety datasets, directly lengthening time-to-market for novel securement formulations.
- Silicone raw material concentration:Supply of medical-grade silicone for gentle-release neonatal applications concentrates among limited specialty chemical producers.
Strategic Opportunities
- Neonatal care specialization:Underpenetrated demand for epidermal-integrity-preserving securement exists in European tertiary centers managing premature infant vascular access.
- Integrated securement-dressing systems:Technology convergence between antimicrobial barriers and mechanical anchors offers pathway to reduce dressing change frequency.
- Japan's aging infusion population:METI-supported home healthcare expansion creates channel for ambulatory securement devices in Asia-Pacific's fastest-aging demographic.
Industry Challenges
- Regulatory affairs talent scarcity:Specialized expertise in FDA 510(k) and EU MDR dual-track submissions commands premium compensation, constraining mid-tier manufacturer expansion.
- Legacy hospital purchasing system integration:New securement technologies face friction from entrenched GPO contracts and established SKU rationalization protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Catheter Stabilization Devices Market |
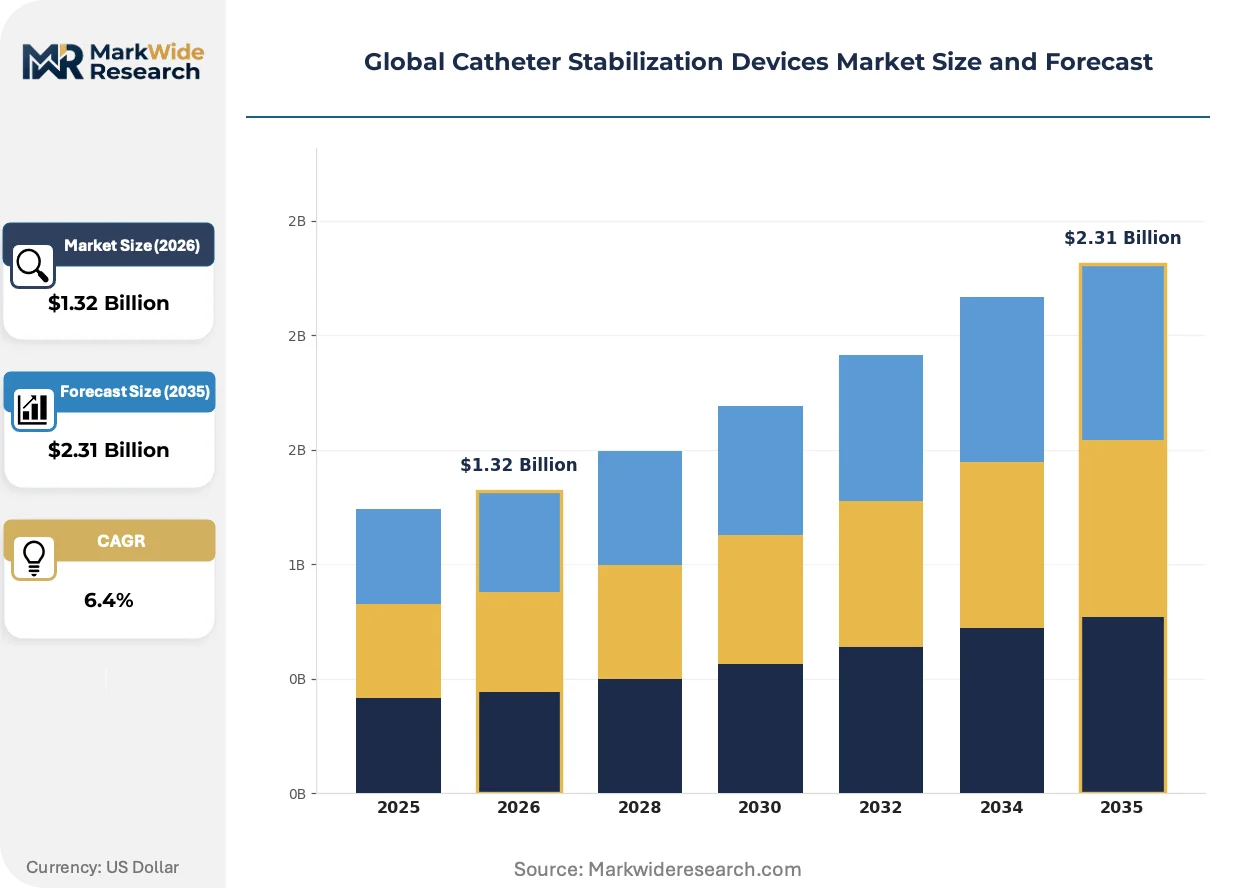
| Market Size in 2026 | $1.32 Billion |
| Market Size in 2035 | $2.31 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adhesive Anchors, Suture Anchors, Securement Bands, Stabilization Tapes, Magnetic Holders Application: ICU Procedures, Ambulatory Care, Neonatal Care, Geriatric Care, Surgical Units End User: Critical Care Units, Outpatient Clinics, Diagnostic Centers, Rehabilitation Facilities, Home Healthcare Technology: Hydrocolloid Adhesives, Silicone-Based Fasteners, Elastic Straps, Non-Latex Materials, Biocompatible Polymers |
| Companies Covered | Cardinal Health, 3M, BD, TIDI Products, Medline Industries, ICU Medical, Merit Medical Systems, Dale Medical Products, B. Braun SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Catheter Stabilization Devices Market Shifts & Advancements
Silicone interface materials are fragmenting traditional adhesive anchor dominance as clinical evidence accumulates on skin trauma reduction, while regulatory pressure on solvent-based manufacturing reshapes supply geography.
Hydrocolloid formulation chemistry is fragmenting competitive positioning in catheter securement. These moisture-responsive adhesives maintain peel-force stability across temperature and humidity variation. Neonatal ICUs in Germany and the United States are adopting hydrocolloid-based systems at accelerated rates. The technology is fragmenting procurement categories previously consolidated around standard acrylic adhesives.
EU MDR Article 10 clinical evaluation requirements are elevating post-market surveillance obligations for securement device manufacturers. This regulatory shift demands continuous safety data collection beyond initial clearance. Small-to-mid manufacturers without dedicated post-market infrastructure face disproportionate compliance burden, accelerating consolidation toward scaled players.
Hospital value analysis committees are compressing securement device evaluation cycles as infection prevention bundles gain purchasing authority. Traditional materials management departments are ceding influence to clinical quality teams. This behavioral shift is most visible in United States health systems adopting CDC central line insertion practice bundles.
Global Catheter Stabilization Devices Market Segmentation
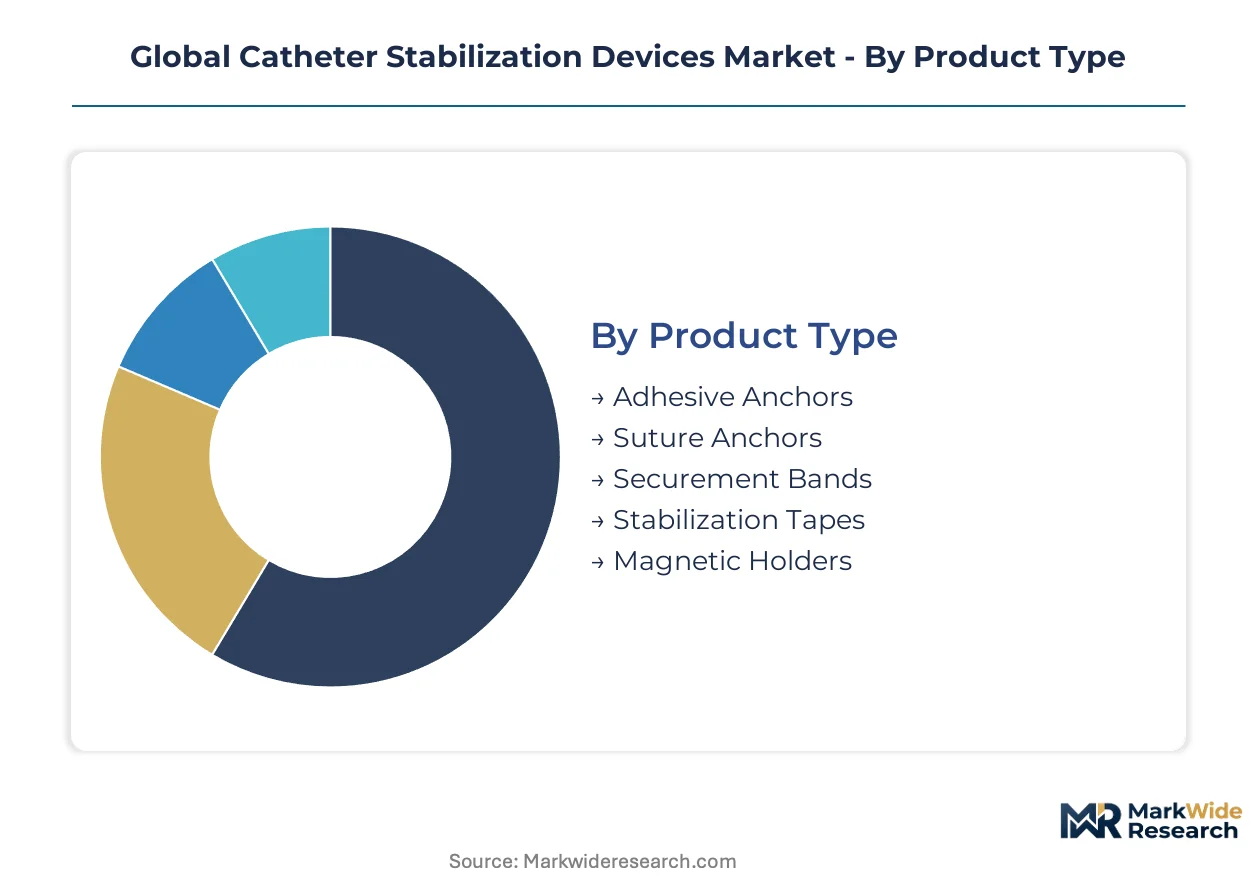
Catheter stabilization devices fragment across four critical dimensions that determine procurement pathways and margin capture. Product type and technology choices directly influence clinical outcomes and reimbursement positioning, while application and end-user segments dictate channel strategy and regulatory burden.
Product Type:
Adhesive anchors command the deepest margin pools due to universal compatibility and recurring consumable demand, while specialized securement technologies extract premiums in high-acuity settings.
- Adhesive Anchors:Hydrocolloid and acrylic formulations dominate hospital procurement with peel-force ratings between 0.5 and 2.0 N/cm. United States ICU protocols are standardizing these across central line bundles to meet CDC infection prevention criteria.
- Suture Anchors:Mechanical fixation systems using non-absorbable polymers for high-mobility patients. German tertiary centers favor these in cardiac catheterization labs where catheter dislodgement risks procedural failure.
- Securement Bands:Elastic retention systems for peripheral IV lines in high-patient-turnover settings.
- Stabilization Tapes:Low-cost acrylic options for short-duration procedures in outpatient settings.
- Magnetic Holders:Emerging fixation technology for MRI-compatible catheter management in diagnostic environments.
Adhesive anchors hold installed capacity. Suture anchors are rotating up the share rankings.
Application:
Volume concentrates in acute care settings, though ambulatory migration is redistributing growth toward lower-acuity environments with different performance requirements.
- ICU Procedures:The most concentrated demand segment where bloodstream infection prevention protocols mandate securement device inclusion in insertion kits. United States hospitals bundle these with central line placements under quality improvement mandates.
- Neonatal Care:Specialized epidermal-integrity applications requiring gentle-release silicone interfaces. German and United States NICUs are adopting hydrocolloid-silicone hybrids at accelerated rates to prevent skin trauma in premature infants.
- Ambulatory Care:Patient-applied securement for infusion therapy outside hospital settings.
- Geriatric Care:Fragile-skin applications in long-term care facilities with elevated fall risks.
- Surgical Units:Intraoperative catheter management during patient positioning and transport.
ICU procedures anchor current revenue. Neonatal care is gaining share fastest.
End User:
Procurement authority varies sharply across settings, with critical care units maintaining clinical veto power while home healthcare channels expand through distributor relationships.
- Critical Care Units:Hospital-based intensive care with infection control committees driving securement specification. These units command premium pricing for validated devices with ISO 10993 biocompatibility documentation.
- Home Healthcare:The steepest expansion trajectory as United States discharge protocols shift infusion management to ambulatory settings. Patient-applied devices require simplified application and reduced adhesive trauma profiles.
- Outpatient Clinics:High-throughput environments prioritizing rapid application and cost efficiency.
- Diagnostic Centers:Imaging-compatible securement for interventional radiology procedures.
- Rehabilitation Facilities:Extended-duration securement for patients with limited mobility.
Critical care units retain purchasing authority. Home healthcare is climbing the fastest.
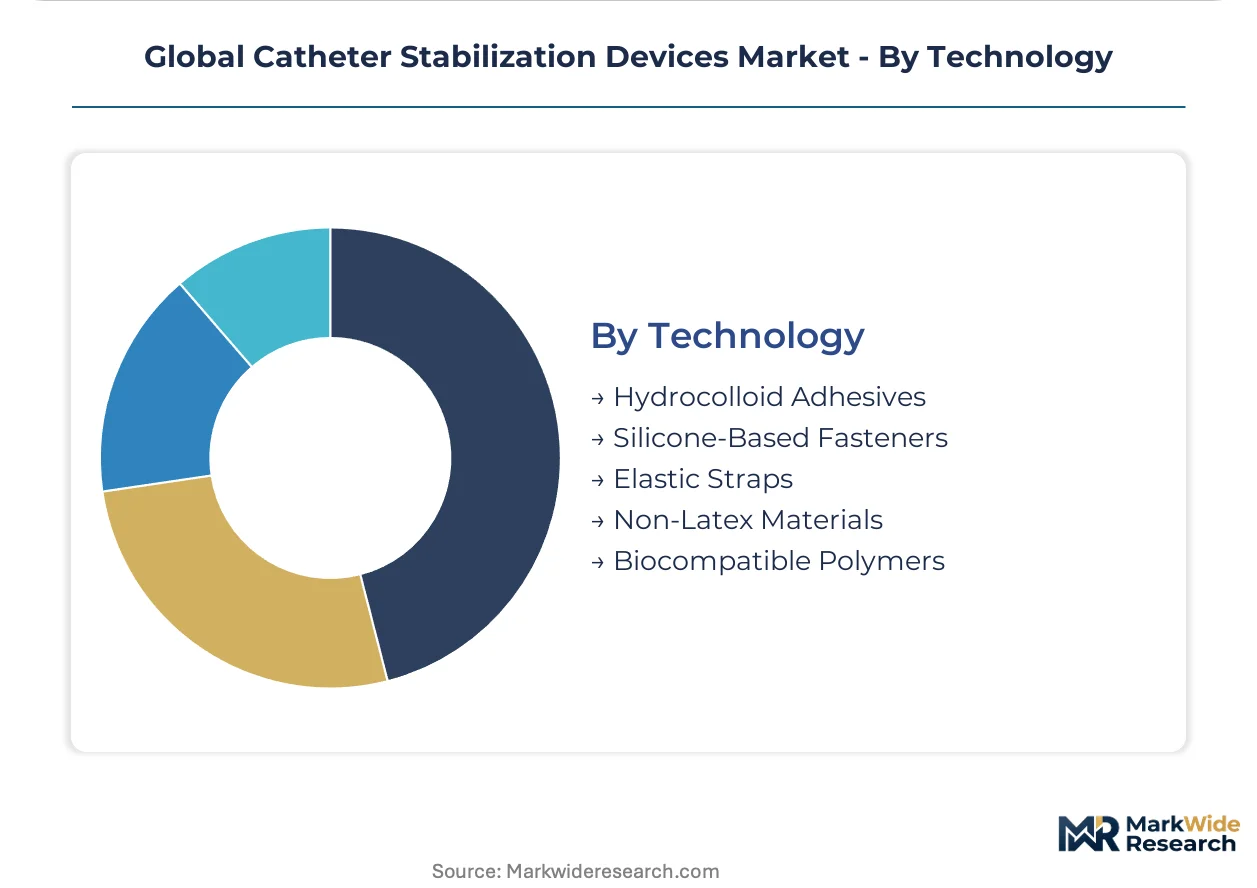
Technology:
Material chemistry differentiation is fragmenting competitive positioning as clinical evidence accumulates on skin trauma reduction and regulatory pressure escalates on solvent-based manufacturing.
- Hydrocolloid Adhesives:Moisture-responsive formulations maintaining peel-force stability across temperature and humidity variation. These systems are displacing standard acrylics in neonatal ICUs across Germany and the United States.
- Silicone-Based Fasteners:Gentle-release interfaces for epidermal-integrity-critical applications. Limited medical-grade silicone supply concentrates among specialty chemical producers, constraining manufacturer expansion.
- Elastic Straps:Mechanical retention without adhesive contact for patients with adhesive sensitivity.
- Non-Latex Materials:Hypoallergenic alternatives mandatory in pediatric and allergy-prevalent populations.
- Biocompatible Polymers:Advanced materials meeting elevated ISO 10993 testing requirements for long-term implantation adjacency.
Hydrocolloid adhesives hold technology leadership. Silicone-based fasteners are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in the United States, Germany, and Japan concentrate purchasing authority for catheter stabilization devices. These buyer archetypes prioritize ISO 10993 documentation and infection prevention bundle compliance over unit cost.
United States
ICU central line insertion protocols drive securement device bundling under CDC quality improvement mandates. FDA 510(k) clearance timelines are extending validation requirements for adhesive-based systems. Boston and Minneapolis medical device clusters host manufacturers with dedicated regulatory affairs infrastructure.
Germany
National healthcare quality standards mandate enhanced insertion site protection, accelerating replacement cycles for securement devices. EU MDR Article 10 clinical evaluation requirements elevate post-market surveillance obligations for manufacturers. Tübingen and Aachen tertiary centers are standardizing hydrocolloid-silicone hybrid systems in neonatal ICUs.
Japan
METI-supported home healthcare expansion creates demand for patient-applied ambulatory securement solutions. PMDA medical device review pathways are converging with international standards, streamlining market access for validated manufacturers. Osaka and Tokyo metropolitan hospitals are piloting integrated securement-dressing systems for aging infusion populations.
China
NMPA medical device registration reforms are elevating biocompatibility testing requirements for imported securement products. National hospital grading standards increasingly weight catheter-related infection prevention in accreditation criteria. Shanghai and Suzhou industrial clusters are developing domestic hydrocolloid adhesive manufacturing capacity.
United Kingdom
NHS infection prevention procurement frameworks are standardizing securement device specifications across acute care trusts. MHRA post-Brexit regulatory autonomy is maintaining alignment with EU MDR standards while streamlining UK-specific clearance pathways. London and Manchester hospital systems are consolidating GPO contracts toward validated manufacturers with ISO 10993 documentation.
Global Catheter Stabilization Devices Market Competitive Landscape
Player mix skews toward diversified medical device conglomerates with hospital distribution networks and dedicated regulatory infrastructure. Market structure concentrates procurement authority among scaled manufacturers capable of absorbing extended FDA and EU MDR validation timelines. Two strategic archetypes dominate: conglomerates leveraging backward integration into material supply, and specialized securement-focused manufacturers with neonatal care portfolios. Competitive moves center on portfolio diversification into integrated securement-dressing systems and geographic expansion into METI-supported Japanese home healthcare channels.
Within the conglomerate tier, Cardinal Health and BD occupy positions anchored by hospital distribution scale and captive supply chain control. B. Braun SE exemplifies the specialized archetype, with its SE corporate structure signaling European manufacturing concentration. These three entities represent the competitive poles: distribution-leveraged volume leadership, upstream material integration, and clinical-specialization differentiation.
| Leading Market Players |
|---|
| Cardinal Health |
| 3M |
| BD |
| TIDI Products |
| Medline Industries |
| ICU Medical |
| Merit Medical Systems |
| Dale Medical Products |
| B. Braun SE |
| Others |
Supply & Pricing Matrix
ISO 10993 biocompatibility certification gates both supplier qualification and price differentiation in catheter securement, forcing manufacturers to absorb validation costs that stratify procurement tiers while concentrating volume toward validated incumbents with dedicated regulatory infrastructure.
Pricing Analysis
Cost-plus contracts with medical-grade silicone indexation dominate adhesive anchor procurement. Three-tier pricing structure across premium, standard, and economy levels separates hydrocolloid-silicone hybrids from standard acrylics and commodity stabilization tapes. Cost compression in economy tiers intensifies as Chinese manufacturers expand domestic hydrocolloid capacity. Outpatient clinics and high-turnover peripheral IV settings exhibit highest price sensitivity, while United States critical care units prioritize ISO 10993 documentation over unit economics.
Supply Chain Analysis
Inbound logistics costs from Asia-Pacific trade lanes constrain just-in-time delivery for hydrocolloid raw materials, with port congestion at Shanghai and Busan elevating working capital requirements. Medical-grade silicone concentrates in Germany, Japan, and the United States, while hydrocolloid adhesive production feeds from China, South Korea, and domestic United States chemical processors. Single-source vulnerability in specialty silicone feedstock creates procurement risk for neonatal securement manufacturers. Distribution runs through hospital GPO contracts and specialized medical device distributors with cold-chain capabilities for temperature-sensitive adhesive formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Catheter stabilization devices represent a service-attach opportunity where post-market surveillance and clinical training subscriptions expand faster than hardware unit sales, particularly as EU MDR Article 10 obligations mandate continuous safety data collection beyond initial device clearance.
For Market Incumbents: Consolidate regulatory affairs infrastructure to absorb extended FDA 510(k) and EU MDR validation timelines that smaller competitors cannot match. Deepen backward integration into hydrocolloid formulation supply to defend margin position against raw material volatility. Channel control through exclusive GPO contracts remains essential as hospital value analysis committees compress evaluation cycles.
For New Entrants and Emerging Players: Lead with neonatal care specialization in European tertiary centers where epidermal-integrity demands create premium positioning opportunities outside consolidated adhesive anchor markets. Target Japan's METI-supported home healthcare expansion for patient-applied ambulatory securement solutions. Partner with regional distributors possessing existing hospital relationships rather than building direct sales infrastructure.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across integrated securement-dressing systems as antimicrobial barrier convergence demands expanded R&D infrastructure. Five-to-ten year viability favors manufacturers with dedicated post-market surveillance capabilities and dual-track FDA-EU regulatory expertise. Monitor FDA guidance on catheter-related bloodstream infection prevention as signal for hospital purchasing criteria shifts toward validated securement accessories.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Article 10 Compliance Investment | Post-market surveillance infrastructure satisfies elevated clinical evaluation requirements for German hospital procurement. |
| Hospital GPO Contract Consolidation | Exclusive supply agreements with United States group purchasing organizations lock out emerging competitors from volume tiers. |
| Hydrocolloid-Silicone Hybrid Development | Moisture-responsive gentle-release formulations capture neonatal ICU preference in Tübingen and Aachen centers. |
| Japanese Home Healthcare Channel Entry | METI-supported ambulatory infusion expansion creates distribution pathway for patient-applied securement devices. |
| ISO 10993 Biocompatibility Certification | Material safety documentation filters subscale suppliers and consolidates procurement toward validated manufacturers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and GPO contract disclosures. Primary interviews engaged regulatory affairs directors, biomedical engineers, hospital purchasing committee members, and GPO contracts managers across the United States, Germany, and Japan. Secondary validation drew from SEC 10-K disclosures, customs trade data, and ISO 10993 testing laboratory records. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the analysis window.
Segmentation dimensions modeled include product type, application setting, end-user procurement authority, and material technology chemistry across the projection horizon. CAGRs derived from weighted scenario analysis incorporating regulatory timeline probabilities, replacement cycle acceleration factors, and channel migration patterns. Forecast inputs incorporated EPA solvent emission compliance cost trajectories and medical-grade silicone supply concentration indices.
The analysis sits within stated boundaries; outcomes outside sustained FDA-EU regulatory convergence or unanticipated raw material supply disruptions would require recalibration. Forecasts reflect documented assumptions regarding hospital infection prevention bundle adoption rates and home healthcare discharge protocol permanence. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Organ Care Systems (OCS) Market
Medical Devices
Phototherapy Lamps Market
Medical Devices
Global Artificial Skin Market
Medical Devices
Electrophysiology Market
Medical Devices
Soft Tissue Release Systems Market
Medical Devices
Automated CPR Devices Market
Medical Devices
Injection Pen Market
Medical Devices
Global Infusion Pump Software Market
Medical Devices
Robotic Hair Transplant System Market
Medical Devices
IV Equipment Market
Medical Devices
Smart Bassinet Market
Medical Devices
Electrosurgical Devices Market
Medical Devices
North America Portable Medical and Healthcare Devices Market
Medical Devices
Asia-Pacific Intraoral Scanners Market
Medical Devices
Global Body Composition Analyzers Market
Medical Devices
France Contraceptive Devices Market