
 Skin Revitalizing Handheld Devices Market | 2026-2036
Skin Revitalizing Handheld Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Skin Revitalizing Handheld Devices Market Analytics
Med-spa chains and aesthetic clinics are restructuring the professional end-user segment as they scale multi-location service menus beyond traditional dermatology. Lumenis anchors its position through R&D intensity in fractional radiofrequency platforms. FOREO competes in the consumer tier with compact ultrasonic form factors. Nu Skin Enterprises controls direct-to-consumer channels across Asia-Pacific markets.
Skin revitalizing handheld devices are portable electromechanical instruments that deliver controlled energy—typically 1-3 MHz ultrasonic waves, 0.3-1.0 MHz radiofrequency, or 400-700 nm LED wavelengths—to dermal and subdermal tissue for non-invasive cosmetic treatment. Radiofrequency and microcurrent device types dominate professional procurement due to higher per-treatment efficacy and clinical validation requirements. LED light therapy technology sustains the fastest consumer adoption curve given lower price points and home-use safety profiles. Wrinkle reduction and skin tightening applications occupy the deepest margin pools as aging demographics prioritize collagen-stimulating interventions.
FDA 510(k) clearance requirements and the EU Medical Device Regulation shape product development timelines and market access barriers for manufacturers seeking dual-territory distribution. ISO 13485 quality management standards and IEC 60601-1 electrical safety protocols further constrain design choices for devices incorporating thermal or electrical stimulation. Stakeholders must monitor evolving classification thresholds as regulators reassess borderline cosmetic-medical device distinctions.
Market Dynamics
Professional-grade radiofrequency and microcurrent units are concentrating procurement power within dermatology clinic chains and med-spa networks, compressing margins for device manufacturers while elevating clinical validation requirements as the central competitive filter.
Growth Catalysts
- FDA 510(k) pathway maturation:Streamlined pre-market notification for Class II devices with predicate equivalence is accelerating clearance timelines for radiofrequency platforms targeting wrinkle reduction applications.
- South Korea MFDS cosmetic-medical borderline guidance:Clearer classification thresholds for home-use LED devices are reducing regulatory uncertainty and enabling faster product launches in the Asia-Pacific consumer tier.
- Med-spa chain consolidation:Multi-location aesthetic service providers are standardizing device procurement across portfolios, creating volume commitments that justify manufacturer R&D investment in modular platform architectures.
Market Restraints
- EU MDR technical documentation burden:The Medical Device Regulation's intensified clinical evidence requirements for electrical stimulation devices are extending time-to-market by 18-24 months for manufacturers lacking notified body relationships.
- GaN semiconductor supply concentration:Gallium nitride components critical for compact radiofrequency generators face sourcing constraints from Taiwan and China-based foundries, creating input cost volatility.
- Topical retinoid substitution:Prescription and over-the-counter vitamin A derivatives remain cost-competitive alternatives for collagen stimulation, limiting price ceiling expansion in the consumer segment.
Strategic Opportunities
- Germany aesthetic clinic penetration:Underdeveloped med-spa density relative to dermatology offices in secondary cities offers white space for professional device placement with bundled service agreements.
- Ultrasonic-microcurrent convergence:Hybrid platforms combining 1-3 MHz ultrasound with galvanic current delivery are opening new treatment protocols for facial contouring applications previously requiring separate devices.
- Direct-to-consumer telehealth integration:Virtual consultation platforms are emerging as novel distribution channels enabling remote device prescription and compliance monitoring for home-use systems.
Industry Challenges
- Biomedical engineering talent scarcity:The intersection of dermatological science, electrical engineering, and regulatory affairs requires specialized expertise that remains concentrated in Boston, Seoul, and Stuttgart metropolitan clusters.
- ISO 13485 certification timeline:Quality management system implementation for startups without prior medical device experience typically requires 12-18 months before notified body audit readiness.
- Patent thickets around electrode geometries:Dense intellectual property landscaping in radiofrequency applicator designs is forcing licensing negotiations or design-around investments for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Skin Revitalizing Handheld Devices Market |
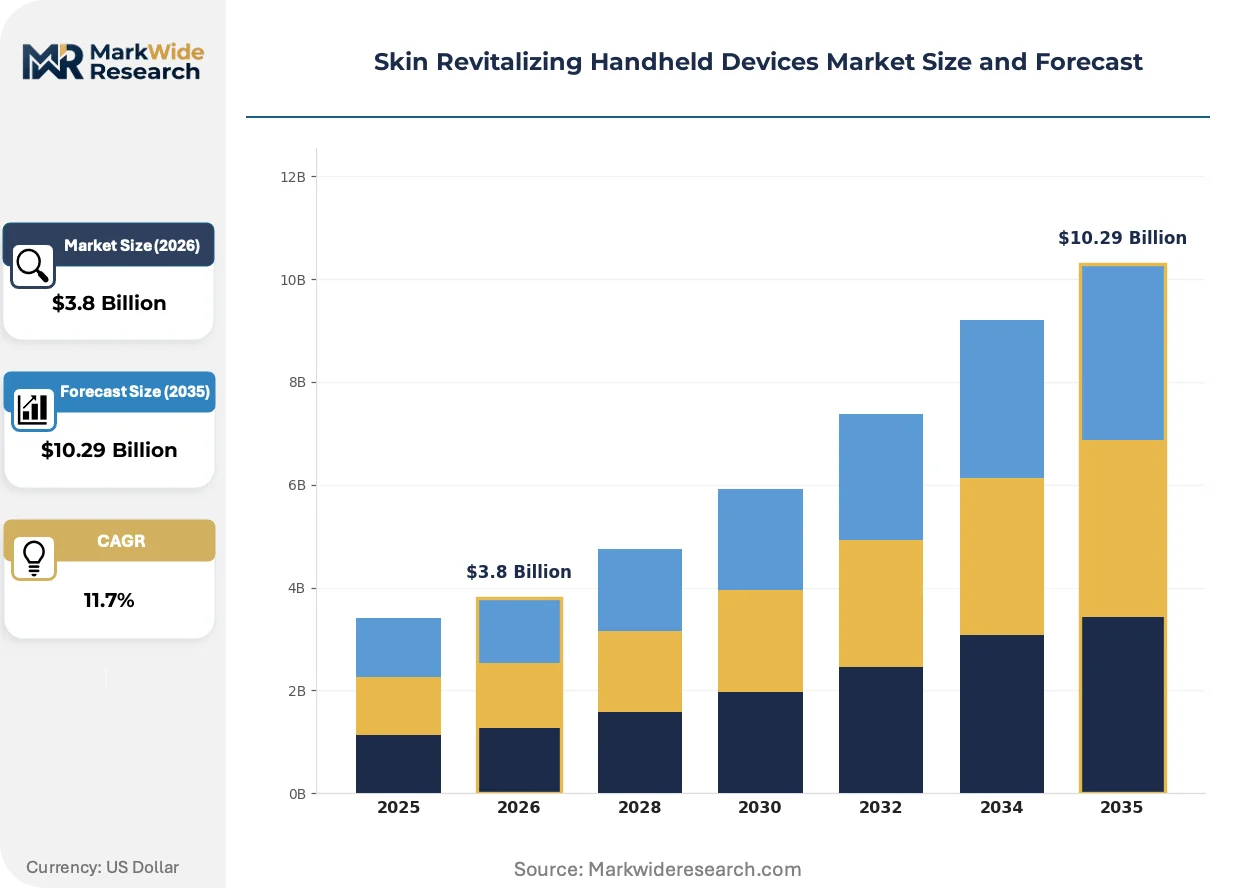
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: LED, Ultrasonic, Radiofrequency, Microcurrent Technology: Light Therapy, Thermal Therapy, Vibration Therapy, Electric Stimulation Application: Skin Tightening, Wrinkle Reduction, Acne Treatment, Hydration End User: Consumers, Professionals, Aesthetic Clinics, Spa Chains |
| Companies Covered | Lumenis, Cutera, Inc., Syneron Candela, Alma Lasers, Philips, Panasonic Corporation, FOREO, Nu Skin Enterprises, NIRA Skincare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Skin Revitalizing Handheld Devices Market Evolving Landscape
Device architectures are converging around multi-modal energy delivery platforms, while regulatory frameworks on both sides of the Atlantic recalibrate safety thresholds for home-use electrical stimulation systems. These forces are compressing product development cycles and reshaping competitive differentiation.
Multi-modal handheld systems are unifying radiofrequency, microcurrent, and LED capabilities within single chassis designs. Dermatology clinics in the United States are adopting these consolidated platforms to maximize treatment room utilization and reduce capital equipment footprint. This convergence is unifying previously separate device categories into standardized platform ecosystems that lock in consumable revenue streams and complicate single-technology competitor positioning.
EU MDR Annex XVI expansion is reclassifying certain high-intensity home-use devices as medical devices requiring notified body intervention. Manufacturers targeting European distribution are restructuring quality management systems and clinical evaluation reports to address the regulation's intensified post-market surveillance obligations. Professional-grade radiofrequency units with thermal injury risk profiles face the steepest compliance burden, prompting some brands to restrict European availability to clinical channels exclusively.
Subscription-based device access models are displacing outright purchase arrangements in the United States consumer segment. Med-spa chains and aesthetic clinics are piloting hardware-as-a-service programs that bundle device leasing with consumable supplies and training certification. This shift is most visible in California and Florida, where capital-light expansion strategies dominate multi-location rollouts and operational flexibility outweighs depreciation tax advantages.
Skin Revitalizing Handheld Devices Market Segmentation
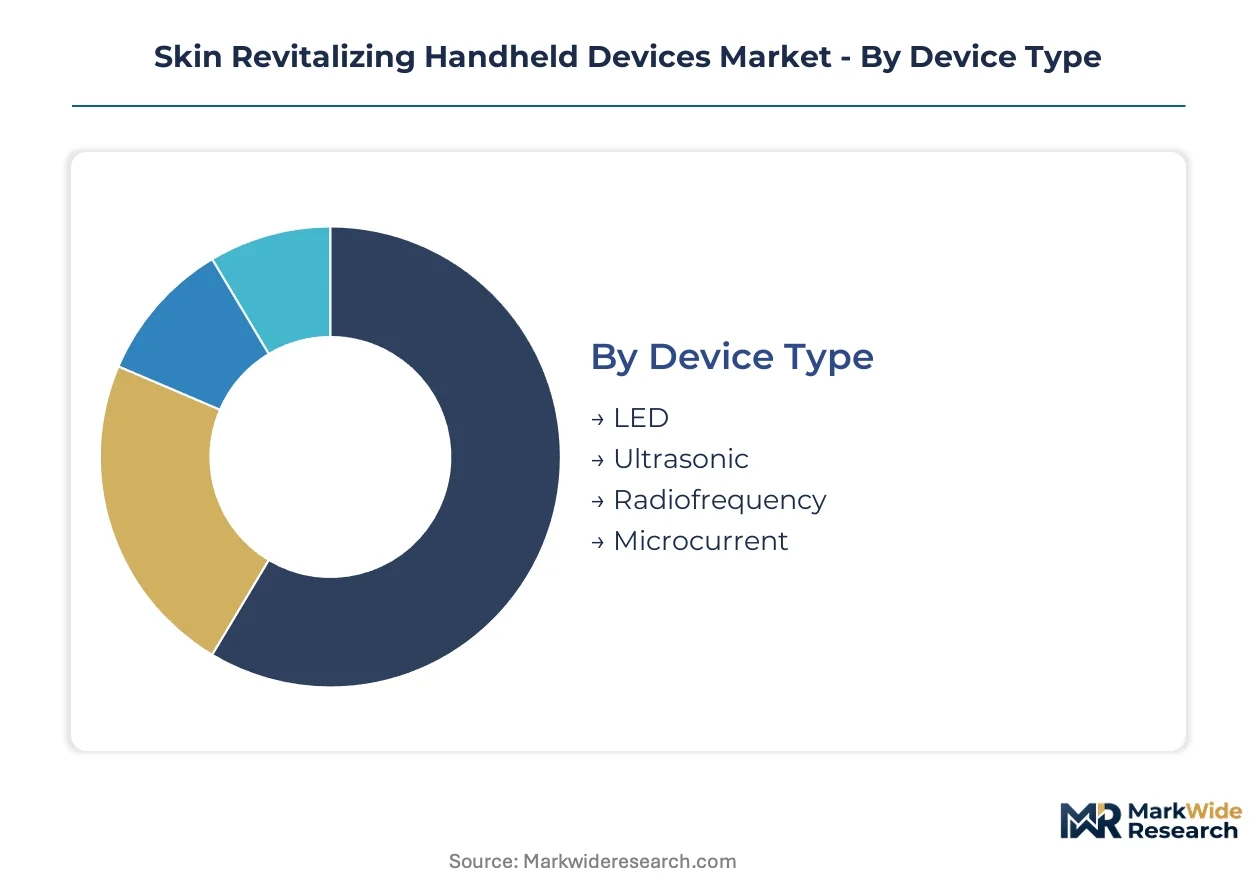
Segmentation in skin revitalizing handheld devices reveals how technical specifications, clinical validation requirements, and distribution channels fragment procurement decisions across professional and consumer tiers. Manufacturers must align platform architectures with distinct margin structures and regulatory pathways governing each category.
Device Type:
Standardization dominates LED and ultrasonic formats for home use, while radiofrequency and microcurrent units require greater customization for professional settings with adjustable energy parameters.
- LED:Compact arrays emitting 400-700 nm wavelengths target home-use safety profiles and price accessibility. Demand clusters in United States direct-to-consumer channels where FDA cosmetic classification avoids medical device overhead. Lower regulatory burden accelerates product refresh cycles.
- Radiofrequency:Thermal delivery systems operating at 0.3-1.0 MHz penetrate subdermal tissue for collagen remodeling. Dermatology clinics in Germany and South Korea concentrate procurement, driven by clinical evidence requirements and per-treatment efficacy premiums that justify capital investment.
- Ultrasonic:1-3 MHz acoustic wave platforms enable topical product penetration without thermal injury risk. Compact form factors suit Asian consumer markets seeking portable solutions.
- Microcurrent:Low-level electrical stimulation devices target facial muscle toning with sub-sensory current delivery. Professional certification requirements limit distribution to trained aesthetic practitioners.
Leading the category by volume: LED. Growing fastest: Radiofrequency.
Technology:
Cost tiers separate premium thermal and electric stimulation platforms from accessible light and vibration modalities, with reimbursement eligibility and clinical outcome data determining placement.
- Light Therapy:Photobiomodulation systems leverage discrete wavelength specificity for targeted chromophore absorption. Consumer adoption in South Korea and United States reflects home-use convenience and minimal contraindication profiles.
- Thermal Therapy:Controlled dermal heating induces neocollagenesis through denaturation thresholds. Professional applications in aesthetic clinics command premium pricing supported by visible single-session outcomes and liability protocols.
- Vibration Therapy:Mechanical oscillation enhances lymphatic drainage and product absorption. Lower price points and intuitive operation expand mass-market penetration.
- Electric Stimulation:Microcurrent and radiofrequency energy delivery requires precise impedance matching and electrode design. Regulatory complexity restricts deployment to clinical channels with trained operators.
Dominant by margin contribution: Thermal Therapy. Expanding most quickly: Light Therapy.
Application:
Volume concentration in anti-aging applications contrasts with specialized therapeutic uses, while hydration represents an emerging crossover between cosmetic and dermatological positioning.
- Skin Tightening:Collagen contraction and remodeling interventions address laxity in facial and neck zones. Med-spa chains in California and Florida standardize radiofrequency protocols across multi-location portfolios, creating bundled service revenue streams.
- Wrinkle Reduction:Rhytid-targeting modalities concentrate the deepest margin pools as aging demographics prioritize visible intervention. United States and German aesthetic clinics allocate premium device budgets to platforms with comparative clinical photography documentation.
- Acne Treatment:Blue light antimicrobial and seboregulatory applications target younger demographics with recurrence management needs. Lower price elasticity supports consumer-tier LED adoption.
- Hydration:Ultrasonic and iontophoretic enhancement of topical delivery addresses barrier function and moisture retention. Positioning between cosmetic and therapeutic claims requires careful regulatory navigation.
Highest revenue concentration: Wrinkle Reduction. Steepest expansion trajectory: Hydration.
End User:
Customer type determines procurement scale, with aesthetic clinic chains consolidating volume commitments that reshape manufacturer R&D priorities and platform modularity requirements.
- Consumers:Individual purchasers prioritize safety certification, intuitive interfaces, and price accessibility below professional-grade thresholds. Direct-to-consumer channels in Asia-Pacific markets leverage e-commerce integration and influencer validation.
- Professionals:Licensed practitioners including aestheticians and nurses require training-supported devices with adjustable parameters and liability documentation. Procurement concentrates through specialty distributors with educational bundling.
- Aesthetic Clinics:Physician-supervised facilities demand clinical evidence packages, warranty structures, and consumable revenue attachment. United States dermatology practices prioritize FDA 510(k) clearance for malpractice coverage alignment.
- Spa Chains:Multi-location operators standardize equipment across portfolios to enable staff mobility and brand consistency. Hardware-as-a-service leasing models reduce capital intensity for rollouts in secondary markets.
Largest volume aggregate: Consumers. Fastest procurement growth: Spa Chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in Shenzhen and Incheon concentrate contract manufacturing capacity for radiofrequency generator assemblies. Med-spa chains in Seoul and Los Angeles anchor professional device procurement volumes. Regulatory divergence between FDA 510(k) pathways and EU MDR Annex XVI implementations fragments go-to-market sequencing.
United States
Dermatology clinic consolidation in California and Florida drives bulk procurement of multi-modal platforms. FDA 510(k) clearance timelines for Class II radiofrequency devices average 90-120 days with valid predicate claims. Boston and San Diego biomedical clusters host specialized engineering talent pools for electrode design and impedance matching systems.
South Korea
MFDS cosmetic-medical borderline guidance enables faster home-use LED device launches than peer jurisdictions. Gangnam district aesthetic clinics standardize hardware procurement across multi-location portfolios. Seongnam and Suwon manufacturing corridors supply compact ultrasonic transducers to domestic and export markets.
Germany
EU MDR technical documentation requirements extend time-to-market for electrical stimulation devices by 18-24 months. Stuttgart and Munich metropolitan areas concentrate ISO 13485-certified quality management expertise. Secondary cities in Bavaria and North Rhine-Westphalia show underdeveloped med-spa density relative to dermatology office penetration.
Japan
METI standards for home-use electrical appliances constrain maximum output parameters for consumer-tier microcurrent devices. Osaka-based aesthetic chains pilot subscription-based hardware access models. Kansai region manufacturing bases specialize in miniaturized GaN semiconductor packaging for portable radiofrequency generators.
China
NMPA medical device classification thresholds for intense pulsed light systems require clinical trial data for professional-grade platforms. Yangtze River Delta free trade zones host foreign-invested device assembly operations for Asia-Pacific distribution. Shenzhen electronics corridors supply LED array components and battery management systems.
Skin Revitalizing Handheld Devices Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with professional-tier procurement concentrating around clinically validated platforms while consumer channels fragment across price-accessible formats. The vendor base organizes into three tiers: premium clinical specialists with FDA-cleared portfolios, mid-market consumer brands leveraging direct-to-consumer distribution, and OEM fabricators supplying private-label devices. Consolidation pressure operates most intensely in the professional segment where med-spa chains demand standardized platform ecosystems. Strategic moves center on modular hardware architectures that enable consumable attachment and hardware-as-a-service leasing structures.
Within the premium clinical tier, Lumenis and Cutera occupy positions anchored by regulatory clearance depth and dermatology channel relationships. Alma Lasers and Syneron Candela exemplify the multi-technology platform approach unifying radiofrequency, laser, and light-based modalities within single manufacturer portfolios. FOREO and Nu Skin Enterprises represent the consumer-tier vector where compact form factors and influencer-driven marketing displace clinical validation as the primary purchase determinant.
| Leading Market Players |
|---|
| Lumenis |
| Cutera, Inc. |
| Syneron Candela |
| Alma Lasers |
| Philips |
| Panasonic Corporation |
| FOREO |
| Nu Skin Enterprises |
| NIRA Skincare |
| Others |
Value Network & Pricing Analysis
Biomedical engineering talent scarcity in the Boston-Seoul-Stuttgart corridor feeds directly into pricing-tier spreads, as labor-cost differentials between certified quality-management hubs and emerging assembly zones force manufacturers to stratify device positioning across premium clinical and accessible consumer tiers.
Pricing Analysis
Short lead-time premiums for FDA 510(k)-cleared radiofrequency platforms command pricing separation from spot-inventory LED devices facing cosmetic-classification discount pressure. Three-tier pricing structure across premium, standard, and economy levels rests on certification grade and after-sales service bundling. Cost compression in consumer-tier ultrasonic formats is intensifying because topical retinoid substitution limits ceiling expansion. Spa chains exhibit highest price sensitivity; dermatology clinics prioritize clinical evidence over unit cost.
Supply Chain Analysis
Regional distribution centers in Shenzhen and Incheon anchor hub-and-spoke patterns for Asia-Pacific device fulfillment. Manufacturing concentrates in China, South Korea, and Germany. Critical inputs include GaN semiconductors, ultrasonic transducers, and LED array components. Single-source vulnerability around Taiwan-based foundries creates sourcing risk. Distribution runs through specialty medical-device distributors with training-certification bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR technical documentation burden is compressing weaker manufacturers without notified body relationships, making this market a consolidation play where regulatory compliance investment separates viable competitors from exit-bound players.
For Market Incumbents: To counter patent thicket encumbrance around electrode geometries, Lumenis and Alma Lasers should deepen backward integration into GaN semiconductor sourcing while accelerating modular platform architectures that lock in consumable revenue across med-spa chain rollouts.
For New Entrants and Emerging Players: Enter via direct-to-consumer telehealth integration in Germany's secondary cities, where underdeveloped med-spa density relative to dermatology offices creates white space for remote device prescription and compliance monitoring services.
For Investors and Strategic Acquirers: The window for entry favors ISO 13485-certified mid-cap specialists with existing notified body relationships. Long-term viability hinges on regulatory clearance depth rather than consumer marketing scale. Watch FDA 510(k) clearance velocity as inflection indicator for professional-tier platform competitiveness.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Annex XVI compliance unlocks professional channel access across Stuttgart and Munich clinic networks. |
| Hospital System Partnership | Dermatology clinic chains in California standardize procurement through GPO contracts with training bundling. |
| Software Companion Development | Telehealth integration enables remote compliance monitoring for home-use microcurrent systems. |
| FDA Submission | 510(k) clearance with valid predicate claims accelerates malpractice insurance alignment for aesthetic practices. |
| Reimbursement Strategy | Clinical photography documentation supports wrinkle-reduction outcome claims for premium radiofrequency positioning. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews involving biomedical engineers, dermatology clinic procurement managers, med-spa chain operators, and notified body auditors. FDA 510(k) databases, MFDS cosmetic-medical guidance documents, EU MDR technical documentation, and ISO 13485 certification registries provided validation layers. Bottom-up device shipment estimates and top-down aesthetic services market sizing were triangulated for coherence.
Data-stream reconciliation across the projection horizon modeled device type, technology modality, application focus, and end-user tier segmentation. CAGRs were derived from fitted growth curves against historical clearance timelines and procurement pattern shifts. Forecast inputs incorporated GaN semiconductor supply constraints, regulatory pathway maturation, and med-spa chain consolidation velocity.
Revisions become necessary when EU MDR classification thresholds shift, FDA predicate equivalence standards tighten, or GaN foundry capacity constraints deepen. Forecasts reflect documented assumptions around regulatory timeline stability and professional channel penetration rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Electric Breast Pumps Market
Medical Devices
IV Fluid Monitoring Device Market
Medical Devices
Embryo Transfer Catheters Market
Medical Devices
Middle East and Africa Sperm Separation Devices Market
Medical Devices
Acellular Dermal Matrix Market
Medical Devices
North America Medical Device Regulatory Affairs Outsourcing Market
Medical Devices
Elbow Fixation Systems Market
Medical Devices
Europe Single-Use Medical Device Reprocessing Market
Medical Devices
Controlled-Release Drug Delivery Technology Market
Medical Devices
Mexico Ultrasound Devices Market
Medical Devices
Lancing Devices and Lancets Market
Medical Devices
Bone Growth Stimulators Market
Medical Devices
Pressotherapy Systems Market
Medical Devices
Global Vascular Embolization Devices Market
Medical Devices
Global Micro Guide Catheters Market
Medical Devices
IV Equipment Market