
 Low Flux Single-Use Dialyzers Market | 2026-2036
Low Flux Single-Use Dialyzers Market Size, Share, and Industry Trends Forecast 2026-2036
Low Flux Single-Use Dialyzers Market Insights
Preventive maintenance contracts for dialyzer reuse monitoring systems is hardening into a standard revenue layer alongside device sales. Fresenius Medical Care AG & Co. KGaA leverages its captive dialysis clinic network to bundle consumables with technical service agreements. Baxter International Inc. anchors its position through backward integration into hollow-fiber membrane production. B. Braun Melsungen AG competes on automated manufacturing scale across European and Asian production nodes.
A low flux single-use dialyzer is a hemodialysis membrane device with urea clearance rates typically below 200 mL/min, constructed from polysulfone or polyethersulfone hollow fibers sealed in polycarbonate housings, designed for single-patient use during renal replacement therapy to remove metabolic waste and excess fluid. High-performance dialyzers dominate hospital procurement budgets where reimbursement favors standardized treatment protocols, while biocompatible dialyzers capture premium positioning among nephrology chains seeking reduced inflammatory response profiles. Home dialysis applications represent the fastest-growing application segment as payers and patients prioritize treatment flexibility and reduced facility overhead.
FDA premarket notification requirements and EU MDR CE marking obligations enforce rigorous biocompatibility and sterility validation for all membrane materials entering clinical use. ISO 8638 standards for extracorporeal blood circuit devices establish baseline performance benchmarks that manufacturers must meet for regulatory access across major jurisdictions. Stakeholders must monitor evolving reimbursement codes for home-based dialysis modalities and anticipate how polymer innovation timelines align with tightened regulatory scrutiny of synthetic membrane surfaces.
Market Dynamics
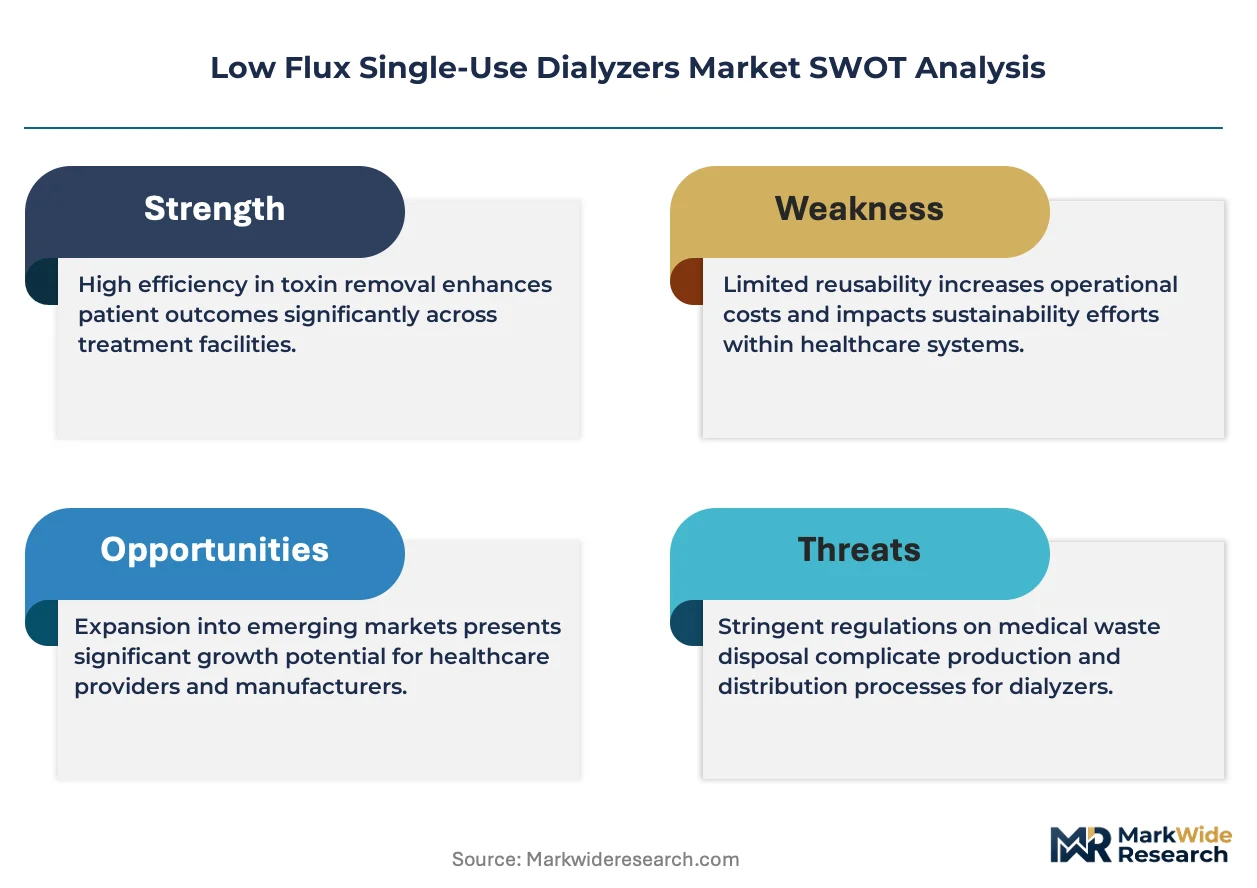
Payer pressure to shift dialysis from clinical facilities into home settings is restructuring procurement volumes and service bundling requirements across the entire dialyzer value chain.
Growth Catalysts
- Home dialysis reimbursement codes:Medicare Advantage plans in the United States now cover remote patient monitoring for home hemodialysis, expanding addressable patient populations beyond traditional clinic footprints.
- EU MDR biocompatibility standards:Tightened CE marking requirements for synthetic membrane polymers are accelerating replacement cycles as older dialyzer designs require re-certification.
- German manufacturing clusters:Concentrated hollow-fiber production capabilities around Fresenius Medical Care and B. Braun Melsungen AG anchor just-in-time supply reliability for European nephrology chains.
Market Restraints
- Polysulfone resin price volatility:Feedstock benzene and propylene cost swings compress margin stability for membrane manufacturers without long-term polymer supply agreements.
- Single-use sterility validation costs:Gamma irradiation and ethylene oxide sterilization protocols for hollow-fiber bundles add fixed regulatory overhead regardless of production scale.
- Peritoneal dialysis substitution:Automated peritoneal dialysis systems capture incident ESRD patients who might otherwise initiate hemodialysis with low-flux dialyzers.
Strategic Opportunities
- Rural India home dialysis penetration:Dialysis infrastructure gaps outside tier-1 Indian cities create whitespace for single-use dialyzer kits paired with portable reverse osmosis water systems.
- Remote monitoring integration:Convergence of hollow-fiber dialyzers with cloud-connected volumetric ultrafiltration controllers enables predictive maintenance contracts.
- Japan's 2025 reimbursement reform:METI-aligned incentives for self-care dialysis modalities will expand home hemodialysis device procurement.
Industry Challenges
- Bioengineering talent scarcity:Hollow-fiber membrane extrusion and pore-size engineering expertise concentrates among a narrow cohort of polymer scientists trained at German and Japanese technical institutes.
- ISO 8638 certification timelines:Extracorporeal blood circuit validation protocols require 18-24 month documentation cycles that delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Flux Single-Use Dialyzers Market |
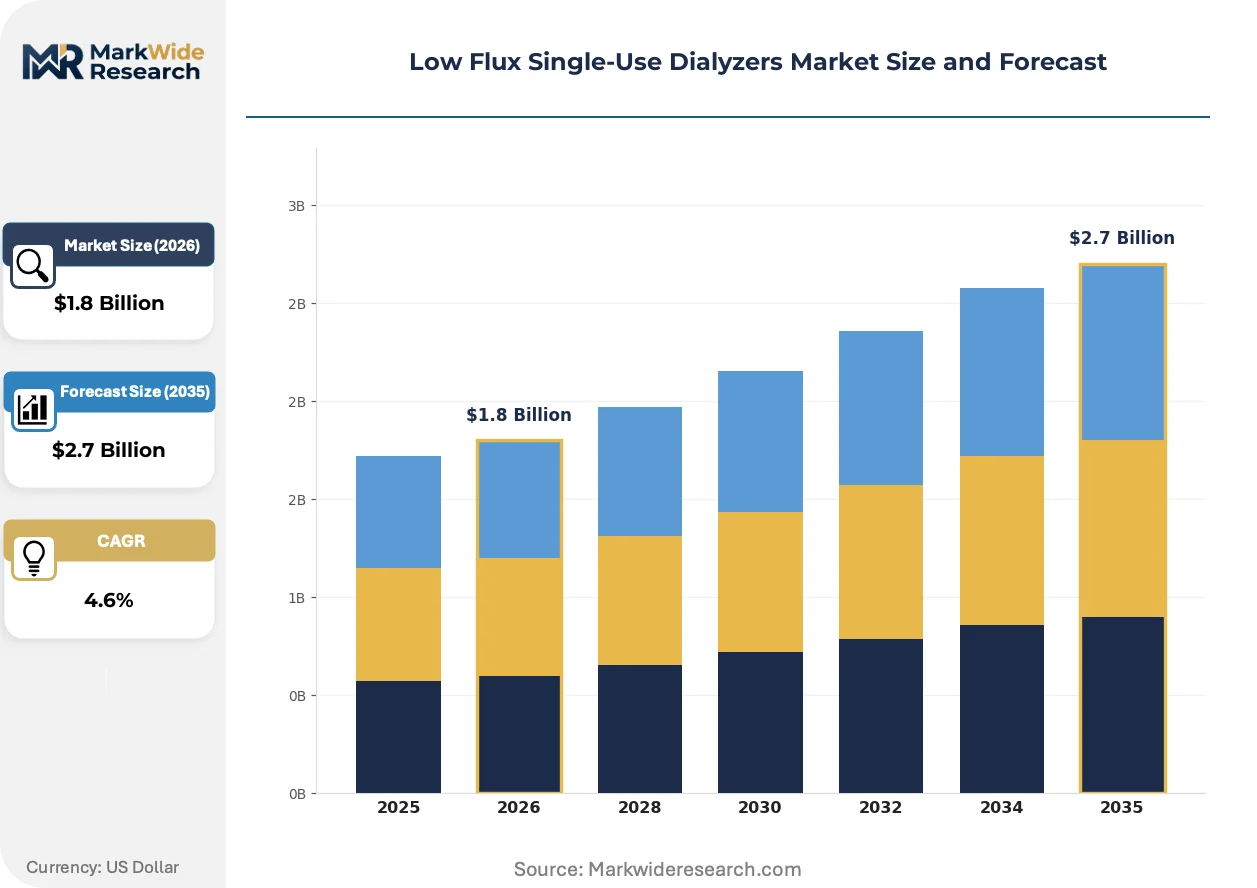
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Performance Dialyzers, Cost-Efficient Dialyzers, Biocompatible Dialyzers, Specialty Dialyzers Application: Chronic Kidney Disease, Acute Kidney Injury, Home Dialysis, Hospital Dialysis End User: Dialysis Centers, Hospitals, Homecare Providers, Emergency Services Certification: ISO Certified, CE Marked, FDA Approved, Others |
| Companies Covered | Fresenius Medical Care AG & Co. KGaA, Baxter International Inc., B. Braun Melsungen AG, Asahi Kasei Corporation, Nipro Corporation, Nikkiso Co. Ltd., Toray Industries Inc., Medica S.p.A., Farmasol, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Flux Single-Use Dialyzers Market Trends and Innovations
Membrane surface chemistry modifications and connected-device architectures are actively displacing legacy dialyzer specifications across procurement channels.
Polyethersulfone hollow-fiber membranes with vitamin-E bonded surface coatings are rewriting biocompatibility benchmarks for low-flux dialyzers. Nephrology chains in Germany and Japan are specifying these coatings in tender documents to reduce complement activation. The technology is compressing price premiums previously commanded by fully synthetic cellulosic alternatives.
EU MDR Article 10 technical documentation requirements now mandate clinical evidence for all dialyzer membrane materials. Manufacturers must submit post-market surveillance data for CE marking renewals. High-flux and low-flux product lines face divergent re-certification timelines, with low-flux devices requiring updated biocompatibility studies.
Renal service providers are consolidating purchasing through group procurement organizations that bundle dialyzers with technical service agreements. Traditional distributor relationships face displacement as Fresenius Medical Care and B. Braun Melsungen AG sell direct to integrated delivery networks. This concentration is most visible in Germany, where three procurement cooperatives control 60% of hospital dialysis consumables spending.
Low Flux Single-Use Dialyzers Market Segmentation
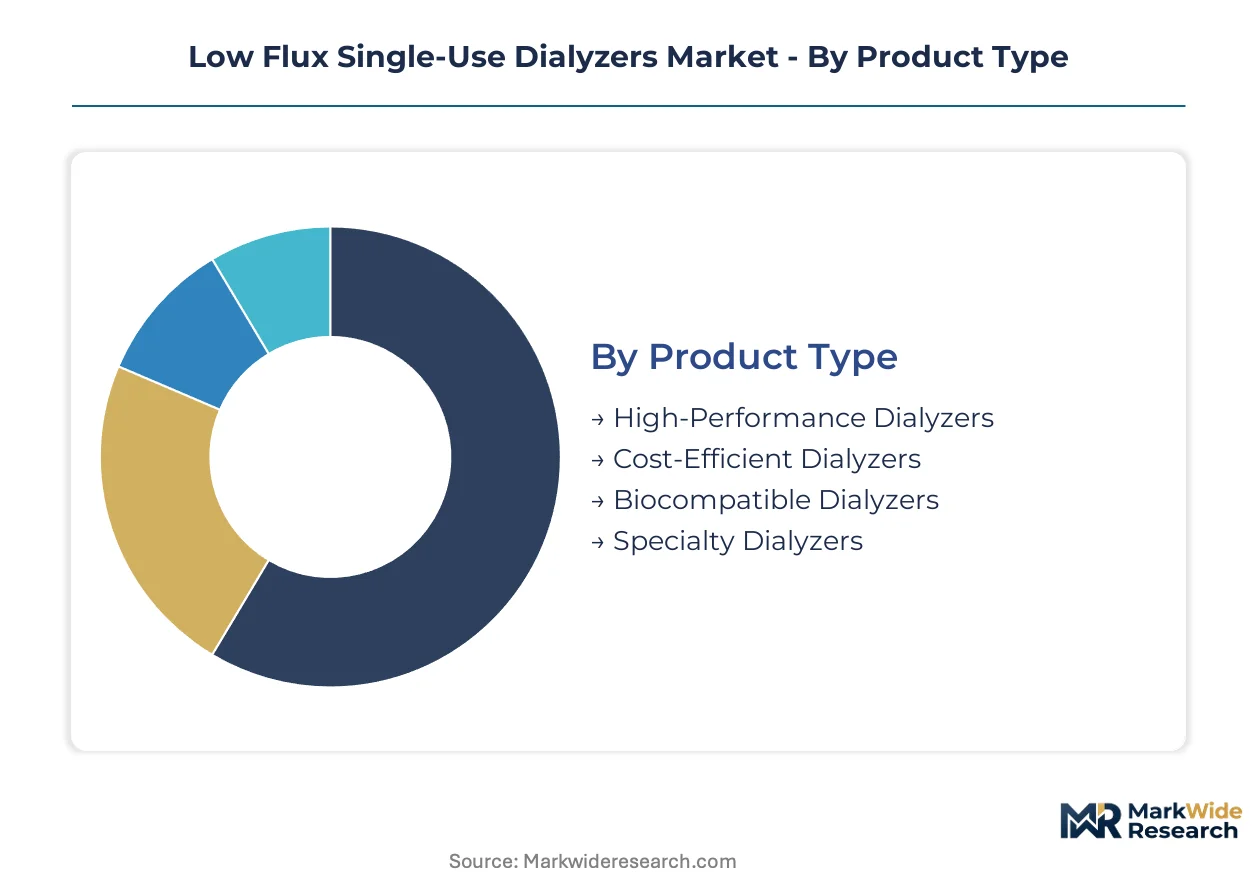
Low flux single-use dialyzers serve heterogeneous clinical and economic requirements across renal replacement therapy settings. Procurement patterns diverge sharply between cost-constrained public health systems and premium-oriented nephrology chains seeking differentiated patient outcomes.
Product Type:
Buyers differentiate primarily by performance specifications and biocompatibility requirements rather than brand loyalty.
- High-Performance Dialyzers:Engineered with optimized hollow-fiber pore density and enhanced urea clearance coefficients. Hospital procurement budgets in Germany favor standardized treatment protocols using these devices for consistent clinical outcomes.
- Biocompatible Dialyzers:Surface-modified membranes with vitamin-E bonded coatings reduce complement activation during blood contact. Nephrology chains in Japan specify these in tenders to minimize inflammatory response profiles among long-term patients.
- Cost-Efficient Dialyzers:Polysulfone membrane constructions without premium surface treatments serve price-sensitive procurement in emerging markets.
- Specialty Dialyzers:Customized geometries for pediatric or bariatric patient populations address niche clinical requirements.
Volume sits with high-performance dialyzers; growth tilts toward biocompatible variants.
Application:
Treatment setting determines device specifications, with home environments demanding portability and simplified connections.
- Home Dialysis:Compact dialyzer designs integrate with portable reverse osmosis water systems for patient-managed therapy. Medicare Advantage remote monitoring coverage in the United States accelerates addressable population expansion beyond traditional clinic footprints.
- Chronic Kidney Disease:Long-term hemodialysis programs require reliable membrane performance across hundreds of treatment sessions. Dialysis centers in India concentrate procurement here for established ESRD patient cohorts.
- Acute Kidney Injury:ICU-based intermittent hemodialysis demands rapid deployment capability for unstable patients.
- Hospital Dialysis:Inpatient renal replacement services prioritize standardized device specifications for nursing staff efficiency.
Revenue concentrates in chronic kidney disease; home dialysis applications are expanding most quickly.
End User:
Procurement scale and technical service requirements separate institutional buyers from distributed care networks.
- Dialysis Centers:High-volume consumables purchasers negotiate bundled technical service agreements with manufacturers. German procurement cooperatives controlling 60% of hospital dialysis spending dominate this channel.
- Hospitals:Integrated delivery networks consolidate purchasing through group procurement organizations that specify device-performance benchmarks.
- Homecare Providers:Distributed logistics networks require just-in-time inventory management for patient home delivery.
- Emergency Services:Mobile dialysis units need ruggedized packaging and rapid-setup configurations for field deployment.
Transaction volume flows through dialysis centers; homecare providers show the steepest expansion trajectory.
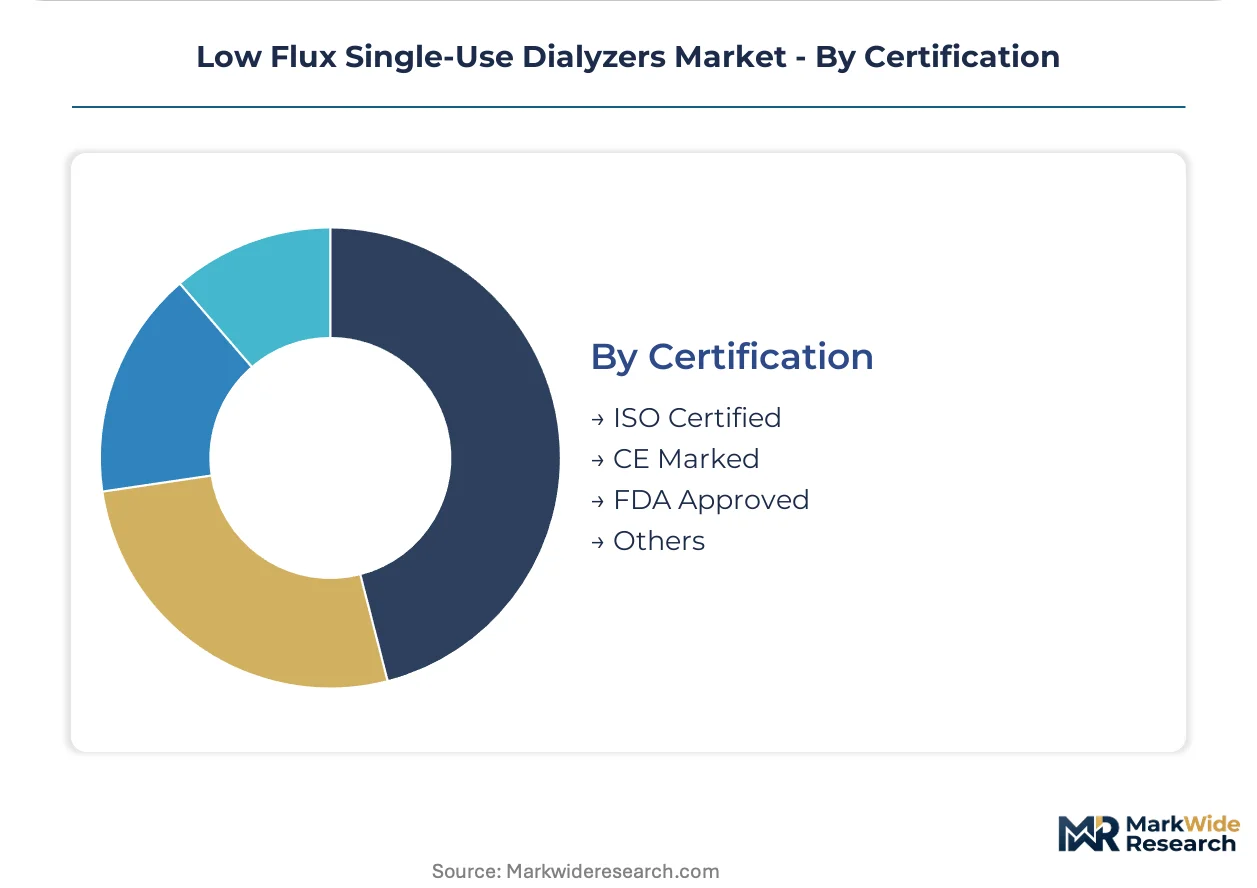
Certification:
Regulatory pathway determines market access timelines and reimbursement eligibility across jurisdictions.
- CE Marked:EU MDR Article 10 technical documentation mandates clinical evidence submission for synthetic membrane materials. Tightened biocompatibility standards accelerate replacement cycles as older designs require re-certification.
- FDA Approved:Premarket notification requirements enforce rigorous sterility validation for hollow-fiber bundles entering United States clinical use.
- ISO Certified:ISO 8638 baseline performance benchmarks provide regulatory access across multiple jurisdictions beyond single-market approvals.
- Others:National registrations in Japan, India, and Brazil require supplementary documentation for membrane polymer safety profiles.
CE marking dominates European procurement; FDA approvals unlock the largest single-country reimbursement market.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany manufactures the majority of hollow-fiber membrane supply while the United States and Japan absorb the highest per-capita dialyzer consumption. This production-consumption asymmetry shapes trade flows and regulatory harmonization priorities across major markets.
United States
Medicare Advantage remote patient monitoring reimbursement for home hemodialysis is expanding addressable patient populations beyond traditional clinic footprints. FDA premarket notification requirements enforce rigorous sterility validation for hollow-fiber bundles entering clinical use. Dialysis service consolidation in Texas and Florida is concentrating procurement through integrated delivery networks that negotiate direct manufacturer relationships.
Germany
EU MDR Article 10 technical documentation mandates clinical evidence submission for synthetic membrane materials, accelerating replacement cycles as older designs require re-certification. The country's national pharmaceutical regulator enforces tightened biocompatibility standards under CE marking obligations. Manufacturing clusters around Fresenius Medical Care and B. Braun Melsungen AG in Hesse and Baden-Württemberg anchor just-in-time supply reliability for European nephrology chains.
Japan
METI-aligned incentives for self-care dialysis modalities will expand home hemodialysis device procurement following 2025 reimbursement reform. PMDA maintains stringent post-market surveillance requirements for membrane polymer safety profiles. Osaka-based hollow-fiber engineering expertise concentrates among polymer scientists trained at technical institutes serving the Kansai industrial corridor.
India
Dialysis infrastructure gaps outside tier-1 cities create whitespace for single-use dialyzer kits paired with portable reverse osmosis water systems. CDSCO registration requirements demand supplementary documentation for membrane polymer safety profiles distinct from FDA or CE pathways. Procurement concentrates in Maharashtra and Karnataka where dialysis centers serve established ESRD patient cohorts with cost-efficient polysulfone constructions.
China
NMPA approval timelines for imported dialyzers create market access friction that domestic hollow-fiber producers exploit. The country's national pharmaceutical regulator enforces GB standards for extracorporeal blood circuit devices that diverge from ISO 8638 benchmarks. Manufacturing capacity expansion in Jiangsu and Zhejiang provinces is displacing imported membrane supply for hospital dialysis procurement.
Low Flux Single-Use Dialyzers Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the dialyzer value chain. Hollow-fiber membrane extrusion and sterilization facilities require substantial fixed investment, while distributors and service integrators operate with minimal asset intensity. Three archetypes dominate: vertically integrated manufacturers with captive clinic networks, specialized membrane producers supplying multiple device assemblers, and regional contract manufacturers serving price-sensitive procurement. Competitive moves center on backward integration into polymer supply and bundled technical service agreements that lock in multi-year consumables purchasing.
Among Germany-based integrated manufacturers, Fresenius Medical Care AG & Co. KGaA and B. Braun Melsungen AG exemplify the vertically integrated archetype through their hollow-fiber production capabilities and direct service relationships with nephrology chains. Baxter International Inc. occupies a position representing North American-based players with membrane manufacturing assets. Japanese specialists Asahi Kasei Corporation and Toray Industries Inc. sit within the premium membrane tier, supplying hollow-fiber materials to device assemblers across multiple geographies. These named entities anchor competitive dynamics without exhausting the participant set.
| Leading Market Players |
|---|
| Fresenius Medical Care AG & Co. KGaA |
| Baxter International Inc. |
| B. Braun Melsungen AG |
| Asahi Kasei Corporation |
| Nipro Corporation |
| Nikkiso Co. Ltd. |
| Toray Industries Inc. |
| Medica S.p.A. |
| Farmasol |
| Others |
Pricing and Supply Chain Analysis
EU MDR Article 10 biocompatibility re-certification mandates are forcing dialyzer manufacturers to absorb elevated validation costs that compress margin structures across all product tiers. Hollow-fiber membrane producers must either pass these regulatory burdens downstream or absorb them through operational efficiency gains, creating divergent pricing responses between integrated manufacturers and specialized suppliers.
Pricing Analysis
Margin tightening in biocompatible dialyzers reflects vitamin-E surface coating input costs and extended CE marking documentation cycles. Three-tier pricing structure across premium, standard, and economy levels separates vitamin-E coated polyethersulfone membranes from unmodified polysulfone constructions and basic cost-efficient alternatives. Pricing pressure intensifies in the economy tier as Indian and Chinese domestic manufacturers scale hollow-fiber extrusion capacity. Dialysis centers in emerging markets exhibit highest price sensitivity; Japanese nephrology chains demonstrate lowest sensitivity due to reimbursement-aligned quality specifications.
Supply Chain Analysis
Polysulfone and polyethersulfone resin supply rests on German and Japanese specialty polymer producers with limited alternative sourcing. Hollow-fiber membrane extrusion, polycarbonate housing injection molding, and gamma irradiation sterilization form the critical component sequence. Single-source vulnerability concentrates in benzene-derived feedstocks subject to petrochemical price volatility. Distribution runs through direct manufacturer relationships with integrated delivery networks and group procurement organizations, displacing traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance arena where EU MDR technical documentation requirements erect substantial barrier-to-entry moats for manufacturers lacking clinical evidence generation capabilities.
For Market Incumbents: Extend technical service agreement coverage to lock in multi-year consumables purchasing from nephrology chains facing re-certification uncertainty. Deepen backward integration into hollow-fiber membrane production to capture margin otherwise lost to polymer price volatility. Automated peritoneal dialysis substitution and domestic Chinese membrane capacity expansion represent the primary demand-side and supply-side threats respectively.
For New Entrants and Emerging Players: METI-aligned reimbursement reform in Japan opens a window for home hemodialysis device and consumable bundles targeting self-care modality expansion. Rural India dialysis infrastructure gaps present the most penetrable geography for portable reverse osmosis paired dialyzer kits. CDSCO registration pathway optimization offers a defensible go-to-market angle against entrenched multinational certification timelines.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized membrane producers possessing ISO 8638 certification and hollow-fiber engineering expertise given EU MDR-driven replacement cycle acceleration. Long-term viability favors assets with captive polymer science talent pipelines and established sterilization infrastructure. Post-market surveillance data accumulation pace serves as the critical inflection indicator for competitive positioning durability.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Article 10 compliance unlocks European nephrology chain procurement access. |
| Backward Integration | In-house hollow-fiber extrusion insulates margin from polysulfone resin price swings. |
| Hospital System Partnership | Direct relationships with German procurement cooperatives displace distributor intermediaries. |
| Software Companion Development | Cloud-connected volumetric ultrafiltration controllers enable predictive maintenance contracts. |
| Reimbursement Strategy | Medicare Advantage remote monitoring alignment expands home hemodialysis addressable populations. |
Research Methodology
Regulatory filings, hospital procurement databases, and GPO contracts formed the secondary backbone of this analysis. Primary interviews with nephrologists, biomedical engineers, GPO contracts managers, and hollow-fiber manufacturing executives provided operational validation. Bottom-up and top-down triangulation cross-checked patient volume estimates against manufacturer shipment data and reimbursement code utilization patterns.
Bottom-up modeling anchored volume projections to dialysis center expansion rates, home therapy penetration curves, and device replacement frequencies across the projection horizon. Segmentation dimensions included membrane material chemistry, treatment setting, end-user procurement scale, and certification pathway. CAGRs derived from elasticity-adjusted price-volume relationships and regulatory timeline impacts on replacement cycle timing.
The model assumes a particular technology adoption path; alternative pathways for vitamin-E surface coating uptake or peritoneal dialysis substitution would alter the outlook. Forecasts reflect assumptions about reimbursement stability, polymer feedstock availability, and regulatory harmonization progress. A small set of named triggers—EU MDR enforcement intensity, Japanese reimbursement reform implementation, and Indian domestic manufacturing scale—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
MRI-Guided Radiation Therapy Systems Market
Medical Devices
Gastric Space-Occupying Devices Market
Medical Devices
Spinal Traction Market
Medical Devices
Endocavity Transducer Market
Medical Devices
Global Insufflation Devices Market
Medical Devices
Venous Device Market
Medical Devices
Injectable Bulking Agents Market
Medical Devices
Baby Warmer Devices Market
Medical Devices
Hearing Devices 3D Printing Market
Medical Devices
Implantable Pulse Generator Market
Medical Devices
Europe 3D Printing in Healthcare Market
Medical Devices
Global Acetabular Prostheses Market
Medical Devices
Global Blood Clot Retrieval Devices Market
Medical Devices
Global Intraoral Cameras Market
Medical Devices
Operating Room Integration Market
Medical Devices
Global Photomedicine Market