
 Vaginal Specula Market | 2026-2036
Vaginal Specula Market Size, Share, and Industry Trends Forecast 2026-2036
Vaginal Specula Market Outlook
Single-use sterilization-grade specification is reorganizing procurement priorities across outpatient gynecology. CooperSurgical leverages its integrated manufacturing footprint to dominate disposable speculum supply chains in North America. BD sustains competitive positioning through R&D intensity focused on ergonomic polymer formulations. Medline Industries anchors hospital distribution networks with private-label speculum portfolios that compete on contracted volume pricing.
A vaginal speculum is a hinged or fixed medical instrument designed to dilate the vaginal canal for visual examination of the cervix and vaginal walls, typically manufactured from medical-grade stainless steel or polymer resins such as polystyrene or polycarbonate and subject to tensile strength and biocompatibility testing under ISO 10993. Its primary commercial purpose is to enable safe access for cervical cancer screening, IUD insertion, biopsy collection, and other diagnostic or surgical interventions. Plastic specula represent the fastest-growing product category as outpatient clinics prioritize elimination of autoclave reprocessing costs and cross-contamination liability. Among end users, ambulatory surgery centers command expanding share of premium disposable volumes due to higher throughput per procedure room and limited on-site sterilization infrastructure.
FDA 510(k) clearance requirements and ISO 13485 quality management standards govern device design controls, sterilization validation, and post-market surveillance for manufacturers distributing in the United States. The EU Medical Device Regulation imposes stricter clinical evidence and notified body oversight for specula marketed in Europe, elevating compliance costs for polymer-based single-use entrants. Stakeholders must monitor evolving Extended Producer Responsibility frameworks and state-level restrictions on single-use plastics that could force material transitions or deposit-return systems in key markets.
Market Dynamics
Single-use polymer specula are displacing reusable stainless steel instruments as ambulatory surgery centers eliminate autoclave infrastructure and liability exposure from sterilization failures.
Growth Catalysts
- FDA 510(k) pathway streamlining:Expedited clearances for polymer-based disposable designs accelerate manufacturer entry into outpatient channels.
- Ambulatory surgery center expansion:Freestanding facilities lacking on-site sterilization capacity drive premium disposable volume concentration.
- Polycarbonate material advances:Enhanced tensile strength and optical clarity in medical-grade polymers match stainless steel performance at lower per-procedure cost.
Market Restraints
- Petrochemical feedstock volatility:Polystyrene and polycarbonate resin prices fluctuate with crude oil indices, compressing margins for disposable manufacturers.
- EU MDR clinical evidence requirements:Stricter notified body oversight elevates compliance costs and extends time-to-market for polymer specula entrants.
- Reusable instrument refurbishment:Centralized sterilization services in hospital systems extend stainless steel economic life through reprocessing contracts.
Strategic Opportunities
- Extended Producer Responsibility frameworks:Deposit-return systems for medical plastics create service revenue streams and circular economy positioning.
- Telegynecology screening protocols:Remote diagnostic platforms expand speculum demand into home-based sample collection kits.
- ISO 10993 biocompatibility certification:Premium positioning through comprehensive cytotoxicity and sensitization testing opens hospital contract tiers.
Industry Challenges
- Sterilization validation expertise:FDA requirements for biological indicator testing strain quality assurance staffing at mid-scale manufacturers.
- Legacy instrument inventory:Hospital capital depreciation schedules delay replacement cycles for existing stainless steel sets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vaginal Specula Market |
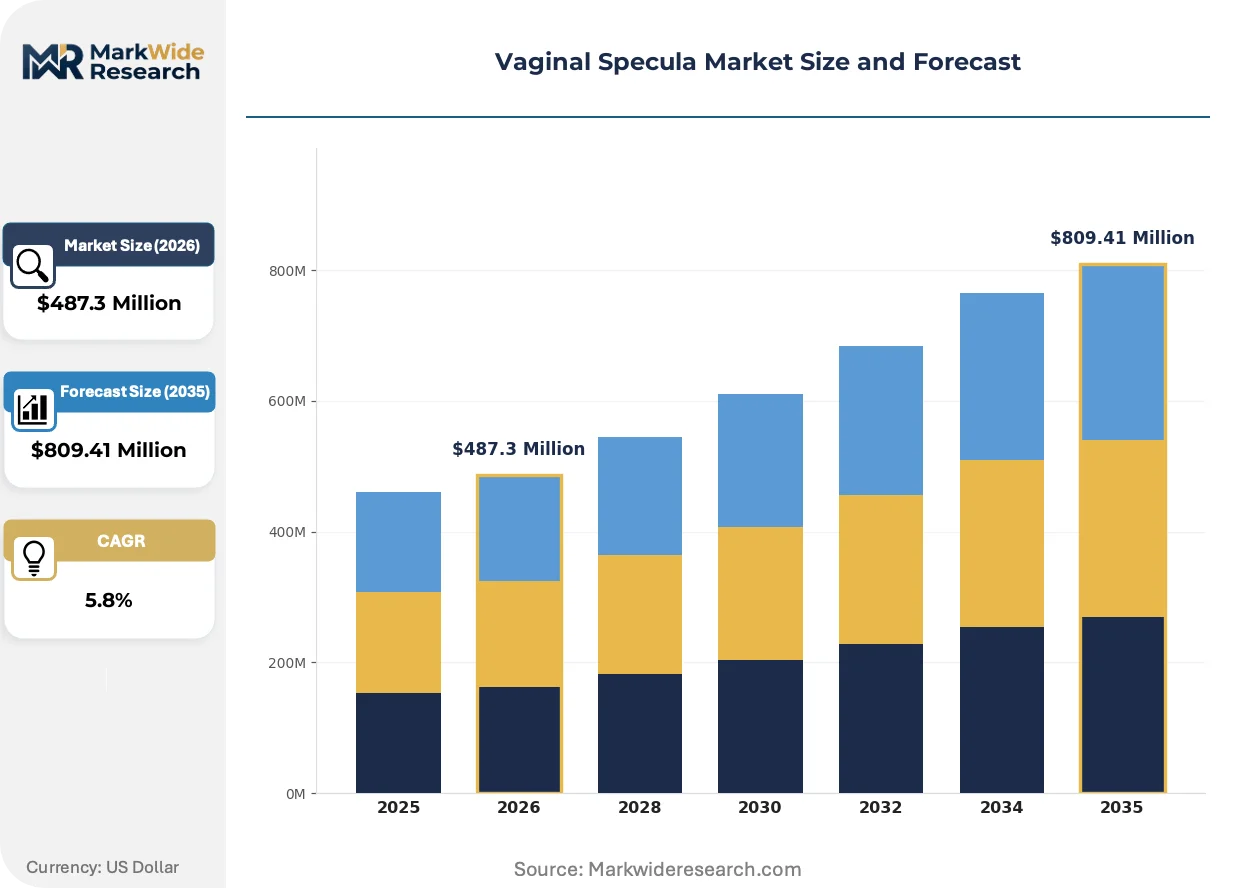
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Metal, Adjustable, Fixed Application: Gynecological Exams, Surgical Procedures, Diagnostics, Preventive Care End User: Hospitals, Clinics, Ambulatory Surgery Centers, Private Practices Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | CooperSurgical, BD, Integra LifeSciences, Medline Industries, B. Braun Melsungen AG, STERIS, MedGyn Products, Welch Allyn, Teleflex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vaginal Specula Market Strategic Shifts
Material science breakthroughs and regulatory pressure on reprocessing safety are compressing the transition timeline from metal to polymer specula across outpatient gynecology.
LED-integrated disposable specula are decomposing the traditional separate-light-source model by embedding illumination directly into polymer frames. Ambulatory surgery centers in the United States adopt these instruments at accelerating rates to eliminate cord management and cross-contamination risks. The convergence is decomplicating procedure room setup while compressing capital equipment budgets into per-procedure consumable costs.
EU Medical Device Regulation post-market surveillance requirements are forcing manufacturers to maintain clinical evidence registries for polymer specula marketed in Europe. Notified bodies now demand real-world performance data beyond initial 510(k) equivalency claims. Single-use polymer entrants face disproportionate compliance burden relative to established stainless steel suppliers with decades of safety documentation.
Hospital systems are consolidating gynecological supply contracts toward single-source disposable portfolios with guaranteed volume pricing. Group purchasing organizations negotiate multi-year agreements that lock out fragmented regional distributors. This concentration is most visible in United States metropolitan markets where health system mergers have reduced independent purchasing authority.
Vaginal Specula Market Segmentation
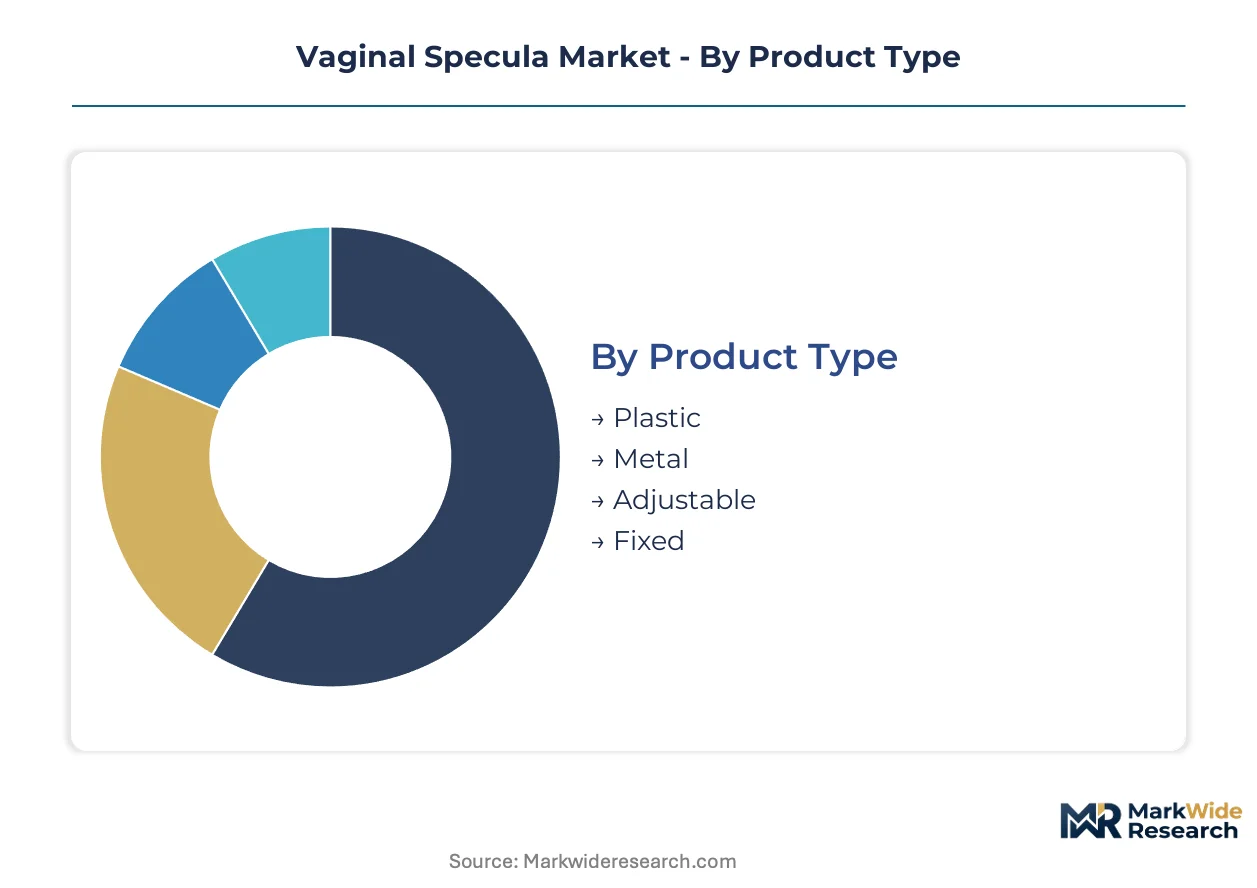
Segmentation in the vaginal specula market reveals how procurement priorities diverge across clinical settings and regulatory environments. Manufacturers must align product portfolios with distinct sterilization requirements, procedure volumes, and contracting structures that vary by end-user type and geography.
Product Type:
Domestic production concentrates on polymer-based disposable formats, while metal instrument manufacturing retains export orientation toward markets with established central sterilization infrastructure.
- Plastic:Medical-grade polystyrene and polycarbonate formulations eliminate autoclave reprocessing costs. Ambulatory surgery centers in the United States prioritize these instruments amid FDA sterilization validation requirements that strain smaller outpatient facilities.
- Metal:Surgical stainless steel instruments with reusable life cycles of 5-10 years under proper maintenance. Hospital systems in Germany and Japan sustain demand through centralized sterilization departments and capital depreciation schedules that delay replacement.
- Adjustable:Hinged designs with screw or lever mechanisms allowing intra-procedure dilation modification. Gynecological surgeons in high-volume academic medical centers specify these for complex diagnostic cases.
- Fixed:Single-position dilation instruments with lower per-unit manufacturing cost. Private practices in cost-sensitive markets select these for routine screening protocols.
Plastic holds the largest share; momentum sits with Adjustable formats as surgical precision requirements intensify.
Application:
Volume concentration follows reimbursement patterns, with preventive screening programs driving the highest procedure frequency and consumable turnover rates.
- Gynecological Exams:Routine cervical visualization for Pap smear collection and visual inspection. Federally qualified health centers in the United States consume substantial disposable volumes through consolidated purchasing agreements.
- Surgical Procedures:IUD insertion, biopsy collection, and minor operative interventions requiring speculum stabilization. Ambulatory surgery centers in metropolitan markets command premium pricing for sterilization-grade polymer instruments.
- Diagnostics:Colposcopy and directed biopsy applications demanding optical clarity and tissue access. European clinics under EU MDR post-market surveillance requirements favor suppliers with established clinical evidence registries.
- Preventive Care:Screening asymptomatic populations for cervical cancer precursors. National health programs in South Korea and Australia distribute specula through centralized procurement at substantial volume scale.
Gynecological Exams generate the highest absolute volume; Diagnostics commands the steepest expansion trajectory as precision requirements tighten.
End User:
Capital intensity and sterilization infrastructure availability determine whether facilities adopt disposable or reusable instrument strategies.
- Hospitals:Integrated delivery networks with captive sterilization departments and group purchasing organization contracts. These institutions balance disposable convenience against stainless steel lifecycle economics.
- Clinics:Outpatient facilities with moderate procedure volumes and limited on-site reprocessing capacity. Clinics in the United States increasingly outsource sterilization or convert to single-use polymers.
- Ambulatory Surgery Centers:Freestanding facilities optimized for throughput per procedure room without autoclave infrastructure. These end users represent the most concentrated demand for premium LED-integrated disposable specula.
- Private Practices:Independent physician offices with purchasing autonomy and space constraints. Practices in suburban and rural markets show highest sensitivity to per-procedure cost differentials.
Hospitals retain the largest installed base; Ambulatory Surgery Centers are gaining share fastest as outpatient migration accelerates.
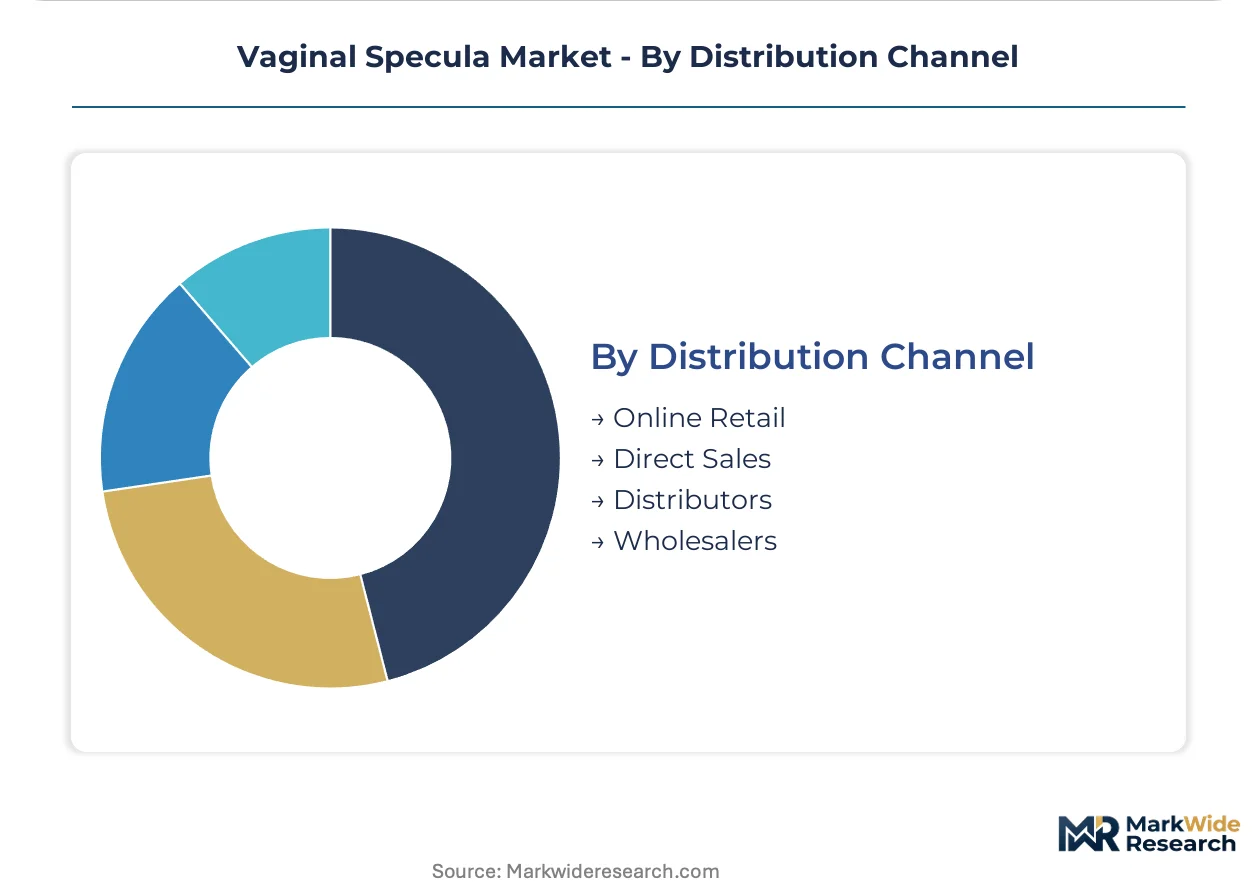
Distribution Channel:
Channel selection reflects customer scale, with high-volume accounts demanding direct manufacturer relationships and smaller purchasers relying on intermediary inventory management.
- Online Retail:E-commerce platforms serving individual practitioners and small practices with expedited fulfillment. These channels expand fastest in markets with fragmented provider landscapes.
- Direct Sales:Manufacturer field representatives negotiating multi-year contracts with health systems and group purchasing organizations. Direct relationships dominate United States metropolitan markets where hospital consolidation has reduced independent purchasing authority.
- Distributors:Regional medical supply intermediaries holding inventory and providing credit terms to mid-size clinics. Distributor networks remain essential in markets with geographic dispersion and logistics complexity.
- Wholesalers:High-volume, low-margin aggregators supplying commodity-grade instruments to cost-sensitive purchasers. Wholesaler channels concentrate in developing markets and public sector procurement.
Direct Sales captures the highest revenue concentration; Online Retail is expanding most quickly as procurement digitization penetrates smaller clinical settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in vaginal specula track divergent sterilization infrastructure across major economies. Net exporters of polymer disposables concentrate in markets with integrated medical device manufacturing, while stainless steel instrument trade persists where centralized reprocessing remains economically dominant.
United States
FDA 510(k) clearance volume for polymer specula outpaces all other jurisdictions, with ambulatory surgery centers in Texas and Florida driving premium disposable procurement. The agency's sterilization validation requirements for reusable instruments have accelerated outpatient conversion to single-use formats. Manufacturing clusters in Minnesota and Massachusetts supply domestic demand while exporting to Canadian and Mexican health systems under USMCA tariff preferences.
Germany
Centralized sterilization departments in university hospitals sustain demand for surgical stainless steel instruments with extended depreciation cycles. EU MDR notified body oversight from TÜV SÜD and DEKRA elevates compliance costs for polymer entrants, preserving incumbent metal instrument positions. The Baden-Württemberg medical technology corridor around Tuttlingen maintains precision machining capabilities for reusable speculum refurbishment services.
China
NMPA medical device registration reforms have streamlined domestic polymer speculum approvals, with Yangtze River Delta manufacturers scaling polycarbonate molding capacity. Hospital procurement consolidation under centralized purchasing platforms favors cost-competitive disposable formats. Shanghai-based distributors increasingly supply Southeast Asian clinics seeking alternatives to European stainless steel imports.
Japan
PMDA quality management requirements sustain premium positioning for domestic manufacturers serving aging population screening programs. Metropolitan Tokyo clinics adopt LED-integrated disposables for efficiency, while rural prefectures retain reusable instruments under regional health authority maintenance contracts. Osaka-based medical device trading houses mediate polymer speculum imports from South Korean and Taiwanese suppliers.
India
CDSCO medical device rules now classify specula as Class B devices, requiring manufacturing license upgrades that consolidate supply among organized sector producers. Government screening programs under the National Health Mission distribute fixed-format plastic specula through state medical supply corporations. Gujarat and Maharashtra polymer processors supply cost-optimized instruments to African and Middle Eastern export markets.
Vaginal Specula Market Competitive Environment
Listed leaders compete with private specialists across capital intensity and regulatory sophistication dimensions. Market structure shows moderate consolidation, with three to five integrated manufacturers commanding hospital system contracts while regional fabricators serve cost-sensitive clinic segments. Archetypes include sterilization-grade polymer specialists, stainless steel precision machinists, and private-label distributors leveraging group purchasing organization relationships. Competitive moves center on manufacturing footprint consolidation and sterilization validation service bundling.
Among North American integrated manufacturers, CooperSurgical and BD occupy positions spanning polymer formulation through hospital distribution, exemplifying the vertical control archetype that dominates premium contract tiers. Medline Industries represents the private-label volume strategy, anchoring contracted supply relationships through scale economics rather than proprietary technology differentiation. These three entities collectively illustrate how regulatory compliance depth and purchasing network breadth determine competitive position in consolidated procurement environments.
| Leading Market Players |
|---|
| CooperSurgical |
| BD |
| Integra LifeSciences |
| Medline Industries |
| B. Braun Melsungen AG |
| STERIS |
| MedGyn Products |
| Welch Allyn |
| Teleflex |
| Others |
Value Chain & Pricing Dynamics
FDA 510(k) clearance requirements gate both supply qualification and price differentiation in vaginal specula procurement, separating sterilization-validated polymer manufacturers from commodity-grade entrants while enabling premium positioning for compliant producers serving ambulatory surgery centers.
Pricing Analysis
Ambulatory surgery centers anchor a three-tier pricing structure across premium LED-integrated, standard disposable, and economy fixed-format instruments. Price differentiation rests on ISO 10993 biocompatibility certification grade and contracted volume scale through group purchasing organizations. Cost compression in economy tiers is intensifying because resin feedstock volatility squeezes margin buffers for mid-scale polymer molders. Private practices in rural United States markets exhibit highest price sensitivity, while integrated hospital networks with captive sterilization departments show lowest sensitivity due to lifecycle cost accounting.
Supply Chain Analysis
United States and China anchor medical-grade polymer speculum production, with Minnesota and Massachusetts clusters serving North American demand and Yangtze River Delta manufacturers scaling polycarbonate molding for Asian and export markets. Raw material dependencies center on polystyrene and polycarbonate resins, LED component modules, and medical-grade colorants. Single-source vulnerability concentrates in polycarbonate suppliers exposed to petrochemical price swings. Distribution runs through group purchasing organization contracts for hospital systems, direct manufacturer relationships for ambulatory surgery centers, and regional distributors for fragmented clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must navigate substitution defense against reusable stainless steel refurbishment services that extend economic life through centralized sterilization contracts in hospital systems.
For Market Incumbents: Consolidate manufacturing footprint control through captive polymer compounding capabilities to defend margin position against resin price volatility. Deepen sterilization validation service bundling to lock ambulatory surgery centers into multi-year disposable portfolios. Prioritize ISO 13485 quality management certification investment as FDA intensifies post-market surveillance requirements.
For New Entrants and Emerging Players: FDA 510(k) pathway streamlining offers fast-track entry into outpatient channels lacking legacy stainless steel infrastructure. Target ambulatory surgery centers in United States metropolitan expansion corridors where group purchasing organization contracts remain unsettled. Pursue private-label partnerships with Medline Industries or comparable distributors to bypass direct hospital sales force buildout.
For Investors and Strategic Acquirers: EU MDR clinical evidence requirements reshape the acquisition landscape toward targets with established notified body relationships and European clinical registries. Five-to-ten year viability favors sterilization-grade polymer specialists with backward integration into resin formulation. Monitor FDA guidance document releases on single-use plastic environmental impact as inflection indicator for material transition risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Sterilization Validation Service Bundling | Locks ambulatory surgery centers into multi-year disposable contracts amid FDA compliance pressure. |
| LED-Integrated Speculum Platform Launch | Captures premium pricing from outpatient facilities eliminating separate illumination capital equipment. |
| ISO 10993 Biocompatibility Certification Investment | Opens hospital contract tiers requiring comprehensive cytotoxicity and sensitization documentation. |
| Group Purchasing Organization Partnership | Secures volume concentration in United States metropolitan markets undergoing health system consolidation. |
| Extended Producer Responsibility Program Development | Positions for circular economy service revenue as state-level plastic restrictions expand. |
Study Parameters
Cross-validation between primary interviews with hospital purchasing committees, ambulatory surgery center administrators, biomedical engineers, and GPO contracts managers and secondary validation through FDA 510(k) filings, hospital procurement databases, CMS Medicare reimbursement data, and customs trade records anchors the qualitative findings. Bottom-up demand modeling from procedure volume data and top-down market sizing from manufacturer revenue disclosures complete the triangulation.
Sensitivity analysis across material cost scenarios, regulatory timeline variations, and ambulatory surgery center expansion rates informs the analytical framework. Segmentation dimensions modeled include product type, application, end user, and distribution channel across the projection horizon. CAGRs derive from procedure volume growth rates, price trajectory assumptions, and mix shift toward premium disposable formats.
Underlying assumptions cover sterilization infrastructure buildout rates, FDA enforcement intensity, and polymer resin price stability, with deviation risk concentrated in EU MDR implementation timelines and state-level single-use plastic legislation. Recalibration cycles align with material shifts in regulatory guidance, health system merger activity, and ambulatory surgery center licensing data.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Trocars Market
Medical Devices
Global Vascular Access Devices Market
Medical Devices
Self-Destructing Syringe Market
Medical Devices
Pharmaceutical Filtration Devices Market
Medical Devices
Pharmaceutical Robots Market
Medical Devices
Global Ultrasound Devices Market
Medical Devices
Global Medical Device Labeling Market
Medical Devices
Automatic Pill Dispenser Machine Market
Medical Devices
Morcellators Market
Medical Devices
Wearable Bioelectronic Skin Patches Market
Medical Devices
Photopheresis Products Market
Medical Devices
Sweden Ophthalmic Devices Market
Medical Devices
Pacemaker Devices Market
Medical Devices
Global Coronary Artery Bypass Graft Devices Market
Medical Devices
Stool Management Systems Market
Medical Devices
Medical Laser Cutting Device Market