
 Global Operating Table Mattresses Market | 2026-2036
Global Operating Table Mattresses Market Size, Share, and Industry Trends Forecast 2026-2036
Global Operating Table Mattresses Market Foresight
Pressure relief specification upgrades across hybrid and gel-filled constructions is redrawing competitive positioning in the Global Operating Table Mattresses Market. Skytron leverages its installed base of surgical tables to bundle mattress replacements, while Schmitz u. Soehne anchors European demand through specialized operating room furnishings. Eschmann Equipment differentiates via hospital-focused distribution channels in the United Kingdom and Ireland.
Operating table mattresses are engineered patient support surfaces, typically constructed with multi-layer polyurethane or memory foam cores bonded to antimicrobial covers, designed to distribute body weight and prevent pressure injuries during surgical procedures lasting two hours or longer. Pressure relief mattresses command premium positioning due to viscoelastic gel integration and extended procedure compatibility, while standard polyurethane configurations occupy high-volume replacement cycles in budget-constrained facilities. Hybrid constructions combining memory foam bases with gel-filled tops represent the fastest-growing material architecture as surgical centers seek dual-performance surfaces without full premium outlay.
FDA 510(k) clearance requirements and EU MDR technical documentation obligations shape product development timelines and market access costs for manufacturers serving North America and Europe. ISO 10993 biocompatibility testing and REACH compliance for foam additives further constrain material sourcing flexibility across the supply base. Stakeholders must monitor evolving pressure injury prevention protocols from WHO and OECD health quality frameworks, as clinical evidence requirements increasingly influence hospital procurement specifications and tender evaluation criteria.
Market Dynamics
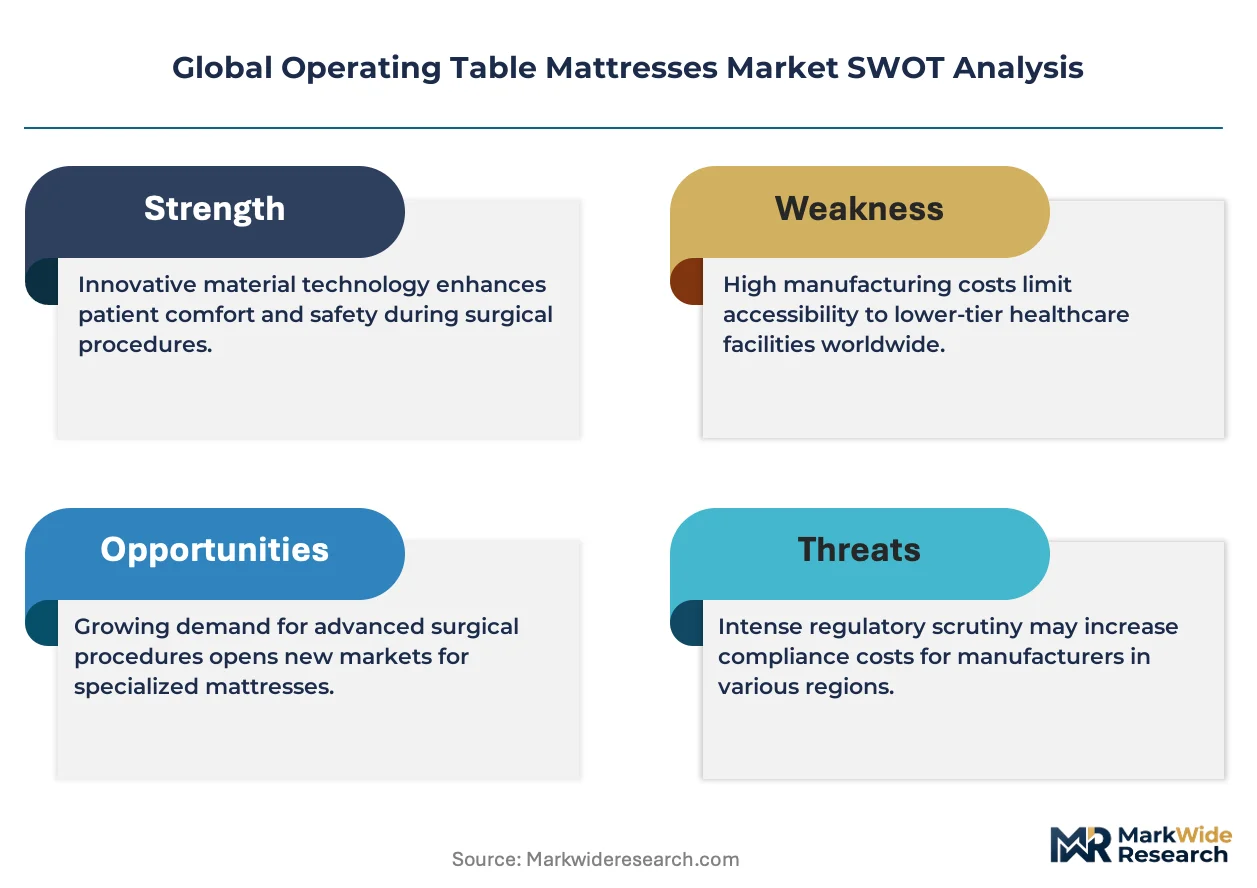
EU MDR technical documentation obligations and FDA 510(k) biocompatibility requirements are compressing product development timelines while elevating capital barriers for new entrants into patient contact surface manufacturing.
Growth Catalysts
- Pressure injury prevention protocols:WHO and OECD health quality frameworks mandate pressure redistribution surfaces for procedures exceeding two hours, expanding replacement cycles in tertiary hospitals across Germany, Japan, and the United States.
- REACH compliance evolution:ECHA restrictions on foam additive chemistries accelerate R&D investment in bio-based polyurethane alternatives, creating first-mover advantages for compliant European manufacturers.
- Ambulatory surgical center expansion:Freestanding ASCs in the United States and Germany procure hybrid gel-foam constructions to balance capital constraints against extended procedure compatibility.
Market Restraints
- Polyether polyol price volatility:Petrochemical feedstock fluctuations compress margin stability for foam core producers concentrated in German and US chemical corridors.
- ISO 10993 testing backlog:Biocompatibility evaluation queues at certified laboratories extend time-to-market by four to eight months for novel antimicrobial cover materials.
- Single-use positioning device substitution:Disposable gel pads for shorter procedures displace reusable mattress investments in cost-optimized outpatient settings.
Strategic Opportunities
- Underpenetrated Indian hospital infrastructure:CDSCO medical device rules implementation creates compliant market entry pathways for pressure relief surface manufacturers targeting tier-two city private hospital chains.
- Rental and service subscription models:Mattress-as-a-service contracts bundling preventive maintenance and cover replacement generate recurring revenue streams from German university hospital consortia.
- Sensor-integrated smart surfaces:Convergence of pressure mapping arrays with operating table control systems enables real-time tissue perfusion monitoring during neurosurgical and cardiac procedures.
Industry Challenges
- Polymer chemist talent scarcity:Formulation expertise for viscoelastic gel-foam bonding commands premium compensation in medical device hubs around Stuttgart and Minneapolis.
- Legacy table compatibility certification:Retrofit validation for fifteen-to-twenty-year-old surgical table installed bases fragments engineering resources across non-standard mounting interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Operating Table Mattresses Market |
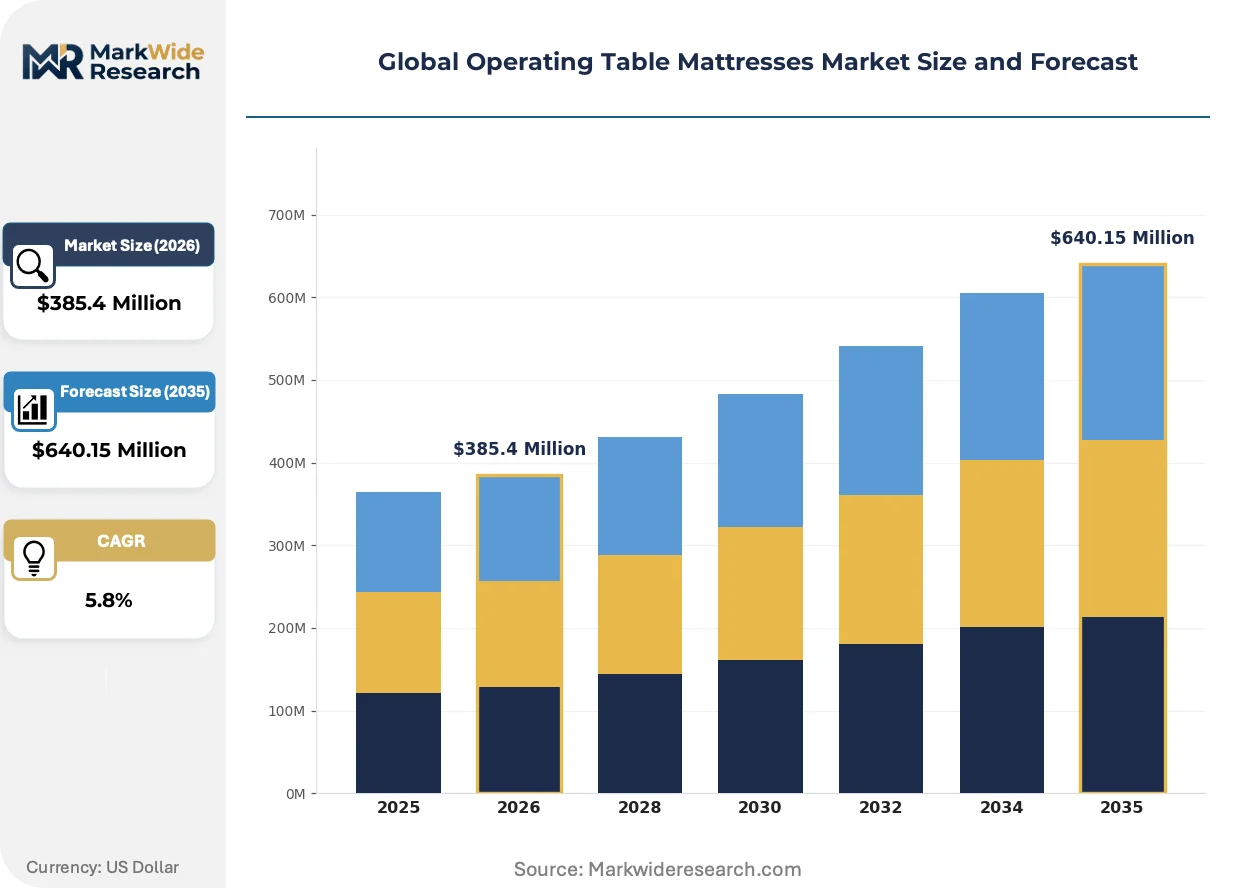
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Mattresses, Pressure Relief Mattresses, Gel-Filled Mattresses, Hybrid Mattresses Material: Polyurethane, Memory Foam, Latex, PVC End User: Hospitals, Surgical Centers, Ambulatory Surgical Centers, Specialty Clinics Feature: Antimicrobial, Waterproof, Easy Clean, Adjustable |
| Companies Covered | Anetic Aid, Teasdale, Ningbo Techart Medical Equipment, Mediland Enterprise, Schmitz u. Soehne, Sizewise, GEL A MED, Skytron, Eschmann Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Operating Table Mattresses Market Shifts & Advancements
Material science advances and regulatory documentation requirements are restructuring competitive advantage around biocompatibility certification depth rather than manufacturing scale alone.
Hybrid gel-memory foam laminates with zoned density gradients is supplanting uniform polyurethane cores in mid-tier hospital procurement specifications. German and Japanese surgical centers prioritize these constructions for bariatric and orthopedic procedures exceeding three hours. This material transition compresses addressable volume for standard foam producers while elevating technical service requirements for gel integration and delamination prevention.
FDA 510(k) predicate device pathways for patient contact surfaces tightened substantially in 2023, requiring substantial equivalence demonstrations for cover material changes previously qualifying as same-device modifications. Submissions now demand ISO 10993-5 cytotoxicity and ISO 10993-10 sensitization data for every foam additive above 0.1% concentration. US-based manufacturers with grandfathered predicates face retrospective compliance investments or portfolio rationalization.
Hospital procurement departments consolidate mattress specifications into system-wide framework agreements, displacing department-level purchasing autonomy. German hospital networks and US integrated delivery networks negotiate three-to-five-year sole-source contracts with performance guarantees on pressure injury incidence. This concentration rewards manufacturers with clinical evidence libraries and field service density in target metropolitan areas.
Global Operating Table Mattresses Market Segmentation
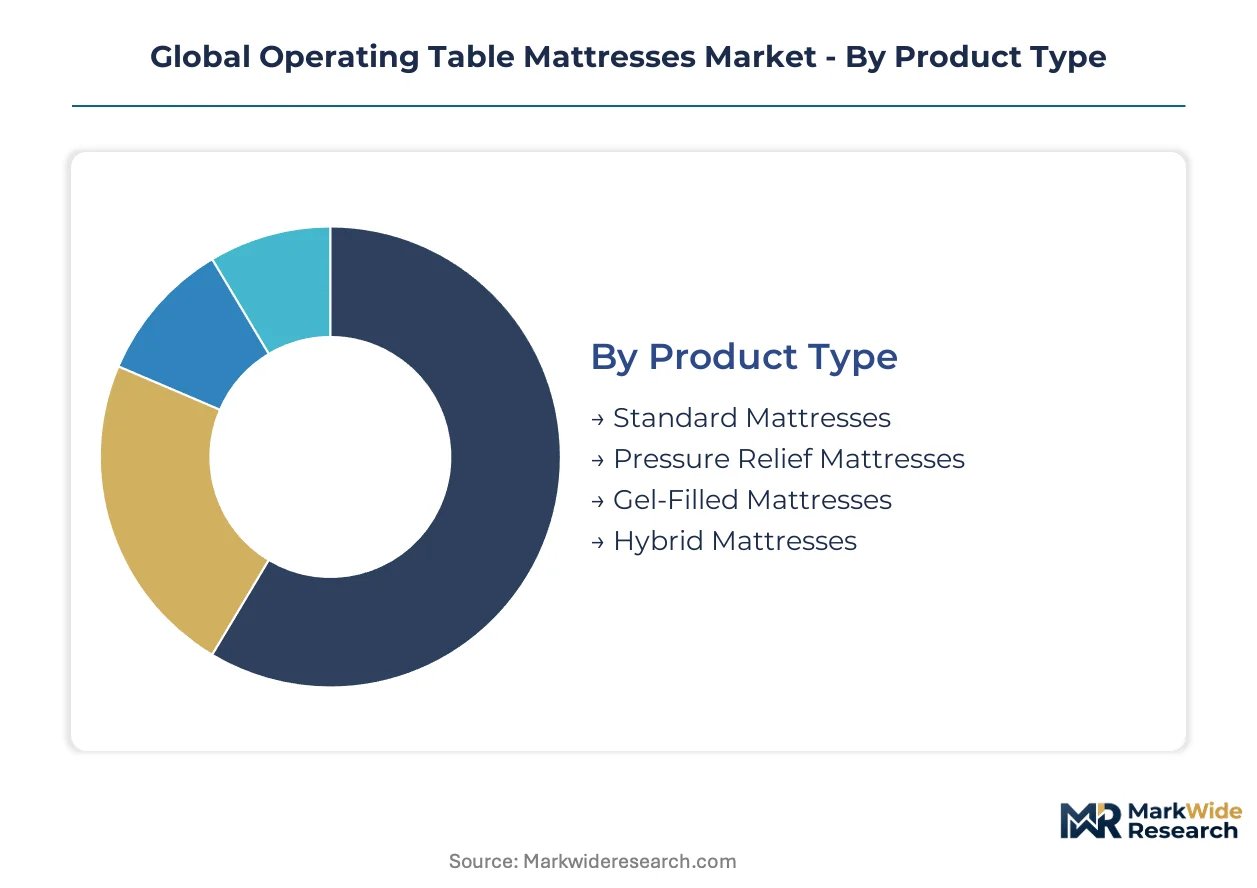
Operating table mattress procurement decisions split across clinical performance specifications, material compliance requirements, and facility capital constraints. Segmentation reveals where premium pricing power concentrates versus commoditized replacement volume.
Product Type:
Margin pools sit deepest in hybrid constructions that bridge premium pressure relief with accessible price positioning.
- Standard Mattresses:Multi-layer polyurethane cores with bonded antimicrobial covers serve high-frequency replacement cycles in budget-constrained facilities. Demand concentrates in German municipal hospital networks where procurement frameworks prioritize capital efficiency over extended procedure compatibility.
- Pressure Relief Mattresses:Viscoelastic gel integration redistributes body weight across zoned density gradients for procedures exceeding three hours. Japanese tertiary hospitals and US academic medical centers anchor demand as pressure injury prevention protocols tighten reimbursement exposure.
- Gel-Filled Mattresses:Liquid gel chambers maximize thermal dissipation during cardiac and neurosurgical interventions.
- Hybrid Mattresses:Memory foam bases laminated to gel-filled tops capture ambulatory surgical center expansion in the United States and Germany.
Standard mattresses hold installed capacity. Hybrid mattresses are rotating up the share rankings.
Material:
REACH compliance evolution and FDA biocompatibility documentation are fragmenting supply base viability across polymer categories.
- Polyurethane:Polyether polyol formulations dominate volume production but face margin compression from petrochemical feedstock volatility. German chemical corridor producers and US Gulf Coast foam manufacturers supply global replacement markets.
- Memory Foam:Viscoelastic polyurethane with slow recovery characteristics enables pressure redistribution without gel component costs. Demand clusters in Japanese orthopedic surgery suites where procedure duration and patient positioning complexity intersect.
- Latex:Natural rubber alternatives serve niche hypoallergenic specifications in European university hospital consortia.
- PVC:Cost-optimized surfaces for short-procedure outpatient settings face displacement from single-use positioning devices.
Polyurethane retains volume leadership. Memory foam is climbing the fastest on clinical evidence requirements.
End User:
Procurement autonomy concentration varies sharply across facility governance structures and capital allocation authority.
- Hospitals:Integrated delivery networks and German hospital consortia negotiate multi-year framework agreements with performance guarantees on pressure injury incidence. Tertiary centers in the United States, Germany, and Japan drive specification upgrades toward hybrid and pressure relief constructions.
- Surgical Centers:Freestanding facilities balance extended procedure compatibility against capital constraints through rental and service subscription models.
- Ambulatory Surgical Centers:Shorter case volumes favor standard polyurethane or disposable alternatives over reusable mattress investments.
- Specialty Clinics:Orthopedic and bariatric focused practices in German and Japanese metropolitan areas procure zoned-density hybrid surfaces.
Hospitals control specification-setting authority. Ambulatory surgical centers are gaining procurement volume fastest.
Feature:
Regulatory documentation depth now differentiates feature claims more than functional performance alone.
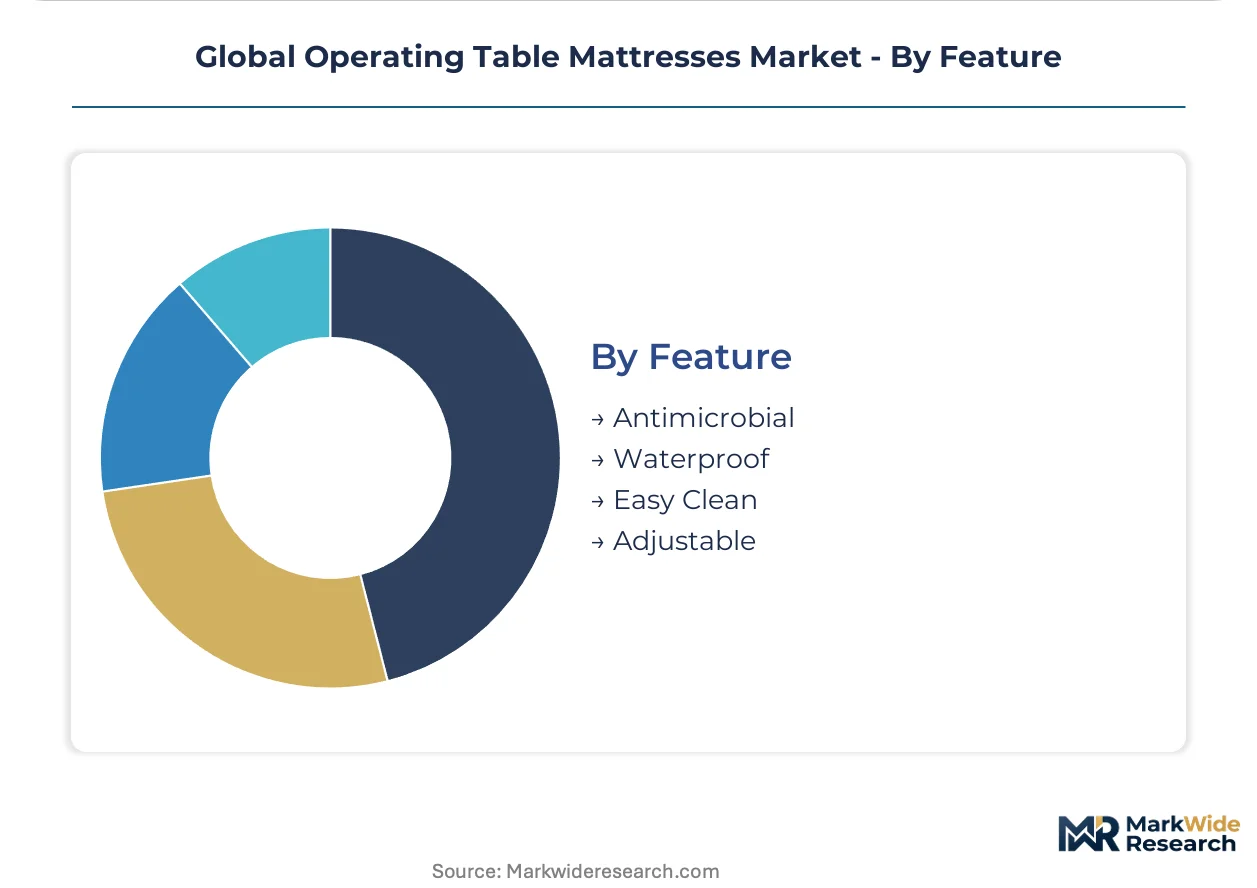
- Antimicrobial:Silver-ion or triclosan-integrated cover materials require ISO 10993-5 cytotoxicity and ISO 10993-10 sensitization data under tightened FDA 510(k) pathways. US and EU manufacturers face retrospective compliance investments for grandfathered predicates.
- Waterproof:Welded seam construction and hydrophobic surface treatments prevent fluid ingress during irrigation-intensive procedures.
- Easy Clean:Chemical resistance to quaternary ammonium and bleach-based disinfectants extends cover replacement intervals.
- Adjustable:Modular sectioning compatible with table articulation mechanisms commands premium positioning in cardiac and neurosurgical suites.
Antimicrobial specifications dominate tender evaluation criteria. Adjustable features are expanding into mid-tier procurement frameworks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polyether polyol supply chains cluster around the US Gulf Coast and Germany's chemical corridor, concentrating foam core production capacity in these regions while finished mattress assembly distributes across surgical equipment manufacturing clusters.
United States
Academic medical centers in Boston and Houston drive specification upgrades toward hybrid gel-foam constructions as pressure injury prevention protocols tighten Medicare reimbursement exposure. FDA 510(k) biocompatibility documentation requirements compress development timelines for antimicrobial cover materials. Minneapolis-St. Paul anchors polymer chemistry talent pools where viscoelastic gel-foam bonding expertise commands premium compensation.
Germany
University hospital consortia in Stuttgart and Munich negotiate multi-year framework agreements with performance guarantees on pressure injury incidence. EU MDR technical documentation obligations elevate market access costs for patient contact surface manufacturers. The Baden-Württemberg surgical equipment cluster concentrates specialized operating room furnishings production with integrated mattress supply chains.
Japan
Tertiary hospitals in Tokyo and Osaka prioritize zoned-density hybrid surfaces for orthopedic procedures exceeding three hours. PMDA medical device registration requirements align with international ISO 10993 biocompatibility standards. The Nagoya medical device manufacturing corridor hosts precision foam fabrication facilities serving domestic replacement cycles.
India
Tier-two city private hospital chains in Maharashtra and Karnataka expand procurement of pressure relief surfaces as surgical volumes rise. CDSCO medical device rules implementation creates compliant market entry pathways for foreign manufacturers. The Delhi-NCR medical equipment distribution hub concentrates import channels for European and US mattress suppliers.
United Kingdom
NHS procurement frameworks consolidate mattress specifications into system-wide agreements with clinical evidence requirements. MHRA post-Brexit regulatory alignment maintains EU MDR-equivalent biocompatibility documentation standards. The West Midlands surgical equipment manufacturing base supports domestic assembly operations with imported foam core supply chains.
Global Operating Table Mattresses Market Competitive Landscape
Concentration sits with surgical table original equipment manufacturers leveraging installed base relationships to bundle mattress replacements. Mid-tier specialized furnishing producers occupy regional strongholds through hospital-focused distribution channels. Fragmentation persists among foam core suppliers facing petrochemical feedstock margin compression. Dominant competitive moves include strategic partnerships between table manufacturers and gel-foam laminators, plus geographic expansion into underpenetrated ambulatory surgical center networks.
Among diversified surgical equipment producers, Skytron and Eschmann Equipment exemplify OEM-anchored positioning that bundles mattress replacements with table installed bases. Schmitz u. Soehne represents the specialized European furnishing archetype with concentrated operating room product portfolios. These three anchors illustrate how competitive advantage fragments across integrated equipment bundling, regional distribution density, and clinical evidence libraries rather than manufacturing scale alone.
| Leading Market Players |
|---|
| Anetic Aid |
| Teasdale |
| Ningbo Techart Medical Equipment |
| Mediland Enterprise |
| Schmitz u. Soehne |
| Sizewise |
| GEL A MED |
| Skytron |
| Eschmann Equipment |
| Others |
Supply & Pricing Matrix
FDA 510(k) biocompatibility tiers and EU MDR technical documentation classifications simultaneously gate supply base qualification and stratify price positioning across patient contact surface manufacturers. These regulatory thresholds force dual investments in ISO 10993 testing infrastructure and predicate device libraries, compressing margin pools for non-compliant foam core suppliers while elevating pricing power for certified gel-foam laminators serving German and US hospital networks.
Pricing Analysis
FDA 510(k) dictates the pricing tier structure across the Global Operating Table Mattresses Market, separating grandfathered predicate holders from entrants facing retrospective ISO 10993-5 cytotoxicity investments. Pricing stratifies across premium pressure relief, standard hybrid, and economy polyurethane tiers based on certification depth and gel integration density. Cost compression in standard foam configurations intensifies as petrochemical feedstock volatility erodes margin stability for Gulf Coast and German chemical corridor producers. Ambulatory surgical centers exhibit highest price sensitivity, while US academic medical centers prioritize performance guarantees over unit economics.
Supply Chain Analysis
Strategic stockpiling of polyether polyol feedstocks characterizes inventory management among German foam core manufacturers facing ECHA REACH restriction timelines. Supply concentrates in the United States, Germany, and Japan, with polyether polyol production anchored in the US Gulf Coast and Baden-Württemberg chemical corridors. Raw material dependencies center on petrochemical derivatives, viscoelastic gel formulations, and antimicrobial cover textiles. Single-source vulnerability runs through specialized gel-foam bonding chemistry suppliers in Stuttgart and Minneapolis-St. Paul. Distribution runs through surgical equipment OEM bundling agreements and hospital-focused furnishing distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sensor-integrated smart surfaces and real-time pressure mapping convergence represent a technological inflection reshaping procurement specifications toward outcome-based contracting. This disruption elevates R&D intensity requirements while compressing addressable volume for standard foam producers.
For Market Incumbents: Shield installed base relationships through preventive maintenance subscription bundling and accelerated EU MDR technical documentation completion for grandfathered predicates. Backward integration into gel-foam lamination capacity in Baden-Württemberg reduces dependency on specialized chemistry suppliers. Channel control through GPO contract exclusivity blocks emerging entrants from US integrated delivery network framework agreements. For New Entrants and Emerging Players: Differentiate on CDSCO-compliant manufacturing for Indian tier-two city private hospital chains, where surgical volume expansion outpaces domestic supply capacity. Rental and service subscription models penetrate German university hospital consortia seeking capital efficiency. White-space concentration sits with hybrid gel-foam constructions for ambulatory surgical centers balancing extended procedure compatibility against budget constraints. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified surgical equipment conglomerates with underoptimized mattress divisions lacking ISO 10993 testing infrastructure. Long-term viability hinges on clinical evidence library depth and field service density in metropolitan hospital clusters. The signal to watch is PMDA alignment with international biocompatibility standards accelerating Japanese market access costs for non-compliant foreign suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Completion | Market access preservation for grandfathered predicate devices across German hospital networks. |
| Sensor-Integrated Smart Surface Development | Real-time tissue perfusion monitoring opens neurosurgical and cardiac procedure premium positioning. |
| CDSCO Manufacturing Compliance Investment | Compliant market entry pathways into Maharashtra and Karnataka private hospital expansion. |
| Rental and Service Subscription Scaling | Recurring revenue capture from German university hospital consortia seeking capital efficiency. |
| Gel-Foam Lamination Capacity Addition | Backward integration reduces dependency on Stuttgart and Minneapolis chemistry talent scarcity. |
Research Methodology
Initial hypotheses were tested against primary input from operating room equipment procurement managers, biomedical engineers, GPO contracts specialists, and foam core manufacturing plant managers, and refined through secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement framework agreements, and customs trade data for polyether polyol derivatives. Bottom-up surgical volume modeling and top-down capital equipment replacement cycle analysis were triangulated to constrain forecast variance.
Variance decomposition across product type, material composition, end-user facility governance structure, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from replacement cycle velocity and specification upgrade penetration curves. Forecast inputs incorporated REACH compliance evolution timelines and ambulatory surgical center expansion trajectories.
Material uncertainties — ECHA restriction acceleration, ISO 10993 testing backlog resolution, and single-use positioning device substitution rates — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding surgical volume elasticity and capital allocation authority concentration. Revision becomes warranted when hybrid construction procurement share crosses threshold dominance in US integrated delivery network frameworks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
PMMA Healthcare Market
Medical Equipment
Water Bath Market
Medical Equipment
Floor-Standing Platelet Agitator Market
Medical Equipment
PCR Plate Sealer Market
Medical Equipment
Medical Equipment Management Software Market
Medical Equipment
Stereotactic Biopsy Tables Market
Medical Equipment
Global Vacuum Mixing Devices Market
Medical Equipment
Photorejuvenation Equipment Market
Medical Equipment
Sanitary Napkin Equipment Market
Medical Equipment
Medical Ultrasonic Baths Market
Medical Equipment
RFID Blood Refrigerators and Freezers Market
Medical Equipment
Apheresis Equipment Market
Medical Equipment
Medical Whirlpool Market
Medical Equipment
Single-Coated Medical Tape Market
Medical Equipment
Benchtop Platelet Agitator Market
Medical Equipment
Global Embryo Incubator Market