
 Global Oversized Cargo Transportation Market | 2026-2036
Global Oversized Cargo Transportation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Oversized Cargo Transportation Market Intelligence
Project cargo handling is realigning what buyers purchase, shifting transactions from per-ton rates to integrated lifecycle contracts covering engineering, routing, and on-site rigging. A.P. Moller–Maersk leverages its vessel fleet and port infrastructure to dominate transoceanic heavy-lift lanes. DHL Group extends specialized logistics networks across European manufacturing corridors. Barnhart Crane & Rigging anchors North American competitiveness through engineered heavy-haul and self-propelled modular transporter assets.
Oversized cargo transportation moves individual pieces or assemblies exceeding standard dimensional or weight thresholds for conventional freight modes, typically requiring specialized trailers, reinforced vessels, or charter aircraft with load capacities above 100 tons. Its primary purpose is delivering non-divisible industrial assets—turbine rotors, refinery columns, bridge segments—to project sites without disassembly. Road transport leads service revenue due to last-mile indispensability, yet multimodal transport represents the fastest-expanding category as project developers seek single-accountability chains across sea, rail, and highway legs. Heavy machinery and wind turbine parts concentrate margin pools because their density-to-value ratios justify premium routing engineering and insurance coverage.
FAA regulations govern U.S. air cargo dimension waivers for aerospace parts movements, while the EU Green Deal and F-Gas Regulation shape infrastructure investment patterns that generate oversized cargo demand for renewable energy components. Germany's KBA and state-level transport authorities coordinate heavy-haul permitting, creating compliance complexity that favors established operators with regulatory navigation capabilities. Stakeholders must monitor evolving carbon-border adjustment mechanisms that could restructure route economics between Asian manufacturing origins and European project destinations.
Market Dynamics
Wind turbine component scaling is forcing route engineering to precede manufacturing decisions, with nacelle dimensions now dictating corridor upgrades before blades leave factories. This inversion of logistics and production timelines concentrates planning power with heavy-haul operators capable of validating transport feasibility during design phases.
Growth Catalysts
- EU Green Deal infrastructure mandates:Cross-border superload permit harmonization accelerates renewable energy component flows between German offshore assembly ports and continental project sites.
- Power generation utilities:Turnkey logistics contracts for wind turbine nacelles displace fragmented spot-market procurement, locking in multi-year heavy-lift service relationships.
- Self-propelled modular transporters:Axle-line modularity enables load distribution reconfiguration mid-route, opening previously inaccessible bridge crossings and rural corridors.
Market Restraints
- Specialized trailer asset scarcity:European manufacturers face 18-24 month order backlogs for hydraulic platform trailers, constraining fleet expansion for German wind corridor operators.
- F-Gas Regulation refrigerant phase-down:Transport refrigeration unit retrofits for temperature-sensitive aerospace cargo impose unrecoverable capital burdens on mid-size road carriers.
- Bridge infrastructure deficit:Aging US interstate crossings below 80-ton load ratings force circuitous routing, inflating per-mile costs for refinery column movements.
Strategic Opportunities
- India PLI scheme manufacturing clusters:Green hydrogen electrolyzer production hubs in Gujarat and Tamil Nadu generate first-mover advantage for integrated heavy-lift and ocean freight operators.
- Digital freight matching platforms:Real-time capacity aggregation for superload movements reduces deadhead positioning costs across fragmented European owner-operator networks.
- Carbon border adjustment mechanism pre-compliance:Emissions-verified transport chains from Asian component origins to EU project sites command premium positioning ahead of 2026 implementation.
Industry Challenges
- Route survey engineer shortage:Germany's KBA-certified corridor planners command salaries exceeding €120,000, with training pipelines producing fewer than 50 qualified specialists annually.
- Multimodal liability fragmentation:Disputes over damage attribution between ocean, rail, and road legs delay claims resolution and erode contractor margins on integrated contracts.
- Legacy permit database incompatibility:German state transport authorities operate non-interoperable approval systems, forcing duplicate documentation for cross-Länder movements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Oversized Cargo Transportation Market |
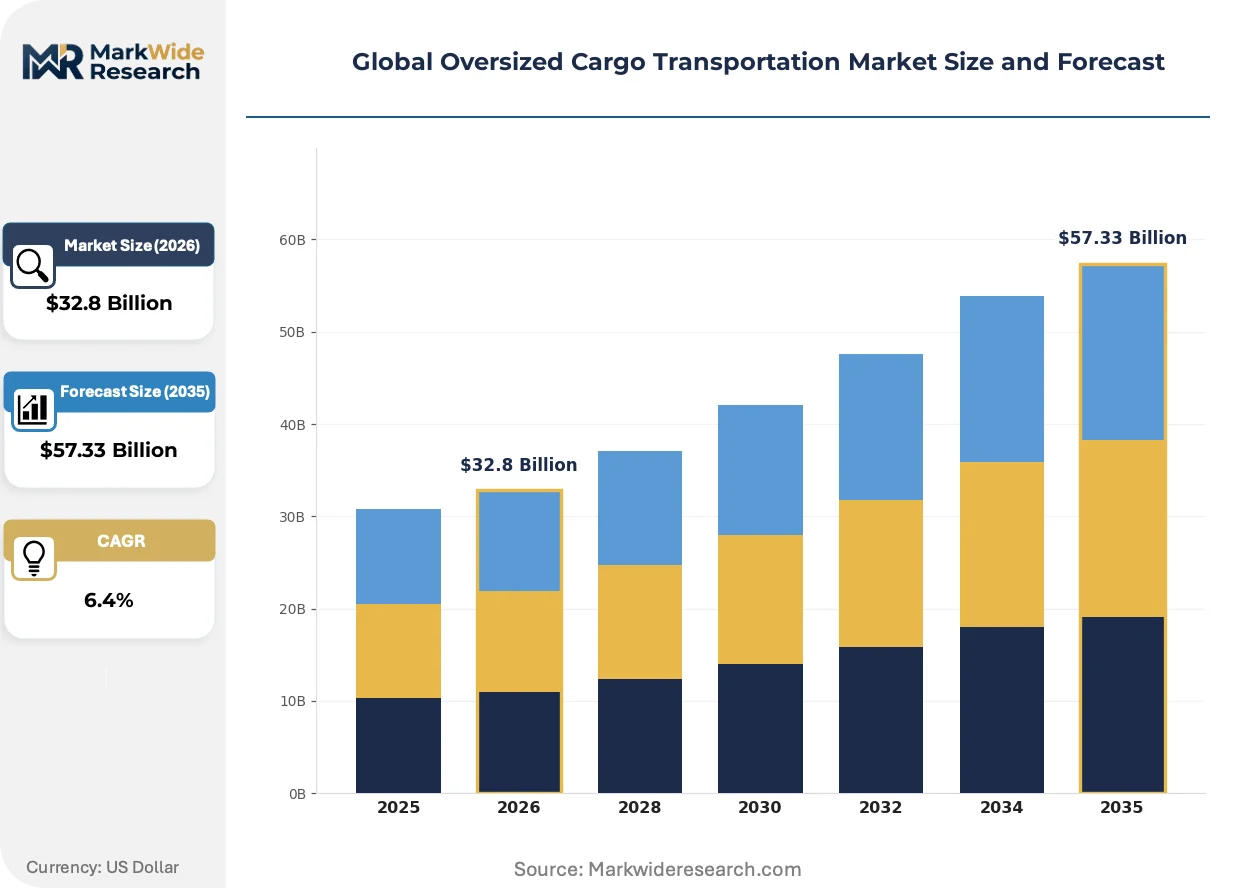
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $57.33 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Cargo Type: Heavy Machinery, Construction Equipment, Industrial Components, Wind Turbine Parts, Aerospace Parts, Marine Vessels Transportation Mode: Road Transport, Sea Freight, Rail Transport, Air Freight, Multimodal Transport End User Industry: Mining, Power Generation, Shipbuilding, Oil & Gas Exploration, Infrastructure Development Service Model: Project Cargo Handling, Breakbulk Cargo Service, Heavy Lift Service, Logistics Management, Custom Clearance |
| Companies Covered | C.H. Robinson, Landstar System, Inc., A.P. Moller–Maersk, Barnhart Crane & Rigging, Orient Overseas Container Line Limited, DHL Group, DSV, Kintetsu World Express, Inc., Kuehne + Nagel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Oversized Cargo Transportation Market Strategic Shifts & Innovations
Digital twin modeling is compressing route validation from weeks to days, while regulatory pressure on emissions transparency is reshaping carrier qualification criteria for renewable energy logistics chains.
Self-propelled modular transporter fleets equipped with real-time axle load monitoring and automated hydraulic leveling are unifying previously separate engineering, permitting, and execution phases into continuous digital workflows. Wind turbine OEMs in Denmark and Spain now require transport contractors to submit finite element analysis of load stresses before contract award. This capability consolidation is compressing project timelines and disqualifying carriers without in-house engineering departments.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon refrigerants is forcing cold-chain heavy-haul operators to retrofit trailers with CO2-based systems or exit temperature-controlled aerospace cargo segments. German and French transport authorities now condition superload permits upon demonstration of low-global-warming-potential refrigeration compliance. Aerospace parts movements through Frankfurt-Hahn and Leipzig-Halle corridors face the steepest compliance cost gradients.
Lifecycle contracting is displacing transactional spot rates as the dominant procurement model for offshore wind developers in the North Sea basin. EPC contractors now bundle transport, installation, and maintenance logistics under single-accountability frameworks spanning 15-20 year asset lifespans. This shift is most pronounced in German and Danish markets, where turbine OEMs have vertically integrated into heavy-lift service provision to capture margin pools previously allocated to third-party carriers.
Global Oversized Cargo Transportation Market Segmentation
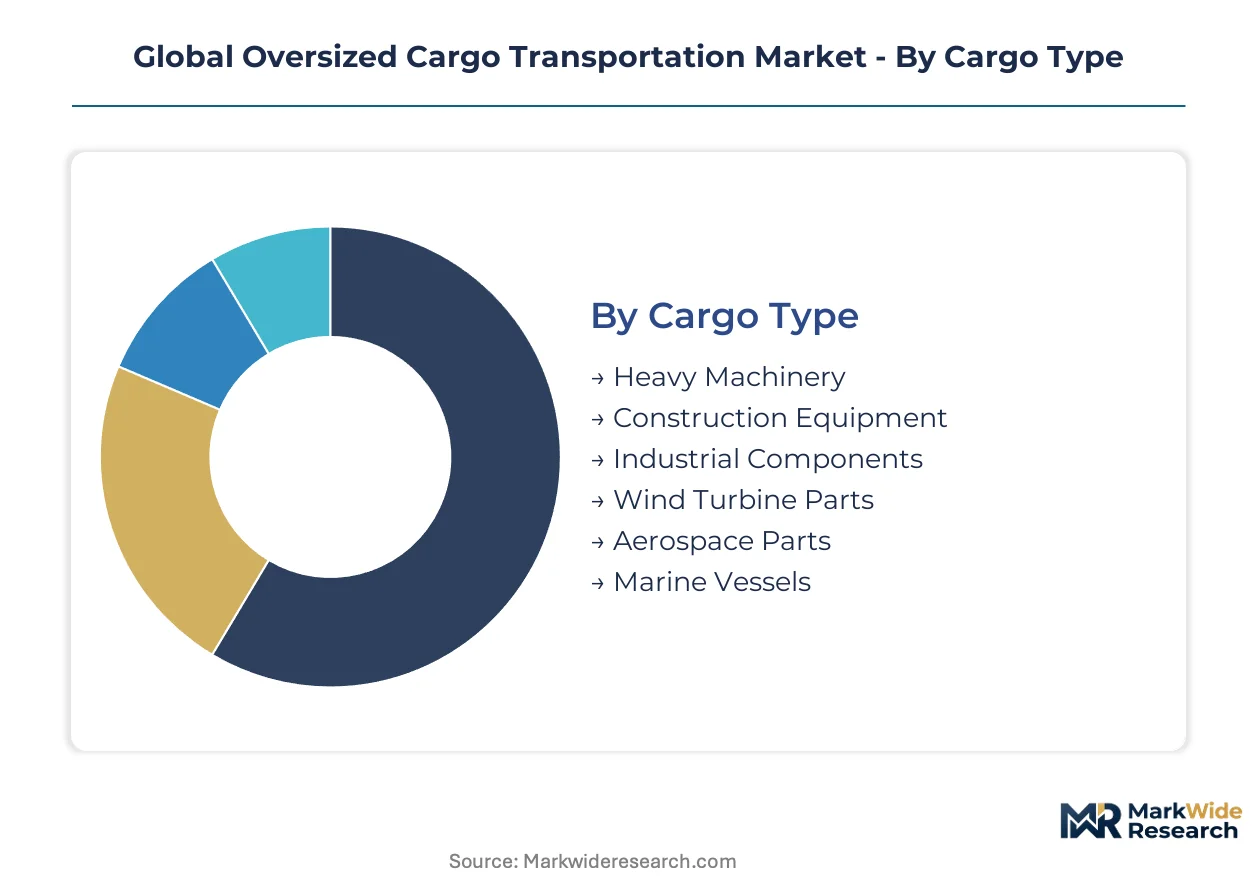
Oversized cargo transportation segments by asset type, mode, and service intensity. Capital allocation decisions hinge on which combinations justify specialized trailer fleets versus chartered vessel deployments.
Cargo Type:
Capital intensity escalates with unit density and dimensional extremity, with wind turbine components demanding the heaviest upfront investment in route engineering and permitting infrastructure.
- Heavy Machinery:Mining excavators and crushing equipment exceed 200-ton thresholds, requiring reinforced hydraulic platform trailers. Demand concentrates in Australian iron ore corridors and Chilean copper belts where pit-to-port distances stretch hundreds of kilometers.
- Wind Turbine Parts:Nacelles and blade assemblies now exceed 100 meters in length, forcing pre-transport corridor validation. German North Sea ports and Danish assembly hubs absorb the bulk of European movements, with nacelle dimensions dictating bridge upgrade schedules before manufacturing commences.
- Construction Equipment:Crawler cranes and tunnel boring machines move on modular axle lines.
- Industrial Components:Refinery columns and heat exchangers dominate petrochemical project logistics.
- Aerospace Parts:Fuselage sections and wing assemblies require temperature-controlled heavy-haul under FAA dimension waivers.
- Marine Vessels:Hull sections and superstructure modules move from shipyards to launch facilities.
Wind turbine parts absorb the bulk of installed capacity; aerospace parts is expanding most quickly on defense and satellite manufacturing demand.
Transportation Mode:
Modal selection tracks the tension between last-mile indispensability and transoceanic economies of scale, with asset specificity determining carrier margin structures.
- Road Transport:Self-propelled modular transporters with real-time axle load monitoring enable load reconfiguration mid-route. German KBA-certified operators command premium positioning for cross-Länder superload movements where state-level permit databases remain non-interoperable.
- Multimodal Transport:Single-accountability chains spanning sea, rail, and highway legs compress project timelines. North Sea offshore wind developers in Germany and Denmark now mandate integrated contracts covering engineering, routing, and on-site rigging under unified liability frameworks.
- Sea Freight:Heavy-lift vessels and deck carriers handle refinery columns and bridge segments.
- Rail Transport:Schnabel cars and depressed-center flatcars move transformers and generators.
- Air Freight:Charter Antonov and Boeing Dreamlifter operations serve aerospace emergency logistics.
Road transport retains the deepest installed base; multimodal transport is climbing the fastest as EPC contractors consolidate vendor accountability.
End User Industry:
Customer procurement maturity varies sharply, with power generation utilities leading the shift from spot-market rates to lifecycle contracting.
- Power Generation:Turnkey logistics contracts for wind turbine nacelles displace fragmented procurement. Offshore wind developers in the North Sea basin now bundle 15-20 year transport, installation, and maintenance logistics under single-accountability frameworks.
- Oil & Gas Exploration:Modular refinery components and offshore platform modules require ice-class vessel chartering. Norwegian continental shelf developments and US Gulf Coast liquefaction projects sustain demand for heavy-lift marine logistics.
- Mining:Pit-to-port haulage of ultra-class trucks and shovels dominates Australian and Chilean corridors.
- Infrastructure Development:Bridge segments and tunnel boring machines move on project-specific schedules.
- Shipbuilding:Hull block transport from fabrication shops to dry docks requires coastal barge coordination.
Power generation commands the largest committed capacity; infrastructure development is gaining share fastest on government stimulus deployment.
Service Model:
Service intensity determines whether carriers capture margin through asset utilization or engineering advisory fees.
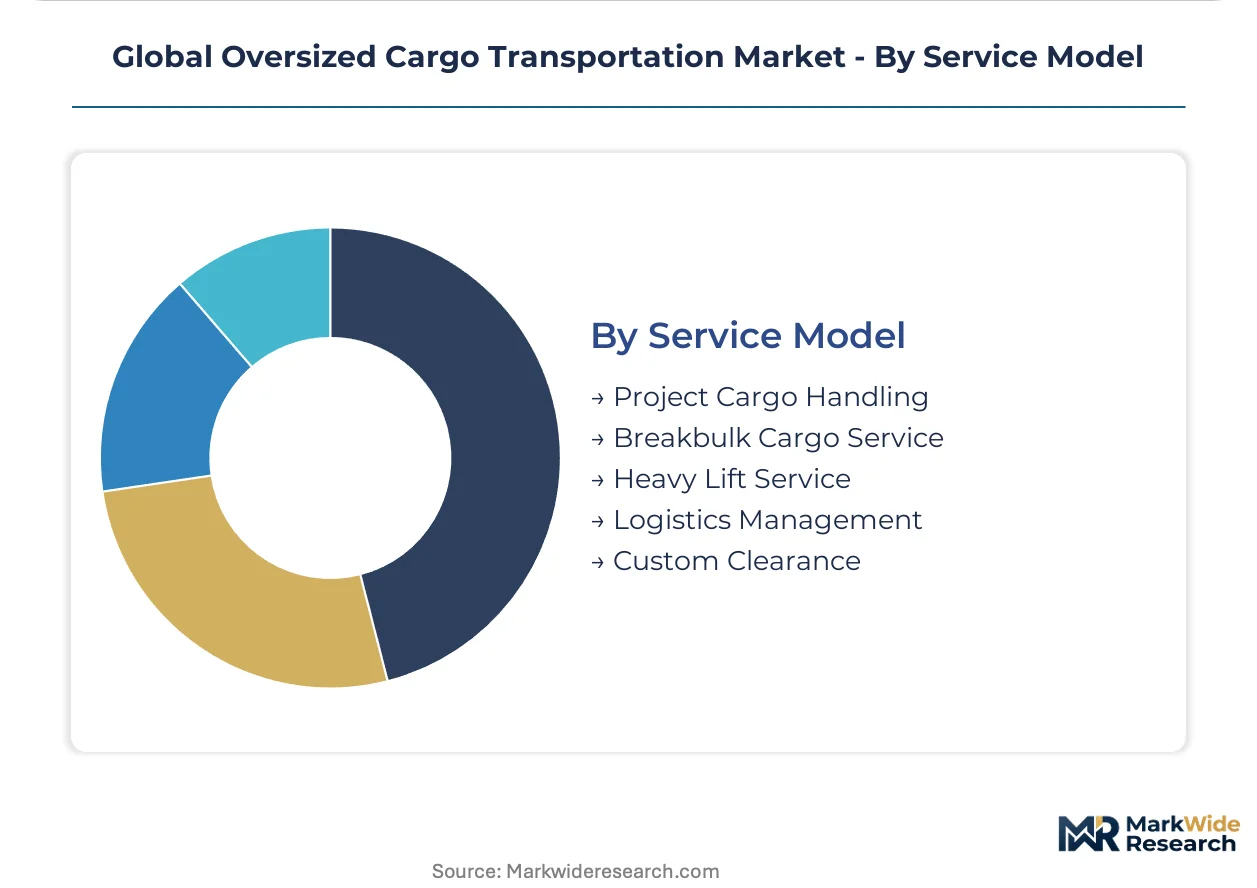
- Project Cargo Handling:Integrated engineering, routing, and rigging services span manufacturing origin through site installation. Danish and Spanish wind turbine OEMs now require finite element analysis of load stresses before contract award, disqualifying carriers without in-house engineering departments.
- Heavy Lift Service:Crane barge operations and jack-up vessel deployment for offshore installation. German offshore assembly ports require specialized heavy-haul corridors validated through digital twin modeling that compresses route validation from weeks to days.
- Breakbulk Cargo Service:Non-containerized general cargo consolidation at breakbulk terminals.
- Logistics Management:Fourth-party oversight of subcontracted modal legs and permit coordination.
- Custom Clearance:Documentation and duty optimization for cross-border superload movements.
Project cargo handling holds the deepest operational footprint; heavy lift service is expanding most rapidly on offshore wind installation demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany manufactures the majority of European wind turbine nacelles yet relies on specialized heavy-haul corridors to move components to North Sea assembly ports. Component production clusters in China and Denmark feed transoceanic routes toward Western European project sites. Brazil and Australia concentrate mining equipment demand but lack domestic manufacturing depth for ultra-class haul trucks.
Germany
Offshore wind assembly ports at Cuxhaven and Rostock absorb nacelle flows from Danish and Spanish OEM factories. The KBA coordinates with state transport authorities on superload permitting, though database non-interoperability forces duplicate documentation for cross-Länder movements. Bavaria's heavy-haul operators command premium positioning for corridor validation services that compress route engineering timelines.
United States
Refinery column movements from Gulf Coast fabrication yards to Permian Basin project sites strain aging interstate bridge infrastructure below 80-ton load ratings. FAA dimension waivers govern aerospace parts transport through Huntsville and Wichita corridors. Barnhart Crane & Rigging anchors competitiveness through self-propelled modular transporter assets deployed across manufacturing belts.
China
Dual carbon goals accelerate domestic wind turbine installation, generating outbound heavy-lift demand for electrolyzer components bound for European hydrogen hubs. MIIT standards shape trailer manufacturing specifications that influence global fleet availability. Yangtze River Delta ports coordinate with inland waterway barge networks for bridge segment movements.
Brazil
Pit-to-port haulage of mining excavators concentrates in Minas Gerais iron ore corridors stretching hundreds of kilometers. ANVISA regulates temperature-controlled transport for aerospace cargo segments serving Embraer supply chains. São Paulo state logistics operators face equipment scarcity for hydraulic platform trailers amid 18-24 month manufacturer backlogs.
India
PLI scheme manufacturing clusters in Gujarat and Tamil Nadu generate green hydrogen electrolyzer production requiring integrated heavy-lift and ocean freight coordination. CEA standards govern transformer movements for grid infrastructure expansion. Mundra Port heavy-haul corridors validate routes through digital twin modeling before manufacturing commences.
Global Oversized Cargo Transportation Market Key Industry Players
Capital-heavy asset owners compete with asset-light logistics orchestrators across distinct margin structures. The vendor base concentrates around integrated vessel-and-port operators, specialized heavy-haul contractors with engineering capabilities, and fourth-party logistics managers coordinating fragmented modal legs. Three archetypes dominate: fleet-heavy transoceanic carriers, engineering-intensive project cargo handlers, and digital freight platforms aggregating superload capacity. Competitive positioning hinges on M&A for corridor-specific permitting expertise and strategic partnerships bundling installation with transport liability.
Among integrated ocean-and-road operators, A.P. Moller–Maersk and DHL Group exemplify archetypes combining vessel fleets with last-mile heavy-haul networks. Barnhart Crane & Rigging occupies a position within the engineering-intensive tier, representing carriers where in-house route validation and self-propelled modular transporter assets disqualify competitors without comparable technical departments.
| Leading Market Players |
|---|
| C.H. Robinson |
| Landstar System, Inc. |
| A.P. Moller–Maersk |
| Barnhart Crane & Rigging |
| Orient Overseas Container Line Limited |
| DHL Group |
| DSV |
| Kintetsu World Express, Inc. |
| Kuehne + Nagel |
| Others |
Cost & Logistics Intelligence
Horizontal integration between heavy-haul operators and specialized trailer manufacturers anchors supply positioning and pricing power, as German wind corridor demand outstrips European production capacity for hydraulic platform trailers. This captive sourcing dynamic concentrates margin capture with fleet owners able to secure 18-24 month order backlogs, while spot-market carriers absorb equipment scarcity through inflated lease rates.
Pricing Analysis
Margin tightening in project cargo handling reflects the shift from transactional spot rates to integrated lifecycle contracts covering engineering, routing, and on-site rigging. Three-tier pricing structure across premium, standard, and economy levels separates carriers with in-house finite element analysis capabilities from asset-only operators and fragmented owner-operator networks. Cost-down pressure on mid-size road carriers accelerates because F-Gas Regulation refrigerant retrofits impose unrecoverable capital burdens for temperature-controlled aerospace segments. Power generation utilities demonstrate lowest price sensitivity due to bundled 15-20 year accountability frameworks, while spot-market mining equipment shippers retain highest sensitivity to per-mile rate fluctuations.
Supply Chain Analysis
Workforce availability constraints in German engineering corridors and Chinese trailer manufacturing clusters tighten equipment delivery timelines and inflate specialist salaries. Geographic supply concentration centers on Germany for route validation services, China for hydraulic platform trailer production, and Denmark for wind turbine OEM manufacturing integration. Raw material dependencies draw from high-strength steel alloys, precision hydraulic systems, and modular axle-line components. Single-source vulnerability permeates the European specialist trailer market where manufacturer backlogs exceed fleet expansion timelines. Distribution runs through integrated ocean-and-road operators, engineering-intensive project cargo handlers, and fragmented European owner-operator networks aggregated through digital freight platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around carriers with captive engineering capabilities and permit navigation expertise, as route survey engineer shortages and legacy database incompatibility force weaker competitors into subcontractor roles or exit.
For Market Incumbents: Extend engineering advisory services upstream into wind turbine design-phase feasibility validation, capturing planning power before manufacturing commitments lock corridor requirements. Deepen captive supply of self-propelled modular transporter assets through strategic trailer manufacturer partnerships, insulating fleet expansion from 18-24 month order backlogs that constrain German corridor competitors. Backward integration into digital twin modeling capabilities compresses route validation timelines and disqualifies asset-only challengers without comparable technical departments.
For New Entrants and Emerging Players: Enter via digital freight matching platforms aggregating fragmented European owner-operator superload capacity, reducing deadhead positioning costs through real-time capacity visibility. Target India's PLI scheme manufacturing clusters in Gujarat and Tamil Nadu, where green hydrogen electrolyzer production generates first-mover advantage for integrated heavy-lift and ocean freight coordination absent established incumbent presence. Pursue carbon border adjustment mechanism pre-compliance positioning, offering emissions-verified transport chains from Asian component origins to EU project sites ahead of regulatory implementation.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of KBA-certified corridor planning specialists with regulatory navigation capabilities and digital twin modeling competencies. Long-term viability over the next decade favors engineering-intensive carriers with unified liability frameworks spanning multimodal legs, as fragmented modal coordination erodes margins and delays claims resolution. Monitor carbon border adjustment mechanism implementation timing as inflection indicator for premium positioning of emissions-verified transport chains.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Trailer Manufacturing | Captive supply of hydraulic platform trailers insulates German operators from 18-24 month manufacturer backlogs. |
| Digital Twin Modeling Capability Acquisition | Route validation compression from weeks to days disqualifies competitors without in-house engineering departments. |
| Lifecycle Contracting Transition | 15-20 year bundled transport, installation, and maintenance frameworks displace fragmented spot-market procurement. |
| Carbon Border Adjustment Pre-Compliance | Emissions-verified chains from Asian origins to EU project sites command premium positioning ahead of regulatory implementation. |
| KBA-Certified Corridor Planning Specialist Acquisition | Regulatory navigation capabilities concentrate with specialists commanding salaries exceeding €120,000 amid training pipeline constraints. |
Research Approach
Document review covered EU Green Deal infrastructure mandates, F-Gas Regulation compliance frameworks, and KBA superload permitting protocols, complemented by interviews with heavy-haul fleet managers, wind turbine OEM logistics directors, EPC contractor procurement leads, and port authority planning officers. Secondary validation drew from FAA dimension waiver filings, German state transport authority permit databases, and MIIT trailer manufacturing specifications. Bottom-up equipment fleet analysis and top-down renewable energy project pipeline assessment provided cross-referencing discipline across the analysis window.
Cross-referencing historical heavy-lift vessel deployment patterns against industry panel input on nacelle dimension scaling established baseline demand trajectories. Segmentation dimensions modeled include cargo type, transportation mode, end user industry, and service intensity, with additional weighting for regulatory framework clusters affecting cross-border superload movements. CAGRs derived from equipment utilization rates, permit issuance velocity, and project cargo contract value aggregation across the projection horizon. Industry-specific forecast inputs incorporated wind turbine OEM manufacturing location decisions and electrolyzer production hub development timelines.
Revisions become necessary when bridge infrastructure upgrade schedules, carbon border adjustment mechanism implementation details, or KBA-state authority database interoperability initiatives materialize differently than modeled assumptions anticipate. Forecasts reflect documented permit processing timelines, equipment order backlogs, and regulatory compliance cost gradients without claiming predictive certainty. Material deviation in named triggers warrants pause and re-evaluation of corridor capacity assumptions and carrier margin structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy-Duty Trucks
North America Heavy Commercial Vehicle (HCV) TMPS Market
Heavy-Duty Trucks
Heavy-Duty Truck Load and Axle Weight Sensor Systems Market
Heavy-Duty Trucks
Garbage Truck Bodies Market
Heavy-Duty Trucks
Mexico Refrigerated Truck Market
Heavy-Duty Trucks
Heavy-Duty Vehicle Engine Brake Market
Heavy-Duty Trucks
Articulated Dump Trucks Market
Heavy-Duty Trucks
Airport Catering Truck Market
Heavy-Duty Trucks
Poly Trucks Market
Heavy-Duty Trucks
Saudi Arabia Refrigerated Truck Market
Heavy-Duty Trucks
United States Tank Trucking Market
Heavy-Duty Trucks
Hard Tonneau Cover Market
Heavy-Duty Trucks
Vacuum Truck Market
Heavy-Duty Trucks
Flatbed Truck Market
Heavy-Duty Trucks
Truck Headache Rack Market
Heavy-Duty Trucks
Hydrogen Trucks Market
Heavy-Duty Trucks
Turret Truck Market