
 Heavy-Duty Vehicle Engine Brake Market | 2026-2036
Heavy-Duty Vehicle Engine Brake Market Size, Share, and Industry Trends Forecast 2026-2036
Heavy-Duty Vehicle Engine Brake Market Foresight
Asset-light leasing and pay-per-mile financing is fragmenting the competitive landscape for engine brake suppliers. AB Volvo leverages captive finance arms to bundle brake retrofits with truck lease contracts across European corridors. Eaton competes through extensive service networks that sustain aftermarket revenue streams for compression release brake maintenance. Jacobs Vehicle Systems dominates OEM supply agreements with North American heavy-duty truck manufacturers.
Heavy-duty vehicle engine brakes are deceleration devices integrated into diesel powertrains, using exhaust restriction or cylinder pressure manipulation to generate retarding force without friction-based wear. Compression release brakes mechanically open exhaust valves during the compression stroke, converting engine momentum into heat dissipated through the exhaust system. Exhaust brakes represent the mature volume base, while electronic control modules are capturing margin pools as fleet telematics integration expands. Mechanical technology still anchors the installed base, though electronic actuator systems are displacing pneumatic controls in premium heavy-duty truck configurations.
EPA emission standards and NHTSA safety regulations in the United States mandate minimum downhill speed control capabilities for commercial vehicles exceeding 26,000 pounds gross vehicle weight. ECE R13 braking performance requirements in Europe enforce comparable deceleration benchmarks for intercity buses and tractor-trailers operating on alpine routes. Stakeholders must monitor how brake-by-wire integration and autonomous emergency braking mandates reshape hardware specifications and supplier qualification timelines.
Market Dynamics
Fleet telematics integration is compressing hardware margins while expanding software-enabled service revenue pools for brake system suppliers. Electronic control modules now capture recurring revenue streams that mechanical actuator manufacturers cannot access.
Growth Catalysts
- EPA Phase 3 GHG Standards:Mandated improvements in vehicle efficiency and emissions control are accelerating retrofit demand for compression release brake systems across Class 8 truck fleets operating interstate corridors.
- Long-haul freight electrification delays:Diesel powertrain longevity requirements are extending service intervals and driving aftermarket brake maintenance volumes in North American corridors.
- Alpine route safety mandates:ECE R13 braking performance requirements are forcing intercity bus operators in Switzerland, Austria, and Italy to upgrade exhaust brake configurations.
Market Restraints
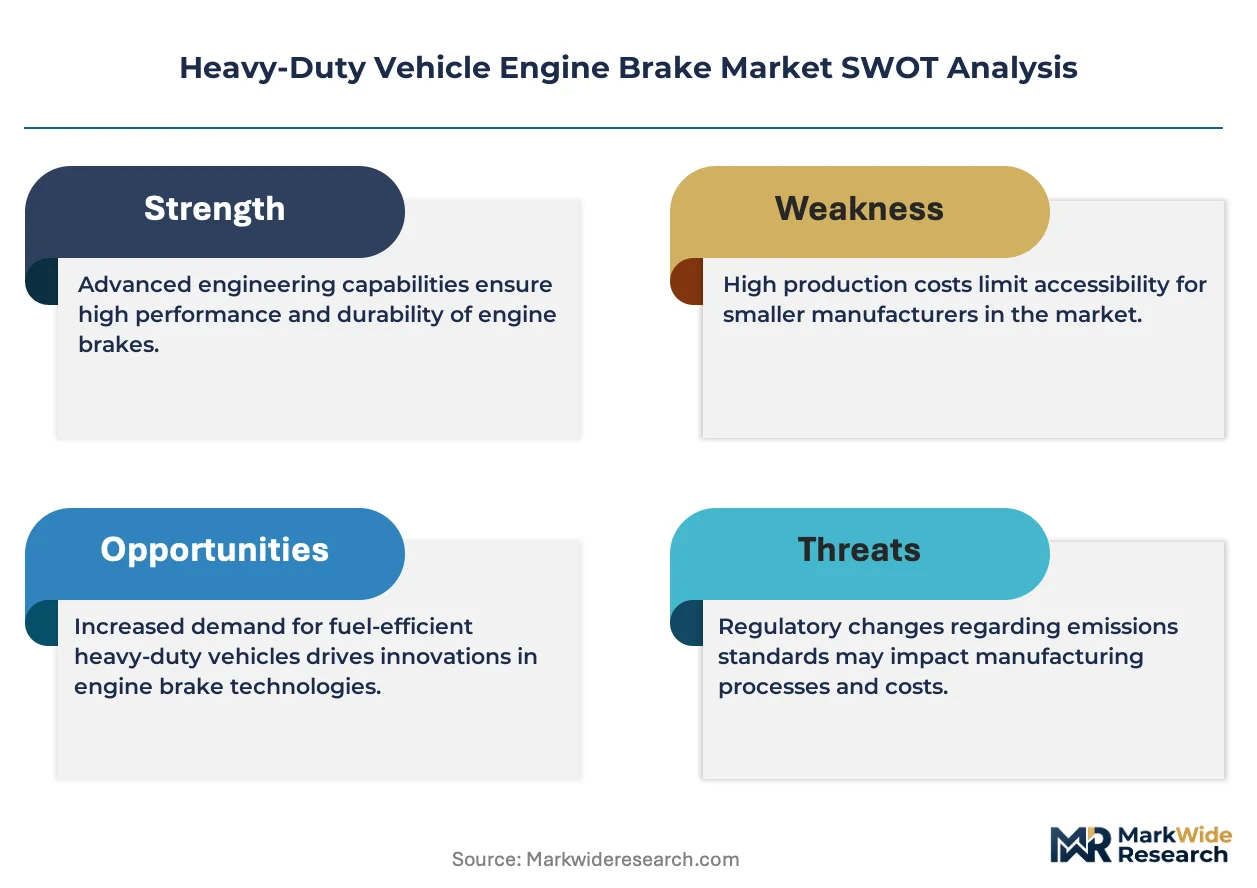
- Steel and rare earth input volatility:Fluctuating costs for electromagnetic actuator materials are compressing margins on electronic brake control modules.
- Supplier concentration in German precision machining:Dependence on specialized valve train component suppliers creates bottleneck risk for compression release brake assembly.
- Friction brake performance improvements:Advances in disc brake thermal management are reducing perceived necessity for auxiliary engine braking in certain vocational applications.
Strategic Opportunities
- Indian commercial vehicle brake standardization:BIS implementation of enhanced braking performance requirements for heavy trucks creates first-mover positioning for electronic actuator suppliers.
- Brake-by-wire convergence with autonomous emergency braking:Integration of predictive deceleration algorithms is opening specification windows for smart engine brake controllers.
- Pay-per-mile financing channels:Asset-light leasing structures are enabling bundled brake retrofit financing through captive finance arms of major truck OEMs.
Industry Challenges
- Embedded software certification timelines:ISO 26262 functional safety validation for electronic brake control modules extends product development cycles by 18-24 months.
- Legacy pneumatic system integration:Retrofit compatibility requirements for existing truck fleets are constraining electronic actuator architecture decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heavy-Duty Vehicle Engine Brake Market |
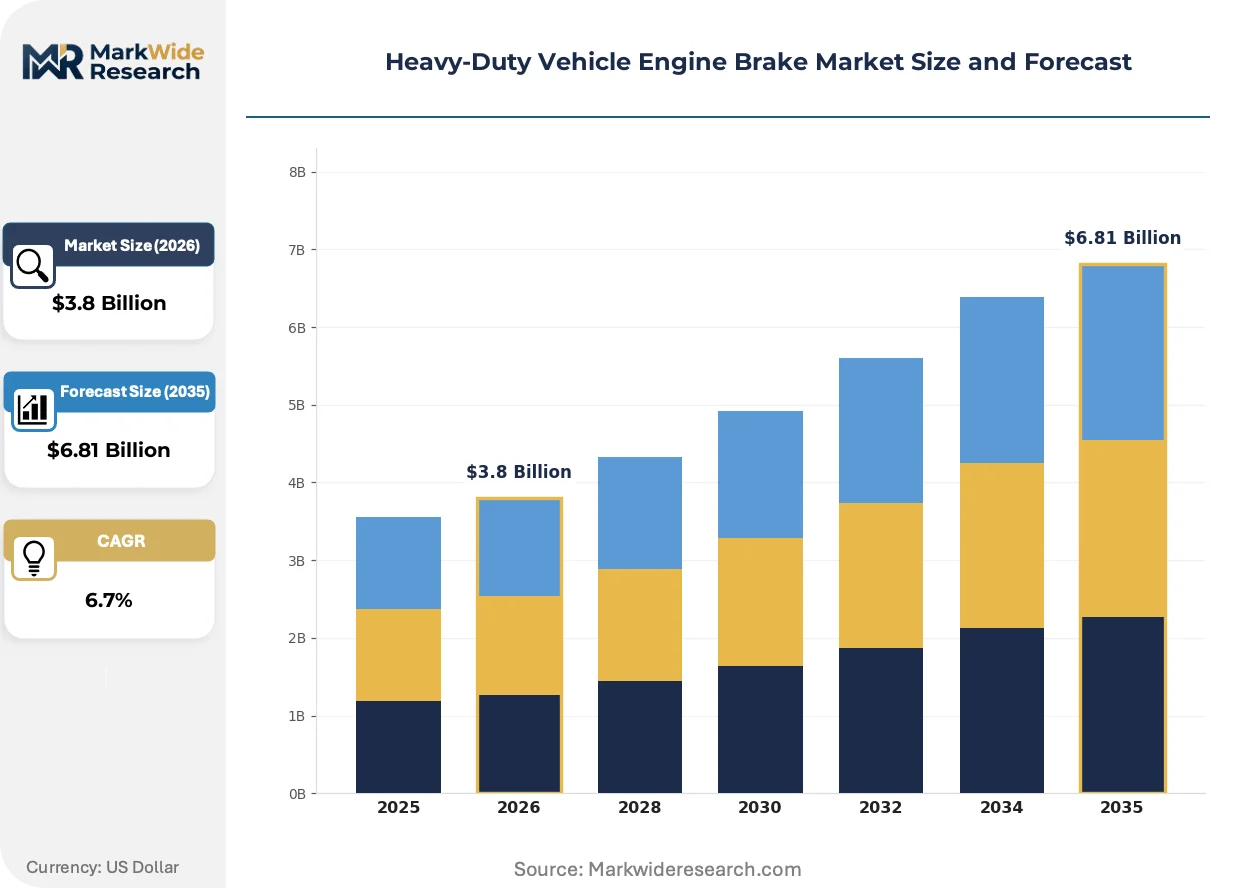
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Exhaust Brakes, Compression Release Brakes, Hydraulic Brakes, Engine Retarders End User: Fleet Operators, Truck Manufacturers, Vehicle Assemblers, Aftermarket Providers Application: Heavy-Duty Trucks, Buses, Commercial Vehicles, Military Vehicles Technology: Mechanical, Electronic, Pneumatic, Hybrid |
| Companies Covered | AB Volvo, FAW Group, Eaton, Jacobs Vehicle Systems, MAN SE, Scania Group, Pacbrake, Streparava, Voith Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heavy-Duty Vehicle Engine Brake Market Shifts & Advancements
Digital twin technology is virtualizing brake system development workflows while predictive maintenance algorithms are compressing unplanned downtime for fleet operators. These shifts are redistributing value from hardware sales toward software-enabled service contracts.
Electronic actuator control systems are virtualizing the traditional pneumatic brake interface by replacing mechanical valve trains with software-defined pressure modulation. Premium heavy-duty truck configurations in Germany and the United States are adopting these systems at accelerating rates. This virtualization is compressing the addressable market for conventional pneumatic component suppliers while expanding margin pools for firmware developers.
ECE R13 braking performance requirements are tightening deceleration benchmarks for intercity buses and tractor-trailers operating on alpine routes across Europe. The regulation is forcing brake system suppliers to validate enhanced compression release configurations under extreme grade conditions. Intercity bus operators in Austria, Switzerland, and northern Italy are responding by accelerating replacement cycles for exhaust brake hardware.
Fleet procurement patterns are unbundling brake system specification from vehicle purchase decisions through separate service contracts and retrofit financing arrangements. Independent service networks and leasing intermediaries are displacing traditional OEM captive distribution for aftermarket brake maintenance. This channel fragmentation is most visible in United States long-haul corridors where asset-light operators concentrate.
Heavy-Duty Vehicle Engine Brake Market Segmentation
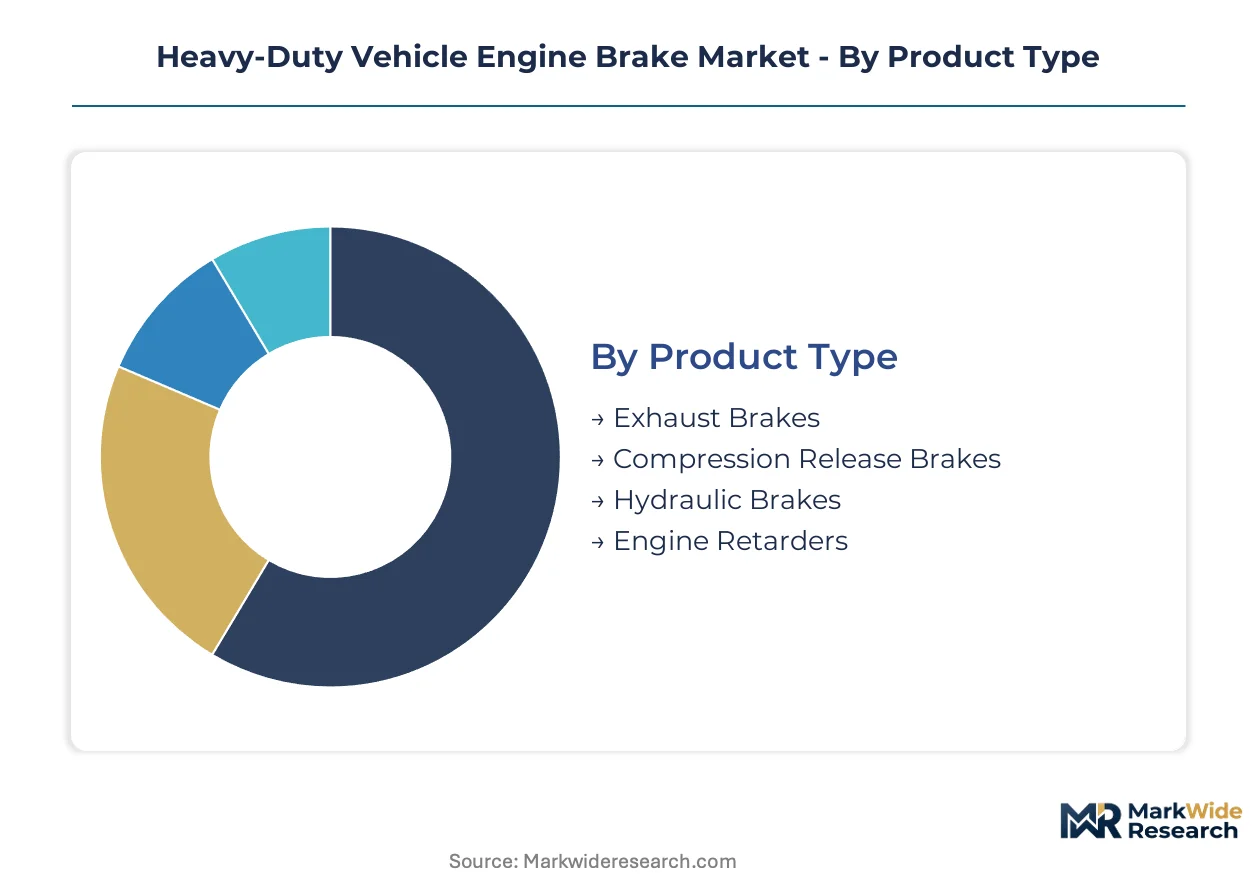
Engine brake procurement cycles vary dramatically across product configurations and end-user categories. Fleet operators replace compression release hardware every 3-5 years under severe-duty alpine contracts, while aftermarket exhaust brake retrofits turn over faster on pay-per-mile financing structures.
Product Type:
Compression release systems command the longest replacement cycles due to embedded installation complexity, while exhaust brake retrofits turn fastest through independent service channels.
- Exhaust Brakes:Mature flap-valve systems restrict exhaust flow to generate backpressure retarding force through turbine housing restriction. Demand concentrates in United States Class 8 vocational fleets where NHTSA deceleration mandates apply, though friction brake thermal advances are compressing specification rates in certain applications.
- Compression Release Brakes:Mechanically-actuated valve train systems open exhaust valves during compression stroke, converting piston momentum into dissipated heat. Operators across Swiss and Austrian alpine corridors are accelerating replacement cycles under ECE R13 enforcement, while EPA Phase 3 efficiency requirements extend retrofit demand in North American long-haul corridors.
- Hydraulic Brakes:Fluid-coupled retarder systems integrated into driveline architecture.
- Engine Retarders:Integrated powertrain deceleration systems combining multiple braking modalities.
Exhaust brakes anchor the volume base while compression release configurations gain share at the steepest rate.
End User:
Procurement authority is fragmenting as captive finance arms and independent leasing intermediaries displace traditional OEM channel control.
- Fleet Operators:Asset-light logistics companies and dedicated contract carriers specifying brake hardware through separate service agreements rather than vehicle purchase bundles. United States interstate operators are unbundling compression release retrofits from truck acquisition decisions through pay-per-mile financing structures.
- Truck Manufacturers:OEM platform engineering teams integrating brake systems at chassis design phase.
- Vehicle Assemblers:Contract manufacturing operations building to fleet specification.
- Aftermarket Providers:Independent service networks capturing maintenance revenue as OEM distribution fragments.
Fleet operators drive the fastest specification velocity while aftermarket channels expand share through financing innovation.
Application:
Alpine route severity and freight corridor length create divergent duty-cycle requirements across vehicle platforms.
- Heavy-Duty Trucks:Class 8 tractor-trailers operating interstate corridors in the United States and Germany. EPA Phase 3 GHG standards and autobahn speed differentials are mandating enhanced compression release configurations for downhill speed control.
- Buses:Intercity coaches operating ECE R13-regulated alpine routes through Austria, Switzerland, and northern Italy.
- Commercial Vehicles:Vocational trucks in construction and refuse applications.
- Military Vehicles:Tactical platforms with specialized brake durability requirements.
Heavy-duty trucks concentrate the revenue base while bus applications expand most quickly under European safety mandates.
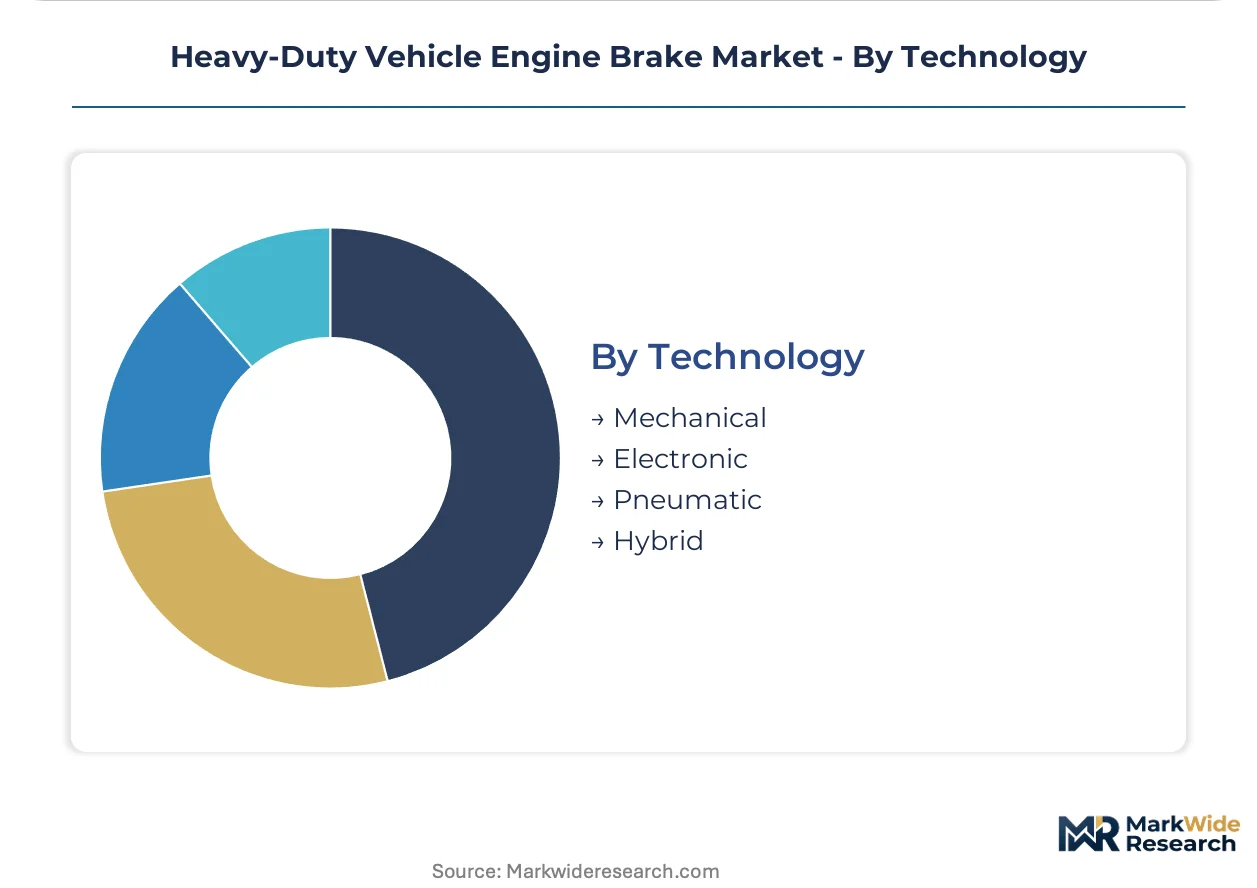
Technology:
Control system architecture is shifting from pneumatic actuation toward software-defined electronic modulation.
- Mechanical:Cam-driven and cable-actuated valve train systems with fixed timing profiles. Legacy installed base remains substantial in developing markets, though electronic displacement is accelerating in premium German and United States truck configurations.
- Electronic:Software-defined actuator control with telematics integration and predictive deceleration algorithms. Electronic control modules are capturing recurring service revenue streams that mechanical manufacturers cannot access.
- Pneumatic:Air-pressure-actuated valve systems with established service infrastructure.
- Hybrid:Combined electronic-pneumatic architectures for retrofit compatibility.
Mechanical systems retain the largest installed base while electronic configurations climb the fastest as brake-by-wire integration advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States runs a structural surplus in heavy-duty engine brake systems, exporting compression release technologies to European alpine fleets while importing electronic actuator components from German precision machining clusters. Germany and China maintain balanced trade positions in exhaust brake hardware, with China increasingly supplying valve train subassemblies to North American retrofit channels.
United States
Class 8 truck fleets across interstate corridors drive specification velocity for compression release retrofits under EPA Phase 3 GHG standards. NHTSA downhill speed control mandates for vehicles exceeding 26,000 pounds GVW enforce minimum deceleration capabilities. Michigan-based engineering clusters near Detroit anchor OEM supply agreements with integrated brake system validation facilities.
Germany
Autobahn speed differentials and alpine freight routes sustain demand for premium electronic actuator configurations in heavy-duty tractor-trailers. KBA enforces ECE R13 braking performance benchmarks that exceed baseline European requirements. Baden-Württemberg precision machining suppliers concentrate valve train component production for compression release brake assemblies serving Austrian and Swiss export markets.
China
Domestic commercial vehicle production scales drive volume demand for exhaust brake systems in medium-duty truck platforms. MIIT fuel efficiency standards for heavy commercial vehicles mandate auxiliary braking integration in new chassis designs. Shandong Province manufacturing clusters supply flap-valve exhaust brake hardware to Southeast Asian aftermarket channels.
Switzerland
Alpine intercity bus operators face the steepest ECE R13 grade-performance requirements across European corridors, accelerating replacement cycles for compression release hardware. Swissmedic does not regulate vehicle equipment; transport safety falls under federal transport authority enforcement. Zurich logistics hubs coordinate cross-border brake retrofit programs serving Austrian and northern Italian fleet operators.
India
Commercial vehicle brake standardization under BIS implementation creates specification windows for electronic actuator suppliers entering heavy truck segments. The country's national automotive regulator is tightening braking performance requirements for multi-axle trucks and intercity coaches. Maharashtra-based vehicle assemblers integrate exhaust brake systems for domestic mining and construction vocational applications.
Heavy-Duty Vehicle Engine Brake Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct capability tiers. Integrated powertrain manufacturers control OEM specification channels through captive brake system engineering. Specialized brake component suppliers anchor aftermarket retrofit volumes through independent service networks. Electronic control module developers capture recurring software service revenue streams unavailable to mechanical actuator producers. Capacity expansion in precision machining clusters and strategic partnerships for telematics integration represent the dominant competitive moves reshaping supplier positioning.
Among European integrated manufacturers, AB Volvo and MAN SE exemplify the captive engineering archetype, bundling brake system development with chassis platform design. Jacobs Vehicle Systems occupies a central position in North American OEM supply relationships, representing the specialized component tier that dominates compression release brake specification. Eaton anchors the aftermarket service network archetype through extensive maintenance infrastructure sustaining retrofit and replacement revenue channels.
| Leading Market Players |
|---|
| AB Volvo |
| FAW Group |
| Eaton |
| Jacobs Vehicle Systems |
| MAN SE |
| Scania Group |
| Pacbrake |
| Streparava |
| Voith Group |
| Others |
Supply & Pricing Matrix
United States interstate corridors impose cost dynamics that concentrate supply leverage among German precision machining clusters while fragmenting downstream pricing power across asset-light fleet operators. Electronic actuator suppliers command premium positioning through ISO 26262 certification tiers, whereas pneumatic component manufacturers face compression from retrofit compatibility demands.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on ISO 26262 certification grade and after-sales service bundling. Cost compression in the electronic control module tier is intensifying because rare earth input volatility feeds through electromagnetic actuator production. Fleet operators exhibit highest price sensitivity on retrofit exhaust brake hardware, while OEM platform engineering teams absorb premium pricing for brake-by-wire integration.
Supply Chain Analysis
Extended payment terms from German valve train suppliers are tightening working capital requirements for North American compression release brake assemblers. Manufacturing concentrates in Germany, China, and the United States. Component sourcing draws from precision-machined steel valve train parts, rare earth electromagnetic materials, and electronic control firmware. Single-source vulnerability runs through Baden-Württemberg machining clusters. Distribution runs through OEM captive channels, independent aftermarket networks, and leasing intermediary bundling arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat structure where regulatory entrenchment protects incumbent positioning through ISO 26262 validation timelines that extend product development cycles beyond entrant capital endurance.
For Market Incumbents: Insulate OEM supply relationships through captive certification investment in brake-by-wire integration protocols. Deepen backward integration into electronic actuator firmware development to capture recurring service revenue streams that mechanical competitors cannot access. Capacity addition in precision machining clusters near Stuttgart defends against supply bottleneck exposure from single-source valve train dependencies. For New Entrants and Emerging Players: Indian commercial vehicle brake standardization under BIS implementation offers the most penetrable specification window for electronic actuator suppliers seeking first-mover positioning. Target pay-per-mile financing channels through leasing intermediary partnerships rather than direct OEM specification contests. Alpine route bus retrofit demand in Switzerland and Austria provides faster revenue validation than North American Class 8 truck OEM supply cycles. For Investors and Strategic Acquirers: Specialized electronic control module developers with embedded software service contracts represent the highest-conviction acquisition archetype. Long-term viability across the analysis window hinges on brake-by-wire convergence with autonomous emergency braking mandates. Monitor NHTSA downhill speed control rulemaking expansion as the inflection signal for compression release brake retrofit demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 26262 Certification Investment | Functional safety validation extends development timelines beyond entrant capital endurance. |
| Telematics Integration Partnership | Fleet data platforms enable predictive maintenance revenue streams for brake suppliers. |
| Backward Integration into Firmware | In-house electronic actuator control captures margin pools from pneumatic displacement. |
| Alpine Route Service Network Expansion | ECE R13 enforcement in Switzerland and Austria accelerates replacement cycle velocity. |
| Pay-per-Mile Financing Channel Development | Asset-light leasing structures unbundle brake specification from vehicle purchase decisions. |
Research Methodology
Initial hypotheses were tested against primary input from OEM platform engineers, fleet maintenance directors, aftermarket service network managers, and electronic control module firmware developers and refined through secondary validation. Sources included NHTSA rulemaking dockets, EPA Phase 3 GHG technical documentation, ECE R13 braking performance standards, vehicle production databases, and SEC filings from listed brake system suppliers. Bottom-up triangulation across fleet procurement surveys and top-down reconciliation with regulatory mandate implementation timelines anchored value estimates.
Demand-supply balance modeling across the projection horizon incorporated product type segmentation by brake mechanism, technology tier by control architecture, end-user category by procurement authority, and application severity by route grade. CAGRs were derived from replacement cycle analysis intersecting regulatory compliance deadlines. Industry-specific forecast inputs included EPA Phase 3 implementation pacing, ECE R13 enforcement intensity across alpine corridors, and brake-by-wire adoption curves in premium truck configurations.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese exhaust brake manufacturers or accelerated electrification timelines from major OEMs would shift outcomes. Macroeconomic freight volume contraction, regulatory delay, or autonomous vehicle deployment acceleration would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy-Duty Trucks
Articulated Dump Trucks Market
Heavy-Duty Trucks
Middle East Refrigerated Truck Market
Heavy-Duty Trucks
Dump Trucks Market
Heavy-Duty Trucks
Digger Derrick Truck Market
Heavy-Duty Trucks
Stacker Truck Market
Heavy-Duty Trucks
Global Boom Truck Market
Heavy-Duty Trucks
Truck Diagnostic Market
Heavy-Duty Trucks
Europe Medium and Heavy-Duty Commercial Vehicles Market
Heavy-Duty Trucks
Europe Medium & Heavy-Duty Truck Rental Market
Heavy-Duty Trucks
High Performance Trucks Market
Heavy-Duty Trucks
North America Heavy Commercial Vehicle (HCV) TMPS Market
Heavy-Duty Trucks
Global Vocational Truck Market
Heavy-Duty Trucks
China Full-Truck-Load (FTL) Market
Heavy-Duty Trucks
United States Tank Trucking Market
Heavy-Duty Trucks
Garbage Truck Bodies Market
Heavy-Duty Trucks
China Full Truckload Road Freight Transport Market