
 North America Heavy Commercial Vehicle (HCV) TMPS Market | 2026-2036
North America Heavy Commercial Vehicle (HCV) TMPS Market Size, Share, and Industry Trends Forecast 2026-2036
North America Heavy Commercial Vehicle (HCV) TMPS Market Analytics
Long-haul freight is rebalancing toward dedicated contract carriage and refrigerated transport, two segments where tire failure costs exceed USD 1,000 per incident. Continental leverages its integrated sensor-to-telemetics pipeline to anchor OEM supply agreements with Detroit-based truck manufacturers. Sensata Technologies competes through MEMS pressure sensor specialization, while Doran Manufacturing sustains aftermarket channel control via direct fleet service networks.
The North America Heavy Commercial Vehicle (HCV) TMPS comprises tire-mounted pressure and temperature sensors, typically operating at 433 MHz RF transmission with battery life exceeding seven years, designed to prevent blowouts and optimize tread wear in vehicles above Class 6 GVWR. Electronic product types lead installed base volume due to real-time data integration with fleet telematics platforms, while Smart segments capture fastest growth as AI-enabled predictive analytics migrate from premium to mid-tier fleet contracts. Application demand tilts toward Logistics over Mining, since route predictability justifies sensor investment payback periods.
NHTSA's Federal Motor Vehicle Safety Standards and the U.S. DOT's Compliance, Safety, Accountability program shape product certification requirements and fleet adoption timelines across the United States. Transport Canada's Motor Vehicle Safety Act and CMVSS 138 align closely with U.S. technical specifications, reducing cross-border product fragmentation. Stakeholders must monitor emerging state-level zero-emission truck mandates in California and Quebec, as electric powertrain weight distribution changes tire load profiles and sensor calibration protocols.
Market Dynamics
Fleet telematics integration is compressing sensor procurement cycles as operators demand unified data streams from tire pressure monitors, engine diagnostics, and electronic logging devices through single vendor contracts.
Growth Catalysts
- NHTSA Federal Motor Vehicle Safety Standards:Mandates for commercial vehicle safety systems are accelerating TMPS retrofit installations in heavy-duty fleets operating across interstate corridors.
- Cross-border freight density:The Texas-Mexico freight corridor generates concentrated sensor demand as logistics operators optimize tire performance on high-volume international routes.
- Refrigerated transport specialization:Temperature-sensitive cargo carriers face tire failure costs exceeding operational thresholds, justifying premium monitoring system deployment.
Market Restraints
- Sensor battery supply concentration:Lithium primary cell manufacturing concentrates in East Asian suppliers, exposing North American TMPS vendors to raw material allocation disruptions.
- 433 MHz spectrum congestion:RF interference from overlapping industrial applications in the Great Lakes industrial corridor degrades signal reliability in dense fleet deployments.
- Retrofit installation labor costs:Class 8 truck sensor mounting requires specialized wheel service equipment, limiting aftermarket penetration among smaller owner-operator fleets.
Strategic Opportunities
- California zero-emission truck mandates:Electric powertrain weight distribution shifts are creating demand for recalibrated load-sensing algorithms in next-generation TMPS units.
- AI-enabled predictive maintenance:Machine learning convergence with tire wear modeling allows fleet managers to transition from reactive to scheduled replacement protocols.
- Direct fleet service networks:Bypassing traditional parts distributors through mobile installation units captures margin from time-sensitive logistics operators.
Industry Challenges
- Telematics platform fragmentation:Proprietary data protocols from competing fleet management systems force sensor manufacturers to maintain multiple firmware variants.
- Cross-border certification alignment:Transport Canada's CMVSS 138 and NHTSA standards require parallel testing programs, extending product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Heavy Commercial Vehicle (HCV) TMPS Market |
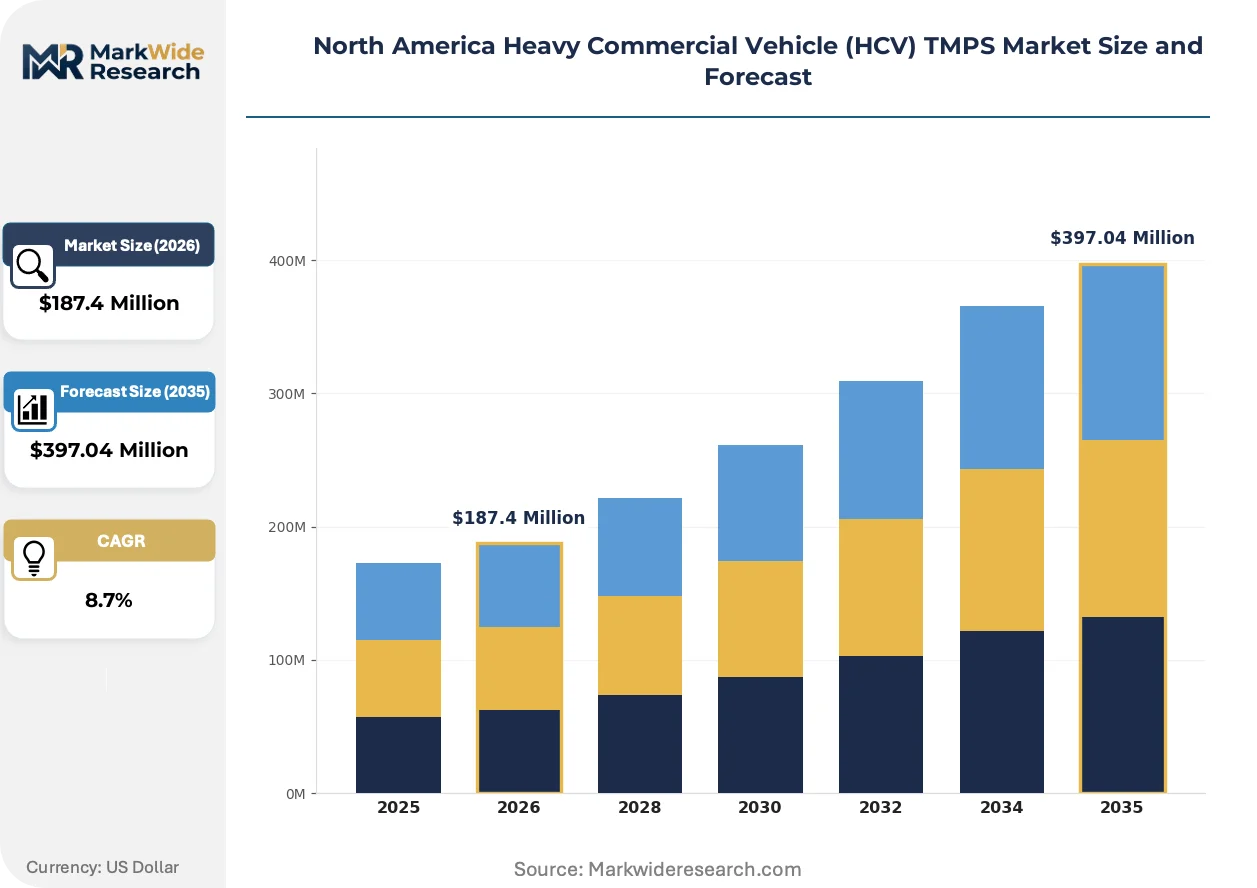
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical, Electronic, Hybrid, Smart Application: Transportation, Construction, Mining, Logistics End User: Fleets, OEMs, Aftermarket Providers, Dealers Installation: Original Equipment, Retrofit, DIY, Professional |
| Companies Covered | Valor, Continental, Bendix Commercial Vehicle Systems LLC, Pacific Industrial, ZF, BH SENS Group, Schrader TPMS Solutions, Sensata Technologies, Doran Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Heavy Commercial Vehicle (HCV) TMPS Market Evolving Landscape
Edge computing architectures are migrating tire data processing from centralized fleet servers to sensor-mounted microcontrollers, reducing latency for critical safety alerts while compressing cellular data transmission costs.
Bluetooth Low Energy mesh networking is decentralizing TMPS architecture by enabling direct sensor-to-cab communication without dedicated RF receivers. Regional less-than-truckload carriers are piloting these configurations to simplify retrofits on mixed-voltage electrical systems. The technology is decentralizing supplier power by reducing dependency on proprietary telematics gateway providers.
NHTSA's phased enforcement of electronic logging device integration requirements is forcing sensor manufacturers to certify dual-protocol compatibility with dominant fleet management platforms. Heavy-duty truck OEMs in Michigan and Ohio are now specifying unified data bus architectures that embed tire pressure signals directly into engine control module outputs. The regulation most impacts long-haul contract carriage fleets operating under strict hours-of-service compliance.
Fleet procurement departments are consolidating sensor purchasing under multi-year vehicle lifecycle contracts rather than transactional replacement orders. Third-party fleet maintenance providers are capturing installation revenue previously retained by dealer networks. This consolidation is most advanced among refrigerated transport operators in the Midwest who coordinate seasonal tire changeovers with sensor recalibration services.
North America Heavy Commercial Vehicle (HCV) TMPS Market Segmentation
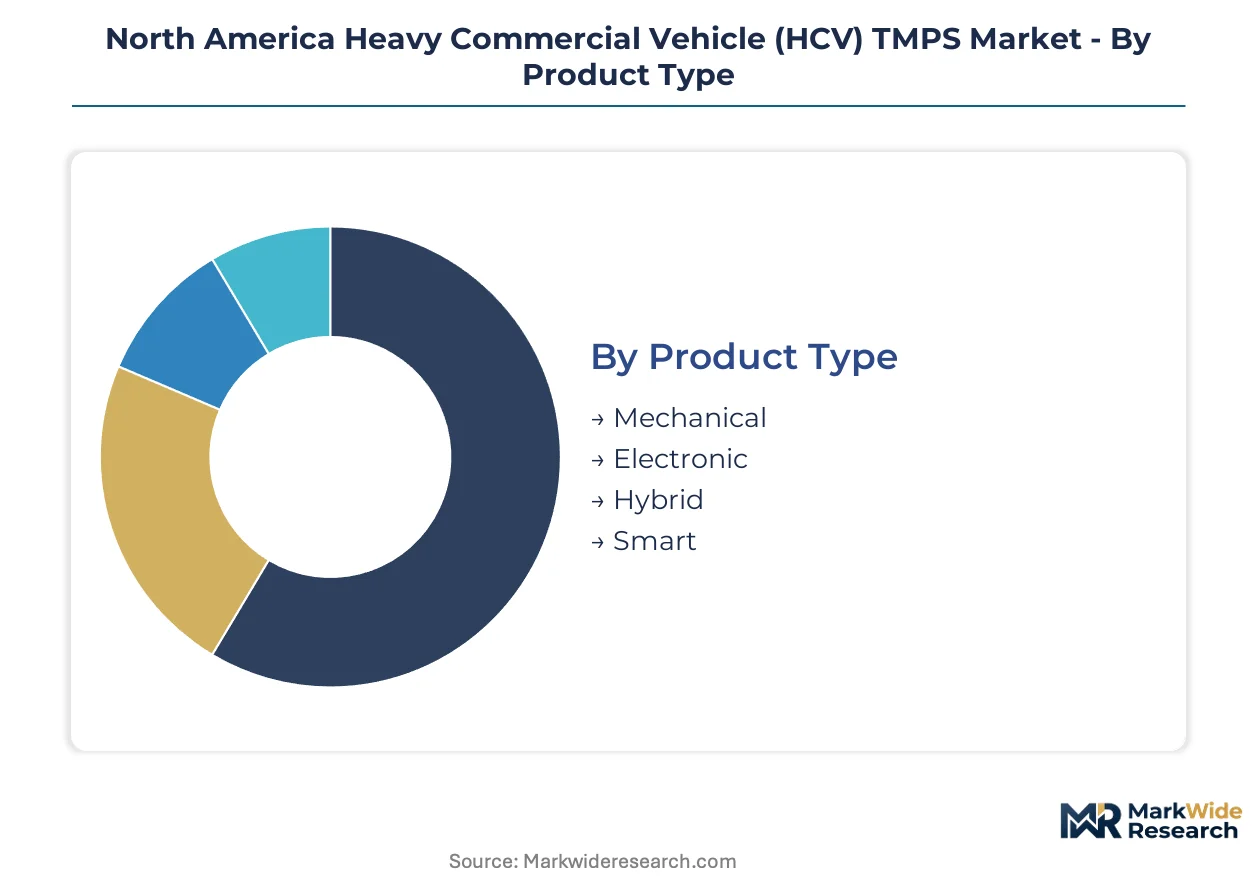
TMPS purchasing decisions in North American heavy commercial vehicles split sharply between upfront system integration and lifecycle cost optimization. Fleet procurement teams weigh sensor durability against telematics compatibility when selecting across product tiers, while application-specific duty cycles determine installation modality.
Product Type:
Volume concentration favors established electronic architectures, while premium expansion concentrates in AI-enabled configurations that command higher per-unit pricing.
- Mechanical:Pressure-indicator valve caps and spring-loaded gauges operate without electrical components. Demand persists among owner-operators in the Texas-Mexico corridor seeking minimal maintenance overhead on older Class 8 tractors.
- Electronic:Battery-powered sensors transmit 433 MHz RF signals to dashboard receivers with seven-plus-year operational life. Long-haul refrigerated fleets across the Great Lakes industrial corridor specify these units for real-time pressure alerts that prevent cargo spoilage from tire-related delays.
- Hybrid:Combines mechanical redundancy with electronic logging for dual-mode operation. Regional less-than-truckload carriers favor this configuration for mixed-voltage electrical systems.
- Smart:Edge-computing microcontrollers process tread wear algorithms locally. California zero-emission truck mandates are accelerating deployment as electric powertrain weight distribution requires recalibrated load-sensing protocols.
Mature deployment sits with Electronic. Newer deployment is concentrated in Smart.
Application:
Route predictability separates investment-ready segments from those where sensor payback periods remain unfavorable.
- Logistics:Dedicated contract carriage operators with fixed hub-and-spoke networks achieve measurable fuel savings from optimized tire pressure maintenance. Cross-border freight density along the Texas-Mexico corridor generates concentrated procurement volume.
- Transportation:Scheduled route operators with repeatable mileage profiles justify sensor capital expenditure through reduced roadside assistance calls. Interstate passenger carriers face NHTSA Federal Motor Vehicle Safety Standards compliance deadlines.
- Construction:Variable terrain and short-haul duty cycles compress sensor lifespan. Off-highway tire damage patterns differ substantially from over-the-road applications.
- Mining:Extreme load conditions and remote site access limit real-time monitoring utility. Pit-to-port operators prioritize mechanical inspection protocols over electronic surveillance.
Established adoption clusters in Logistics. Emerging traction is strongest in Transportation.
End User:
Procurement centralization is redistributing margin capture from distribution channels to direct service relationships.
- Fleets:Multi-year vehicle lifecycle contracts consolidate sensor purchasing under fleet procurement departments. Midwest refrigerated transport operators coordinate seasonal tire changeovers with sensor recalibration services.
- OEMs:Detroit-based truck manufacturers specify unified data bus architectures embedding tire pressure signals into engine control module outputs. Factory installation ensures telematics gateway compatibility from vehicle delivery.
- Aftermarket Providers:Third-party fleet maintenance providers capture installation revenue previously retained by dealer networks. Mobile service units bypass traditional parts distributors for time-sensitive operators.
- Dealers:Service bay capacity constraints limit retrofit throughput. Specialized wheel service equipment requirements restrict penetration among smaller independent operators.
Volume leadership resides with Fleets. Margin expansion concentrates in Aftermarket Providers.
Installation:
Labor specialization requirements create tiered access barriers that segment the addressable market by fleet scale.
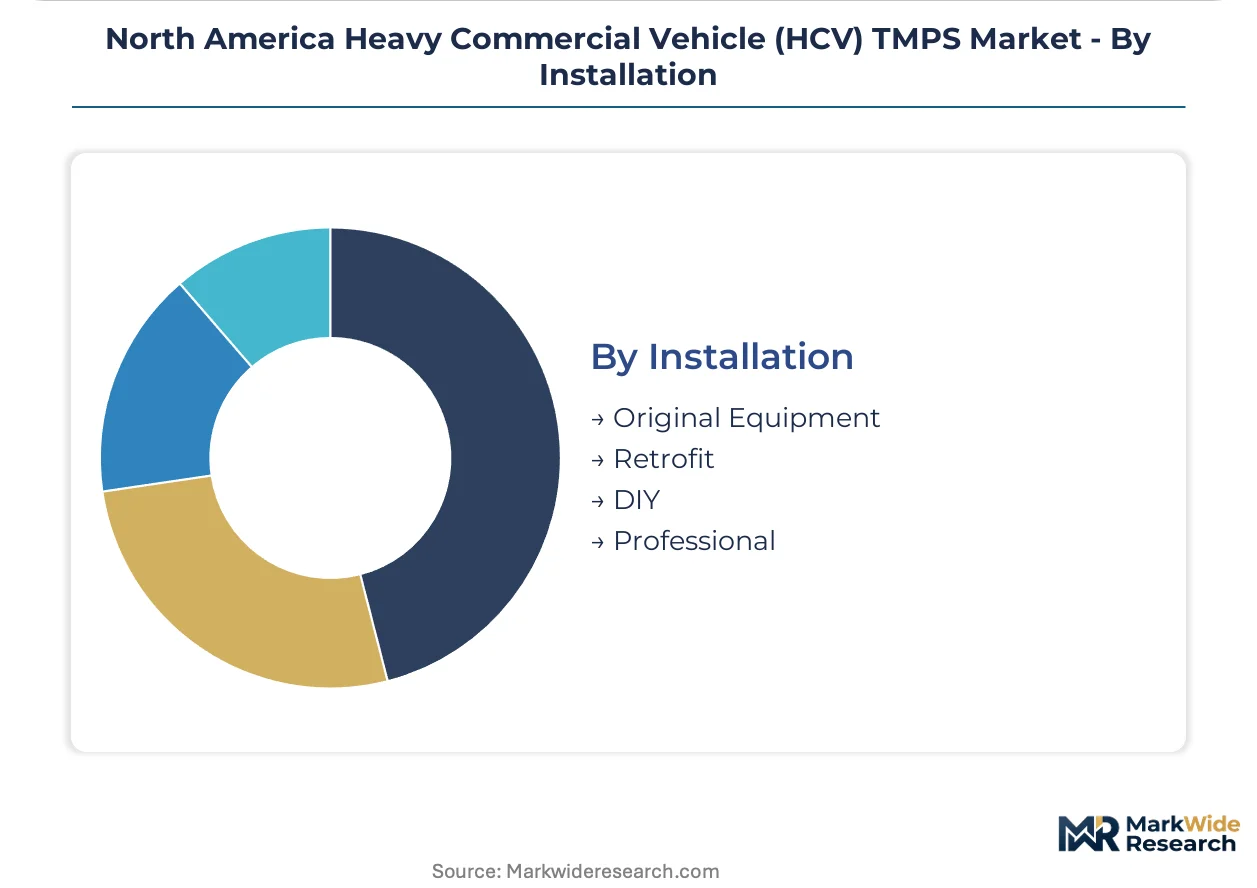
- Original Equipment:Factory-integrated sensors ship with calibrated RF protocols matched to specific telematics platforms. OEM supply agreements lock in multi-year component sourcing commitments.
- Professional:Certified technicians mount sensors using specialized tire service equipment. Class 8 truck wheel handling requirements exclude general automotive repair facilities.
- Retrofit:Post-purchase installation demands protocol compatibility verification with existing fleet management systems. Proprietary data formats from competing telematics platforms force sensor manufacturers to maintain multiple firmware variants.
- DIY:Programmable sensor tools allow owner-operators to clone existing sensor IDs during tire rotation. Limited penetration reflects liability concerns and warranty voiding risks.
Scale concentration favors Original Equipment. Accessibility expansion is concentrated in Professional.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Texas-Mexico freight corridor's foreign-trade-zone incentives concentrate cross-border logistics investment, driving sensor demand along the heaviest truck-traffic routes in North America. Fleet operators cluster near Laredo-Nuevo Laredo and Eagle Pass-Piedras Negras to minimize customs delays and maximize tire-monitoring ROI on high-frequency international runs.
United States
The Great Lakes industrial corridor generates dense procurement volume from refrigerated transport fleets serving Chicago-Detroit-Toronto distribution networks. NHTSA's Federal Motor Vehicle Safety Standards mandate electronic logging device integration, pushing sensor manufacturers toward unified data bus architectures. Michigan-based heavy-duty truck OEMs now embed tire pressure signals directly into engine control module outputs from factory delivery.
Canada
Transport Canada's CMVSS 138 alignment with U.S. technical specifications reduces cross-border product fragmentation for manufacturers serving Ontario-Quebec freight lanes. The Motor Vehicle Safety Act enforces parallel certification requirements that extend product launch timelines but preserve market access. Quebec's zero-emission truck mandates are recalibrating load-sensing protocols for electric powertrain weight distribution shifts in Montreal-Toronto corridor operations.
Mexico
Manufacturing export growth through Nuevo León and Tamaulipas generates concentrated aftermarket demand as cross-border carriers upgrade aging Class 8 tractor fleets. Mexico's Secretariat of Economy automotive regulations increasingly harmonize with U.S. DOT safety standards, simplifying sensor import logistics. The Laredo-Colombia Solidarity International Bridge corridor records the highest heavy truck density per mile in North America, justifying premium monitoring system deployment.
North America Heavy Commercial Vehicle (HCV) TMPS Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with OEM supply agreements concentrating volume among integrated system providers while aftermarket channels sustain fragmented service competition. The vendor base organizes around three strategic archetypes: sensor-to-telematics integrators, MEMS pressure specialists, and direct fleet service network operators. Dominant competitive moves include multi-year vehicle lifecycle contracting and mobile installation unit deployment to bypass traditional distribution.
Among the integrated system providers, Continental and ZF exemplify the OEM-anchored archetype through factory-installation relationships with Detroit-based manufacturers. Sensata Technologies occupies a position within the component-specialist tier, while Doran Manufacturing represents the direct-service network model. These three companies illustrate how competitive positioning diverges between upfront system integration and lifecycle cost optimization strategies.
| Leading Market Players |
|---|
| Valor |
| Continental |
| Bendix Commercial Vehicle Systems LLC |
| Pacific Industrial |
| ZF |
| BH SENS Group |
| Schrader TPMS Solutions |
| Sensata Technologies |
| Doran Manufacturing |
| Others |
Value Network & Pricing Analysis
California's zero-emission truck mandates gate qualified sensor supply and premium-tier pricing access, as electric powertrain weight distribution shifts demand recalibrated load-sensing protocols that only certified manufacturers can deliver. Fleet procurement departments now consolidate multi-year vehicle lifecycle contracts, compressing margin capture toward OEM-anchored integrators and direct-service network operators while squeezing transactional aftermarket channels.
Pricing Analysis
Short lead-time premiums command pricing power as refrigerated transport operators facing NHTSA compliance deadlines pay 15-25% markups for expedited sensor delivery and same-day installation services. Three-tier pricing structure across premium, standard, and economy levels stratifies by telematics integration depth, with AI-enabled predictive analytics units capturing highest per-unit pricing. Cost compression in standard electronic tiers is intensifying because lithium primary cell supply bottlenecks force component substitution. Owner-operators in the Texas-Mexico corridor exhibit highest price sensitivity, while dedicated contract carriage fleets show lowest sensitivity due to cargo spoilage cost exposure.
Supply Chain Analysis
Lithium primary cell manufacturing rests on concentrated East Asian suppliers, exposing North American TMPS vendors to raw material allocation disruptions when regional production pauses trigger allocation protocols. Sensor microcontroller fabrication draws from Taiwan and South Korea, while RF transmitter components source from Japan and China. Single-source vulnerability concentrates in 433 MHz RF chipsets where qualified alternative suppliers require 18-month qualification cycles. Distribution runs through Detroit-based OEM supply agreements, aftermarket mobile installation units, and third-party fleet maintenance providers serving cross-border logistics corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Heavy Commercial Vehicle TMPS market sits in a technology-transition phase as edge-computing microcontrollers displace centralized fleet server architectures, forcing sensor manufacturers to retool firmware development pipelines.
For Market Incumbents: Hedge against Bluetooth Low Energy mesh networking decentralization by maintaining dual-protocol firmware variants for legacy RF and emerging direct sensor-to-cab configurations. Deepen backward integration into lithium primary cell supply through offtake agreements with Korean suppliers, countering East Asian allocation risk. Secure NHTSA certification for unified data bus architectures before electronic logging device integration deadlines tighten. For New Entrants and Emerging Players: Direct-to-fleet digital procurement platforms bypass entrenched parts distribution networks, enabling margin capture from time-sensitive refrigerated transport operators. Target regional less-than-truckload carriers piloting mixed-voltage electrical system retrofits, the most penetrable segment where incumbent sensor-to-telematics pipelines lack flexibility. Lead with mobile installation unit partnerships that compress deployment timelines versus dealer network dependency. For Investors and Strategic Acquirers: California Air Resources Board zero-emission truck mandate acceleration is the leading indicator that recalibrated load-sensing algorithm demand will concentrate acquisition value in sensor-to-telematics integrators with electric powertrain calibration capabilities. Long-term viability favors vendors with OEM supply agreements locked through the analysis window. Watch for NHTSA phased enforcement signals on electronic logging device integration as inflection triggers for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Computing Firmware Development | Reduces latency for critical safety alerts while compressing cellular data transmission costs for fleet operators. |
| Bluetooth Low Energy Mesh Certification | Decentralizes TMPS architecture and reduces dependency on proprietary telematics gateway providers. |
| Mobile Installation Unit Deployment | Captures installation revenue from time-sensitive logistics operators bypassing traditional dealer networks. |
| Multi-Year Vehicle Lifecycle Contracting | Locks in sensor purchasing under fleet procurement departments and secures OEM supply agreement extensions. |
| Zero-Emission Load-Sensing Recalibration | Addresses electric powertrain weight distribution shifts required by California and Quebec mandates. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with fleet procurement directors, OEM platform engineers, aftermarket service technicians, and telematics integration specialists. NHTSA Federal Motor Vehicle Safety Standards documentation, Transport Canada CMVSS 138 certification records, and U.S. DOT electronic logging device compliance databases provided regulatory boundary conditions. Bottom-up sensor shipment estimates triangulated against top-down fleet telematics adoption curves.
Data-stream reconciliation across product type, application, end user, and installation modality dimensions produced volume and value outputs over the projection horizon. CAGRs derived from logistic growth curve fitting against fleet replacement cycle timing and regulatory compliance deadline clustering. Electric powertrain weight distribution modeling and 433 MHz spectrum congestion impact scenarios informed scenario-weighted forecast ranges.
Inputs from fleet operator interviews and OEM specification sheets were available through the study window; gaps in real-time telematics platform data sharing protocols introduce uncertainty bands around AI-enabled predictive maintenance adoption curves. Forecasts reflect documented assumptions regarding NHTSA enforcement timing and cross-border freight density growth. A small set of triggers—California zero-emission mandate acceleration, lithium cell supply disruptions, and Bluetooth Low Energy standard finalization—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy-Duty Trucks
Global Vocational Truck Market
Heavy-Duty Trucks
Automotive High Performance Trucks Market
Heavy-Duty Trucks
Stacker Truck Market
Heavy-Duty Trucks
Truck Racks Market
Heavy-Duty Trucks
United States Tank Trucking Market
Heavy-Duty Trucks
Hard Tonneau Cover Market
Heavy-Duty Trucks
High Performance Trucks Market
Heavy-Duty Trucks
Truck Tank Market
Heavy-Duty Trucks
Global Connected Truck Market
Heavy-Duty Trucks
Europe Fire Truck Market
Heavy-Duty Trucks
Heavy-Duty Truck Axle Locking Actuator Components Market
Heavy-Duty Trucks
Logging Trucks Market
Heavy-Duty Trucks
Hydrogen Trucks Market
Heavy-Duty Trucks
Turret Truck Market
Heavy-Duty Trucks
North America Vacuum Truck Market
Heavy-Duty Trucks
Big Rig Trucks Market