
 Truck Headache Rack Market | 2026-2036
Truck Headache Rack Market Size, Share, and Industry Trends Forecast 2026-2036
Truck Headache Rack Market Insights
Welding and metal fabrication labor availability is redrawing production capacity across the truck headache rack supply chain. BACKRACK leverages its Canadian manufacturing base to sustain consistent alloy rack output for North American fleet channels. Dee Zee anchors its position through vertical control over aluminum extrusion operations in Iowa. Highway Products competes via specialized custom fabrication for utility and energy sector contractors.
A truck headache rack is a protective framework mounted behind a truck cab, typically fabricated from steel or aluminum tubing with welded or bolt-on mounting brackets, designed to shield occupants from shifting cargo during sudden stops or collisions. The assembly integrates with stake pockets or bed rails and often accommodates lighting, tool storage, or ladder racks for commercial duty cycles. Steel product types still dominate fleet procurement for their impact resistance, though aluminum variants are gaining fastest among operators prioritizing payload recovery. Bolt-on installation types occupy the broadest aftermarket channel, while welded configurations concentrate in OEM and severe-service applications where structural integrity standards are highest.
NHTSA Federal Motor Vehicle Safety Standards govern cab protection requirements for commercial trucks operating in the United States, while EPA emissions regulations indirectly shape rack demand by extending truck replacement cycles and preserving aftermarket retrofit activity. OSHA workplace safety directives for construction and utility fleets mandate load-securement protocols that reinforce specification-grade headache rack adoption. Stakeholders must monitor how proposed updates to FMVSS occupant protection rules could redefine minimum load-barrier performance thresholds and disqualify non-compliant legacy inventory.
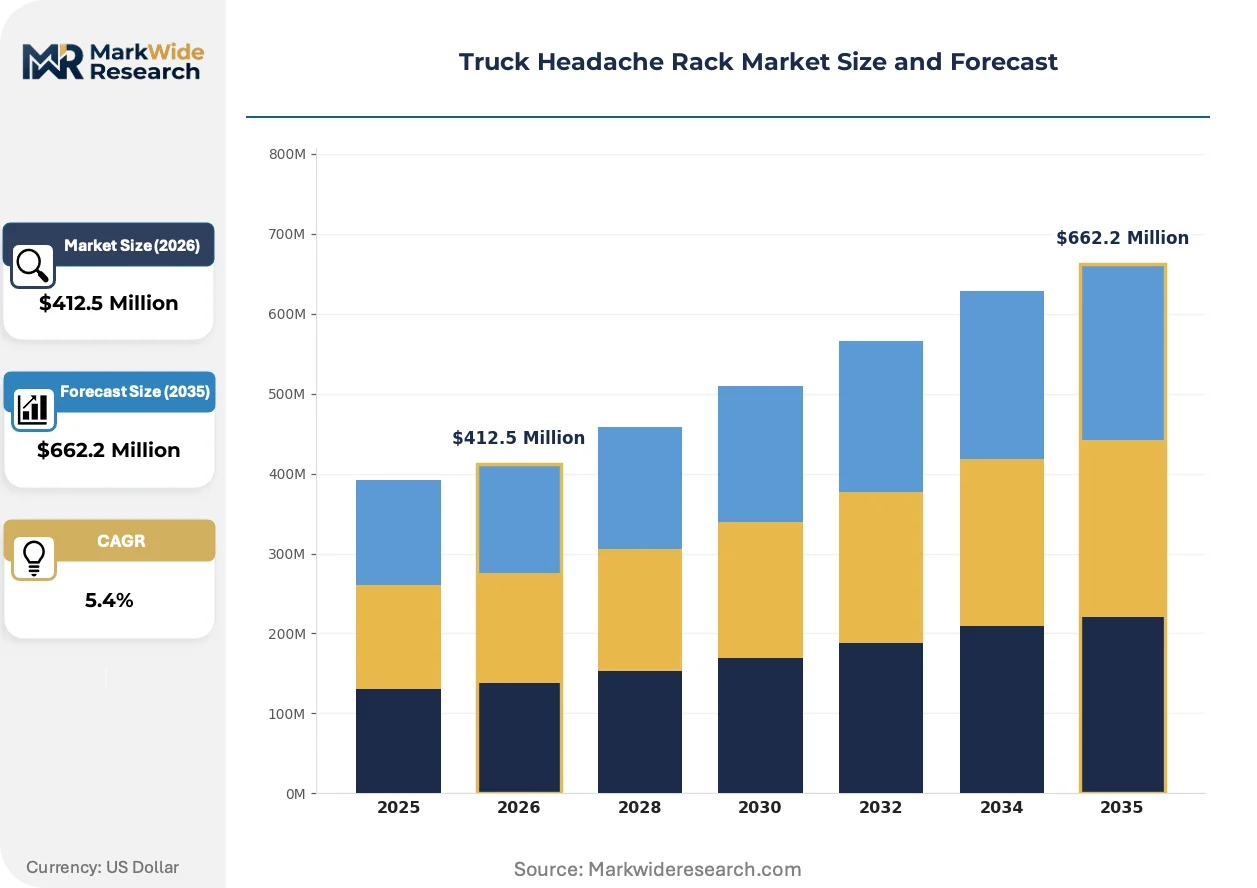
Market Dynamics
NHTSA's proposed FMVSS occupant protection updates are compressing design certification timelines and forcing alloy specification upgrades across the supply base before rule finalization.
Growth Catalysts
- FMVSS Load-Barrier Thresholds:Pending NHTSA revisions mandate higher impact resistance for cab protection equipment, compelling fleet replacement of legacy racks and expanding specification-grade procurement channels.
- OSHA Construction Mandates:Federal workplace safety directives for utility and energy contractors require documented load-securement protocols, directly specification-grade headache rack adoption on work trucks.
- Great Plains Agricultural Intensity:Grain transport and equipment hauling across Texas, Kansas, and Nebraska generates sustained demand for severe-service welded configurations with integrated tool storage.
Market Restraints
- Aluminum Extrusion Supply Concentration:Primary billet sourcing clusters in the US Midwest and Canadian smelter networks create geographic vulnerability to energy cost volatility and tariff exposure.
- Welding Labor Scarcity:Certified aluminum TIG welders command premium wages in fabrication hubs, constraining production scale-up for OEM severe-service contracts.
- Steel Weight Penalty:Fleet operators face payload recovery losses of 150-200 pounds versus aluminum alternatives, creating procurement friction in weight-sensitive applications.
Strategic Opportunities
- California CARB-Compliant Electrification:Battery-electric truck deployments in the state's Central Valley agricultural corridor require lightweight cab protection to preserve range, favoring advanced aluminum honeycomb designs.
- Integrated Telematics Mounting:Convergence of antenna arrays, camera systems, and sensor pods creates white space for rack-integrated connectivity hardware in last-mile logistics fleets.
- E-Commerce Direct Channel:Bolt-on aftermarket configurations bypass traditional distributor markups through manufacturer-direct digital procurement, capturing price-sensitive owner-operators.
Industry Challenges
- FMVSS Pre-Compliance Testing Burden:Third-party crash simulation and physical barrier testing extend product development cycles months before formal rule adoption.
- Legacy Stake-Pocket Incompatibility:New truck bed rail designs from Detroit manufacturers fragment mounting hardware standards, forcing SKU proliferation and inventory complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Truck Headache Rack Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $662.2 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel, Aluminum, Plastic, Composite Installation Type: Welded, Bolt-On, Clamp-On, Integrated End User: Fleet Operators, Individual Owners, Commercial Users, Agricultural Users Feature: Lightweight, Adjustable, Durable, Customizable |
| Companies Covered | BACKRACK, Dee Zee, ARIES, Buyers Products, Go Rhino, Highway Products, RealTruck, Westin, Putco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Truck Headache Rack Market Trends and Innovations
Active material substitution and mounting system modularity are compressing traditional product lifecycles while regulatory pre-positioning accelerates R&D allocation ahead of rule finalization.
Aluminum-magnesium alloy tubing with robotic pulse-arc welding is displacing conventional steel fabrication in fleet procurement specifications. Owner-operators and regional LTL carriers in the Southeastern United States prioritize these configurations for fuel economy gains and corrosion resistance. The shift is displacing incumbent steel rack fabricators from premium fleet channels and compressing margin structures for single-material producers.
NHTSA's pending FMVSS occupant protection updates are forcing structural redesign of load-barrier geometries and mounting bracket shear strength. Engineering teams must validate new configurations through third-party crash simulation before rule formalization. Severe-service OEM applications in energy and utility sectors face the steepest compliance timelines and pre-certification investment requirements.
Fleet procurement offices are consolidating vendor relationships and demanding consolidated cab protection, lighting, and storage packages rather than discrete component sourcing. National LTL operators and agricultural cooperatives in the Midwestern United States drive this specification bundling. The pattern concentrates purchasing power with vertically integrated rack manufacturers capable of delivering configured assemblies direct to upfit facilities.
Truck Headache Rack Market Segmentation
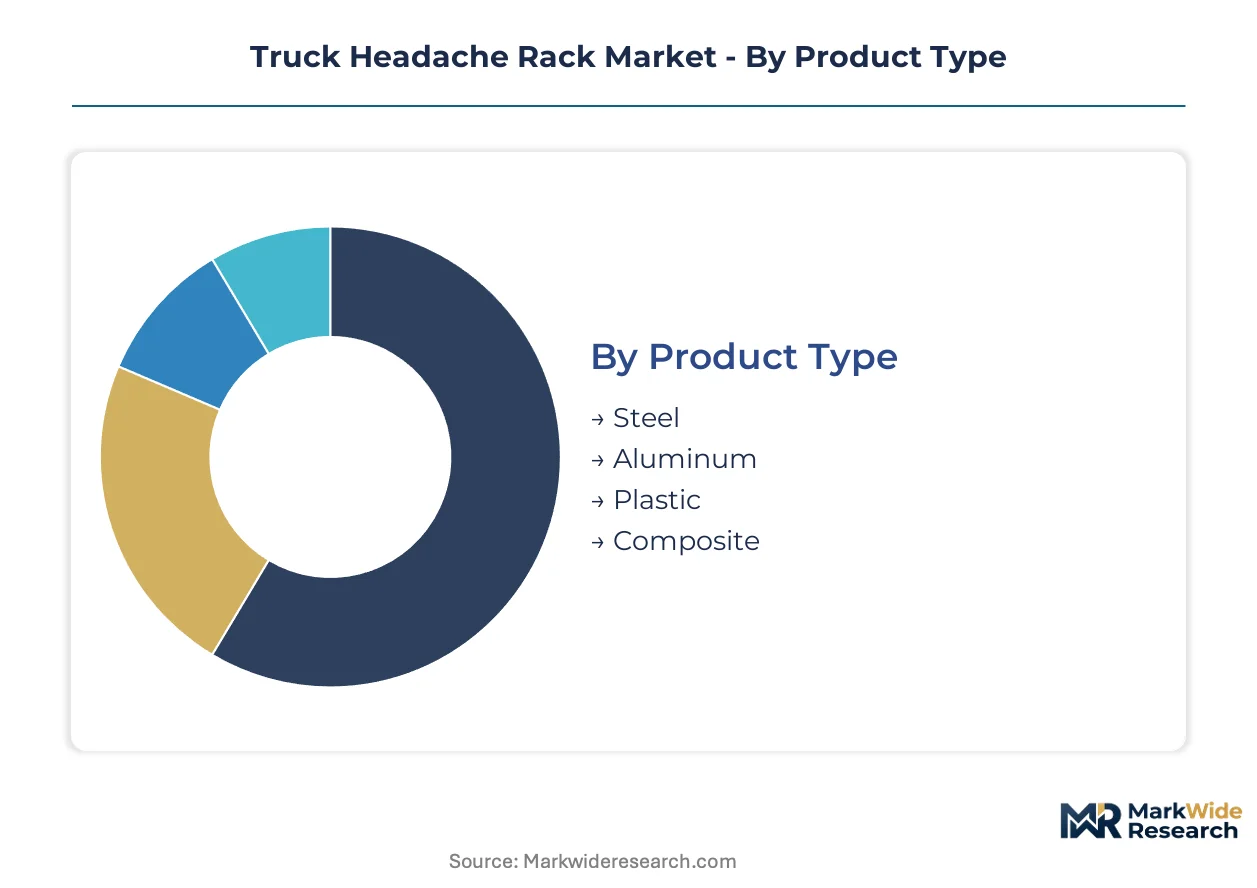
Truck headache rack procurement patterns diverge sharply across material specifications, mounting methodologies, and duty-cycle requirements. Fleet operators, agricultural contractors, and individual owners each impose distinct performance thresholds that reshape vendor product development priorities and channel economics.
Product Type:
Margin pools concentrate in alloy formulations that balance weight reduction against NHTSA impact-resistance mandates, with premium pricing attaching to certified severe-service configurations.
- Steel:Fabricated from high-tensile carbon steel tubing with powder-coated or galvanized finishes, steel racks deliver maximum impact absorption for energy sector and heavy-haul fleets. Demand clusters among Great Plains agricultural operators hauling grain and equipment where collision protection outweighs payload sensitivity. NHTSA's pending FMVSS load-barrier revisions reinforce steel's position in specification-grade procurement.
- Aluminum:Extruded 6061-T6 or 6063-T5 aluminum tubing with robotic pulse-arc welding reduces installed weight by 150-200 pounds versus steel alternatives. California Central Valley battery-electric truck deployments favor these configurations to preserve range, while Southeastern LTL carriers prioritize fuel economy gains.
- Plastic:Molded high-density polyethylene or glass-reinforced nylon components serve light-duty owner-operator applications with minimal cargo-securement requirements.
- Composite:Hybrid aluminum-honeycomb or carbon-fiber-reinforced polymer assemblies target emerging electrified fleet segments requiring maximum weight reduction.
The dominant share belongs to Steel, while Aluminum is closing the gap fastest.
Installation Type:
Channel economics split between aftermarket convenience and OEM structural integration, with welded configurations commanding price premiums for severe-service validation.
- Welded:Permanent cab-to-frame integration through certified aluminum TIG or MIG welding delivers maximum shear strength for utility and energy sector contractors. Iowa-based extrusion operations and Canadian fabrication hubs concentrate supply for this specification tier.
- Bolt-On:Stake-pocket or bed-rail mounting hardware enables rapid field installation without specialized equipment, capturing the broadest aftermarket channel among price-sensitive owner-operators. SKU proliferation accelerates as Detroit manufacturers fragment bed rail designs.
- Clamp-On:Non-drilling mounting systems preserve truck bed warranties for leased fleet vehicles in last-mile logistics applications.
- Integrated:Factory-installed configurations from chassis OEMs consolidate cab protection with lighting and storage packages for national LTL operators.
Welded configurations retain pricing power in OEM channels, though Bolt-On systems are expanding most quickly through direct digital procurement.
End User:
Procurement sophistication varies dramatically, with fleet operators consolidating vendor relationships while agricultural users prioritize severe-service durability over total cost metrics.
- Fleet Operators:National LTL carriers and regional logistics providers demand consolidated cab protection, lighting, and storage packages with documented load-securement protocols for OSHA compliance.
- Individual Owners:Price-sensitive buyers in the aftermarket channel favor bolt-on configurations bypassing traditional distributor markups through manufacturer-direct digital procurement.
- Commercial Users:Utility and energy sector contractors require specification-grade welded racks with integrated tool storage and antenna mounting for telematics hardware.
- Agricultural Users:Grain transport and equipment hauling across Texas, Kansas, and Nebraska sustains demand for severe-service welded configurations with corrosion-resistant finishes.
Fleet Operators command the largest volume commitment, though Agricultural Users are gaining share fastest as commodity prices stabilize.
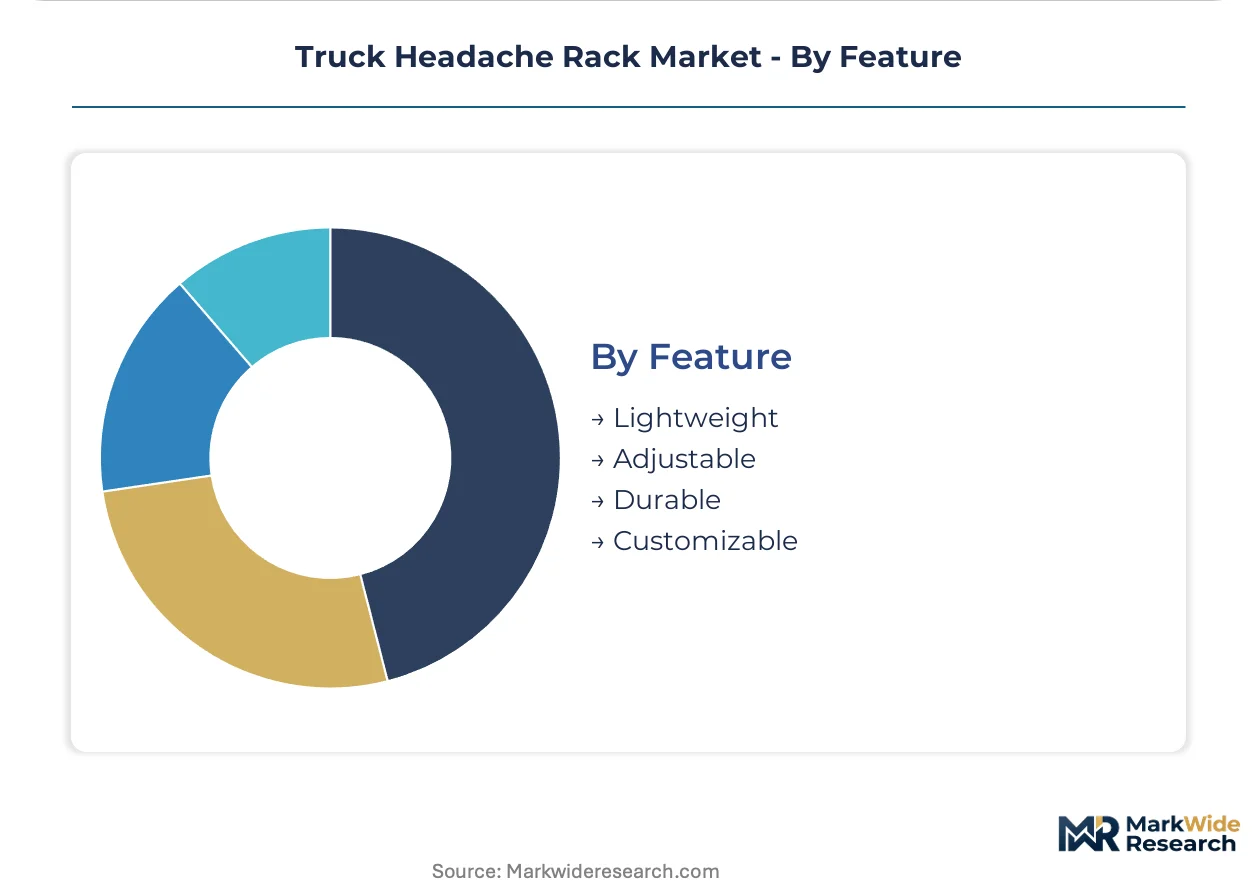
Feature:
Specification bundling is compressing standalone feature premiums, with adjustable and customizable attributes increasingly table stakes rather than differentiators.
- Lightweight:Aluminum-magnesium alloy tubing and honeycomb core designs address payload recovery and electric vehicle range preservation requirements in California and Southeastern fleet conversions.
- Adjustable:Modular height and width configurations accommodate diverse cab geometries and aftermarket upfit variations across multi-brand fleet operations.
- Durable:Powder-coated steel and anodized aluminum finishes with marine-grade hardware target corrosion-intensive agricultural and coastal applications.
- Customizable:Configured assemblies with integrated ladder racks, lighting mounts, and tool storage concentrate purchasing power with vertically integrated manufacturers capable of direct-to-upfit delivery.
Durable specifications anchor fleet procurement standards, while Lightweight configurations are climbing the fastest on electrification tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns for truck headache racks diverge sharply across geographies, with fleet electrification priorities reshaping material preferences in some markets while agricultural durability demands dominate others.
United States
Texas, California, and the Great Plains agricultural corridor generate the densest procurement activity for severe-service welded configurations. NHTSA's pending FMVSS occupant protection updates are compressing design certification timelines for domestic manufacturers. Iowa-based aluminum extrusion operations and Canadian fabrication hubs anchor the supply base for specification-grade fleet contracts.
Canada
Ontario and Quebec manufacturing clusters sustain alloy rack output for North American fleet channels through captive smelter networks. Canadian energy cost volatility and tariff exposure create geographic vulnerability in primary billet sourcing. BACKRACK leverages its Canadian manufacturing base to maintain consistent production capacity for cross-border commercial vehicle upfitters.
Mexico
Northern border states concentrate assembly operations for US-bound commercial vehicle accessories. OEM severe-service contracts from Detroit manufacturers drive demand for welded configurations with integrated tool storage. Mexican fabrication facilities face pressure from certified aluminum TIG welder scarcity as production scales for OEM integration.
Germany
Baden-Württemberg and Bavaria automotive clusters influence commercial vehicle safety equipment standards across European export markets. EU Green Deal emissions regulations indirectly shape rack demand by extending truck replacement cycles. German fleet operators prioritize lightweight aluminum-magnesium configurations for fuel economy compliance in long-haul logistics corridors.
Australia
Queensland and Western Australia mining regions generate demand for corrosion-resistant powder-coated steel racks in coastal and high-salinity environments. Australian Design Rules for commercial vehicle occupant protection govern cab protection equipment specifications. Perth and Brisbane upfit facilities concentrate procurement for utility sector contractors requiring documented load-securement protocols.
Truck Headache Rack Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with vertical control over aluminum extrusion or Canadian fabrication assets distinguishing premium positioning from commodity aftermarket supply. The market structure concentrates specification-grade procurement among three to four fabricators with captive alloy supply or OEM validation credentials, while bolt-on aftermarket channels fragment across dozens of regional metalworkers and import distributors. Two strategic archetypes dominate: vertically integrated extrusion-to-fabrication operators and specialist custom fabricators serving energy and utility contractors. Competitive moves center on backward integration into primary billet sourcing and direct-to-fleet digital procurement channels that bypass traditional distributor markups.
Among North American fabricators, BACKRACK, Dee Zee, and Highway Products exemplify contrasting strategic positions. BACKRACK represents the cross-border integrated archetype with Canadian manufacturing leverage for consistent alloy output. Dee Zee anchors the Midwestern vertical integration model through Iowa-based extrusion control. Highway Products occupies the specialist custom fabrication tier, serving utility and energy sector contractors with severe-service welded configurations. These three companies collectively illustrate how geographic positioning and supply chain architecture determine competitive access to specification-grade procurement channels.
| Leading Market Players |
|---|
| BACKRACK |
| Dee Zee |
| ARIES |
| Buyers Products |
| Go Rhino |
| Highway Products |
| RealTruck |
| Westin |
| Putco |
| Others |
Pricing and Supply Chain Analysis
Forty-five to sixty-day aluminum extrusion lead times in the US Midwest compress procurement flexibility for specification-grade fabricators, concentrating pricing power with Iowa-based operators holding captive billet supply while forcing spot-market buyers into premium surcharges. This inventory-band dynamic tightens margin structures for Canadian fabricators exposed to cross-border tariff volatility and energy cost spikes.
Pricing Analysis
Long-term offtake contracts dominate specification-grade procurement from national LTL carriers and agricultural cooperatives, locking in volume commitments against aluminum price floors while spot-market transactions serve price-sensitive owner-operators through digital channels. Price differentiation rests on FMVSS pre-certification status and OEM validation credentials, with certified severe-service configurations commanding substantial premiums over uncertified aftermarket alternatives. Pricing pressure stems from SKU proliferation driven by fragmented bed-rail designs from Detroit manufacturers, forcing inventory carrying costs upward. Fleet operators demonstrate lowest price sensitivity due to consolidated procurement and OSHA compliance mandates, while individual owner-operators in the Southeast exhibit highest elasticity, prioritizing bolt-on convenience over performance certification.
Supply Chain Analysis
Strategic stockpiling of primary aluminum billet distinguishes vertically integrated fabricators from just-in-time competitors vulnerable to Midwest smelter network disruptions. Supply concentrates in the United States, Canada, and Mexico, with Iowa extrusion operations and Ontario fabrication hubs anchoring North American output. Raw material dependencies center on 6061-T6 and 6063-T5 aluminum alloy, high-tensile carbon steel tubing, and marine-grade hardware fasteners. Single-source vulnerability in Canadian primary smelting creates exposure to electricity tariff fluctuations and cross-border trade policy shifts. Distribution runs through direct-to-fleet channels for specification-grade contracts and aftermarket distributor networks for bolt-on configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NHTSA's pending FMVSS occupant protection overhaul constitutes a regulatory inflection accelerating design certification investment and compressing competitive timelines for cab protection equipment. This disruption favors pre-positioned fabricators with validated severe-service configurations.
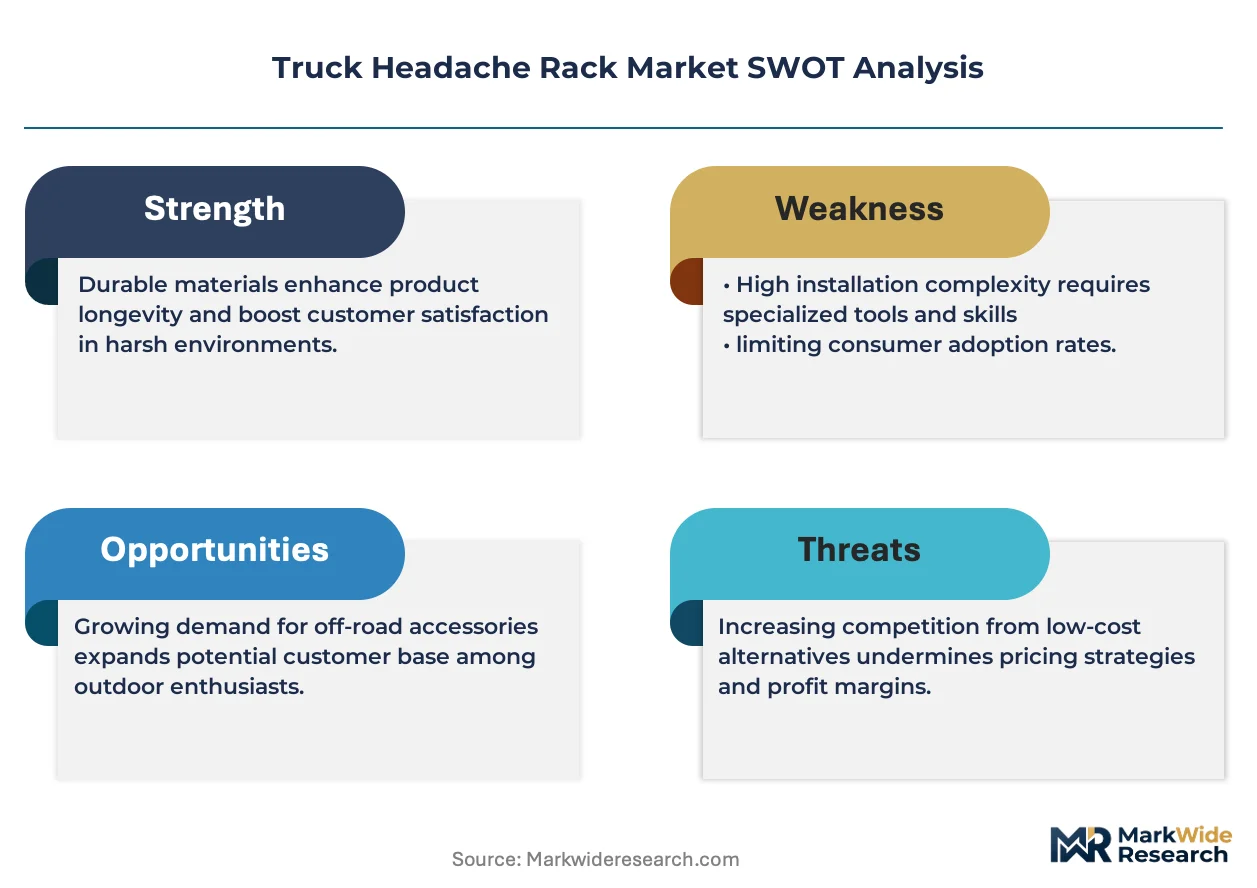
For Market Incumbents: Compound defensive positioning through backward integration into aluminum extrusion capacity and captive certification laboratory investment to compress FMVSS pre-compliance timelines. Threats from robotic pulse-arc welding automation and carbon-fiber composite substitutes demand accelerated R&D allocation. Channel control through direct-to-upfit digital procurement platforms protects margin structures against distributor disintermediation. For New Entrants and Emerging Players: Lead with California battery-electric truck fleet conversions as the most penetrable white-space target, where lightweight honeycomb rack designs address range-preservation requirements underserved by incumbent steel fabricators. Agricultural cooperatives in the Great Plains corridor present secondary entry opportunity through severe-service welded configurations with integrated telematics mounting. Go-to-market execution should emphasize manufacturer-direct digital procurement bypassing traditional aftermarket distributor markups. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because specification-grade procurement concentration and rising certification barriers favor scaled operators with captive alloy supply and OEM validation credentials. Acquisition targets should display vertically integrated extrusion-to-fabrication capabilities or established utility-sector contractor relationships. The signal to watch is FMVSS rule finalization timing, which would trigger accelerated fleet replacement cycles and expand addressable market for compliant inventory.| Strategic Initiative | Industry Significance |
|---|---|
| FMVSS Pre-Certification Investment | Third-party crash simulation validation secures specification-grade procurement channels ahead of rule finalization. |
| Backward Integration into Extrusion | Iowa-based aluminum billet sourcing insulates margin structures from Midwest energy cost volatility. |
| Direct-to-Fleet Digital Channel | Manufacturer-direct procurement captures price-sensitive owner-operators bypassing distributor markups. |
| Lightweight Composite R&D Partnership | Honeycomb core development addresses California battery-electric truck range preservation requirements. |
| Telematics Hardware Integration | Antenna and sensor pod mounting creates specification bundling opportunities with last-mile logistics fleets. |
Research Methodology
The analysis maps steel, aluminum, plastic, and composite product categories, each validated through fleet procurement managers, aftermarket distributor principals, and OEM upfit engineering directors. Primary fieldwork combined structured interviews with secondary validation against NHTSA regulatory filings, EPA emissions databases, and commercial vehicle production records. Bottom-up triangulation across material-specific demand clusters and top-down reconciliation against fleet penetration assumptions anchored volume estimates.
Consistency checks against external benchmarks validated output plausibility across the projection horizon. The analytical framework modeled product type, installation methodology, end-user archetype, and duty-cycle intensity as core segmentation dimensions. CAGRs derived from regression analysis of fleet replacement cycles, regulatory adoption curves, and electrification penetration patterns. Industry-specific inputs included NHTSA rulemaking timelines, OSHA enforcement intensity indices, and agricultural commodity price correlations.
Forecasts assume regulatory continuity in NHTSA FMVSS and OSHA workplace safety regimes; material policy shifts would require re-modeling of certification timelines and fleet procurement acceleration. Aluminum extrusion supply disruptions, welding labor scarcity intensification, or Detroit manufacturer bed-rail standard fragmentation represent specific revision triggers. Revision becomes warranted when FMVSS pre-compliance testing burden crosses thresholds forcing exit of sub-scale fabricators.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy-Duty Trucks
Garbage Truck Bodies Market
Heavy-Duty Trucks
Medium and Heavy Duty Commercial Vehicles (MHCV) Market
Heavy-Duty Trucks
Dump Trucks and Mining Trucks Market
Heavy-Duty Trucks
Heavy-Duty Truck Axle Locking Actuator Components Market
Heavy-Duty Trucks
United States Refrigerated Trucking Market
Heavy-Duty Trucks
Heavy-Duty Truck Load and Axle Weight Sensor Systems Market
Heavy-Duty Trucks
Hard Tonneau Cover Market
Heavy-Duty Trucks
Heavy-Duty Truck Dashboard Switch Panel Systems Market
Heavy-Duty Trucks
Airport Catering Truck Market
Heavy-Duty Trucks
Tipper Truck Market
Heavy-Duty Trucks
Poly Trucks Market
Heavy-Duty Trucks
Mexico Refrigerated Truck Market
Heavy-Duty Trucks
Global Boom Truck Market
Heavy-Duty Trucks
Full Truck Load (FTL) Market
Heavy-Duty Trucks
North America Vacuum Truck Market
Heavy-Duty Trucks
India Vacuum Truck Market