
 Airport Catering Truck Market | 2026-2036
Airport Catering Truck Market Size, Share, and Industry Trends Forecast 2026-2036
Airport Catering Truck Market Analysis
Electric drivetrain certification is reorganizing procurement priorities across airport catering truck fleets. JBT Corporation leverages its established ground support platform to anchor electric product development in North American hubs. Mallaghan Engineering Ltd specializes in custom-height lift mechanisms that differentiate its portfolio for wide-body aircraft compatibility. TLD Group competes through manufacturing scale that sustains cost advantages across European and Middle Eastern contracts.
An airport catering truck is a self-propelled or towed vehicle designed to transport pre-packaged meals, beverages, and cabin supplies from flight kitchens to aircraft galleys, typically featuring insulated compartments, hydraulic lift platforms adjustable to door sill heights between 2.5 and 5.5 meters, and capacity ratings from 500 to 2,000 kilograms. Electric fuel type configurations now command premium positioning as airports phase out diesel equipment under emission reduction commitments. Lift product variants capture the strongest margin pools due to complexity in multi-level adjustment systems and integration with next-generation aircraft door designs.
The FAA mandates specific braking and stability standards for powered ground support equipment operating on commercial aprons, while the EU Green Deal imposes progressive carbon reduction thresholds that reshape fleet procurement timelines at member-state airports. EASA airside safety directives further constrain equipment design, compelling manufacturers to certify collision avoidance and fire suppression systems before market access. Stakeholders must monitor how rapidly evolving battery energy density benchmarks and charging infrastructure commitments at hub airports will reshape total cost of ownership calculations against legacy diesel platforms.
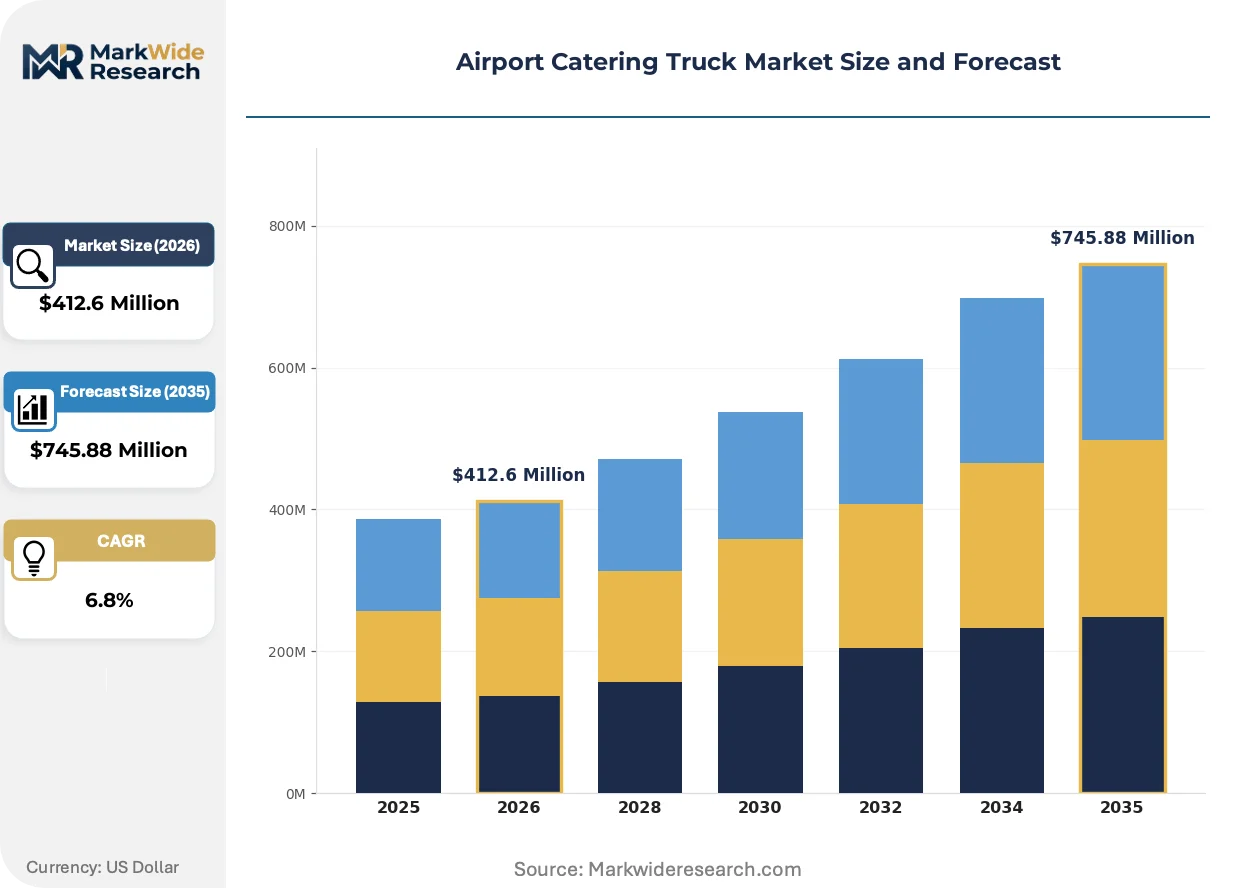
Market Dynamics
Electric drivetrain conversion is compressing procurement cycles at major hub airports as emission mandates harden into enforceable deadlines. Fleet managers now face simultaneous pressure from EU Green Deal carbon thresholds and from airline sustainability commitments that cascade into ground support equipment specifications.
Growth Catalysts
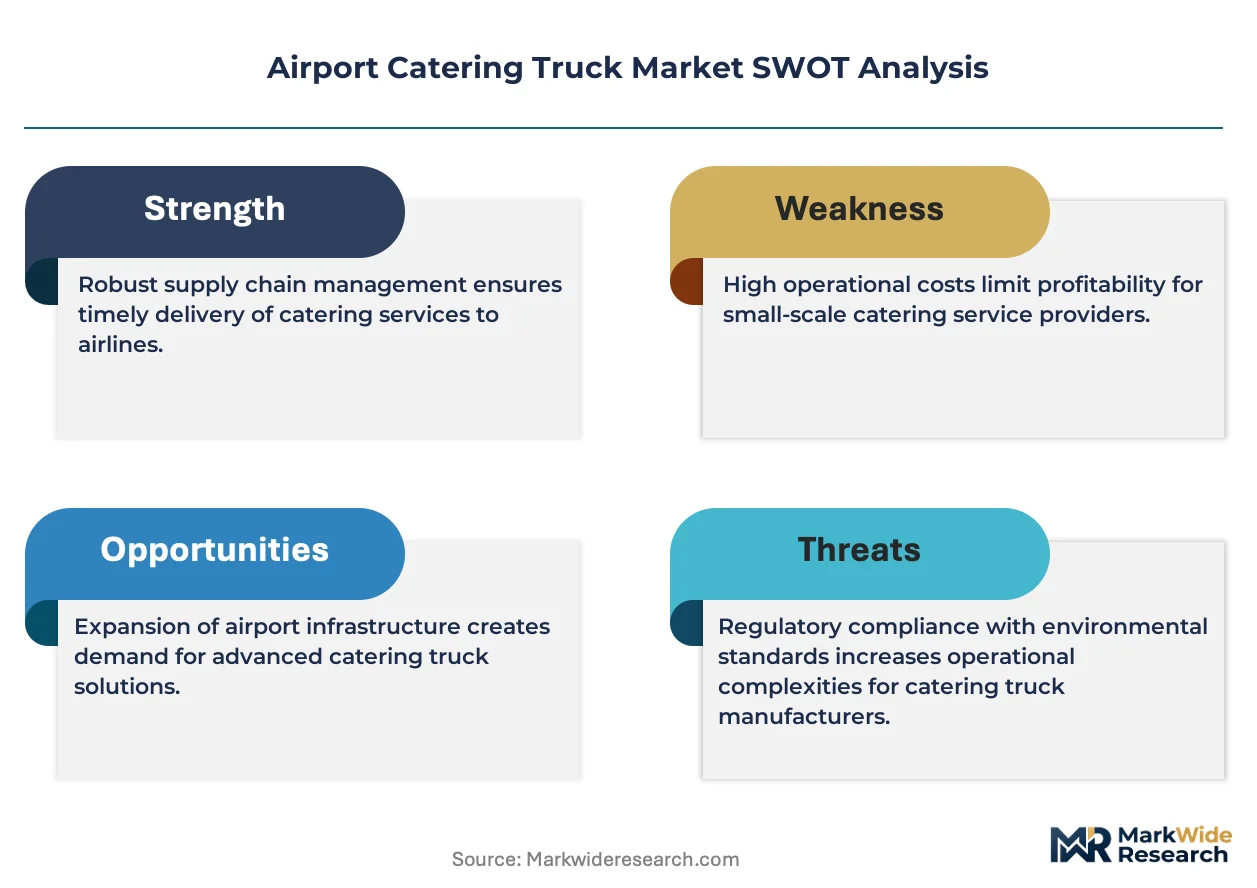
- EU Green Deal mandates:Progressive carbon reduction thresholds at Frankfurt, Munich, and Amsterdam Schiphol are forcing accelerated diesel-to-electric fleet turnover. Airport operators must comply or face operational restrictions.
- Wide-body fleet expansion:Airbus A350 and Boeing 787 deliveries are rising at Qatar Airways, Emirates, and Singapore Airlines. These aircraft require lift platforms reaching 5.5-meter door sills.
- Lithium-ion energy density gains:Battery pack improvements now enable full-shift operation without midday charging. Ground handlers at London Heathrow and Paris CDG are validating 12-hour duty cycles.
Market Restraints
- Charging infrastructure capex:Hub airports must install megawatt-scale charging depots before electric fleets achieve viable deployment. Munich Airport's 2024 apron electrification program required 18-month construction timelines.
- Specialized steel supply concentration:High-strength alloys for hydraulic lift mechanisms source primarily from German and Japanese mills. Geopolitical friction threatens input cost stability.
- EASA airside certification complexity:Collision avoidance and fire suppression system approvals add 8-14 months to product launch schedules. Manufacturers face recurring design iteration costs.
Strategic Opportunities
- India airport privatization wave:Delhi International Airport and Bangalore Kempegowda International are expanding cargo and passenger terminals. Greenfield ground support procurement favors electric-first specifications.
- Autonomous navigation convergence:Lidar-based apron positioning systems combined with electric drivetrains enable unmanned catering operations during night shifts. Dubai International is piloting this configuration.
- US Inflation Reduction Act credits:Section 45W clean commercial vehicle incentives reduce electric truck acquisition costs for ground handlers at Atlanta Hartsfield-Jackson and Dallas Fort Worth.
Industry Challenges
- High-voltage technician scarcity:Electric drivetrain maintenance requires certified specialists that airport engineering departments rarely retain. Training pipelines at vocational institutions remain underdeveloped.
- Legacy diesel fleet stranding risk:Residual value collapse for combustion-powered units complicates financing for operators with mixed fleets. Lenders are tightening collateral requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airport Catering Truck Market |
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tugger, Mobile Cart, Lift, Bus Fuel Type: Electric, Diesel, Gasoline, Hybrid End User: Airlines, Ground Handlers, Airports, Cargo Operators Deployment Mode: On-ground, Off-site, Shared, Exclusive |
| Companies Covered | Mallaghan Engineering Ltd, JBT Corporation, Global Ground Support Equipment LLC, Alvest Group, DOLL Fahrzeugbau GmbH, Eagle Industries DWC-LLC, Jiangsu Tianyi Airport Special Equipment Co., Ltd, WEIHAI GUANGTAI Airport Equipment Co., Ltd, TLD Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airport Catering Truck Market Emerging Trajectories
Equipment intelligence and energy architecture are converging to redefine how catering trucks interface with aircraft and airport systems. Manufacturers are embedding connectivity and automation to capture premium positioning.
Solid-state battery chemistries are supplanting conventional lithium-ion packs in next-generation prototypes. JBT Corporation and Mallaghan Engineering are testing ceramic electrolyte configurations that promise faster charging and thermal stability. This technology is enabling manufacturers to compress platform weight while extending range, directly challenging diesel residual economics.
The EU Green Deal's progressive carbon reduction thresholds are reshaping procurement timelines at member-state airports. Airlines now embed ground support emission clauses in airport use agreements, transferring compliance pressure to equipment lessors. Wide-body compatible lift variants face the steepest certification urgency as long-haul carriers prioritize sustainability credentials.
Airline fleet renewal programs are consolidating purchasing authority into centralized procurement hubs. Lufthansa Group and Air France-KLM now specify ground support equipment through single-source framework agreements, displacing fragmented airport-level tendering. This concentration is most visible at Frankfurt and Paris CDG, where standardized electric specifications dominate recent awards.
Airport Catering Truck Market Segmentation
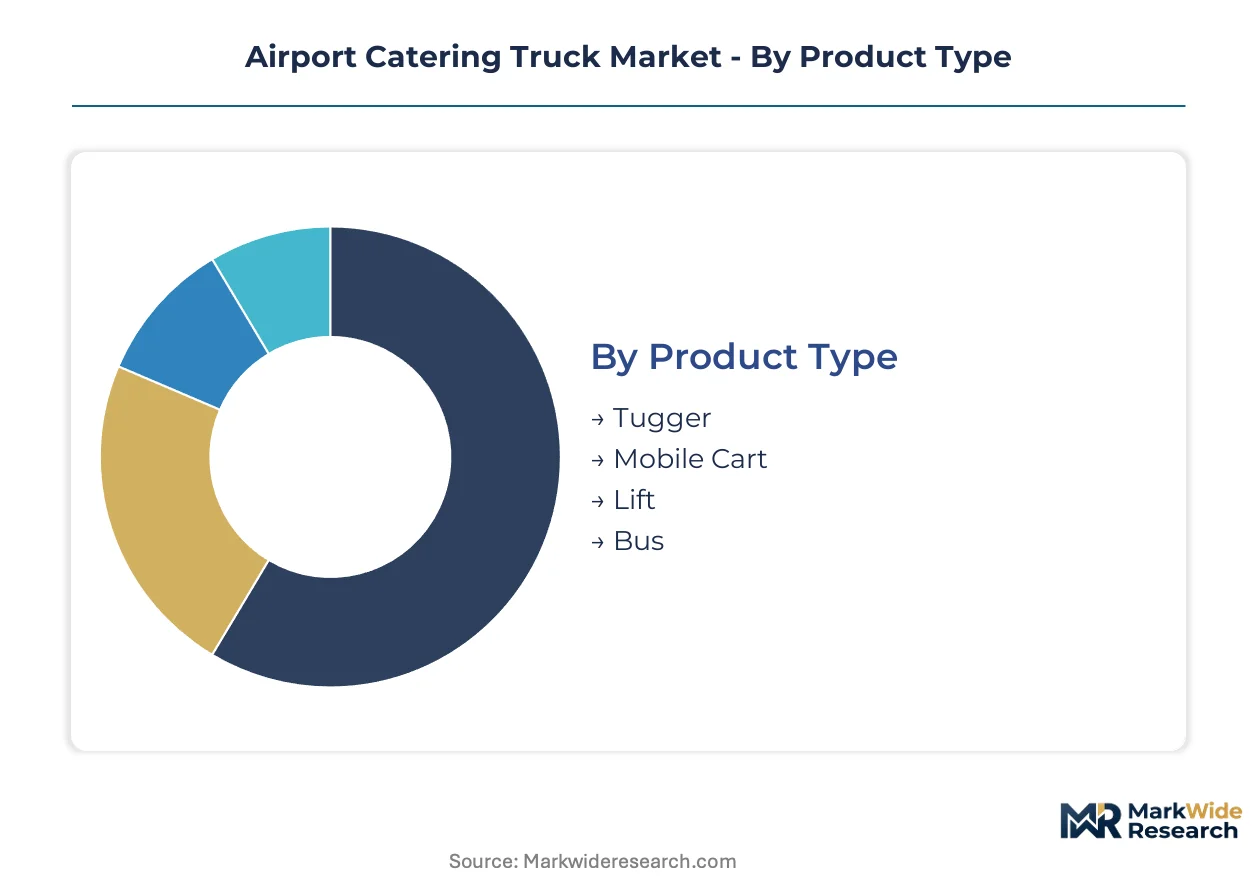
Airport catering truck procurement splits across equipment configuration, energy architecture, operational ownership, and service deployment models. Each dimension carries distinct margin profiles and regulatory exposure that reshape vendor prioritization and fleet investment cycles.
Product Type:
Lift variants command the steepest premium pricing due to hydraulic complexity and aircraft door integration requirements.
- Lift:Hydraulic platforms adjust between 2.5 and 5.5 meters to match wide-body door sills. Demand concentrates at Frankfurt and Munich airports where Lufthansa Group specifications mandate electric lift compatibility for A350 and 787 fleets.
- Tugger:Towable units haul multiple meal carts across apron distances. Ground handlers at London Heathrow and Paris CDG favor tuggers for narrow-body turnarounds where speed outweighs vertical reach requirements.
- Mobile Cart:Self-propelled compartmentalized vehicles serve regional aircraft with lower door heights.
- Bus:High-capacity shuttle configurations transport cabin crew and supplies simultaneously.
Lift holds installed capacity. Tugger is rotating up the share rankings.
Fuel Type:
Electric configurations now absorb disproportionate R&D investment as emission deadlines harden into procurement mandates.
- Electric:Lithium-ion packs with ceramic electrolyte prototypes are supplanting conventional chemistries. EU Green Deal thresholds at Amsterdam Schiphol and Frankfurt force diesel displacement, compressing fleet turnover timelines to 18-month electrification windows.
- Diesel:Legacy compression-ignition units face residual value collapse as lenders tighten collateral terms for mixed fleets. Ground handlers at Dubai International and Singapore Changi still deploy diesel for long-haul cargo operations beyond current battery range.
- Gasoline:Spark-ignition variants persist at smaller airports with limited charging infrastructure.
- Hybrid:Parallel drivetrains bridge range anxiety during transition periods.
Electric is climbing the fastest. Diesel retains transitional volume.
End User:
Airline procurement centralization is displacing fragmented airport-level tendering across major European hubs.
- Airlines:Lufthansa Group and Air France-KLM now specify equipment through single-source framework agreements. Sustainability clauses in airport use agreements cascade compliance pressure directly to ground support lessors.
- Ground Handlers:Swissport and dnata operate mixed fleets under simultaneous pressure from airline sustainability mandates and EU Green Deal carbon thresholds. Technician scarcity for high-voltage maintenance strains operational uptime.
- Airports:Frankfurt and Munich airports are retrofitting owned fleets with electric alternatives under national zero-emission mandates.
- Cargo Operators:Dedicated freight handlers at Luxembourg and Leipzig prioritize payload capacity over galley loading speed.
Airlines control specification authority. Ground Handlers absorb execution risk.
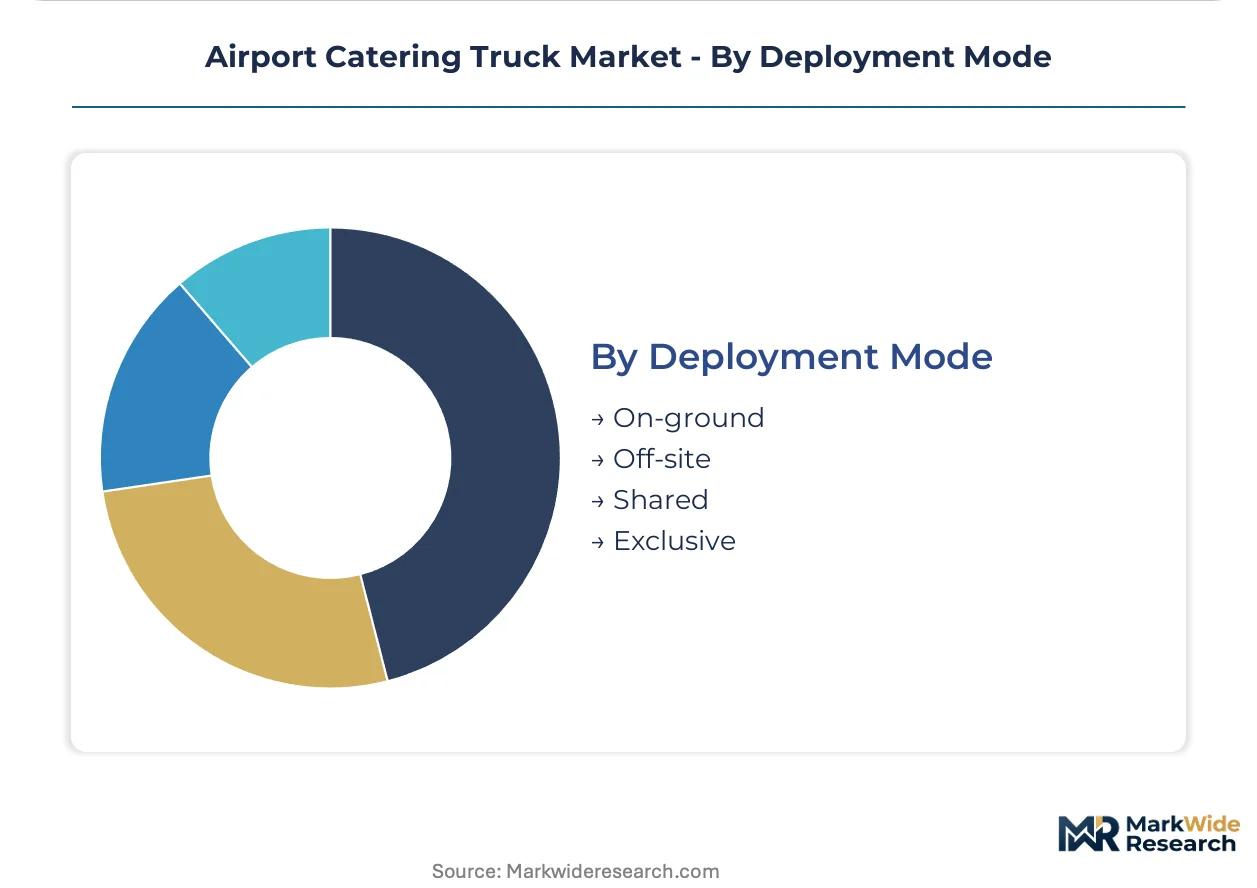
Deployment Mode:
Exclusive contracts concentrate capital commitment while shared models spread utilization risk across multiple carriers.
- Exclusive:Single-airline dedicated fleets at Emirates and Qatar Airways enable customized height configurations for A380 and 777 door sills. Capital intensity locks in long-term supplier relationships.
- Shared:Multi-tenant pooling at London Heathrow Terminal 5 and Paris CDG Terminal 2E maximizes asset turns across British Airways and Air France schedules. Utilization rates exceed 85% during peak banks.
- On-ground:Apron-based staging positions equipment for immediate aircraft access.
- Off-site:Remote flight kitchen coordination requires extended-range electric configurations.
Exclusive locks in margin. Shared is expanding fastest in capacity-constrained hubs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows from German and Chinese manufacturers dominate international procurement, while import dependence concentrates among Middle Eastern and Southeast Asian hub airports retrofitting ground support fleets. Trade balances tilt toward surplus in precision hydraulic component exports from Japan and South Korea. Regional regulatory divergence is fragmenting certification requirements across major aviation markets.
Germany
Lufthansa Group's centralized procurement mandates electric lift compatibility for A350 and 787 fleets at Frankfurt and Munich hubs. The EU Green Deal imposes progressive carbon reduction thresholds that compress diesel-to-electric turnover timelines to 18-month windows. Bavaria's manufacturing corridor around Munich anchors production of high-strength alloy hydraulic systems for wide-body door integration.
United States
Atlanta Hartsfield-Jackson and Dallas Fort Worth ground handlers leverage Section 45W clean commercial vehicle incentives to offset electric truck acquisition costs. FAA braking and stability standards for powered ground support equipment constrain design parameters for apron operation. The Southeast aviation cluster spanning Georgia and Texas dominates domestic fleet renewal procurement volumes.
China
Beijing Capital and Shanghai Pudong airports are retrofitting owned fleets under national dual carbon goals and municipal zero-emission mandates for ground support equipment. MIIT certification requirements for new energy commercial vehicles extend to airport-specific applications. The Yangtze River Delta manufacturing base supplies lithium-ion battery packs and electric drivetrain assemblies for regional export markets.
United Arab Emirates
Dubai International pilots autonomous navigation convergence combining lidar-based apron positioning with electric drivetrains for unmanned night-shift catering operations. MOHAP and local aviation regulators coordinate airside safety directives with equipment certification timelines. The Dubai South aviation district concentrates ground handler fleet investment for Emirates and flydubai network expansion.
India
Delhi International Airport and Bangalore Kempegowda International greenfield terminal expansions specify electric-first ground support procurement under airport privatization frameworks. BIS technical standards for electric commercial vehicles are adapting to apron-specific duty cycles and charging infrastructure requirements. The Delhi-Mumbai Industrial Corridor logistics nodes are emerging as assembly locations for imported drivetrain components.
Airport Catering Truck Market Vendor Landscape
Concentration sits with diversified ground support equipment manufacturers that leverage established apron equipment platforms to anchor electric product development. The vendor base organizes around three strategic tiers: full-line suppliers with integrated manufacturing scale, regional specialists in custom lift mechanisms, and emerging Asian fabricators competing on cost-adjusted specifications. Dominant competitive moves include strategic partnerships with battery cell suppliers for energy density advantages and geographic expansion through hub airport framework agreements.
Among European-based diversified manufacturers, JBT Corporation and TLD Group occupy positions exemplifying full-line supply archetypes with established certification pathways across FAA and EASA jurisdictions. Mallaghan Engineering Ltd represents the specialist tier with concentrated expertise in adjustable-height lift platforms. Chinese fabricators including Jiangsu Tianyi Airport Special Equipment Co., Ltd and WEIHAI GUANGTAI Airport Equipment Co., Ltd anchor cost-competitive positioning for emerging market procurement.
| Leading Market Players |
|---|
| Mallaghan Engineering Ltd |
| JBT Corporation |
| Global Ground Support Equipment LLC |
| Alvest Group |
| DOLL Fahrzeugbau GmbH |
| Eagle Industries DWC-LLC |
| Jiangsu Tianyi Airport Special Equipment Co., Ltd |
| WEIHAI GUANGTAI Airport Equipment Co., Ltd |
| TLD Group |
| Others |
Supply Flow & Price Mechanics
Solid-state battery chemistries replacing conventional lithium-ion packs are redrawing procurement geography and compressing pricing premiums for electric lift variants. Ceramic electrolyte configurations from German and Japanese suppliers now command sourcing priority as manufacturers validate thermal stability benchmarks, forcing equipment vendors to absorb upstream alloy cost volatility or pass through to airline framework agreements.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure that locks in volume commitments across 18-month fleet turnover windows. Price differentiation separates EASA-certified collision avoidance systems from baseline apron configurations, with after-sales service bundling adding margin protection. Cost compression in diesel residual markets is intensifying because lenders have tightened collateral requirements for mixed fleets. Ground handlers at hub airports show highest price sensitivity due to simultaneous EU Green Deal compliance pressure, while airline procurement hubs leverage single-source framework agreements to extract standardization discounts.
Supply Chain Analysis
Germany and Japan anchor high-strength alloy production for hydraulic lift mechanisms, with Chinese fabricators scaling electric drivetrain assembly for cost-adjusted export positioning. Raw material flows draw from specialized steel mills in Bavaria's manufacturing corridor and lithium-ion cell production across the Yangtze River Delta. Single-source vulnerability concentrates in German hydraulic component suppliers exposed to geopolitical friction. Distribution runs through hub airport framework agreements that consolidate purchasing authority into airline procurement hubs at Frankfurt and Paris CDG.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The airport catering truck market tracks a cyclical recovery pattern as airline fleet renewal programs accelerate ground support equipment replacement waves. Wide-body deliveries at Gulf carriers and Asian flag airlines are compressing procurement timelines for lift-compatible electric units.
For Market Incumbents: Compound certification advantages by accelerating EASA collision avoidance and fire suppression approvals before emission mandates harden at Amsterdam Schiphol and Frankfurt. Backward integration into ceramic electrolyte sourcing from Japanese cell suppliers secures energy density gains that challenge diesel residual economics. Capacity addition in India's Delhi-Mumbai Industrial Corridor captures greenfield terminal procurement under airport privatization frameworks.
For New Entrants and Emerging Players: Anchor in autonomous navigation convergence by partnering with lidar-based apron positioning developers for unmanned night-shift configurations at Dubai International. The most penetrable white space sits with shared-deployment pooling models at capacity-constrained European hubs where utilization rates exceed 85% during peak banks. A servitization go-to-market angle—leasing electric lift units with bundled high-voltage technician training—addresses ground handler maintenance scarcity.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed ground support equipment lessors holding fragmented airport-level contracts that airline procurement centralization is displacing. Long-term viability over a 5-10 year window hinges on electric fleet penetration rates at EU hub airports and the pace of charging infrastructure capex commitments. The signal to watch is Munich Airport's megawatt-scale depot completion timelines as a proxy for viable electric deployment velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Ceramic electrolyte partnerships with Japanese cell suppliers secure thermal stability advantages for JBT Corporation and Mallaghan Engineering prototypes. |
| Geographic Manufacturing Footprint | Assembly expansion in India's Delhi-Mumbai Industrial Corridor captures greenfield procurement at Bangalore Kempegowda International under privatization frameworks. |
| Regulatory Certification Pathway | EASA collision avoidance and fire suppression approvals compress product launch schedules for wide-body lift variants at Frankfurt and Munich. |
| Charging Infrastructure Partnership | Megawatt-scale depot collaboration with hub airports enables 12-hour duty cycle validation at London Heathrow and Paris CDG. |
| Autonomous Technology Licensing | Lidar-based apron positioning systems from Dubai International pilots transfer to unmanned night-shift catering operations across Middle Eastern hubs. |
Methodological Framework
A spread of perspectives from fleet procurement directors at Lufthansa Group and Air France-KLM, ground handler operations heads at Swissport and dnata, airport engineering departments at Frankfurt and Munich, and electric drivetrain specialists at JBT Corporation converged on the working assumptions. Secondary validation drew from EASA airside safety directives, FAA ground support equipment standards, EU Green Deal carbon threshold documentation, and customs trade flows for high-strength alloy imports. Bottom-up unit economics from individual hub airport fleet turnover timelines triangulated against top-down airline framework agreement values.
Segmentation dimensions modeled span product type configuration, fuel type architecture, end-user procurement authority, and deployment mode exclusivity across the projection horizon. The analytical framework incorporated lithium-ion energy density improvement curves, EASA certification timeline distributions, and airline sustainability clause penetration in airport use agreements. CAGRs derived from fleet replacement cycle compression at EU hubs and greenfield terminal specifications in India.
Decision-makers should treat outputs as directional under assumptions of EU Green Deal enforcement continuity and battery pack weight reduction trajectories; material deviation in charging infrastructure deployment velocity or geopolitical disruption to German steel supply would warrant model refresh. Recalibration cycles align with material shifts in airline fleet renewal program announcements and national zero-emission mandate adoption at major hub airports.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy-Duty Trucks
Turret Truck Market
Heavy-Duty Trucks
Garbage Truck Bodies Market
Heavy-Duty Trucks
Dump Trucks and Mining Trucks Market
Heavy-Duty Trucks
Heavy-Duty Vehicle Engine Brake Market
Heavy-Duty Trucks
Bucket Trucks Market
Heavy-Duty Trucks
Heavy Duty Truck Wash Market
Heavy-Duty Trucks
US Vacuum Truck Market
Heavy-Duty Trucks
Truck Bedliner Market
Heavy-Duty Trucks
Europe Fire Truck Market
Heavy-Duty Trucks
Middle East Refrigerated Truck Market
Heavy-Duty Trucks
Dump Trucks Market
Heavy-Duty Trucks
Hard Tonneau Cover Market
Heavy-Duty Trucks
Heavy-Truck Composite Component Market
Heavy-Duty Trucks
Full Truckload Transportation Market
Heavy-Duty Trucks
Heavy-Duty Truck Fleet Control Unit Architectures Market
Heavy-Duty Trucks
China Full Truckload Road Freight Transport Market