
 Heavy Haulage Trucks Market | 2026-2036
Heavy Haulage Trucks Market Size, Share, and Industry Trends Forecast 2026-2036
Heavy Haulage Trucks Market Analytics
Mining logistics is restructuring demand patterns across heavy haulage categories as surface extraction projects deepen in Australia, Chile, and Kazakhstan. Volvo Group leverages its autonomous haulage systems to sustain technology leadership in high-altitude mining corridors. Daimler Truck anchors European compliance roadmaps through its integrated powertrain engineering centers. PACCAR Inc competes in North American long-haul configurations with sleeper-cab specialization for equipment transport.
Heavy haulage trucks are purpose-built commercial vehicles engineered for gross combination weights exceeding 40 tonnes, utilizing reinforced chassis architectures, multi-axle configurations, and high-displacement diesel or dual-fuel powerplants rated above 400 HP for sustained gradient performance. Their primary industrial purpose centers on transporting oversized machinery, bulk raw materials, and modular construction components across low-density road networks. Articulated trucks dominate margin pools in open-pit mining applications where frame articulation protects drivetrain integrity on unimproved haul roads. Heavy Duty Trucks in the 800+ HP power rating band leads fleet renewal cycles as operators seek single-trip payload maximization. Flatbed trucks occupies mature demand in equipment transportation for wind turbine component logistics.
EPA greenhouse gas standards for heavy-duty vehicles and NHTSA fuel efficiency mandates jointly reshape engine displacement strategies and aerodynamic package requirements in the United States. Euro VII frameworks from the European Commission impose stricter NOx and particulate thresholds that accelerate after-treatment system complexity. China's MIIT enforces GB standards on commercial vehicle fuel consumption that constrain imported powertrain architectures. Fleet operators and OEM engineering teams must monitor regulatory divergence between emission jurisdictions to avoid platform fragmentation.
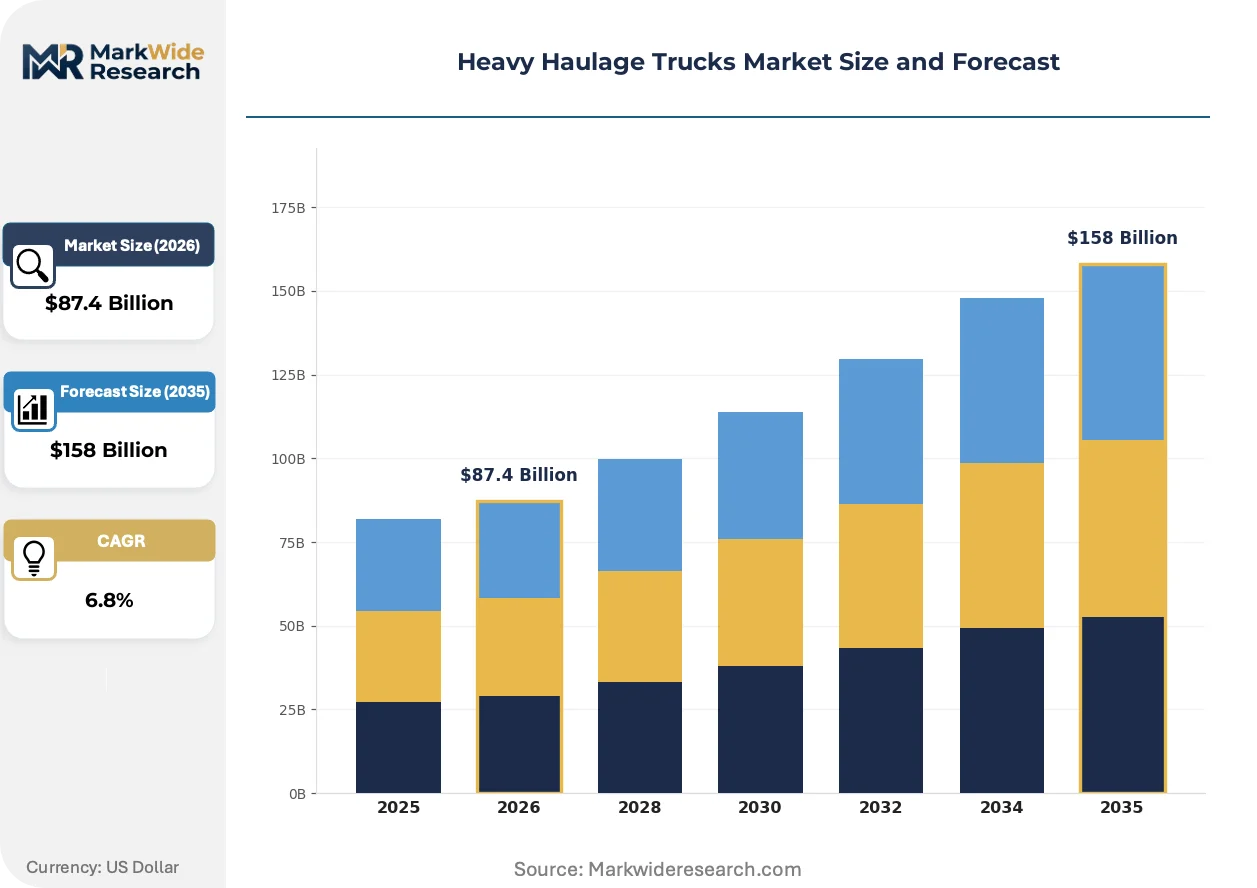
Market Dynamics
Euro VII emission standards from the European Commission are compressing engine development cycles while mining operators in Australia and Chile accelerate fleet renewal for deeper ore extraction operations.
Growth Catalysts
- Autonomous haulage deployment:Mining corridors in Western Australia and Kazakhstan are integrating self-driving truck systems to sustain 24-hour extraction schedules without operator fatigue constraints.
- Euro VII compliance mandates:The European Commission's stricter NOx thresholds are forcing OEMs to redesign after-treatment architectures, creating replacement demand for pre-compliant fleets.
- Infrastructure corridor development:China's western provinces require sustained heavy-lifting capacity for trans-provincial freight networks connecting mineral basins to coastal processing zones.
Market Restraints
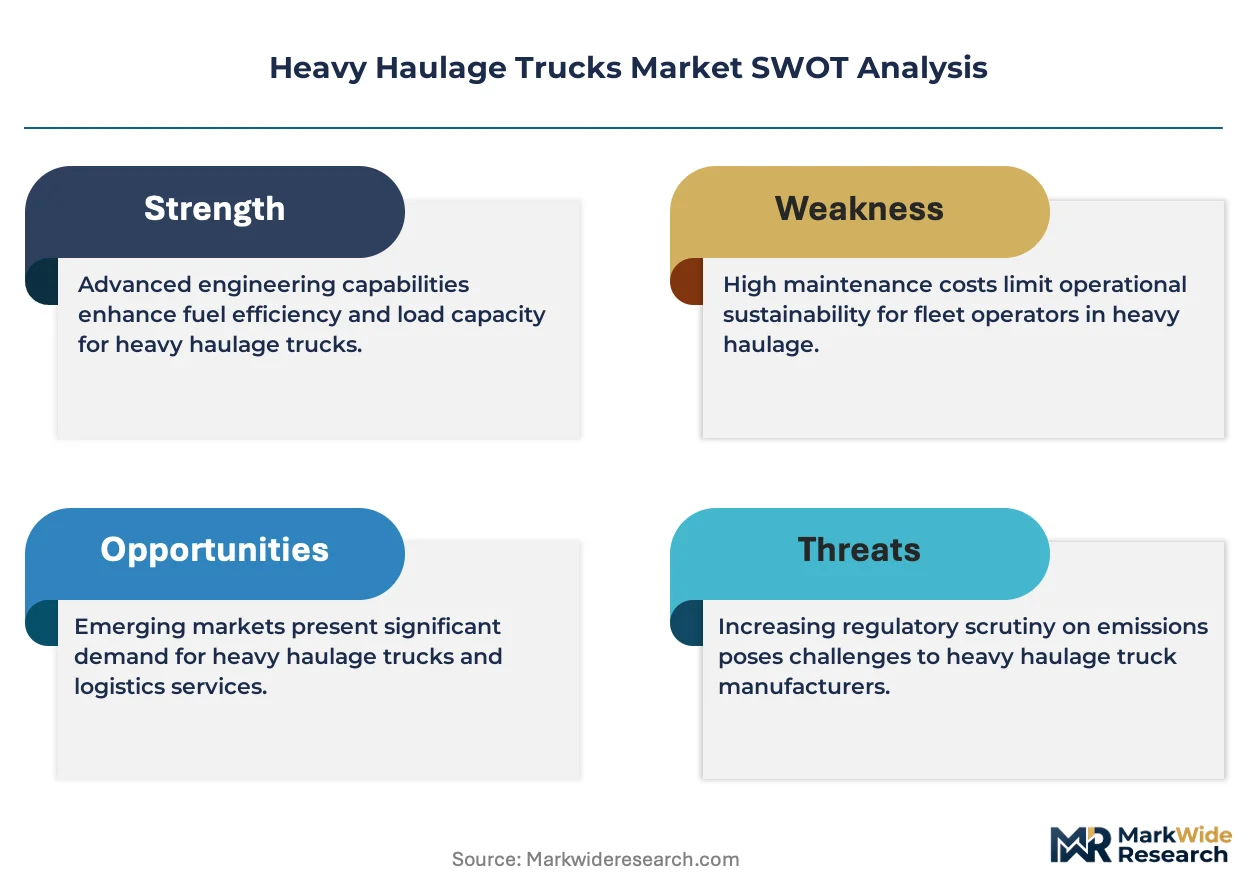
- High-strength steel input volatility:Reinforced chassis architectures depend on specialized alloy supply concentrated in select Asian and European foundries.
- After-treatment system complexity:Euro VII and EPA greenhouse gas standards jointly escalate engineering costs for dual-certification platforms serving multiple jurisdictions.
- Battery-electric payload limitations:Current energy density constraints restrict electric heavy haulage to sub-100-tonne applications, excluding deep-pit mining configurations.
Strategic Opportunities
- Dual-fuel retrofit markets:LNG-diesel hybrid powerplants offer compliance pathways for existing fleet assets in Chilean and Australian mining operations.
- Modular wind turbine logistics:Flatbed configurations for 80-meter blade transport represent expansion potential in North American renewable energy corridors.
- MIIT fuel consumption incentives:China's GB standards on commercial vehicle efficiency create preferential market access for powertrain architectures meeting sub-40L/100km thresholds.
Industry Challenges
- Autonomous systems integration:Mining operators face extended commissioning timelines for sensor fusion and fleet management software on heterogeneous truck generations.
- Multi-jurisdiction certification synchronization:Divergent EPA, Euro VII, and GB standard timelines fragment platform engineering resources across compliance roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heavy Haulage Trucks Market |
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $158 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Articulated Trucks, Flatbed Trucks, Lowboy Trucks, Heavy Duty Trucks End User: Construction, Mining, Oil & Gas, Logistics Power Rating: 200-400 HP, 401-600 HP, 601-800 HP, 800+ HP Application: Infrastructure Development, Material Transport, Equipment Transportation, Heavy Lifting |
| Companies Covered | Volvo Group, Daimler Truck, PACCAR Inc, Traton Group, Scania AB, Navistar International Corporation, Dongfeng Motor Group, MAN Truck & Bus, IVECO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heavy Haulage Trucks Market Evolving Landscape
Powertrain electrification, autonomous operation systems, and predictive maintenance platforms are converging to redefine fleet economics and operator labor models across heavy haulage categories.
Dual-fuel engine architectures are unifying diesel reliability with LNG cost advantages for high-altitude mining applications. Chilean copper operators are piloting these systems at 4,000-meter elevations where thin-air combustion efficiency degrades conventional powerplants. The technology is unifying fuel flexibility with emission compliance across geographically dispersed extraction sites.
EPA greenhouse gas standards for heavy-duty vehicles and NHTSA fuel efficiency mandates are jointly mandating aerodynamic package redesigns and low-rolling-resistance tire specifications. Long-haul operators in the United States must now spec integrated roof fairings and side skirt packages to meet combined tractor-trailer drag coefficient targets. Sleeper-cab configurations for equipment transport face the steepest engineering adaptation costs.
Condition-based maintenance contracts are displacing fixed-interval service schedules as fleet operators prioritize uptime guarantees over component ownership. Mining logistics providers in Western Australia are unbundling drivetrain servicing from OEM purchase agreements, sourcing aftermarket support from specialized rebuild centers. This shift concentrates most visibly in open-pit operations where unplanned downtime carries six-figure hourly cost exposure.
Heavy Haulage Trucks Market Segmentation
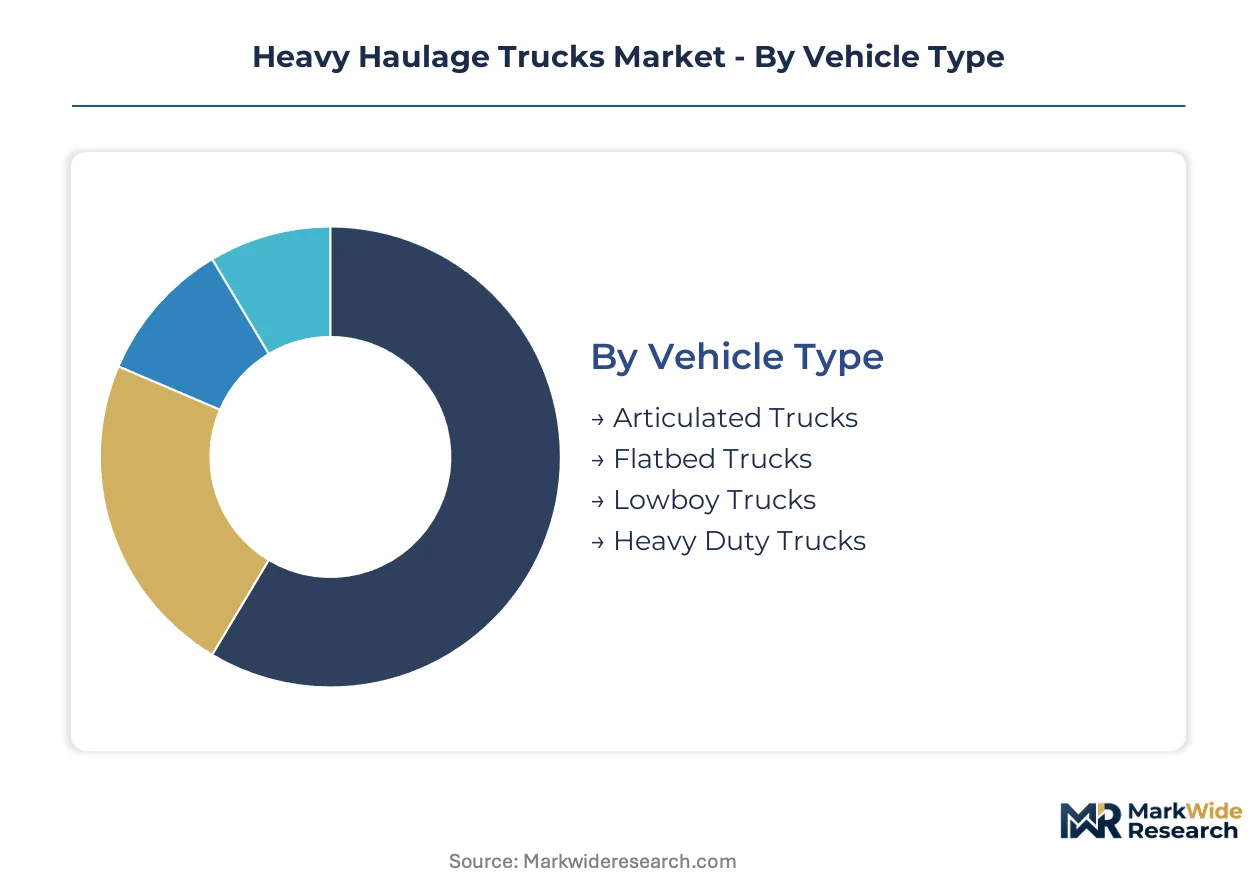
Heavy haulage truck procurement decisions pivot on payload requirements, duty cycle intensity, and regulatory compliance costs across mining, construction, and energy logistics. Segment boundaries blur when operators spec multi-purpose platforms for seasonal work patterns.
Vehicle Type:
Fleet managers select chassis architectures based on terrain severity and load distribution needs across unimproved haul roads.
- Articulated Trucks:Frame articulation joints protect drivetrain components from torsional stress on uneven surfaces. Mining corridors in Western Australia and Kazakhstan concentrate replacement demand as open-pit operations deepen extraction levels.
- Heavy Duty Trucks:Reinforced ladder-frame constructions support gross combination weights exceeding 120 tonnes with multi-axle configurations. China's western provinces drive fleet expansion for trans-provincial mineral transport connecting inland basins to coastal processing zones.
- Flatbed Trucks:Modular deck configurations accommodate wind turbine blade transport up to 80-meter lengths.
- Lowboy Trucks:Drop-deck designs minimize center of gravity for oversized machinery relocation.
Volume sits with Heavy Duty Trucks; growth tilts toward Articulated Trucks.
End User:
Capital expenditure cycles diverge sharply between commodity-driven extractive industries and infrastructure project timelines.
- Mining:Surface extraction operators in Australia and Chile run 24-hour continuous schedules requiring autonomous-ready platforms. Copper and iron ore price volatility compresses replacement windows during commodity upswings.
- Construction:Modular building component logistics and tunnel boring machine transport create episodic demand spikes tied to megaproject approvals. Urban densification projects in China's interior provinces sustain medium-duty configurations.
- Oil & Gas:Remote wellhead equipment transport demands all-terrain mobility for pipeline corridor access.
- Logistics:Specialized carriers serving renewable energy and industrial relocation markets operate on contract-based fleet sizing.
Procurement intensity clusters in Mining; contract flexibility expands fastest in Logistics.
Power Rating:
Engine displacement selection balances gradient performance against fuel consumption compliance under EPA and Euro VII frameworks.
- 800+ HP:High-displacement powerplants rated above 800 HP sustain loaded climbs at 4,000-meter elevations where thin-air combustion degrades conventional engines. Chilean copper operators at altitude drive specification demand for dual-fuel architectures.
- 601-800 HP:Mid-heavy configurations dominate European long-haul equipment transport where Euro VII NOx thresholds force after-treatment complexity. Sleeper-cab specifications in this band face steepest engineering adaptation costs for aerodynamic compliance.
- 401-600 HP:Regional distribution and construction logistics favor this band for fuel efficiency optimization.
- 200-400 HP:Light-heavy applications in urban infrastructure and secondary road networks concentrate here.
Fleet composition centers on 601-800 HP; specification momentum builds fastest in 800+ HP.
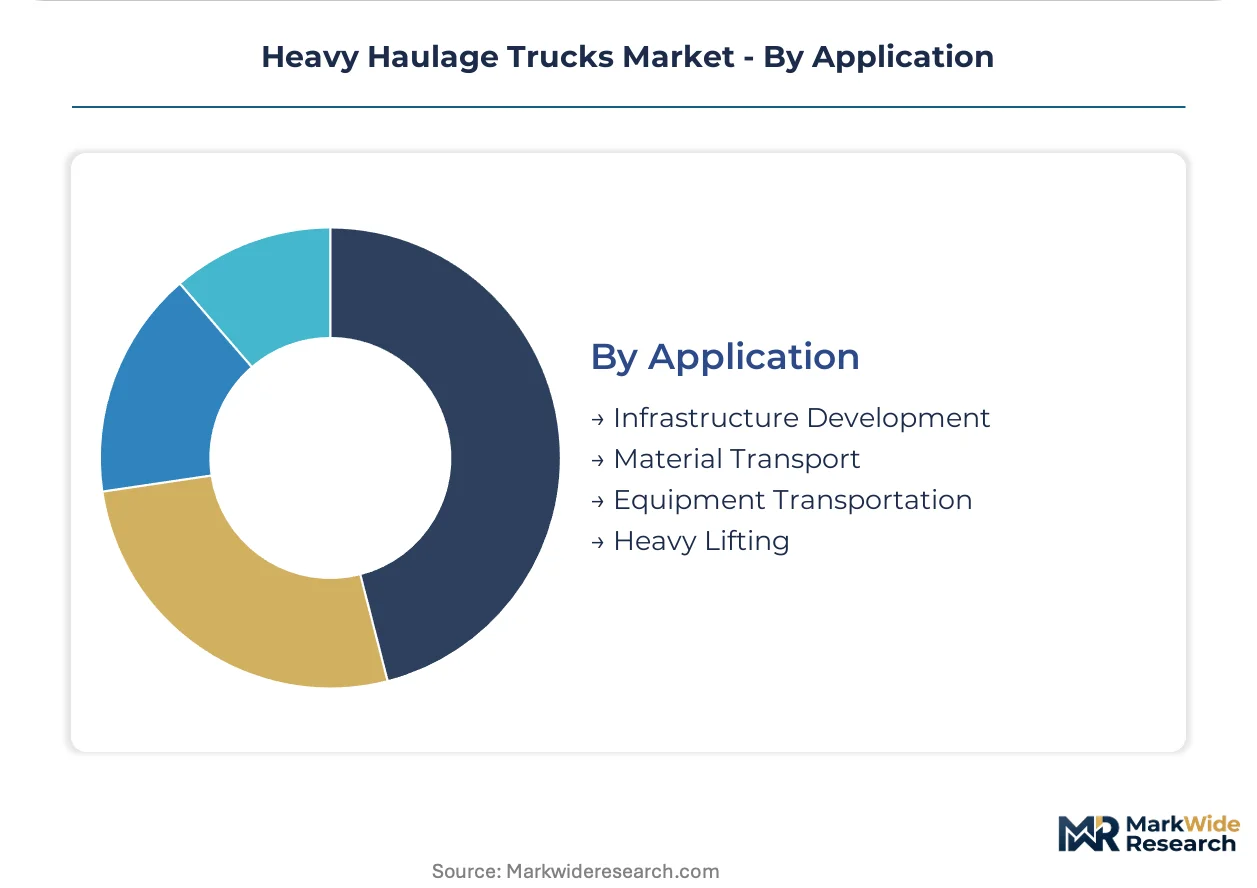
Application:
Route characteristics and load securing requirements determine body configuration and axle spacing decisions.
- Material Transport:Bulk ore and aggregate movement demands reinforced tipping bodies with abrasion-resistant steel linings. Australian iron ore corridors operate the highest payload-per-trip configurations globally.
- Equipment Transportation:Wind turbine component logistics requires extendable flatbed platforms with hydraulic steering for blade maneuverability. North American renewable energy corridors drive specialized trailer engineering.
- Infrastructure Development:Bridge segment and precast concrete delivery follows project-specific permitting for overweight permits.
- Heavy Lifting:Crane-mounted configurations and self-propelled modular transporters serve industrial relocation and port logistics.
Activity volume concentrates in Material Transport; specialized engineering investment flows toward Equipment Transportation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in Germany and Sweden while consumption tilts toward mining-intensive economies. Australian iron ore operators and Chilean copper extractors drive fleet procurement intensity despite limited domestic production.
Australia
Western Australia's Pilbara region sustains the world's densest autonomous haulage corridors. The National Heavy Vehicle Regulator oversees Performance-Based Standards permitting multi-combination vehicles up to 60 metres. BHP and Rio Tinto operations near Port Hedland deploy 400-tonne payload configurations on 24-hour extraction schedules.
Chile
Copper extraction at 4,000-metre elevations in the Atacama Desert demands dual-fuel powerplants combating thin-air combustion degradation. The Ministry of Mining's decarbonization roadmap pressures fleet operators toward LNG-diesel hybrid architectures. Codelco's Chuquicamata and Escondida complexes anchor South American procurement volume.
China
Western province infrastructure corridors connecting Xinjiang and Qinghai mineral basins to coastal processing zones require sustained heavy-lifting capacity. MIIT enforces GB standards on commercial vehicle fuel consumption that constrain imported powertrain architectures. Sichuan-Chongqing manufacturing clusters produce articulated chassis for domestic mining logistics.
Germany
Engineering centers in Stuttgart and Munich anchor European powertrain development for Euro VII compliance. The KBA administers type approval for after-treatment systems meeting stricter NOx thresholds. MAN Truck & Bus and Daimler Truck operations concentrate R&D investment in integrated drivetrain architectures.
United States
EPA greenhouse gas standards and NHTSA fuel efficiency mandates reshape long-haul equipment transport specifications. Sleeper-cab configurations for wind turbine blade logistics face steepest aerodynamic adaptation costs. Texas and Oklahoma oilfield service corridors sustain demand for all-terrain heavy haulage platforms.
Heavy Haulage Trucks Market Competitive Landscape
Top-tier vendors anchor integrated powertrain engineering, while mid-tier specialists concentrate on regional compliance adaptation. The vendor base stratifies across three tiers: full-line OEMs with autonomous capabilities, regional chassis assemblers, and aftermarket retrofit providers. Two strategic archetypes dominate: technology leaders pursuing autonomous haulage systems and compliance-focused engineers optimizing for Euro VII and EPA dual-certification. Competitive intensity concentrates on strategic partnerships for sensor fusion software and geographic expansion into Kazakhstan and Mongolian mining corridors.
Among European-based engineering groups, Volvo Group, Daimler Truck, and MAN Truck & Bus occupy positions representing the integrated powertrain archetype. Volvo Group exemplifies technology leadership through autonomous system deployment. Daimler Truck anchors compliance engineering capacity for multi-jurisdiction certification. MAN Truck & Bus sits within the premium chassis segment serving mining and construction logistics. These three entities collectively represent the engineering-intensive tier competing on emission architecture and fleet management software rather than unit volume.
| Leading Market Players |
|---|
| Volvo Group |
| Daimler Truck |
| PACCAR Inc |
| Traton Group |
| Scania AB |
| Navistar International Corporation |
| Dongfeng Motor Group |
| MAN Truck & Bus |
| IVECO |
| Others |
Value Network & Pricing Analysis
Euro VII compliance mandates from the European Commission are compressing procurement timelines for after-treatment architectures, forcing fleet operators to absorb premium pricing for short-lead-time deliveries or risk operational downtime during platform transitions.
Pricing Analysis
Short-lead-time premiums dominate pricing negotiations as mining operators in Australia and Chile accelerate fleet renewal cycles ahead of emission deadlines. Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification urgency and after-sales bundling intensity. Price differentiation rests on EPA dual-certification status and autonomous system readiness as primary tiering variables. Cost compression in the mid-tier segment is intensifying because foundry capacity constraints for high-strength steel chassis components limit supplier flexibility.
Supply Chain Analysis
Single-source vulnerability sits with specialized high-strength steel alloy production concentrated in Germany, South Korea, and select Chinese foundries. Reinforced chassis architectures draw from manganese steel plate, heavy-duty axle assemblies, and SCR after-treatment modules as critical input categories. Logistics chokepoint risk concentrates at Baltic Sea ports handling European powertrain component exports to Kazakh mining corridors. Distribution runs through OEM-authorized dealer networks for new equipment, with independent rebuild centers capturing aftermarket drivetrain servicing volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around integrated powertrain engineering capabilities as Euro VII and EPA dual-certification requirements force smaller assemblers into exit or acquisition pathways.
For Market Incumbents: Anchor technology leadership through captive development of sensor fusion software for autonomous haulage corridors in Western Australia and Kazakhstan. Deepen backward integration into high-strength steel alloy supply through offtake agreements with German and South Korean foundries to mitigate single-source exposure. Defensive positioning must counter emerging retrofit specialists offering LNG-diesel conversion kits for pre-compliant fleet assets. For New Entrants and Emerging Players: Capture white-space opportunity in dual-fuel retrofit markets serving Chilean copper operators at 4,000-meter elevations where thin-air combustion degradation creates specification gaps. Modular wind turbine logistics for 80-meter blade transport in North American renewable energy corridors offers the most penetrable entry point. Go-to-market execution should prioritize condition-based maintenance contracts unbundled from OEM purchase agreements. For Investors and Strategic Acquirers: The window for entry favors vertically integrated mid-cap chassis assemblers with established Euro VII engineering roadmaps and autonomous system partnerships. Long-term viability hinges on acquisition targets demonstrating sustained R&D investment in integrated drivetrain architectures rather than regional compliance adaptation alone. Watch for inflection signals in Kazakh and Mongolian mining corridor procurement announcements as indicators of geographic demand migration.| Strategic Initiative | Industry Significance |
|---|---|
| Autonomous Haulage Deployment | Volvo Group's sensor fusion platforms enable 24-hour extraction schedules without operator fatigue constraints in Pilbara operations. |
| Dual-Fuel Powertrain Development | LNG-diesel hybrid architectures address thin-air combustion degradation at Chilean copper elevations above 4,000 meters. |
| After-Treatment System Integration | MAN Truck & Bus engineering centers anchor Euro VII compliance through SCR and DPF architecture redesigns. |
| Condition-Based Maintenance Unbundling | Western Australian mining logistics providers now source drivetrain servicing from specialized aftermarket rebuild centers. |
| High-Strength Steel Supply Security | Daimler Truck's foundry partnerships in Germany and South Korea mitigate chassis component single-source vulnerability. |
Research Methodology
Document review covered SEC 10-K filings from heavy-duty vehicle OEMs, EPA emission certification databases, and Euro VII regulatory impact assessments, complemented by interviews with fleet procurement directors at Australian iron ore operators, Chilean copper mining engineering heads, and European powertrain R&D directors. Secondary validation drew from MIIT GB standard enforcement notices, KBA type approval records, and customs trade data for high-strength steel alloy shipments. Bottom-up fleet deployment estimates and top-down OEM production forecasts underwent cross-triangulation.
Market sizing outputs reflect segment-level modeling across vehicle type, power rating band, and end-use application dimensions, with regional splits calibrated to mineral extraction project pipelines and infrastructure corridor development schedules. CAGRs were derived from fleet replacement cycle analysis and emission compliance deadline impacts. Industry-specific forecast inputs included autonomous haulage adoption curves in Western Australia and dual-fuel penetration rates at high-altitude mining elevations.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to battery-electric energy density breakthroughs and divergent regulatory timeline synchronization between EPA, Euro VII, and GB standard jurisdictions. Forecasts reflect documented assumptions regarding commodity price volatility effects on mining capital expenditure cycles and foundry capacity expansion timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Freight Trucking Market
Commercial Vehicles
Europe LCV Rental Market
Commercial Vehicles
Commercial Vehicle Steering Column Market
Commercial Vehicles
Global Light Commercial Vehicles Market
Commercial Vehicles
Global Timber Trailer Market
Commercial Vehicles
Truck-As-A-Service Market
Commercial Vehicles
Asia Pacific Non Passenger Vehicle Market
Commercial Vehicles
Utility Vehicle Market
Commercial Vehicles
Russia Commercial Vehicle Market
Commercial Vehicles
United States Commercial Vehicles Market
Commercial Vehicles
Truck-Mounted Road Sweeper Market
Commercial Vehicles
Cryogenic Liquid Transport Vehicle Market
Commercial Vehicles
Commercial Vehicle Driveline Support Bearings Market
Commercial Vehicles
Industrial Truck Market
Commercial Vehicles
Automated Truck Market
Commercial Vehicles
United States Vans Market