
 Poly Trucks Market | 2026-2036
Poly Trucks Market Size, Share, and Industry Trends Forecast 2026-2036
Poly Trucks Market Analytics
EU Green Deal commercial vehicle decarbonization targets is shifting procurement criteria toward lightweight, recyclable polymer truck bodies across European municipal fleets. Daimler AG leverages its modular platform architecture to integrate polymer composite cabs and cargo modules at scale. Volvo Group anchors its Nordic and North European presence through cold-climate polymer formulations that resist salt corrosion. Tata Motors Limited competes on cost-engineered rotational molding lines serving price-sensitive South Asian and African markets.
Poly trucks are commercial vehicles constructed with polymer-based body panels, cargo beds, or entire cab structures, typically fabricated through rotational molding or injection molding of polyethylene, polypropylene, or fiber-reinforced thermoplastic composites, delivering weight reductions of 30-50% versus steel equivalents while eliminating rust degradation in harsh service environments. The product type landscape shows dump trucks and flatbed trucks commanding current volume as construction and mining operators prioritize payload-to-weight optimization, while livestock trailers represent an emerging margin pool where antimicrobial polymer linings command premium positioning. End user demand from waste management is accelerating fastest as hydrogen sulfide and leachate exposure destroys metal bodies within five to seven years, driving replacement cycles toward polymer alternatives.
Federal EPA emissions standards and OSHA workplace safety regulations in the United States shape polymer truck specifications through weight-based fuel economy incentives and slip-resistant surface mandates. REACH chemical compliance and CE marking requirements in Europe restrict certain plasticizers and flame retardants, forcing reformulation of cabin interior polymers. India's BIS certification for automotive plastics and the PLI scheme for advanced manufacturing are accelerating domestic polymer truck component production. Stakeholders must monitor evolving extended producer responsibility frameworks for end-of-life vehicle recycling, as polymer content thresholds will determine future design compliance costs and material substitution trajectories.
Market Dynamics
Municipal fleet operators across North America and Europe are accelerating polymer truck procurement as corrosion-related metal body replacement costs exceed lifecycle budgets, forcing procurement departments to rewrite specifications around material durability rather than initial capital outlay.
Growth Catalysts
- EU Green Deal commercial vehicle mandates:European municipal fleets face binding decarbonization targets that favor lightweight, recyclable polymer bodies over steel alternatives. Procurement criteria now embed lifecycle carbon metrics.
- Waste management fleet corrosion cycles:Hydrogen sulfide and leachate exposure destroys conventional metal truck bodies within five to seven years. Operators in the United States and Germany are specifying polymer alternatives for refuse collection vehicles.
- Rotational molding quality advances:India's BIS polymer certification standards and improved domestic rotational molding capabilities are lifting production quality, enabling local supply of corrosion-resistant truck components.
Market Restraints
- Petrochemical feedstock volatility:Polyethylene and polypropylene resin prices fluctuate with crude oil benchmarks, compressing margin predictability for body fabricators locked into municipal tender pricing.
- Repair network concentration:Polymer body damage requires specialized thermal welding and rotational molding repair capabilities concentrated in Germany, the United States, and China, extending downtime for remote fleet operators.
- Steel substitution persistence:Heavy-haul mining and construction segments in Australia and Canada continue specifying steel dump bodies for extreme abrasion environments where polymer wear rates remain uncompetitive.
Strategic Opportunities
- Livestock trailer antimicrobial linings:Premium-positioned polymer formulations with embedded silver-ion or copper-based antimicrobial properties command margin premiums in European and North American agricultural logistics.
- India PLI scheme manufacturing incentives:India's Production Linked Incentive scheme for advanced manufacturing is accelerating domestic polymer truck component production, creating export-competitive supply for African and Southeast Asian markets.
- End-of-life recycling infrastructure:Extended producer responsibility frameworks in Germany and California are creating first-mover advantages for manufacturers with established polymer recovery and reprocessing capabilities.
Industry Challenges
- Polymer welding technician scarcity:Fleet maintenance departments lack trained thermal welding specialists for polymer body repair, forcing reliance on OEM service networks with extended lead times.
- REACH compliance reformulation cycles:European chemical restrictions on plasticizers and flame retardants require continuous cabin interior polymer reformulation, extending product development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poly Trucks Market |
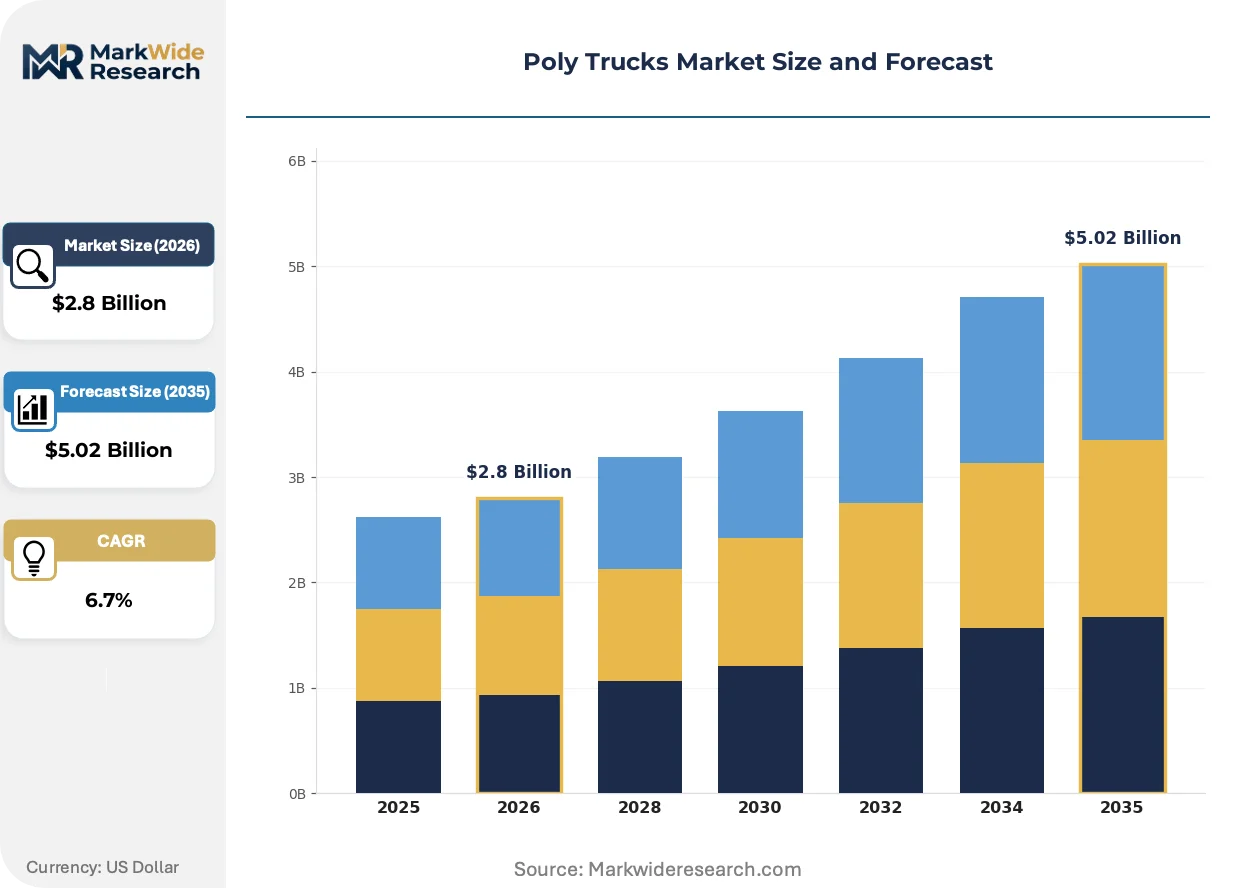
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dump Trucks, Flatbed Trucks, Horse Trailers, Livestock Trailers End User: Agriculture, Construction, Logistics, Waste Management Manufacturing Stage: Injection Molding, Rotational Molding, Extrusion, Blow Molding Size: Small Trucks, Medium Trucks, Large Trucks, Heavy-Duty Trucks |
| Companies Covered | Daimler AG, PACCAR Inc., Volvo Group, Traton Group, Navistar International Corporation, Isuzu Motors, Tata Motors Limited, Dongfeng Motor Group, Eicher Motors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poly Trucks Market Evolving Landscape
Material science breakthroughs and regulatory chemistry restrictions are converging to reshape polymer truck specification standards, with fleet operators demanding performance validation data that exceeds traditional metals-based testing protocols.
Fiber-reinforced thermoplastic composites are absorbing structural load requirements previously reserved for steel cabs and cargo modules. Mining operators in Western Australia and Chile are piloting these materials for payload-to-weight optimization in articulated dump trucks. The technology is absorbing certification complexity as manufacturers commission new crash-test and fatigue-validation protocols specific to polymer structural performance.
REACH chemical compliance in Europe is restricting legacy plasticizers and halogenated flame retardants in cabin interior polymers. ECHA substance evaluations are forcing compounders to reformulate with bio-based plasticizers and phosphorus-based fire retardants. German municipal fleet tenders now require full material disclosure documentation, shifting competitive advantage toward vertically integrated compounders with in-house regulatory affairs capabilities.
Lifecycle service contracting is displacing traditional capital purchase models for municipal waste fleets. French and Italian municipalities are bundling polymer body supply with fifteen-year maintenance and end-of-life recovery obligations. This model concentrates vendor selection criteria on total cost of ownership analytics rather than upfront unit pricing, favoring established European manufacturers with proven field service networks over low-cost import competitors.
Poly Trucks Market Segmentation
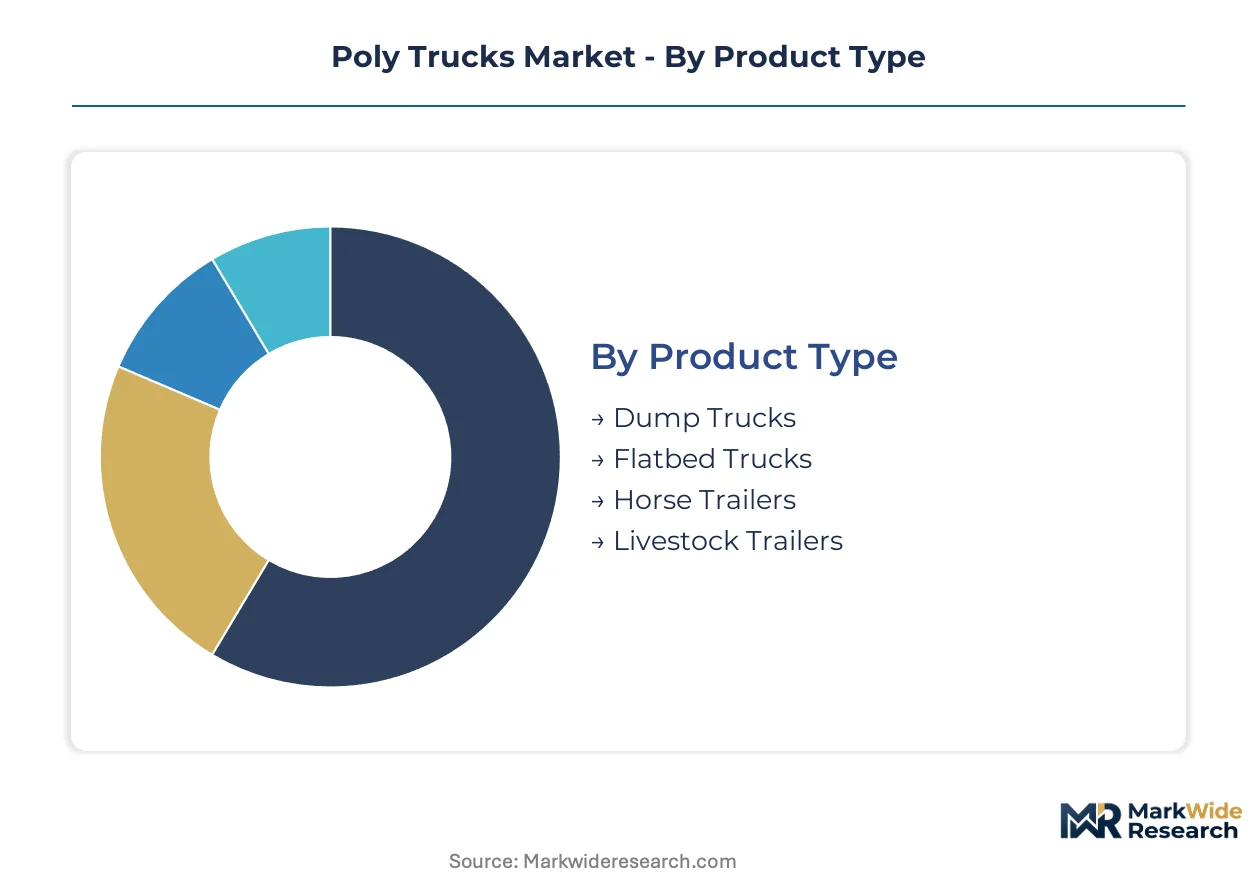
Poly truck procurement cycles diverge sharply across end-use applications, with replacement timelines driven by corrosion exposure rather than mechanical wear. Fleet operators now specify polymer bodies based on total lifecycle cost models that privilege material durability over initial capital expenditure.
Product Type:
Upgrade cycles vary dramatically by vocational application, with construction and mining operators prioritizing payload optimization while agricultural buyers emphasize hygiene and biosecurity features.
- Dump Trucks:Articulated and rigid dump trucks utilize high-density polyethylene cargo beds with steel-reinforced edges for abrasion resistance. Mining operators in Western Australia and Chile specify these for 30-50% weight reduction against steel equivalents, though extreme abrasion environments still favor metal in some haulage segments.
- Flatbed Trucks:Polymer flatbeds fabricated through rotational molding eliminate rust degradation in salt-exposed logistics corridors. German freight operators along North Sea routes have accelerated procurement as corrosion-related steel replacement costs exceed operational budgets.
- Horse Trailers:Lightweight polymer composite walls reduce towing strain and improve fuel economy for private equestrian transport.
- Livestock Trailers:Rotational-molded polymer interiors with antimicrobial linings command premium positioning in European agricultural logistics.
Dump trucks sit at the top of the volume ranking, with livestock trailers climbing the fastest.
End User:
Cost tier stratification separates municipal fleet operators with fifteen-year service contracting models from price-sensitive agricultural buyers operating on shorter replacement cycles.
- Waste Management:Refuse collection vehicles face hydrogen sulfide and leachate exposure that destroys metal bodies within five to seven years. United States municipal fleets now mandate polymer construction in tender specifications, with French and Italian operators bundling supply with lifecycle maintenance obligations.
- Construction:Payload-to-weight optimization drives polymer adoption in dump trucks and material handlers. Mining operators balance polymer weight advantages against steel durability in extreme abrasion environments.
- Agriculture:Livestock and horse transport operators prioritize antimicrobial surfaces and washdown compatibility. European biosecurity regulations accelerate specification of embedded silver-ion polymer linings.
- Logistics:Parcel and general freight operators specify polymer bodies for corrosion resistance in coastal and de-iced highway corridors.
Waste management leads current procurement volume, with agriculture expanding most quickly on antimicrobial premium positioning.
Manufacturing Stage:
Application requirements dictate process selection, with structural load-bearing components demanding fiber reinforcement while hollow bodies suit rotational molding economics.
- Rotational Molding:Hollow, seamless polymer bodies for cargo modules and livestock trailers achieve uniform wall thickness without weld lines. India's BIS certification standards and advancing domestic capabilities are lifting production quality for export-competitive supply.
- Injection Molding:High-volume cab interior components and structural brackets demand dimensional precision and surface finish quality. REACH chemical compliance in Europe forces continuous reformulation of plasticizers and flame retardants.
- Extrusion:Continuous polymer profiles for structural reinforcements and edge protection strips.
- Blow Molding:Hollow fuel tanks and fluid reservoirs integrate with polymer body systems.
Rotational molding dominates body fabrication volume, with injection molding gaining share fastest on cabin interior complexity.
Size:
Customer type fragmentation separates municipal fleet aggregators with standardized tender specifications from specialized operators demanding custom payload configurations.
- Large Trucks:Heavy-haul refuse collection and construction dump trucks require structural fiber reinforcement to replace steel load-bearing capacity. German and United States manufacturers lead crash-test validation protocols for polymer structural performance.
- Medium Trucks:Regional logistics and municipal service vehicles balance payload capacity with maneuverability requirements. European urban access regulations favor weight-optimized polymer construction.
- Small Trucks:Last-mile delivery and light agricultural use cases prioritize corrosion resistance over structural loading.
- Heavy-Duty Trucks:Mining articulated haulers pilot fiber-reinforced thermoplastic composites for extreme payload-to-weight optimization.
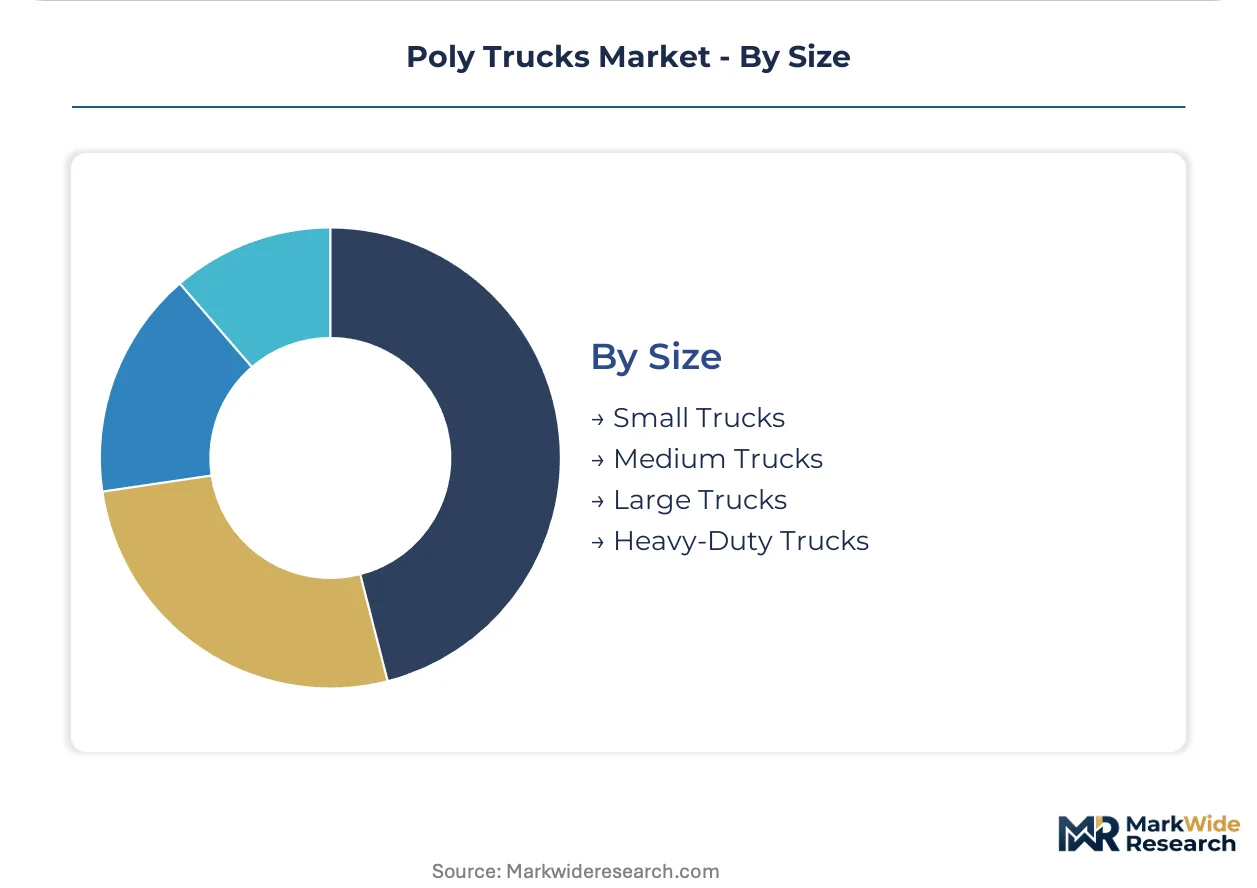
Large trucks capture the highest procurement volume, with heavy-duty trucks on the steepest expansion trajectory as mining operators validate composite structural performance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Poly truck manufacturing traces its commercial origins to German rotational molding workshops serving municipal waste fleets in the 1980s, with industrial-scale adoption spreading through Nordic markets seeking corrosion-resistant alternatives to steel salt degradation.
United States
Municipal waste management fleets in California and the Northeast corridor are retrofitting refuse collection vehicles with polymer bodies as EPA emissions standards reward weight-based fuel economy improvements. OSHA workplace safety regulations mandate slip-resistant surfaces on commercial vehicle cargo areas. Detroit-area manufacturing clusters host specialized thermal welding repair networks serving Great Lakes region fleet operators.
Germany
North Sea logistics corridors drive polymer flatbed procurement as salt corrosion destroys steel alternatives within operational lifecycles. REACH chemical compliance and CE marking requirements restrict legacy plasticizers in cabin interior polymers. Bavaria-based compounders maintain in-house regulatory affairs capabilities to manage continuous ECHA substance evaluation cycles.
China
Domestic production quality advances through MIIT industrial standards and rotational molding capability expansion serving construction and mining payload optimization demand. Dual carbon goals accelerate lightweight material specification in municipal fleet procurement. Yangtze River Delta manufacturing bases supply fiber-reinforced thermoplastic composite components for articulated dump truck pilots.
India
BIS polymer certification standards and PLI scheme manufacturing incentives are lifting domestic rotational molding quality for export-competitive supply to African and Southeast Asian markets. CDSCO-equivalent automotive plastics regulations align with international crash-test validation protocols. Maharashtra and Gujarat industrial corridors concentrate new production capacity serving price-sensitive regional demand.
Australia
Western Australian mining operators pilot fiber-reinforced thermoplastic composites for extreme payload-to-weight optimization in articulated haulers. Heavy-haul construction segments persist with steel dump bodies for abrasion environments where polymer wear rates remain uncompetitive. Perth-based service networks specialize in polymer structural repair for remote fleet maintenance.
Poly Trucks Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across tiered market positions. The vendor base clusters around three strategic archetypes: European premium-tier manufacturers with established field service networks, Asian cost-engineered specialists serving price-sensitive emerging markets, and diversified automotive conglomerates leveraging modular platform architectures. Competitive dynamics center on lifecycle service contracting displacement of capital purchase models and vertical integration into polymer compounding capabilities.
Among European-based manufacturers, Daimler AG and Volvo Group occupy positions exemplifying premium-tier positioning through cold-climate formulation expertise and modular integration capabilities. Tata Motors Limited represents the cost-engineered archetype, with Indian production bases serving rotational molding demand across South Asian and African price-sensitive segments. These three anchors illustrate the geographic and tier-based stratification governing vendor selection in municipal tender processes.
| Leading Market Players |
|---|
| Daimler AG |
| PACCAR Inc. |
| Volvo Group |
| Traton Group |
| Navistar International Corporation |
| Isuzu Motors |
| Tata Motors Limited |
| Dongfeng Motor Group |
| Eicher Motors |
| Others |
Value Network & Pricing Analysis
Polyethylene resin price indices cascading from crude oil benchmarks transmit volatility through three distinct pricing tiers for polymer truck body fabricators. Municipal tender pricing locks compress margins when feedstock costs spike, forcing procurement departments to weight lifecycle durability premiums against capital budget constraints.
Pricing Analysis
Lifecycle service contracting separates premium European manufacturers bundling fifteen-year maintenance obligations from price-sensitive import competitors. Price differentiation hinges on REACH-compliant material certification grades and established thermal welding repair network density. Cost compression in the standard tier intensifies as Indian rotational molding capacity expands export-competitive supply. Agricultural livestock trailer buyers exhibit highest price sensitivity, while German municipal fleet operators prioritize total cost of ownership over upfront unit costs.
Supply Chain Analysis
Freight cost differentials between German compounders and Indian rotational molding centers shape competitive positioning in African and Southeast Asian markets. Supply concentrates in Germany, the United States, and China for specialized polymer compounding and thermal welding repair capabilities. Raw material flows draw from Saudi Arabian and Qatari petrochemical feedstock, with European REACH-compliant additive packages sourced from Bavaria-based specialty chemical producers. Single-source vulnerability concentrates in rotational molding equipment suppliers concentrated in Northern Italy. Distribution runs through OEM-authorized service networks for municipal fleet operators, with independent distributors serving agricultural and construction segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The poly trucks market functions as a regulatory compounder where EU Green Deal commercial vehicle decarbonization mandates harden procurement criteria toward lightweight recyclable alternatives.
For Market Incumbents: Cement cold-climate formulation leadership through proprietary salt-corrosion resistant polymer blends targeting Nordic and North American municipal fleets. Deepen backward integration into REACH-compliant compounding capabilities to capture margin from continuous ECHA substance evaluation cycles. Defend against Indian cost-engineered entrants by expanding thermal welding repair network density in secondary European markets. For New Entrants and Emerging Players: Municipal fleet aggregators in France and Italy represent the most penetrable channel partner type, with lifecycle service contracting models displacing capital purchase paradigms. Target antimicrobial livestock trailer linings in European agricultural logistics where biosecurity regulations accelerate specification of embedded silver-ion formulations. Pursue joint development agreements with Yangtze River Delta fiber-reinforced thermoplastic composite suppliers to bypass capital-heavy rotational molding infrastructure. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated compounders possessing in-house regulatory affairs capabilities managing REACH reformulation cycles. Five-to-ten year viability favors manufacturers with established polymer recovery and reprocessing infrastructure ahead of extended producer responsibility framework maturation. Watch California and German end-of-life vehicle recycling threshold announcements as inflection indicators for material substitution trajectories and design compliance cost allocation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Bavaria-based compounders capture margin from continuous ECHA plasticizer reformulation mandates. |
| Lifecycle Service Contracting Model | French and Italian municipalities bundle polymer body supply with fifteen-year maintenance obligations. |
| Antimicrobial Livestock Trailer Lining Development | European biosecurity regulations accelerate specification of embedded silver-ion polymer formulations. |
| Fiber-Reinforced Thermoplastic Composite Certification | German and United States manufacturers commission crash-test protocols for structural polymer performance. |
| End-of-Life Recycling Infrastructure Buildout | Extended producer responsibility frameworks in Germany and California reward established recovery capabilities. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with municipal fleet procurement directors, rotational molding plant managers, polymer compounder regulatory affairs leads, and aftermarket thermal welding service technicians informed demand-side and supply-side dynamics. Secondary sources include EPA emissions filings, ECHA substance evaluation databases, BIS certification registries, and customs trade data for polyethylene and polypropylene resin flows. Bottom-up segment sizing triangulated against top-down macroeconomic drivers.
Rate-of-change decomposition across product type, end user, manufacturing stage, and size dimensions structures the analytical framework. Modeled segments include dump trucks, flatbed trucks, horse trailers, and livestock trailers by product type; waste management, construction, agriculture, and logistics by end user; rotational molding, injection molding, extrusion, and blow molding by manufacturing stage; and large, medium, small, and heavy-duty trucks by size. CAGRs derived from regression analysis of historical procurement cycles against regulatory milestone timing and fleet replacement timelines. Industry-specific inputs include hydrogen sulfide corrosion exposure rates for refuse collection vehicles and mining payload-to-weight optimization validation data.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to petrochemical feedstock volatility and REACH chemical restriction scope expansion. Forecasts reflect assumptions around municipal sustainability mandate enforcement consistency and rotational molding quality advancement trajectories. A model refresh is warranted upon material change in extended producer responsibility polymer content thresholds or BIS certification standard revision announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy-Duty Trucks
India Vacuum Truck Market
Heavy-Duty Trucks
Hard Tonneau Cover Market
Heavy-Duty Trucks
China Full Truckload Road Freight Transport Market
Heavy-Duty Trucks
US Tanker Truck Market
Heavy-Duty Trucks
Saudi Arabia Refrigerated Truck Market
Heavy-Duty Trucks
Heavy-Duty Vehicle Engine Brake Market
Heavy-Duty Trucks
Automotive High Performance Trucks Market
Heavy-Duty Trucks
Truck Diagnostic Market
Heavy-Duty Trucks
Dump Trucks and Mining Trucks Market
Heavy-Duty Trucks
Stacker Truck Market
Heavy-Duty Trucks
Heavy-Duty Truck Axle Locking Actuator Components Market
Heavy-Duty Trucks
Fire Trucks Market
Heavy-Duty Trucks
Truck Racks Market
Heavy-Duty Trucks
Mexico Refrigerated Truck Market
Heavy-Duty Trucks
Medium and Heavy Duty Commercial Vehicles (MHCV) Market
Heavy-Duty Trucks
Garbage Truck Bodies Market