
 Flatbed Truck Market | 2026-2036
Flatbed Truck Market Size, Share, and Industry Trends Forecast 2026-2036
Flatbed Truck Market Insights
Energy sector logistics is collapsing into flatbed demand as renewable infrastructure deployment accelerates across North America. Knight-Swift Transportation leverages its terminal network to dominate cross-border heavy-haul corridors. PGT Trucking Inc. specializes in steel and building materials transport, sustaining pricing power through dedicated flatbed capacity.
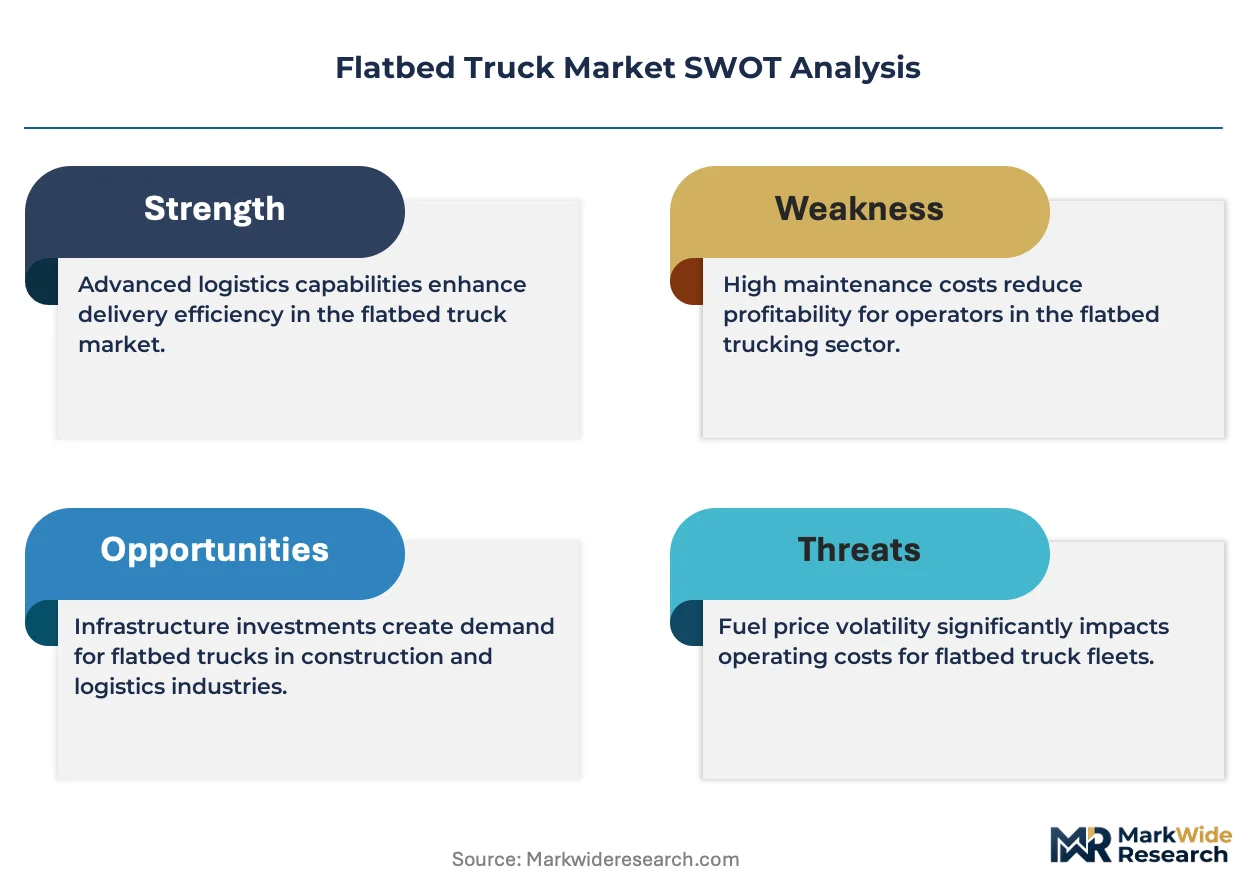
A flatbed truck is an open-deck commercial vehicle with a level platform lacking fixed sides or roof, typically constructed from high-tensile steel or aluminum alloys rated for loads exceeding 80,000 pounds gross vehicle weight, designed to haul oversized, irregular, or non-containerized freight that cannot fit in enclosed trailers. Heavy-duty load capacity segments anchor the revenue pool due to infrastructure and energy project requirements, while electric fuel type variants represent the fastest-growing category as fleet operators navigate zero-emission mandates. Standard flatbed vehicle types occupy the mature volume position, though drop deck configurations command premium positioning for height-restricted cargo.
The EPA Phase 3 greenhouse gas standards and NHTSA fuel efficiency rules are forcing diesel-dependent operators toward hybrid and electric powertrains, reshaping fleet procurement timelines and total cost of ownership calculations. FMCSA hours-of-service regulations and state-level weight limit variances further fragment operational compliance across interstate corridors. Stakeholders must monitor powertrain certification pipelines and charging infrastructure buildouts to secure competitive positioning before regulatory thresholds harden.
Market Dynamics
The EPA Phase 3 greenhouse gas standards are compressing diesel procurement timelines and forcing fleet operators to recalculate total cost of ownership around electric and hybrid powertrains, fundamentally restructuring capital deployment across heavy-haul logistics.
Growth Catalysts
- Infrastructure Investment:Federal highway and bridge appropriations in the United States are accelerating flatbed deployment for steel, concrete, and heavy equipment transport to job sites.
- Renewable Energy Buildout:Wind turbine component logistics and solar farm construction in China and Germany are generating specialized heavy-haul demand that standard enclosed trailers cannot accommodate.
- Battery-Electric Powertrain Maturation:Lithium-ion energy density improvements and thermal management advances are extending electric flatbed range into viable territory for regional freight corridors.
Market Restraints
- Charging Infrastructure Gaps:Interstate highway electrification remains uneven, with corridor coverage concentrated in coastal United States markets and major German autobahn routes.
- Steel Price Volatility:Flatbed platform fabrication depends on high-tensile steel and aluminum alloy inputs subject to tariff fluctuations and energy-intensive smelting cost spikes.
- Weight Penalty Tradeoffs:Battery-electric drivetrains add 8,000-12,000 pounds to gross vehicle weight, reducing legal payload capacity under Federal Bridge Formula limits.
Strategic Opportunities
- Drop Deck Specialization:Height-restricted cargo segments including heavy machinery and modular construction components command premium positioning in United States and German markets.
- Cross-Border Heavy-Haul Corridors:United States-Mexico-Canada Agreement implementation is standardizing dimensional permitting for oversized loads across North American trade lanes.
- Telematics-Enabled Fleet Optimization:Integration of route planning software with real-time load board visibility is creating asset-light brokerage models for owner-operators.
Industry Challenges
- Certification Bottlenecks:EPA and CARB powertrain approval timelines for electric heavy-duty platforms are extending 18-24 months beyond diesel certification cycles.
- Driver Qualification Scarcity:Specialized endorsements for oversized load escort and securement expertise are concentrating qualified operator pools in legacy freight markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flatbed Truck Market |
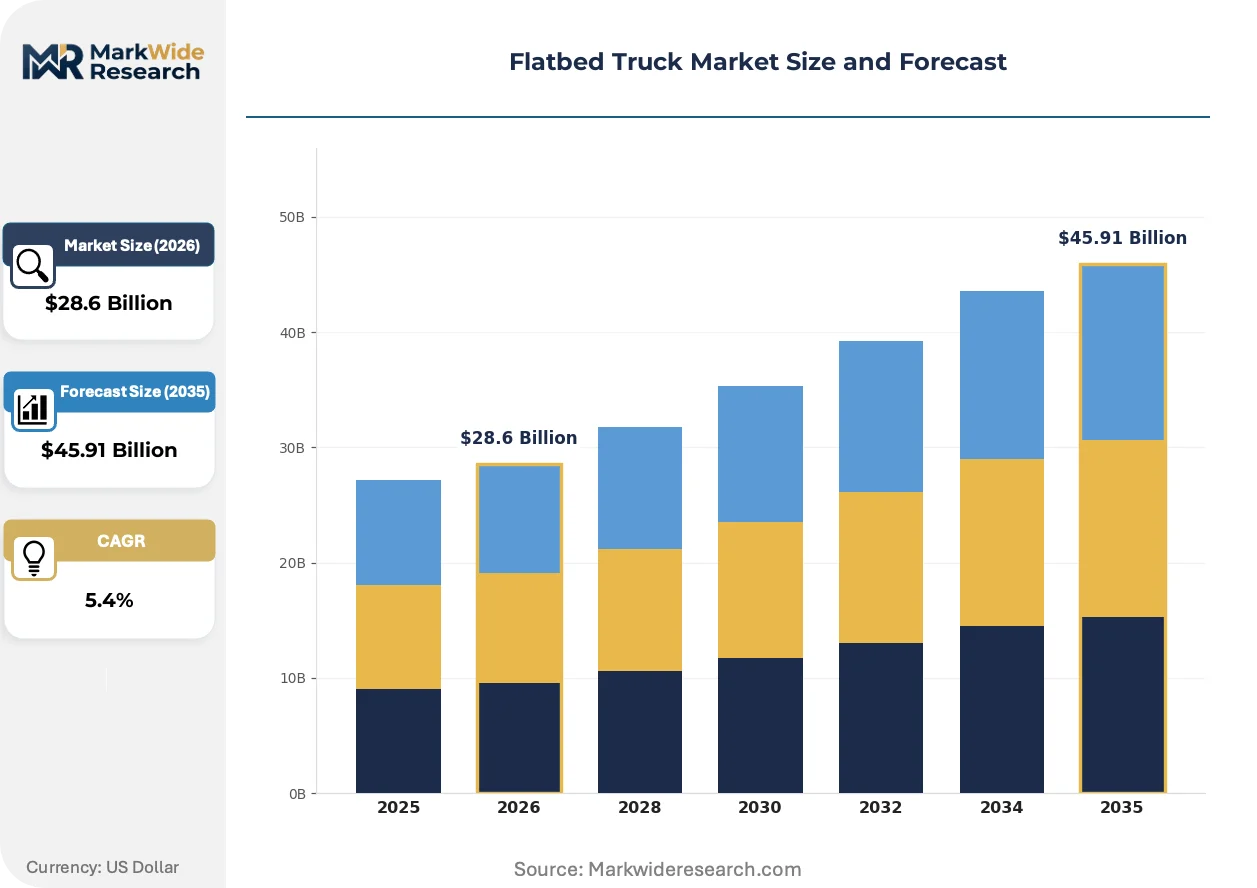
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $45.91 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Standard Flatbed, Lowboy, Drop Deck, High-Rail Application: Construction, Agriculture, Logistics, Material Handling Load Capacity: Light-Duty, Medium-Duty, Heavy-Duty, Extra Heavy-Duty Fuel Type: Diesel, Gasoline, Electric, Hybrid |
| Companies Covered | Schneider National, Mercer Transportation, TFI International, TMC Transportation, Maverick USA, Knight-Swift Transportation, Prime Inc., PGT Trucking Inc., J.B. Hunt Transport Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flatbed Truck Market Trends and Innovations
Powertrain diversification is fragmenting fleet standardization as operators balance zero-emission mandates against payload economics and charging infrastructure availability. Three forces are compressing procurement timelines and reshaping competitive positioning.
Aluminum alloy platform construction is fragmenting the traditional steel-dominated manufacturing base. Fleet operators seeking weight reduction for electric drivetrain compensation are specifying aluminum-intensive decks at 15-20% cost premiums. This materials shift is compressing supplier margins and forcing fabricators to retool welding and heat-treatment processes.
The EPA Phase 3 greenhouse gas standards and companion NHTSA fuel efficiency rules are mandating 40% CO2 reduction from 2027 model year heavy-duty vehicles. Diesel-dependent operators face accelerated depreciation schedules and residual value uncertainty. United States-based fleet managers are pre-ordering electric platforms ahead of certification finalization to secure production slots.
Digital freight matching platforms are disintermediating traditional broker relationships for spot flatbed capacity. Owner-operators and small fleets in the United States are adopting app-based load discovery that bypasses legacy telephone dispatch. This channel shift concentrates pricing power with platforms that aggregate real-time supply visibility across fragmented carrier bases.
Flatbed Truck Market Segmentation
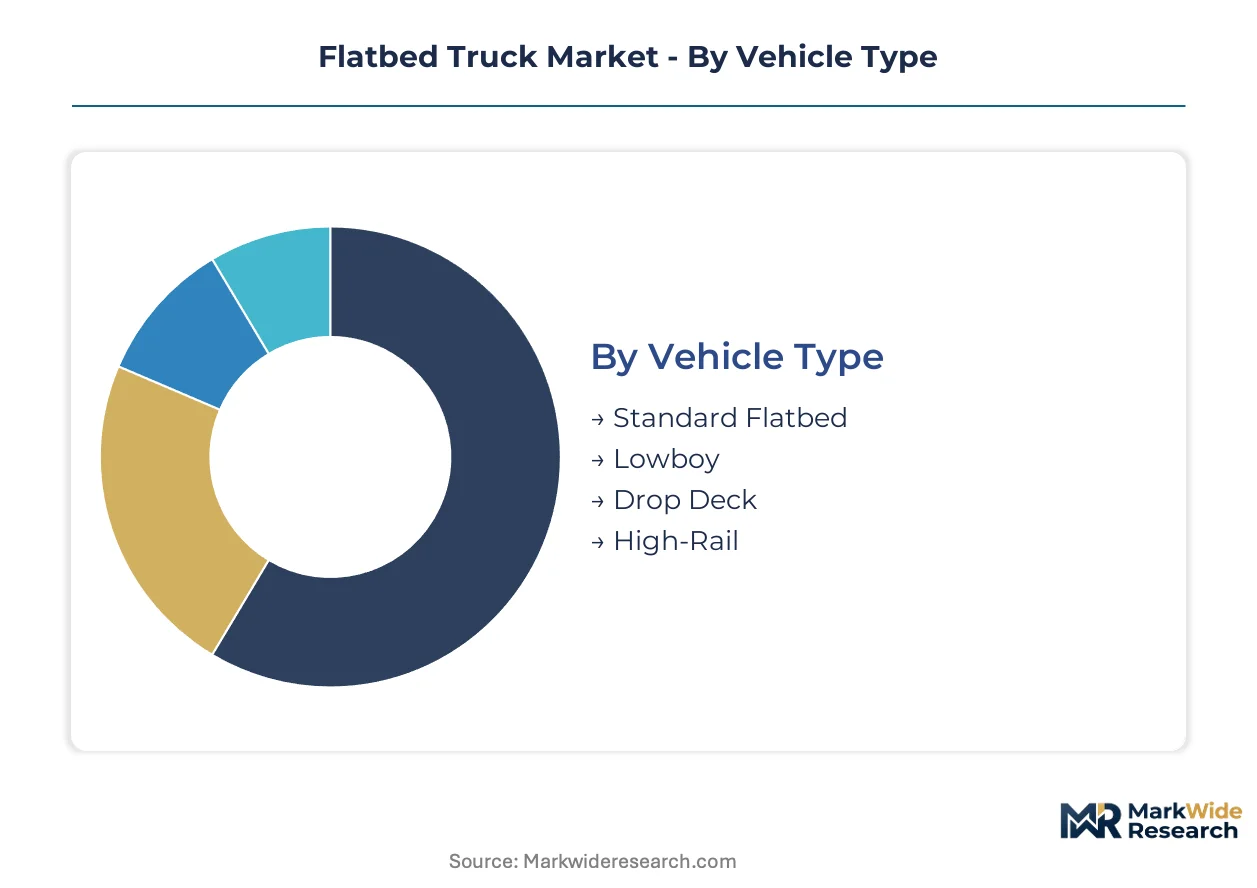
Flatbed truck segmentation reveals how regulatory pressure and cargo specialization fragment procurement strategies across fleet operators. Distinct vehicle configurations, duty cycles, and powertrain specifications command divergent pricing premiums and residual value profiles.
Vehicle Type:
EPA Phase 3 greenhouse gas standards and state-level dimensional permitting rules create divergent compliance burdens across platform configurations, reshaping fleet standardization priorities.
- Standard Flatbed:The classic open-deck platform with fixed height and no specialized lowering mechanisms dominates volume procurement for general freight. Construction material haulers in the United States specify this configuration for steel beam and lumber transport where vertical clearance permits standard loading heights. Established volume favors Standard Flatbed; emerging adoption favors Drop Deck.
- Drop Deck:A two-level platform with a lowered rear deck accommodates height-restricted cargo while maintaining legal road clearances. German heavy-haul operators deploy Drop Deck configurations for wind turbine nacelle transport under autobahn bridge restrictions. The configuration commands 15-20% pricing premiums over standard platforms due to specialized engineering.
- Lowboy:Extremely low deck height enables oversized machinery and construction equipment transport with minimized center of gravity.
- High-Rail:Dual-mode road-rail capability serves maintenance-of-way contractors on Class I railroad networks in the United States.
Established volume favors Standard Flatbed; emerging adoption favors Drop Deck.
Application:
End-use concentration determines duty cycle severity and replacement frequency, with infrastructure and energy logistics commanding premium specifications.
- Construction:Hauls steel, concrete, and heavy equipment to active job sites under severe loading conditions. United States infrastructure appropriations are accelerating fleet turnover in this segment as contractors expand capacity for bridge and highway projects. Established volume favors Construction; emerging adoption favors Logistics.
- Logistics:Cross-border freight and specialized heavy-haul corridors demand telematics-integrated platforms with real-time load tracking. The segment is expanding most quickly as digital freight matching platforms aggregate spot capacity for irregular routes.
- Agriculture:Seasonal harvest equipment and bulk commodity transport requires corrosion-resistant decking and specialized securement points.
- Material Handling:Intermodal container drayage and warehouse feed operations utilize standardized chassis configurations for rapid turnaround.
Construction anchors current procurement volumes; Logistics is climbing the fastest on e-commerce fulfillment and renewable energy component movement.
Load Capacity:
Federal Bridge Formula limits and state weight permit variances fragment operational economics across duty classifications, with electric drivetrain weight penalties disproportionately impacting payload calculations.
- Heavy-Duty:Rated for 26,001-33,000 pounds gross vehicle weight, this classification anchors fleet revenue pools for infrastructure and energy project logistics. Chinese operators specify Heavy-Duty platforms for solar farm construction equipment deployment under MIIT commercial vehicle standards.
- Extra Heavy-Duty:Exceeds 33,000 pounds GVW and requires specialized permitting for superload configurations on interstate corridors.
- Medium-Duty:14,001-26,000 pounds GVW serves regional delivery and last-mile construction material distribution.
- Light-Duty:Under 14,000 pounds GVW accommodates utility and service applications with simplified operator licensing requirements.
Heavy-Duty configurations dominate capital deployment; Extra Heavy-Duty is gaining share fastest on wind turbine component logistics scaling.
Fuel Type:
CARB and EPA certification timelines are compressing diesel procurement windows while battery-electric range limitations reshape duty cycle assignments.
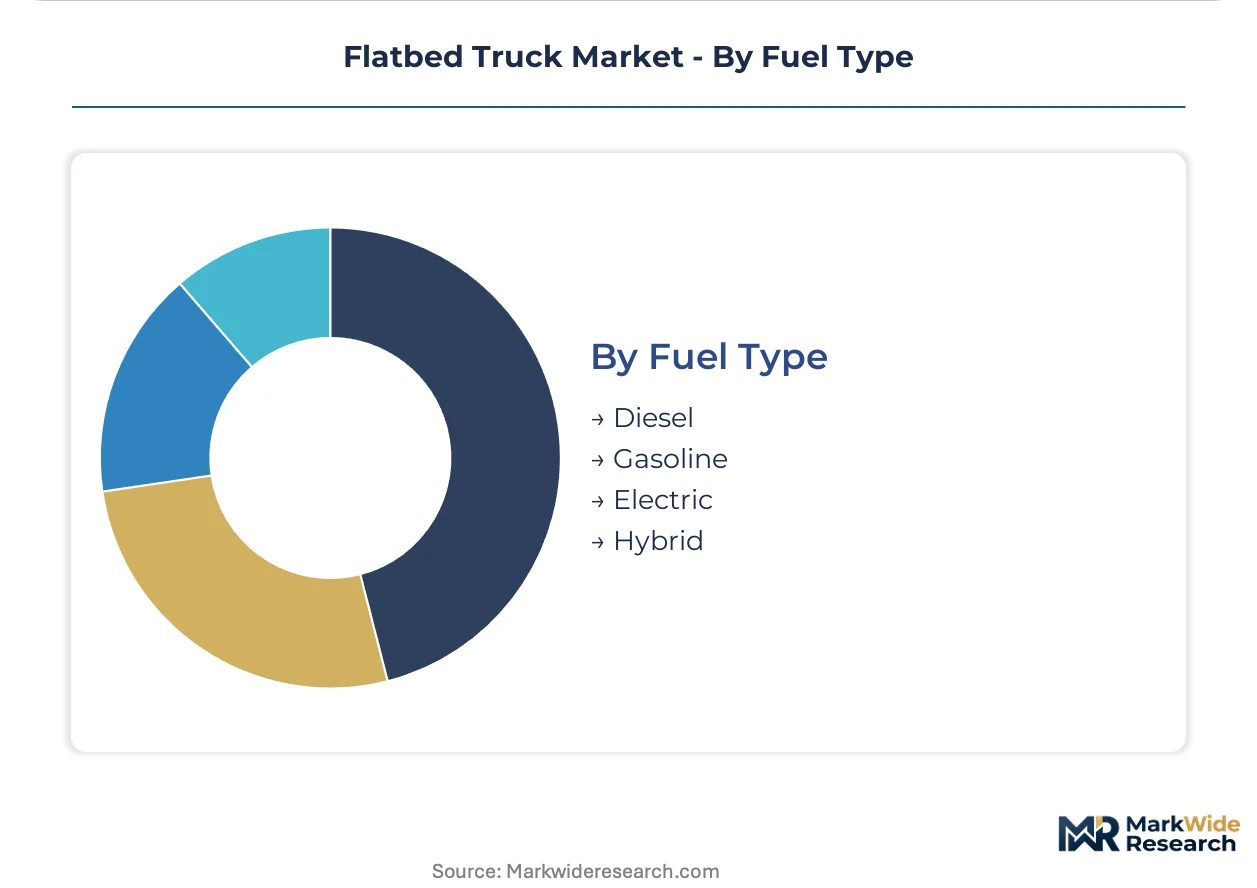
- Electric:Lithium-ion platforms with 200-300 mile regional range are securing production slots ahead of final EPA powertrain approval. Fleet operators in California navigate CARB Advanced Clean Trucks mandates through early electric platform adoption.
- Diesel:Compression-ignition powertrains retain dominance in long-haul heavy-haul corridors where charging infrastructure remains sparse.
- Hybrid:Diesel-electric architectures bridge range anxiety and emission reduction requirements for variable-duty cycles.
- Gasoline:Spark-ignition engines serve light-duty and medium-duty applications with lower upfront capital requirements.
Diesel retains established fleet share; Electric is expanding most quickly on zero-emission mandate compliance and total cost of ownership recalculation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexican flatbed manufacturers supply cross-border capacity into the United States and Canada through USMCA-standardized permitting corridors. German fabricators export specialized drop-deck platforms for wind turbine logistics across European heavy-haul networks. Chinese producers dominate solar farm construction equipment deployment throughout Asia-Pacific infrastructure zones.
United States
Federal highway appropriations under the Infrastructure Investment and Jobs Act accelerate steel and concrete transport to bridge construction sites. EPA Phase 3 greenhouse gas standards compress diesel procurement timelines while CARB Advanced Clean Trucks mandates reshape California fleet composition. The Permian Basin energy corridor in Texas anchors heavy-haul demand for drilling equipment and modular refinery components.
Germany
Wind turbine nacelle logistics generate specialized drop-deck procurement under strict autobahn dimensional restrictions. KBA certification requirements for electric heavy-duty platforms extend approval cycles beyond conventional diesel timelines. The Ruhr industrial cluster concentrates aluminum-intensive platform fabrication for weight-sensitive electric drivetrain applications.
China
Solar farm construction across western provinces drives heavy-duty flatbed deployment for panel racking and inverter station equipment. MIIT commercial vehicle standards govern powertrain efficiency benchmarks and domestic content requirements. The Yangtze River Delta manufacturing belt supplies standardized platforms for Belt and Road infrastructure exports into Southeast Asia.
Canada
Oil sands equipment logistics in Alberta and Saskatchewan sustain extra heavy-duty platform demand for superload configurations. Transport Canada vehicle safety regulations align with US FMCSA standards to facilitate seamless cross-border heavy-haul operations. The Vancouver gateway cluster handles oversized cargo inbound from Pacific Rim manufacturing centers for distribution throughout North American interior markets.
India
National highway expansion projects under the Bharatmala program multiply flatbed requirements for road construction machinery and precast concrete segments. BIS certification mandates for commercial vehicle safety systems raise entry barriers for imported platform configurations. The Delhi-Mumbai Industrial Corridor anchors logistics demand for heavy equipment transport between manufacturing zones and emerging smart city construction sites.
Flatbed Truck Market Competitive Landscape
Listed leaders compete with private specialists across terminal network density and dedicated capacity contracts. The vendor base fragments between asset-heavy fleet operators and technology-enabled brokerage platforms. Three archetypes dominate: integrated trucking-and-logistics conglomerates, specialized heavy-haul carriers with escort capabilities, and digital freight matching platforms aggregating spot capacity. Competitive intensity concentrates on M&A consolidation of regional flatbed fleets and strategic partnerships with renewable energy developers for dedicated turbine transport contracts.
Within the integrated carrier tier, Knight-Swift Transportation and J.B. Hunt Transport Services exemplify scale-driven operators leveraging terminal networks for cross-border corridor dominance. PGT Trucking Inc. represents the specialized heavy-haul archetype, occupying a position in steel and building materials transport where dedicated flatbed capacity commands pricing premiums. These three companies illustrate how divergent scale and specialization strategies coexist within fragmented procurement environments.
| Leading Market Players |
|---|
| Schneider National |
| Mercer Transportation |
| TFI International |
| TMC Transportation |
| Maverick USA |
| Knight-Swift Transportation |
| Prime Inc. |
| PGT Trucking Inc. |
| J.B. Hunt Transport Services |
| Others |
Pricing and Supply Chain Analysis
EPA Phase 3 greenhouse gas standards and CARB Advanced Clean Trucks mandates gate both supplier qualification and price differentiation simultaneously, compressing diesel procurement windows while elevating electric platform premiums. Fleet operators face accelerated depreciation schedules that reshape total cost of ownership calculations across powertrain generations.
Pricing Analysis
Current-generation diesel platforms, prior-generation hybrid architectures, and next-generation battery-electric systems stratify across premium, standard, and economy tiers. Electric flatbeds command 25-35% upfront premiums over diesel equivalents, justified by CARB compliance value and residual certainty under zero-emission mandates. Cost compression in the diesel tier intensifies because fleet operators front-load electric pre-orders ahead of certification finalization. Regional freight operators show highest price sensitivity due to thin margins on irregular routes, while dedicated heavy-haul contractors for renewable energy projects absorb premiums for specialized drop-deck configurations.
Supply Chain Analysis
Port congestion on Trans-Pacific lanes and container availability fluctuations in Los Angeles-Long Beach inflate inbound logistics costs for high-tensile steel and aluminum alloy inputs. Platform fabrication concentrates in China, Germany, and Mexico, with Chinese producers dominating standardized deck production and German fabricators specializing in aluminum-intensive configurations for weight-sensitive electric applications. Supply chains draw from Australian bauxite, Russian nickel, and Chilean lithium for battery-electric drivetrain integration. Single-source vulnerability in semiconductor-based telematics controllers threatens production continuity. Distribution runs through OEM direct sales for large fleet operators and specialized dealer networks serving owner-operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flatbed procurement sits in early-cycle expansion as renewable infrastructure deployment accelerates specialized heavy-haul demand beyond standard freight capacity. Infrastructure appropriations and zero-emission mandates compound fleet turnover requirements.
For Market Incumbents: Consolidate regional flatbed fleets through targeted acquisition of specialized heavy-haul operators with escort capabilities and dimensional permitting expertise. Deepen backward integration into aluminum platform fabrication to capture weight-reduction premiums for electric drivetrain compensation. Knight-Swift Transportation's terminal network density and PGT Trucking's steel-focused dedicated capacity illustrate defensible positions against digital freight matching disintermediation. For New Entrants and Emerging Players: Cross-border heavy-haul corridor fragmentation under USMCA implementation offers white-space entry points for owner-operators with specialized securement endorsements. Target the United States-Mexico steel and construction equipment lanes where legacy brokers maintain telephone-dependent dispatch inefficiencies. Deploy telematics-integrated asset-light brokerage models that aggregate spot capacity through app-based load discovery. For Investors and Strategic Acquirers: EPA Phase 3 finalization in 2027 reshapes the acquisition landscape toward electric platform readiness and CARB certification pipelines. Five-to-ten-year viability favors specialized heavy-haul carriers with renewable energy developer contracts over general freight exposure. Target acquisition archetypes: regional flatbed fleets with USMCA permitting capabilities and aluminum-intensive fabrication relationships. Monitor charging infrastructure buildout velocity along interstate corridors as inflection indicator for electric platform residual value realization.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Platform Pre-Ordering | Secures production slots ahead of EPA certification finalization for CARB compliance. |
| Aluminum Deck Specialization | Captures 15-20% pricing premiums for weight-sensitive electric drivetrain applications. |
| Cross-Border Permit Harmonization | Exploits USMCA standardization for oversized load corridors between United States, Mexico, Canada. |
| Telematics-Enabled Brokerage | Disintermediates legacy telephone dispatch through real-time load board visibility aggregation. |
| Renewable Energy Logistics Contracts | Locks dedicated capacity for wind turbine component transport under long-term offtake structures. |
Research Methodology
Initial hypotheses were tested against primary input from fleet procurement managers, heavy-haul operations directors, platform fabrication engineers, and renewable energy logistics coordinators and refined through secondary validation. Fleet operators, OEM sales executives, and aftermarket service providers contributed operational perspective on duty cycle economics and replacement timing. Secondary sources included EPA and CARB regulatory filings, FMCSA hours-of-service enforcement data, customs trade records for steel and aluminum inputs, and state-level dimensional permitting databases. Bottom-up fleet composition analysis triangulated against top-down infrastructure appropriation flow estimates.
Variance decomposition separated volume drivers from pricing dynamics across the projection horizon. Segmentation modeling incorporated vehicle type configuration, load capacity classification, fuel type transition pathways, and application-specific duty cycle severity. CAGRs were derived from fleet replacement cycle analysis and powertrain adoption curve interpolation. Key inputs included charging infrastructure deployment schedules, Federal Bridge Formula weight limit enforcement patterns, and renewable energy project development pipelines.
Forecasts assume regulatory continuity in EPA Phase 3 and CARB Advanced Clean Trucks regimes; material policy shifts would require re-modeling. Steel and aluminum price volatility, semiconductor availability constraints, and driver qualification scarcity constitute specific risk factors that could revise projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy-Duty Trucks
Truck Headache Rack Market
Heavy-Duty Trucks
Vacuum Truck Market
Heavy-Duty Trucks
US Tanker Truck Market
Heavy-Duty Trucks
Medium and Heavy Duty Commercial Vehicles (MHCV) Market
Heavy-Duty Trucks
Hydrogen Trucks Market
Heavy-Duty Trucks
Fire Trucks Market
Heavy-Duty Trucks
Truck Bedliner Market
Heavy-Duty Trucks
United States Refrigerated Trucking Market
Heavy-Duty Trucks
North America Heavy Commercial Vehicle (HCV) TMPS Market
Heavy-Duty Trucks
Tipper Truck Market
Heavy-Duty Trucks
Bucket Trucks Market
Heavy-Duty Trucks
Full Truckload Transportation Market
Heavy-Duty Trucks
Global Oversized Cargo Transportation Market
Heavy-Duty Trucks
Heavy-Duty Truck Load and Axle Weight Sensor Systems Market
Heavy-Duty Trucks
Global Connected Truck Market
Heavy-Duty Trucks
US Vacuum Truck Market