
 Hydrogen Trucks Market | 2026-2036
Hydrogen Trucks Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Trucks Market Foresight
The EU Green Deal's heavy-duty vehicle CO2 standards is expanding the addressable market for zero-emission commercial vehicles across European freight corridors. Hyundai Motor Company leverages its integrated fuel cell stack manufacturing to control supply chain costs for heavy-duty platforms. Daimler Truck AG anchors its European market position through the Mercedes-Benz GenH2 program targeting long-haul routes. AB Volvo competes with cellcentric, its joint venture dedicated to fuel cell powertrain industrialization.
Hydrogen trucks are heavy-duty commercial vehicles powered by proton exchange membrane fuel cells (PEMFC) or solid oxide systems that convert hydrogen gas into electricity for electric drivetrains, typically operating at 350-700 bar storage pressure for ranges exceeding 800 kilometers on a single fill. Heavy duty configurations dominate current OEM development pipelines due to the energy density advantage over batteries in weight-sensitive long-haul applications. Urban delivery segments show faster adoption velocity where depot-based refueling solves infrastructure constraints and daily route predictability reduces range anxiety. PEMFC technology leads commercial deployment while solid oxide systems attract R&D investment for higher efficiency at elevated operating temperatures.
The EPA's Clean Trucks Plan and NHTSA fuel efficiency standards are tightening compliance pathways for US freight operators, while China's MIIT dual carbon goals mandate new energy vehicle penetration in commercial fleets. Japan's METI hydrogen roadmap directs subsidy allocation toward heavy-duty transport corridor development. Stakeholders must monitor regulatory alignment between fuel certification standards and vehicle eligibility criteria as hydrogen sourcing rules determine market access across jurisdictions.
Market Dynamics
The hydrogen trucks market is experiencing structural pressure from the divergence between fleet operator decarbonization commitments and the capital intensity of hydrogen refueling infrastructure deployment. This tension concentrates risk along freight corridors where early station networks must achieve utilization thresholds before scaling.
Growth Catalysts
- EU Green Deal heavy-duty CO2 standards:The regulatory framework mandates progressive emissions reductions for freight operators, creating compliance-driven demand for zero-emission alternatives across European long-haul routes.
- Depot-based refueling infrastructure:Urban logistics hubs in California and Germany are installing captive hydrogen stations, eliminating range anxiety for predictable daily routes.
- Proton exchange membrane fuel cell cost curves:Manufacturing scale effects from adjacent passenger vehicle programs are compressing stack costs for heavy-duty applications.
Market Restraints
- Electrolyzer supply concentration:Proton exchange membrane electrolyzer manufacturing clusters in Germany and Japan, creating input bottlenecks for green hydrogen production.
- 350-700 bar storage certification timelines:Tank recertification protocols in the US and EU extend asset depreciation schedules beyond battery-electric alternatives.
- Battery-electric substitution in sub-500km routes:Lithium-ion energy density improvements are capturing medium-haul segments where hydrogen held early advantage.
Strategic Opportunities
- Japan METI hydrogen corridor subsidies:Dedicated funding for heavy-duty transport infrastructure along the Tokyo-Osaka freight axis reduces station deployment risk.
- Solid oxide fuel cell convergence with waste heat recovery:Higher operating temperatures enable auxiliary power applications that proton exchange membrane systems cannot serve.
- Third-party hydrogen supply contracting:Fleet operators are outsourcing fuel procurement to specialized traders, decoupling vehicle acquisition from infrastructure investment.
Industry Challenges
- High-pressure systems engineering talent scarcity:The intersection of cryogenic handling and electrical safety certification exceeds current vocational training pipeline output.
- Vehicle-to-station communication protocol fragmentation:Incompatible refueling interface standards between Japanese, European, and North American equipment complicates cross-border fleet operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Trucks Market |
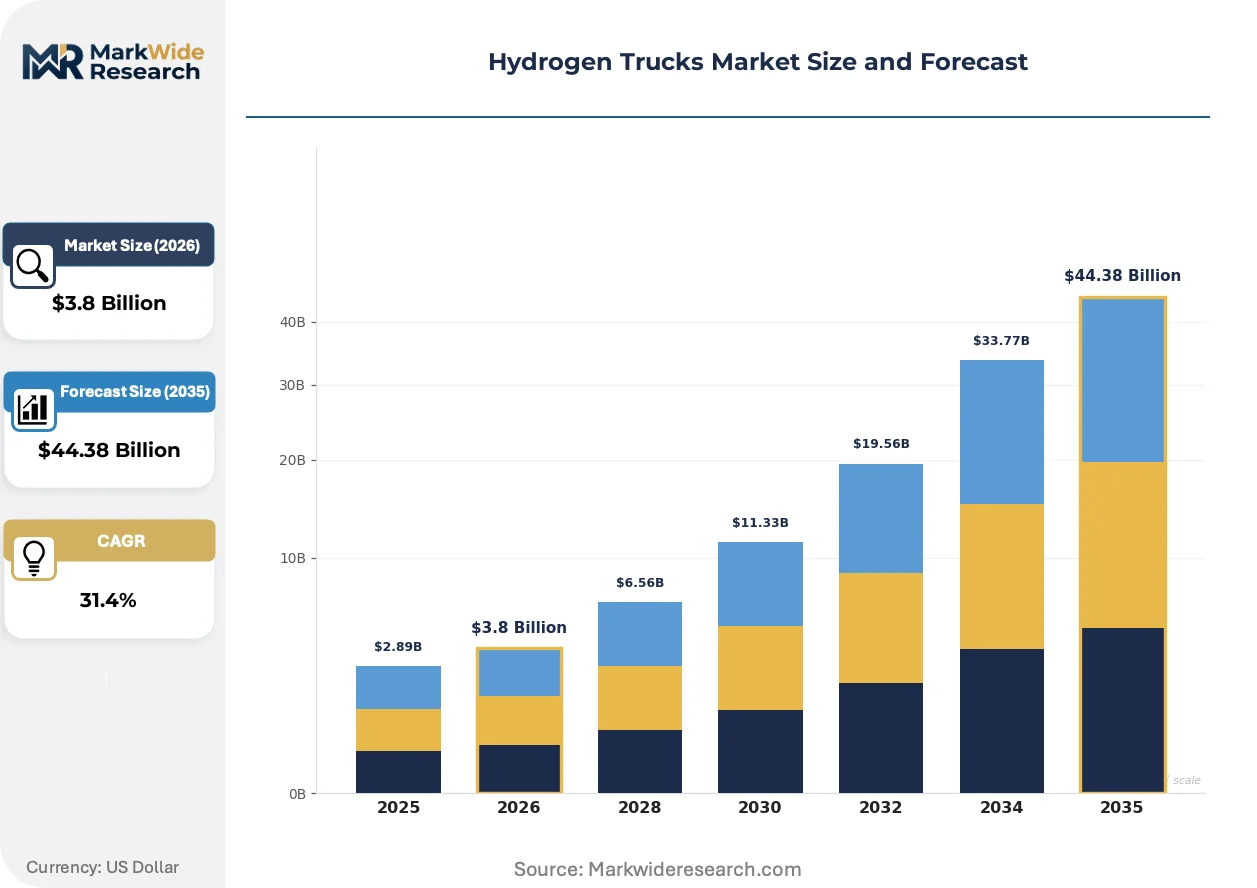
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $44.38 Billion |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Light Duty, Medium Duty, Heavy Duty, Specialty End User: Public Transportation, Freight Logistics, Construction, Military Fuel Cell Technology: PEMFC, AFC, Solid Oxide, DMFC Application: Urban Delivery, Long-Haul Transport, Waste Management, Mining |
| Companies Covered | Hyundai Motor Company, Nikola Corporation, Daimler Truck AG, Toyota Motor Corp., AB Volvo, Kenworth Truck Company, Hyzon Motors, Hino Motors, Iveco Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Trucks Market Shifts & Advancements
Technology convergence between fuel cell stacks and electric drivetrain architectures is compressing development cycles for heavy-duty platforms. Three distinct trajectories are reshaping competitive positioning across the value chain.
Proton exchange membrane fuel cell technology is integrating bipolar plate and membrane electrode assembly designs from passenger car programs into heavy-duty stacks. Freight operators in Germany are adopting these consolidated platforms for 40-tonne tractor configurations. The technology is integrating thermal management and power electronics into single-module architectures that reduce packaging volume by one-third.
The EPA Clean Trucks Plan is tightening NOx and greenhouse gas standards for Class 8 vehicles through 2027 model year compliance windows. US freight operators face accelerating fleet turnover requirements that hydrogen platforms must satisfy. Long-haul segments with duty cycles exceeding 12 hours daily are most affected, as battery-electric alternatives cannot meet range demands without payload-compromising battery mass.
Fleet procurement is consolidating around total cost of ownership models that internalize carbon pricing and residual value risk. Large logistics operators in California are displacing traditional diesel procurement committees with cross-functional teams integrating sustainability metrics. This behavioral shift is most visible among retail supply chain operators with Science Based Targets initiative commitments.
Hydrogen Trucks Market Segmentation
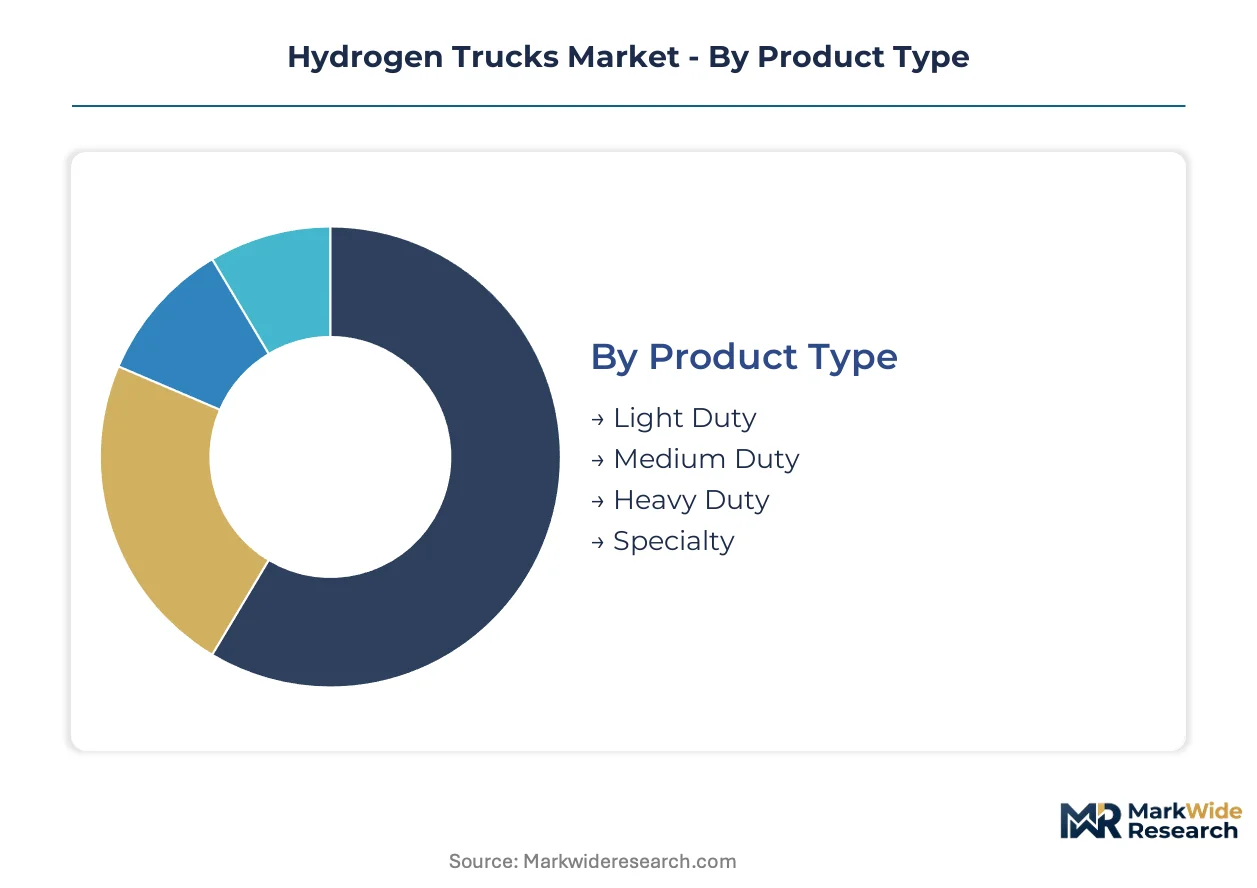
Segmentation in the hydrogen trucks market reveals how duty cycle requirements, infrastructure availability, and payload sensitivity create distinct competitive arenas. Fleet operators select platforms based on route predictability, refueling access, and total cost of ownership calculations that vary sharply across weight classes and operating environments.
Product Type:
Fleet procurement committees weight payload capacity against refueling infrastructure investment when selecting platform weight classes.
- Heavy Duty:Configurations exceed 40 tonnes gross vehicle weight with 700-bar hydrogen storage enabling 800-kilometer ranges. Demand concentrates along Germany's Rhine-Alpine freight corridor where depot-based refueling supports continuous long-haul operations.
- Medium Duty:Platforms span 12-26 tonnes with modular fuel cell stacks adapted from passenger vehicle programs. California's urban logistics hubs drive adoption where daily route predictability eliminates range anxiety and captive hydrogen stations reduce fuel procurement complexity.
- Light Duty:Last-mile delivery vans with reduced storage pressure requirements serve municipal procurement contracts in Japan's metropolitan prefectures.
- Specialty:Custom chassis configurations address airport ground support and port terminal tractor applications with specialized safety certification protocols.
Heavy Duty leads on scale; Medium Duty leads on momentum.
End User:
Operational intensity and carbon disclosure requirements determine which sectors absorb first-mover cost premiums.
- Freight Logistics:Third-party operators with Science Based Targets initiative commitments deploy hydrogen tractors on fixed long-haul lanes. European contract logistics providers anchor early fleet trials to satisfy EU Green Deal compliance timelines.
- Public Transportation:Municipal bus operators in California and Japan integrate hydrogen coaches where battery-electric charging infrastructure cannot support continuous service schedules.
- Construction:Heavy equipment rental fleets evaluate hydrogen dump trucks for urban low-emission zones with intermittent duty cycles.
- Military:Defense procurement programs in Germany and Japan fund tactical vehicle development for supply chain resilience in fuel-denied environments.
Freight Logistics commands capital deployment; Public Transportation expands most quickly through subsidy-dependent procurement.
Fuel Cell Technology:
Stack efficiency curves and thermal management complexity drive technology selection for specific operating temperature ranges.
- PEMFC:Proton exchange membrane systems dominate commercial deployment with cold-start capability below freezing and power density exceeding 2.5 kW/liter. Manufacturing scale effects from adjacent passenger programs compress stack costs for heavy-duty applications.
- Solid Oxide:Ceramic electrolyte systems operating at 600-800°C enable waste heat recovery for auxiliary power in stationary applications. Japan's METI research programs fund heavy-duty transport adaptation for combined heat and power configurations.
- AFC:Alkaline fuel cell architectures with liquid electrolyte circulation serve niche maritime and rail applications where weight constraints relax.
- DMFC:Direct methanol systems with liquid fuel storage attract military interest for supply chain simplification in forward deployment scenarios.
PEMFC leads on scale; Solid Oxide gains share fastest through efficiency advantages in combined-cycle configurations.
Application:
Route predictability and infrastructure control determine whether hydrogen platforms outcompete battery-electric alternatives.
- Long-Haul Transport:Continuous duty cycles exceeding 12 hours daily require energy density that lithium-ion cannot provide without payload-compromising battery mass. US freight operators facing EPA Clean Trucks Plan compliance anchor platform development.
- Urban Delivery:Predictable daily routes under 200 kilometers enable depot-based refueling with captive hydrogen production. German retail supply chains deploy medium-duty configurations for last-mile distribution.
- Waste Management:Refuse collection vehicles with stop-start duty cycles benefit from fuel cell durability under transient load conditions.
- Mining:Underground operations with ventilation constraints drive zero-emission mandates for haul trucks in selective extraction environments.
Long-Haul Transport anchors OEM platform investment; Urban Delivery climbs the fastest as infrastructure deployment concentrates around logistics hubs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's METI hydrogen roadmap established the foundational policy architecture for heavy-duty fuel cell transport, with Germany and California subsequently scaling demonstration corridors through public-private station networks.
United States
California's freight logistics operators anchor North American fleet trials along the I-5 corridor, where the EPA's Clean Trucks Plan tightens NOx standards through 2027. The state's Low Carbon Fuel Standard generates compliance credits that offset hydrogen procurement premiums for early adopters.
Germany
Rhine-Alpine corridor freight density drives heavy-duty platform demand, with the EU Green Deal's CO2 standards mandating progressive emissions reductions for long-haul operators. Bavaria's hydrogen refueling clusters around Munich and Nuremberg support continuous 40-tonne tractor operations.
Japan
Tokyo-Osaka freight axis concentration attracts METI subsidy allocation for heavy-duty transport infrastructure development. Chubu region manufacturing bases supply fuel cell stack components to domestic OEM platforms targeting 2025 commercialization timelines.
China
MIIT dual carbon goals mandate new energy vehicle penetration in commercial fleets across Yangtze River Delta logistics hubs. Sichuan-Chongqing corridor pilot programs test 700-bar storage configurations for mountainous long-haul routes.
South Korea
Ulsan petrochemical complex proximity enables blue hydrogen supply contracting for Busan port terminal tractor applications. Seoul Capital Area regulations accelerate zero-emission mandates for urban delivery segments with depot-based refueling.
Hydrogen Trucks Market Competitive Landscape
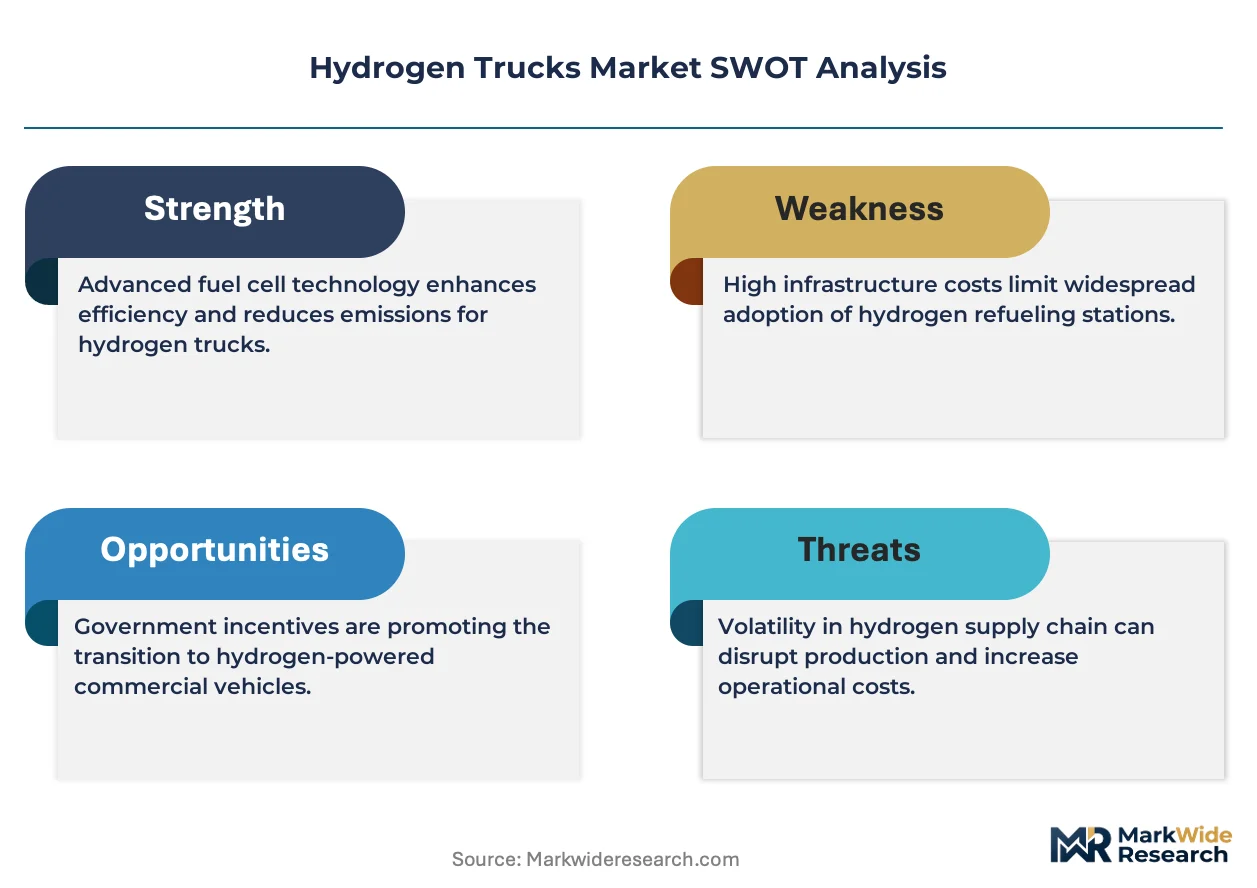
Premium-margin players sit above commodity-margin players across integrated fuel cell manufacturing depth, with stack in-house production separating cost-control leaders from assembly-dependent followers. The vendor base concentrates around three strategic archetypes: automotive OEMs with captive fuel cell divisions, dedicated hydrogen commercial vehicle specialists, and powertrain joint ventures pooling R&D expenditure. Dominant competitive moves include backward integration into membrane electrode assembly production and strategic partnerships for hydrogen supply contracting.
Within the automotive OEM tier, Hyundai Motor Company and Toyota Motor Corp. exemplify integrated manufacturing architectures, while Daimler Truck AG anchors European market positioning through captive platform development. AB Volvo occupies a joint-venture structure with cellcentric, representing an alternative model for fuel cell powertrain industrialization without full vertical integration.
| Leading Market Players |
|---|
| Hyundai Motor Company |
| Nikola Corporation |
| Daimler Truck AG |
| Toyota Motor Corp. |
| AB Volvo |
| Kenworth Truck Company |
| Hyzon Motors |
| Hino Motors |
| Iveco Group |
| Others |
Supply & Pricing Matrix
Captive fuel cell stack manufacturing anchors both supply security and pricing power for heavy-duty platform developers. Hyundai Motor Company and Toyota Motor Corp. leverage in-house proton exchange membrane production to compress stack costs below assembly-dependent competitors, while third-party procurement strategies expose fleet operators to electrolyzer supply bottlenecks concentrated in Germany and Japan.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates integrated OEM platforms from joint-venture assemblies and conversion retrofit kits. Price differentiation centers on membrane electrode assembly certification grade and after-sales service bundling. Cost compression in the standard tier is intensifying because manufacturing scale effects from passenger vehicle programs are compressing bipolar plate costs. Fleet operators with Science Based Targets initiative commitments show least price sensitivity; independent owner-operators exhibit highest procurement cost consciousness.
Supply Chain Analysis
Refurbishment flows for high-pressure tank recertification create reverse-logistics complexity that extends asset depreciation schedules beyond battery-electric alternatives. Manufacturing gravity draws from Germany for proton exchange membrane electrolyzers, South Korea for fuel cell stack components, and Japan for 700-bar storage systems. Raw material dependencies rest on platinum group metals for catalyst coatings, carbon fiber for tank winding, and specialized polymers for membrane substrates. Single-source vulnerability concentrates in membrane electrode assembly production. Distribution runs through captive depot networks and third-party hydrogen supply contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between California's Low Carbon Fuel Standard credit premiums and Germany's EU Green Deal compliance cost structures. The regulatory differential creates margin capture opportunities for fleet operators with cross-border logistics networks.
For Market Incumbents: Anticipate battery-electric substitution pressure in sub-500km urban delivery segments by accelerating heavy-duty platform differentiation through 800-kilometer range certification. Prioritize backward integration into membrane electrode assembly production to defend stack cost positions against emerging Asian suppliers. Monitor EPA Clean Trucks Plan timeline acceleration as a regulatory threat requiring accelerated fleet turnover partnerships.
For New Entrants and Emerging Players: Begin with medium-duty urban delivery configurations in California logistics hubs where depot-based refueling eliminates infrastructure investment barriers. Target municipal procurement contracts in Japan's metropolitan prefectures for light-duty van penetration. Pursue third-party hydrogen supply contracting as the go-to-market angle to decouple vehicle sales from fuel infrastructure capital deployment.
For Investors and Strategic Acquirers: Roll-up economics work for fuel cell powertrain specialists because manufacturing scale thresholds favor consolidated membrane electrode assembly production over fragmented component sourcing. The five-to-ten-year viability window hinges on green hydrogen cost curves achieving parity with diesel. Acquire targets with captive electrolyzer partnerships or in-house stack production. Watch Japan METI subsidy allocation velocity as the inflection signal for corridor infrastructure deployment momentum.
| Strategic Initiative | Industry Significance |
|---|---|
| Fuel Cell Stack Backward Integration | In-house membrane electrode assembly production compresses costs below joint-venture competitors. |
| Hydrogen Supply Contracting Partnership | Third-party fuel procurement decouples vehicle acquisition from infrastructure capital intensity. |
| Depot-Based Refueling Network Deployment | Captive station installation eliminates range anxiety for predictable urban delivery routes. |
| 700-Bar Storage Certification Investment | Higher pressure ratings enable 800-kilometer range differentiation against battery-electric alternatives. |
| Cross-Border Fleet Standardization Program | Unified vehicle-to-station protocols reduce operational friction for international logistics operators. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged fleet procurement directors at freight logistics operators, fuel cell platform engineers at OEM powertrain divisions, hydrogen infrastructure developers, and regulatory affairs specialists at METI and EPA. Secondary validation drew from vehicle production databases, hydrogen refueling station deployment registries, SEC filings from listed hydrogen vehicle specialists, and EU Green Deal implementation progress reports. Bottom-up fleet deployment tracking and top-down market sizing triangulated volume estimates.
Historical reference periods anchored the projection horizon to demonstrated fleet trial expansion rates and infrastructure buildout velocities across Germany, California, and Japan. The analytical framework modeled segmentation across vehicle weight class, fuel cell technology type, duty cycle application, and regional regulatory cluster. CAGRs derived from compounding annual fleet penetration assumptions tied to compliance deadline proximity. Industry-specific inputs included electrolyzer manufacturing capacity expansion schedules and heavy-duty CO2 standard phase-in timelines.
Several conditions sit outside the modeled scope, including breakthrough solid oxide fuel cell commercialization timelines, hydrogen sourcing rule amendments affecting vehicle eligibility, and geopolitical disruptions to platinum group metal supply chains. Forecasts reflect assumptions about infrastructure utilization thresholds achieving station network viability. Periodic stress-testing of base assumptions is recommended against METI subsidy allocation velocity and EPA rulemaking acceleration signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy-Duty Trucks
China Full-Truck-Load (FTL) Market
Heavy-Duty Trucks
Big Rig Trucks Market
Heavy-Duty Trucks
Truck Headache Rack Market
Heavy-Duty Trucks
Full Truck Load (FTL) Market
Heavy-Duty Trucks
Bucket Trucks Market
Heavy-Duty Trucks
Saudi Arabia Refrigerated Truck Market
Heavy-Duty Trucks
Middle East Refrigerated Truck Market
Heavy-Duty Trucks
Heavy-Truck Composite Component Market
Heavy-Duty Trucks
Heavy-Duty Truck Load and Axle Weight Sensor Systems Market
Heavy-Duty Trucks
US Vacuum Truck Market
Heavy-Duty Trucks
Global Connected Truck Market
Heavy-Duty Trucks
Global Oversized Cargo Transportation Market
Heavy-Duty Trucks
Malaysia Fire Truck Market
Heavy-Duty Trucks
Truck Bedliner Market
Heavy-Duty Trucks
Medium and Heavy Duty Commercial Vehicles (MHCV) Market
Heavy-Duty Trucks
Tipper Truck Market