
 Cargo Transportation Market | 2026-2036
Cargo Transportation Market Size, Share, and Industry Trends Forecast 2026-2036
Cargo Transportation Market Analysis
The EU Green Deal is repositioning cargo transportation demand toward lower-emission logistics networks across European trade corridors. FedEx Corporation leverages its integrated air-ground network to sustain express delivery dominance in North American lanes. Old Dominion Freight Line anchors its market position through dense less-than-truckload terminal networks that compete on transit-time reliability.
Cargo transportation encompasses the physical movement of goods via road, rail, air, and sea vessels operating at specified weight capacities, temperature controls, and routing protocols to fulfill supply chain requirements. Its primary purpose is bridging geographic separation between production centers and consumption endpoints through scheduled or on-demand freight services. Intermodal services are capturing expanding margin pools as shippers prioritize cost-efficient mode-switching across rail and road legs, while express delivery segments lead growth velocity fueled by e-commerce fulfillment expectations. Full truckload operations remain the mature revenue base for asset-heavy carriers, though less-than-truckload networks are narrowing the profitability gap through density optimization.
The International Maritime Organization's carbon intensity regulations and the EPA's heavy-duty vehicle emission standards are tightening compliance thresholds for fleet operators across ocean and road modes. The EU's Fit for 55 framework extends these pressures into European trucking and short-sea shipping, reshaping capital allocation toward alternative fuel vehicles and shore power infrastructure. Stakeholders must monitor regulatory phase-in timelines against fleet replacement cycles to avoid stranded asset risk and secure preferential port access.
Market Dynamics
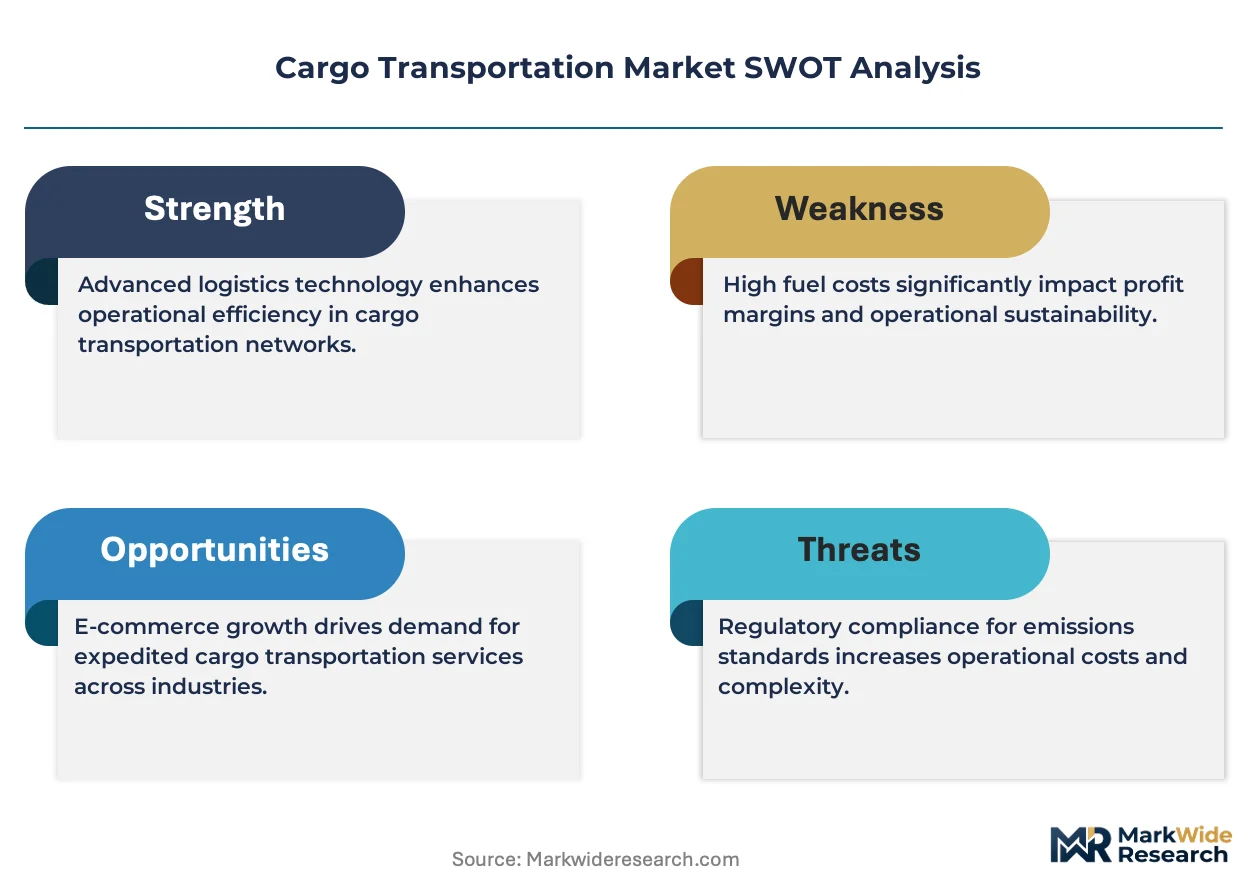
Fleet decarbonization mandates across the EU Green Deal, EPA heavy-duty standards, and IMO carbon intensity rules are compressing replacement cycles and redirecting capital toward alternative fuel infrastructure and shore power systems.
Growth Catalysts
- E-commerce fulfillment density:Parcel networks are expanding sortation capacity to match same-day delivery expectations in urban corridors. Last-mile node construction is accelerating across North American and European metropolitan zones.
- EU ETS maritime extension:The emissions trading scheme inclusion for shipping is forcing container lines to optimize slow-steaming routes and invest in methanol dual-fuel vessels.
- Battery-electric drivetrains:Cell chemistry improvements are extending electric truck range thresholds for regional haul applications. Fleet operators in California and the Netherlands are piloting depot-charging networks.
Market Restraints
- Charging infrastructure gaps:Highway electrification lags behind vehicle availability, stranding early adopters in long-haul corridors without guaranteed charging access.
- Shipyard capacity concentration:Container vessel construction is consolidating in South Korean and Chinese yards, creating orderbook bottlenecks for specialized low-emission designs.
- Green methanol feedstock scarcity:Biomethanol and e-methanol production remains insufficient to fuel committed dual-fuel fleet orders, forcing reliance on fossil-methanol blending.
Strategic Opportunities
- India port infrastructure:Sagarmala-linked container terminal expansion at Mundra and JNPT is creating demand for integrated logistics parks and cold-chain connectivity.
- Autonomous yard tractors:Convergence of LiDAR perception systems and 5G private networks is enabling driverless container handling at high-throughput terminals.
- EU Fit for 55 truck incentives:Member state purchase subsidies for zero-emission heavy-duty vehicles are opening fleet replacement windows ahead of 2035 ICE phase-out mandates.
Industry Challenges
- Technician training deficits:High-voltage battery maintenance and fuel-cell stack servicing require certifications that existing diesel mechanic workforces lack, slowing electric fleet deployment.
- Intermodal data fragmentation:Rail, road, and ocean carriers operate incompatible cargo visibility platforms, forcing shippers to maintain multiple tracking interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cargo Transportation Market |
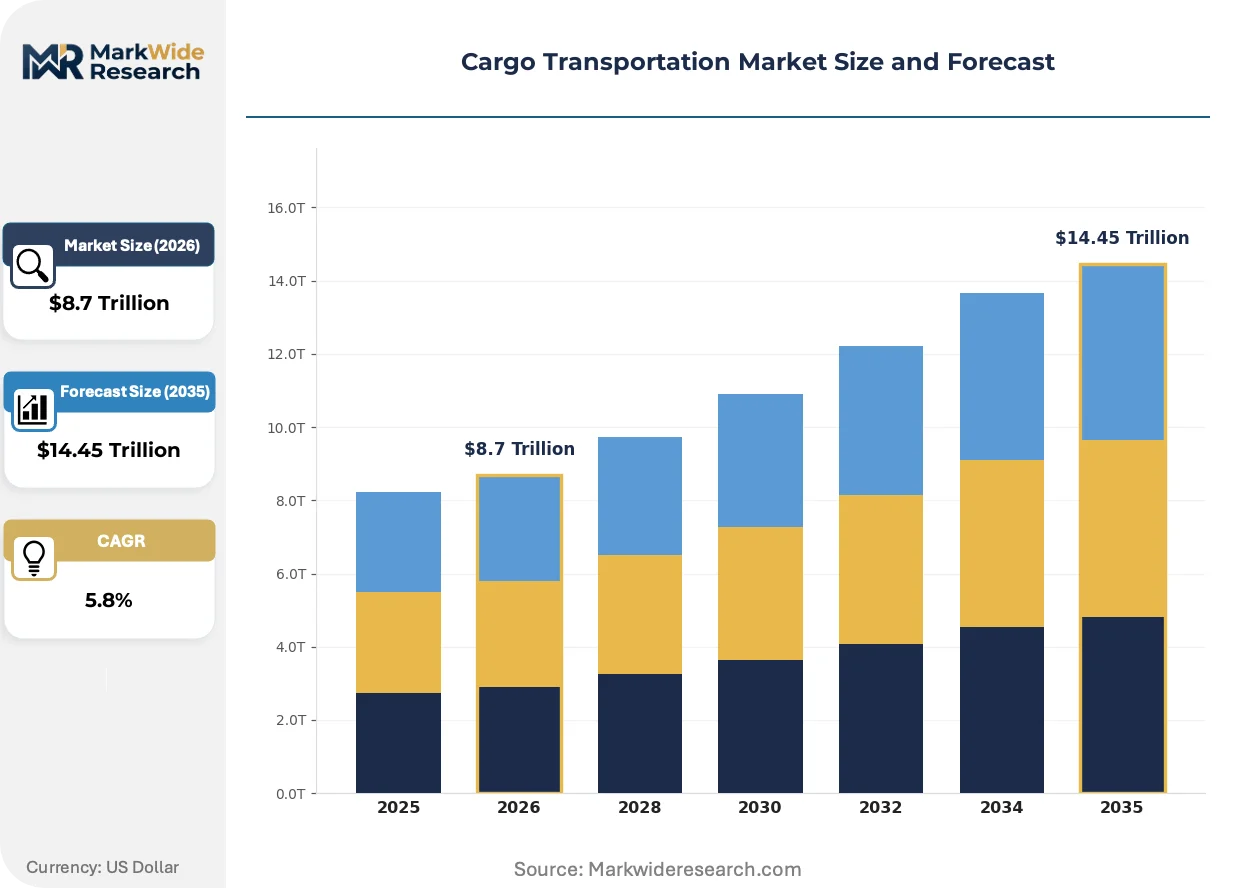
| Market Size in 2026 | $8.7 Trillion |
| Market Size in 2035 | $14.45 Trillion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Freight Forwarding, Intermodal, Third-Party Logistics, Express Delivery Transport Mode: Road, Rail, Air, Sea Load Type: Full Truckload, Less Than Truckload, Bulk Cargo, Breakbulk Industry Vertical: Retail, Manufacturing, E-Commerce, Pharmaceuticals |
| Companies Covered | Knight-Swift Transportation, XPO Logistics, FedEx Corporation, Saia Inc., Estes Express Lines, United Parcel Service, Old Dominion Freight Line, R+L Carriers, J.B. Hunt Transport Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cargo Transportation Market Emerging Trajectories
Digital freight matching platforms and predictive cargo routing algorithms are compressing procurement cycles and displacing traditional broker networks across fragmented trucking markets.
Platooning automation systems using vehicle-to-vehicle communication are reducing aerodynamic drag in convoy operations. Long-haul carriers in the US and Germany are testing two-truck formations on designated interstate corridors. This technology is electrifying interest in coordinated fleet scheduling to maximize fuel savings across paired tractor deployments.
The EPA's updated heavy-duty vehicle emission standards and the EU's CO2 performance standards for heavy-duty vehicles are tightening gram-per-ton-mile thresholds. Engine manufacturers are accelerating investments in hydrogen internal combustion and fuel-cell range extenders. European truck OEMs are responding with modular platform architectures that accommodate battery, fuel-cell, and combustion variants from shared chassis designs.
Shippers are consolidating procurement through contracted load boards and dynamic spot-market algorithms that bypass traditional freight broker intermediaries. Large retail and manufacturing accounts are building in-house transportation management systems with API connections to carrier dispatch platforms. This shift is most visible in the US and German markets where large shippers possess sufficient freight volume to justify direct carrier negotiations and technology investments.
Cargo Transportation Market Segmentation
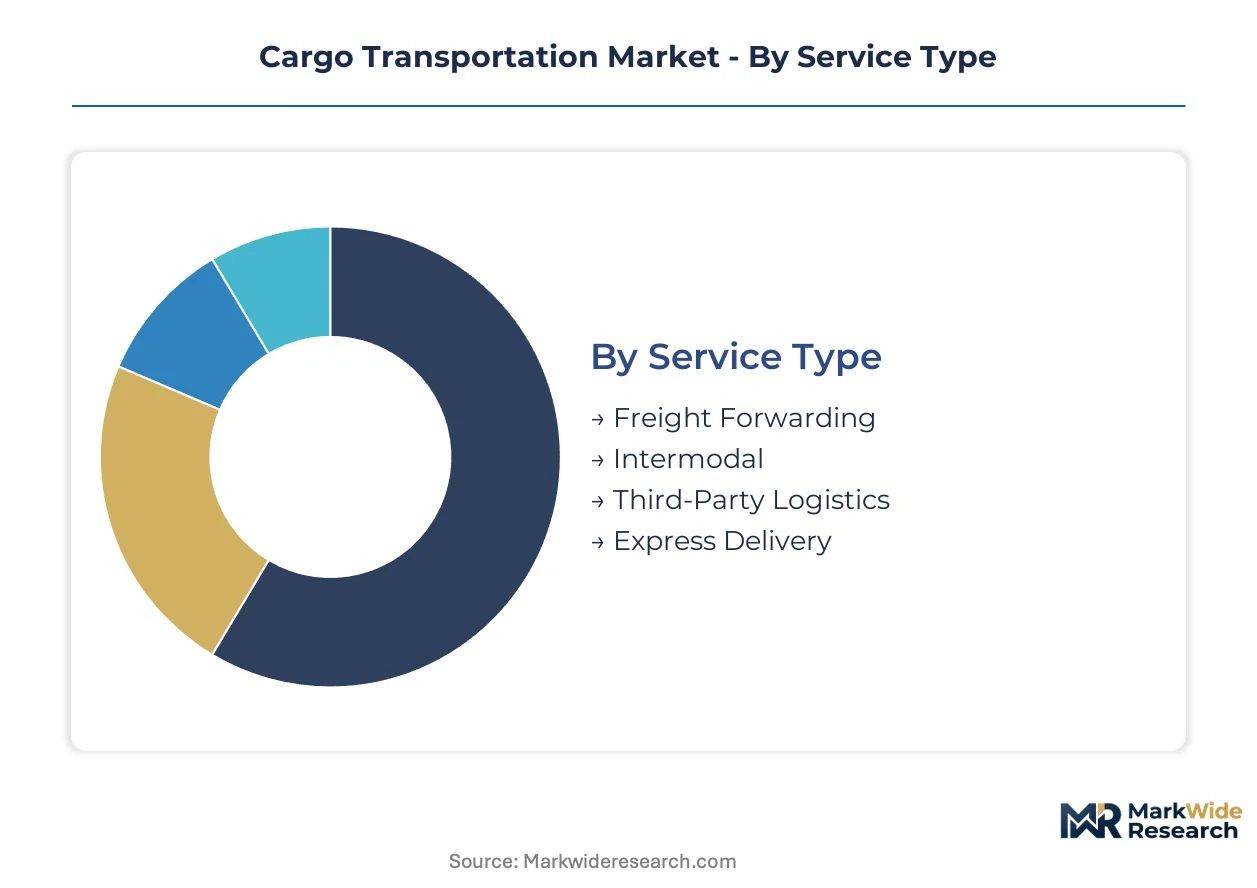
Cargo transportation segmentation reveals how regulatory compliance burdens concentrate across service tiers and transport modes. Shippers select segments based on cargo value density, temperature sensitivity, and delivery velocity requirements rather than cost alone.
Service Type:
Freight forwarding operations require customs brokerage licenses and IATA cargo agent accreditation. Third-party logistics providers face ISO 28000 supply chain security certifications. Express delivery networks must secure aviation authority approvals for air cargo screening. Intermodal operators navigate combined rail-road regulatory frameworks across multiple jurisdictions.
- Freight Forwarding:Non-asset-based coordinators managing documentation, customs clearance, and carrier procurement on behalf of shippers. Demand concentrates in China-originated manufacturing exports where NVOCC licensing and MIIT freight forwarding permits create operational barriers for new entrants.
- Intermodal:Integrated rail-road or sea-rail services optimizing cost over pure speed. European corridors between Rotterdam and Duisburg capture expanding volume as EU ETS maritime extension forces mode-switching away from short-sea shipping.
- Third-Party Logistics:Contracted warehousing, inventory management, and transport execution bundled under multi-year agreements. Retail replenishment networks in Germany and the Netherlands drive specification toward WMS-integrated visibility platforms.
- Express Delivery:Time-definite parcel services operating dedicated air networks and last-mile density. E-commerce fulfillment expectations in California and New York metropolitan zones are compressing delivery windows toward same-day thresholds.
Freight forwarding sits at the top of the volume ranking, with express delivery climbing the fastest.
Transport Mode:
Capital intensity and fuel infrastructure requirements stratify transport mode selection. Road transport demands lowest entry capital but faces tightening EPA and EU CO2 performance standards. Maritime operations require IMO-compliant vessel certifications and port state control inspections.
- Road:Flexible routing across distributed pickup and delivery points using diesel, battery-electric, or hydrogen drivetrains. California CARB Advanced Clean Trucks regulation and Netherlands zero-emission zone mandates are accelerating fleet replacement cycles.
- Rail:Scheduled block trains and single-car services operating on fixed infrastructure with lower per-ton-mile emissions. Bulk commodity flows between US Midwest agricultural zones and Pacific Northwest export terminals sustain core volume.
- Air:High-velocity cargo carriage in dedicated freighter and belly-hold configurations. Temperature-controlled pharmaceutical shipments from Swissmedic-regulated Swiss manufacturing sites drive premium yield segments.
- Sea:Container, bulk, and breakbulk vessel operations governed by SOLAS safety conventions and EU ETS carbon pricing. Methanol dual-fuel newbuilds at South Korean yards are capturing orderbook preference over conventional designs.
Road transport holds the largest volume position, while rail gains share fastest on corridor density improvements.
Load Type:
Asset utilization economics and handling equipment requirements differentiate load type profitability. Full truckload operations maximize vehicle productivity through direct point-to-point routing. Less-than-truckload networks depend on terminal density and line-haul consolidation efficiency.
- Full Truckload:Dedicated trailer capacity contracted for single-shipper movements without intermediate handling. US heartland manufacturing supply chains between Michigan automotive plants and Mexico assembly operations anchor contract volumes.
- Less Than Truckload:Multi-shipper consolidation through hub-and-spoke terminal networks with palletized sorting. Old Dominion Freight Line and comparable carriers compete on transit-time reliability in dense Northeast and Midwest corridors.
- Bulk Cargo:Unpacked commodities including grain, coal, and ore requiring specialized pneumatic or belt handling. Australian iron ore exports through Port Hedland and Brazilian soy shipments via Santos dominate seaborne tonnage.
- Breakbulk:Individual heavy or oversized items exceeding container dimensions, handled by specialized lifting equipment. German wind turbine component exports from Rostock and Bremerhaven require project cargo expertise and port heavy-lift capacity.
Full truckload dominates volume rankings, with less-than-truckload expanding most quickly on e-commerce parcel injection.
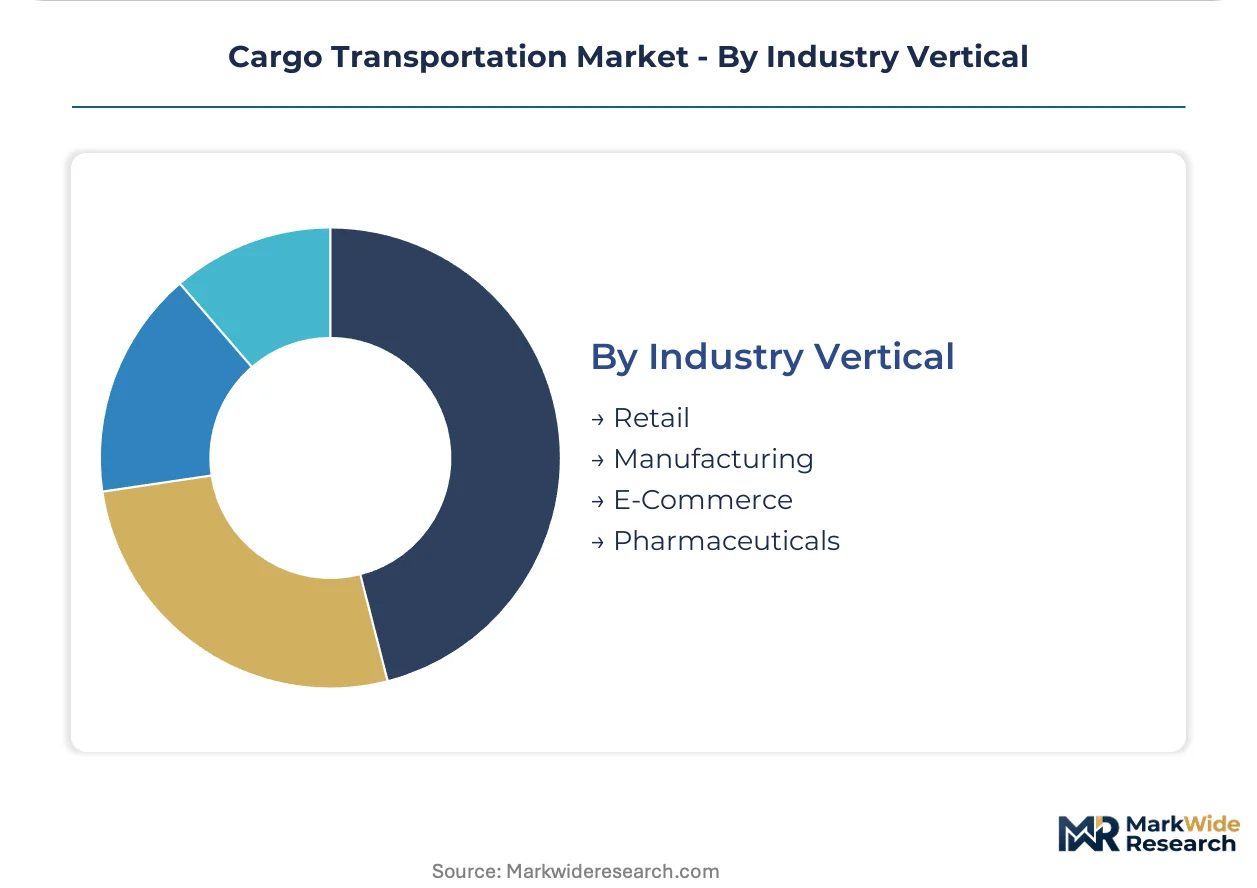
Industry Vertical:
Cargo handling protocols and liability frameworks vary sharply across vertical applications. Pharmaceutical shipments demand GDP-compliant temperature documentation. Retail networks prioritize velocity over absolute transport cost.
- Retail:Seasonal inventory replenishment and promotional event logistics requiring flexible capacity scaling. US big-box distribution centers in Pennsylvania and Ohio receive continuous container flows from Ningbo and Shanghai.
- Manufacturing:Just-in-time component delivery and finished goods distribution with penalty clauses for production line stoppages. German automotive supplier parks adjacent to Wolfsburg and Stuttgart assembly plants mandate precise sequencing.
- E-Commerce:Direct-to-consumer parcel flows with high return rates and last-mile complexity. Sortation hub construction accelerates across Paris, London, and Milan metropolitan zones to match delivery density requirements.
- Pharmaceuticals:Temperature-validated cold chain with serialization tracking and customs priority clearance. Indian CDSCO-regulated API exports and Belgian EMA-certified finished dose movements command premium rate structures.
Retail commands the highest volume position, with pharmaceuticals gaining share fastest on cold-chain infrastructure investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The modern cargo transportation industry traces its scaled origins to the United States, where the interstate highway system and deregulation under the Motor Carrier Act of 1980 established the template for integrated freight networks that now span multiple continents.
United States
E-commerce fulfillment density and automotive supply chain restructuring drive freight demand across the Midwest and Southeast corridors. EPA heavy-duty vehicle emission standards and California CARB Advanced Clean Trucks regulation are accelerating fleet electrification timelines. The Dallas-Fort Worth metroplex anchors expanding intermodal terminals connecting Mexican manufacturing zones to US distribution centers.
Germany
Automotive just-in-time component flows and pharmaceutical cold-chain exports sustain high-value cargo volumes through Rhine-Ruhr logistics clusters. The EU Fit for 55 framework and national zero-emission zone mandates in Hamburg and Berlin are redirecting capital toward hydrogen fuel-cell and battery-electric truck procurement. The Port of Rotterdam-Duisburg corridor captures expanding rail freight as EU ETS maritime extension forces mode-switching from short-sea shipping.
China
Domestic consumption growth and port infrastructure expansion at Ningbo-Zhoushan and Shanghai are reshaping Asia-Pacific trade lane configurations. MIIT freight forwarding permits and NVOCC licensing create operational barriers that protect incumbent logistics providers. The Yangtze River Delta manufacturing belt generates continuous container flows toward European and North American import gateways.
India
Sagarmala-linked container terminal expansion at Mundra and JNPT is creating demand for integrated logistics parks and cold-chain connectivity. CDSCO pharmaceutical export regulations and DGFT trade facilitation measures are streamlining customs processes for temperature-sensitive cargo. The Delhi-Mumbai Industrial Corridor anchors dedicated freight rail investments linking hinterland manufacturing to port access.
Netherlands
Rotterdam's status as Europe's largest seaport concentrates transshipment flows requiring multimodal distribution across the continent. National zero-emission zone mandates in Amsterdam and Rotterdam are accelerating electric truck deployment for last-mile operations. The Randstad logistics cluster integrates dense warehousing capacity with barge connections to German and Belgian industrial zones.
Cargo Transportation Market Vendor Landscape
Premium-margin players sit above commodity-margin players across service reliability and network density dimensions. The market structures around three tiers: integrated express carriers with dedicated air fleets, asset-heavy less-than-truckload networks competing on transit-time precision, and non-asset freight forwarders capturing margin through customs brokerage and carrier procurement. Strategic archetypes include integrated express operators, regional LTL specialists, and digital freight brokers. Capacity expansion and fleet decarbonization represent the dominant competitive moves across all tiers.
Within the integrated express tier, FedEx Corporation and United Parcel Service exemplify network-scale operators with dedicated aviation assets and last-mile density in North American metropolitan zones. Old Dominion Freight Line occupies a position among asset-heavy LTL specialists competing on transit-time reliability through dense terminal networks. These three companies represent divergent strategic archetypes: integrated air-ground express, premium LTL density play, and integrated parcel-express hybrid.
| Leading Market Players |
|---|
| Knight-Swift Transportation |
| XPO Logistics |
| FedEx Corporation |
| Saia Inc. |
| Estes Express Lines |
| United Parcel Service |
| Old Dominion Freight Line |
| R+L Carriers |
| J.B. Hunt Transport Services |
| Others |
Supply Flow & Price Mechanics
Large retail procurement consortia concentrated in the US Midwest and German Rhine-Ruhr corridors negotiate contract-based long-term offtake agreements that compress margins for asset-heavy carriers while rewarding density-optimized networks. This buyer concentration forces pricing stratification across premium express, standard intermodal, and economy full-truckload tiers.
Pricing Analysis
Contract-based long-term offtake agreements dominate high-volume lanes, with price differentiation hinging on transit-time reliability and EU ETS compliance certification. Volume scale and fuel surcharge pass-through mechanics separate premium express tiers from standard road freight. Cost compression in the full-truckload segment is intensifying as digital freight matching platforms displace traditional broker markups. Small and mid-sized shippers exhibit highest price sensitivity, while pharmaceutical and automotive verticals absorb premium rates for temperature-validated and just-in-time services.
Supply Chain Analysis
Regional distribution centers in the Netherlands Randstad and Dallas-Fort Worth metroplex anchor hub-and-spoke patterns feeding last-mile nodes across European and North American corridors. Manufacturing concentration in China's Yangtze River Delta, automotive assembly in Mexico, and pharmaceutical production in India and Switzerland creates multi-polar supply origins. Container chassis availability and specialized refrigerated equipment constitute critical input dependencies. Tariff exposure on China-originated electronics and machinery creates rerouting pressure through Southeast Asian transshipment hubs. Distribution runs through integrated logistics parks co-located with port terminals and intermodal ramps.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet decarbonization investments and e-commerce fulfillment density gains are compressing unit costs while opening premium-tier pricing for zero-emission certified services. Margin expansion rests on operational leverage from automated sortation and electric vehicle scale economics.
For Market Incumbents: Lock in terminal density advantages through targeted capacity additions in the US Southeast and Indian Delhi-Mumbai Industrial Corridor before EU Fit for 55 enforcement widens compliance gaps. Secure shore power infrastructure at Rotterdam and Long Beach to preempt port access restrictions for conventional vessels. Deepen backward integration into alternative fuel supply through biomethanol offtake agreements with Scandinavian producers. For New Entrants and Emerging Players: Autonomous yard tractor systems at high-throughput terminals offer a technology-first wedge into container handling operations currently dominated by unionized labor. Underpenetrated cold-chain connectivity between Indian pharmaceutical clusters and European distribution hubs presents addressable white space. Target Sagarmala-linked port modernization contracts with integrated logistics park development as the go-to-market angle. For Investors and Strategic Acquirers: Integrated express carriers with dedicated air fleets are the most active acquirer in this space, consolidating regional LTL specialists to capture e-commerce injection volume. Five-to-ten year viability favors asset-light freight forwarders with customs brokerage licensing moats in China and India. Monitor EU ETS maritime extension enforcement timelines as the inflection signal for methanol dual-fuel vessel orderbook acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Methanol Dual-Fuel Fleet Conversion | EU ETS maritime extension forces container lines toward IMO-compliant low-carbon propulsion at South Korean yards. |
| Automated Sortation Hub Expansion | Same-day delivery expectations in California and New York metropolitan zones demand parcel density investments. |
| Depot-Charging Network Pilot | California CARB Advanced Clean Trucks regulation accelerates electric truck deployment for regional haul applications. |
| Integrated Logistics Park Development | Sagarmala-linked terminal expansion at Mundra and JNPT creates demand for cold-chain connectivity infrastructure. |
| Digital Freight Matching Platform Launch | API-connected procurement systems displace traditional broker intermediaries in fragmented US and German trucking markets. |
Methodological Framework
Bottom-up e-commerce fulfillment and automotive supply chain modeling reconciled against top-down vessel orderbook and fleet replacement tracking forms the analytical core. Primary interviews with fleet operations directors, terminal managers, customs brokerage leads, and pharmaceutical logistics planners combined with secondary validation from IMO vessel registration databases, EPA emission certification filings, EU ETS transaction registries, and port authority throughput statistics. Triangulation across carrier dispatch platform data and shipper procurement system disclosures ensures coverage alignment.
Historical trendline analysis of freight rates, vessel charter indices, and trucking spot market volatility informs the projection framework. Segmentation dimensions span service type, transport mode, load configuration, and industry vertical with regional regulatory cluster overlays. CAGRs derive from capacity expansion schedules, fleet replacement cycles, and e-commerce penetration curves across the analysis window. Forecast inputs incorporate EU Green Deal phase-in timelines and battery-electric truck range threshold improvements.
The model holds under stable regulatory enforcement schedules and continued e-commerce growth; deviation in IMO carbon intensity rule acceleration or green methanol feedstock supply disruption would shift fleet investment patterns and carrier profitability trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
China Freight Forwarding Market
Logistics and Shipping
Europe Domestic Courier Market
Logistics and Shipping
Canada Project Logistics Market
Logistics and Shipping
Freight Forwarding Market
Logistics and Shipping
North America Freight Brokerage Market
Logistics and Shipping
Secure Logistics Market
Logistics and Shipping
California Freight and Logistics Market
Logistics and Shipping
Malaysia Freight and Logistics Market
Logistics and Shipping
Asia-Pacific Shipping Agency Services Market
Logistics and Shipping
US Air Freight Transport Market
Logistics and Shipping
Czech Republic Freight and Logistics Market
Logistics and Shipping
Empty Container Repositioning Optimization Platforms Market
Logistics and Shipping
Mexico Freight Forwarding Market
Logistics and Shipping
Thailand Courier Express Parcel (CEP) Market
Logistics and Shipping
Straddle Carrier Market
Logistics and Shipping
Italy Apparel Logistics Market