
 Articulated Dump Trucks Market | 2026-2036
Articulated Dump Trucks Market Size, Share, and Industry Trends Forecast 2026-2036
Articulated Dump Trucks Market Analysis
Swedish and German powertrain engineering is realigning articulated dump truck production toward electrified drivelines. Caterpillar leverages its global dealer network to sustain aftermarket parts revenue across mining corridors. Volvo Construction Equipment anchors European market presence through integrated autonomous haul solutions. Komatsu differentiates via its electric drive technology leadership in heavy earthmoving segments.
An articulated dump truck is a wheeled material-hauling vehicle with a pivot joint between its tractor and trailer units, typically rated for payloads exceeding 25 tonnes and engineered for off-road gradients exceeding 35 percent. Its primary purpose is to transport loose aggregates, overburden, or ore across unimproved terrain where rigid-frame trucks lack maneuverability. The 3-Axle and 4-Axle product types dominate volume production due to their balance between payload capacity and site accessibility, while 6-Axle configurations represent the fastest-growing category as open-pit operators seek single-trip efficiency gains. Application demand concentrates in Mining and Construction, with Waste Management emerging as a margin-rich segment where municipalities specify low-emission fleet replacements.
The EPA and NHTSA shape North American product standards through emissions and vehicle safety mandates, while the EU Green Deal and Stage V regulations from ECHA force powertrain redesigns across European supply chains. ISO 3450 braking performance standards and ISO 5010 stability testing protocols govern international market access for manufacturers exporting into regulated jurisdictions. Stakeholders must monitor battery-electric range validation under loaded cycle conditions and assess whether charging infrastructure at remote mine sites will constrain fleet conversion timelines.
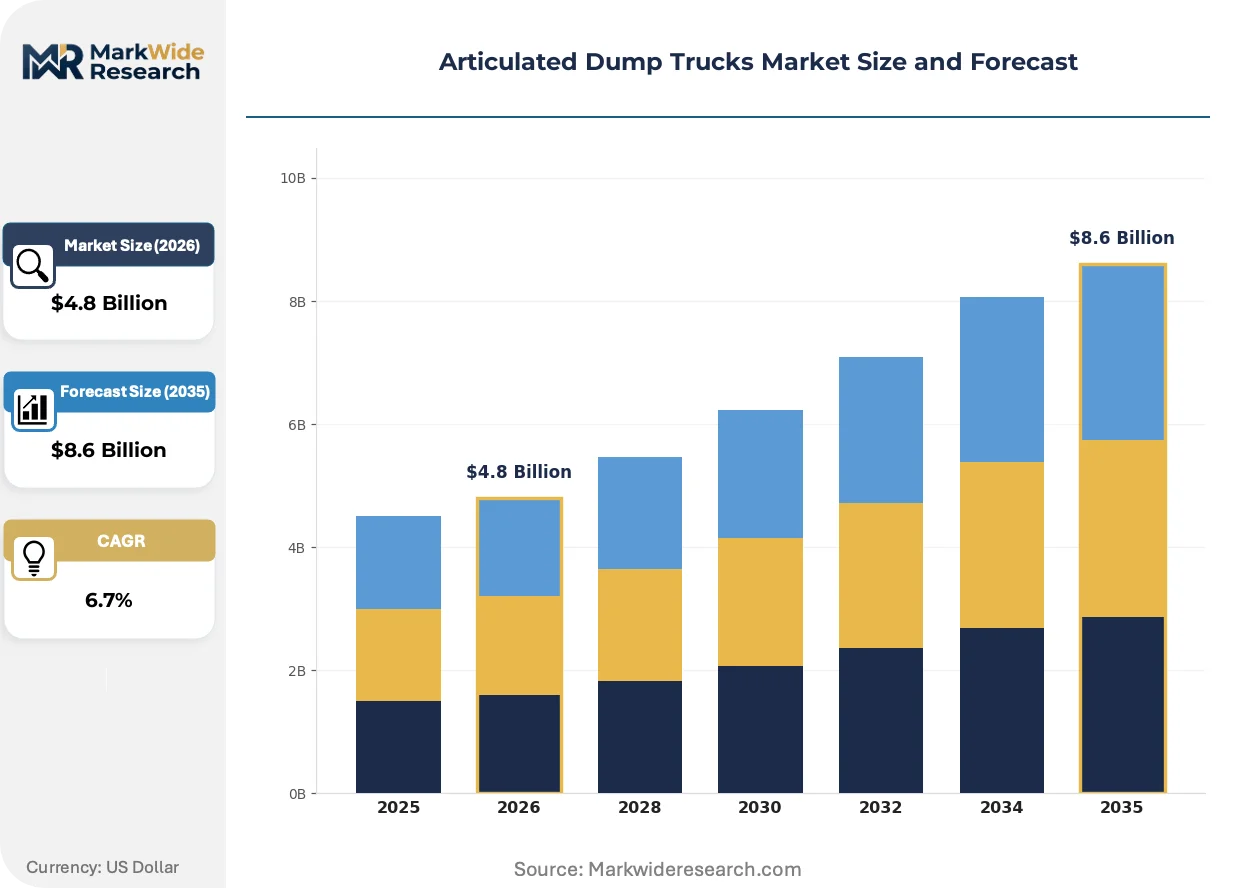
Market Dynamics
The transition toward hybrid-electric and battery-electric powertrains is compressing development cycles across articulated dump truck supply chains, forcing manufacturers to redesign thermal management systems and axle configurations simultaneously.
Growth Catalysts
- Stage V and Tier 4 Final emissions mandates:European and North American regulators are compelling fleet operators to retire legacy diesel units ahead of mechanical end-of-life, creating replacement demand for compliant haulers.
- Open-pit mining depth expansion:Copper and iron ore operations in Australia and Canada require 6-axle configurations to maintain productivity on steeper haul roads with tighter turning radii.
- Autonomous haulage integration:Mine operators are retrofitting articulated fleets with perception sensors and V2X communication modules to blend manned and unmanned operations within the same pit.
Market Restraints
- Battery cell supply concentration:Lithium-nickel-manganese-cobalt cathode production clusters in China create geopolitical exposure for European and North American OEMs scaling electric variants.
- Charging infrastructure capital intensity:Remote mine sites lack grid capacity for megawatt-scale fast charging, forcing operators to deploy mobile hydrogen fuel cells or diesel-battery hybrids as bridging solutions.
- Steel and alloy input volatility:High-strength boron steel plate prices fluctuate with energy costs, compressing margin visibility for manufacturers quoting multi-year fleet contracts.
Strategic Opportunities
- Waste management fleet electrification:Municipal contracts in Sweden and Germany now specify zero-emission waste transport, opening a margin-rich segment outside traditional mining customers.
- Telematics-enabled outcome pricing:OEMs are piloting availability-based contracts where customers pay per tonne-kilometer moved rather than unit acquisition, capturing aftermarket revenue streams.
- Battery swapping standardization:Interoperable swap station networks could eliminate range anxiety for electric articulated trucks operating on fixed haul circuits.
Industry Challenges
- Electrification skill scarcity:Field service technicians trained in high-voltage battery systems and inverter diagnostics remain scarce relative to internal combustion expertise.
- ISO 3450 braking recertification:Regenerative braking integration requires extensive validation of blended friction-electric stopping distances under loaded downhill conditions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Articulated Dump Trucks Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2-Axle, 3-Axle, 4-Axle, 6-Axle Application: Construction, Mining, Agriculture, Waste Management Size: Medium, Large, Extra Large, Compact End User: Contractors, Mining Companies, Municipalities, Fleet Operators |
| Companies Covered | Caterpillar, Volvo Construction Equipment, Komatsu, John Deere, Bell Equipment, Liebherr, Hitachi Construction Machinery, DEVELON, Hydrema, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Articulated Dump Trucks Market Emerging Trajectories
Powertrain electrification is converging with autonomous control architectures to redefine articulated dump truck value propositions, while regulatory pressure accelerates the obsolescence of mechanical-only drivetrains.
Autonomous haulage software is automating operator decision-making in repetitive load-haul-dump cycles. Iron ore and copper producers in Western Australia are deploying retrofit kits on existing 40-tonne-class fleets before committing to greenfield all-electric purchases. This technology is automating the transition pathway from manned diesel operations to fully autonomous electric fleets without requiring simultaneous capital outlays.
The EU Green Deal's carbon border adjustment mechanism is tightening embodied emissions accounting for imported mining equipment. Manufacturers sourcing steel and battery cells from coal-intensive production regions face competitive disadvantage in European public procurement tenders. Nordic contractors are responding by mandating supplier declarations covering Scope 3 emissions from raw material extraction through final assembly.
Long-term rental and managed fleet services are displacing outright equipment purchases among mid-tier construction contractors. Equipment lessors in Germany and France now bundle telematics, preventive maintenance, and emissions compliance verification into single monthly rates. This shift is most pronounced in urban infrastructure projects where municipal clients require documented sustainability performance across subcontractor supply chains.
Articulated Dump Trucks Market Segmentation
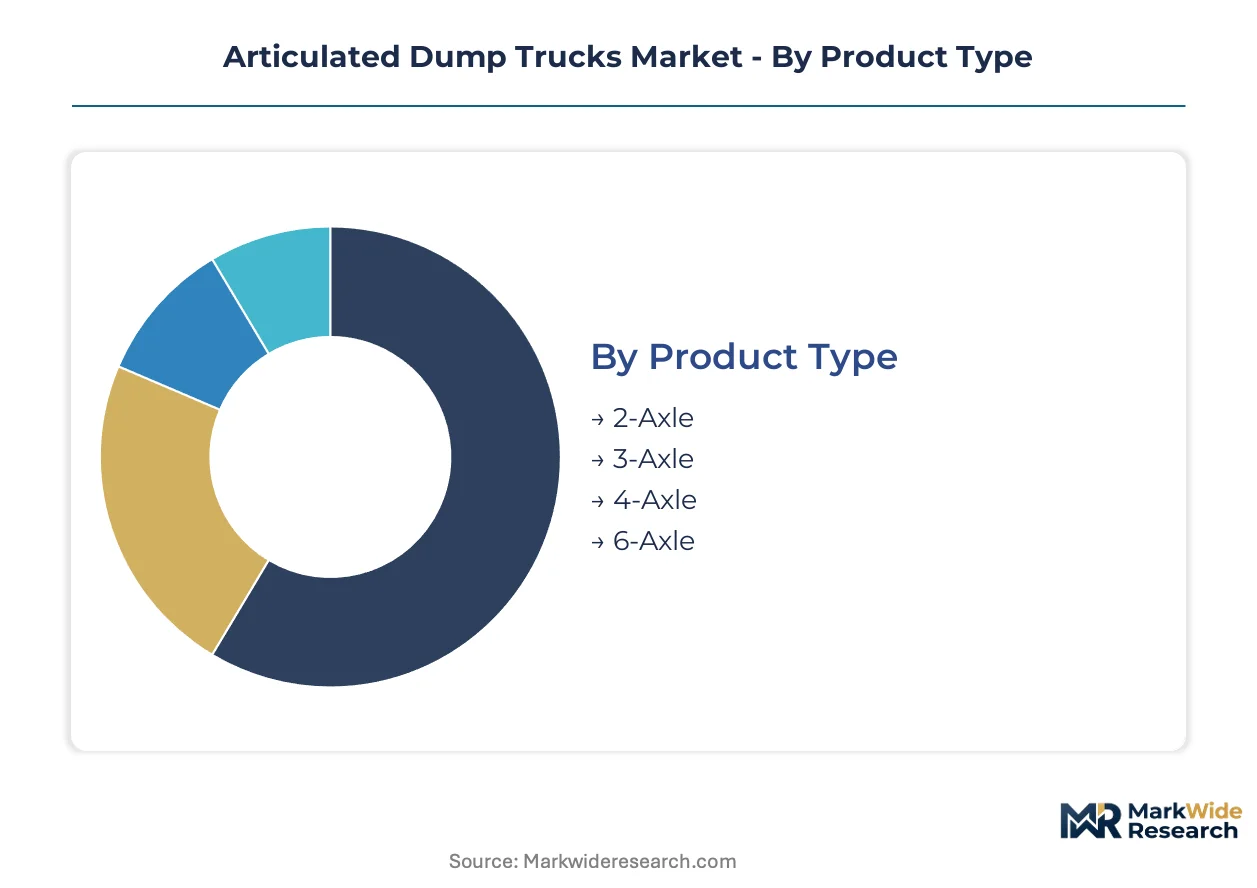
Articulated dump truck purchasing decisions pivot on axle configuration, payload requirements, and site-specific terrain constraints. Fleet operators segment procurement across duty cycles, emissions zones, and ownership models to optimize total cost of ownership across multi-year contracts.
Product Type:
Volume production concentrates in mid-range axle configurations where payload flexibility meets dealer availability, while premium engineering resources flow toward extended configurations for deep-pit mining.
- 3-Axle:Rated for 25-35 tonne payloads with oscillating hitch articulation optimized for quarry haul roads and urban infrastructure sites. Australian and Canadian contractors specify this configuration for its balance between maneuverability on tight turns and sufficient capacity for aggregate transport. Demand concentrates in medium-scale construction contracts where site access limits larger units.
- 4-Axle:Carries 35-50 tonnes through reinforced frame rails and dual-axle rear bogies engineered for 40 percent gradients. Iron ore producers in Western Australia deploy 4-axle fleets on mid-depth open pits where haul distances justify larger single-trip loads without requiring 6-axle infrastructure investments. This configuration anchors replacement cycles for Tier 4 Final compliance in North American mining corridors.
- 2-Axle:Compact units rated below 25 tonnes serve confined construction sites and tunneling projects where turning radius constraints dominate payload priorities.
- 6-Axle:Extra-large haulers exceeding 50 tonnes target deep-pit copper operations in Chile and Kazakhstan where single-trip efficiency offsets higher capital costs.
Mature deployment sits with 3-Axle and 4-Axle configurations across established mining districts. Newer deployment is concentrated in 6-Axle units as open-pit depth expansion accelerates in high-altitude South American and Central Asian corridors.
Application:
Margin profiles diverge sharply between commodity-driven mining procurement and municipal waste contracts where emissions specifications command price premiums.
- Mining:Copper, iron ore, and gold operations drive demand for 40+ tonne payloads across unimproved haul roads exceeding 15 kilometers. Autonomous retrofit compatibility now filters equipment selection in Western Australia and northern Canada where blended manned-unmanned fleets operate. Fleet standardization around single OEM platforms reduces parts inventory complexity at remote sites.
- Construction:Highway, dam, and tunnel contractors prioritize rapid cycle times and dealer service density over maximum payload. Nordic infrastructure projects increasingly specify Stage V compliance for urban proximity work.
- Agriculture:Sugar cane and aggregate transport in Brazil and Southeast Asia utilizes medium-duty units on seasonal harvest cycles.
- Waste Management:Municipal contracts in Sweden and Germany mandate zero-emission fleet replacements, opening premium pricing for battery-electric variants with dedicated charging infrastructure.
Volume concentration remains in Mining. Steepest expansion trajectory is emerging in Waste Management as EU Green Deal procurement rules tighten across German and Swedish municipal tendering.
Size:
Physical envelope constraints determine site eligibility more than payload optimization in urban and tunneling applications.
- Large:35-50 tonne rated capacity dominates open-pit production economics where fuel efficiency per tonne-kilometer determines fleet selection criteria.
- Extra Large:Exceeding 50 tonnes, these units require dedicated haul road width and gradient engineering. Kazakh and Chilean copper operators specify extra-large configurations for vertical pit depth beyond 400 meters.
- Medium:20-35 tonne range serves quarry and construction markets where road weight limits and bridge ratings constrain equipment selection.
- Compact:Sub-20 tonne units access tunneling, landfill compaction, and confined urban demolition sites where turning radius below 8 meters is mandatory.
Revenue concentration sits with Large and Extra Large units in mining procurement. Emerging deployment is accelerating in Compact configurations as urban tunneling projects expand in Switzerland and Austria.
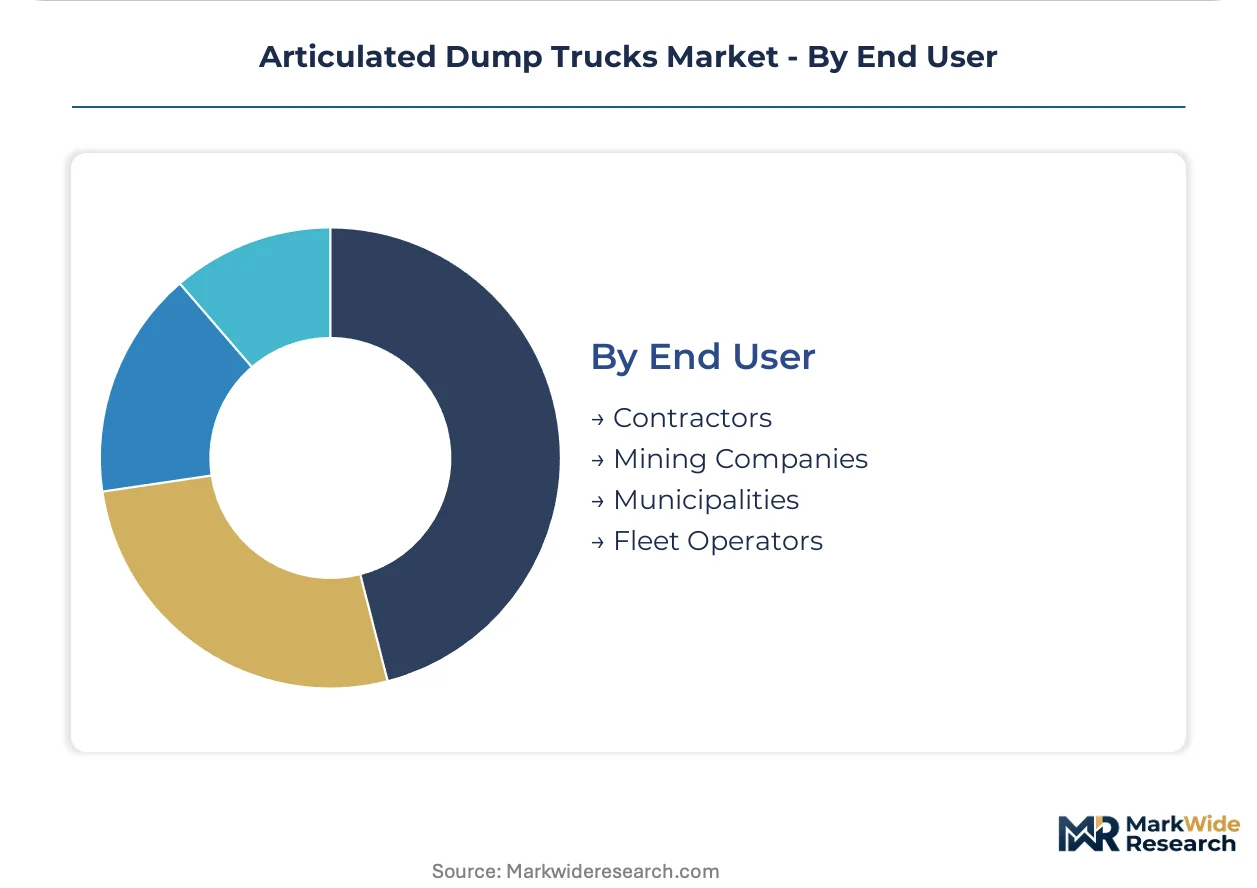
End User:
Ownership models are bifurcating between capital-rich mining majors and service-oriented contractors seeking operational leasing.
- Mining Companies:BHP, Rio Tinto, and Vale standardize fleet specifications across continental operations to maximize parts commonality and technician training efficiency. These operators pilot autonomous haulage retrofits before greenfield electric fleet commitments.
- Contractors:Mid-tier construction firms in France and Germany increasingly favor long-term rental bundles incorporating telematics, preventive maintenance, and emissions compliance verification.
- Fleet Operators:Equipment lessors aggregate demand across multiple contractor clients, requiring flexible specification ranges to maintain utilization rates.
- Municipalities:Swedish and German waste authorities specify zero-emission mandates with documented Scope 3 emissions across supplier chains.
Established purchasing power sits with Mining Companies. Shifting procurement patterns are concentrating in Contractors as outcome-based availability contracts displace outright acquisition in European urban infrastructure markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Iron ore deposits in Western Australia's Pilbara region anchor articulated dump truck procurement volumes, with copper belts in Chile and Kazakhstan driving demand for extra-large haul configurations. Fleet operators in these mining corridors prioritize single-trip efficiency over capital cost minimization.
Australia
BHP and Rio Tinto operate blended manned-autonomous fleets across Pilbara iron ore corridors, retrofitting existing 40-tonne-class trucks with perception sensors before greenfield electric commitments. The country's national mining safety regulator mandates ISO 3450 braking validation for all autonomous retrofits. Perth anchors aftermarket parts distribution networks serving remote Queensland and Western Australian mine sites.
Chile
Codelco and Anglo American specify 6-axle configurations exceeding 50 tonnes for copper operations below 400-meter vertical pit depths where haul road gradients exceed 35 percent. Chile's environmental assessment service enforces emissions compliance for fleet renewals in the Atacama Desert mining district. Antofagasta concentrates service technician training facilities supporting cross-border operations into Peruvian copper belts.
Canada
Teck Resources and Canadian Natural Resources expand fleet orders for Tier 4 Final compliant haulers across Alberta oil sands and northern Saskatchewan uranium corridors. Environment and Climate Change Canada enforces federal emissions standards aligning with EPA mandates for cross-border equipment interoperability. Edmonton hosts regional dealer technical centers stocking high-availability components for remote Arctic mine access roads.
Sweden
Kommuninvest-financed municipal waste contracts in Stockholm and Gothenburg mandate zero-emission fleet replacements with documented Scope 3 emissions across supplier chains. The Swedish Environmental Protection Agency enforces Stage V compliance for urban construction equipment operating within low-emission zones. Eskilstuna anchors Volvo Construction Equipment's integrated autonomous haul solution development for Nordic infrastructure projects.
Germany
Mid-tier construction contractors in Bavaria and North Rhine-Westphalia favor long-term rental bundles incorporating telematics, preventive maintenance, and emissions verification for urban infrastructure tenders. The Federal Motor Transport Authority enforces KBA certification for braking system modifications on electrified retrofits. Munich concentrates equipment lessor headquarters bundling outcome-based availability contracts displacing outright acquisition.
Articulated Dump Trucks Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue electrification specialization and autonomous retrofit compatibility. The supplier base concentrates around full-line construction equipment manufacturers with integrated dealer networks and regional service density. Three archetypes dominate: diversified heavy equipment conglomerates with mining-optimized portfolios, specialized articulated hauler manufacturers with Nordic engineering heritage, and industrial technology providers leveraging electric drive expertise from adjacent heavy machinery segments. Competitive dynamics center on strategic partnerships for battery cell supply security and geographic expansion through dealer network acquisition.
Within the diversified conglomerate tier, Caterpillar and Komatsu exemplify scale-driven positioning through global aftermarket parts revenue capture across mining corridors. Volvo Construction Equipment represents integrated solution architecture combining autonomous software stacks with electrified powertrain development. Among specialized regional fabricators, Hydrema anchors Nordic supply chain presence through municipal waste fleet electrification contracts in Denmark and Sweden.
| Leading Market Players |
|---|
| Caterpillar |
| Volvo Construction Equipment |
| Komatsu |
| John Deere |
| Bell Equipment |
| Liebherr |
| Hitachi Construction Machinery |
| DEVELON |
| Hydrema |
| Others |
Supply Flow & Price Mechanics
High-strength boron steel plate flows from German and Swedish mills through tiered fabrication stages, accumulating cost premiums at each ISO 3450 braking certification checkpoint before reaching fleet operators in Western Australia and Chile.
Pricing Analysis
Warranty bundling separates premium tiers from standard procurement. Extended powertrain coverage and telematics-enabled predictive maintenance anchor three-tier pricing structure across premium, standard, and economy levels. Stage V certification drives price differentiation between European-compliant and legacy diesel units. Cost compression in standard tiers is intensifying because Chinese battery cell supply concentration forces OEMs to absorb margin pressure. Mid-tier contractors exhibit highest price sensitivity; mining majors prioritize availability guarantees over unit cost.
Supply Chain Analysis
ISO 3450 braking validation gates market access for axle and driveline suppliers. High-strength steel production centers on Germany, Sweden, and Japan. Battery cell supply draws from South Korean and Chinese cathode processing. Single-source vulnerability in lithium-nickel-manganese-cobalt chemistry creates geopolitical exposure. Distribution runs through Caterpillar and Volvo Construction Equipment dealer networks serving remote mining corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
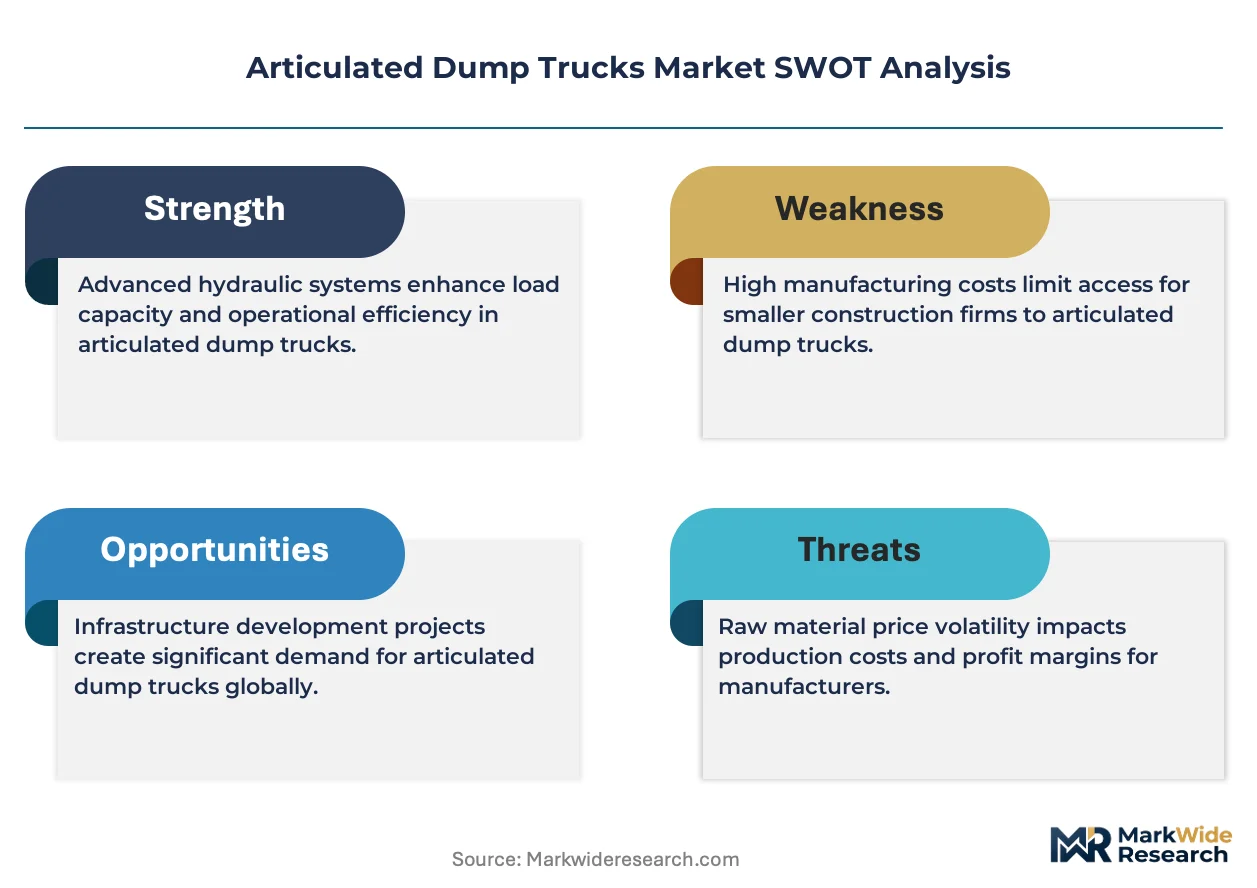
The articulated dump truck sector is becoming a vertical-integration race as manufacturers pursue captive battery cell supply to secure electric variant scaling.
For Market Incumbents: Lock in long-term offtake agreements with South Korean battery producers before cathode supply tightens. Acquire Nordic municipal waste fleet operators to anchor zero-emission reference installations. Defend against autonomous retrofit specialists by integrating perception software stacks in-house. For New Entrants and Emerging Players: Capture waste management electrification contracts in Stockholm and Gothenburg where Stage V mandates outpace incumbent response capacity. Target German equipment lessors seeking white-label electric variants for urban infrastructure bundles. Lead with battery swapping compatibility as the primary go-to-market wedge. For Investors and Strategic Acquirers: Kommuninvest-financed municipal zero-emission mandates accelerating is the leading indicator that waste management fleet conversion timelines will compress. Five-to-ten-year viability hinges on charging infrastructure deployment at remote mine sites. Pursue mid-cap axle fabricators with ISO 3450 certification infrastructure. Watch for BHP or Rio Tinto greenfield electric fleet commitments as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures lithium-nickel-manganese-cobalt cathode flow from South Korean producers for electric variant scaling. |
| Autonomous Retrofit Partnership | Integrates perception sensors and V2X modules into existing 40-tonne-class fleets for blended operations. |
| Charging Infrastructure Joint Venture | Deploys megawatt-scale fast charging or mobile hydrogen fuel cells at remote Chilean and Kazakh mine sites. |
| ISO 3450 Recertification Investment | Validates regenerative braking performance under loaded downhill conditions for European market access. |
| Municipal Fleet Acquisition | Captures Stockholm and Gothenburg zero-emission waste contracts with documented Scope 3 compliance. |
Methodological Framework
Document review covered SEC 10-K filings from construction equipment manufacturers, EU Green Deal procurement databases, and mining fleet operator sustainability reports, complemented by interviews with maintenance directors at Western Australian iron ore operations, OEM procurement teams in Germany and Sweden, aftermarket service heads serving Chilean copper belts, and municipal waste fleet managers in Nordic cities.
Historical production volumes from vehicle registration databases were cross-referenced against panel input from platform engineers and dealer operations heads. The analytical framework models axle configuration, application segment, emissions compliance tier, and ownership model across the projection horizon. CAGRs were derived from bottom-up fleet replacement cycle analysis and top-down mining capital expenditure trajectories. Forecast inputs include copper price corridors and Stage V enforcement timelines.
The model holds under stable battery cell supply and emissions enforcement schedules; deviation in lithium raw material export restrictions or autonomous haulage adoption curves would shift replacement demand timing. A model refresh is warranted upon material change in EU carbon border adjustment mechanism implementation scope.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy-Duty Trucks
Dump Truck & Body Market
Heavy-Duty Trucks
Global Connected Truck Market
Heavy-Duty Trucks
Big Rig Trucks Market
Heavy-Duty Trucks
Truck Bedliner Market
Heavy-Duty Trucks
Global Snow Sweeper Truck Market
Heavy-Duty Trucks
Asia Pacific Garbage Truck Bodies Market
Heavy-Duty Trucks
Dump Trucks Market
Heavy-Duty Trucks
Europe Medium & Heavy-Duty Truck Rental Market
Heavy-Duty Trucks
North America Vacuum Truck Market
Heavy-Duty Trucks
Heavy-Duty Truck Dashboard Switch Panel Systems Market
Heavy-Duty Trucks
Garbage Truck Bodies Market
Heavy-Duty Trucks
US Tanker Truck Market
Heavy-Duty Trucks
Heavy-Duty Truck Load and Axle Weight Sensor Systems Market
Heavy-Duty Trucks
Vacuum Truck Market
Heavy-Duty Trucks
North America Heavy Commercial Vehicle (HCV) TMPS Market
Heavy-Duty Trucks
United States Refrigerated Trucking Market