
 Saudi Arabia Refrigerated Truck Market | 2026-2036
Saudi Arabia Refrigerated Truck Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Refrigerated Truck Market Insights
Cold-chain logistics networks in Saudi Arabia is fragmenting as pharmaceutical distributors and food retailers build dedicated fleets rather than relying on third-party haulers. Carrier Transicold leverages its Gulf service infrastructure to sustain aftermarket parts availability across the kingdom. Thermo King competes through telematics-integrated refrigeration units that anchor fleet visibility for pharmaceutical clients. Naqel Express dominates last-mile cold delivery from Riyadh's King Khalid International Airport free zone.
A refrigerated truck is a temperature-controlled commercial vehicle employing vapor-compression refrigeration with insulated composite panels maintaining cargo compartments between minus 25 degrees Celsius and plus 20 degrees Celsius for perishable goods transport. The primary purpose is preserving pharmaceutical efficacy and food safety across Saudi Arabia's arid climate where ambient temperatures exceed 45 degrees Celsius seasonally. Van configurations lead in urban pharmaceutical distribution where maneuverability through Riyadh's dense commercial zones commands premium positioning. Trailer segments sustain margin pools on long-haul routes connecting Jeddah Islamic Port to inland logistics hubs. Electric fuel type variants are gaining fastest among municipal food delivery fleets as Saudi Energy Efficiency Center standards tighten diesel emissions thresholds.
SFDA mandates GDP-compliant cold-chain documentation for all pharmaceutical transport vehicles operating within Saudi Arabia. SASO energy efficiency labeling requirements for transport refrigeration equipment are reshaping procurement specifications toward lower-carbon compressor technologies. The General Authority of Ports regulates reefer container handling standards at Jeddah and Dammam terminals. Stakeholders must monitor how Saudi Vision 2030 logistics privatization timelines reshape fleet ownership models between state enterprises and private operators.
Market Dynamics
SFDA enforcement of GDP-compliant cold-chain documentation is fragmenting fleet ownership models as pharmaceutical distributors abandon third-party haulers for captive refrigerated truck operations.
Growth Catalysts
- Biologics distribution surge:Temperature-sensitive mRNA vaccines and cell therapies require minus 25 degrees Celsius transport capabilities across Riyadh and Jeddah corridors.
- Saudi Vision 2030 logistics privatization:State-owned fleet divestitures are creating procurement windows for private cold-chain operators at King Khalid International Airport free zone.
- SASO energy efficiency labeling:Mandatory compressor performance standards are accelerating fleet replacement cycles toward lower-carbon refrigeration units.
Market Restraints
- Insulated panel import dependency:Composite sandwich materials for cargo box construction concentrate sourcing from Turkish and Chinese suppliers, exposing margins to currency volatility.
- Specialized technician scarcity:Vapor-compression system diagnostics and refrigerant handling certification programs remain underdeveloped in the kingdom's vocational training infrastructure.
- Diesel price subsidy phase-out:Saudi Energy Efficiency Center reforms are eroding the total-cost-of-ownership advantage that sustained conventional refrigeration unit dominance.
Strategic Opportunities
- Eastern Province pharmaceutical cluster:Dammam's King Fahd Industrial Port lacks dedicated cold-chain infrastructure compared to Jeddah, creating first-mover positioning for fleet operators.
- Telematics-integrated predictive maintenance:IoT sensor networks enabling remote refrigeration unit diagnostics are compressing service response times for pharmaceutical clients.
- Municipal electric fleet mandates:Riyadh Municipality's zero-emission last-mile delivery zones are opening procurement channels for battery-electric refrigerated vans.
Industry Challenges
- GDP qualification timeline compression:SFDA vehicle certification audits for pharmaceutical transport require 90-day documentation trails that strain fleet deployment schedules.
- Legacy fleet retrofit complexity:Existing diesel-powered refrigeration units face mounting incompatibility with emerging telematics platforms and emissions monitoring systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Refrigerated Truck Market |
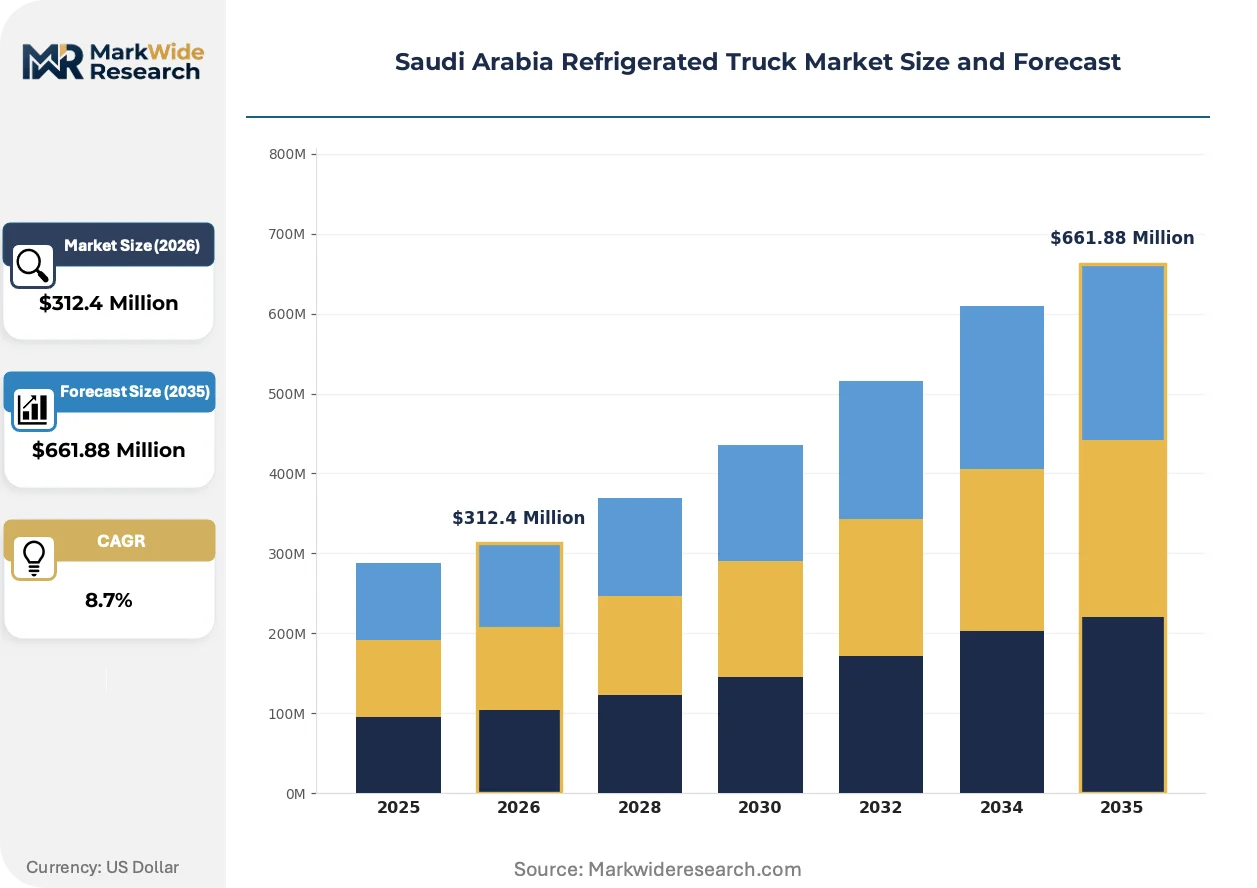
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Van, Trailer, Chassis, Container End User: Food & Beverage, Pharmaceuticals, Chemicals, Agriculture Temperature Range: Frozen, Chilled, Ambient, Deep Freeze Fuel Type: Diesel, Electric, CNG, LPG |
| Companies Covered | Carrier Transicold, Thermo King, Daikin, Frigoblock, Zanotti, Foton Group, ISUZU, Naqel Express, ColdStores Group of Saudi Arabia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Refrigerated Truck Market Trends and Innovations
Digital cold-chain verification systems are displacing paper-based temperature logs as pharmaceutical buyers demand real-time cargo condition transparency across Saudi distribution networks.
Telematics-integrated refrigeration control systems are virtualizing fleet management by enabling remote temperature monitoring, automated alert generation, and predictive compressor maintenance scheduling. Pharmaceutical distributors operating from Riyadh's free zones are adopting these platforms fastest, with full-fleet deployment timelines compressing from 18 months to 6 months. This virtualization is collapsing the information asymmetry that previously sustained premium pricing for established third-party cold-chain haulers.
SFDA Good Distribution Practice enforcement is mandating continuous temperature documentation with 15-minute interval logging for all pharmaceutical transport vehicles. The regulation requires calibration-certified data loggers and audit-ready electronic records spanning 24 months. Van configurations serving urban pharmacy distribution face the steepest compliance retrofit costs, with operators in Jeddah's commercial districts accelerating replacement of pre-2020 refrigeration units.
Direct fleet ownership is displacing contracted third-party cold-chain services as pharmaceutical manufacturers prioritize cargo custody control over cost minimization. Major biologics producers are establishing captive refrigerated truck pools rather than outsourcing to general freight operators. This shift concentrates most visibly around King Khalid International Airport's pharmaceutical free zone, where import volumes of temperature-sensitive therapies have expanded cold-chain infrastructure requirements beyond third-party capacity.
Saudi Arabia Refrigerated Truck Market Segmentation
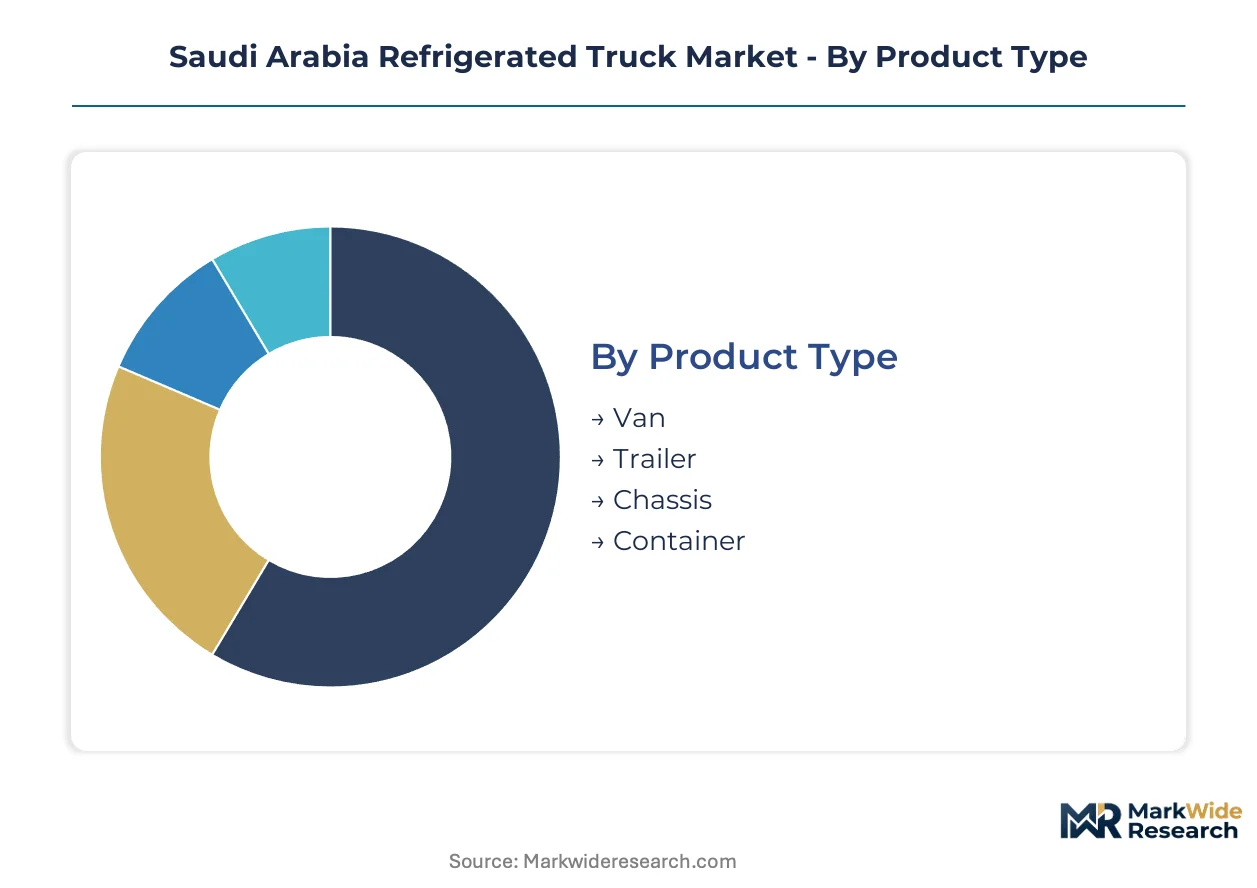
Segmentation in Saudi Arabia's refrigerated truck market reveals how regulatory pressure and climate extremes reshape procurement priorities. Fleet operators balance SFDA compliance costs against fuel economics and route-specific cargo requirements.
Product Type:
Mature configurations dominate established corridors while emerging formats capture municipal electrification mandates.
- Van:Compact insulated bodies with integrated refrigeration units serve urban pharmaceutical distribution through Riyadh's dense commercial districts. Maneuverability commands premium positioning as SFDA GDP audits tighten last-mile documentation requirements.
- Trailer:Detachable insulated semi-trailers sustain long-haul operations connecting Jeddah Islamic Port to inland logistics hubs. High-volume food import flows justify dedicated fleet investment despite higher capital deployment.
- Chassis:Cab-and-chassis platforms with aftermarket refrigeration mounting serve mid-scale distributors seeking configuration flexibility.
- Container:Intermodal reefer containers bridge maritime and overland cold chains at King Fahd Industrial Port.
Trailer configurations retain volume leadership; electric van variants hold the steepest expansion curve.
End User:
Regulatory intensity varies sharply across customer categories, concentrating vendor specialization.
- Food & Beverage:Temperature-controlled transport of dairy, meat, and prepared foods dominates fleet utilization across Saudi Arabia's import-dependent food supply chain. Jeddah's commercial districts generate concentrated demand for multi-temperature zone vehicles.
- Pharmaceuticals:Biologics distribution requires minus 25 degrees Celsius capabilities with continuous telematics monitoring. SFDA enforcement of GDP standards is fragmenting fleet ownership toward captive pharmaceutical operator models.
- Chemicals:Temperature-sensitive industrial reagents and specialty coatings transport commands specialized hazardous-materials certification.
- Agriculture:Domestic date and dairy production generates seasonal cold-chain demand from Al-Qassim and Asir regions.
Food and beverage applications absorb the greatest fleet capacity; pharmaceutical logistics demonstrates the fastest margin expansion.
Temperature Range:
Specification tiers align with cargo value density and regulatory scrutiny intensity.
- Frozen:Minus 18 degrees Celsius standard for meat and seafood imports dominates reefer container throughput at Jeddah terminals. Established compressor technologies sustain cost-efficient fleet operations.
- Chilled:Zero to 4 degrees Celsius range serves dairy and fresh produce distribution across Riyadh Municipality's retail networks. SASO energy efficiency labeling is accelerating replacement toward lower-carbon refrigeration units.
- Ambient:Controlled-temperature transport for heat-sensitive non-refrigerated goods fills niche pharmaceutical adjacencies.
- Deep Freeze:Minus 25 degrees Celsius capabilities for mRNA vaccines and cell therapies command specialized fleet investment around King Khalid International Airport free zone.
Chilled transport retains the broadest application base; deep freeze specifications are gaining share fastest in biologics corridors.
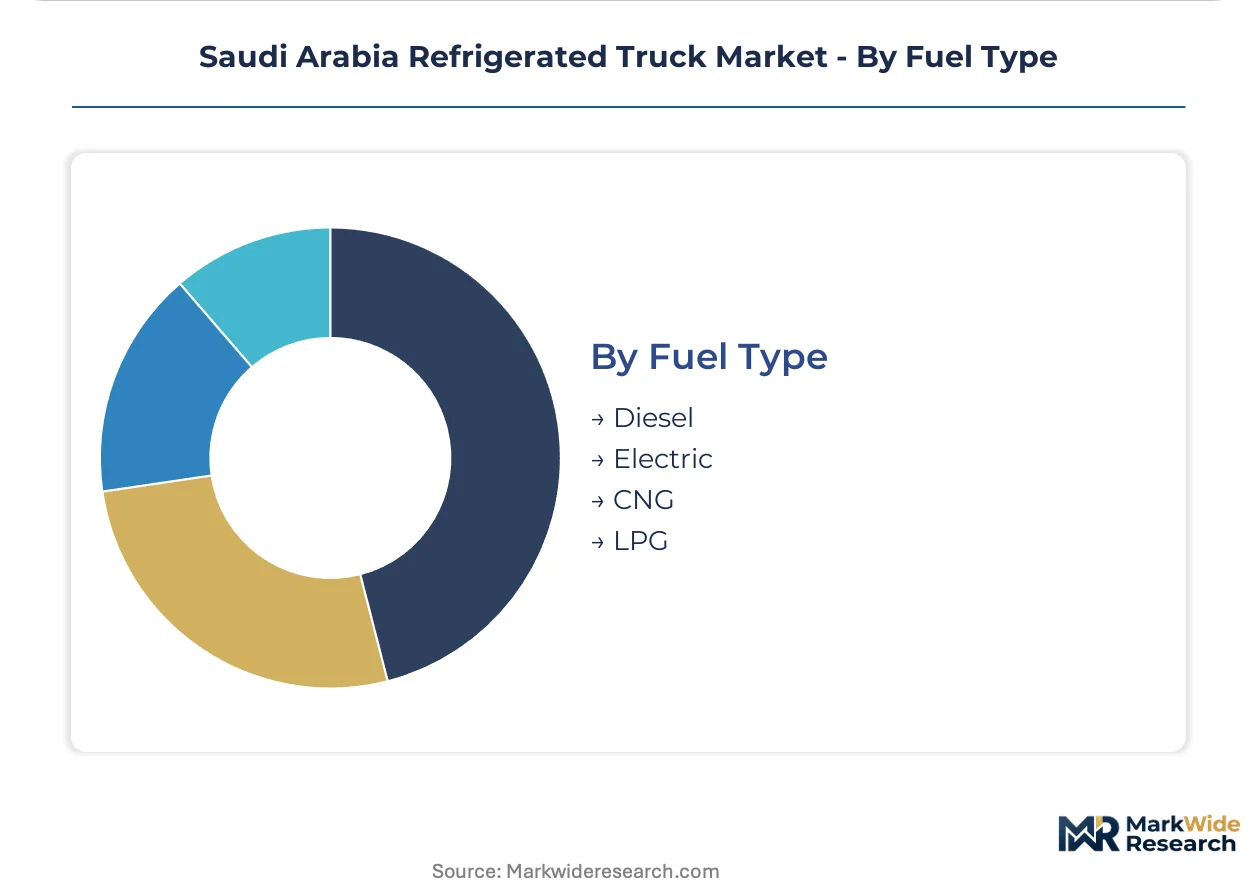
Fuel Type:
Energy transition policies are restructuring total-cost-of-ownership calculations across fleet procurement.
- Diesel:Conventional compression-ignition engines with transport refrigeration unit power-takeoff dominate existing fleet composition. Saudi Energy Efficiency Center subsidy phase-out is eroding historical cost advantages.
- Electric:Battery-electric vans with integrated electric refrigeration compressors serve Riyadh Municipality's zero-emission last-mile zones. Fastest-growing procurement channel despite charging infrastructure constraints.
- CNG:Compressed natural gas conversions offer intermediate emissions reduction for heavy-duty chassis applications.
- LPG:Liquefied petroleum gas systems retain niche deployment in independent operator fleets seeking fuel cost arbitrage.
Diesel platforms retain installed-base dominance; electric variants are climbing the fastest on municipal procurement mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
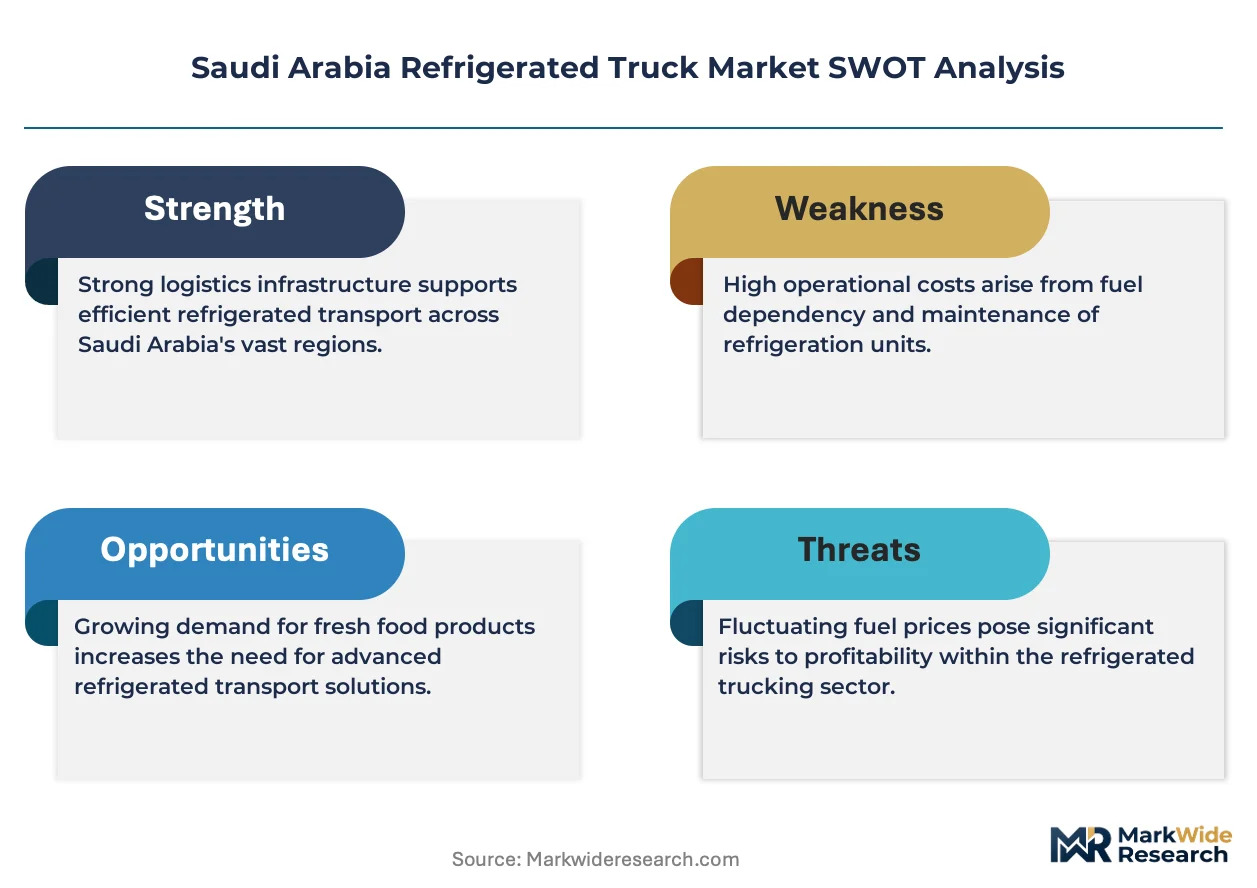
Jeddah Islamic Port anchors Saudi Arabia's refrigerated truck demand through its status as the kingdom's busiest maritime gateway for temperature-sensitive food and pharmaceutical imports.
Riyadh
Pharmaceutical distribution clusters around King Khalid International Airport's free zone drive fleet investment toward deep-freeze capable vans. SFDA GDP enforcement mandates telematics integration for all vehicles serving biologics corridors. The capital's dense commercial districts reward maneuverable configurations that navigate last-mile pharmacy networks.
Eastern Province
Dammam's King Fahd Industrial Port generates containerized reefer throughput connecting to petrochemical and food processing zones. The region lacks dedicated cold-chain infrastructure compared to Jeddah, creating procurement gaps for fleet operators. Jubail's industrial city sustains chemical transport demand requiring specialized temperature control.
Western Region
Makkah and Madinah pilgrimage logistics generate seasonal spikes in food and pharmaceutical distribution requiring surge fleet capacity. The Red Sea coastal corridor links Jeddah port to inland population centers through long-haul trailer operations. Taif's agricultural output creates chilled transport demand for domestic date and dairy products.
NEOM Northwest
The giga-project's construction phase imports temperature-sensitive materials and prefabricated components through bespoke logistics arrangements. Regulatory sandbox provisions allow pilot deployment of electric refrigerated vehicles in designated zones. Future city planning integrates dedicated cold-chain corridors from inception rather than retrofitting legacy infrastructure.
Saudi Arabia Refrigerated Truck Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying refrigeration compressors, insulated panels, and telematics modules. Market structure concentrates around three to four full-system providers while fragmented aftermarket service networks populate secondary cities. Strategic archetypes include Gulf-based service infrastructure players, European refrigeration technology licensors, and domestic logistics operators building captive fleets. Competitive moves center on telematics platform partnerships and vertical integration into cold storage warehousing.
Among the named participants, Carrier Transicold and Thermo King occupy positions as established system integrators with regional service footprints, while Naqel Express exemplifies the logistics-operator archetype expanding dedicated pharmaceutical delivery capabilities. Daikin represents Japanese industrial diversification into transport refrigeration, and ColdStores Group of Saudi Arabia anchors domestic fleet ownership models. Foton Group and ISUZU sit within the chassis supply tier where vehicle platform selection constrains downstream refrigeration mounting options.
| Leading Market Players |
|---|
| Carrier Transicold |
| Thermo King |
| Daikin |
| Frigoblock |
| Zanotti |
| Foton Group |
| ISUZU |
| Naqel Express |
| ColdStores Group of Saudi Arabia |
| Others |
Pricing and Supply Chain Analysis
Jeddah Islamic Port's containerized reefer throughput capacity governs downstream pricing power for Saudi Arabia's refrigerated truck operators, with import volume concentration at this maritime gateway enabling logistics providers to command premium positioning on long-haul routes to Riyadh.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement negotiations, with GDP-certified telematics integration and SFDA audit documentation separating premium fleet operators from commodity haulers. Price differentiation centers on compressor technology grade and after-sales service bundling, with pharmaceutical distributors showing lowest price sensitivity due to cargo value density. Cost compression in economy-tier diesel units is intensifying because Saudi Energy Efficiency Center subsidy phase-out erodes total-cost-of-ownership advantages.
Supply Chain Analysis
Extended payment terms from Turkish and Chinese insulated panel suppliers are financing working capital for Saudi fleet operators amid currency volatility exposure. Manufacturing concentration in Turkey, China, and Germany for composite sandwich materials and vapor-compression components creates import dependency. Single-source vulnerability concentrates around refrigerant supply chains, with distribution running through Jeddah bonded warehouses to inland logistics hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward pharmaceutical distributors consolidating captive fleet ownership, fragmenting third-party cold-chain service markets as biologics producers prioritize cargo custody control over cost minimization.
For Market Incumbents: Harden telematics platform integration with predictive maintenance capabilities to defend against emerging electric fleet entrants capturing Riyadh Municipality zero-emission zones. Invest in GDP certification capacity at King Khalid International Airport free zone to anchor pharmaceutical client retention. Backward integration into cold storage warehousing creates stickier customer relationships.
For New Entrants and Emerging Players: Pursue Eastern Province pharmaceutical cluster development, where Dammam's King Fahd Industrial Port lacks dedicated cold-chain infrastructure compared to Jeddah. Target municipal electric van procurement channels opened by Riyadh zero-emission last-mile mandates. Position through telematics-first fleet offerings with compressed deployment timelines.
For Investors and Strategic Acquirers: Carve-out targets emerge from state-owned logistics enterprises divesting under Saudi Vision 2030 privatization timelines. Long-term viability favors operators with integrated pharmaceutical certification capabilities and electric fleet transition readiness. Watch SFDA enforcement intensity as inflection indicator for captive fleet expansion rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Remote diagnostics compress pharmaceutical client response times and anchor recurring service revenue. |
| GDP Certification Investment | SFDA-compliant documentation capabilities unlock biologics distribution contracts at King Khalid Airport. |
| Electric Fleet Procurement | Riyadh Municipality zero-emission zones create first-mover positioning in municipal food delivery. |
| Backward Integration into Cold Storage | Captive warehousing at Jeddah Islamic Port secures import handling margins from maritime to last-mile. |
| Eastern Province Infrastructure Buildout | Dammam's underserved pharmaceutical corridor offers expansion runway ahead of competitor entry. |
Research Methodology
The analysis maps van, trailer, chassis, and container configurations, each validated through fleet operations managers, pharmaceutical logistics directors, cold-chain procurement officers, and refrigeration unit service technicians. Primary interviews combined with secondary validation from SASO energy efficiency filings, SFDA GDP audit records, General Authority of Ports reefer throughput data, and Saudi Energy Efficiency Center subsidy program disclosures. Bottom-up fleet deployment counts triangulated against top-down import volume flows through Jeddah and Dammam terminals.
Assumptions held SFDA enforcement timelines and Saudi Vision 2030 logistics privatization schedules fixed while varying diesel subsidy phase-out velocity and electric vehicle adoption curves across the projection horizon. Segmentation modeling incorporated product type, end-user vertical, temperature range specification, and fuel type transition pathways. CAGRs derived from fleet replacement cycle analysis and import corridor volume elasticity to pharmaceutical and food sector demand.
Sensitivities concentrate around SFDA audit intensity escalation and electric charging infrastructure deployment pace. Forecasts reflect documented assumptions on regulatory enforcement and energy transition policy continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy-Duty Trucks
Bucket Trucks Market
Heavy-Duty Trucks
Global Connected Truck Market
Heavy-Duty Trucks
Garbage Truck Bodies Market
Heavy-Duty Trucks
Garbage Collection Trucks Market
Heavy-Duty Trucks
Heavy Duty Truck Wash Market
Heavy-Duty Trucks
Fire Trucks Market
Heavy-Duty Trucks
Articulated Dump Trucks Market
Heavy-Duty Trucks
Global Vocational Truck Market
Heavy-Duty Trucks
Egypt Trucks Market
Heavy-Duty Trucks
North America Vacuum Truck Market
Heavy-Duty Trucks
Digger Derrick Truck Market
Heavy-Duty Trucks
Hard Tonneau Cover Market
Heavy-Duty Trucks
India Vacuum Truck Market
Heavy-Duty Trucks
Flatbed Truck Market
Heavy-Duty Trucks
Heavy-Duty Truck Load and Axle Weight Sensor Systems Market
Heavy-Duty Trucks
Utility Trucks Market