
 Vacuum Truck Market | 2026-2036
Vacuum Truck Market Size, Share, and Industry Trends Forecast 2026-2036
Vacuum Truck Market Analysis
Multi-source procurement for vacuum truck chassis and tank assemblies is expanding as fleet operators diversify supplier risk across North American and European vendors. Federal Signal Corporation leverages vertical integration in hydro-excavation systems to sustain pricing power across municipal contracts. KOKS Group BV anchors its position in industrial cleaning through specialized ATEX-certified builds for petrochemical environments. Cappellotto S.p.A. competes on manufacturing scale in combination truck configurations serving Italian and export markets.
A vacuum truck is a heavy-duty vehicle integrating a high-capacity tank vessel with a suction pump system, typically achieving vacuum levels of 85-95% and tank capacities ranging from 1,000 to 15,000 gallons for material collection and transport. These units perform essential functions in hazardous waste removal, underground utility exposure, and industrial process cleaning where mechanical excavation risks infrastructure damage. Combination trucks command the widest application scope across municipal and oilfield segments, while liquid vacuum units dominate waste management fleets where single-phase recovery suffices. Hydro excavation represents the fastest-growing application as fiber-optic and gas distribution networks expand, though oil and gas end users retain the highest per-unit specification requirements.
EPA emissions regulations under Tier 4 Final and Stage V standards in Europe are forcing engine redesigns and aftertreatment integration that elevate chassis costs and extend replacement cycles. OSHA confined-space entry standards and DOT hazmat transport rules shape tank construction, pressure relief, and operator certification requirements across jurisdictions. Stakeholders must monitor evolving decarbonization mandates in Germany and California, where zero-emission powertrain trials could reshape fleet procurement criteria before the decade closes.
Market Dynamics
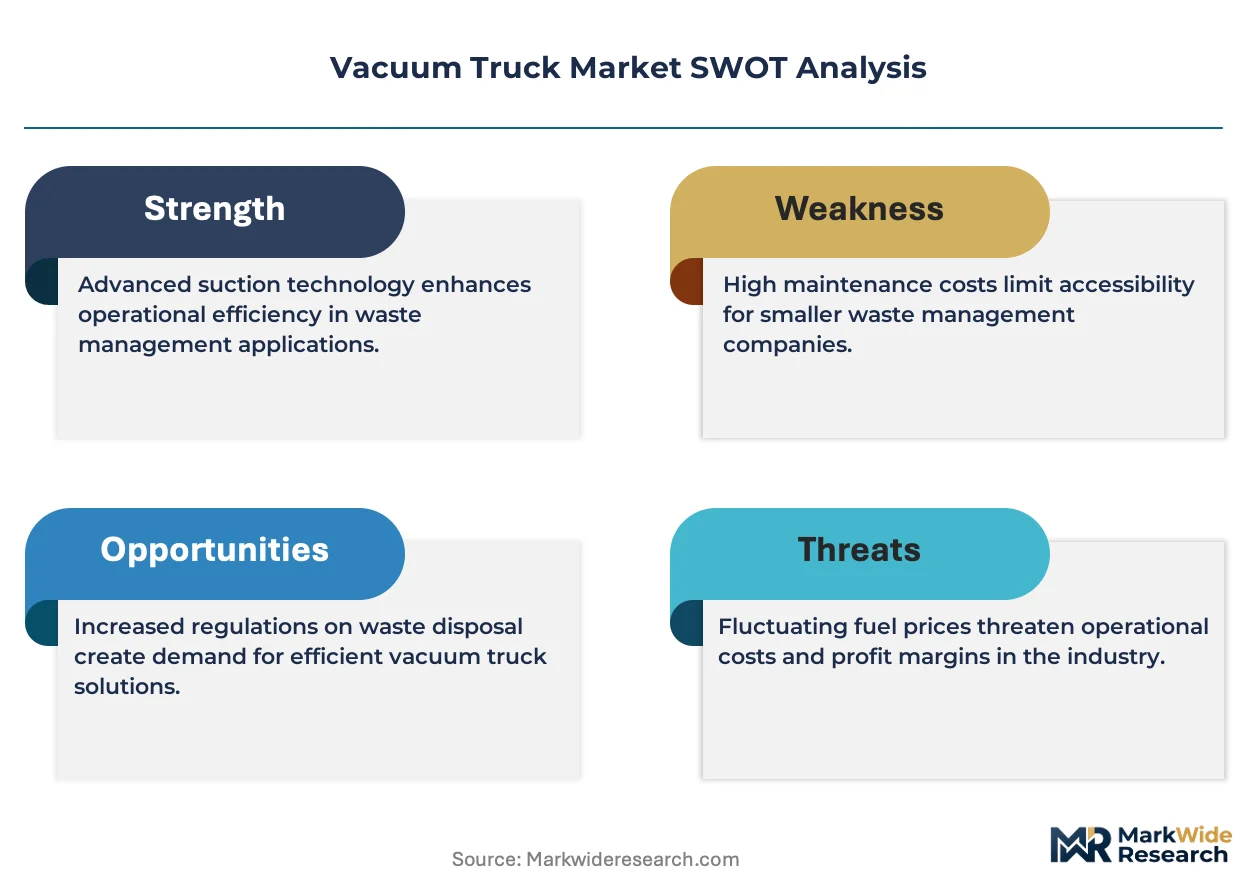
EPA Tier 4 Final and Stage V emissions mandates are forcing engine redesigns and aftertreatment integration that elevate chassis costs and compress replacement cycles across municipal and industrial fleets. Fleet operators must now balance compliance spending against extended asset utilization timelines.
Growth Catalysts
- Fiber-optic network expansion:Telecommunications infrastructure buildouts in the United States and Germany are accelerating hydro excavation demand for underground utility exposure with minimal surface disruption.
- OSHA confined-space entry standards:Stricter enforcement of 29 CFR 1910.146 is compelling industrial facilities to outsource hazardous tank cleaning to certified vacuum truck operators rather than perform work in-house.
- Aging underground infrastructure:Century-old sewer systems in northeastern US cities require frequent debris removal and line maintenance, sustaining municipal fleet procurement.
Market Restraints
- Chassis supply concentration:Heavy-duty truck chassis production concentrates among three North American manufacturers, creating allocation bottlenecks during emissions transition periods.
- Specialized steel and aluminum input costs:Tank vessel fabrication depends on corrosion-resistant alloys subject to commodity price volatility and tariff exposure.
- Technical limitation in electric powertrain range:Current battery-electric chassis configurations lack the duty cycle endurance required for continuous suction and hydro excavation operations.
Strategic Opportunities
- ATEX-certified builds for petrochemical clusters:Gulf Coast refinery expansion and European chemical corridor maintenance programs reward specialized explosion-proof configurations.
- Zero-emission powertrain trials in California:CARB fleet electrification mandates are creating early-mover advantage for OEMs developing hydrogen fuel cell and battery-electric prototypes.
- Telematics and predictive maintenance convergence:Integration of IoT sensors with fleet management software enables usage-based service contracting and remote diagnostics.
Industry Challenges
- Certified vacuum truck operator shortage:CDL hazmat endorsements and confined-space rescue training requirements extend hiring timelines and elevate labor costs.
- Multi-jurisdictional compliance complexity:DOT hazmat transport rules, state weight limits, and municipal noise ordinances create operational friction for interstate fleet deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vacuum Truck Market |
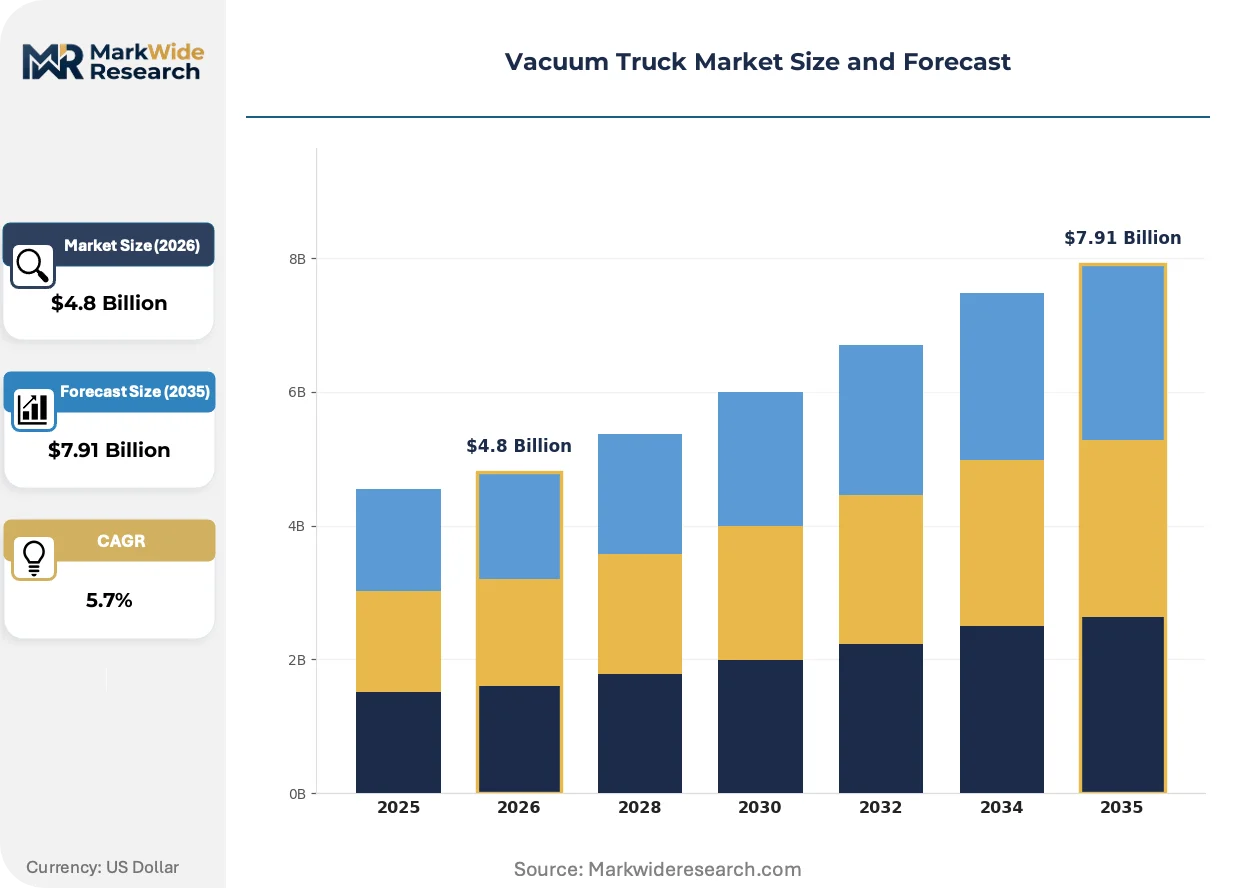
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Vacuum Trucks, Dry Vacuum Trucks, Combination Trucks, Industrial Vacuum Trucks Application: Waste Management, Hydro Excavation, Industrial Cleaning, Oil & Gas End User: Municipalities, Construction Companies, Oil & Gas Companies, Environmental Services Technology: Pneumatic Systems, Positive Displacement, Liquid Ring, Centrifugal |
| Companies Covered | Federal Signal Corporation, Cappellotto S.p.A., Vac-Con Inc., KOKS Group BV, FULONGMA Group Co. Ltd., GapVax Inc., Keith Huber Corporation, Alamo Group Inc., Amphitec B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vacuum Truck Market Emerging Trajectories
Equipment specification and procurement logic are transforming as emissions mandates tighten and end-users prioritize total cost of ownership over upfront capital expenditure. Three developments are compressing traditional competitive advantages.
High-pressure water recycling systems are rewriting hydro excavation economics. These closed-loop units filter and reuse water on-site, cutting disposal volumes by half and reducing municipal permit burdens. Pipeline contractors in Texas and Alberta are adopting these configurations fastest, compressing project timelines and lowering per-foot excavation costs.
Stage V non-road engine standards in Europe are mandating diesel particulate filters and selective catalytic reduction across all power classes above 19 kW. Industrial cleaning fleets in Germany and the Netherlands face retrofit obligations or accelerated replacement schedules. OEMs with in-house aftertreatment engineering are capturing share from chassis-dependent assemblers.
Performance-based service contracting is displacing traditional equipment procurement in municipal sewer maintenance. Cities in Ohio and Pennsylvania now specify debris tons removed per month rather than truck availability, transferring operational risk to contractors. This shift favors fleet operators with telematics-enabled asset utilization tracking and in-house technician benches.
Vacuum Truck Market Segmentation
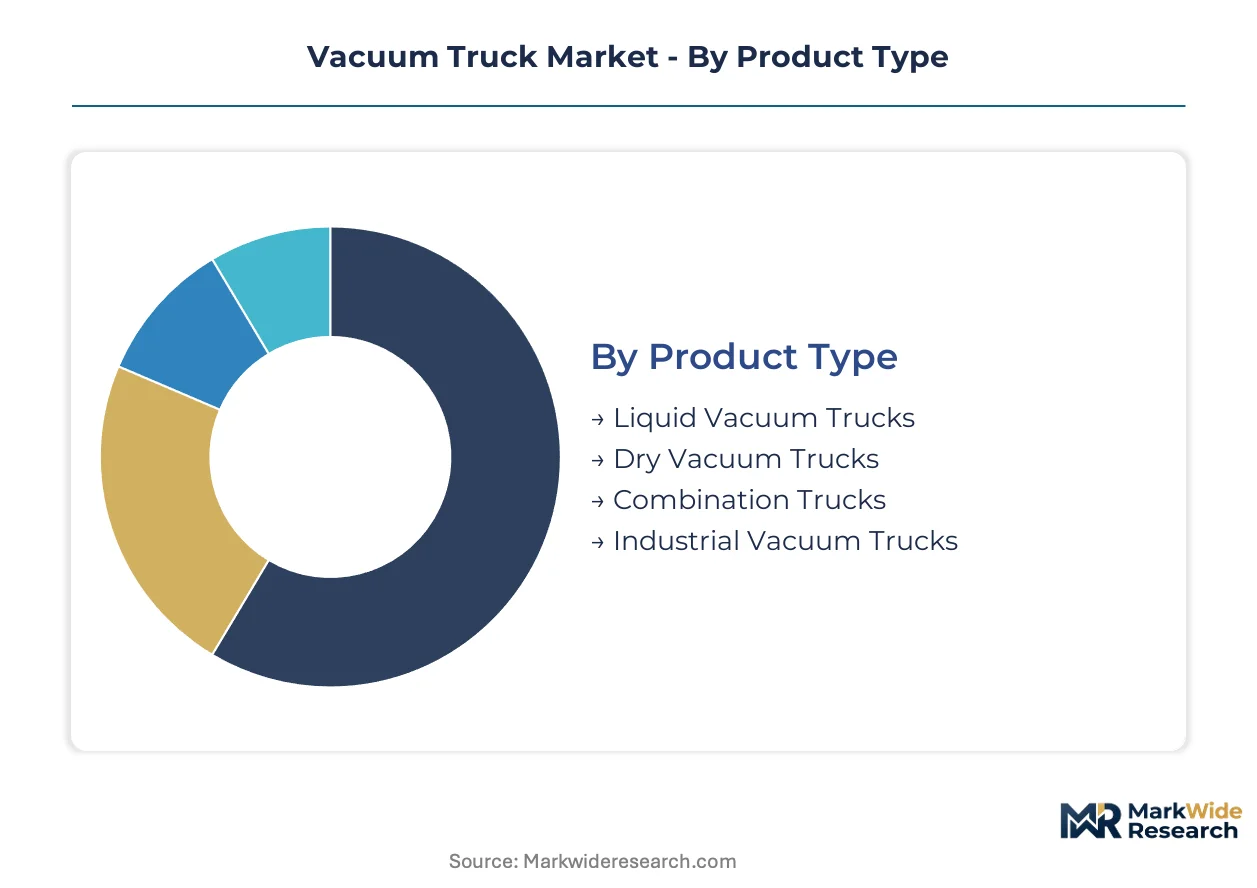
Equipment specification varies sharply across end-use environments, forcing buyers to match tank configuration, vacuum technology, and chassis integration to specific material handling demands. Segmentation logic in this market centers on duty cycle intensity, regulatory exposure, and operational mobility requirements rather than simple capacity scaling.
Product Type:
Fleet procurement decisions hinge on material phase compatibility and single-purpose versus multi-function deployment economics.
- Combination Trucks:Dual-phase recovery systems integrate liquid and dry material handling in a single tank vessel with partitioned chambers or sequential filtration. Municipal sewer departments in the United States and pipeline contractors in Alberta specify these units most heavily, driven by route density optimization and capital constraint pressures that favor flexible asset utilization over dedicated fleets.
- Liquid Vacuum Trucks:Single-phase tank vessels with corrosion-resistant linings and high-flow pumps achieve rapid evacuation of septic, industrial process, and hydrocarbon liquids. Waste management fleets concentrate procurement here where material consistency permits simplified tank cleaning and faster turnaround between loads.
- Dry Vacuum Trucks:Cyclonic separation and baghouse filtration handle powders, aggregates, and granular industrial waste without liquid contamination risks.
- Industrial Vacuum Trucks:High-horsepower blower packages and reinforced tank construction address abrasive materials and continuous-duty cycles in foundries and cement plants.
Combination trucks lead on scale; hydro excavation specialization is gaining share fastest among new orders.
Application:
Contractor revenue stability and equipment utilization rates diverge significantly across project-based versus recurring service models.
- Hydro Excavation:High-pressure water injection combined with immediate vacuum recovery exposes buried utilities with minimal mechanical damage risk. Telecommunications infrastructure buildouts in Germany and fiber-optic network expansion across Texas are accelerating specification of water recycling configurations that cut disposal costs and municipal permit burdens.
- Waste Management:Septic pumping, grease trap servicing, and portable toilet evacuation constitute the volume base of municipal and commercial fleet operations. The recurring revenue predictability of route-based service contracts sustains replacement demand even through construction cycle downturns.
- Industrial Cleaning:Confined-space tank entry and process vessel maintenance require ATEX-certified equipment and specialized operator training.
- Oil & Gas:Drilling mud recovery, production tank cleaning, and pipeline maintenance demand the highest per-unit specifications for pressure rating and hazardous area certification.
Waste management anchors fleet volumes; hydro excavation demonstrates the steepest expansion trajectory.
End User:
Capital availability and in-house technical capability determine whether buyers self-operate fleets or outsource to specialized contractors.
- Municipalities:City sewer departments and public works agencies operate the largest installed base of combination trucks for debris removal and line maintenance. Aging infrastructure in northeastern US cities sustains procurement despite budget cyclicality.
- Environmental Services:Specialized remediation contractors combine vacuum truck fleets with treatment and disposal assets to offer turnkey hazardous waste management. Superfund site activity and industrial facility decommissioning drive specification of high-vacuum units with vapor recovery systems.
- Construction Companies:Underground utility contractors and site preparation specialists deploy hydro excavation for potholing and trenching with reduced surface restoration costs.
- Oil & Gas Companies:Integrated operators and field service contractors maintain captive fleets for production maintenance and drilling support.
Municipalities retain the largest installed base; environmental services contractors are capturing share through performance-based contracting.
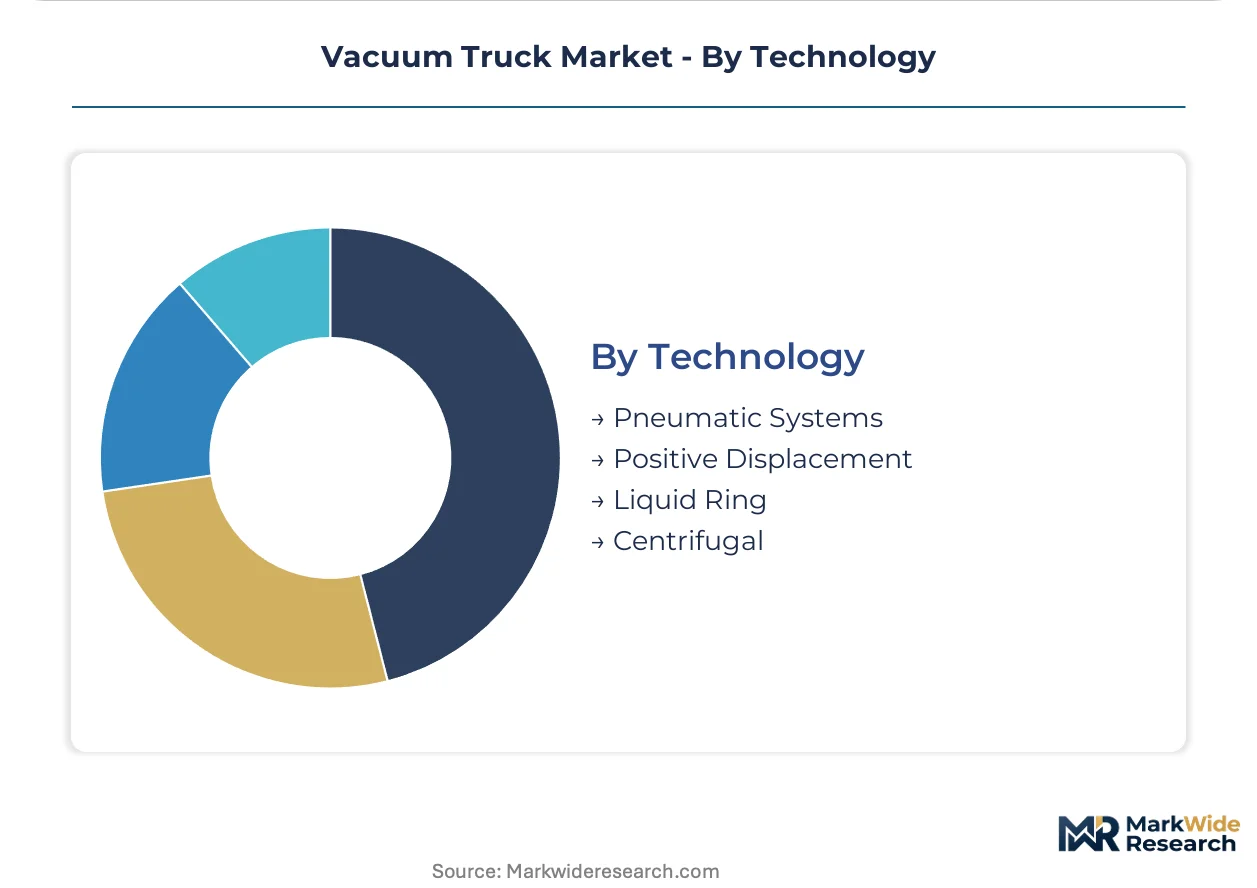
Technology:
Vacuum generation method determines maximum achievable vacuum depth, airflow volume, and tolerance for moisture or particulate contamination.
- Positive Displacement:Rotary vane or rotary lobe blowers achieve deep vacuum levels to 28 inches Hg for heavy material lifting and long suction hose runs. Industrial cleaning applications in petrochemical facilities favor this technology for reliable performance across varying load conditions.
- Liquid Ring:Sealed compression chambers using service liquid as the piston tolerate high moisture content and explosive vapors without mechanical wear. ATEX-certified builds for European chemical corridor maintenance specify liquid ring systems for intrinsic safety.
- Pneumatic Systems:Venturi-based vacuum generation offers simplicity and low maintenance for light-duty material transfer.
- Centrifugal:High-volume, low-vacuum blowers suit pneumatic conveying of granular materials over short distances.
Positive displacement dominates industrial specifications; liquid ring systems are expanding most quickly in hazardous environment deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Permian Basin anchors vacuum truck deployment density, where oilfield service contractors maintain captive fleets for drilling mud recovery and production tank maintenance. Fiber-optic network buildouts across Texas and the Marcellus Shale region are accelerating hydro excavation specification. Regulatory fragmentation across state DOT hazmat rules and municipal noise ordinances complicates interstate fleet deployment.
United States
Municipal sewer departments in Cleveland, Pittsburgh, and Philadelphia sustain combination truck procurement for century-old infrastructure maintenance. EPA Tier 4 Final emissions mandates force engine redesigns and aftertreatment integration that elevate chassis costs. The Marcellus Shale region in Pennsylvania and West Virginia concentrates hydro excavation demand for pipeline exposure with minimal surface disruption.
Germany
Industrial cleaning fleets in the Rhine-Ruhr chemical corridor face Stage V non-road engine retrofit obligations or accelerated replacement schedules. ECHA REACH compliance shapes tank vessel material specifications for hazardous waste transport. The Port of Rotterdam adjacent chemical cluster drives ATEX-certified liquid ring vacuum system specification for intrinsic safety in explosive atmospheres.
Canada
Alberta oil sands operators specify the highest per-unit vacuum truck configurations for tailings pond maintenance and process water recovery. Environment Canada regulations on industrial wastewater discharge tighten tank cleaning and disposal protocols. The Calgary-Edmonton corridor concentrates environmental services contractors offering turnkey hazardous waste management to upstream operators.
Australia
Mining operations in Western Australia's Pilbara region deploy industrial vacuum trucks for abrasive material handling and continuous-duty foundry support. The country's national occupational health and safety regulator enforces confined-space entry standards that elevate operator certification requirements. Queensland's Surat Basin coal seam gas fields sustain production maintenance fleet procurement.
United Arab Emirates
ADNOC refinery expansion in the Western Region rewards specialized explosion-proof vacuum configurations for petrochemical maintenance programs. The country's environmental agency mandates vapor recovery systems on hazardous waste transport vehicles. Dubai's Jebel Ali industrial zone concentrates environmental services contractors serving offshore platform decommissioning and onshore facility cleaning.
Vacuum Truck Market Vendor Landscape
Global majors compete with regional champions across emissions compliance capabilities and municipal contract tenure. Chassis-dependent assemblers face margin compression as in-house aftertreatment engineering becomes a prerequisite for European market access. Three archetypes dominate: vertically integrated hydro-excavation system builders, specialized ATEX-certified fabricators for hazardous environments, and scale-driven combination truck manufacturers. Competitive moves center on backward integration into tank vessel production and telematics-enabled service contracting to capture recurring revenue streams.
Within the hazardous environment specialization tier, KOKS Group BV and Amphitec B.V. occupy positions anchored by Dutch engineering heritage and North Sea offshore service lineage. Federal Signal Corporation exemplifies the vertically integrated archetype through captive supply of hydro-excavation components. Cappellotto S.p.A. represents scale-driven manufacturing concentration in combination truck configurations. These three entities illustrate how geographic origin and corporate structure shape strategic positioning without converging on identical capability portfolios.
| Leading Market Players |
|---|
| Federal Signal Corporation |
| Cappellotto S.p.A. |
| Vac-Con Inc. |
| KOKS Group BV |
| FULONGMA Group Co. Ltd. |
| GapVax Inc. |
| Keith Huber Corporation |
| Alamo Group Inc. |
| Amphitec B.V. |
| Others |
Supply Flow & Price Mechanics
EPA Tier 4 Final emissions mandates gate qualified chassis supply and premium-tier pricing access for vacuum truck OEMs, compressing margins for assemblers lacking in-house aftertreatment engineering while rewarding vertically integrated builders with pricing power across municipal procurement cycles.
Pricing Analysis
Input-cost pass-through from corrosion-resistant steel alloys and specialized aluminum tank vessels runs through contract-based long-term offtake agreements with tiered escalation clauses. Price differentiation centers on ATEX certification grade and after-sales service bundling, with explosion-proof petrochemical configurations commanding substantial premiums over standard municipal builds. Cost compression in mid-tier combination trucks is intensifying because chassis-dependent assemblers face margin squeeze during emissions transition periods. Municipal sewer departments exhibit highest price sensitivity due to budget cyclicality, while oilfield service contractors demonstrate lowest sensitivity given operational risk mitigation priorities.
Supply Chain Analysis
Domestic-content mandates in the United States and Buy America provisions for federally funded infrastructure projects are reshaping sourcing patterns for chassis and tank vessel components. Manufacturing concentrates in the United States, Germany, and Italy, with specialized blower packages drawing from Dutch engineering clusters. Raw material dependencies rest on high-grade stainless steel from European mills, aluminum plate from Canadian smelters, and specialized elastomer seals from German chemical suppliers. Single-source vulnerability in heavy-duty truck chassis production among three North American manufacturers creates allocation bottlenecks. Distribution runs through authorized dealer networks with regional service capability and direct municipal contract channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between the United States and Germany, where divergent Stage V versus Tier 4 Final compliance timelines create cost and certification differentials for fleet operators with cross-border deployment capabilities.
For Market Incumbents: Anticipate margin compression from chassis supply concentration by deepening captive production of tank vessels and blower packages. Secure backward integration into hydro-excavation component manufacturing to defend pricing power against emissions-driven cost escalation. Prioritize telematics-enabled service contracting to lock in recurring revenue streams and transfer operational risk from municipal buyers.
For New Entrants and Emerging Players: Begin with zero-emission powertrain prototyping for California CARB fleet electrification mandates, where early-mover advantage exists before decade-end procurement criteria shifts. Target environmental services contractors in the Ohio-Pennsylvania corridor adopting performance-based debris removal contracting. Pursue ATEX-certified liquid ring system specialization for European chemical corridor maintenance as the most penetrable premium tier.
For Investors and Strategic Acquirers: Valuations sit cheapest among chassis-dependent assemblers lacking in-house aftertreatment engineering, presenting consolidation targets for vertically integrated OEMs seeking European market access. Long-term viability favors operators with captive manufacturing of explosion-proof configurations and telematics infrastructure. Monitor hydrogen fuel cell prototype trials as the signal indicating inflection toward zero-emission fleet procurement criteria.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tank Vessel Production | Captive manufacturing of corrosion-resistant alloys insulates margin from steel price volatility and tariff exposure. |
| Telematics-Enabled Service Contracting | IoT sensor integration with fleet management software transfers operational risk and locks recurring revenue from municipal clients. |
| ATEX Certification Investment | Explosion-proof liquid ring configurations unlock petrochemical maintenance contracts in the Rhine-Ruhr and Gulf Coast corridors. |
| Zero-Emission Powertrain Development | Hydrogen fuel cell and battery-electric prototypes position OEMs for CARB fleet electrification mandates in California. |
| High-Pressure Water Recycling System Deployment | Closed-loop filtration configurations cut disposal volumes and municipal permit burdens for hydro excavation contractors. |
Methodological Framework
Multiple input streams — fleet operator interviews, OEM engineering consultations, municipal procurement director discussions, and aftermarket service manager exchanges — were reconciled against regulatory filing databases, customs trade records, and equipment registration data. Primary engagement with maintenance directors at municipal sewer departments, plant engineers at petrochemical facilities, and procurement teams at environmental services contractors informed operational utilization assumptions. Secondary validation drew from EPA emissions compliance filings, DOT hazmat transport records, and European Stage V certification databases. Bottom-up unit economics and top-down fleet replacement modeling were cross-referenced to anchor volume estimates.
Historical fleet deployment patterns were cross-referenced against expert panel inputs from chassis manufacturers and tank fabricators to construct the projection framework across the analysis window. Segmentation dimensions modeled include product type, application intensity, end-user capital availability, and vacuum technology specification. CAGRs were derived from trend extrapolation of replacement cycle compression and expansion of telecommunications infrastructure buildouts. Industry-specific forecast inputs incorporated fiber-optic network deployment schedules and refinery maintenance program cycles.
Several conditions sit outside the modeled scope, including unannounced regulatory accelerations of zero-emission mandates, abrupt commodity price dislocations in specialty steel markets, and chassis allocation disruptions from supplier production constraints. Forecasts reflect documented assumptions regarding emissions compliance timelines and infrastructure investment continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy-Duty Trucks
Full Truckload Transportation Market
Heavy-Duty Trucks
Truck Headache Rack Market
Heavy-Duty Trucks
Articulated Hauler Market
Heavy-Duty Trucks
Global Boom Truck Market
Heavy-Duty Trucks
Heavy-Duty Truck Fleet Control Unit Architectures Market
Heavy-Duty Trucks
Mexico Refrigerated Truck Market
Heavy-Duty Trucks
Airport Catering Truck Market
Heavy-Duty Trucks
Big Rig Trucks Market
Heavy-Duty Trucks
Dump Trucks and Mining Trucks Market
Heavy-Duty Trucks
Heavy-Duty Truck Axle Locking Actuator Components Market
Heavy-Duty Trucks
China Full Truckload Road Freight Transport Market
Heavy-Duty Trucks
Europe Medium & Heavy-Duty Truck Rental Market
Heavy-Duty Trucks
Dump Trucks Market
Heavy-Duty Trucks
Egypt Trucks Market
Heavy-Duty Trucks
Heavy-Duty Truck Load and Axle Weight Sensor Systems Market
Heavy-Duty Trucks
Medium and Heavy Duty Commercial Vehicles (MHCV) Market