
 Hard Tonneau Cover Market | 2026-2036
Hard Tonneau Cover Market Size, Share, and Industry Trends Forecast 2026-2036
Hard Tonneau Cover Market Foresight
Modular three-panel folding configurations is pivoting buyer preference away from single-piece hinged designs by offering bed access flexibility without full removal. BAK Industries leverages proprietary hinge sealing technology to sustain premium positioning in this segment. Rough Country anchors its competitive stance through aggressive pricing on aluminum folding platforms. LEER dominates the original equipment channel through long-standing supply contracts with Detroit automakers.
A hard tonneau cover constitutes a rigid, weather-resistant panel system—typically fabricated from aluminum, fiberglass, or reinforced ABS composite—designed to enclose and secure the cargo bed of a pickup truck. These covers generally withstand loads between 300 and 500 pounds and integrate locking mechanisms that align with the vehicle's central locking system. Folding and retractable product types command the largest installed base due to their balance of security and bed accessibility, while hard shell one-piece variants retain margin concentration in the premium aftermarket. Aluminum as a material category is capturing incremental share from fiberglass as weight reduction becomes a priority for fuel-conscious commercial operators.
The National Highway Traffic Safety Administration (NHTSA) imposes visibility and rear-illumination standards that constrain cover design geometry, while the EPA's fuel economy testing protocols create implicit demand for aerodynamic bed enclosures that improve certified mileage figures. State-level vehicle modification codes in California and Texas further shape installation method acceptance, with no-drill clamp systems avoiding warranty disputes that drill-on methods trigger. Stakeholders must monitor evolving FMVSS interpretations around rear camera and sensor integration as manufacturers embed backup assist technology into tailgate assemblies.
Market Dynamics
Commercial fleet operators are consolidating purchasing power around aluminum-intensive hard tonneau covers that deliver measurable fuel economy gains through aerodynamic bed enclosure, while no-drill clamp systems are displacing traditional drill-on installation methods to preserve vehicle warranty coverage.
Growth Catalysts
- Fuel economy certification protocols:EPA testing methodologies reward aerodynamic bed enclosures with improved mileage ratings, creating implicit pull from Detroit automakers seeking compliance credits.
- Commercial fleet security mandates:Logistics operators across the United States are standardizing locking hard covers to reduce cargo theft exposure and insurance premiums.
- Aluminum material substitution:Weight reduction priorities among fuel-conscious operators are accelerating adoption of aluminum platforms over legacy fiberglass constructions.
Market Restraints
- Raw material cost volatility:Aluminum pricing fluctuations tied to energy-intensive smelting operations compress margin stability for cover fabricators.
- Installation labor concentration:Skilled aftermarket installer networks cluster in Texas and California, creating geographic access bottlenecks for rural buyers.
- Rear visibility compliance:NHTSA standards constrain cover geometry options, limiting design freedom for manufacturers integrating with backup camera systems.
Strategic Opportunities
- Sensor integration white space:Convergence of hard cover assemblies with tailgate-embedded backup assist technology creates premium upgrade paths for safety-conscious buyers.
- Direct-to-consumer channel expansion:E-commerce platforms are capturing share from traditional brick-and-mortar accessory retailers, enabling margin recapture for branded manufacturers.
- State-level modification code harmonization:California and Texas vehicle equipment standards are converging toward no-drill acceptance, reducing SKU complexity for national distribution.
Industry Challenges
- Cross-platform fitment complexity:Proliferating truck bed dimensions across Ford, General Motors, and Stellantis lineups strain inventory management and demand forecasting precision.
- Warranty liability fragmentation:Drill-on installation methods trigger disputes between cover manufacturers, installers, and vehicle OEMs over corrosion and structural damage claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hard Tonneau Cover Market |
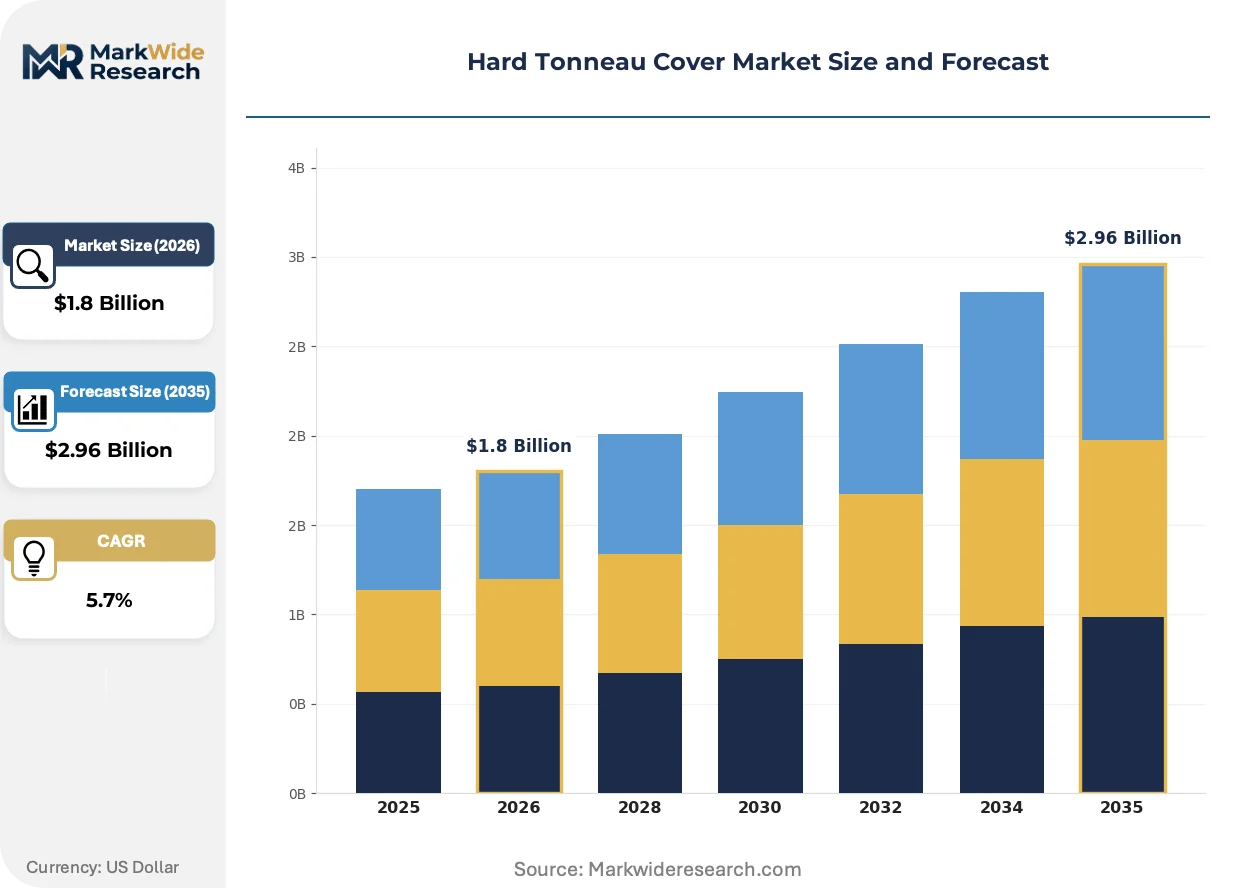
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Folding, Rolling, Retractable, Hard Shell Material: Aluminum, Steel, Fiberglass, Plastic End User: Commercial, Recreational, Automotive Enthusiasts, General Consumers Installation Type: Clamp-On, Drill-On, No-Drill, Drop-In |
| Companies Covered | UnderCover, Rough Country, BAK Industries, Tyger Auto, Pace Edwards, Extang, LEER, INEXRUD, Worksport, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hard Tonneau Cover Market Shifts & Advancements
Product architecture is pivoting toward modular configurations that sacrifice no structural integrity while enabling partial bed access, with material science and regulatory compliance emerging as the twin axes of competitive differentiation.
Electrification-ready hard tonneau covers with integrated solar panel mounting channels are electrifying the premium aftermarket segment. Fleet operators preparing for electric pickup adoption are specifying these platforms to preserve bed functionality without compromising aerodynamic efficiency. The technology is electrifying supplier R&D priorities, compressing development cycles for compatible accessory ecosystems.
EPA fuel economy testing protocols are tightening enforcement around aerodynamic drag coefficients for light-duty trucks. Manufacturers must now submit bed enclosure configurations for certification to claim mileage improvements. The regulatory pressure falls most heavily on full-size pickup segments where Detroit automakers compete for fleet sales volume.
Installer certification programs are displacing informal training networks as the dominant qualification pathway. National retail chains now require documented competence in no-drill clamp systems before authorizing warranty-backed installations. The credentialing shift is most visible in Texas, where commercial fleet density supports specialized training center economics.
Hard Tonneau Cover Market Segmentation
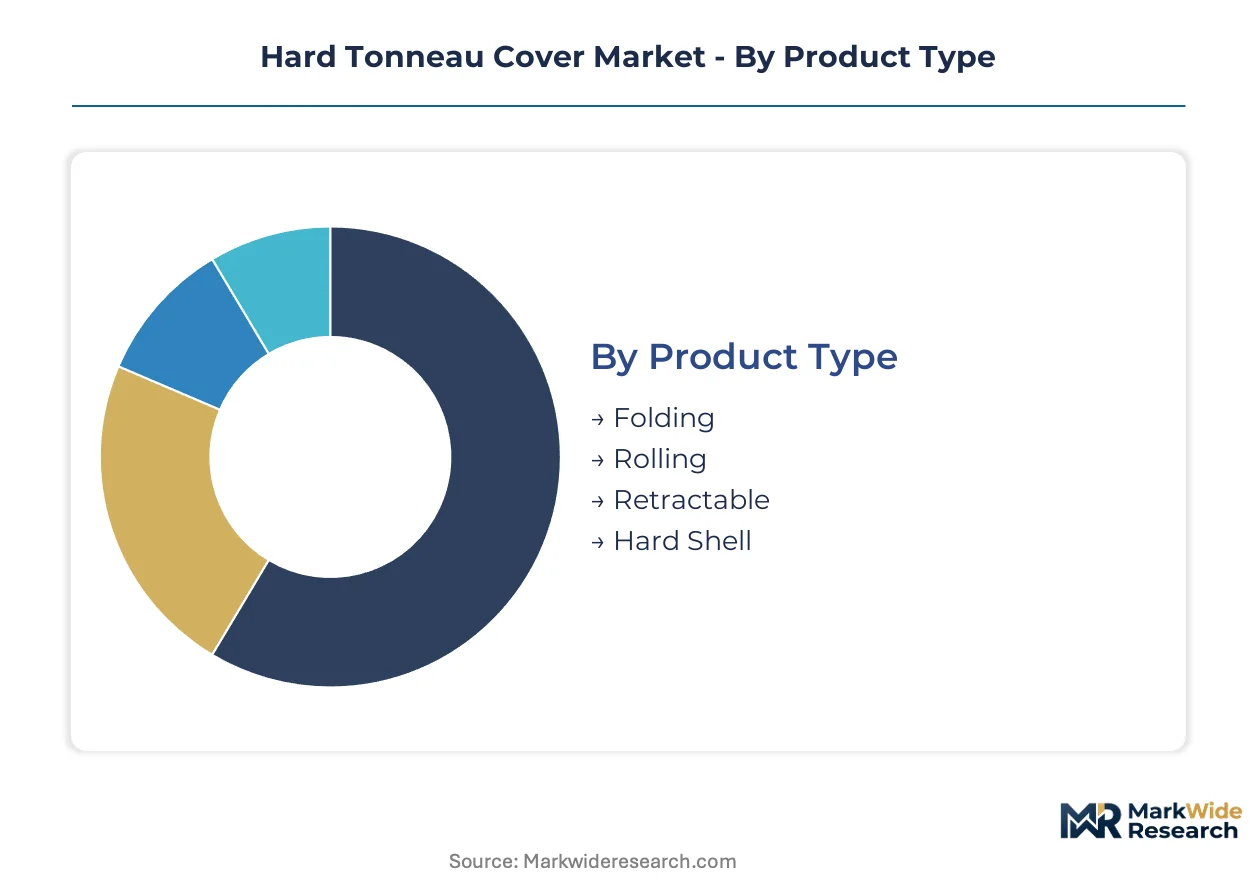
Hard tonneau cover procurement patterns diverge sharply across product architecture, material specification, and installation methodology. Fleet operators prioritize aerodynamic efficiency and warranty preservation, while recreational buyers emphasize bed accessibility and aesthetic integration. Understanding these segment boundaries enables manufacturers to align R&D investment with profit pool concentration.
Product Type:
Supply-side tooling investments cluster around folding and retractable platforms, where aluminum-intensive designs achieve scale economies through shared hinge and rail subassemblies across multiple truck bed configurations.
- Folding:Three-panel aluminum platforms dominate aftermarket volume through balance of security and partial bed access. Demand concentrates among Texas-based commercial fleets seeking fuel economy gains without sacrificing cargo flexibility. Clamp-compatible rail systems from BAK Industries and Rough Country anchor this segment's installer network density.
- Retractable:Canister-mounted aluminum slats retract into forward bed storage, preserving full bed utility when open. California recreational buyers favor this architecture for compatibility with fifth-wheel hitches and adventure equipment mounting. Premium positioning reflects complex rail integration and motorized actuation options.
- Rolling:Vinyl-over-aluminum slat construction offers lightweight weather protection at entry price points. General consumers in rural markets select this format for simplicity and lower shipping costs.
- Hard Shell:Single-piece hinged fiberglass or ABS designs retain margin concentration in premium aftermarket channels. Automotive enthusiasts specify paint-matched finishes for aesthetic continuity with vehicle exterior.
Today's leader: Folding. Tomorrow's challenger: Retractable.
Material:
Cost tier differentiation separates aerospace-grade aluminum suppliers from commodity resin compounders, with mid-market steel platforms losing ground to weight-optimized alternatives.
- Aluminum:5052-H32 and 6061-T6 alloys deliver strength-to-weight ratios critical for EPA fuel economy certification. Commercial fleet procurement specifications increasingly mandate aluminum platforms to achieve measurable mileage improvements and reduce axle load stress.
- Fiberglass:Gel-coated composite shells enable seamless paint integration for aesthetic-conscious buyers. Recreational segments in sun-belt states favor UV-resistant formulations despite weight penalties versus aluminum.
- Steel:Powder-coated carbon steel retains position in entry price tiers and specialized security applications. General consumer demand concentrates where initial acquisition cost outweighs fuel economy considerations.
- Plastic:Reinforced ABS and thermoplastic olefin compounds serve drop-in replacement markets and budget-sensitive channels. Limited structural load ratings constrain adoption beyond light-duty recreational use.
Aluminum commands current volume; fiberglass defends premium aesthetic positioning.
End User:
Application-driven specification divergence separates fleet procurement standardization from enthusiast customization, with margin structure inversely correlating to purchase volume scale.
- Commercial:Logistics operators standardize locking hard covers to reduce cargo theft exposure and insurance premium escalation. Fleet purchasing consolidates around aluminum folding platforms with centralized locking and no-drill installation to preserve vehicle warranty coverage.
- Recreational:Weekend adventure seekers prioritize bed accessibility for gear mounting and campsite utility. Retractable and tri-fold configurations dominate this segment where convenience outweighs maximum security requirements.
- Automotive Enthusiasts:Paint-matched hard shells and integrated lighting systems command premium pricing. This segment tolerates longer lead times for custom fabrication and specialized finish matching.
- General Consumers:Price-sensitive pickup owners select entry-level rolling or clamp-on folding covers for basic weather protection. Distribution concentrates through mass retail and direct-to-consumer e-commerce channels.
Commercial fleets drive volume scale; enthusiasts capture margin expansion.
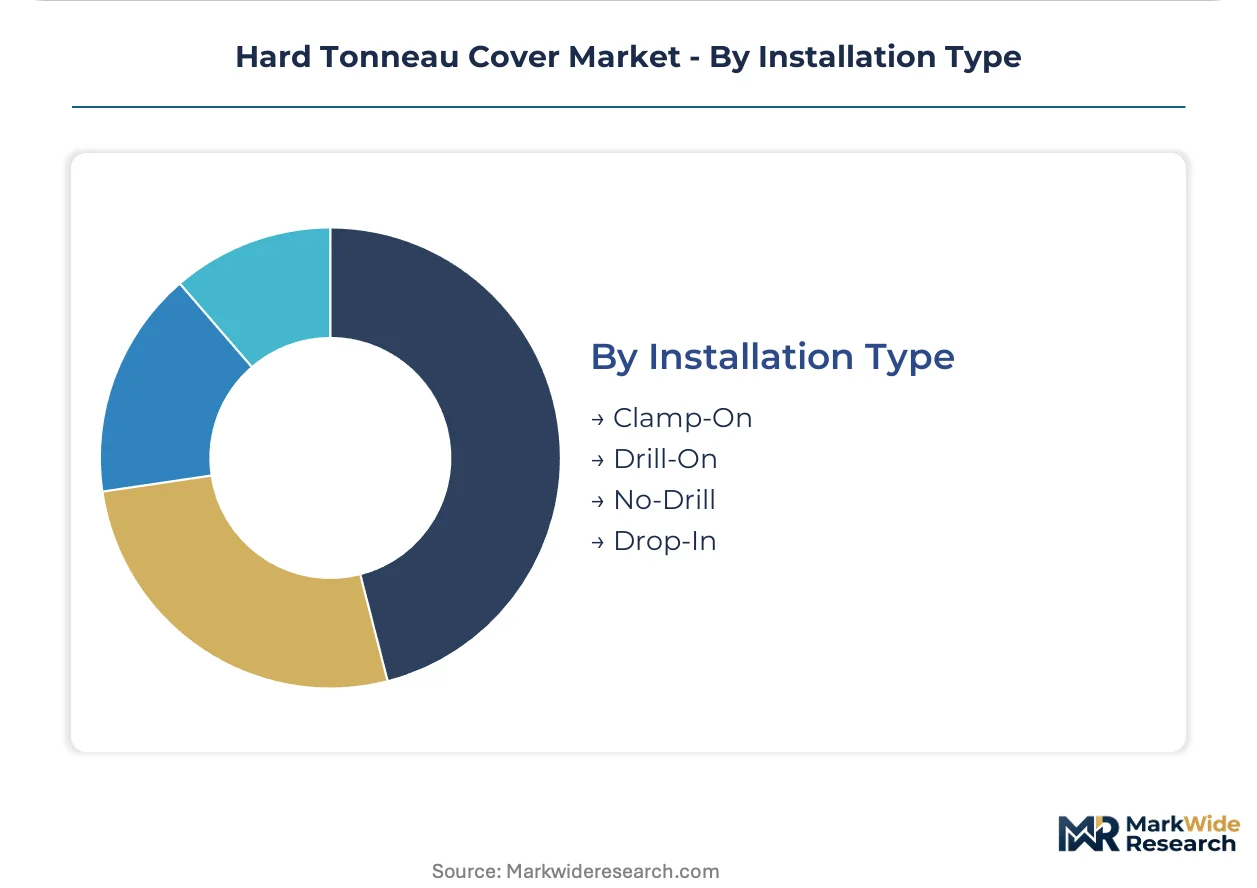
Installation Type:
Customer type fragmentation between warranty-conscious fleet buyers and DIY-capable consumers determines installer network economics and product liability allocation.
- No-Drill:Clamp rail systems engage bed rail caps without sheet metal penetration, eliminating corrosion risk and OEM warranty disputes. California and Texas vehicle modification codes increasingly favor this methodology for commercial fleet compliance.
- Clamp-On:Stake pocket-mounted brackets enable tool-free attachment on compatible truck configurations. Recreational buyers value seasonal removal capability for bed liner maintenance.
- Drill-On:Permanent rail mounting through bed sheet metal provides maximum structural integrity for heavy-load applications. Declining share reflects warranty liability fragmentation between installers, manufacturers, and vehicle OEMs.
- Drop-In:Bed rail cap replacement systems integrate cover mounting into factory stake pocket geometry. Limited platform compatibility constrains SKU proliferation for national distribution.
No-Drill installations lead current preference; Clamp-On formats gain enthusiast traction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hard tonneau cover manufacturing originated in the United States during the post-war pickup truck boom, with Detroit-area metalworkers pioneering fiberglass shell fabrication for commercial fleets. The industry subsequently diffused to aluminum fabrication centers in Canada and Mexico, following the regionalization of North American automotive supply chains under successive trade agreements.
United States
Full-size pickup truck ownership underpins category volume, with Texas and California accounting for disproportionate fleet procurement. NHTSA visibility standards constrain cover geometry design, particularly for models integrating with backup camera systems. Houston hosts the densest concentration of certified aftermarket installers, where commercial logistics operators standardize aluminum folding platforms for fuel economy certification.
Canada
Resource extraction industries in Alberta and British Columbia drive demand for heavy-load-rated hard shells on work trucks. Transport Canada maintains alignment with FMVSS standards while adding cold-weather durability requirements for latch mechanisms. The Greater Toronto Area anchors distribution infrastructure serving cross-border fleet operators with harmonized no-drill installation protocols.
Mexico
Automotive assembly plants in Nuevo León and the Bajío Region generate OEM supply contracts for hard tonneau cover fabricators. Mexican labor cost advantages support aluminum component manufacturing for re-export to United States aftermarket channels. Monterrey-based metalworking clusters specialize in extruded rail systems for clamp-compatible folding platforms.
Germany
Precision engineering capabilities in Baden-Württemberg and Bavaria support retractable cover mechanism production for premium European pickup segments. KBA type-approval requirements enforce rigorous load-testing protocols exceeding North American standards. Stuttgart-area suppliers leverage automotive supplier networks to develop motorized actuation systems for high-end applications.
Australia
Rural utility vehicle culture in Queensland and Western Australia sustains demand for hard shell covers rated for roof-load compatibility. The Australian Design Rules mandate specific weather-sealing performance for outback operating conditions. Melbourne-based fabricators serve mining fleet operators with powder-coated steel platforms optimized for corrosion resistance in coastal environments.
Hard Tonneau Cover Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material specification and installation methodology tiers, with aluminum-intensive designs commanding price premiums over vinyl-over-aluminum alternatives. The vendor base organizes into three strategic archetypes: OEM-integrated suppliers with Detroit automaker contracts, aftermarket specialists with certified installer networks, and direct-to-consumer e-commerce platforms. Capacity expansion and portfolio diversification dominate competitive moves, as fabricators add retractable and electrification-ready configurations to folding-centric product lines.
Among United States-based specialists, UnderCover and BAK Industries exemplify the premium-tier positioning built around proprietary sealing technologies and no-drill rail systems. Rough Country anchors the value-tier segment through aggressive pricing on aluminum folding platforms. LEER occupies a distinctive position as the dominant OEM-channel supplier, with long-standing supply relationships underpinning original equipment fitment on Detroit-manufacturer vehicles.
| Leading Market Players |
|---|
| UnderCover |
| Rough Country |
| BAK Industries |
| Tyger Auto |
| Pace Edwards |
| Extang |
| LEER |
| INEXRUD |
| Worksport |
| Others |
Supply & Pricing Matrix
Certified aftermarket installer networks in Texas and California create labor-cost differentials that widen pricing-tier spreads between premium no-drill platforms and economy drill-on alternatives, with rural buyers facing geographic access premiums that compress margin capture for mid-market fabricators.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates paint-matched fiberglass hard shells from aluminum folding platforms and vinyl-over-aluminum rolling covers, with quality grade and installation methodology driving differentiation. Price differentiation reflects NHTSA compliance certification costs and no-drill rail system complexity. Cost compression in the economy tier is intensifying because resin compounders pass through energy-indexed raw material volatility. Fleet procurement managers demonstrate lowest price sensitivity due to fuel economy certification ROI, while general consumers exhibit highest elasticity to initial acquisition cost.
Supply Chain Analysis
Aluminum sheet and extruded rail supply rests on primary smelting capacity in Canada, Mexico, and the United States, with 5052-H32 and 6061-T6 alloy specifications drawing from energy-intensive electrolytic production concentrated in Quebec and the American Southwest. Reinforced ABS compounds and gel-coat resins feed from petrochemical complexes along the Gulf Coast. Single-source vulnerability in aerospace-grade aluminum rolling mills creates supply chain risk for premium platform fabricators. Distribution runs through certified installer networks in Texas and California, direct-to-consumer e-commerce platforms, and OEM supply contracts with Detroit automakers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Mexican aluminum component manufacturing labor costs and United States fleet procurement willingness-to-pay for EPA fuel economy certification compliance.
For Market Incumbents: Hedge margin exposure to aluminum price volatility through backward integration into extruded rail production or long-term offtake agreements with Quebec smelters. Defend installer network density in Texas against emerging direct-to-consumer platforms by embedding sensor-integration capabilities that require professional calibration. Prioritize R&D investment in electrification-ready solar-mounting channels to capture fleet pre-positioning for electric pickup adoption. For New Entrants and Emerging Players: Begin with retractable platform motorized actuation systems, where German precision engineering capabilities create white-space opportunity below premium European positioning. Target California recreational buyers seeking fifth-wheel hitch compatibility, a segment where established players underinvest in rail integration complexity. Pursue go-to-market partnerships with national retail chains requiring documented no-drill installer certification. For Investors and Strategic Acquirers: Automotive supplier conglomerates seeking pickup truck accessory portfolio expansion are the most active acquirer in this space, with platform standardization across Ford, General Motors, and Stellantis lineups creating scale economics for bolt-on acquisitions. Long-term viability hinges on electrification-ready product architecture compatibility. Monitor EPA fuel economy testing protocol enforcement tightening as inflection indicator for aerodynamic bed enclosure demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Extrusion | Quebec smelter proximity reduces energy-cost exposure for rail system production. |
| Sensor-Integration Platform Development | NHTSA backup camera compliance creates premium upgrade path for safety-conscious fleet buyers. |
| Direct-to-Consumer Channel Expansion | E-commerce platforms recapture margin from traditional brick-and-mortar accessory retailers. |
| Installer Certification Program Investment | Texas training center economics support national warranty-backed installation network density. |
| Electrification-Ready Product Architecture | Solar panel mounting channels preserve bed functionality for electric pickup fleet pre-positioning. |
Research Methodology
Direct dialogue with aftermarket distribution channel managers, certified installation network operators, fleet procurement directors at logistics operators, and aluminum fabrication plant managers grounded qualitative assessment, combined with secondary validation from NHTSA FMVSS interpretation documents, EPA fuel economy certification databases, SEC 10-K filings of automotive suppliers, and vehicle production registration data from IHS Markit. Bottom-up demand aggregation across product architecture, material specification, and end-user segments triangulated against top-down market sizing from trade flow analysis.
Segment-level value and volume trajectories across the analysis window reflect econometric modeling of aluminum price elasticity, fleet procurement cycle timing, and regulatory compliance cost pass-through. Modeled dimensions include product type, material alloy grade, installation methodology, and end-user application intensity. CAGRs derive from regression-based projection of historical adoption patterns against fleet electrification readiness indicators and state-level vehicle modification code harmonization momentum.
Several conditions sit outside the modeled scope, including unannounced Detroit automaker platform architecture changes, abrupt aluminum tariff regime shifts, and NHTSA rear-visibility standard reinterpretations affecting cover geometry constraints. Material deviation in aluminum smelting energy costs, fleet electrification adoption curves, or no-drill installation code harmonization timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy-Duty Trucks
Truck Headache Rack Market
Heavy-Duty Trucks
Heavy-Duty Vehicle Engine Brake Market
Heavy-Duty Trucks
Airport Catering Truck Market
Heavy-Duty Trucks
Articulated Hauler Market
Heavy-Duty Trucks
Europe Fire Truck Market
Heavy-Duty Trucks
Big Rig Trucks Market
Heavy-Duty Trucks
Europe Medium & Heavy-Duty Truck Rental Market
Heavy-Duty Trucks
Logging Trucks Market
Heavy-Duty Trucks
Articulated Dump Trucks Market
Heavy-Duty Trucks
Full Truckload Transportation Market
Heavy-Duty Trucks
Heavy-Duty Truck Fleet Control Unit Architectures Market
Heavy-Duty Trucks
Dump Truck & Body Market
Heavy-Duty Trucks
Asia Pacific Garbage Truck Bodies Market
Heavy-Duty Trucks
China Full-Truck-Load (FTL) Market
Heavy-Duty Trucks
Heavy-Truck Composite Component Market
Heavy-Duty Trucks
Dump Trucks Market