
 Temperature-Controlled Last-Mile Delivery Services Market | 2026-2036
Temperature-Controlled Last-Mile Delivery Services Market Size, Share, and Industry Trends Forecast 2026-2036
Temperature-Controlled Last-Mile Delivery Services Market Insights
Real-time IoT telemetry is narrowing the gap between warehouse climate systems and vehicle-mounted refrigeration units, creating continuous temperature visibility from origin to doorstep. DHL Supply Chain leverages its pharmaceutical-certified network across Europe and North America to anchor high-value biologics contracts. FedEx sustains competitive position through its SenseAware monitoring platform, which extends traceability into patient-direct delivery. JD Logistics dominates same-day chilled fulfillment in Chinese urban corridors, operating proprietary refrigerated micro-fulfillment nodes.
Temperature-controlled last-mile delivery denotes the short-haul transport of thermosensitive goods using active or passive cooling systems maintained within specified ranges, typically minus 80°C to plus 8°C for pharmaceuticals and 0°C to 4°C for fresh food categories, with telematics logging interval data at 15-minute increments or less to prove chain-of-custody compliance. Cold chain services within the service type dimension capture the dominant margin pool due to pharmaceutical payload premiums and insurance requirements, while drone vehicle types represent the fastest-growing segment as regulators in the United States and United Arab Emirates approve beyond-visual-line-of-sight routes for vaccine distribution. Chilled transport applications for perishables remain structurally mature with compressed margins, forcing providers to compete on route density and reverse logistics efficiency.
The FDA enforces current Good Distribution Practice standards that mandate documented temperature controls for biologics, directly shaping fleet investment decisions among third-party logistics operators. In Europe, the EU GDP guidelines and F-Gas Regulation jointly constrain refrigerant choices and mandate equipment upgrade cycles that favor electric refrigeration units. China's NMPA and SAMR have tightened import cold chain requirements for overseas vaccines, creating compliance barriers that only providers with certified cross-border infrastructure can navigate. Stakeholders must monitor regulatory divergence across jurisdictions as divergent refrigerant phase-out timelines and data localization requirements determine which providers can operate profitably at scale.
Market Dynamics
Cell and gene therapy commercialization is compressing delivery windows from days to hours, forcing logistics networks to reconfigure around patient-centric fulfillment nodes rather than traditional distribution centers.
Growth Catalysts
- FDA Cold Chain Integrity Mandates:Updated guidance on biologics distribution requires continuous temperature logging, compelling 3PLs to retrofit fleets with IoT sensor arrays.
- Cell Therapy Manufacturing Concentration:Production clusters in Massachusetts and North Carolina generate radiating demand for ultra-low-temperature last-mile capacity.
- Electric Refrigeration Units:Advancements in battery-thermal management systems enable extended range without diesel auxiliary power, reducing payload penalties.
Market Restraints
- Refrigerant Supply Concentration:EU F-Gas Regulation phase-out timelines constrain hydrofluorocarbon availability, elevating unit retrofit costs for European operators.
- Sensor Hardware Fragmentation:Proprietary telematics protocols from equipment manufacturers create integration friction with fleet management platforms.
- Dry Ice Substitution Limits:Carbon dioxide supply volatility in pharmaceutical corridors restricts passive cooling options for ultra-cold payloads.
Strategic Opportunities
- Indian Cold Chain Modernization:FSSAI enforcement of food safety standards in tier-2 cities creates compliant infrastructure gaps for organized logistics entrants.
- Drone Beyond-Visual-Line-of-Sight Routes:FAA and UAE GCAA approvals for vaccine distribution open last-mile networks in rural and island geographies.
- Reverse Logistics Integration:Return of temperature-sensitive clinical trial materials from investigative sites remains underserved, offering margin expansion.
Industry Challenges
- Certified Technician Scarcity:EPA Section 608 and F-Gas certification requirements for refrigerant handling outpace vocational training pipeline output.
- Multi-Temperature Zone Complexity:Single vehicles must simultaneously maintain frozen, chilled, and ambient compartments, complicating routing algorithms and load planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Temperature-Controlled Last-Mile Delivery Services Market |
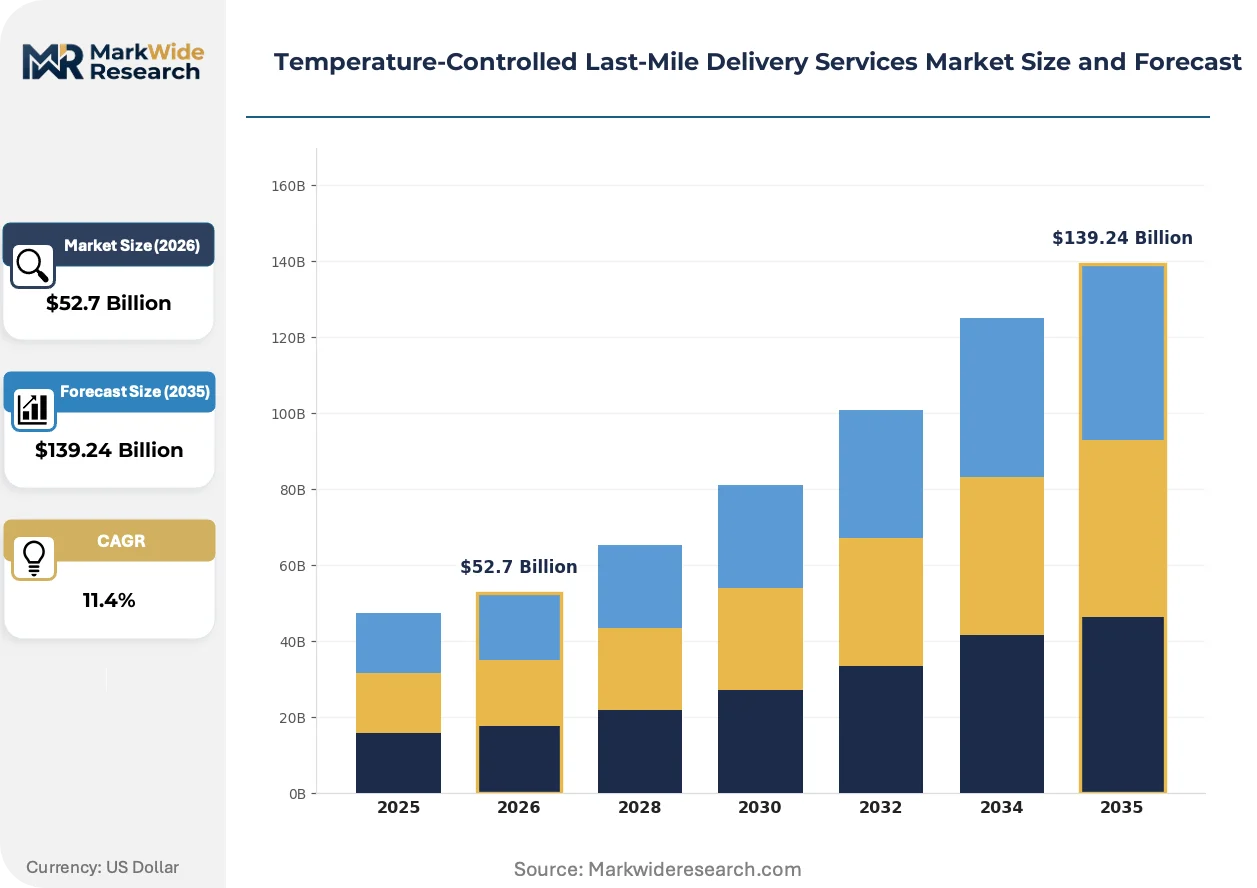
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $139.24 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cold Chain, Frozen Logistics, Chilled Transport, Ambient Shipping Application: Pharmaceuticals, Perishables, Biotechnology, Floral Products, Gourmet Foods Vehicle Type: Refrigerated Vans, Insulated Trucks, Cargo Bikes, Drones Customer Type: Pharmacies, Food Retailers, Research Institutions, Specialty Outlets |
| Companies Covered | DHL Supply Chain, United Parcel Service, FedEx, SF Express, JD Logistics, Lineage Logistics, Americold Logistics, DoorDash, Instacart, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Temperature-Controlled Last-Mile Delivery Services Market Trends and Innovations
Real-time visibility infrastructure is collapsing the information lag between shipper and recipient, enabling proactive intervention before temperature excursions breach regulatory thresholds.
Blockchain-anchored temperature logs are digitizing chain-of-custody documentation for pharmaceutical shipments. Cell therapy manufacturers in the United States and Germany now require immutable audit trails as a condition of contract award. This shift is compressing competitive differentiation around data integrity rather than pure transport speed.
EU F-Gas Regulation is accelerating refrigerant transition timelines across European cold chain fleets. Operators face mandatory equipment replacement cycles that favor CO2 transcritical systems over traditional HFC-based units. Pharmaceutical-certified providers in Germany and the Netherlands are absorbing capex premiums to maintain GDP compliance.
Hospital and pharmacy buyers are consolidating vendor relationships around integrated cold chain service providers. Standalone transport contracts are yielding to bundled offerings that encompass packaging, monitoring, and compliance documentation. This pattern concentrates most visibly in United States specialty pharmacy networks and Japanese hospital group purchasing organizations.
Temperature-Controlled Last-Mile Delivery Services Market Segmentation
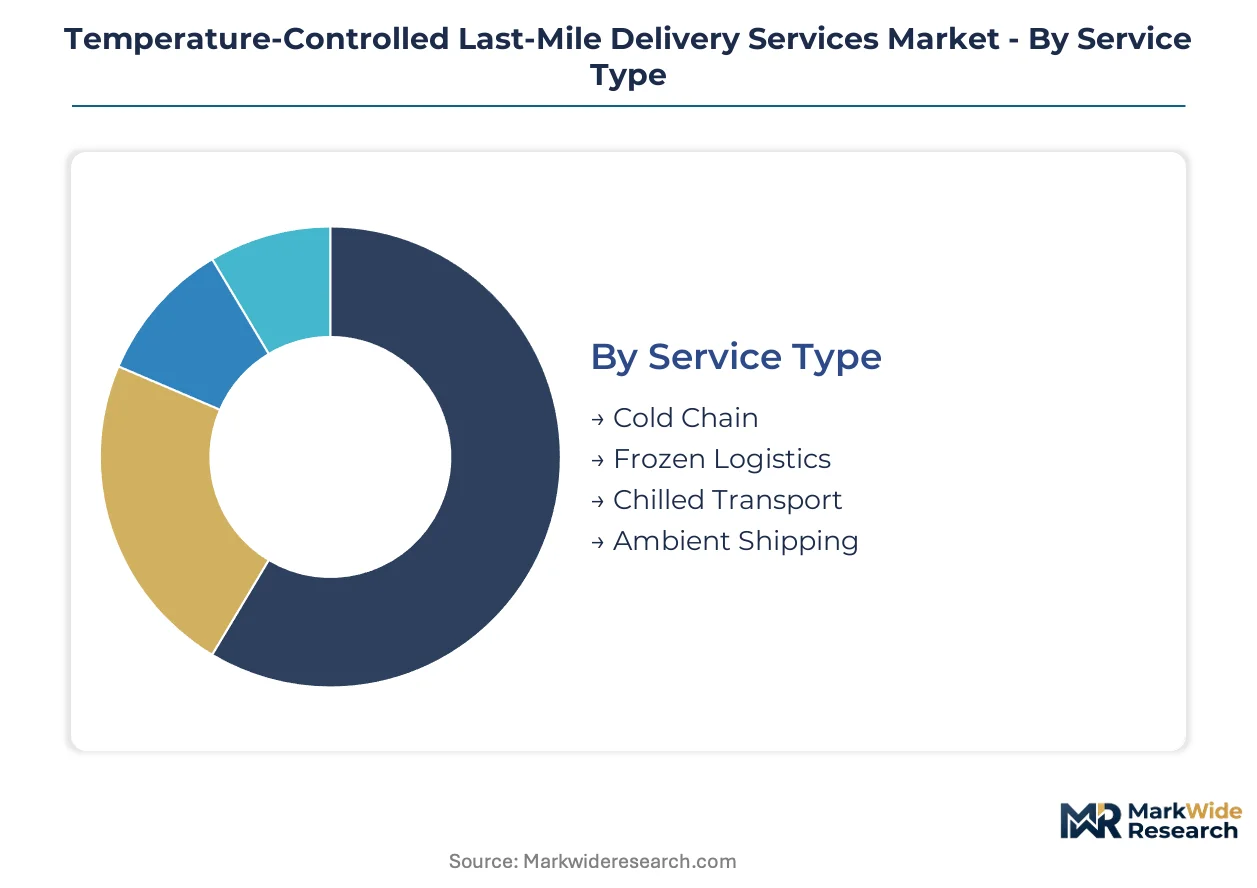
Temperature-controlled last-mile delivery demands precise segment alignment between payload thermal requirements and equipment specifications. Service contracts now bundle compliance documentation with physical transport, raising the service intensity threshold for every segment.
Service Type:
After-sales service intensity varies dramatically across thermal protocols, with pharmaceutical-certified cold chain operations requiring 24/7 monitoring support and excursion response teams.
- Cold Chain:Continuous temperature maintenance between minus 80°C and plus 8°C using active refrigeration or validated passive packaging. Pharmaceutical distributors in Massachusetts and North Carolina drive demand concentration as cell therapy manufacturing clusters expand. FDA GDP mandates force providers to maintain redundant sensor arrays and certified response protocols.
- Frozen Logistics:Sustained transport below minus 18°C for biologics and specialty food categories. Dry ice substitution limits in major pharmaceutical corridors constrain capacity scaling for ultra-cold payloads.
- Chilled Transport:Zero to 4°C maintenance for fresh food and short-shelf-life pharmaceuticals. Grocery delivery platforms in the United States deploy captive fleets to control perishable quality at checkout.
- Ambient Shipping:Climate-protected transport without active cooling for stable pharmaceuticals and shelf-stable goods. Lower compliance burden attracts price-competitive regional operators.
By volume, Chilled Transport leads. By growth pace, Cold Chain is ahead.
Application:
Cost tier stratification separates premium biologics transport from commoditized perishable fulfillment, with certification requirements determining pricing bands.
- Pharmaceuticals:Temperature-sensitive drugs, vaccines, and biologics requiring GDP-compliant documentation. Cell and gene therapy commercialization compresses delivery windows from days to hours.
- Perishables:Fresh produce, dairy, and meat categories with 0°C to 4°C requirements. Route density and reverse logistics efficiency separate profitable operators from margin-challenged competitors.
- Biotechnology:Clinical trial materials, laboratory specimens, and research reagents. Return logistics from investigative sites remains structurally underserved.
- Floral Products:Humidity-controlled chilled transport extending vase life for premium cultivars. Specialty outlets in urban corridors drive consolidation around integrated cold chain providers.
- Gourmet Foods:Artisan cheese, craft chocolate, and premium seafood with narrow temperature windows. Small-batch producers absorb packaging premiums to access direct-to-consumer channels.
Pharmaceuticals command the highest revenue per kilogram. Perishables move the largest aggregate tonnage.
Vehicle Type:
Application specificity dictates equipment selection, with multi-temperature zone vehicles commanding procurement premiums for pharmaceutical route diversity.
- Refrigerated Vans:Light commercial vehicles with electric or engine-driven compressor systems. Battery-thermal management advancements enable extended range without diesel auxiliary power.
- Insulated Trucks:Heavy-duty chassis with multi-compartment temperature zones for consolidated pharmaceutical and food loads. Single-vehicle frozen-chilled-ambient capability complicates load planning algorithms.
- Cargo Bikes:Human-powered or electric-assisted last-mile units with passive cooling inserts. Urban congestion zones in European cities favor zero-emission payload capacity.
- Drones:Autonomous aerial systems with thermal payload compartments. FAA and UAE GCAA beyond-visual-line-of-sight approvals open rural and island vaccine distribution networks.
Refrigerated Vans dominate installed fleet count. Drones are climbing the fastest.
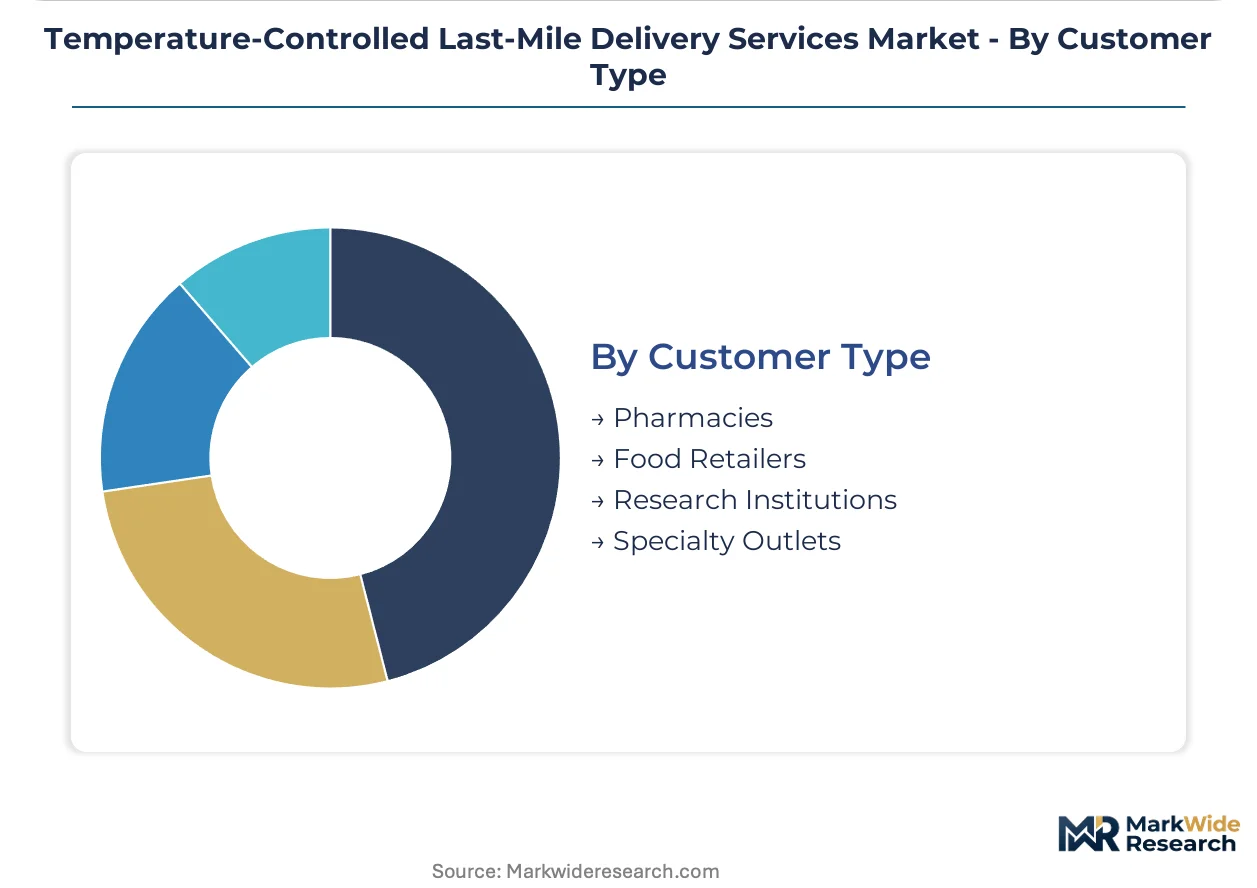
Customer Type:
Customer procurement maturity separates integrated cold chain buyers from transactional transport purchasers, with vendor consolidation accelerating among sophisticated accounts.
- Pharmacies:Retail and specialty dispensaries requiring patient-direct delivery for temperature-sensitive prescriptions. United States specialty pharmacy networks bundle packaging, monitoring, and compliance documentation.
- Food Retailers:Grocery chains and meal-kit platforms building captive chilled fleets for same-day fulfillment. Major chains in the United States prioritize reverse logistics efficiency for reusable packaging.
- Research Institutions:Universities, hospitals, and contract research organizations moving clinical specimens and trial materials. Immutable audit trail requirements compress competitive differentiation around data integrity.
- Specialty Outlets:Independent florists, gourmet shops, and boutique food producers with sporadic high-value shipments. Smaller accounts absorb per-delivery premiums for certified cold chain access.
Food Retailers generate the highest shipment frequency. Pharmacies are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmacy chains and grocery delivery platforms in the United States concentrate buying power, while cell therapy manufacturing clusters in Germany and China pull specialized cold chain investment toward regional production nodes.
United States
Specialty pharmacy networks and grocery delivery platforms deploy captive chilled fleets for same-day fulfillment. FDA GDP mandates on biologics distribution force continuous temperature logging retrofits across third-party logistics operators. The Greater Boston and Research Triangle Park corridors generate radiating demand for ultra-low-temperature last-mile capacity as cell therapy manufacturing concentrates.
Germany
Pharmaceutical-certified providers absorb capex premiums to maintain EU GDP compliance amid CO2 transcritical system transitions. The EU F-Gas Regulation accelerates refrigerant phase-out timelines, constraining hydrofluorocarbon availability for fleet operators. Industrial clusters in North Rhine-Westphalia and Baden-Württemberg anchor pharmaceutical distribution networks serving European biologics markets.
China
Same-day chilled fulfillment dominates urban corridors through proprietary refrigerated micro-fulfillment nodes. NMPA and SAMR tightening of import cold chain requirements for overseas vaccines creates compliance barriers favoring certified cross-border infrastructure providers. The Yangtze River Delta and Pearl River Delta manufacturing belts concentrate demand for temperature-sensitive pharmaceutical logistics.
India
FSSAI enforcement of food safety standards in tier-2 cities generates compliant infrastructure gaps for organized logistics entrants. The country's national pharmaceutical regulator maintains import cold chain requirements that elevate certification thresholds for vaccine distribution. Maharashtra and Gujarat industrial corridors concentrate pharmaceutical manufacturing that pulls specialized refrigerated transport investment.
United Arab Emirates
GCAA beyond-visual-line-of-sight approvals for vaccine distribution open last-mile networks in rural and island geographies. The national aviation regulator's drone route authorizations enable autonomous aerial systems with thermal payload compartments. Dubai and Abu Dhabi logistics free zones concentrate pharmaceutical transshipment activity linking Asian manufacturing to African and Middle Eastern markets.
Temperature-Controlled Last-Mile Delivery Services Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where pharmaceutical-certified networks command premium positioning. The market exhibits consolidation around integrated cold chain service providers as hospital and pharmacy buyers bundle packaging, monitoring, and compliance documentation. Three archetypes dominate: global express networks with pharmaceutical certification, regional cold chain specialists with GDP-compliant infrastructure, and captive fleets operated by grocery and pharmacy chains. Competitive moves center on M&A for certified facility acquisition and strategic partnerships for last-mile density in urban corridors.
Among global express networks, DHL Supply Chain and FedEx occupy positions anchoring high-value biologics contracts through pharmaceutical-certified infrastructure. JD Logistics exemplifies the regional captive fleet archetype, operating proprietary refrigerated micro-fulfillment nodes that dominate same-day chilled fulfillment in Chinese urban corridors. These three represent distinct strategic paths: certification-led pharmaceutical specialization, technology-enabled monitoring platforms, and vertically integrated urban logistics density.
| Leading Market Players |
|---|
| DHL Supply Chain |
| United Parcel Service |
| FedEx |
| SF Express |
| JD Logistics |
| Lineage Logistics |
| Americold Logistics |
| DoorDash |
| Instacart |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in European refrigerated transport capacity is elevating spot pricing volatility and compelling pharmaceutical shippers to absorb multi-year contract premiums for guaranteed GDP-compliant capacity.
Pricing Analysis
Cost-plus contracts with diesel and electricity indexation dominate pharmaceutical cold chain procurement, insulating providers from fuel volatility while passing refrigerant cost escalations to buyers. Price differentiation rests on GDP certification tier and real-time telemetry granularity, with FDA-validated sensor arrays commanding premiums over basic temperature logging. Pricing pressure stems from grocery delivery platforms building captive fleets that bypass third-party margins. Food retailers exhibit acute price sensitivity, while cell therapy manufacturers prioritize compliance over cost.
Supply Chain Analysis
Extended payment terms from pharmaceutical distributors are compressing working capital for equipment manufacturers, accelerating supply-chain finance facility adoption among refrigeration unit suppliers. Manufacturing concentrates in Germany, China, and the United States for compressor systems and IoT sensor arrays. Fleet operators draw from lithium battery cells, specialized refrigerants, and telematics hardware. Single-source vulnerability in CO2 refrigerant supply chains poses structural risk. Distribution runs through pharmaceutical-certified 3PL networks and captive retail fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The temperature-controlled last-mile delivery market is experiencing high-growth disruption as cell therapy commercialization compresses delivery windows from days to hours, forcing infrastructure reconfiguration around patient-centric fulfillment nodes.
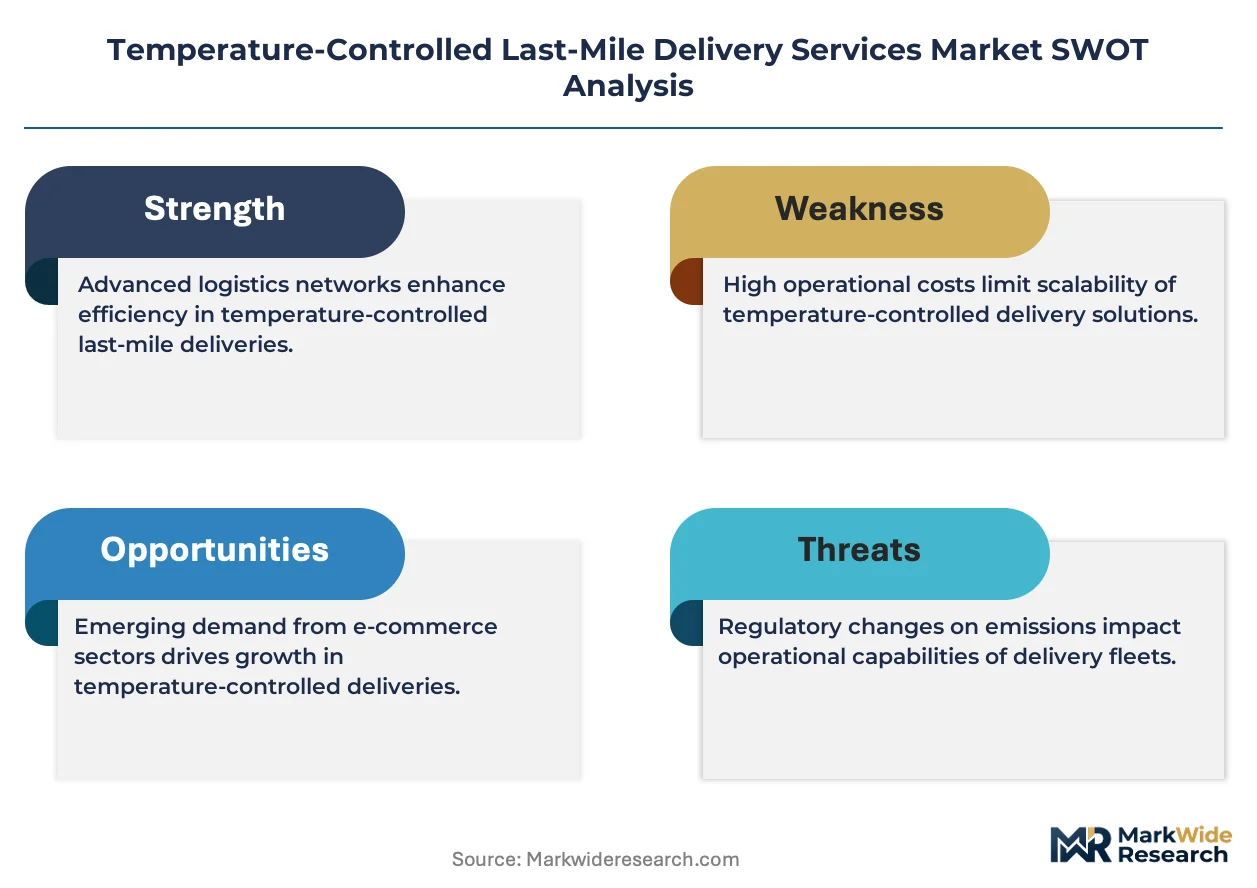
For Market Incumbents: Harden pharmaceutical-certified network positions through M&A for GDP-compliant facility acquisition, particularly in Massachusetts and North Carolina cell therapy corridors. Invest in redundant sensor arrays and 24/7 excursion response teams to defend against emerging technology-enabled monitoring specialists. Prioritize electric refrigeration unit retrofit programs to preempt EU F-Gas Regulation compliance penalties. For New Entrants and Emerging Players: Pursue reverse logistics integration for temperature-sensitive clinical trial materials, a structurally underserved segment with margin expansion potential. Target tier-2 Indian cities where FSSAI enforcement has created compliant infrastructure gaps for organized logistics entrants. Lead with drone-based vaccine distribution in GCAA-approved UAE corridors to establish beyond-visual-line-of-sight operational credentials. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electric refrigeration fleet transitions as battery-thermal management systems and CO2 transcritical units demand elevated capex deployment. Long-term viability favors providers with cross-border certified infrastructure capable of navigating divergent regulatory timelines. Acquisition focus should center on regional cold chain specialists with GDP-compliant networks in pharmaceutical manufacturing clusters. Monitor FAA drone route authorization velocity as inflection indicator for autonomous last-mile network scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Fleet Transition | CO2 transcritical refrigeration systems enable EU F-Gas Regulation compliance while reducing diesel auxiliary power penalties. |
| Real-Time Telemetry Integration | IoT sensor arrays logging 15-minute interval data satisfy FDA GDP mandates for continuous temperature visibility. |
| Patient-Centric Node Deployment | Micro-fulfillment positioning near cell therapy manufacturing clusters compresses delivery windows to hours. |
| Drone Route Authorization | FAA and GCAA beyond-visual-line-of-sight approvals unlock rural and island vaccine distribution networks. |
| Reverse Logistics Capability Buildout | Return logistics for clinical trial materials from investigative sites captures underserved margin pools. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade databases, and fleet operator disclosures across the temperature-controlled logistics sector. Primary interviews engaged cold chain operations directors, pharmaceutical distribution executives, fleet procurement managers, and regulatory compliance officers at GDP-certified providers. Secondary sources included FDA guidance documents, EU F-Gas Regulation implementation reports, NMPA import cold chain requirements, and customs data on refrigerated transport equipment trade flows. Bottom-up fleet capacity estimates and top-down pharmaceutical shipment value projections were triangulated to anchor market sizing.
Forecast inputs span service type segmentation across cold chain, frozen logistics, chilled transport, and ambient shipping; vehicle type disaggregation covering refrigerated vans, insulated trucks, cargo bikes, and drones; and application dimensions spanning pharmaceuticals, perishables, biotechnology, and gourmet foods. CAGRs were derived from elasticity modeling against pharmaceutical biologics growth, cell therapy commercialization curves, and grocery e-commerce penetration rates. Electric refrigeration adoption timelines and refrigerant phase-out schedules informed equipment replacement cycle assumptions.
Macroeconomic conditions sit as an overlay; deviation in diesel and electricity pricing, carbon credit valuations, or pharmaceutical R&D funding levels would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement intensity and technology cost curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Transportation Vehicle Automated Passenger Counting (APC) System Market
Smart Transportation Solutions
Rail Internet of Things (IoT) Market
Smart Transportation Solutions
Automatic Identification Systems (AIS) Market
Smart Transportation Solutions
E-Scooter Sharing Market
Smart Transportation Solutions
Traffic Management System Market
Smart Transportation Solutions
Global Parking Meter Apps Market
Smart Transportation Solutions
Rail Freight Digital Transformation Market
Smart Transportation Solutions
Electric Kick Scooters Market
Smart Transportation Solutions
Sustainable Last-Mile Delivery Network Design Services Market
Smart Transportation Solutions
Smart Bus Shelters Market
Smart Transportation Solutions
Car E-Hailing Market
Smart Transportation Solutions
Europe Car Parking Market
Smart Transportation Solutions
North America IoT Transportation Market
Smart Transportation Solutions
Road Asset Management Software Market
Smart Transportation Solutions
Vehicle As a Service Market
Smart Transportation Solutions
Mobility As a Service Market