
 Semi-Tractor Trailer Market | 2026-2036
Semi-Tractor Trailer Market Size, Share, and Industry Trends Forecast 2026-2036
Semi-Tractor Trailer Market Analytics
The shortage of certified diesel technicians and commercial vehicle operators is reorganizing fleet management strategies across the heavy-duty logistics sector. Wabash National leverages its composite materials expertise to differentiate refrigerated trailer offerings against traditional steel builds. Schmitz Cargobull sustains manufacturing scale advantages across European production centers while extending quality systems into North American assembly operations. Great Dane anchors its market position through specialized tank trailer engineering for chemical and food-grade transport applications.
A semi-tractor trailer consists of a powered tractor unit coupled to one or more unpowered trailers, with gross combination weights typically ranging from 80,000 pounds in the United States to higher permitted loads in select Australian and Nordic jurisdictions, designed primarily for long-haul freight movement and intermodal container transfer. Dry van trailers occupy the largest product category by unit volume, serving the non-perishable goods backbone of retail distribution networks, while refrigerated trailers command premium pricing through specialized insulation and temperature control systems for pharmaceutical and fresh food supply chains. Tandem axle configurations dominate highway freight operations due to load distribution efficiency, though lift axle systems are gaining traction in jurisdictions with variable weight regulations and bridge formula compliance requirements.
The Federal Motor Carrier Safety Administration enforces hours-of-service rules and electronic logging device mandates that directly constrain fleet utilization rates and drive trailer count expansion to maintain shipping capacity. EPA greenhouse gas Phase 3 standards, alongside California Air Resources Board advanced clean trucks regulations, are forcing powertrain diversification and aerodynamic trailer requirements that alter total cost of ownership calculations for freight operators. Stakeholders must monitor the pace of charging infrastructure deployment along major freight corridors and the evolving resale value trajectory of diesel assets as zero-emission mandates phase in across multiple state jurisdictions.
Market Dynamics
EPA Phase 3 greenhouse gas standards are forcing fleet operators to recalculate total cost of ownership around aerodynamic trailers and alternative powertrains, compressing diesel asset residual values while accelerating trailer specification changes.
Growth Catalysts
- E-commerce fulfillment networks:Parcel carriers and third-party logistics providers are expanding trailer pools to maintain velocity across California-Texas-Tennessee distribution corridors.
- California Air Resources Board advanced clean trucks regulation:Zero-emission mandates in the country's largest freight market are pulling forward demand for compatible trailer aerodynamics and weight reduction.
- Composite material substitution:Refrigerated trailer manufacturers are replacing steel structural members with fiber-reinforced polymers to improve thermal efficiency and payload capacity.
Market Restraints
- Aluminum and steel input volatility:Trailer manufacturers face margin compression from commodity price swings in structural metals and refrigeration unit copper coils.
- Certified technician scarcity:The shortage of diesel and electric powertrain specialists constrains fleet maintenance capacity and extends vehicle downtime.
- Bridge formula compliance complexity:Variable state weight regulations force operators to spec lift axle systems that add capital cost without generating revenue miles.
Strategic Opportunities
- Platooning and autonomous convoy technology:Freight carriers in Texas and Nevada test corridors are piloting linked-tractor configurations that reduce fuel consumption through aerodynamic drafting.
- Pharmaceutical cold chain expansion:Temperature-validated trailer demand is accelerating from vaccine distribution infrastructure and biologics transport requirements.
- Utility-managed charging infrastructure:Electric tractor deployment depends on corridor-based megawatt charging stations along I-40 and I-10 freight routes.
Industry Challenges
- Commercial driver availability:Fleet operators compete for qualified operators against construction and energy sector wage premiums.
- Electronic logging device integration:Hours-of-service compliance systems require ongoing software updates and driver training across mixed fleet ages.
- Resale value uncertainty:Diesel tractor residual pricing faces compression as zero-emission phase-in dates approach in multiple state jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semi-Tractor Trailer Market |
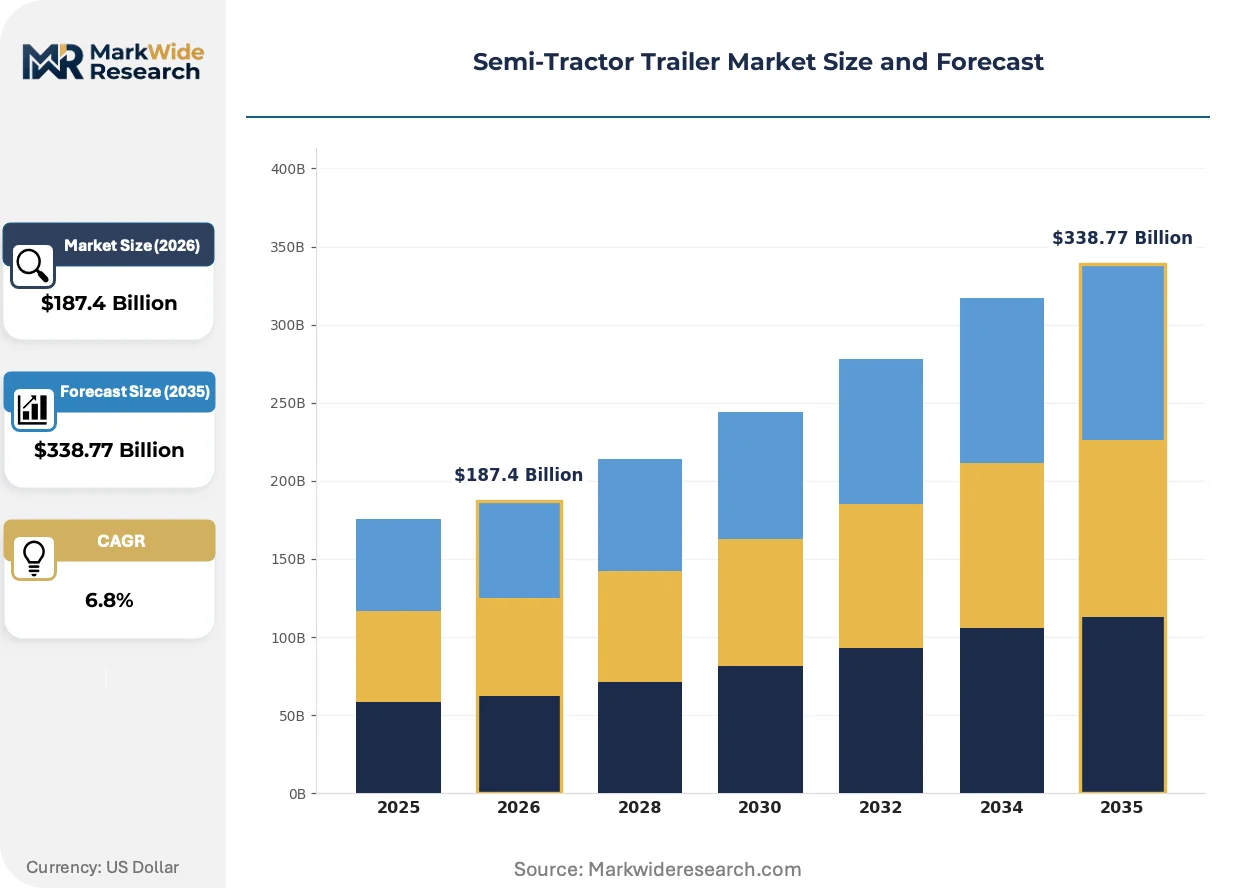
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flatbed Trailers, Refrigerated Trailers, Tank Trailers, Dry Van Trailers End User: Freight Companies, Logistics Providers, Retail Distributors, Construction Firms Vehicle Configuration: Single Axle, Tandem Axle, Tri-Axle, Lift Axle Material: Aluminum, Steel, Composite, Plastic |
| Companies Covered | Krone, Sinotruk, CIMC Vehicles, Hyundai Translead, Utility Trailer, Schmitz Cargobull, Great Dane, FAW Jiefang, Wabash National, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semi-Tractor Trailer Market Evolving Landscape
Powertrain electrification and autonomous assist technologies are rewriting trailer design requirements, while regulatory pressure on emissions intensifies material and aerodynamic innovation cycles.
Composite refrigerated trailer panels are supplanting traditional steel-and-foam construction in temperature-controlled applications. Foodservice distributors and pharmaceutical carriers are specifying fiber-reinforced polymer structural members to reduce thermal bridging and extend refrigeration unit duty cycles. This material transition is compressing the performance gap between premium and standard trailer tiers while raising repair network complexity.
EPA greenhouse gas Phase 3 standards are mandating trailer aerodynamic devices and low-rolling-resistance tires for model year compliance. The regulation forces dry van and refrigerated trailer manufacturers to integrate side skirts, boat tails, and automatic tire inflation systems as standard equipment. Long-haul fleets operating across multiple states face the steepest compliance cost absorption.
Asset utilization models are shifting from ownership toward managed service contracts with guaranteed availability terms. Large retail shippers are unbundling trailer procurement from tractor leasing, pressuring traditional fleet operators to demonstrate uptime metrics against third-party logistics benchmarks. This behavioral change is most pronounced among e-commerce fulfillment networks in the Southwest and Southeast distribution zones.
Semi-Tractor Trailer Market Segmentation
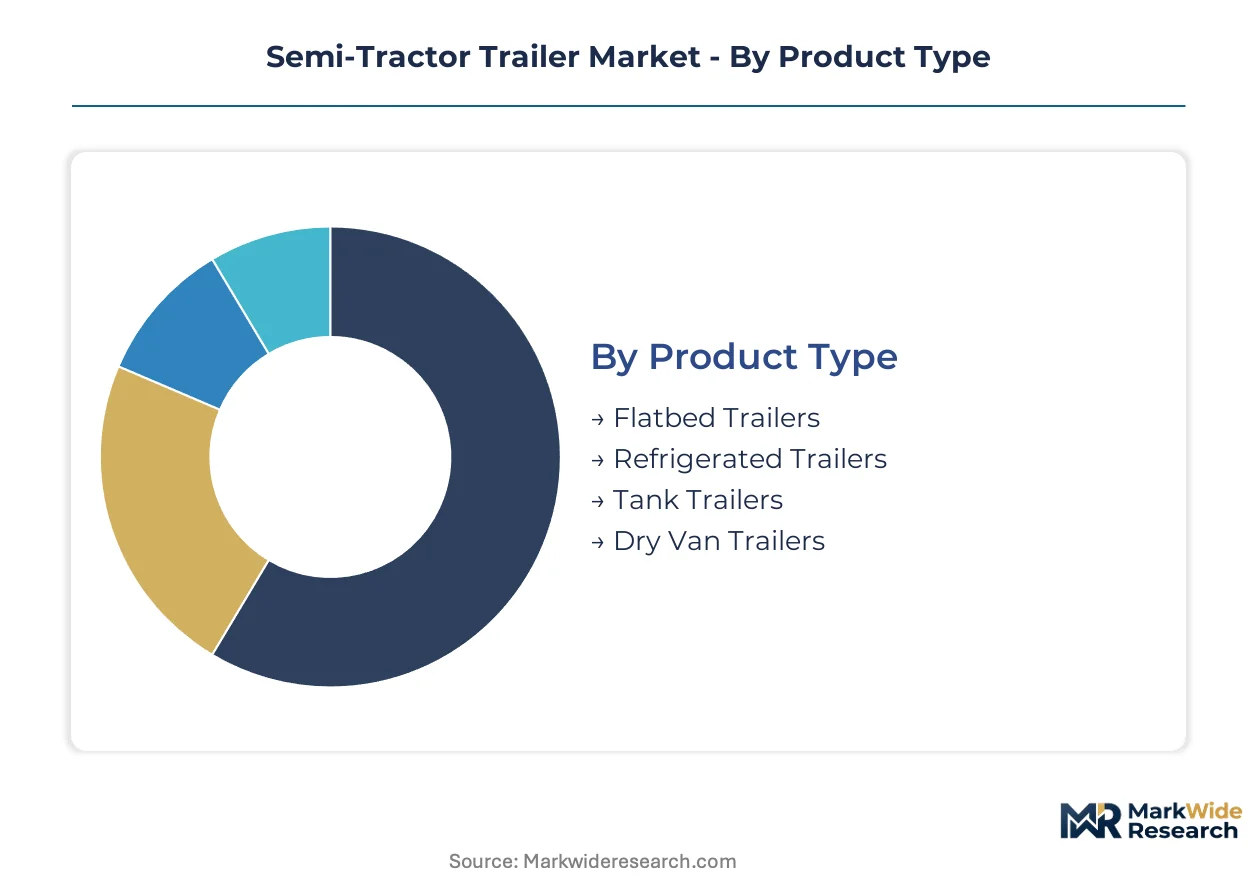
Trailer specification choices directly determine fleet operating economics through payload capacity, fuel consumption, and maintenance intervals. Understanding segment boundaries reveals where procurement power concentrates and which technical specifications command pricing premiums across freight operator categories.
Product Type:
Dry van configurations capture the widest margin pools through volume scale, while refrigerated and tank variants extract value through specialized engineering barriers.
- Dry Van Trailers:Enclosed box construction with hardwood or composite flooring serves non-perishable retail distribution and parcel networks. Demand clusters along the I-40 and I-10 corridors connecting California distribution hubs to Texas and Tennessee fulfillment centers, driven by e-commerce velocity requirements and just-in-time inventory systems.
- Refrigerated Trailers:Insulated composite panels with integrated refrigeration units maintain temperature-controlled environments for pharmaceutical and fresh food supply chains. Pharmaceutical cold chain expansion and vaccine distribution infrastructure are pulling forward specification upgrades in thermal efficiency and telematics integration.
- Flatbed Trailers:Open deck design accommodates oversized construction materials and machinery with tie-down flexibility. Steel and aluminum deck variants serve building supply distributors and equipment haulers.
- Tank Trailers:Cylindrical pressure vessels transport liquid chemicals, food-grade products, and petroleum derivatives. Specialized engineering requirements limit supplier base concentration in chemical corridor operations.
Dry van trailers hold installed capacity across fleet rotations. Refrigerated trailers are rotating up the share rankings through pharmaceutical and fresh food cold chain investments.
End User:
Freight company procurement patterns center on asset utilization rates, while retail distributors prioritize trailer availability guarantees over ownership economics.
- Freight Companies:Asset-heavy operators optimize total cost of ownership through aerodynamic specifications and weight-reduction technologies. EPA Phase 3 compliance costs and residual value uncertainty are forcing powertrain diversification strategies across California-Texas freight lanes.
- Logistics Providers:Third-party operators compete on guaranteed availability metrics and unbundle trailer procurement from tractor leasing contracts. E-commerce fulfillment velocity requirements in Southwest and Southeast distribution zones are accelerating managed service contract adoption.
- Retail Distributors:Private fleet operators balance seasonal demand fluctuations against dedicated capacity needs. Regional grocery and big-box chains specify refrigerated configurations for perishable inbound logistics.
- Construction Firms:Project-based demand drives flatbed and lowboy trailer utilization for equipment and material transport. Infrastructure spending cycles create lumped procurement patterns distinct from steady-state freight operations.
Freight companies anchor current fleet composition. Logistics providers are climbing the fastest through third-party managed service expansion.
Vehicle Configuration:
Axle count specifications trade capital efficiency against regulatory compliance flexibility across variable state weight jurisdictions.
- Tandem Axle:Dual rear axle sets distribute 80,000-pound gross combination weights across standard highway operations. Dominant configuration for long-haul freight due to load distribution efficiency and bridge formula compliance in most jurisdictions.
- Lift Axle:Deployable auxiliary axles adjust load footprint for variable weight regulations and bridge formula requirements. California and Texas permit structures drive adoption despite capital cost without proportional revenue mile generation.
- Single Axle:Reduced weight and capital cost suit short-haul and urban delivery applications with lower gross weight requirements. Regional parcel and last-mile operators specify for maneuverability.
- Tri-Axle:Triple axle configurations accommodate heavier permitted loads in select Australian and Nordic jurisdictions. Limited North American adoption outside specialized heavy-haul permits.
Tandem axle configurations hold installed capacity. Lift axle systems are gaining share fastest through regulatory complexity in multi-state operations.
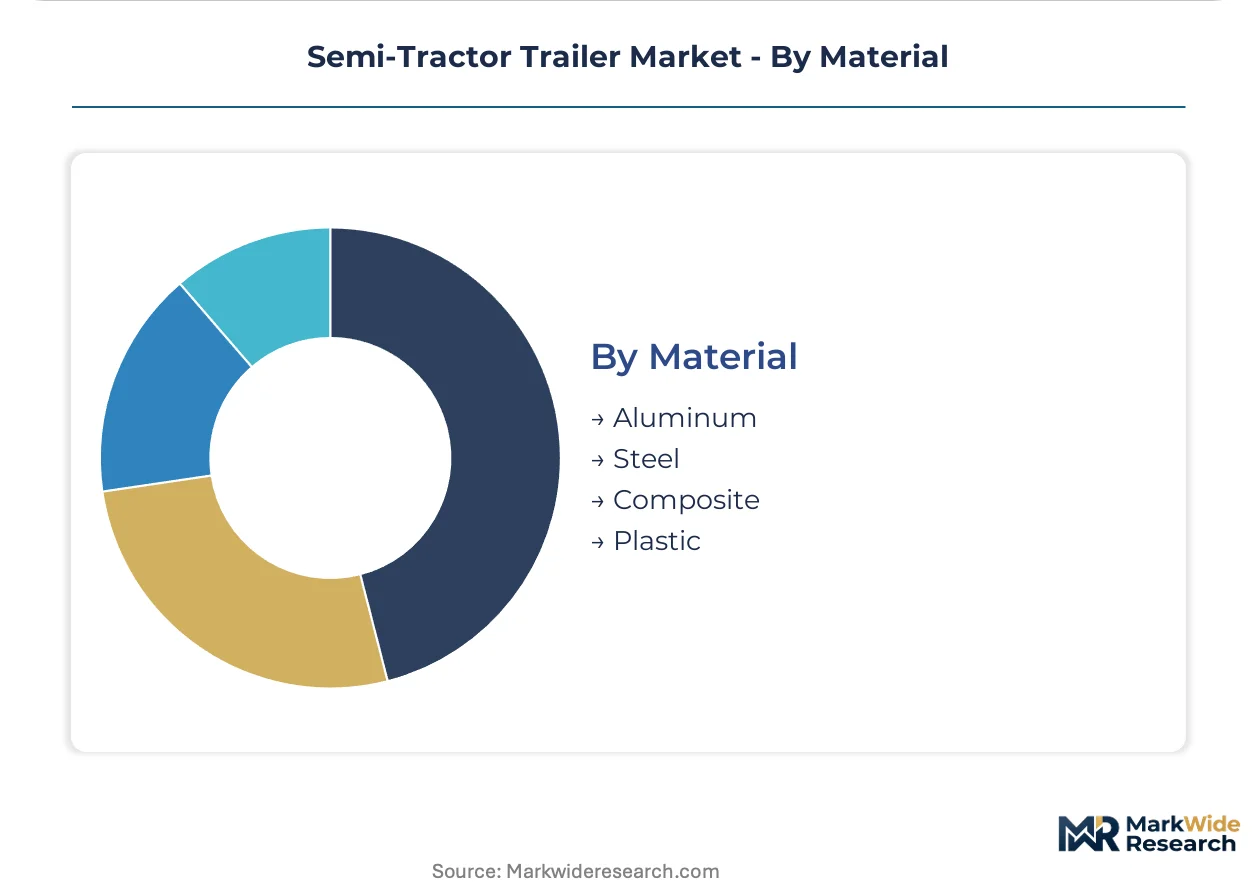
Material:
Structural material selection determines thermal performance, payload capacity, and repair network complexity across trailer lifecycle economics.
- Composite:Fiber-reinforced polymer structural members reduce thermal bridging in refrigerated applications and extend insulation performance. Wabash National and refrigerated trailer specialists specify composite panels to differentiate against traditional steel builds.
- Aluminum:Lightweight structural extrusions improve payload capacity and fuel efficiency in weight-sensitive operations. Dry van sidewalls and flatbed decks balance corrosion resistance against repair complexity.
- Steel:Conventional structural material dominates dry van framing and undercarriage components. Commodity price volatility in aluminum and steel inputs compresses manufacturer margins.
- Plastic:Interior liners and non-structural panels reduce weight and improve cleanability in food-grade applications. Limited structural load-bearing applications.
Steel construction holds installed capacity. Composite materials are rotating up the share rankings through refrigerated trailer thermal efficiency demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Phase 3 greenhouse gas standards anchor North American regulatory pressure, while European CO2 performance standards and China's dual carbon goals reshape tractor-trailer specifications across major freight corridors.
United States
E-commerce fulfillment networks along the I-40 and I-10 corridors drive dry van trailer demand connecting California, Texas, and Tennessee distribution hubs. The Federal Motor Carrier Safety Administration enforces electronic logging device mandates that constrain fleet utilization and expand trailer count requirements. Dallas-Fort Worth and Memphis logistics clusters concentrate refrigerated trailer procurement for pharmaceutical cold chain infrastructure.
Germany
Schmitz Cargobull sustains manufacturing scale advantages across European production centers serving cross-border freight operators. The EU Green Deal and CO2 performance standards for heavy-duty vehicles accelerate aerodynamic trailer specifications and alternative powertrain compatibility. The North Rhine-Westphalia industrial corridor anchors trailer engineering clusters near major logistics terminals.
China
Domestic freight volume expansion and Belt and Road Initiative logistics drive heavy-duty tractor demand across intermodal networks. MIIT fuel consumption standards and provincial dual carbon implementation timelines force fleet modernization cycles. The Yangtze River Delta manufacturing belt concentrates trailer production capacity serving both domestic and export markets.
India
Highway freight growth and organized retail expansion pull refrigerated trailer investments for perishable supply chains. Bureau of Indian Standards axle load norms and state-level commercial vehicle scrappage policies reshape fleet composition. The Delhi-Mumbai Industrial Corridor and Gujarat logistics parks concentrate trailer procurement for pharmaceutical and food-grade transport.
Mexico
Nearshoring manufacturing relocation and USMCA trade corridor growth expand cross-border trailer demand for automotive and electronics supply chains. NOM environmental standards and federal freight modernization programs accelerate fleet replacement cycles. The Nuevo León and Bajío Region industrial clusters concentrate refrigerated trailer specifications for produce exports to US markets.
Semi-Tractor Trailer Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the semi-tractor trailer market. The vendor base organizes around three strategic tiers: European engineering specialists with composite materials expertise, North American scale manufacturers serving domestic fleet operators, and Chinese volume producers capturing emerging market expansion. Consolidation pressures concentrate around refrigerated trailer thermal efficiency and aerodynamic dry van specifications. Competitive moves center on composite material substitution for weight reduction and strategic partnerships for electric powertrain compatibility.
Among European engineering specialists, Schmitz Cargobull and Krone occupy positions exemplifying advanced refrigerated trailer architecture and cross-border manufacturing scale. Wabash National represents the North American technology tier through composite materials differentiation against traditional steel construction. CIMC Vehicles anchors the volume-production archetype serving cost-sensitive freight markets across Asia-Pacific corridors.
| Leading Market Players |
|---|
| Krone |
| Sinotruk |
| CIMC Vehicles |
| Hyundai Translead |
| Utility Trailer |
| Schmitz Cargobull |
| Great Dane |
| FAW Jiefang |
| Wabash National |
| Others |
Value Network & Pricing Analysis
Long-term fleet procurement contracts with take-or-pay structures lock in trailer supply access and price visibility for North American freight operators facing EPA Phase 3 compliance cost absorption. These arrangements concentrate purchasing power among asset-heavy carriers while compressing spot-market pricing flexibility for smaller logistics providers.
Pricing Analysis
Geographic price spreads widen substantially between California CARB-compliant specifications and standard interstate configurations. Three-tier pricing structure across premium composite refrigerated, standard aerodynamic dry van, and economy steel-frame tiers reflects thermal efficiency certification and weight-reduction technology. Pricing pressure stems from aluminum and steel commodity volatility eroding manufacturer margins. Asset-light logistics providers exhibit highest price sensitivity, while pharmaceutical cold chain operators accept premium positioning for temperature-validated specifications.
Supply Chain Analysis
China and Germany anchor structural steel and aluminum extrusion supply for trailer framing, while Mexico and the United States concentrate final assembly operations. Production draws from copper refrigeration coils, fiber-reinforced polymer composites, and low-rolling-resistance tire compounds. Single-source vulnerability concentrates in specialized refrigeration unit compressors sourced from limited European and Asian suppliers. Distribution runs through OEM-direct fleet contracts and dealer networks serving regional operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market exhibits cyclical recovery characteristics anchored to e-commerce fulfillment network expansion and infrastructure replacement cycles following regulatory compliance deadlines.
For Market Incumbents: Consolidate manufacturing footprint around composite materials expertise and aerodynamic engineering capabilities to defend against emerging electric powertrain compatibility requirements. Deepen backward integration into refrigeration unit supply chains to offset copper coil price volatility and secure service network capacity. For New Entrants and Emerging Players: Anchor in pharmaceutical cold chain trailer specifications where temperature-validation certification creates engineering barriers against commodity competition. Target managed service contract structures for e-commerce logistics providers unbundling trailer procurement from tractor leasing. For Investors and Strategic Acquirers: Refrigerated trailer specialists with composite panel manufacturing capabilities represent priority acquisition targets given thermal efficiency premium capture and pharmaceutical demand acceleration. Monitor charging infrastructure deployment velocity along I-40 and I-10 corridors as inflection signal for electric tractor-trailer compatibility investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Composite Materials Manufacturing Scale-Up | Wabash National and refrigerated specialists leverage fiber-reinforced polymers to differentiate thermal efficiency against steel construction. |
| Aerodynamic Trailer Specification Integration | EPA Phase 3 compliance mandates side skirts and boat tails as standard equipment across dry van and refrigerated configurations. |
| Electric Powertrain Compatibility Partnership | Utility-managed megawatt charging infrastructure deployment along California-Texas-Tennessee freight corridors enables zero-emission fleet transition. |
| Pharmaceutical Cold Chain Certification Investment | Temperature-validated trailer demand accelerates from vaccine distribution infrastructure and biologics transport requirements. |
| Managed Service Contract Expansion | Third-party logistics providers compete on guaranteed availability metrics unbundling trailer procurement from traditional ownership models. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EPA regulatory filings, FMCSA enforcement data, and manufacturer production disclosures. Primary interviews engaged fleet procurement directors, trailer manufacturer engineering leads, refrigerated transport operators, and logistics provider contract managers. Secondary validation incorporated customs trade records, state vehicle registration databases, and utility infrastructure planning documents. Bottom-up unit volume estimates triangulate against top-down freight demand modeling.
Segmentation dimensions modeled span product type, end-user category, vehicle configuration, and structural material composition across the projection horizon. CAGRs derive from regression analysis against freight ton-mile growth, fleet replacement cycles, and regulatory phase-in schedules. Industry-specific forecast inputs include e-commerce fulfillment velocity indices and charging infrastructure deployment timelines.
Material uncertainties — commodity price volatility, zero-emission mandate acceleration, and technician labor availability — sit outside the modeled envelope. Forecasts reflect assumptions around EPA Phase 3 implementation consistency and CARB advanced clean trucks regulation continuity. Recalibration cycles align with material shifts in powertrain technology adoption and federal hours-of-service enforcement patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Electric Drive Mining Truck Market
Commercial Vehicles
Middle East Vacuum Truck Market
Commercial Vehicles
Refrigerated Vans Market
Commercial Vehicles
Peru Commercial Vehicle Market
Commercial Vehicles
Electric Truck Chassis Market
Commercial Vehicles
Farm Trucks Market
Commercial Vehicles
Heavy-Duty Trucks Market
Commercial Vehicles
Commercial Vehicle Driveline Support Bearings Market
Commercial Vehicles
Global Commercial Vehicle Fuel Tank Market
Commercial Vehicles
Chile Commercial Vehicle Market
Commercial Vehicles
Service Truck Market
Commercial Vehicles
Modular Trailer Market
Commercial Vehicles
Indonesia Box Truck Market
Commercial Vehicles
Cryogenic Road Tankers Market
Commercial Vehicles
Truck-As-A-Service Market
Commercial Vehicles
Tank Car Market