
 Global Oven Bags Market | 2026-2036
Global Oven Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Global Oven Bags Market Intelligence
A shift from single-source supply agreements to multi-source procurement for specialized polymer films is realigning the competitive landscape. Reynolds Consumer Products leverages its extensive distribution network and brand recognition in the household segment. S. C. Johnson & Son sustains a strong market presence through its portfolio of home care products. Meanwhile, Sirane Ltd differentiates with its focus on innovative food packaging solutions, including microwaveable and oven-safe materials.
Oven bags are heat-resistant pouches, typically manufactured from polyester or nylon films, capable of withstanding temperatures up to 220°C (425°F). Their primary function is to trap moisture during cooking, which tenderizes meats and vegetables while simplifying cleanup. Polyester films continue to dominate the material segment due to proven performance, though biodegradable films are gaining traction. While home cooking remains the largest application, the foodservice sector represents the fastest-growing opportunity due to labor-saving benefits.
Product safety and market access are governed by food contact material regulations. In the United States, the FDA specifies approved polymers, while in Europe, materials must comply with Regulation (EC) No 1935/2004, overseen by bodies like EFSA. Navigating the transition toward sustainable materials like biodegradable films while maintaining thermal performance will be a central challenge for manufacturers.
Market Dynamics
The central dynamic shaping the oven bags market is the supply chain realignment for specialized polymer films. This shift is driven by a dual-sided pressure: strategic moves toward multi-source procurement and sustainability mandates demanding novel biodegradable materials.
Growth Catalysts
- Foodservice Adoption:Demand from the commercial foodservice sector, including restaurants and institutional catering, provides a significant growth engine due to the product's labor-saving benefits in high-volume kitchens.
- Sustainability Mandates:Regulatory frameworks like the EU Green Deal are compelling manufacturers to innovate, creating a market for oven bags made from new biodegradable and compostable films.
- Convenience-Driven Consumers:In developed markets like the United States, strong consumer preference for simple, time-saving cooking methods and easy cleanup continues to sustain demand in the household segment.
Market Restraints
- Performance of Alternatives:Biodegradable films often struggle to match the proven thermal stability and tear resistance of conventional polyester and nylon, limiting their immediate, full-scale substitution.
- Specialized Polymer Supply:The market's reliance on a concentrated group of suppliers for high-temperature-grade polymer films creates vulnerability to price volatility and potential supply chain disruptions.
- Substitution by Cookware:The rising popularity of multi-functional kitchen appliances like air fryers and electric pressure cookers presents a substitution threat, offering alternative methods for tender cooking and easy cleanup.
Strategic Opportunities
- Emerging Market Penetration:Significant opportunity exists in regions with a growing middle class, such as Brazil and India, where adoption of convenience-oriented cooking products is still in its early stages.
- Meal Kit Integration:Custom-sized oven bags can be integrated directly into meal kit delivery services and pre-packaged "ready-to-cook" retail food products, creating a new B2B channel.
- Certified Compostable Products:Developing films that achieve certifications for industrial or home compostability can unlock premium pricing and appeal to environmentally-focused consumer segments in Europe and North America.
Industry Challenges
- Regulatory Compliance Pathways:Navigating the distinct and complex food contact material regulations set by the FDA in the U.S. and EFSA in Europe for new materials is a time-consuming and costly challenge for manufacturers.
- Manufacturing Line Adaptation:Re-tooling existing extrusion and converting lines designed for polyester to handle the different processing characteristics of new biopolymers requires significant capital investment and technical expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Oven Bags Market |
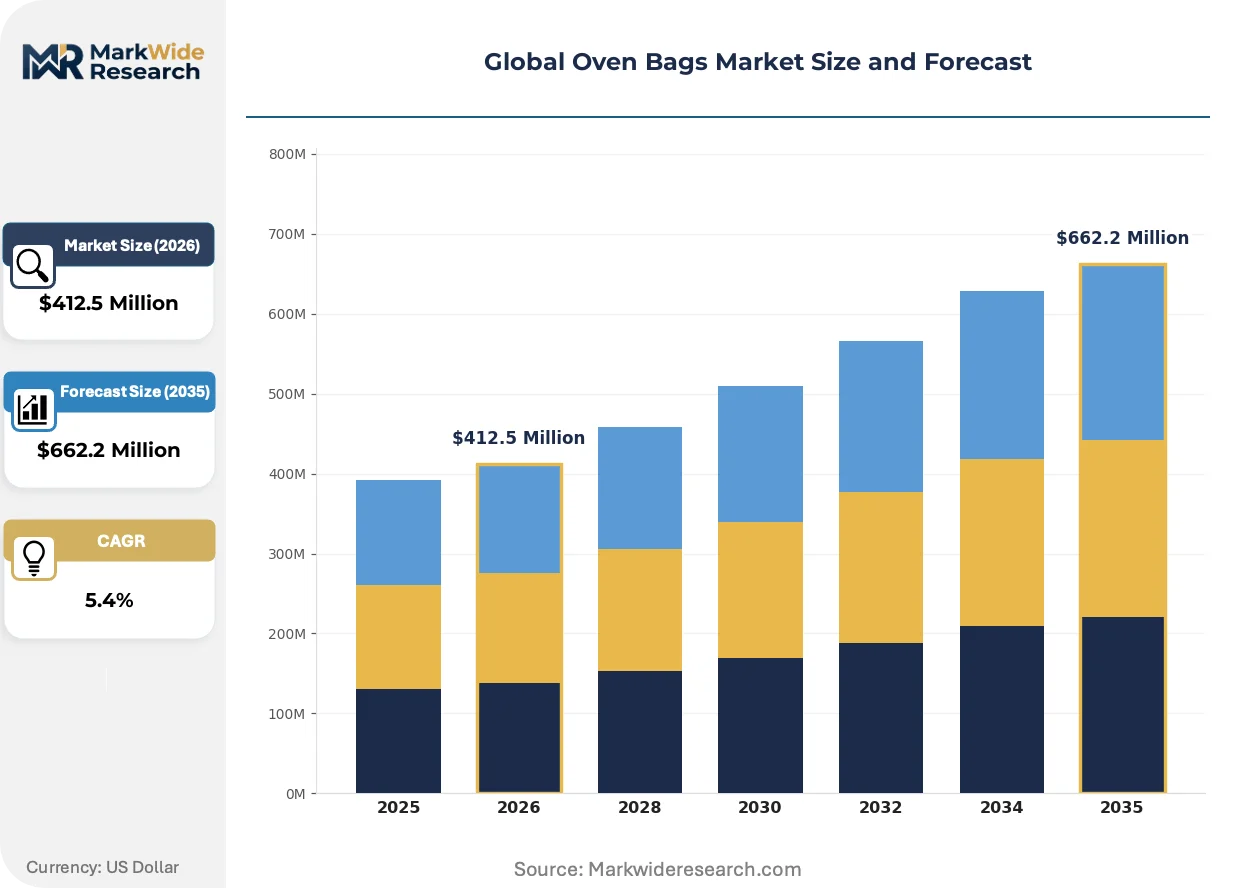
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $662.2 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Oven Bags, Premium Oven Bags, Non-Stick Oven Bags, Flavored Oven Bags, Disposable Oven Bags Material: Polyethylene, Polyester, Nylon, Biodegradable Films, Composite Laminates Application: Home Cooking, Foodservice, Catering, Commercial Kitchens, Meal Preparation End User: Households, Restaurants, Hotels, Food Manufacturers, Institutional Kitchens |
| Companies Covered | Reynolds Consumer Products, Flexipol Packaging Limited, S. C. Johnson & Son, Sealed Air, Sirane Ltd, Sunkey Plastic Packaging Co. Ltd, M&Q Packaging Ltd, Extra Packaging Corp, Xiamen Threestone Packing Material Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Oven Bags Market Strategic Shifts & Innovations
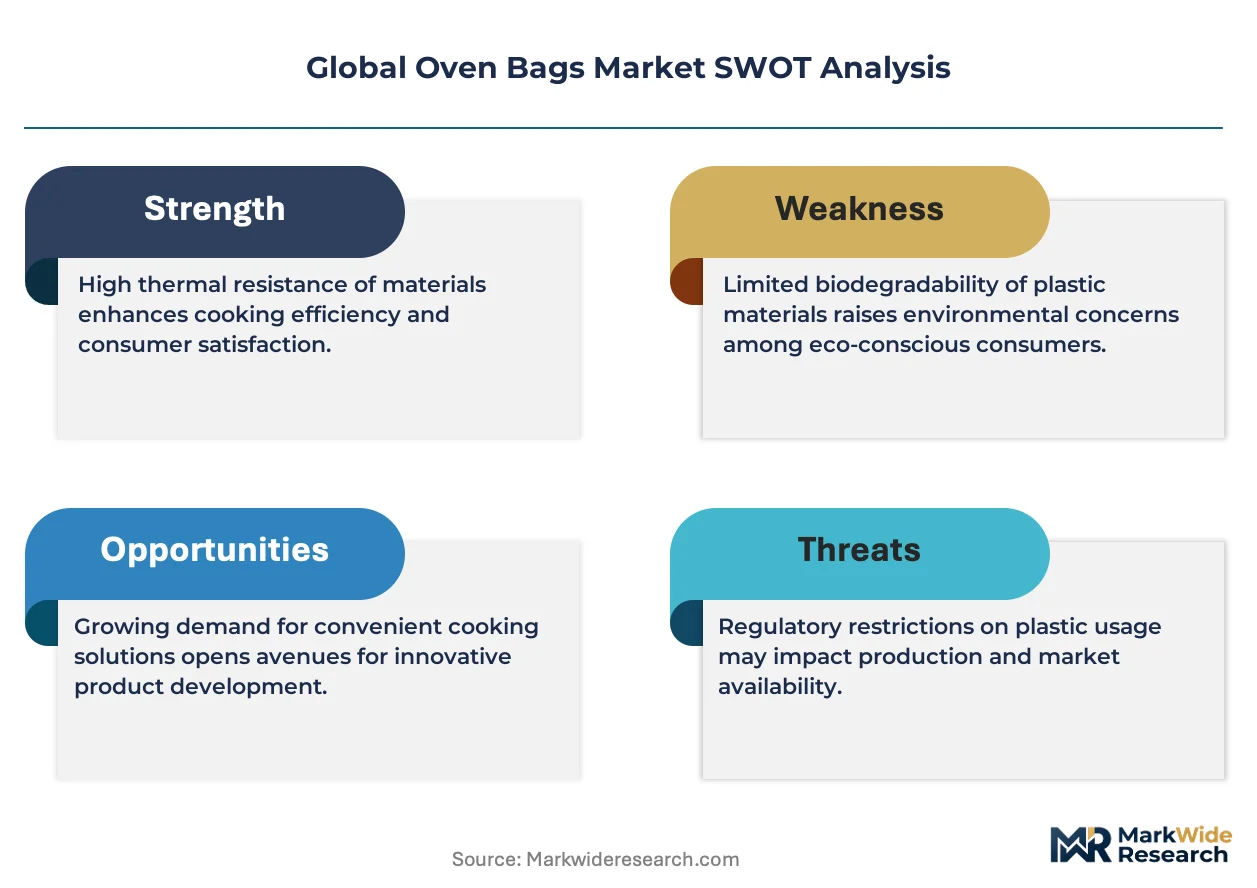
Material science innovation is intersecting with global sustainability pressures, fundamentally altering product development priorities. Manufacturers must now balance the historical focus on thermal performance with new demands for biodegradability, compostability, and regulatory transparency across the entire product lifecycle.
Biodegradable polymers offer a sustainable alternative to traditional petroleum-based films. Environmentally conscious consumers and foodservice providers are driving initial adoption, though it is paced by performance validation. The industry's push for circularity is absorbing R&D capital previously dedicated to enhancing the heat resistance of conventional nylon and polyester films.
European Union Regulation (EC) No 1935/2004 establishes a rigorous legal framework for all materials intended to come into contact with food. This directive requires comprehensive safety assessments, slowing market access for novel polymers until their safety is proven. Manufacturers targeting the EU are most affected, investing heavily in compliance testing to meet EFSA standards.
A distinct behavioral shift is happening as large foodservice chains and grocery retailers diversify their suppliers for specialized packaging films. This pattern disrupts legacy single-source relationships, creating openings for innovative producers to gain entry. The trend is most visible in North America, where supply chain resilience has become a critical procurement objective.
Global Oven Bags Market Segmentation
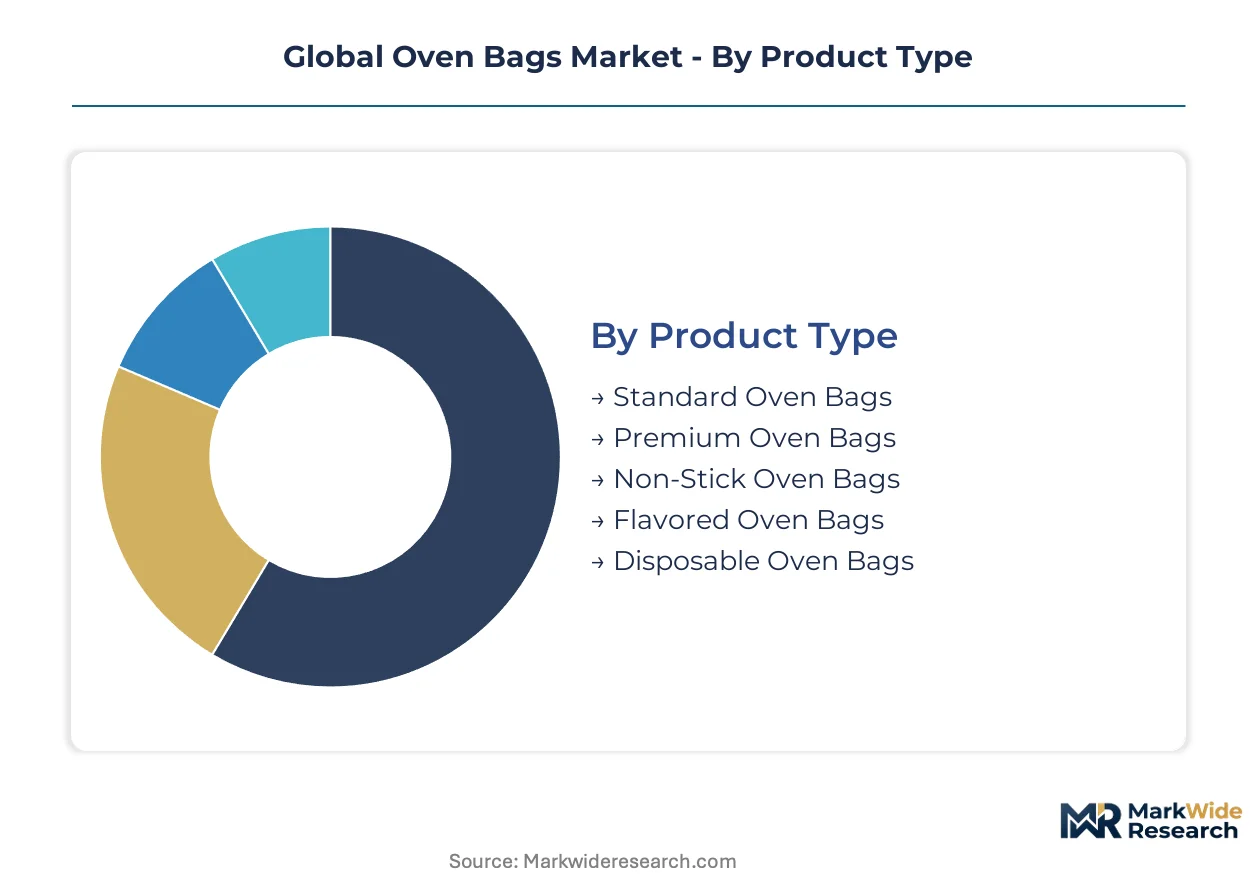
The global oven bags market demonstrates varied demand patterns influenced by material innovation, application requirements, and end-user preferences. Understanding these distinct segments is crucial for manufacturers to tailor product development and market entry strategies effectively. Regulatory compliance for food contact materials also shapes product offerings within each category.
Product Type:
Compliance with food contact material regulations, such as those from the FDA in the United States and EFSA in Europe, dictates the permissible components for each oven bag product type.
- Standard Oven Bags:These basic heat-resistant pouches are typically made from polyester or nylon and designed for general roasting and baking. Demand remains robust in households across North America due to their proven functionality and cost-effectiveness.
- Disposable Oven Bags:Engineered for single-use convenience, these bags simplify cleanup and reduce labor in various cooking scenarios. The foodservice sector in Europe drives significant adoption, valuing the efficiency gains in high-volume operations.
- Premium Oven Bags:These products often feature enhanced heat resistance or specialized coatings for superior performance.
- Non-Stick Oven Bags:Designed to prevent food from adhering, these bags cater to specific cooking requirements for delicate items.
- Flavored Oven Bags:Infused with seasonings, these bags offer a convenient method to impart taste directly during the cooking process.
Leading the category by volume: Standard Oven Bags. Growing fastest: Disposable Oven Bags.
Material:
The supply concentration of specialized polymer films significantly influences the material segment, impacting both availability and pricing across different oven bag formulations.
- Polyester:This material dominates the market due to its excellent thermal stability and tear resistance, making it suitable for high-temperature cooking. Its widespread use in both household and commercial applications, particularly in the United States, underpins its market leadership.
- Biodegradable Films:These innovative materials offer an environmentally friendly alternative, aligning with sustainability mandates and consumer preferences for eco-conscious products. Adoption is gaining traction in European markets, driven by stringent regulatory frameworks like the EU Green Deal.
- Polyethylene:Used primarily for lower-temperature applications, polyethylene offers flexibility and cost advantages in specific product lines.
- Nylon:Valued for its strength and high-temperature performance, nylon serves as a key material in specialized oven bag constructions.
- Composite Laminates:These multi-layered structures combine different material properties to achieve enhanced barrier or thermal characteristics.
Polyester films maintain the largest share, while biodegradable films are expanding most quickly in response to environmental pressures.
Application:
The diverse range of end-use applications for oven bags highlights their utility across various cooking environments, from individual households to large-scale catering operations.
- Home Cooking:This segment encompasses everyday use by individual consumers for preparing meals in domestic kitchens. The convenience factor, including simplified cleanup and consistent cooking results, sustains consistent demand in developed economies such as Canada.
- Foodservice:Commercial kitchens, including restaurants and institutional catering, utilize oven bags for efficient, high-volume food preparation. Labor-saving benefits and consistent product quality are critical drivers for this segment's rapid expansion, particularly in the United Kingdom.
- Catering:Catering services leverage oven bags for preparing and transporting large quantities of food while maintaining quality and temperature.
- Commercial Kitchens:This application involves industrial-scale food preparation where efficiency and food safety are paramount considerations.
- Meal Preparation:Oven bags are integrated into pre-packaged meal kits and ready-to-cook food products for retail consumers.
Home cooking represents the largest application, with foodservice demonstrating the steepest expansion trajectory.
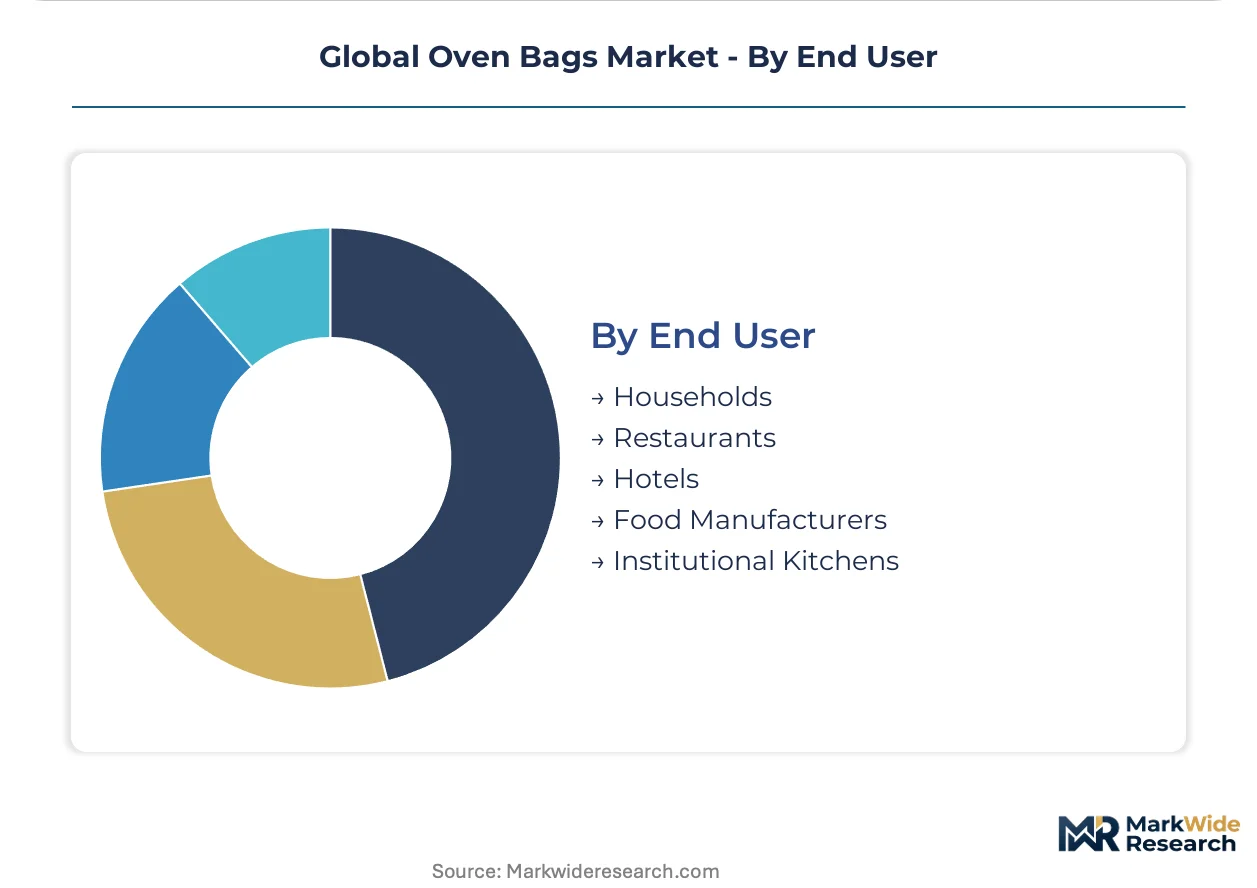
End User:
Customer type segmentation reveals distinct purchasing behaviors and product requirements, ranging from individual household consumers to large institutional buyers.
- Households:Individual consumers purchase oven bags for personal cooking needs, prioritizing convenience, ease of use, and effective meal preparation. Consumer preference for simple cooking solutions in countries like Germany drives consistent demand in this segment.
- Food Manufacturers:These entities integrate oven bags into their production lines for pre-packaged, ready-to-cook meals, ensuring product quality and extending shelf life. The demand from large-scale food processors in Australia is significant for bulk procurement.
- Restaurants:Eateries employ oven bags for efficient food preparation, ensuring consistent quality and reducing labor costs in their kitchens.
- Hotels:Hospitality establishments use oven bags for banquet preparation and in-room dining services, valuing their ability to maintain food quality.
- Institutional Kitchens:This segment includes hospitals, schools, and corporate cafeterias that utilize oven bags for large-volume, standardized meal production.
Households constitute the primary end-user base, while food manufacturers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's extensive polymer manufacturing capabilities underpin a significant portion of the global oven bag material supply chain. This industrial base supports both domestic demand and international export of specialized films. Its expanding middle class also contributes to a growing market for convenience cooking solutions.
United States
United States consumers drive demand for oven bags due to strong preferences for convenient, time-saving cooking. The FDA specifies approved polymers for food contact, ensuring product safety and market access. Midwest food processing hubs around Chicago integrate oven bags into ready-to-cook meals.
Germany
German households consistently demand oven bags, valuing simplified cleanup and effective meal preparation. Products must comply with EU Regulation (EC) No 1935/2004, overseen by EFSA, for market entry. Bavaria's specialized packaging firms actively research and develop sustainable film technologies.
United Kingdom
Foodservice sector expansion in the United Kingdom significantly boosts oven bag adoption, driven by labor-saving benefits and consistent quality. UK food safety standards, aligned with EU frameworks, govern all food contact materials. London's vibrant catering industry utilizes oven bags for efficient, high-volume food preparation.
India
Expanding middle-class populations in India present a significant opportunity for convenience-oriented cooking products like oven bags. The FSSAI regulates food contact materials, ensuring safety and quality for domestic consumers. Mumbai's burgeoning retail sector sees growing integration of oven bags into pre-packaged meal solutions.
China
Rapid urbanization and rising disposable incomes in China fuel demand for convenient cooking aids across household and commercial applications. National GB standards dictate material composition and safety for all food contact packaging. Shanghai's advanced packaging industry develops specialized polymer films for domestic and export markets.
Global Oven Bags Market Key Industry Players
Global majors compete with regional champions across distribution networks and innovation in specialized polymer films. The market exhibits a tiered structure, with a few established brands holding significant household presence alongside numerous specialized packaging producers. Archetypes include consumer product conglomerates, focused material science innovators, and contract manufacturers providing flexible solutions. Companies pursue portfolio diversification and strategic partnerships to enhance their market reach and material sourcing capabilities.
Within the established household brand tier, Reynolds Consumer Products and S. C. Johnson & Son exemplify companies leveraging extensive distribution networks and strong brand recognition. These firms occupy a position focused on consumer convenience and broad market access, supplying a wide range of household products. Sirane Ltd. represents the specialized innovator archetype, focusing on advanced food packaging solutions including microwaveable and oven-safe materials. This company anchors a segment driven by specific performance requirements and material science expertise, differentiating through technological advancements.
| Leading Market Players |
|---|
| Reynolds Consumer Products |
| Flexipol Packaging Limited |
| S. C. Johnson & Son |
| Sealed Air |
| Sirane Ltd |
| Sunkey Plastic Packaging Co. Ltd |
| M&Q Packaging Ltd |
| Extra Packaging Corp |
| Xiamen Threestone Packing Material Co. Ltd |
Cost & Logistics Intelligence
Foodservice sector procurement, driven by efficiency and volume, often establishes long-term contract-based pricing models with manufacturers. This buyer concentration influences pricing stability for bulk quantities, contrasting with more variable pricing in the household segment.
Pricing Analysis
Product features like non-stick properties or enhanced thermal stability are often bundled into the base price, offering differentiation from standard offerings. Per-unit transactional pricing dominates the household segment, while contract-based agreements are prevalent for commercial buyers. Price differentiation stems from certification levels, such as FDA or EFSA compliance, and the volume scale of purchases. Pricing pressure stems from the performance gap of biodegradable alternatives, which often require higher input costs. Households in developed economies demonstrate higher price sensitivity compared to commercial foodservice operations valuing labor savings.
Supply Chain Analysis
Logistics and freight costs significantly impact the final price of oven bags, particularly for specialized polymer films sourced internationally. Geographic supply concentration for high-temperature polymer films primarily resides in China, the United States, and Germany. The market draws from raw material dependencies on polyester, nylon, and emerging biopolymer films. Single-source vulnerability for specialized polymer films creates a structural supply chain risk. Distribution runs through established retail channels for household products and specialized B2B distributors for the foodservice and food manufacturing sectors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a cost-of-compliance story, where adherence to food contact material regulations like EU Regulation (EC) No 1935/2004 creates a significant barrier-to-entry moat for compliant players.
For Market Incumbents: Cement existing brand loyalty through continuous investment in product performance and safety certifications. Diversify polymer film sourcing to mitigate supply chain risks originating from concentrated regions. Invest in R&D for next-generation biodegradable films that match the thermal stability of conventional materials, addressing the substitution threat from alternative cookware. Pursue strategic partnerships with biopolymer producers to secure future material supply and maintain market share.
For New Entrants and Emerging Players: E-commerce platforms offer a direct-to-consumer route for specialty oven bags, bypassing traditional retail gatekeepers. Target the meal kit integration segment with custom-sized, certified compostable oven bags for a clear B2B channel. Focus initial market penetration on emerging economies like India and Brazil, where convenience-oriented cooking products are still gaining traction. Differentiate through novel material science, such as home-compostable films, to appeal to environmentally conscious consumers in Europe.
For Investors and Strategic Acquirers: The window for entry favors specialized material science firms with proven biopolymer expertise. Long-term viability is sustained by the persistent consumer demand for cooking convenience and the accelerating regulatory push for sustainable packaging. Target acquisition profiles include regional manufacturers with strong distribution networks in underserved emerging markets or companies holding key patents in advanced film technologies. The signal to watch is the widespread commercial validation of high-performance, certified compostable films.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Reduces environmental footprint and aligns with global sustainability mandates like the EU Green Deal. |
| Long-term Supply Agreement | Secures access to critical specialized polymer films, mitigating price volatility and supply disruptions. |
| Product Launch (Certified Compostable) | Captures premium pricing and appeals to environmentally conscious consumer segments in Europe and North America. |
| Distribution Channel Expansion (Meal Kits) | Unlocks a new B2B revenue stream and integrates products into the growing convenience food ecosystem. |
| Strategic Partnership (Biopolymer Suppliers) | Accelerates R&D for sustainable materials and ensures a competitive edge in product innovation. |
Research Approach
Independent corroboration across industry reports, regulatory filings, and trade publications underwrites the qualitative findings and quantitative projections within this analysis. Primary interviews with packaging engineers, procurement managers, and R&D directors informed market dynamics. The study integrates both bottom-up aggregation of segment data and top-down validation against macroeconomic indicators and consumer spending trends.
The rate-of-change decomposition framework was applied to project market growth across the analysis window. This model segmented the market by product type, material, application, end-user, and regional regulatory frameworks to capture granular shifts. Compound annual growth rates were derived from historical trends and future projections, integrating inputs such as polymer film prices and consumer convenience indices.
Inputs from published industry reports and regulatory databases were available through the study window; gaps in proprietary R&D investment data introduce uncertainty bands. Forecasts reflect assumptions regarding technological advancements and regulatory enforcement. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Packaged Vegan Foods Market
Packaged Foods
Non-Fried Instant Noodles Market
Packaged Foods
Europe Ready Meals Market
Packaged Foods
Instant Beverage Premix Market
Packaged Foods
Dried Honey Market
Packaged Foods
Alginate Casings Market
Packaged Foods
Asia-Pacific Ready Meals Market
Packaged Foods
South America Pasta and Noodles Market
Packaged Foods
Organic Energy Bar Market
Packaged Foods
Brio Bowls Market
Packaged Foods
Instant Cereals Market
Packaged Foods
North America Pasta Market
Packaged Foods
North America Pasta and Noodles Market
Packaged Foods
India Instant Noodles Market
Packaged Foods
Ready to Use Fillings Market
Packaged Foods
North America Breakfast Cereals Market