
 Non-Fried Instant Noodles Market | 2026-2036
Non-Fried Instant Noodles Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Fried Instant Noodles Market Insights
Air-drying technology is tilting production economics away from palm oil-dependent frying lines toward lower-calorie, cleaner-label outputs. Nissin Foods leverages its Japanese R&D base to sustain premium positioning in air-dried noodle formulations. Indofood anchors Southeast Asian supply through backward integration into wheat flour milling and seasoning production. Nongshim competes on kimchi-flavored air-dried variants that dominate Korean convenience store sets.
Non-fried instant noodles are wheat-based noodles manufactured through hot-air drying rather than deep-frying, typically containing 15-25% less fat than fried counterparts while retaining rehydration performance in under four minutes. The primary commercial purpose is delivering convenient, shelf-stable meals to health-aware consumers unwilling to sacrifice speed for nutritional profile. Bowl and cup packaging formats command margin pools in urban convenience channels, while sachet and bag formats dominate value-tier household stockpiling in emerging markets. Spicy flavor profiles lead volume in Southeast Asia, whereas savory variants anchor mature demand in Northeast Asian retail.
China's SAMR enforces GB standards on sodium content and additive labeling that force reformulation of seasoning sachets sold domestically. Japan's Ministry of Health, Labour and Welfare monitors trans-fat thresholds in processed foods, while Indonesia's BPOM requires halal certification for national distribution. Stakeholders must monitor how tightening sodium regulations across East Asian markets reshape seasoning chemistry and brand loyalty thresholds.
Market Dynamics
Air-drying technology is compressing capital requirements for new market entrants while China's GB sodium standards force simultaneous reformulation of seasoning chemistry across all export-bound production lines.
Growth Catalysts
- Urban health consciousness:Southeast Asian metropolitan consumers prioritize reduced-fat meal solutions that retain convenience attributes. Air-dried formats satisfy this preference without cooking-time penalties.
- GB 28050 nutrition labeling:China's mandatory sodium disclosure rules accelerate clean-label seasoning development. Domestic manufacturers reformulate to maintain shelf positioning.
- Hot-air drying equipment:Energy-efficient tunnel dryers cut palm oil dependency. Japanese equipment vendors supply turnkey lines to Indonesian greenfield facilities.
Market Restraints
- Wheat price volatility:Australian and Black Sea supply disruptions inflate flour input costs. Noodle margins compress when grain futures spike.
- Halal certification bottlenecks:Indonesia's BPOM requires facility-level audits that extend new product launch timelines. Smaller exporters lack audit navigation expertise.
- Texture-performance gap:Air-dried noodles achieve 15-25% fat reduction but risk inferior mouthfeel versus fried equivalents. Sensory rejection limits premium pricing power.
Strategic Opportunities
- Vietnam convenience retail:Modern trade penetration lags Indonesia by half. Early movers secure exclusive listings in expanding Minimart and GS25 networks.
- Plant-based protein fortification:Pea and soy isolates integrate into seasoning sachets. Products target flexitarian households in Seoul and Tokyo.
- Single-serve bowl formats:Urban office workers in Bangkok and Jakarta favor microwaveable packaging. This channel commands margin premiums over multi-serve bags.
Industry Challenges
- Flavor chemist scarcity:Clean-label sodium reduction demands specialized formulation talent. Universities in Malaysia and Thailand lack dedicated programs.
- Equipment commissioning delays:Air-drying line installation requires humidity-controlled environments. Tropical ambient conditions complicate Thai and Philippine facility startups.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Fried Instant Noodles Market |
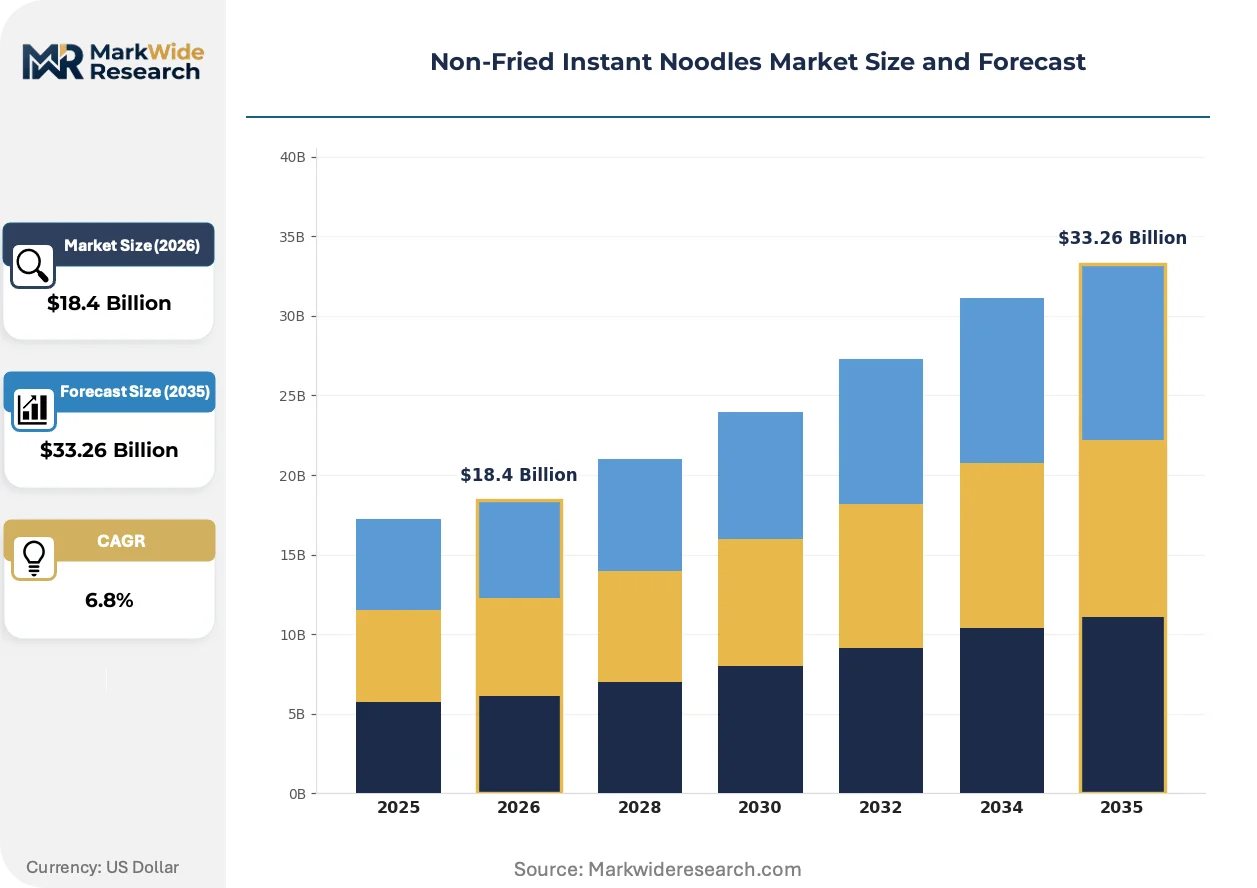
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $33.26 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetable, Chicken, Beef, Seafood Flavor Profile: Spicy, Mild, Savory, Sweet Packaging Type: Bowl, Cup, Sachet, Bag Distribution Channel: Online, Supermarkets, Convenience Stores, Specialty Stores |
| Companies Covered | Nissin Foods, Indofood, Unilever, Monde Nissin, Nongshim, Samyang Food, Ottogi, Thai President Foods, Acecook, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Fried Instant Noodles Market Trends and Innovations
Production technology and regulatory chemistry are converging to redefine competitive advantage. Manufacturers that master simultaneous fat reduction and sensory fidelity capture shelf space from legacy fried-noodle portfolios.
Infrared-assisted drying systems reduce rehydration time to under three minutes while preserving protein structure. Premium brands in Japan and South Korea adopt these lines to defend position against fresh-delivery meal services. The technology is rendering obsolete conventional hot-air tunnels that required longer drying cycles and produced tougher noodle texture.
Japan's Ministry of Health, Labour and Welfare enforces trans-fat thresholds below 1% in processed foods. Domestic manufacturers reformulate palm oil blends and accelerate air-dried product migration. The policy most impacts mid-tier brands that lack R&D resources for rapid oil-system substitution.
Health-aware procurement now prioritizes sodium-per-serving metrics over unit cost in Seoul and Singapore corporate cafeterias. Foodservice distributors respond with curated low-sodium SKUs. This pattern concentrates in Northeast Asian institutional channels where wellness programs influence purchasing committee decisions.
Non-Fried Instant Noodles Market Segmentation
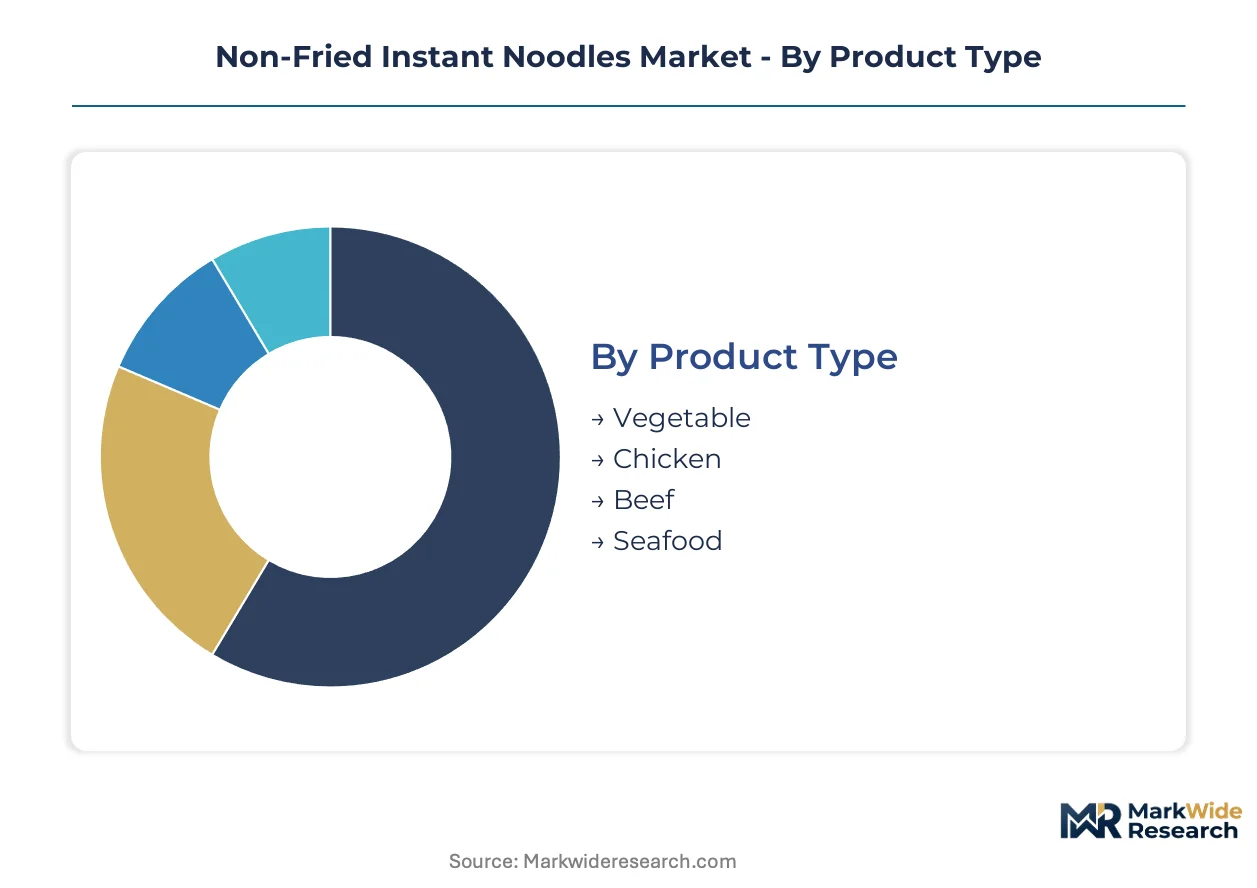
Segmentation in non-fried instant noodles reveals how health positioning, convenience requirements, and channel economics split demand into distinct profit pools. Manufacturers configure production lines and seasoning chemistry differently for each slice, with cycle times varying dramatically from impulse convenience purchases to planned household stockpiling.
Product Type:
Chicken and vegetable SKUs turn over fastest in urban convenience channels, while beef and seafood variants move more slowly through premium retail and foodservice procurement cycles.
- Vegetable:Formulations incorporate dehydrated carrot, cabbage, and mushroom with plant-based broth powders. Demand concentrates in Seoul and Tokyo corporate cafeterias where sodium-per-serving metrics drive procurement committee decisions.
- Chicken:Air-dried noodle bases pair with poultry-derived seasoning stocks and turmeric coloring. Indonesian modern trade channels move the highest volumes, with BPOM halal certification requirements extending launch timelines for new entrants.
- Beef:Richer mouthfeel profiles target premium positioning through hydrolyzed soy protein and yeast extract blends. Distribution runs through Japanese and South Korean specialty retailers.
- Seafood:Kelp and bonito-derived umami bases dominate formulations. Thai and Vietnamese coastal cities show strongest repeat purchase rates.
Chicken dominates installed base. Vegetable is where expansion concentrates.
Flavor Profile:
Cost tiers separate mass-market sachet formats from premium bowl positioning, with seasoning complexity and oil-system investment scaling accordingly.
- Spicy:Chili oil emulsions and Sichuan peppercorn extracts define Southeast Asian preference. Bangkok and Jakarta convenience stores stock multiple Scoville-tier variants.
- Mild:Reduced sodium targets children and elderly consumers in Japan's Ministry of Health-monitored retail environment. Reformulation costs compress margins.
- Savory:Mushroom and soy sauce bases anchor Northeast Asian household penetration. Seoul supermarket chains allocate prime shelf positioning.
- Sweet:Caramelized onion and mirin-influenced profiles serve niche demand in Japanese premium channels. Limited production runs sustain artisan positioning.
Savory commands the broadest installed base. Spicy is climbing the fastest.
Packaging Type:
Application context dictates format selection: office consumption, travel portability, or home pantry storage each favor different structural solutions.
- Bowl:Polypropylene containers with vented lids enable microwave preparation. Urban office workers in Bangkok and Jakarta pay margin premiums for single-serve convenience.
- Cup:Double-walled insulation maintains serving temperature. Japanese railway kiosks and Korean convenience stores rotate flavors seasonally.
- Sachet:Multi-serve bundles target value-conscious households. Indonesian traditional trade channels dominate volume.
- Bag:Flexible pouches minimize shipping cube for export markets. Australian and Middle Eastern importers prefer this format for cost efficiency.
Sachet dominates installed base. Bowl is where expansion concentrates.
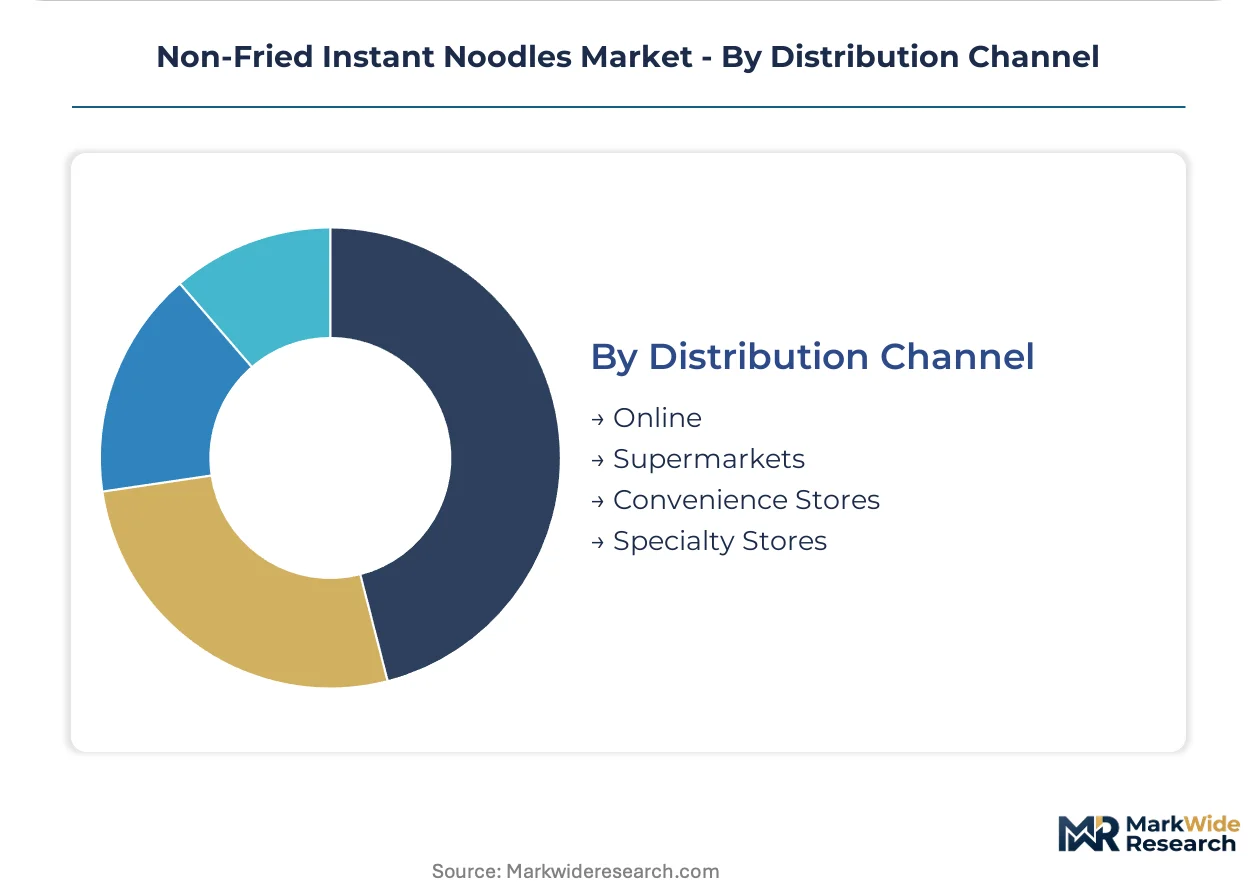
Distribution Channel:
Customer type separates impulse purchasers from planned buyers, with channel-specific packaging and pricing architecture reflecting these behavioral differences.
- Online:Subscription bundles and bulk discounts drive repeat purchase algorithms. Seoul and Singapore direct-to-consumer platforms curate low-sodium assortments.
- Supermarkets:End-cap displays and multi-buy promotions sustain household stockpiling patterns. Modern trade penetration in Vietnam lags Indonesia by half.
- Convenience Stores:24-hour availability captures immediate consumption occasions. GS25 and Minimart networks in Vietnam expand shelf space for air-dried formats.
- Specialty Stores:Curated imports and limited editions serve expatriate and premium-seeking segments. Tokyo depachika basements anchor this channel.
Supermarkets dominate installed base. Online is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health-conscious urban professionals in Seoul, Tokyo, and Jakarta drive premium air-dried noodle adoption. Metro convenience channels in these cities rotate low-sodium and single-serve formats fastest. Regulatory pressure on sodium and trans-fat content accelerates product reformulation cycles across Northeast and Southeast Asia.
China
GB 28050 nutrition labeling mandates force domestic manufacturers to disclose sodium-per-serving metrics prominently. SAMR enforcement of clean-label standards compresses seasoning reformulation timelines to under six months. Shanghai and Guangzhou modern trade channels now allocate dedicated shelf sets for sub-800mg sodium SKUs.
Japan
Ministry of Health, Labour and Welfare trans-fat thresholds below 1% push mid-tier brands toward air-dried migration. METI energy-efficiency guidelines for hot-air drying equipment shape capital expenditure decisions. Kanto region production clusters around Tokyo and Yokohama host the densest concentration of infrared-assisted drying lines.
Indonesia
BPOM halal certification requirements extend new product launch timelines by four to six months for facility-level audits. Urban middle-class households in Jakarta and Surabaya prioritize reduced-fat formats in modern trade channels. Indofood's backward integration into wheat flour milling anchors national supply security.
South Korea
MFDS sodium reduction campaigns target processed food categories with phased compliance deadlines. Seoul convenience store networks rotate kimchi-flavored air-dried variants seasonally. Busan-Ulsan industrial corridor houses specialized tunnel dryer manufacturing for export to Southeast Asian greenfield facilities.
Vietnam
Modern trade penetration lags Indonesia by half, creating first-mover advantages in expanding Minimart and GS25 networks. Urban office workers in Ho Chi Minh City and Hanoi favor microwaveable bowl formats for lunch occasions. Regulatory harmonization with ASEAN food safety standards streamlines import substitution for domestic producers.
Non-Fried Instant Noodles Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The structure concentrates around three archetypes: integrated food conglomerates with milling-to-retail control, flavor-specialist manufacturers with R&D-intensive seasoning capabilities, and regional distributors with exclusive modern trade listings. Competitive moves center on backward integration into wheat supply and technology licensing for energy-efficient drying equipment.
Within the integrated conglomerate tier, Nissin Foods and Indofood occupy positions defined by captive supply chains and national distribution density. Nissin Foods exemplifies the Japanese R&D-intensive archetype with premium air-dried formulations, while Indofood represents Southeast Asian scale through upstream control over flour milling and seasoning production. Nongshim sits within the Korean flavor-specialist segment, anchoring kimchi-variant positioning in convenience retail rotations.
| Leading Market Players |
|---|
| Nissin Foods |
| Indofood |
| Unilever |
| Monde Nissin |
| Nongshim |
| Samyang Food |
| Ottogi |
| Thai President Foods |
| Acecook |
| Others |
Pricing and Supply Chain Analysis
Australian and Black Sea wheat milling concentration anchors input cost volatility that compresses margin pools at the economy-tier sachet segment while premium bowl formats capture pricing power through convenience premiums in Jakarta and Bangkok urban channels.
Pricing Analysis
Cost-plus contracts with Australian wheat futures indexation dominate procurement between Indonesian millers and flour suppliers. Three-tier pricing structure across premium, standard, and economy levels separates microwaveable bowl SKUs from multi-serve bags and traditional trade sachets. Pricing pressure stems from grain futures volatility that erodes noodle manufacturer margins when Black Sea supply disruptions spike. Value-conscious households in Indonesian traditional trade channels exhibit highest price sensitivity, while Seoul corporate cafeteria procurement committees prioritize sodium-per-serving metrics over unit cost.
Supply Chain Analysis
Supplier-financing facilities from Japanese equipment vendors extend payment terms to 180 days for Indonesian greenfield air-drying line installations. Wheat flour sourcing concentrates in Australia, Ukraine, and domestic Indonesian milling operations that Indofood controls through backward integration. Palm oil, hydrolyzed soy protein, and dehydrated vegetable flakes constitute critical seasoning sachet inputs. Single-source vulnerability runs through Australian wheat export channels exposed to El Niño drought cycles. Distribution runs through modern trade supermarkets in Jakarta and Surabaya, convenience store networks in Bangkok, and traditional trade warungs across rural Java.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Air-drying technology disruption is accelerating market restructuring as GB sodium standards and METI energy-efficiency guidelines force simultaneous capital and chemistry reinvestment across Northeast and Southeast Asian production bases.
For Market Incumbents: Pre-empt flavor chemist scarcity by underwriting dedicated clean-label formulation programs at Malaysian and Thai technical universities before competitor hiring drains available talent pools. Secure exclusive infrared-assisted drying equipment allocation from Kanto-region vendors to lock out mid-tier brands from texture-performance parity. Defend against Nongshim's kimchi-variant rotations by accelerating seasonal SKU velocity in Korean convenience channels. For New Entrants and Emerging Players: Establish a beachhead in Vietnam's underpenetrated modern trade segment before GS25 and Minimart network expansion closes listing windows to exclusive suppliers. Target halal-certified chicken variants for Indonesian BPOM audit navigation where smaller exporters lack facility-level expertise. Pursue direct-to-corporate-cafeteria distribution in Seoul and Singapore where wellness-program procurement committees curate low-sodium assortments absent from retail shelf competition. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Southeast Asian distribution platforms holding exclusive modern trade listings in expanding Vietnamese convenience networks. Long-term viability hinges on backward integration into wheat milling and seasoning production that insulates against input cost volatility. Watch for BPOM halal certification backlog resolution as signal for Indonesian new product launch velocity inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wheat Milling | Captive flour supply secures margin stability against Australian futures volatility for Indonesian producers. |
| Infrared-Assisted Drying Line Deployment | Sub-three-minute rehydration performance defends premium positioning against fresh-delivery meal services in Tokyo. |
| Clean-Label Seasoning Reformulation | GB 28050 sodium disclosure compliance maintains shelf positioning in Shanghai modern trade channels. |
| Halal Certification Facility Investment | BPOM audit readiness compresses new product launch timelines for Indonesian national distribution. |
| Corporate Cafeteria Direct Distribution | Seoul wellness-program procurement channels capture margin premiums absent from supermarket price competition. |
Research Methodology
Cross-validation between primary interviews and regulatory filing analysis anchors the qualitative findings in this study. Conversations with noodle manufacturing plant managers, seasoning formulation chemists, modern trade category buyers, and BPOM halal certification auditors informed production economics and launch timeline assessments. Secondary validation drew from GB standards documentation, SAMR enforcement bulletins, METI equipment guidelines, and ASEAN food safety harmonization protocols. Bottom-up production capacity modeling and top-down retail audit data triangulated volume estimates across the analysis window.
Calibration against historical CAGRs in adjacent convenience food categories refined growth trajectory assumptions throughout the forecast period. Segmentation modeling incorporated product type, flavor profile, packaging format, and distribution channel dimensions alongside regional regulatory cluster differentiation. Wheat futures volatility indices, palm oil price series, and air-drying equipment shipment records from Japanese vendors supplied industry-specific forecast inputs. CAGRs derived from slope-consistent trend projection with inflection adjustment for regulatory compliance deadlines.
Sensitivities concentrate around BPOM halal certification processing speeds, Australian wheat harvest yields, and METI equipment efficiency standard revisions. Forecasts reflect documented assumptions regarding urban health consciousness trajectory and modern trade penetration rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Canned Mushroom Market
Packaged Foods
Hummus Market
Packaged Foods
Global Oven Bags Market
Packaged Foods
North America Pasta and Noodles Market
Packaged Foods
Ready to Use Fillings Market
Packaged Foods
United Kingdom Food Spreads Market
Packaged Foods
United States Online Grocery Market
Packaged Foods
Sugar Free Cookies Market
Packaged Foods
Middle East and Africa Energy Bar Market
Packaged Foods
Asia-Pacific Sweet Biscuits Market
Packaged Foods
Pre-Packaged Sandwich Market
Packaged Foods
Low Calorie Noodles Market
Packaged Foods
Jams and Spreads Market
Packaged Foods
Global Dessert Mixes Market
Packaged Foods
Europe Breakfast Cereals Market
Packaged Foods
Private Label Food and Beverage Market