
 Instant Cereals Market | 2026-2036
Instant Cereals Market Size, Share, and Industry Trends Forecast 2026-2036
Instant Cereals Market Outlook
Single-serve cup and sachet bundling is recalibrating how households and foodservice buyers evaluate portion economics and pantry flexibility. Quaker leverages its North American milling infrastructure to control oat supply from field to shelf. Nestle anchors its portfolio through micronutrient fortification protocols that meet diverse national standards. Kellogg competes via flake-process specialization that preserves texture stability across climate zones.
Instant cereals comprise pre-cooked, dehydrated grain formulations—typically oats, corn, rice, or mixed grains—that reconstitute with hot water or milk within 60 to 120 seconds, engineered for shelf stability through roller drying or extrusion. Their commercial purpose centers on delivering caloric and micronutrient density to time-constrained consumers without conventional cooking infrastructure. Oatmeal occupies the largest margin pool among product types due to its premium positioning in heart-health and weight-management claims. Powdered form leads volume throughput in emerging markets where reconstitution flexibility matters, while bars capture the fastest expansion among athletes and commuter segments. Online distribution channels are pulling ahead in growth rate as direct-to-subscription models reduce retail slotting costs.
The FDA governs nutritional labeling and health claim substantiation for instant cereals sold in the United States, while the EFSA evaluates novel ingredient approvals and fortification ceilings across European member states. India's FSSAI mandates front-of-pack labeling and progressively tightens sugar thresholds in children's cereal formulations. Stakeholders must monitor how diverging national fortification mandates and sugar tax schedules reshape formulation portfolios and manufacturing footprint decisions.
Market Dynamics
The EU's Farm to Fork Strategy is compressing formulation timelines as manufacturers scramble to meet sugar-reduction targets and clean-label mandates before enforcement windows close. This regulatory pressure cascades through procurement decisions, ingredient sourcing, and regional production footprints.
Growth Catalysts
- Asia-Pacific Urban Professional Demand:Single-serve oatmeal formats are capturing breakfast occasions among time-constrained white-collar workers in Indian and Indonesian metro corridors. Office pantry programs and commuter retail are normalizing daily consumption.
- EFSA Fortification Protocols:Harmonized micronutrient ceilings across European member states are enabling pan-EU product platforms. Manufacturers gain scale economies by designing formulations that satisfy multiple national standards simultaneously.
- Roller Drying Equipment Advances:New heat-exchange configurations are reducing reconstitution times below 90 seconds. Foodservice operators in Japan and South Korea are adopting these formats for grab-and-go breakfast stations.
Market Restraints
- Oat Supply Concentration:Premium milling-grade oat stocks concentrate in Canadian prairie provinces and Nordic growing regions. Weather volatility and rail logistics bottlenecks transmit price spikes downstream.
- FSSAI Sugar Threshold Escalation:India's progressively tightening front-of-pack labeling requirements for children's cereals force repeated reformulation cycles. Compliance costs disproportionately burden mid-tier domestic producers.
- Fresh Breakfast Substitution:Cold-chain expansion in Southeast Asian cities enables refrigerated yogurt and smoothie alternatives. These options compete directly on convenience and health-positioning.
Strategic Opportunities
- Indonesian Archipelago Distribution:E-commerce logistics networks now reach secondary island markets previously served only by informal retail. Direct-to-consumer subscription models bypass traditional wholesale layers.
- EU Green Deal Procurement Incentives:Public sector catering tenders increasingly weight carbon footprint metrics. Low-emission oat sourcing and biodegradable single-serve packaging qualify for preferential scoring.
- Athlete Segment Bar Formats:Protein-fortified instant cereal bars remain underdeveloped relative to conventional sports nutrition. Specialized formulations targeting endurance and strength training protocols represent open positioning space.
Industry Challenges
- Clean-Label R&D Talent Scarcity:Formulation chemists capable of replacing synthetic preservatives with natural alternatives command premium compensation. Recruitment pipelines lag demand in European and North American hubs.
- Dual-Certification Timeline Compression:Simultaneous pursuit of organic and non-GMO certifications extends validation cycles. Auditing backlogs at accredited bodies delay product launches.
- Legacy Extrusion Asset Stranding:Existing high-temperature processing lines cannot accommodate heat-sensitive novel ingredients. Retooling decisions require multi-year capital commitment amid uncertain regulatory finalization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Instant Cereals Market |
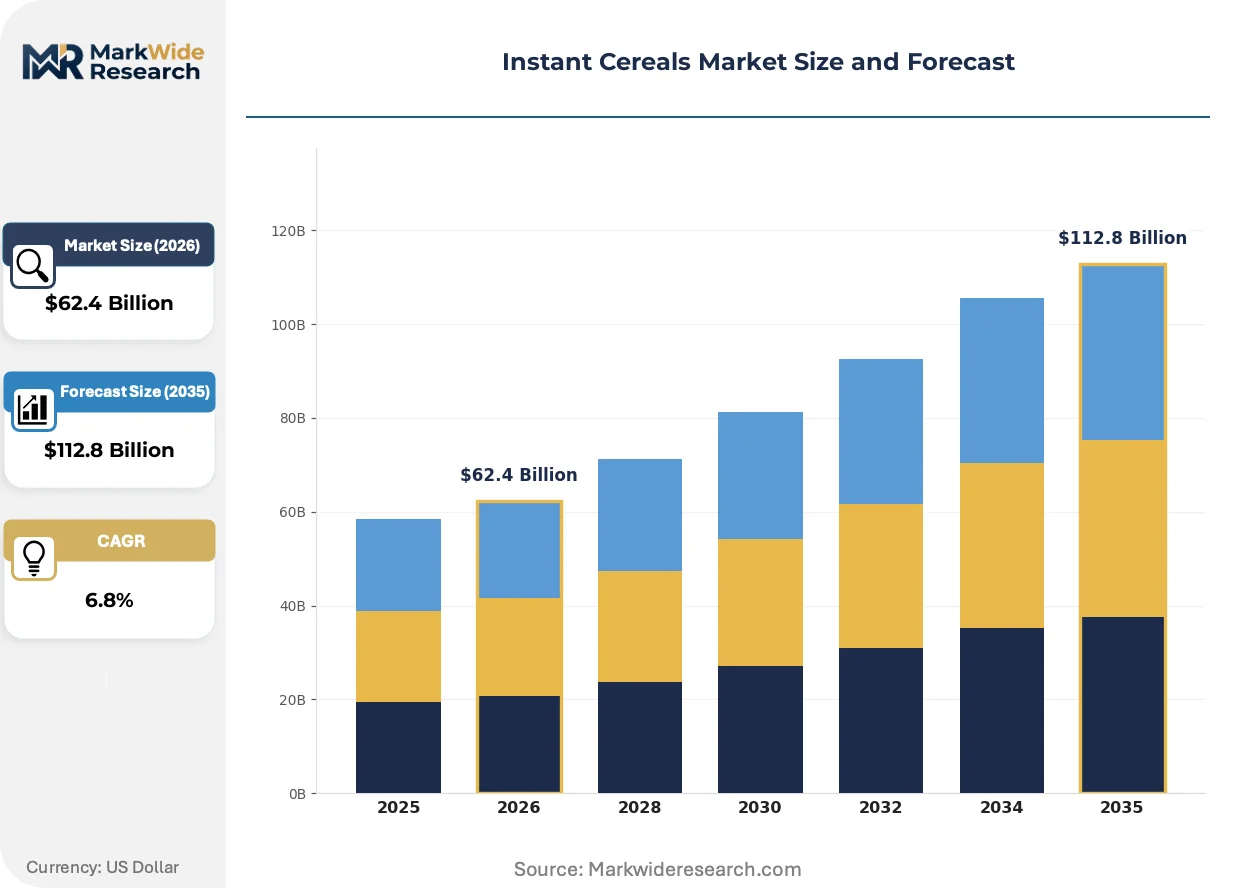
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $112.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oatmeal, Cornflakes, Muesli, Rice Puffs Form: Powdered, Flakes, Granules, Bars End User: Children, Adults, Health-Conscious, Athletes Distribution Channel: Supermarkets, Online, Convenience Stores, Health Food Shops |
| Companies Covered | Quaker, Nestle, General Mills, Kellogg, Gold Kili, NutreMill, Post Holdings, Unisoy, Marico, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Instant Cereals Market Strategic Shifts
Spray-dried fruit inclusions and probiotic fortification are redefining what instant cereals deliver beyond caloric density. Manufacturers now compete on functional benefit portfolios rather than convenience alone.
High-pressure processing of oat bases is overtaking conventional heat treatment for premium-positioned products. Specialty retailers in Germany and Switzerland are prioritizing these formats for their digestibility and enzyme preservation claims. The technology is compressing margins for standard roller-dried alternatives in the premium tier.
India's FSSAI front-of-pack labeling mandate is forcing disclosure hierarchy redesigns across entire product portfolios. Domestic manufacturers are shrinking serving-size declarations and reformulating to avoid red-flag thresholds. Children's cereal SKUs face the most intensive reformulation pressure as sugar ceilings tighten.
Direct subscription procurement is displacing supermarket replenishment among urban dual-income households in Tokyo and Seoul. These buyers prioritize pantry automation and flavor variety rotation over price minimization. Foodservice distributors are responding with customized B2B subscription portals for corporate cafeteria operators.
Instant Cereals Market Segmentation
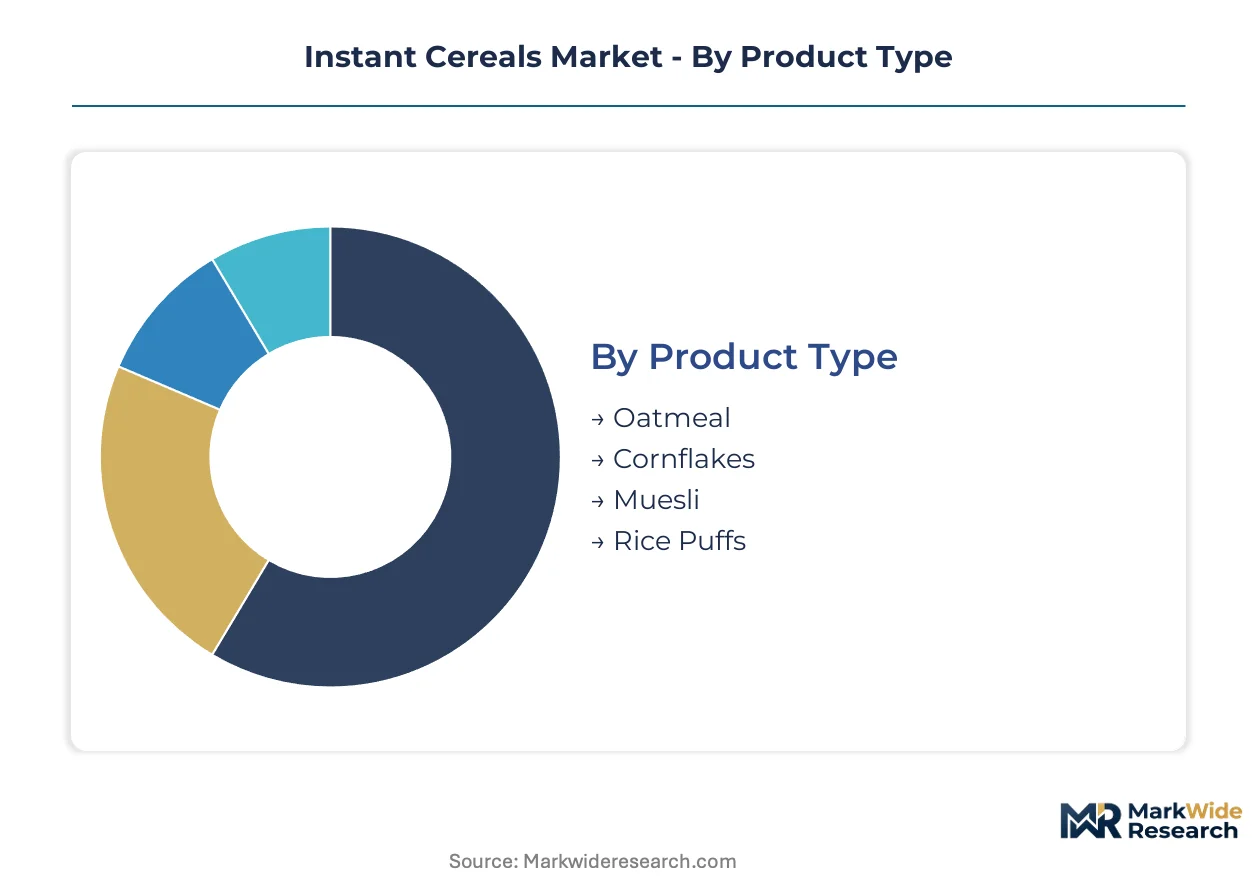
Segmentation in instant cereals reveals divergent margin structures and formulation requirements across consumption occasions. Manufacturers configure production lines and procurement strategies around distinct buyer priorities rather than pursuing universal platforms.
Product Type:
Buyers select product types based on health-positioning credibility and preparation ritual preferences, with heart-health claims and texture familiarity driving repeat purchase.
- Oatmeal:Rolled or steel-cut oat formulations processed through roller drying or extrusion deliver beta-glucan fiber claims. Demand concentrates among urban professionals in Indian and Indonesian metro corridors where single-serve cups normalize daily breakfast routines. Heart-health positioning commands premium shelf placement.
- Cornflakes:Maize-based flake products undergo toasting and coating processes for crisp texture retention. German and Swiss specialty retailers prioritize high-pressure processed alternatives for digestibility claims, compressing margins for standard heat-treated versions.
- Muesli:Raw or toasted oat blends with dried fruit and nut inclusions require separate supply chains for ingredient integrity. Swissmedic-regulated markets favor clean-label muesli with spray-dried fruit.
- Rice Puffs:Extruded rice formulations offer gluten-free positioning and rapid reconstitution. Southeast Asian fresh breakfast substitution pressure limits expansion in refrigerated yogurt-accessible cities.
Oatmeal leads on scale; rice puffs gain share fastest among allergen-avoidant buyers.
Form:
Form selection trades reconstitution flexibility against portability, with emerging markets favoring adaptability and commuter segments prioritizing ready-to-eat formats.
- Powdered:Finely milled grain bases dissolve in hot water or milk within 60 seconds. Volume concentrates in emerging markets where reconstitution flexibility matters and cooking infrastructure remains limited.
- Flakes:Roller-dried or extruded flat grains maintain texture stability across climate zones. Japanese and South Korean foodservice operators adopt advanced heat-exchange configurations for sub-90-second preparation.
- Granules:Intermediate particle size offers spoonable consistency without full dissolution. Middle-tier domestic producers in India face FSSAI sugar threshold escalation costs disproportionately.
- Bars:Compressed and bound cereal formats deliver portable caloric density. Athlete and commuter segments in Tokyo and Seoul drive expansion through direct subscription procurement.
Powdered form dominates volume throughput; bars climb fastest on athlete segment targeting.
End User:
End user targeting determines fortification protocols, serving size architecture, and flavor profile intensity, with regulatory scrutiny varying sharply by demographic.
- Children:Micronutrient-fortified formulations with controlled sugar levels face India's progressively tightening FSSAI front-of-pack labeling requirements. Reformulation cycles burden domestic manufacturers.
- Adults:Standard fortification meeting diverse national standards enables pan-EU product platforms under EFSA protocols. Scale economies reward harmonized formulations.
- Health-Conscious:Clean-label positioning with natural preservatives and reduced sugar commands premium compensation for scarce formulation chemists in European hubs.
- Athletes:Protein-fortified and macronutrient-optimized formats remain underdeveloped relative to conventional sports nutrition. Endurance and strength training protocols represent open positioning space.
Adult targeting anchors revenue; athlete positioning shows steepest expansion trajectory.
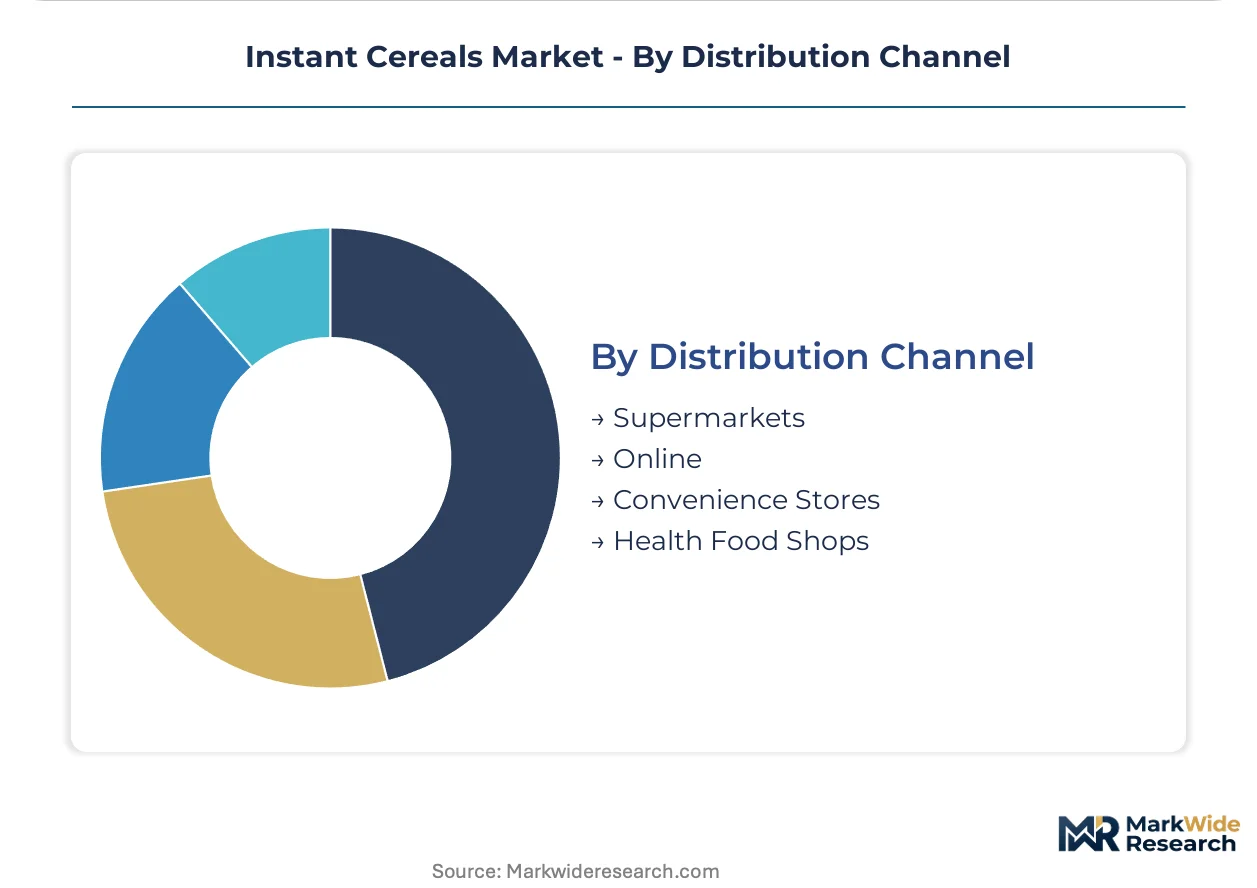
Distribution Channel:
Channel selection determines working capital requirements, margin retention, and consumer data access, with digital platforms disrupting traditional wholesale economics.
- Supermarkets:Traditional retail slotting demands shelf placement fees and promotional support. Retail slotting costs drive manufacturers toward direct alternatives.
- Online:Direct-to-subscription models reduce retail slotting costs and enable flavor variety rotation. Urban dual-income households in Tokyo and Seoul prioritize pantry automation.
- Convenience Stores:Impulse-oriented single-serve formats capture commuter breakfast occasions. Office pantry programs normalize daily consumption in Indian metro corridors.
- Health Food Shops:Specialty retailers in Germany and Switzerland prioritize high-pressure processed oat bases for enzyme preservation claims. Premium tier concentration rewards differentiated positioning.
Supermarkets retain volume leadership; online channels expand most quickly on subscription model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The instant cereals industry traces its modern commercial origins to late-nineteenth-century American milling innovations, with roller-drying technology first scaling in the Great Lakes region before diffusing to European and Asian manufacturing centers.
United States
Single-serve oatmeal cups dominate commuter breakfast occasions in Chicago and New York metro corridors, while heart-health claims sustain premium pricing in coastal markets. The FDA governs nutritional labeling and health claim substantiation, with particular scrutiny on beta-glucan fiber assertions. Minneapolis-St. Paul anchors North American oat milling infrastructure, where integrated processors control supply from prairie fields to retail shelf.
Germany
Specialty retailers in Berlin and Munich prioritize high-pressure processed oat bases for digestibility and enzyme preservation claims, compressing margins for conventional heat-treated alternatives. EFSA fortification protocols enable pan-EU product platforms through harmonized micronutrient ceilings. The Cologne-Düsseldorf corridor concentrates clean-label R&D talent scarce across European formulation hubs.
India
Urban professionals in Mumbai and Bangalore metro corridors normalize daily single-serve oatmeal consumption through office pantry programs and commuter retail channels. FSSAI mandates progressively tighten front-of-pack sugar thresholds, forcing repeated reformulation cycles particularly burdensome to mid-tier domestic producers. Ahmedabad and Pune host manufacturing clusters serving archipelago distribution through emerging e-commerce logistics networks.
Indonesia
Jakarta and Surabaya concentrate fastest-growing demand for fortified instant cereals among time-constrained white-collar workers seeking convenient breakfast solutions. National food safety regulations align with ASEAN harmonization frameworks while maintaining distinct front-of-pack disclosure requirements. E-commerce subscription models now reach secondary island markets previously served only by informal wholesale layers.
Switzerland
Swissmedic-regulated markets favor clean-label muesli formulations with spray-dried fruit inclusions and probiotic fortification, setting quality benchmarks for premium European positioning. The EU Green Deal's carbon footprint metrics increasingly weight public sector catering tenders, favoring low-emission oat sourcing and biodegradable packaging. The Zurich-Basel corridor anchors specialty retail prioritization of functional benefit portfolios over convenience alone.
Instant Cereals Market Competitive Environment
The competitive structure tilts toward diversified multinational food conglomerates with captive milling infrastructure and established retail slotting relationships. Three strategic archetypes dominate: integrated grain processors controlling field-to-shelf supply chains, micronutrient fortification specialists navigating divergent national standards, and clean-label innovators leveraging high-pressure processing for premium positioning. Capacity expansion in roller-drying equipment and strategic partnerships for e-commerce distribution constitute the dominant competitive moves reshaping market presence.
Among North American integrated processors, Quaker and Kellogg exemplify archetypes of supply chain control and flake-process specialization respectively, while Nestle represents the fortification-specialist model with protocols meeting diverse regulatory ceilings across multiple jurisdictions. These three occupy positions that illustrate how scale, technical specialization, and regulatory navigation combine to structure competitive advantage in instant cereals manufacturing.
| Leading Market Players |
|---|
| Quaker |
| Nestle |
| General Mills |
| Kellogg |
| Gold Kili |
| NutreMill |
| Post Holdings |
| Unisoy |
| Marico |
| Others |
Value Chain & Pricing Dynamics
Milling-grade oat premiums originating in Canadian prairie provinces and Nordic growing regions transmit downstream through three distinct pricing tiers before reaching retail shelf. Roller-drying energy costs and rail logistics surcharges compound at each transfer point, compressing margins for mid-tier domestic producers while rewarding integrated processors with captive supply.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates high-pressure processed organic formats from conventional roller-dried products and private-label commodity offerings. Certification grade and geographic delivery cost drive price differentiation, with EU Green Deal carbon footprint metrics now qualifying products for preferential public sector tender scoring. Pricing pressure stems from FSSAI sugar threshold escalation forcing repeated reformulation cycles. Economy-tier buyers in Indonesian secondary island markets exhibit highest price sensitivity, while Tokyo and Seoul subscription households prioritize pantry automation over cost minimization.
Supply Chain Analysis
Premium milling-grade oat supply rests on Canadian prairie provinces, Nordic growing regions, and North American Great Lakes processing clusters. Raw material dependencies center on roller-drying equipment, heat-exchange configurations, and spray-dried fruit inclusion supply chains. Single-source vulnerability concentrates in rail logistics bottlenecks connecting prairie fields to Minneapolis-St. Paul milling infrastructure. Distribution runs through integrated field-to-shelf processors, e-commerce subscription platforms, and traditional supermarket wholesale layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The instant cereals market reads as a late-cycle quality story as Asia-Pacific urban professionals shift demand toward single-serve formats with heart-health and clean-label credentials.
For Market Incumbents: Acquire roller-drying equipment manufacturers and high-pressure processing technology licensors to lock in processing capacity before regulatory windows close. Consolidate oat milling infrastructure in North American prairie corridors to defend against supply concentration risks. EFSA fortification protocol harmonization and FSSAI sugar threshold escalation represent dual regulatory threats requiring preemptive formulation investment. For New Entrants and Emerging Players: EU Green Deal procurement incentives in Germany and Switzerland open a window for biodegradable single-serve packaging specialists to capture public sector catering tenders. Target Indonesian archipelago e-commerce distribution through direct-to-consumer subscription models bypassing traditional wholesale layers. Athlete segment protein-fortified bars remain the most penetrable white-space, with endurance and strength training protocols offering specialized positioning angles. For Investors and Strategic Acquirers: Consolidation pressure builds where clean-label R&D talent scarcity and dual-certification timeline compression disadvantage mid-tier domestic producers. Long-term viability favors integrated processors with captive milling infrastructure and established retail slotting relationships over pure-play formulation specialists. Watch FSSAI sugar threshold enforcement intensity as the inflection indicator for reformulation cycle frequency and compliance cost burden.| Strategic Initiative | Industry Significance |
|---|---|
| High-Pressure Processing Capacity Expansion | German and Swiss specialty retailers prioritize digestibility claims, compressing margins for conventional heat-treated alternatives. |
| Biodegradable Single-Serve Packaging Transition | EU Green Deal carbon footprint metrics in public sector tenders favor low-emission sourcing and sustainable materials. |
| Direct-to-Consumer Subscription Platform Launch | Tokyo and Seoul urban dual-income households prioritize pantry automation and flavor variety rotation over price. |
| Athlete Segment Protein Fortification R&D | Endurance and strength training protocols represent underdeveloped positioning space relative to conventional sports nutrition. |
| Indonesian E-Commerce Logistics Network Partnership | Secondary island markets previously served only by informal retail now accessible through emerging distribution infrastructure. |
Study Parameters
Multiple input streams — category buyer interviews, supply chain manager discussions, regulatory affairs consultations, and formulation chemist panels — were reconciled against trade customs data, FSSAI enforcement bulletins, and EFSA novel ingredient approval registers. Primary fieldwork engaged brand managers at multinational conglomerates, procurement leads at Asian foodservice distributors, and clean-label R&D directors in European hubs. Secondary validation drew from Nielsen retail audit data, oat futures pricing archives, and SEC 10-K disclosures from integrated processors. Bottom-up SKU-level volume builds and top-down category spend estimates underwent iterative triangulation.
Cross-referencing historical consumption patterns against panel-based demand projections anchored the analytical framework across the analysis window. Segmentation dimensions modeled include product type, form, end user demographic, and distribution channel, with regional regulatory cluster variations. CAGRs derived from curve-fitting techniques applied to normalized volume and value trajectories. Industry-specific forecast inputs incorporated FSSAI sugar threshold implementation schedules and EU Farm to Fork Strategy enforcement timelines.
Revisions become necessary when FSSAI enforcement intensity exceeds modeled assumptions, oat supply disruptions from prairie weather volatility materialize, or fresh breakfast substitution accelerates beyond projected rates in Southeast Asian metro corridors. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Pastry Fillings Market
Packaged Foods
Mexico Packaged Food Products Market
Packaged Foods
Convenience Food Market
Packaged Foods
Middle East and Africa Energy Bar Market
Packaged Foods
Pre-Packaged Food Market
Packaged Foods
Canned Legumes Market
Packaged Foods
Canned Fruits Market
Packaged Foods
Private Label Food and Beverage Market
Packaged Foods
Middle-East and Africa Ready-To-Eat Food Market
Packaged Foods
Iraq Dried Pasta Market
Packaged Foods
Global Oven Bags Market
Packaged Foods
Cereal Flakes Market
Packaged Foods
Prepared Flour Mixes Market
Packaged Foods
Instant Rice Market
Packaged Foods
Impulse Ice-Cream Market
Packaged Foods
Food and Beverages Market