
 Low Temperature Yogurt Market | 2026-2036
Low Temperature Yogurt Market Size, Share, and Industry Trends Forecast 2026-2036
Low Temperature Yogurt Market Insights
The gap between premium probiotic strains and commodity private-label offerings is expanding across refrigerated dairy cases. Danone leverages its specialized fermentation expertise to command shelf space in European and North American supermarkets. Chobani anchors its position through Greek yogurt specialization with live active cultures. Inner Mongolia Yili Industrial Group dominates domestic distribution networks across tier-one Chinese cities.
Low temperature yogurt denotes refrigerated dairy products fermented at controlled temperatures below standard ambient thresholds, typically incorporating Lactobacillus bulgaricus and Streptococcus thermophilus cultures with live probiotic counts maintained through cold-chain integrity. Greek yogurt leads value contribution due to protein concentration and premium positioning, while drinkable yogurt formats sustain the fastest volume trajectory in Asian convenience channels. Plastic cups occupy the majority of unit packaging despite growing pouch adoption for on-the-go fitness enthusiasts.
FDA standards for live and active cultures, EU hygiene regulations under EFSA oversight, and China's SAMR dairy safety protocols collectively shape formulation requirements and import access conditions. Stakeholders must monitor evolving sugar taxation frameworks and probiotic health claim substantiation rules across multiple jurisdictions. Cold-chain reliability and clean-label certification will determine which suppliers capture expanding refrigerated shelf allocations.
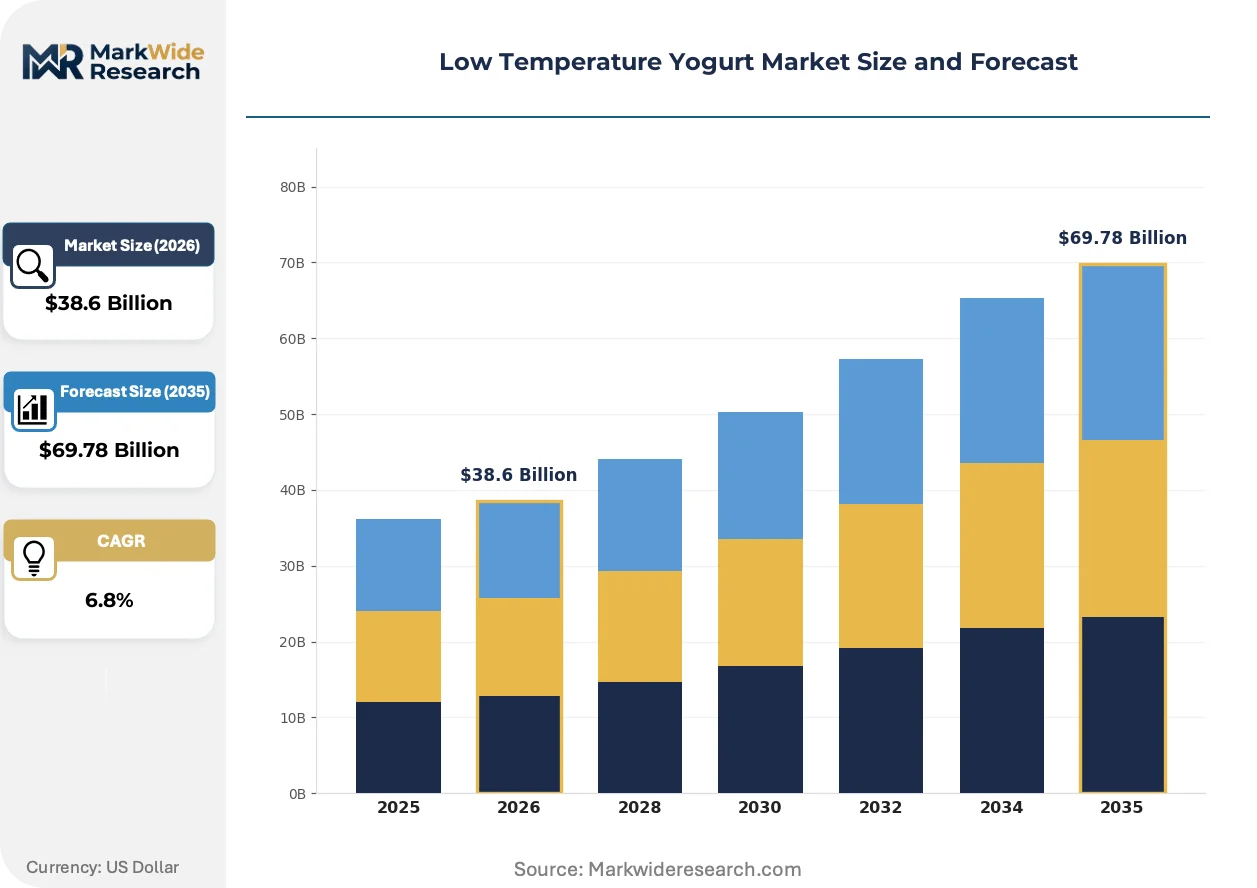
Market Dynamics
Cold-chain infrastructure expansion in emerging economies is redistributing refrigerated dairy access from coastal metros toward interior population centers, forcing manufacturers to reconfigure distribution networks around temperature integrity rather than shelf-stability.
Growth Catalysts
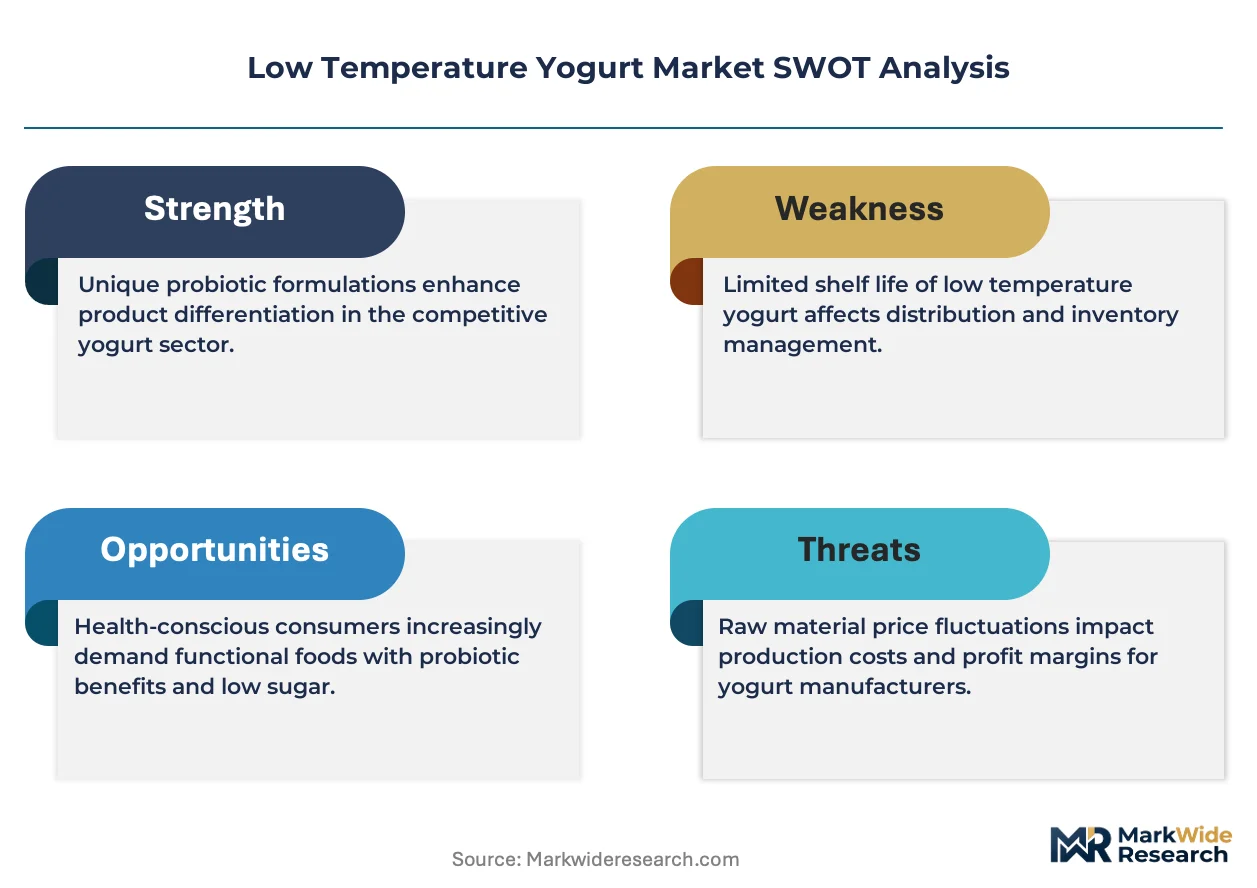
- EU clean-label mandates:EFSA substantiation requirements for probiotic health claims are accelerating reformulation investments toward reduced-sugar, high-live-culture recipes that command retail premiums.
- Urban cold-chain maturation:Tier-two Chinese cities now maintain consistent sub-6°C distribution corridors, unlocking refrigerated yogurt penetration where ambient-stable alternatives previously dominated.
- Precision fermentation advances:Novel starter culture selection methods are reducing batch-to-batch variability, enabling consistent live-active-culture counts that satisfy FDA standards for refrigerated products.
Market Restraints
- Dairy input cost volatility:Fluid milk price swings in New Zealand and EU dairy auctions compress margin predictability for refrigerated yogurt producers locked into annual retail price agreements.
- Cold-chain capital intensity:Last-mile refrigerated logistics require specialized vehicle fleets and depot infrastructure that concentrate viable distribution among capitalized national players.
- Plant-based substitution:Oat and coconut fermented alternatives are capturing shelf space in North American and Western European natural-food channels, displacing conventional dairy probiotic positioning.
Strategic Opportunities
- Indian metropolitan expansion:Mumbai, Bangalore, and Delhi NCR cold-chain investments are creating first-mover advantage for refrigerated yogurt formats in a market historically dominated by ambient curd.
- Sports nutrition channel convergence:Protein-fortified Greek yogurt is penetrating gym and fitness-center retail, bypassing traditional grocery slotting fees through direct-to-consumer refrigerated vending.
- Sugar taxation tailwinds:UK soft drinks industry levy expansion discussions and similar frameworks under review in Mexico are incentivizing sub-5g sugar formulations that align with clean-label positioning.
Industry Challenges
- Live-culture certification timelines:Third-party validation of CFU counts at expiration requires 45-60 day stability studies that delay new product launches and compress innovation cycles.
- Cold-chain talent scarcity:Refrigerated logistics operations face shortages of qualified cold-chain managers capable of maintaining HACCP compliance across multi-temperature zone distribution networks.
- Legacy dairy integration complexity:Ambient yogurt producers retrofitting for refrigerated production encounter incompatible pasteurization protocols and packaging sterilization requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Temperature Yogurt Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Greek Yogurt, Regular Yogurt, Frozen Yogurt, Drinkable Yogurt Packaging Type: Plastic Cups, Glass Jars, Tetra Packs, Pouches Distribution Channel: Supermarkets, Specialty Stores, Online Retail, Convenience Stores Consumer Type: Health-Conscious Consumers, Families, Fitness Enthusiasts, Kids |
| Companies Covered | Danone, China Mengniu Dairy Company Limited, Inner Mongolia Yili Industrial Group, Chobani, Nestlé, Lactalis, General Mills, Unternehmensgruppe Theo Müller, Fage International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Temperature Yogurt Market Trends and Innovations
Refrigerated dairy is experiencing simultaneous pressure from automation investments, regulatory tightening on health claims, and channel fragmentation that separates fitness-oriented consumption from family household purchasing.
Continuous-flow fermentation technology is automating culture propagation and inoculation sequences that previously required manual batch monitoring. Mid-sized producers in Germany and South Korea are adopting these systems to reduce labor dependence while maintaining EFSA-compliant live-culture documentation. The technology is automating quality-control sampling intervals, compressing the gap between artisanal batch consistency and industrial throughput economics.
China's SAMR dairy safety protocols are tightening import documentation requirements for refrigerated probiotic products, mandating cold-chain temperature logs from production through retail. Domestic manufacturers with captive distribution networks gain compliance advantage over importers dependent on third-party logistics. The regulations are accelerating consolidation among Chinese producers capable of end-to-end cold-chain verification.
Fitness enthusiasts are shifting refrigerated yogurt purchasing toward subscription-based direct delivery models that bypass conventional grocery restocking cycles. Protein-forward Greek and skyr formats dominate these channels in urban Australia and coastal US markets. The behavior is most pronounced among 25-40 year old consumers who prioritize macronutrient transparency over brand loyalty in refrigerated case selections.
Low Temperature Yogurt Market Segmentation
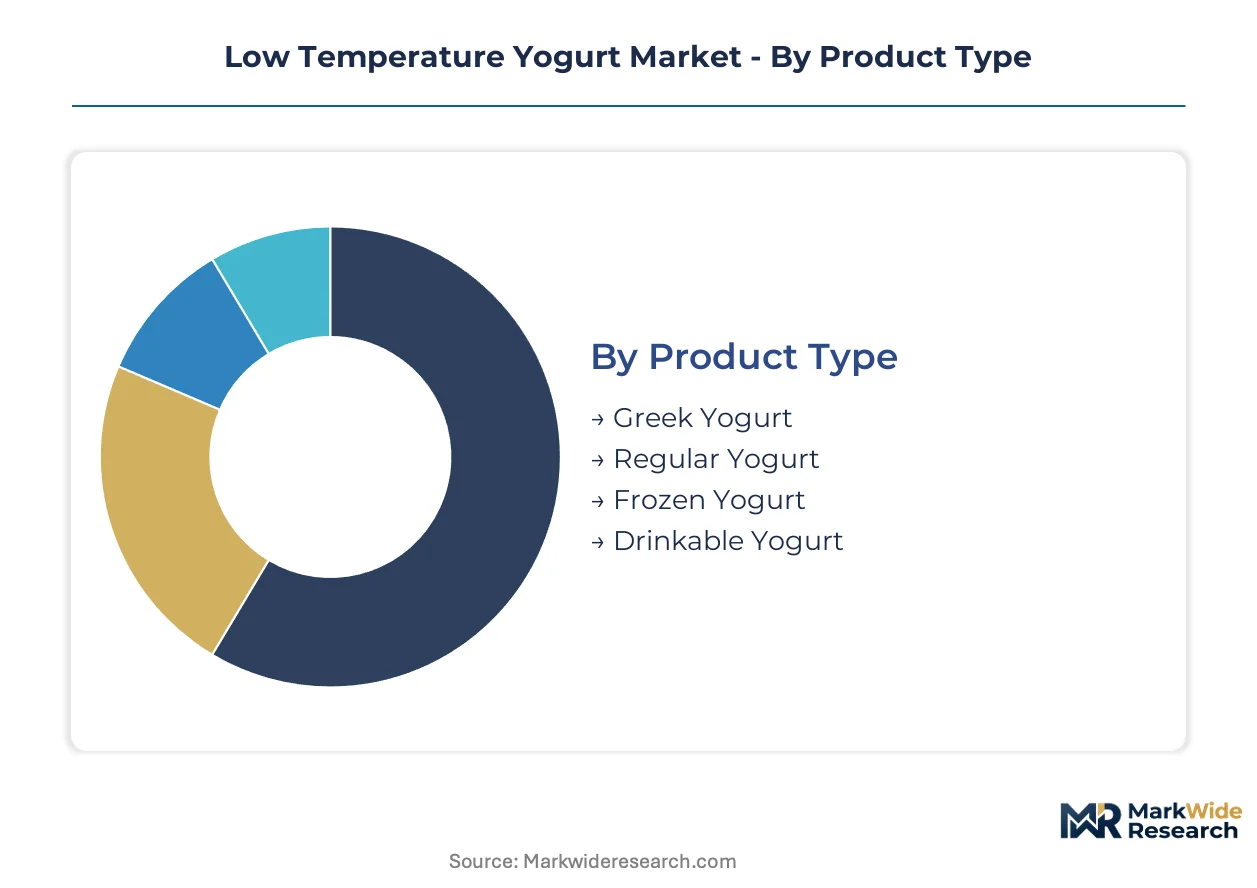
Low temperature yogurt segmentation reflects divergent cold-chain requirements across product formats and packaging technologies. Channel and consumer stratification determines margin capture and live-culture integrity investments.
Product Type:
Strained protein concentration and fermentation duration differentiate functional benefits and shelf positioning.
- Greek Yogurt:Triple-strained whey removal produces 15-20g protein per serving. Demand concentrates in US coastal metropolitan areas where fitness-oriented consumers prioritize macronutrient density. Premium pricing supports cold-chain infrastructure amortization.
- Drinkable Yogurt:Fluid viscosity enables on-the-go consumption through narrow-neck bottles. Expansion concentrates in Chinese tier-one cities where convenience-store penetration supports grab-and-go breakfast substitution. SAMR dairy safety protocols mandate temperature logging from production through retail.
- Regular Yogurt:Standard viscosity with unstrained whey content serves family household volume purchasing.
- Frozen Yogurt:Sub-zero storage requirements create distinct distribution economics through dedicated freezer cabinets.
Mature deployment sits with Regular Yogurt. Newer deployment is concentrated in Drinkable Yogurt.
Packaging Type:
Barrier properties and thermal mass determine cold-chain tolerance and retail display flexibility.
- Plastic Cups:Polypropylene tubs with foil lidding dominate refrigerated case economics. Demand concentrates in North American supermarkets where single-serve portability drives impulse purchasing. Lightweight construction reduces per-unit freight costs.
- Pouches:Flexible film with spout fitments enables consumption without utensils. Expansion concentrates in Japanese convenience channels where fitness enthusiasts prioritize gym-bag portability. Reduced thermal mass requires stricter cold-chain compliance.
- Glass Jars:Premium positioning supports artisanal brand differentiation in European specialty retail.
- Tetra Packs:Aseptic filling compatibility creates hybrid ambient-refrigerated distribution options.
Established infrastructure favors Plastic Cups. Emerging adoption clusters in Pouches.
Distribution Channel:
Slotting fees and temperature control capabilities segment margin structures and brand access.
- Supermarkets:Refrigerated dairy cases with dedicated 4°C maintenance support live-culture viability. Demand concentrates in German and French retail networks where EFSA probiotic claim substantiation commands shelf premiums. Annual price negotiations lock in volume commitments.
- Online Retail:Direct-to-subscription models bypass slotting fees through insulated cold-box delivery. Expansion concentrates in Australian urban corridors where refrigerated last-mile logistics achieve same-day fulfillment. Customer acquisition costs shift from trade spend to digital marketing.
- Specialty Stores:Curated assortments emphasize clean-label certification and local sourcing claims.
- Convenience Stores:Limited cold-case footage prioritizes high-velocity SKUs with extended shelf life.
Volume concentration remains with Supermarkets. Fastest share gains occur in Online Retail.
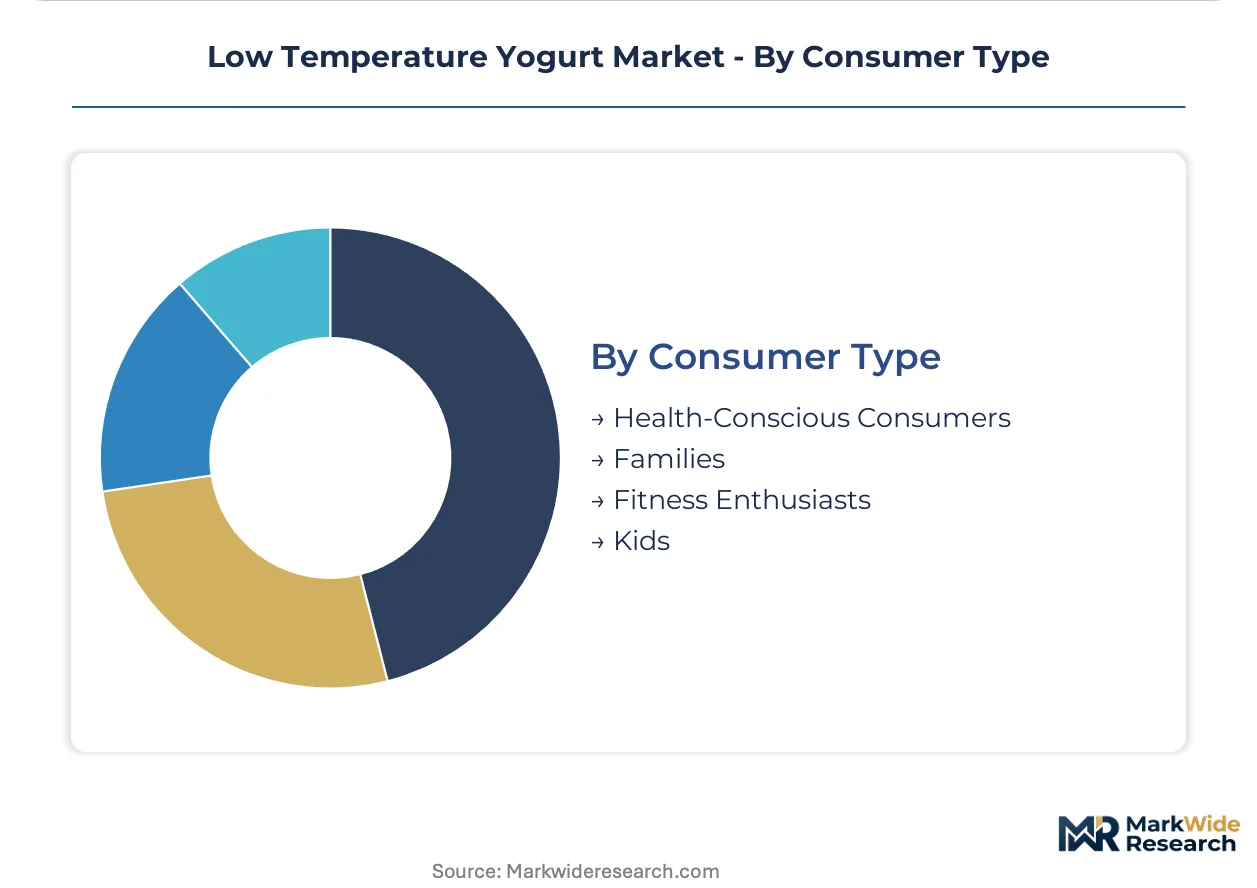
Consumer Type:
Protein targets and sugar tolerance thresholds drive formulation differentiation and channel selection.
- Fitness Enthusiasts:Post-workout protein timing demands 20g+ per serving with sub-5g sugar. Demand concentrates in US gym-channel vending and subscription delivery. Precision fermentation advances enable consistent live-active-culture counts that satisfy FDA standards.
- Health-Conscious Consumers:Probiotic colony-forming-unit transparency prioritizes EFSA-compliant labeling. Expansion concentrates in UK and Netherlands retail where sugar taxation frameworks incentivize reformulation. Clean-label certification determines purchase decisions.
- Families:Multi-serve packaging and mild flavor profiles support household replenishment cycles.
- Kids:Portion-controlled formats with palatable sweetness levels navigate parental purchasing gatekeeping.
Established purchasing sits with Families. Accelerating engagement targets Fitness Enthusiasts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors refrigerated dairy expansion through its integrated cold-chain corridor linking Yangtze River Delta production to metropolitan retail. Tier-one Chinese cities now sustain sub-6°C distribution networks that were impossible five years ago. This infrastructure maturation is redrawing competitive maps across multiple continents.
United States
Fitness-oriented consumers in coastal metros drive protein-forward Greek yogurt demand through gym-channel vending and subscription delivery. FDA live-and-active-culture standards enforce rigorous third-party CFU validation that delays product launches by 45-60 days. New York and Los Angeles concentrate premium refrigerated case space where Chobani and Fage International occupy shelf positions.
China
Urban cold-chain maturation in tier-two cities unlocks refrigerated yogurt penetration previously dominated by ambient-stable alternatives. SAMR dairy safety protocols mandate end-to-end temperature logging from production through retail, favoring domestic producers with captive distribution. Inner Mongolia Yili Industrial Group leverages tier-one city networks to outflank import-dependent competitors.
Germany
EFSA probiotic health claim substantiation requirements accelerate reformulation toward reduced-sugar, high-live-culture recipes commanding retail premiums. Continuous-flow fermentation technology adoption concentrates in Bavarian and North Rhine-Westphalian production facilities. Munich and Cologne anchor automated quality-control sampling that compresses batch-to-batch variability.
India
Mumbai, Bangalore, and Delhi NCR cold-chain investments create first-mover advantage for refrigerated formats in a market historically dominated by ambient curd. FSSAI dairy safety standards are tightening import documentation requirements for probiotic products. Maharashtra and Karnataka production clusters retrofit legacy ambient facilities for refrigerated pasteurization protocols.
Australia
Subscription-based direct delivery models bypass conventional grocery slotting fees through insulated cold-box fulfillment in Sydney and Melbourne corridors. Protein-forward skyr formats penetrate fitness-center retail with macronutrient transparency prioritizing brand-agnostic purchasing. TGA oversight of therapeutic probiotic claims shapes formulation substantiation investments.
Low Temperature Yogurt Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across refrigerated dairy value chains. Cold-chain infrastructure ownership separates national-scale players from regional contract manufacturers dependent on third-party logistics. Three archetypes dominate: integrated dairy conglomerates with captive distribution, specialized Greek yogurt fermenters leveraging protein concentration premiums, and emerging drinkable-format specialists exploiting Asian convenience channels. Consolidation pressures concentrate among cold-chain capitalized operators, while portfolio diversification toward plant-based alternatives displaces conventional probiotic positioning.
Within the integrated conglomerate tier, Danone and Nestlé occupy positions exemplifying transnational refrigerated dairy scale. China Mengniu Dairy Company Limited and Inner Mongolia Yili Industrial Group represent domestic Chinese producers leveraging SAMR compliance advantages and tier-one city distribution density. Among specialized fermenters, Chobani and Fage International anchor Greek yogurt positioning through protein concentration differentiation. Unternehmensgruppe Theo Müller and Lactalis sit within European premium-private-label intersections where EFSA claim substantiation creates regulatory moats.
| Leading Market Players |
|---|
| Danone |
| China Mengniu Dairy Company Limited |
| Inner Mongolia Yili Industrial Group |
| Chobani |
| Nestlé |
| Lactalis |
| General Mills |
| Unternehmensgruppe Theo Müller |
| Fage International |
| Others |
Pricing and Supply Chain Analysis
Fluid milk procurement costs cascade through refrigerated yogurt pricing tiers from New Zealand and EU auction floors to retail shelf positioning, with protein concentration levels and live-culture certification grades separating premium Greek formats from commodity private-label alternatives. Cold-chain capital intensity concentrates margin capture among producers with captive distribution networks, forcing asset-light competitors toward contract manufacturing arrangements that surrender pricing autonomy.
Pricing Analysis
Value-based pricing anchors on live-active-culture counts at expiration and protein density per serving, with EFSA-compliant probiotic substantiation commanding retail premiums over generic fermented alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects cold-chain reliability certification, brand heritage, and sugar reduction compliance. Cost compression in private-label tiers intensifies because fluid milk price volatility transfers directly through annual retail price agreements. Fitness enthusiasts demonstrate lowest price sensitivity, prioritizing macronutrient transparency over per-unit cost, while family household purchasers gravitate toward promotional multi-buy formats.
Supply Chain Analysis
Dual-sourcing requirements for starter culture strains and specialized probiotic inoculants mandate multi-supplier qualification across European fermentation technology providers and North American culture banks. Geographic supply concentration centers on Germany, France, and the Netherlands for precision fermentation equipment; New Zealand and the EU for fluid milk powders; and China for polypropylene packaging substrates. Raw material dependencies rest on lactose derivatives, specialized bacterial cultures, and cold-chain refrigerants. Single-source vulnerability pervades live-culture strain intellectual property held by concentrated fermentation technology licensors. Distribution runs through refrigerated depot networks with HACCP-compliant multi-temperature zone capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The low temperature yogurt market is becoming a vertical-integration race, with cold-chain infrastructure ownership and proprietary starter culture development emerging as the decisive upstream and downstream levers separating national-scale competitors from margin-squeezed contract manufacturers.
For Market Incumbents: Cement shelf-position dominance through backward integration into captive starter culture propagation facilities, reducing batch-to-batch variability and accelerating EFSA-compliant product launch timelines. Fortify tier-one Chinese city distribution density against SAMR-compliant domestic producers by acquiring refrigerated logistics operators in Yangtze River Delta corridors. Plant-based substitution in North American natural-food channels threatens conventional dairy probiotic positioning.
For New Entrants and Emerging Players: Enter via Indian metropolitan cold-chain infrastructure gaps in Mumbai and Bangalore, where refrigerated format penetration remains nascent against ambient curd dominance. Target sports nutrition channel convergence through protein-fortified Greek yogurt vending placements in fitness centers, bypassing supermarket slotting fee barriers. Direct-to-subscription delivery models anchored on macronutrient transparency offer the most penetrable go-to-market angle among 25-40 year old urban consumers.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap refrigerated logistics operators in Australia and coastal US markets, where subscription-based fulfillment infrastructure trades below replacement cost amid capital constraints. Long-term viability across the analysis window hinges on cold-chain verification technology and clean-label certification capabilities rather than brand equity alone. Watch for sugar taxation framework adoption in Mexico and UK levy expansion discussions as inflection indicators for reformulation investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Acquisition | Captive refrigerated logistics networks satisfy SAMR temperature logging mandates in China. |
| Precision Fermentation Technology Adoption | Continuous-flow systems reduce labor dependence while maintaining EFSA live-culture documentation. |
| Protein-Fortified Format Extension | Greek and skyr variants penetrate gym-channel vending with 20g+ protein positioning. |
| Subscription Delivery Model Launch | Insulated cold-box fulfillment bypasses supermarket slotting fees in Australian urban corridors. |
| Clean-Label Certification Investment | Reduced-sugar formulations align with UK soft drinks levy expansion discussions. |
Research Methodology
Multi-period observation of cold-chain infrastructure deployment, probiotic health claim substantiation timelines, and refrigerated dairy case space allocation anchored the trend analysis, supplemented by interviews with fermentation technology directors, cold-chain logistics managers, supermarket category buyers, dairy safety compliance officers, and sports nutrition channel distributors. Secondary validation drew from FDA live-and-active-culture standards documentation, EFSA probiotic claim guidance, SAMR dairy safety protocol releases, Nielsen retail audit data, and EU dairy auction price series. Bottom-up volume modeling across product formats triangulated against top-down category spend estimates.
Input-output matrix framing connected fluid milk input costs, fermentation duration parameters, and cold-chain depreciation schedules to price realization across distribution channels. Segmentation dimensions modeled encompassed product type, packaging technology, distribution channel, and consumer archetype alongside regional regulatory cluster variations. CAGRs were derived from slope-intercept trajectory fitting across the projection horizon. Industry-specific forecast inputs incorporated cold-chain reliability indices and clean-label certification penetration curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt sugar taxation implementation or live-culture validation timeline extensions. Forecasts reflect documented assumptions regarding cold-chain infrastructure maturation rates and probiotic health claim substantiation evolution. Deviation in EU clean-label mandate enforcement intensity or New Zealand fluid milk auction volatility would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Buttermilk Powder Market
Dairy Products
Europe Drinkable Yogurt Market
Dairy Products
Low-Lactose Dairy Foods Market
Dairy Products
Solidified Yogurt Market
Dairy Products
Canada Dairy Market
Dairy Products
Lactose Free Dairy Products Market
Dairy Products
Germany Milk Protein Market
Dairy Products
Mexico Lactose-Free Dairy Market
Dairy Products
North America Casein Market
Dairy Products
Fruit Yogurt Market
Dairy Products
Cheddar Cheese Market
Dairy Products
Dairy Blends Market
Dairy Products
Middle East and Africa Flavored Milk Market
Dairy Products
Asia-Pacific Dairy Protein Market
Dairy Products
Europe Dairy Market
Dairy Products
US and Europe Nuts and Seeds Cheese Market