
 Alginate Casings Market | 2026-2036
Alginate Casings Market Size, Share, and Industry Trends Forecast 2026-2036
Alginate Casings Market Analysis
Plant-based protein processors are unwinding long-standing reliance on traditional collagen and cellulose casings as alginate formulations gain formulation share among clean-label meat alternatives. FMC Corporation leverages its marine biopolymer extraction infrastructure to supply food-grade sodium alginate at scale. Cargill anchors its position through backward integration into seaweed sourcing, while ALGAIA specializes in tailored viscosity grades for extruded sausage analogues.
Alginate casings are edible or non-edible tubular films formed from salts of alginic acid, typically cross-linked with calcium ions to create thermally stable, moisture-retentive barriers with gel strengths ranging from 200 to 800 mPa·s depending on seaweed source and extraction method. These structures serve primarily to shape, protect, and texturize processed meat, seafood, and plant-based analogue products during thermal processing and shelf-stable distribution. Fibrous alginate variants lead in high-speed industrial sausage production where tensile strength determines line efficiency, while uncoated grades capture growth in small-batch artisan applications where simplicity and cost control matter more than barrier performance. Composite formulations, blending alginate with pectin or carrageenan, concentrate margin pools in pharmaceutical encapsulation where modified-release kinetics command specification premiums.
FDA food-contact substance notifications and EU REACH compliance requirements jointly determine which seaweed-derived extracts achieve commercial food-grade status, with EFSA evaluations of heavy-metal bioaccumulation in brown algae directly constraining European supply eligibility. The US EPA and state-level water-quality regulators in California influence extraction facility siting for domestic alginate producers, adding geographic contingency to capacity planning. Stakeholders must monitor evolving EFSA guidance on novel food classifications for fermented alginate variants, as reclassification would trigger extended safety assessment timelines and reshape competitive access to European food processing channels.
Market Dynamics
Plant-based sausage manufacturers are accelerating alginate casing adoption as collagen alternatives face scrutiny from European regulators and clean-label consumers. This shift concentrates procurement power among mid-sized extrusion facilities seeking thermally stable, moisture-retentive barriers without animal-derived inputs.
Growth Catalysts
- EU REACH compliance pressure:Heavy-metal bioaccumulation limits on brown algae extracts are disqualifying legacy collagen suppliers, redirecting formulation budgets toward certified sodium alginate grades.
- German retail shelf economics:Clean-label meat alternatives command premium placement in Bundesrepublik supermarkets, forcing processors to switch casing materials for label compliance.
- Calcium-ion cross-linking advances:Improved gel strength consistency above 600 mPa·s enables high-speed industrial sausage lines to maintain throughput without cellulose backup stocks.
Market Restraints
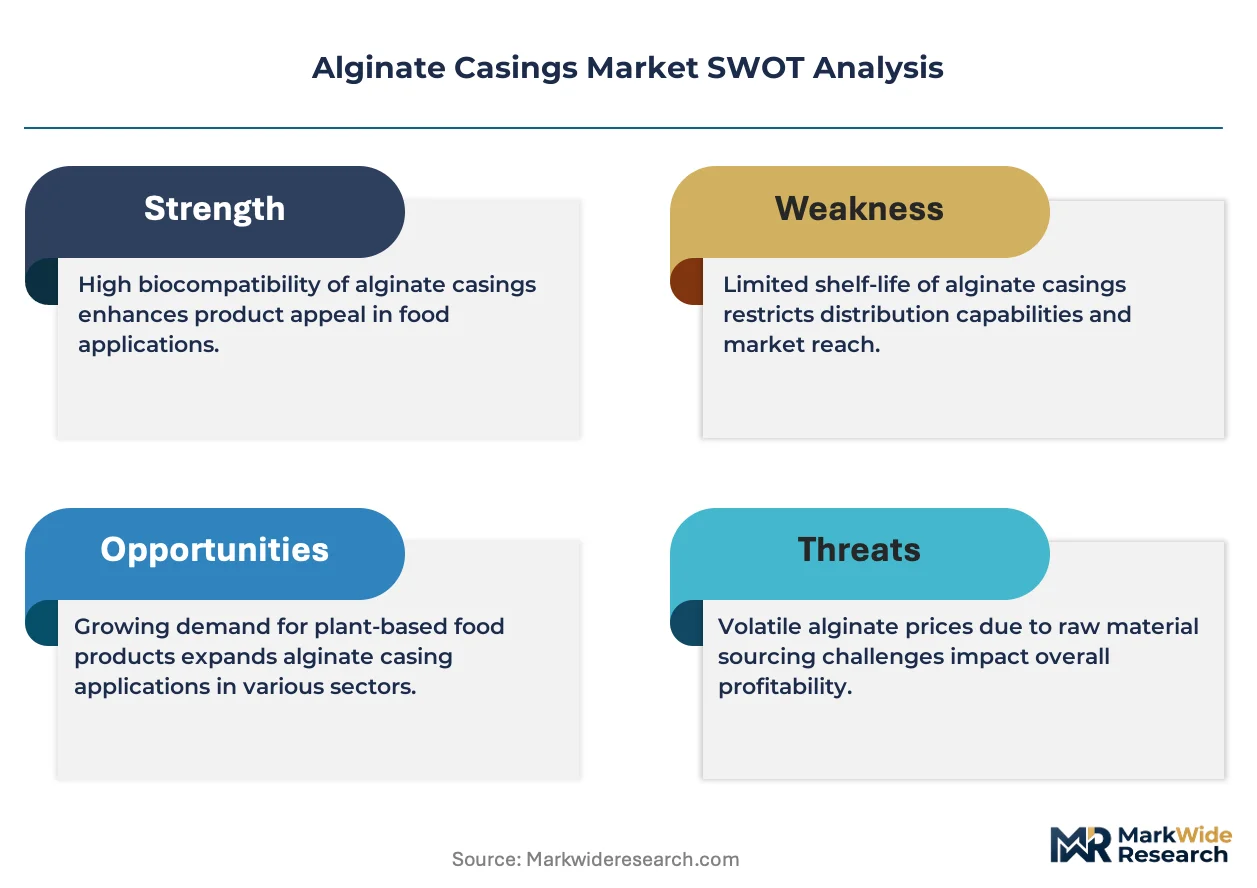
- Seaweed supply geography:Laminaria digitata harvests concentrate in coastal Norway and France, exposing processors to North Atlantic weather volatility and quota restrictions.
- Extraction facility siting:US EPA water-quality standards in California and Maine constrain domestic alginate production capacity, perpetuating import dependence for North American food processors.
- Collagen price compression:Bovine and porcine hide-derived casings retain cost advantages in commodity sausage segments, limiting alginate penetration below premium positioning tiers.
Strategic Opportunities
- Pharmaceutical encapsulation convergence:Modified-release kinetics from alginate-pectin composites command specification premiums in oral dosage manufacturing, opening margin pools beyond food applications.
- Artisan processor channel:Uncoated alginate grades capture growth in small-batch operations where simplicity and cost control outweigh barrier performance requirements.
- EFSA novel food pathway:Fermented alginate variants awaiting reclassification create first-mover advantage for suppliers completing extended safety assessments ahead of regulatory clarity.
Industry Challenges
- Marine polymer extraction talent:Food-grade sodium alginate purification requires specialized phycologists and process chemists in short supply outside established seaweed research clusters.
- Dual certification timelines:Simultaneous FDA food-contact substance notification and EU REACH dossier preparation extends commercialization cycles by 18-24 months for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alginate Casings Market |
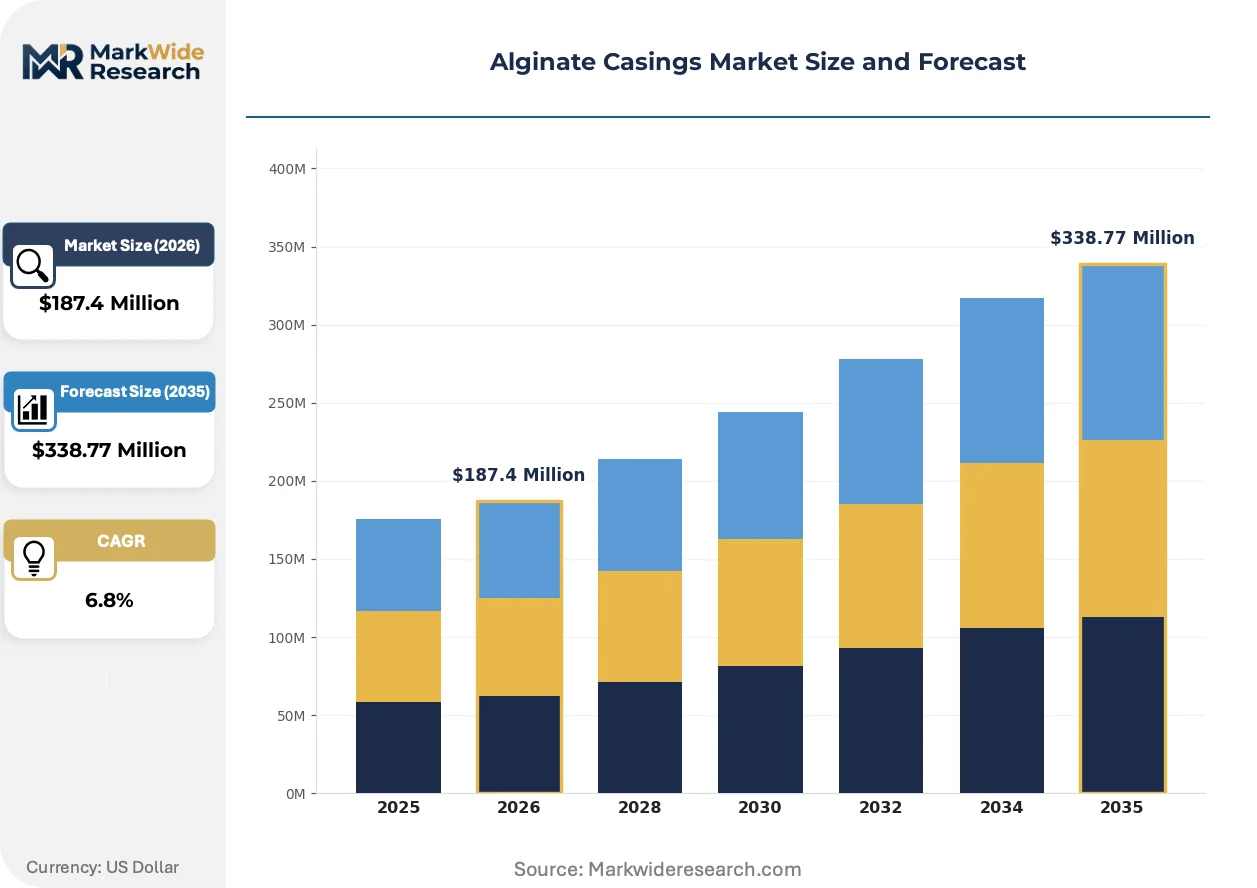
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
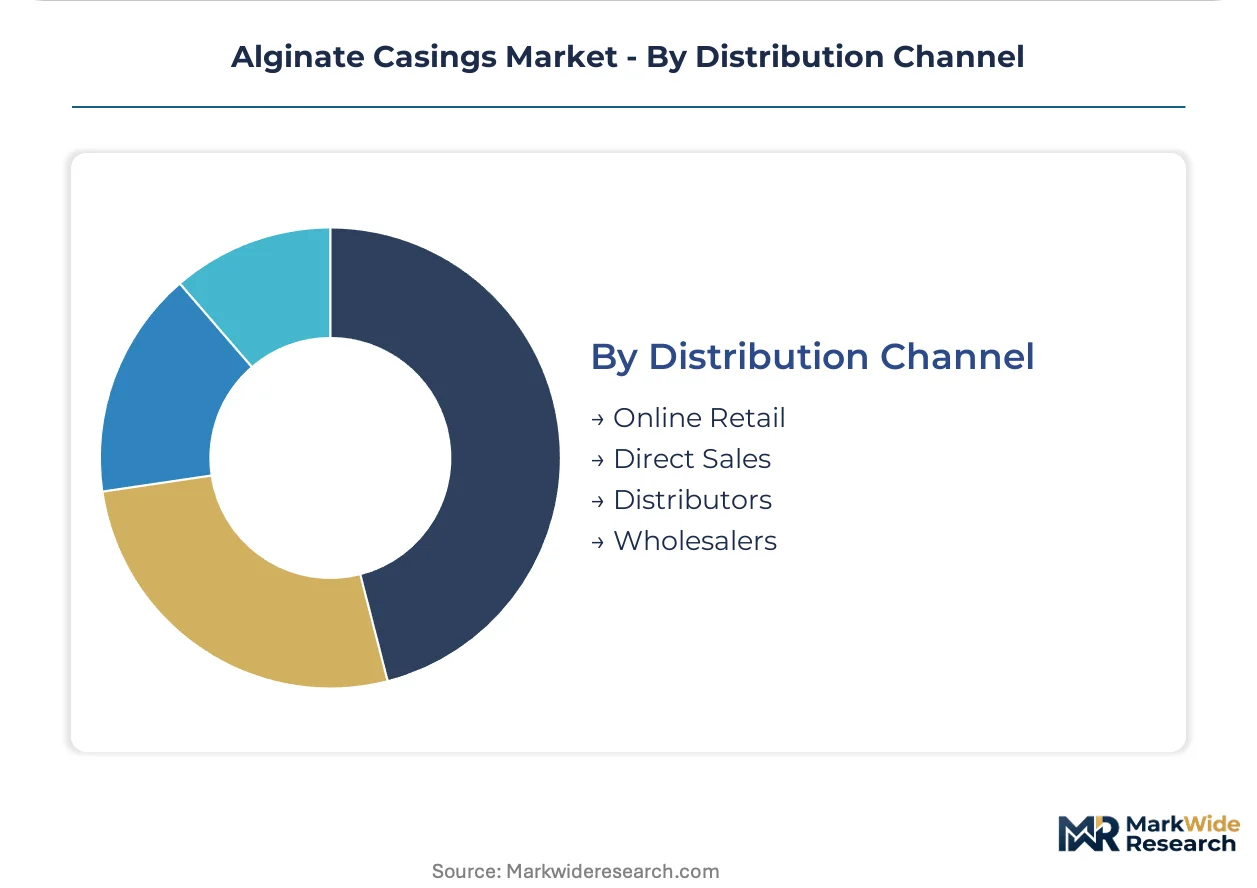
| Segmentation | Product Type: Fibrous, Coated, Uncoated, Composite End User: Food Processing, Pharmaceuticals, Nutraceuticals, Cosmetics Application: Biodegradable Packaging, Edible Films, Encapsulation, Coating Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | FMC Corporation, Promar, Visko Teepak, Reiser, Qingdao Hyzlin Biology Technology Development Co., Vaessen-Schoemaker, Cargill, ALGAIA, Ceamsa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alginate Casings Market Emerging Trajectories
Extrusion technology and regulatory reclassification are jointly reshaping how alginate casings penetrate food and pharmaceutical manufacturing. These forces compress legacy material margins while opening specification-controlled premium segments.
Fibrous alginate variants optimized for tensile strength above 500 mPa·s are displacing cellulose casings in high-speed industrial sausage production. German and Dutch plant-based meat processors have adopted these grades at line speeds exceeding 300 units per minute. The structural consequence is margin compression for cellulose suppliers unable to match thermal stability performance.
EFSA evaluations of heavy-metal bioaccumulation in brown algae are tightening European supply eligibility beyond existing REACH frameworks. Food-grade alginate producers must now document cadmium and lead levels below 0.5 ppm across harvest batches. German and French extraction facilities are responding by vertically integrating into controlled aquaculture sourcing rather than wild harvest dependence.
Ingredient procurement for clean-label meat alternatives now prioritizes single-source seaweed traceability over cost minimization. Retailers in Berlin and Munich are rejecting blended-origin alginate certificates, forcing processors to consolidate supplier relationships. This behavioral shift concentrates procurement volume among three certified Norwegian and French extraction operations with full-chain documentation systems.
Alginate Casings Market Segmentation
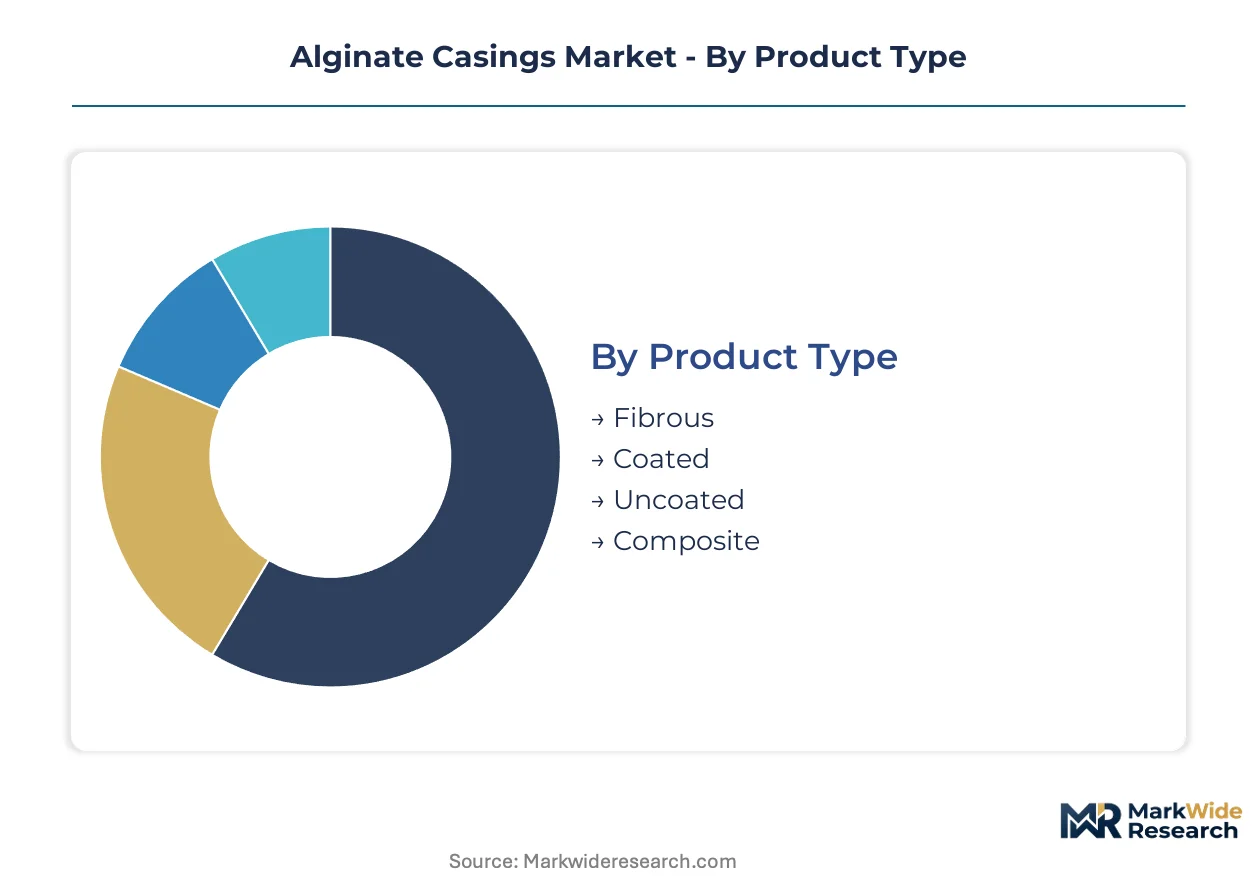
Alginate casing procurement patterns diverge sharply across product grades and end-use channels. Material specifications, regulatory compliance tiers, and distribution economics reshape how suppliers structure their segment portfolios.
Product Type:
Domestic production concentrates fibrous and coated grades in Norway and France for European food processors. Export-led segments serve North American pharmaceutical and Asian nutraceutical manufacturers through specialized viscosity certification.
- Fibrous:High-tensile formulations above 500 mPa·s withstand industrial sausage line speeds exceeding 300 units per minute. German and Dutch plant-based meat processors dominate procurement volumes as clean-label requirements displace cellulose alternatives.
- Composite:Alginate-pectin and alginate-carrageenan blends enable modified-release kinetics in oral dosage manufacturing. Pharmaceutical encapsulation demand in Switzerland and Germany commands specification premiums beyond food-grade margins.
- Coated:Barrier-enhanced films for moisture-sensitive applications serve premium processed seafood distribution in Japan and South Korea.
- Uncoated:Simplified grades capture artisan processor channels where cost control outweighs barrier performance requirements.
Fibrous commands the established base. The steepest expansion runs through Composite.
End User:
Cost tier stratification separates commodity food processing from premium pharmaceutical and cosmetics applications. Certification requirements and batch documentation intensity determine margin capture across these verticals.
- Food Processing:Sausage, seafood, and plant-based analogue manufacturers drive volume demand. EFSA heavy-metal limits below 0.5 ppm cadmium and lead constrain European supply eligibility, redirecting procurement toward certified Norwegian and French extraction operations with full-chain traceability systems.
- Pharmaceuticals:Modified-release encapsulation and wound dressing applications require GMP-compliant sodium alginate with documented endotoxin levels. Swiss and German dosage form manufacturers specify viscosity grades between 200-800 mPa·s with batch-specific certificates of analysis.
- Nutraceuticals:Probiotic and omega-3 encapsulation demand climbs in North American and Asian supplement markets.
- Cosmetics:Film-forming and thickening applications in skincare formulations utilize food-grade surplus streams.
Food Processing absorbs the volume anchor. Pharmaceuticals generate the margin concentration.
Application:
Volume scale separates mass-market biodegradable packaging from specialized encapsulation and coating segments. Customer type fragmentation—industrial processors versus research laboratories—shapes procurement channel selection.
- Encapsulation:Oral dosage and nutraceutical delivery systems require precise gel strength control for release kinetics. German pharmaceutical manufacturers specify alginate-pectin composites for colon-targeted delivery, paying premiums for documented dissolution profiles under USP and EP methodologies.
- Edible Films:Direct-consumption casings for processed meat and plant-based alternatives eliminate disposal requirements. French and Italian charcuterie processors adopt these grades for premium product positioning in domestic and export markets.
- Biodegradable Packaging:Non-food film applications expand in European single-use plastic restriction zones.
- Coating:Moisture barrier layers for fresh-cut produce and seafood extend shelf life in Japanese retail distribution.
Encapsulation delivers the margin pool. Edible Films scale the fastest operationally.
Distribution Channel:
Supply concentration in coastal extraction clusters dictates channel economics. Direct relationships with Norwegian and French producers dominate high-volume procurement, while fragmented buyer geography sustains intermediary layers.
- Direct Sales:Large food processors and pharmaceutical manufacturers contract directly with FMC Corporation, Cargill, and ALGAIA for certified sodium alginate volumes. These arrangements bypass distributor margins and enable custom viscosity grade production with dedicated batch documentation.
- Distributors:Regional chemical and ingredient distributors serve mid-sized processors lacking procurement scale for direct manufacturer relationships. German and Benelux distribution networks maintain inventory positions for just-in-time delivery to sausage and analogue manufacturers.
- Online Retail:Small-batch artisan processors and research laboratories source gram-to-kilogram quantities through specialized biochemical suppliers.
- Wholesalers:Commodity-grade alginate for non-food industrial applications moves through bulk chemical trading channels.
Direct Sales anchors high-volume procurement. Distributors capture the mid-market expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norwegian extraction facilities export certified sodium alginate to German and Dutch food processors, establishing the dominant Atlantic trade corridor for food-grade marine biopolymers.
Germany
Berlin and Munich retailers enforce clean-label compliance for plant-based meat alternatives, rejecting blended-origin alginate certificates. EFSA heavy-metal limits below 0.5 ppm cadmium constrain supply eligibility. Bavarian sausage manufacturers operate high-speed extrusion lines exceeding 300 units per minute using fibrous alginate grades.
France
Coastal extraction clusters in Brittany process Laminaria digitata harvests for domestic charcuterie and pharmaceutical encapsulation. REACH compliance requirements disqualify legacy collagen suppliers from export markets. The Normandy food processing corridor adopts edible alginate films for premium positioning in Italian export channels.
Norway
Controlled aquaculture sourcing replaces wild harvest dependence for North Atlantic brown algae. The country's national pharmaceutical regulator aligns with EFSA bioaccumulation standards. Bergen-area extraction operations supply full-chain traceability documentation required by Bundesrepublik supermarket procurement teams.
United States
California and Maine extraction facilities face EPA water-quality constraints that perpetuate import dependence. FDA food-contact substance notifications determine commercial food-grade status for seaweed-derived extracts. Midwestern sausage processors source certified sodium alginate through direct contracts with Atlantic suppliers.
Japan
Premium processed seafood distribution in Tokyo and Osaka drives demand for coated alginate barrier films. METI standards influence regional adoption of moisture-retentive packaging technologies. The Kanto industrial corridor integrates alginate casings into shelf-life extension systems for fresh-cut produce retail.
Alginate Casings Market Vendor Landscape
Listed leaders compete with private specialists across certification tiers and sourcing geographies. The vendor base separates into three functional layers: multinational chemical conglomerates with marine biopolymer divisions, dedicated alginate extraction specialists with coastal facility networks, and regional distributors serving mid-sized processors lacking procurement scale. Two strategic archetypes dominate competitive positioning: backward-integrated seaweed harvesters controlling supply from aquaculture through purification, and formulation technology licensors enabling customer-specific viscosity grades. M&A activity concentrates on captive supply acquisitions, while capacity expansion focuses on GMP-compliant pharmaceutical-grade production lines.
Among publicly traded chemical conglomerates, FMC Corporation exemplifies the scale-driven archetype through its marine biopolymer extraction infrastructure. Cargill occupies a position within the agribusiness-integrated tier, leveraging upstream control over seaweed sourcing networks. ALGAIA represents the specialist archetype, anchoring the tailored viscosity grade segment for extruded sausage analogue applications. These three entities collectively illustrate how competitive positioning fragments across certification depth, geographic sourcing control, and end-use specification intensity.
| Leading Market Players |
|---|
| FMC Corporation |
| Promar |
| Visko Teepak |
| Reiser |
| Qingdao Hyzlin Biology Technology Development Co. |
| Vaessen-Schoemaker |
| Cargill |
| ALGAIA |
| Ceamsa |
| Others |
Supply Flow & Price Mechanics
Collagen-to-alginate substitution in European sausage manufacturing simultaneously concentrates supply geography around Norwegian and French extraction clusters and compresses pricing premiums for legacy animal-derived casings. This dual restructuring forces processors to absorb certification costs for heavy-metal-compliant sodium alginate while suppliers capture margin from REACH-driven supply disqualification.
Pricing Analysis
Cross-generation pricing gaps separate legacy collagen casings from current-generation fibrous alginate grades and next-generation fermented variants awaiting EFSA novel food classification. Three-tier pricing structure across premium pharmaceutical-grade, standard food-grade, and economy uncoated levels reflects certification depth and batch documentation intensity. Cost compression in standard food-grade tiers intensifies as German retailers reject blended-origin certificates and consolidate procurement among three certified Norwegian and French suppliers. Small-batch artisan processors exhibit highest price sensitivity, while Swiss pharmaceutical encapsulation manufacturers absorb premiums for GMP-compliant sodium alginate with documented endotoxin levels.
Supply Chain Analysis
North Atlantic weather volatility at Laminaria digitata harvest zones in coastal Norway and France creates seasonal chokepoints that constrain processor inventory planning. Supply concentrates in these two countries for food-grade extraction, with China and Japan contributing pharmaceutical-grade purification capacity. Raw material dependencies center on brown algae biomass, calcium chloride cross-linking agents, and purified water systems meeting EPA discharge standards. Single-source vulnerability runs through wild harvest dependence as extraction facilities transition toward controlled aquaculture sourcing. Distribution runs through direct manufacturer contracts for high-volume German and Dutch processors, with regional distributors capturing mid-sized Benelux sausage manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense as collagen suppliers invest in heavy-metal remediation to reclaim European formulation share from alginate incumbents. Incumbents must navigate this threat while capturing pharmaceutical encapsulation premiums.
For Market Incumbents: Shield market position by securing captive supply through backward integration into Norwegian controlled aquaculture operations, eliminating wild harvest volatility that disrupts German retailer compliance timelines. Accelerate EFSA novel food dossier completion for fermented alginate variants to establish first-mover regulatory moats against collagen remediation advances. Prioritize GMP-compliant pharmaceutical-grade capacity expansion in Bergen-area extraction clusters where Swiss and German dosage form manufacturers concentrate procurement. For New Entrants and Emerging Players: Service-layer gaps in small-batch artisan processor technical support create entry points where incumbent chemical conglomerates under-invest. Target uncoated alginate grades for French and Italian charcuterie operations seeking simplified extrusion without barrier performance requirements. Deploy direct-to-processor technical service teams offering viscosity calibration and line-speed optimization, bypassing distributor relationships that fragment margin capture. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed coastal extraction specialists possessing full-chain traceability systems but lacking pharmaceutical-grade certification infrastructure. Five-to-ten year viability hinges on regulatory divergence between EFSA heavy-metal frameworks and FDA food-contact substance pathways, with multi-certification capabilities commanding acquisition premiums. Monitor EFSA novel food reclassification timelines as inflection indicator for fermented variant competitive access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Controlled Aquaculture | Eliminates North Atlantic weather volatility disrupting German retailer compliance timelines. |
| GMP-Compliant Pharmaceutical-Grade Capacity Expansion | Captures specification premiums from Swiss and German oral dosage manufacturers. |
| EFSA Novel Food Dossier Completion | Establishes first-mover regulatory moat for fermented alginate variants ahead of competitor filings. |
| Direct Technical Service Deployment | Bypasses distributor margin fragmentation in French and Italian artisan processor channels. |
| Multi-Certification Infrastructure Investment | Enables simultaneous FDA notification and REACH dossier preparation compressing commercialization cycles. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EFSA guidance documents, FDA food-contact substance notifications, and trade flow data from Norwegian and French customs authorities. Primary interviews engaged extraction facility operations managers, German sausage manufacturer procurement directors, Swiss pharmaceutical formulators, and marine biopolymer R&D specialists at coastal research clusters. Secondary validation drew from REACH compliance databases, EMA regulatory filings, and SEC disclosures from publicly traded chemical conglomerates with marine biopolymer divisions. Bottom-up demand modeling from processor consumption patterns triangulates against top-down supply capacity assessments from extraction facility audits.
Segmentation dimensions modeled span product grade tier, end-use vertical, application type, and distribution channel structure across the analysis window. CAGRs derive from volume trajectory analysis incorporating substitution elasticity estimates between alginate and collagen casings, regulatory compliance cost pass-through rates, and pharmaceutical encapsulation specification premium capture. Industry-specific forecast inputs include EFSA heavy-metal limit enforcement timelines and German retailer clean-label procurement policy evolution.
Forecasts assume regulatory continuity in EU REACH and FDA food-contact substance regimes; material policy shifts would require re-modeling substitution dynamics and certification cost structures. Practitioners should keep alternative scenarios live as EFSA novel food classification decisions and collagen supplier remediation investments evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Protein Packed Foods Market
Packaged Foods
Bangladesh Instant Noodles Market
Packaged Foods
Cookie Butter Spread Market
Packaged Foods
Reduced Fat Packaged Food Market
Packaged Foods
United States Online Grocery Market
Packaged Foods
Japan Packaged Food Products Market
Packaged Foods
Brio Bowls Market
Packaged Foods
Iraq Dried Pasta Market
Packaged Foods
Quinoa Pasta Market
Packaged Foods
Private Label Food and Beverage Market
Packaged Foods
Morning Goods Market
Packaged Foods
North America Breakfast Cereals Market
Packaged Foods
Packaged Zhug Market
Packaged Foods
Impulse Ice-Cream Market
Packaged Foods
North America Pasta and Noodles Market
Packaged Foods
Eco Bowls Market