
 Europe Ready Meals Market | 2026-2036
Europe Ready Meals Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Ready Meals Market Foresight
Market Context
Poland is narrowing its production capacity gap with Western European ready meal manufacturing hubs through expanded cold-chain infrastructure and contract manufacturing investments. Nestlé S.A. leverages its pan-European frozen distribution network to sustain shelf presence across multiple price tiers. Bakkavor Group PLC anchors its competitive position through chilled ready meal specialization for UK and Irish retail banners. Kerry Group plc differentiates via taste and texture ingredient systems supplied to both branded and private-label manufacturers.
Technical Definition and Segment Structure
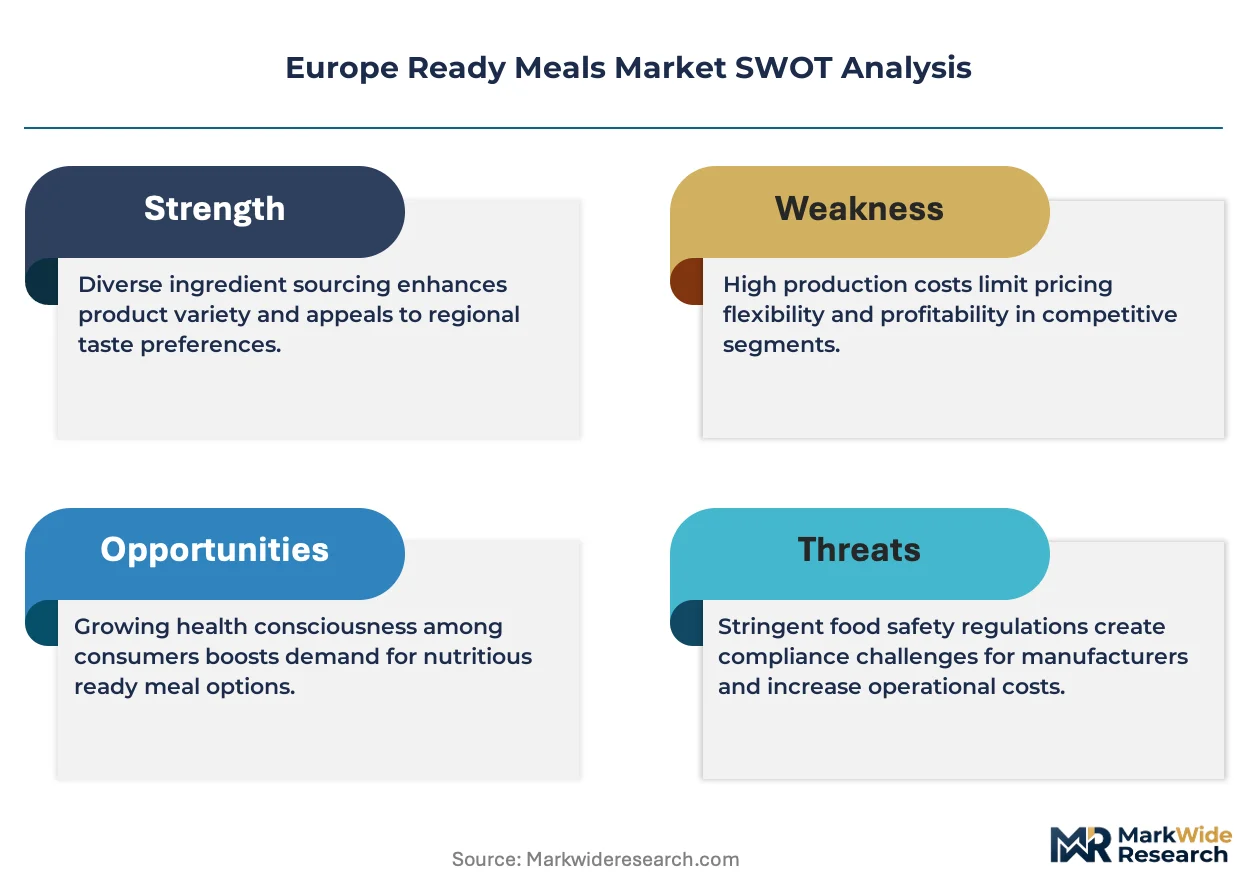
Europe ready meals comprise pre-cooked, portioned food products requiring minimal consumer preparation, typically preserved through freezing, chilling, modified atmosphere packaging, or thermal sterilization to achieve shelf stability. These products serve industrial and commercial purposes by reducing household cooking time, standardizing portion costs, and enabling food service operators to manage labor constraints. Frozen meals occupy the largest volume share due to extended shelf life and established retail freezer infrastructure, while chilled meals capture expanding margin pools through fresher positioning and shorter ingredient declarations. The organic price tier grows fastest among value-oriented segments as EFSA-aligned clean-label claims reshape consumer trust and retail assortment priorities.
Regulatory Framework and Outlook
EU Green Deal packaging regulations and EFSA nutrition labeling standards constrain permissible additives and mandate recyclability timelines across member states. REACH chemical compliance and national food safety authorities in France, Germany, and Italy enforce contaminant thresholds that elevate quality assurance costs for cross-border suppliers. Stakeholders must monitor evolving Extended Producer Responsibility schemes and carbon footprint disclosure rules that will determine which production locations and packaging formats retain retail access.
Market Dynamics
Single-person household expansion across Germany and France is compressing traditional family-format packaging economics while elevating demand for portion-flexible chilled and frozen formats. EU Green Deal packaging mandates and EFSA nutrition labeling requirements are forcing simultaneous reformulation and material transitions that favor suppliers with integrated R&D and regulatory affairs capabilities.
Growth Catalysts
- EU Green Deal packaging mandates:Recyclability timelines are accelerating capital deployment into mono-material films and fiber-based trays, creating first-mover advantages for producers with pilot-scale testing capabilities.
- Chilled ready meal specialization:Shorter ingredient declarations and fresher positioning command retail shelf space premiums in UK and Irish banners, pulling margin pools away from frozen commoditization.
- Poland cold-chain infrastructure:Expanded contract manufacturing investments are narrowing production capacity gaps with Western European hubs, enabling cost-competitive supply to Berlin and Vienna metropolitan corridors.
Market Restraints
- Input cost volatility:Wheat and dairy price swings compress formulation cost predictability for pasta-based and cream-sauce meal lines, forcing hedging costs onto mid-tier producers.
- Supply concentration risk:Modified atmosphere packaging film supply clusters in German and Benelux chemical corridors, exposing cross-border suppliers to single-point disruption.
- Technical limitation:Clean-label preservation without synthetic additives shortens chilled meal shelf life, constraining distribution radius from production facilities.
Strategic Opportunities
- Underpenetrated geography:Southern European markets, particularly Spain and Portugal, show chilled ready meal penetration gaps versus Paris and London benchmarks, offering format introduction potential.
- Regulatory tailwind:EFSA-aligned organic certification claims are reshaping retail assortment priorities, opening shelf space for third-party verified clean-label portfolios.
- Distribution innovation:Direct-to-subscriber chilled meal platforms are bypassing traditional retail slotting fee structures in Scandinavian urban centers.
Industry Challenges
- Skill gap in sensory science:Clean-label reformulation demands expertise in natural flavor modulation and texture engineering that outpaces current food technology graduate pipeline output.
- Capex intensity:Mono-material packaging line conversions require seven-figure capital commitments with payback horizons exceeding typical private-label contract renewal cycles.
- Compliance timeline compression:REACH chemical registration updates and national food safety authority contaminant threshold revisions in France and Italy are accelerating quality assurance system overhaul demands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Ready Meals Market |
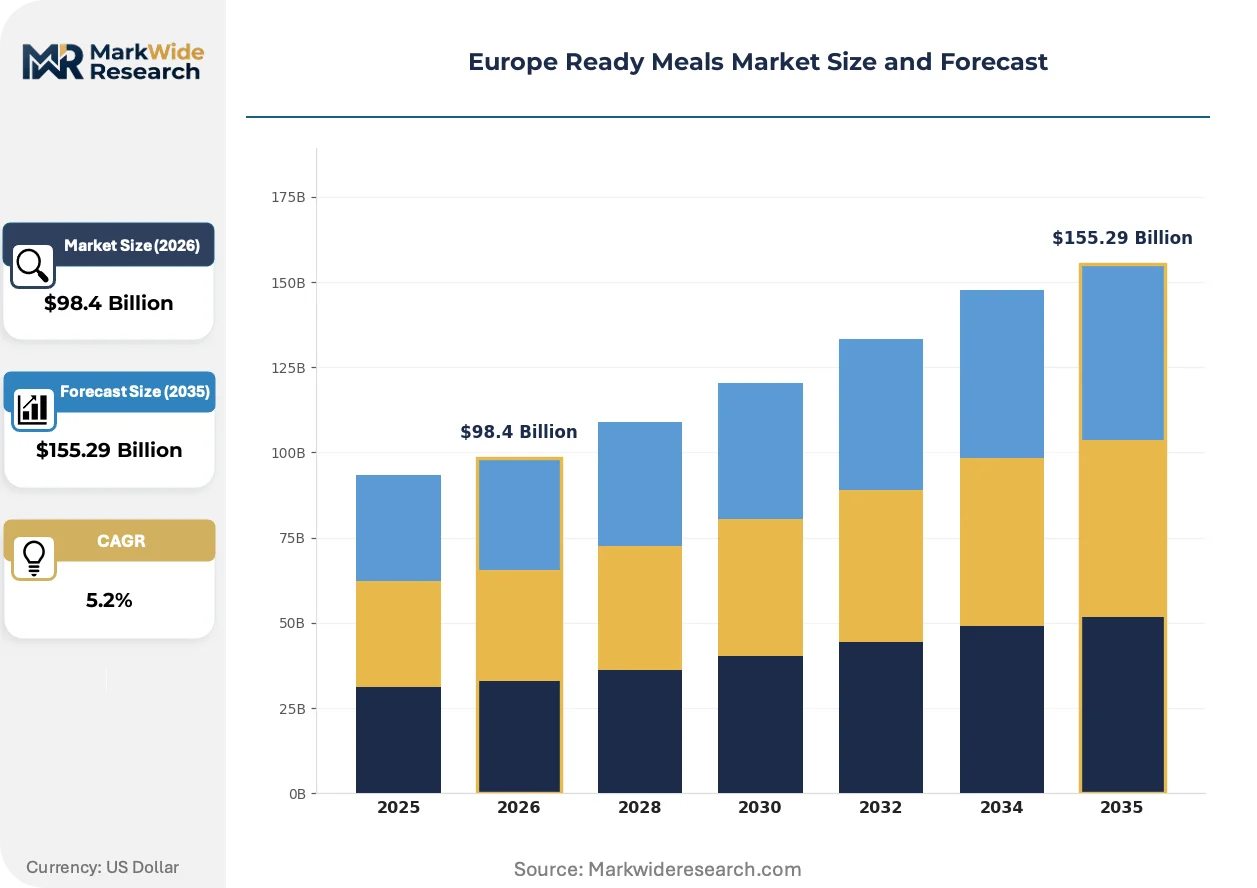
| Market Size in 2026 | $98.4 Billion |
| Market Size in 2035 | $155.29 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Meals, Chilled Meals, Shelf-Stable Meals, Prepared Salads End User: Households, Restaurants, Cafés, Catering Services Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Food Service Price Tier: Premium, Mid-Range, Value, Organic |
| Companies Covered | Dr. Oetker GmbH, Kerry Group plc, Nestlé S.A., 2 Sisters Food Group, Bakkavor Group PLC, Unilever PLC, Orkla ASA, Conagra Brands, Inc., Nomad Foods Ltd., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Ready Meals Market Shifts & Advancements
High-pressure processing and advanced modified atmosphere technologies are collapsing the freshness-versus-shelf-life trade-off that has historically separated chilled from frozen competitive positioning. These innovations enable new product architectures that challenge established category boundaries.
High-pressure processing technology uses extreme isostatic pressure to inactivate spoilage organisms without thermal degradation. Premium chilled meal producers in the UK and Netherlands are adopting systems at commercial scale. This is collapsing the shelf-life gap between chilled and frozen formats, enabling distribution radius expansion without preservative additives.
EFSA nutrition labeling standards now mandate front-of-pack interpretive formats that compress consumer decision time. Manufacturers must reformulate to achieve favorable color-coded scores or accept retail delisting risk. Chilled ready meal portfolios with shorter ingredient lists and controlled sodium content are capturing preferred shelf positioning in French and German banners.
Urban consumer purchasing patterns are fragmenting across channel types, with convenience-store chilled meal capture rising in Paris and Berlin transit corridors. Traditional weekly supermarket stock-up trips are compressing into impulse-driven micro-purchases. This rotation favors localized production footprints and rapid replenishment logistics over centralized frozen distribution networks.
Europe Ready Meals Market Segmentation
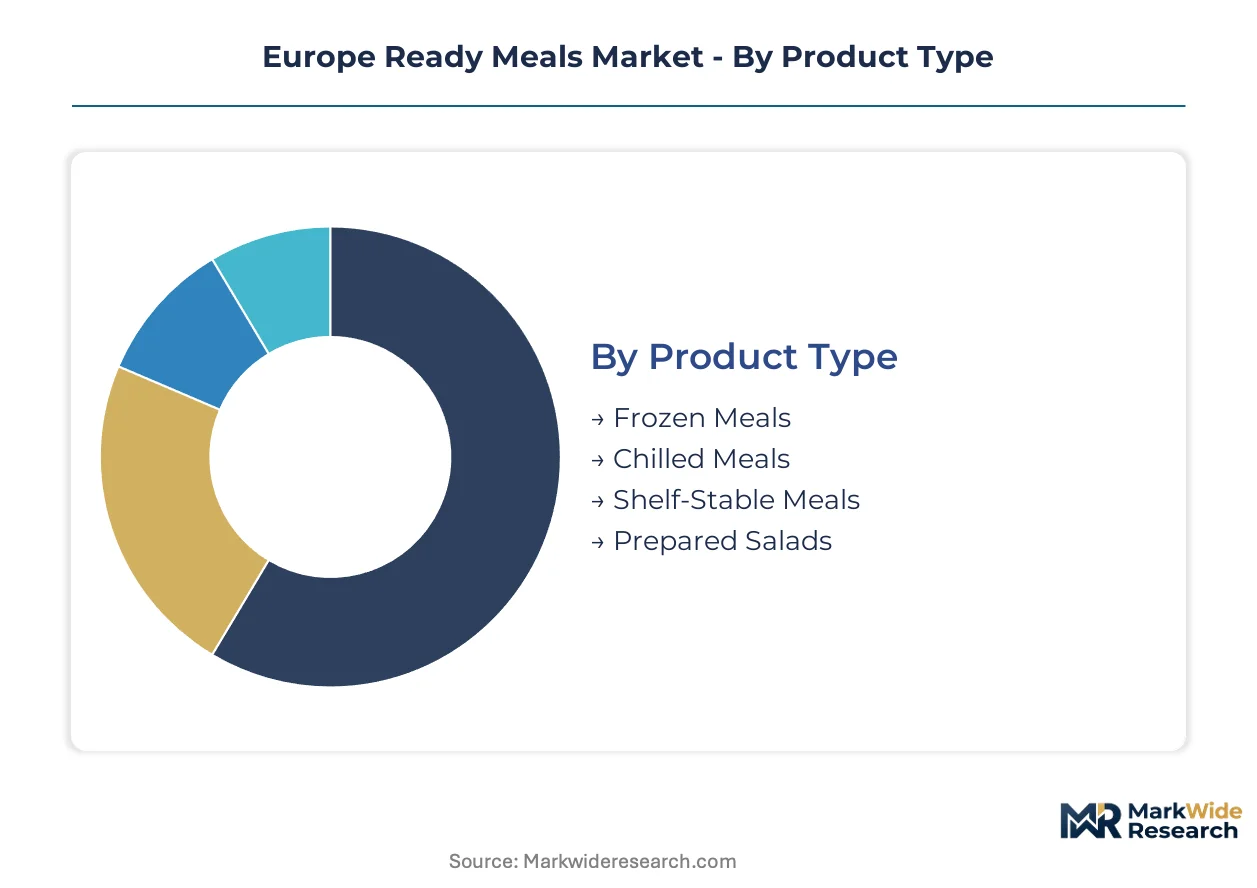
Ready meal segmentation in Europe tracks divergent preservation technologies and channel economics. Format choices determine cold-chain requirements, shelf-life constraints, and margin structures across national markets.
Product Type:
Mature freezing infrastructure dominates volume throughput while emerging chilled technologies capture premium positioning.
- Frozen Meals:Thermal preservation at sub-zero temperatures extends shelf stability to 12-18 months. German and French retail banners maintain dedicated freezer aisle space driven by single-person household stock-up behavior. Extended shelf life reduces waste write-offs for distributors.
- Chilled Meals:Modified atmosphere packaging maintains 5-10 day freshness windows without synthetic preservatives. UK and Irish demand concentrates around shorter ingredient declarations and perceived freshness. EFSA-aligned clean-label claims command retail slotting premiums.
- Shelf-Stable Meals:Retort pouch and thermal sterilization technologies enable ambient distribution without refrigeration. Limited penetration in Western European markets due to taste degradation concerns.
- Prepared Salads:High-pressure processing extends chilled shelf life for raw vegetable and protein combinations. Paris and Berlin convenience store channels show rising capture rates.
Frozen meals handle the majority of throughput; chilled meals are gaining share fastest on margin expansion.
End User:
Cost tier stratification separates household impulse purchases from food service procurement at volume scale.
- Households:Individual and two-person units drive portion-flexible format demand across German urban centers. Weekly shopping trip compression elevates convenience store and online channel capture.
- Restaurants:Labor cost pressures push mid-tier dining operators toward pre-portioned protein and sauce components. Kitchen footprint reduction in Paris and London high-rent districts accelerates adoption.
- Cafés:Limited cooking infrastructure creates demand for ambient and chilled grab-and-go meal solutions. Transit corridor locations in Berlin and Vienna show format experimentation.
- Catering Services:Event and corporate contract volumes favor frozen bulk formats with predictable portion costing. Poland-based production hubs supply cost-competitive alternatives to Western European sources.
Households absorb the greatest volume absolute; restaurants are expanding most quickly on labor substitution economics.
Distribution Channel:
Channel concentration patterns reflect urban logistics constraints and replenishment velocity requirements.
- Supermarkets:Centralized freezer and chilled aisle infrastructure supports weekly stock-up trip economics. French and German hypermarket banners maintain category captain relationships with multinational suppliers.
- Convenience Stores:Transit-adjacent locations in London, Paris, and Berlin corridors capture impulse chilled meal demand. Limited backroom refrigeration constrains assortment breadth.
- Online Retail:Direct-to-subscriber models bypass traditional slotting fees in Scandinavian urban markets. Cold-chain last-mile delivery costs remain a margin compression factor.
- Food Service:Broadline distributors serve restaurant and catering accounts with frozen bulk formats. Contract pricing structures favor producers with pan-European production footprints.
Supermarkets retain the dominant throughput position; online retail shows the steepest expansion trajectory on subscription model adoption.
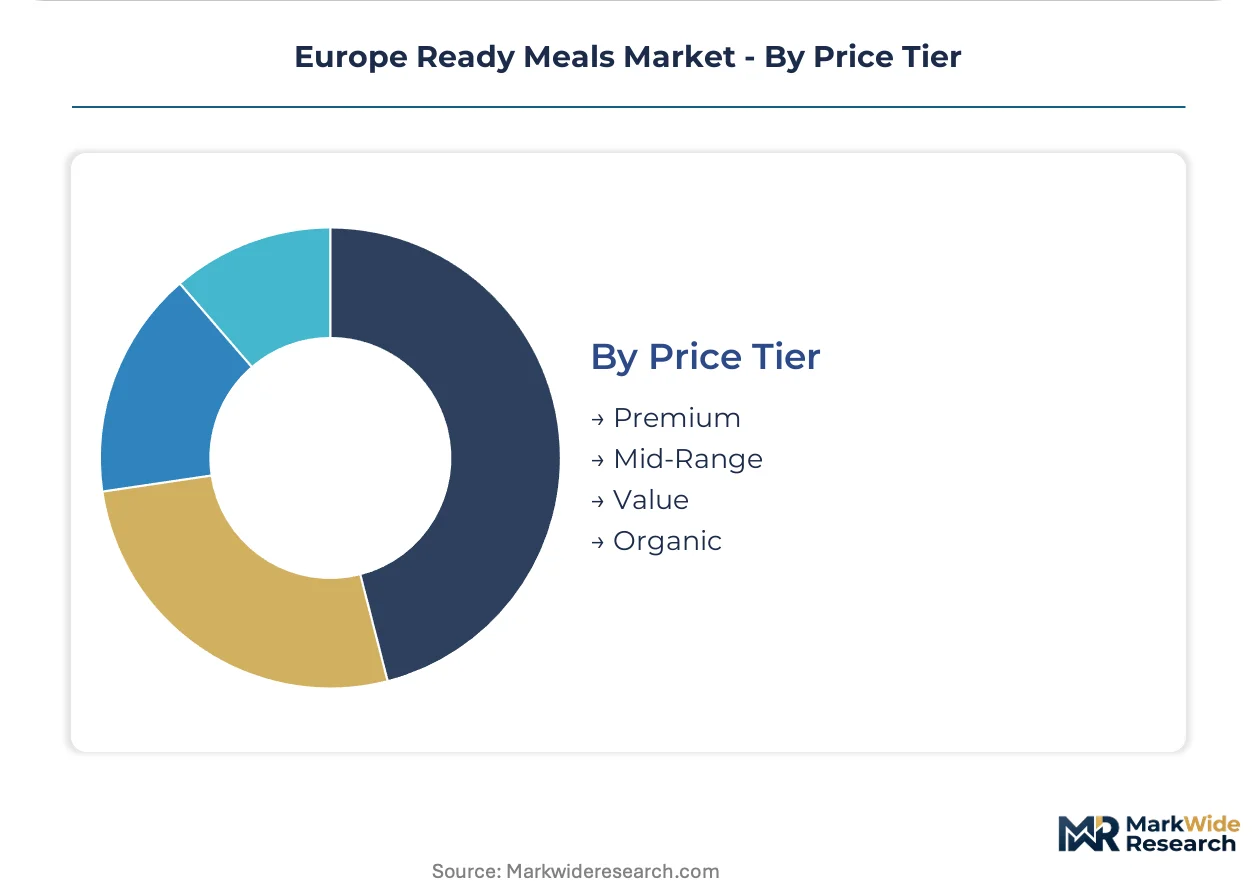
Price Tier:
Margin stratification aligns with certification requirements and ingredient sourcing intensity.
- Premium:Restaurant-quality positioning with chef-endorsement and regional provenance claims. UK and Irish chilled segments command shelf space premiums.
- Mid-Range:Balanced formulation cost and clean-label compliance for mainstream retail banners. Volume concentration in German and French family-format offerings.
- Value:Price-driven frozen pasta and protein combinations with extended ingredient declarations. Private-label dominance in Southern European markets.
- Organic:Third-party verified supply chains with EFSA-aligned nutrition labeling. Fastest-growing tier on retail assortment priority shifts in Paris and Berlin.
Mid-range captures the greatest volume share; organic certification shows the fastest climb on regulatory tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA nutrition labeling standards and EU Green Deal packaging mandates anchor Western European demand concentration, while Poland's cold-chain investments reshape supply geography across the continent.
Germany
Single-person households in Berlin and Hamburg compress traditional family-format economics while elevating portion-flexible chilled demand. The national food safety authority enforces contaminant thresholds that elevate quality assurance costs for cross-border suppliers. Bavaria-based production clusters are deploying mono-material packaging lines to meet recyclability timelines.
United Kingdom
Chilled ready meal specialization commands retail shelf space premiums through shorter ingredient declarations and perceived freshness. EFSA-aligned clean-label claims reshape retail assortment priorities in London and Birmingham metropolitan corridors. Bakkavor Group PLC anchors competitive positioning through dedicated chilled production for UK and Irish retail banners.
France
Paris transit corridors show rising convenience-store chilled meal capture as weekly stock-up trips fragment into impulse-driven micro-purchases. ANSM and national food safety authorities enforce REACH chemical compliance that constrains permissible additives. Île-de-France production facilities face compressed distribution radius constraints from clean-label preservation without synthetic additives.
Poland
Expanded cold-chain infrastructure and contract manufacturing investments narrow production capacity gaps with Western European hubs. EU Green Deal packaging regulations accelerate capital deployment into fiber-based tray pilot programs near Warsaw and Kraków. These facilities now supply cost-competitive alternatives to Berlin and Vienna metropolitan corridors.
Italy
Southern European chilled ready meal penetration gaps versus Paris and London benchmarks offer format introduction potential in Milan and Rome. National food safety authority contaminant threshold revisions accelerate quality assurance system overhaul demands. Northern Italian production clusters are testing high-pressure processing systems to collapse the freshness-versus-shelf-life trade-off.
Europe Ready Meals Market Competitive Landscape
Pan-European conglomerates and national chilled specialists split the market between scale-driven frozen distribution and margin-focused fresh positioning. Consolidation pressure intensifies as EFSA compliance costs and packaging conversion capex favor integrated R&D capabilities. Two archetypes dominate: multinational frozen networks with pan-European logistics footprints, and chilled specialists with retail banner relationships. Competitive moves concentrate on mono-material packaging line conversions and direct-to-subscriber platform launches.
Among diversified food conglomerates, Nestlé S.A. and Unilever PLC exemplify scale-driven archetypes with frozen distribution networks spanning multiple price tiers. Kerry Group plc occupies a distinct position supplying taste and texture ingredient systems to both branded and private-label manufacturers. These three entities represent the strategic spectrum from captive retail shelf presence to upstream formulation partnerships.
| Leading Market Players |
|---|
| Dr. Oetker GmbH |
| Kerry Group plc |
| Nestlé S.A. |
| 2 Sisters Food Group |
| Bakkavor Group PLC |
| Unilever PLC |
| Orkla ASA |
| Conagra Brands, Inc. |
| Nomad Foods Ltd. |
| Others |
Supply & Pricing Matrix
Warsaw-Kraków production clusters are narrowing cost differentials with Western European hubs, compressing margin premiums that Bavarian and Île-de-France facilities once commanded in Berlin and Paris metropolitan markets. This geographic rebalancing is redistributing pricing power toward contract manufacturers with integrated cold-chain capabilities and EFSA-aligned certification systems.
Pricing Analysis
Price spreads between Western European urban centers and Central European supply corridors are collapsing as Polish cold-chain infrastructure matures. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification intensity and ingredient declaration length, with organic EFSA-aligned tiers commanding shelf space premiums. Pricing pressure stems from input cost volatility in wheat and dairy formulations, compressing mid-tier producer margins. Value-tier frozen pasta lines show highest price sensitivity among German single-person households, while premium chilled portfolios in UK and Irish banners retain elasticity.
Supply Chain Analysis
REACH chemical compliance and EU Green Deal packaging mandates restrict modified atmosphere packaging film flows from non-EU sources, concentrating supply within German and Benelux chemical corridors. Raw material dependencies center on mono-material films, fiber-based tray substrates, and high-pressure processing equipment sourced from Netherlands and UK technology providers. Single-source vulnerability in MAP film supply exposes cross-border suppliers to disruption. Distribution runs through pan-European frozen networks for bulk formats and localized chilled replenishment for freshness-positioned lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Meal-kit subscription platforms and quick-commerce grocery delivery pose direct substitution threats to traditional ready meal incumbents, forcing defensive repositioning around convenience attributes and clean-label credentials that replicate freshness perception without last-mile complexity.
For Market Incumbents: Harden category captain relationships with French and German hypermarket banners through exclusive chilled line development and EFSA-aligned nutrition scoring optimization. Deepen backward integration into mono-material packaging production to capture EU Green Deal compliance margins and reduce third-party film exposure. Lock in multi-year contract manufacturing agreements with Polish cold-chain facilities to secure cost-competitive supply buffers against Central European expansion by rival networks.
For New Entrants and Emerging Players: Build out direct-to-subscriber chilled meal platforms in Scandinavian urban centers where traditional slotting fee structures burden incumbent economics. Target Southern European penetration gaps in Spain and Portugal with ambient-stable format introductions that bypass underdeveloped chilled retail infrastructure. Leverage high-pressure processing technology licensing to collapse shelf-life constraints and enable distribution radius expansion without synthetic preservative investments.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors chilled specialists with retail banner relationships and integrated R&D capabilities over scale-driven frozen distributors facing commoditization pressure. Acquisition candidates with pilot-scale mono-material testing facilities and EFSA regulatory affairs teams offer defensive value across the analysis window. Watch for inflection signals in Extended Producer Responsibility scheme enforcement timelines that would accelerate packaging line conversion capex demands and consolidate viable production footprints.
| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Packaging Conversion | EU Green Deal recyclability timelines in Germany and France mandate fiber-based tray deployment by 2030. |
| High-Pressure Processing Scale-Up | UK and Netherlands facilities adopting HPP systems collapse chilled-frozen shelf-life gaps for premium positioning. |
| Direct-to-Subscriber Platform Launch | Scandinavian urban markets bypass traditional retail slotting fees through subscription chilled meal logistics. |
| EFSA Clean-Label Certification Investment | Third-party verified organic tiers capture fastest-growing price segment in Paris and Berlin metropolitan corridors. |
| Polish Cold-Chain Capacity Expansion | Warsaw and Kraków facilities supply cost-competitive alternatives to Berlin and Vienna metropolitan markets. |
Research Methodology
Operator-level perspectives from category buyers at French and German retail banners, chilled ready meal production managers, EFSA regulatory affairs consultants, and cold-chain logistics coordinators anchored the qualitative base. Secondary validation drew from EU trade statistics, EFSA nutrition labeling guidance documents, national food safety authority contaminant threshold publications, and SEC filings of listed ready meal manufacturers. Bottom-up volume modeling triangulated against top-down macroeconomic consumption indicators.
Scenario-bracketing around regulatory compliance timelines and input cost volatility bands structured the analytical framework across the projection horizon. Segmentation dimensions modeled include preservation technology, distribution channel economics, price tier certification intensity, and end-user procurement scale. CAGRs derived from trend-line extrapolation of historical consumption patterns adjusted for demographic shifts in household composition. Forecast inputs incorporated EFSA labeling enforcement schedules and EU Green Deal packaging mandate phase-ins.
Stress conditions across wheat and dairy price swings, MAP film supply disruption scenarios, and REACH chemical registration revision timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory adherence and cold-chain infrastructure deployment rates. Material shifts in Extended Producer Responsibility enforcement intensity or EFSA front-of-pack scoring algorithm revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Bangladesh Instant Noodles Market
Packaged Foods
Packaged Rice Market
Packaged Foods
High-End Instant Noodles Market
Packaged Foods
Europe Free from Food Market
Packaged Foods
Packaged Vegan Foods Market
Packaged Foods
Instant Rice Market
Packaged Foods
Canned Pasta Market
Packaged Foods
Instant Cereals Market
Packaged Foods
Mexico Packaged Food Products Market
Packaged Foods
Impulse Ice-Cream Market
Packaged Foods
Cocoa Fillings Market
Packaged Foods
Global Dessert Mixes Market
Packaged Foods
Dried Honey Market
Packaged Foods
Convenience Food Market
Packaged Foods
Breakfast Food Market
Packaged Foods
Iraq Dried Pasta Market