
 Oven Market | 2026-2036
Oven Market Size, Share, and Industry Trends Forecast 2026-2036
Oven Market Outlook
The EU Ecodesign Directive is shifting procurement criteria across European foodservice operations toward lower-carbon cooking equipment. Thermo Fisher Scientific leverages its laboratory thermal processing expertise to serve adjacent industrial oven segments requiring precision temperature control. BINDER GmbH dominates environmental simulation chambers while competing in specialized heating equipment for pharmaceutical stability testing. Wisconsin Oven Corporation anchors North American industrial batch and continuous process oven supply with heavy-gauge fabrication capabilities.
An oven is an enclosed thermally insulated chamber designed to deliver controlled heat typically ranging from ambient to over 500°C for cooking, curing, drying, or material processing applications. Convection ovens, which force heated air circulation via fans to reduce temperature variation and cooking time, now lead commercial kitchen specifications due to throughput advantages. Wall ovens within the residential built-in category command margin pools tied to kitchen renovation cycles and premium cabinetry integration. Electric energy source configurations are outpacing gas alternatives in new European residential construction where district heating interfaces and renewable grid integration shape installation preferences.
EU Ecodesign and Energy Labelling regulations, enforced by national market surveillance authorities in member states, mandate minimum efficiency thresholds that disqualify legacy resistance-heating designs from new sales. The US Department of Energy maintains separate test procedures and conservation standards for residential cooking products under appliance efficiency rules administered by the Federal Trade Commission. Stakeholders must monitor pending amendments to these frameworks that will likely tighten standby power limits and expand testing protocols to connected smart oven functionalities.
Market Dynamics
The EU Ecodesign Directive is compressing replacement cycles across commercial foodservice operations while simultaneously disqualifying legacy resistance-heating designs from new sales channels, forcing capital deployment toward induction-based convection systems and connected thermal processing equipment.
Growth Catalysts
- Induction-based convection systems:Commercial bakeries in Germany, France, and the United Kingdom are accelerating equipment turnover as utility rebate programs concentrate demand for energy-efficient thermal processing.
- EU Ecodesign and Energy Labelling regulations:These frameworks mandate minimum efficiency thresholds that redirect procurement toward lower-carbon cooking equipment across European foodservice operations.
- Restaurant chain expansion:Multi-unit operators are standardizing on precision temperature control platforms that reduce variation and compress cooking time across distributed locations.
Market Restraints
- Copper and steel input volatility:Heavy-gauge fabrication requirements for industrial batch and continuous process ovens expose manufacturers to commodity price swings that compress margin pools.
- Supply concentration in North American fabrication:Wisconsin Oven Corporation anchors regional supply with specialized heavy-gauge capabilities, creating geographic dependency for precision thermal equipment.
- Legacy resistance-heating obsolescence:The EU Ecodesign Directive disqualifies established heating architectures from new sales, stranding installed base knowledge and forcing premature capital redeployment.
Strategic Opportunities
- Pharmaceutical stability testing equipment:BINDER GmbH's environmental simulation chamber expertise creates adjacent entry into specialized heating equipment for temperature-sensitive drug validation protocols.
- District heating interface integration:Electric energy source configurations in new European residential construction are outpacing gas alternatives where renewable grid integration shapes installation preferences.
- Laboratory thermal processing crossover:Thermo Fisher Scientific leverages precision temperature control expertise from scientific instrumentation to serve industrial oven segments requiring tight thermal tolerances.
Industry Challenges
- Connected smart oven testing protocols:Pending amendments to US Department of Energy conservation standards will expand testing procedures to networked functionalities, lengthening certification timelines.
- Standby power limit compliance:Federal Trade Commission appliance efficiency rules are tightening standby consumption thresholds, requiring firmware and hardware redesigns for residential cooking products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oven Market |
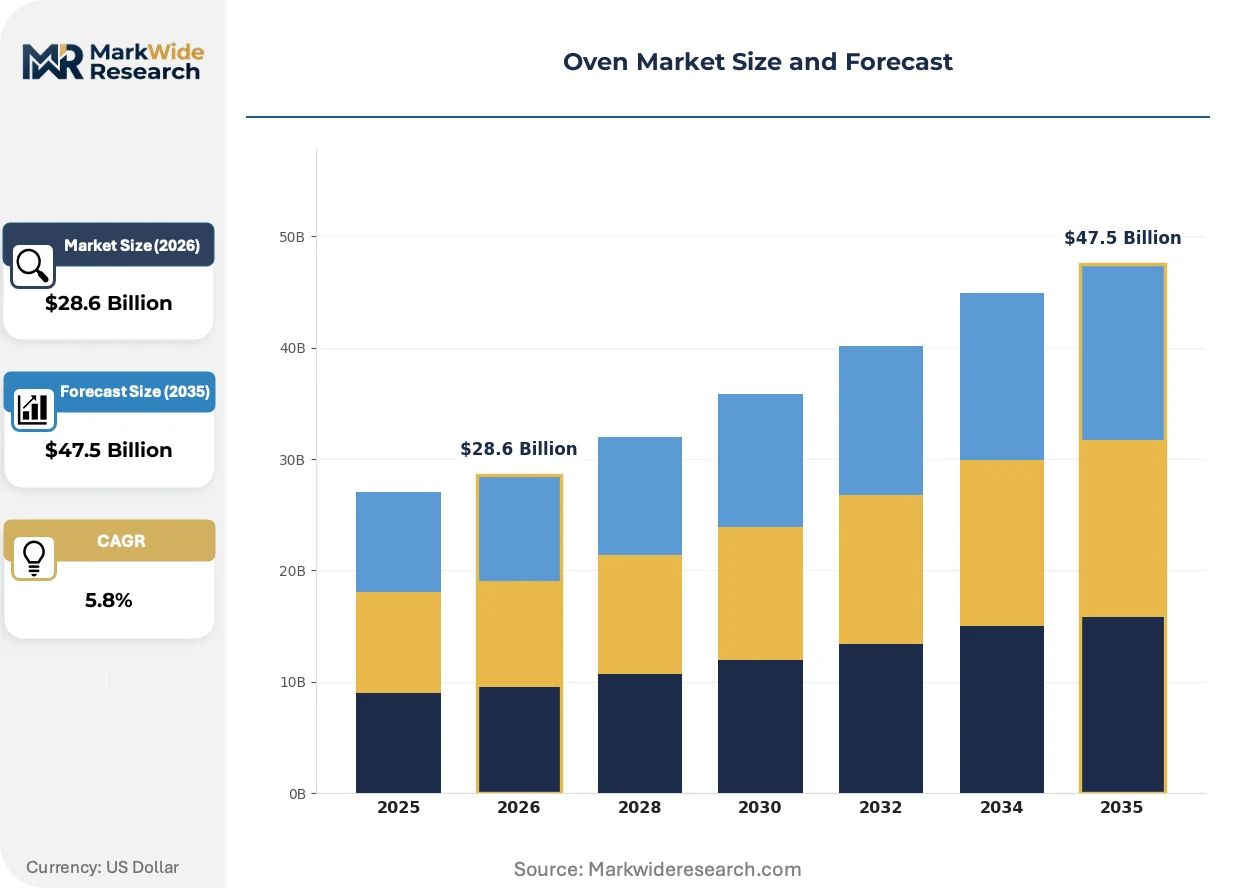
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional Ovens, Convection Ovens, Toaster Ovens, Wall Ovens End User: Residential, Commercial, Hospitality, Restaurant Installation Type: Built-in, Freestanding, Under-counter, Countertop Energy Source: Electric, Gas, Induction, Wood |
| Companies Covered | Carbolite Gero, Sheldon Manufacturing, Thermo Fisher Scientific, PHC Corporation, Despatch Industries, BINDER GmbH, Yamato Scientific, Miele, Wisconsin Oven Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oven Market Strategic Shifts
Automation and connectivity are compressing operational boundaries between residential, commercial, and industrial thermal processing equipment while regulatory frameworks accelerate equipment replacement cycles across all segments.
Sensor-integrated thermal management systems are automating real-time temperature calibration and predictive maintenance protocols in commercial kitchen environments. Multi-unit restaurant operators are deploying these platforms to standardize output quality across distributed locations. The technology is automating labor-intensive monitoring tasks while reducing energy waste through dynamic load adjustment.
The US Department of Energy maintains separate test procedures and conservation standards for residential cooking products under appliance efficiency rules administered by the Federal Trade Commission. Pending amendments to these frameworks will likely tighten standby power limits and expand testing protocols to connected smart oven functionalities. Manufacturers serving the US market are pre-emptively redesigning control architectures to accommodate these anticipated requirements.
Equipment-as-a-service models are displacing traditional capital purchase arrangements in commercial foodservice operations. Large restaurant chains and institutional buyers are unbundling after-sales service from upfront acquisition, shifting risk to manufacturers and OEMs. This behavioral shift is most visible in Germany and the United Kingdom where energy-efficiency mandates already compress replacement cycles and create recurring revenue opportunities for thermal equipment suppliers.
Oven Market Segmentation
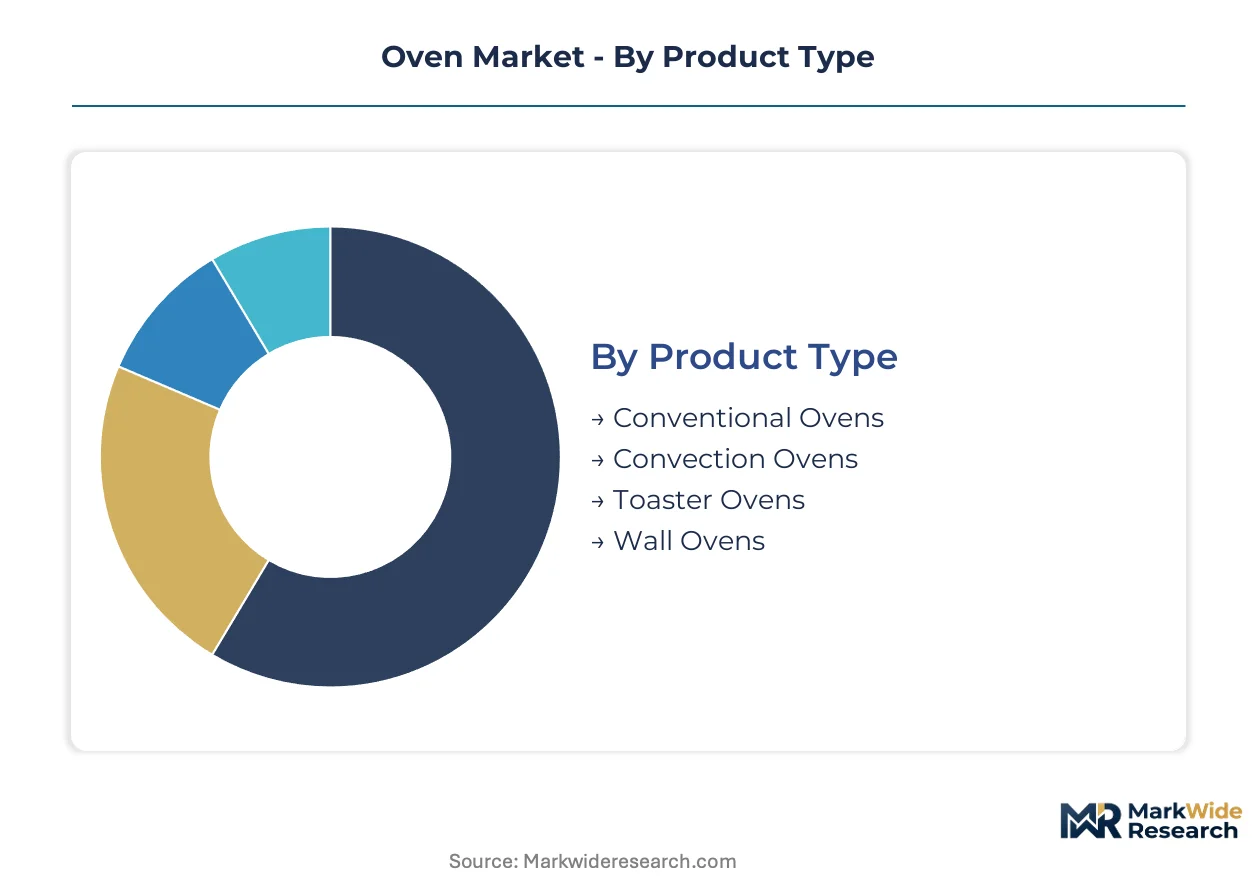
Oven manufacturers configure product portfolios around thermal engineering specifications, installation constraints, and energy interface requirements. Each segmentation axis carries distinct margin profiles, replacement cycle dynamics, and regulatory exposure that shape capital allocation decisions.
Product Type:
Thermal distribution architecture determines throughput efficiency, temperature uniformity, and energy recovery potential across residential and commercial deployments.
- Convection Ovens:Forced-air circulation via integrated fans reduces temperature variation and compresses cooking duration compared to static heating. Restaurant chains in Germany and the United Kingdom specify these systems to standardize output quality across distributed locations while qualifying for utility rebate programs.
- Wall Ovens:Built-in residential units integrate with premium cabinetry during kitchen renovation cycles. These configurations command elevated margin pools tied to aesthetic customization and smart connectivity features in North American and European markets.
- Conventional Ovens:Static thermal radiation designs retain installed base presence in budget residential segments where replacement cycles lag regulatory efficiency mandates.
- Toaster Ovens:Compact countertop units serve single-person households and secondary cooking tasks with minimal energy footprint and abbreviated preheat requirements.
Convection ovens lead on scale; wall ovens lead on momentum.
End User:
Operational intensity and utilization patterns create divergent procurement behaviors across customer categories.
- Commercial:Bakeries and food production facilities operate equipment through extended duty cycles that prioritize thermal consistency and throughput volume. EU Ecodesign compliance costs accelerate replacement timelines for legacy resistance-heating installations.
- Restaurant:Multi-unit operators standardize equipment specifications to reduce training burden and maintain menu consistency across locations. These buyers increasingly favor equipment-as-a-service arrangements that unbundle capital expenditure from maintenance obligations.
- Residential:Individual households select ovens based on kitchen renovation schedules, energy source availability, and smart home integration preferences.
- Hospitality:Hotels and institutional caterers demand ruggedized construction with rapid recovery capabilities to accommodate variable load patterns during peak service windows.
Commercial installations dominate installed base volume; restaurant chains are expanding most quickly.
Installation Type:
Physical integration with built environment infrastructure shapes distribution channel requirements and service attachment rates.
- Built-in:Cabinetry-integrated units require coordinated delivery with kitchen renovation timelines and specialized installation labor. These configurations generate recurring service revenue through warranty extensions and preventive maintenance contracts.
- Freestanding:Self-contained units with finished side panels allow flexible kitchen layout and simplified replacement without cabinetry modification.
- Under-counter:Space-constrained installations in compact urban kitchens and galley configurations maximize floor plan efficiency.
- Countertop:Portable supplemental cooking capacity serves temporary foodservice operations and residential secondary preparation tasks.
Built-in configurations anchor premium pricing; freestanding units maintain volume leadership.
Energy Source:
Utility interface specifications determine regulatory compliance burden, operating cost structure, and grid integration potential.
- Electric:Resistance and induction heating elements interface with district heating systems and renewable electricity grids in new European residential construction. These configurations outpace gas alternatives where building codes mandate decarbonization pathways.
- Induction:Electromagnetic field generation delivers rapid thermal response with superior energy conversion efficiency. Commercial bakeries in France and Germany accelerate adoption to capture utility incentives and satisfy EU Ecodesign thresholds.
- Gas:Combustion-based heating retains installed base in North American markets with established natural gas distribution infrastructure and lower per-therm energy costs.
- Wood:Solid fuel combustion serves specialty culinary applications and off-grid installations where traditional flavor profiles justify operational complexity.
Electric configurations command the steepest expansion trajectory; gas maintains legacy installed base dominance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered industrial thermal processing equipment manufacturing during the early twentieth century, establishing precision engineering standards that persist across European foodservice and laboratory applications today.
Germany
Commercial bakeries in Bavaria and North Rhine-Westphalia are accelerating replacement of resistance-heating ovens with induction-based convection systems. The EU Ecodesign Directive mandates minimum efficiency thresholds that disqualify legacy equipment from new sales channels. Stuttgart's industrial equipment cluster hosts specialists in precision temperature control for pharmaceutical and laboratory applications.
United States
Restaurant chains are standardizing on connected thermal processing platforms to reduce variation across distributed locations. The Department of Energy maintains separate test procedures and conservation standards under Federal Trade Commission appliance efficiency rules. Wisconsin anchors North American supply of heavy-gauge industrial batch and continuous process ovens with specialized fabrication capabilities.
France
Utility rebate programs are concentrating demand for energy-efficient thermal processing equipment among commercial foodservice operators. National market surveillance authorities enforce EU Energy Labelling regulations that redirect procurement toward lower-carbon cooking equipment. The Île-de-France region hosts equipment-as-a-service providers serving multi-unit restaurant operators.
United Kingdom
Multi-unit restaurant operators are unbundling after-sales service from upfront acquisition, shifting risk to manufacturers and OEMs. The country's national energy regulator coordinates with EU-aligned efficiency mandates that compress replacement cycles. Greater Manchester's foodservice equipment distribution hub is expanding service attachment rates for built-in configurations.
Japan
Laboratory thermal processing demand is expanding from pharmaceutical stability testing and environmental simulation applications. The Ministry of Economy, Trade and Industry oversees standards alignment with international thermal equipment protocols. Osaka's precision instrumentation cluster supplies sensor-integrated thermal management systems for automated calibration protocols.
Oven Market Competitive Environment
Premium-margin players sit above commodity-margin players across thermal precision and heavy-gauge fabrication capabilities. The vendor base organizes into three tiers: precision laboratory specialists, industrial-scale fabricators, and residential appliance manufacturers. Strategic archetypes include scientific instrumentation crossovers, environmental simulation chamber specialists, and heavy-gauge batch process anchors. Dominant competitive moves involve equipment-as-a-service model expansion and firmware redesigns for standby power compliance.
Within the scientific instrumentation tier, Thermo Fisher Scientific and BINDER GmbH exemplify precision temperature control expertise applied to adjacent industrial segments. Wisconsin Oven Corporation anchors North American supply for heavy-gauge fabrication requirements. These three occupy positions that span laboratory, industrial, and specialized thermal processing applications without direct segment overlap.
| Leading Market Players |
|---|
| Carbolite Gero |
| Sheldon Manufacturing |
| Thermo Fisher Scientific |
| PHC Corporation |
| Despatch Industries |
| BINDER GmbH |
| Yamato Scientific |
| Miele |
| Wisconsin Oven Corporation |
| Others |
Value Chain & Pricing Dynamics
Backward integration into heavy-gauge steel fabrication anchors pricing power for North American industrial oven manufacturers while compressing margins for competitors sourcing from dispersed supplier networks. Wisconsin Oven Corporation's captive production of specialized thermal chambers insulates it from commodity volatility that erodes pricing flexibility among assembly-only rivals serving commercial foodservice segments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates precision laboratory equipment from commercial foodservice units and residential appliances. Certification grade under EU Ecodesign and UL safety standards commands substantial premiums, while volume scale discounts dominate procurement negotiations for multi-unit restaurant chains. Cost compression in the standard tier is intensifying because steel and copper input volatility squeezes fabrication margins. Residential buyers exhibit highest price sensitivity, whereas pharmaceutical stability testing laboratories demonstrate minimal elasticity due to regulatory compliance requirements.
Supply Chain Analysis
Freight cost escalation for heavy-gauge fabricated components has reshaped regional sourcing patterns across the oven industry. Germany, the United States, and Japan anchor precision thermal equipment manufacturing, while China and Mexico supply standardized residential components. Production draws from specialized steel alloys, induction coil assemblies, and sensor-integrated control modules. Single-source vulnerability concentrates in heavy-gauge fabrication capabilities concentrated in Wisconsin and Stuttgart. Distribution runs through manufacturer-direct channels for industrial clients and specialized kitchen equipment distributors serving commercial foodservice operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The oven market represents a late-cycle quality story as EU Ecodesign mandates and utility rebate programs redirect procurement toward premium energy-efficient configurations. Precision temperature control platforms now command sustained margin premiums across laboratory, pharmaceutical, and commercial foodservice deployments.
For Market Incumbents: Anticipate accelerated obsolescence of legacy resistance-heating architectures by accelerating firmware redesigns for standby power compliance ahead of FTC rule amendments. Defend position by deepening captive supply of induction coil assemblies and sensor-integrated control systems. Certification investment in EU Ecodesign and UL safety tiers creates switching costs that lock in pharmaceutical and commercial bakery accounts. For New Entrants and Emerging Players: The mid-tier price gap between premium laboratory equipment and economy residential units offers white-space opportunity for specialized commercial foodservice configurations. Target underpenetrated segments in French and UK utility rebate programs where equipment-as-a-service models displace capital purchase arrangements. Pursue go-to-market partnerships with regional distributors in Greater Manchester and Île-de-France that already service multi-unit restaurant operators. For Investors and Strategic Acquirers: Roll-up economics work for precision thermal processing specialists because regulatory compliance complexity fragments the vendor base and creates recurring service revenue attachment. Five-to-ten-year viability hinges on exposure to pharmaceutical stability testing and environmental simulation applications rather than commodity residential segments. Monitor FDA and EMA validation protocol changes as inflection indicators for laboratory equipment demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Equipment-as-a-Service Model Expansion | Unbundles capital expenditure from maintenance obligations for German and UK restaurant chains. |
| Induction-Based Convection System Development | Captures utility rebate programs in France, Germany, and the United Kingdom. |
| Pharmaceutical Stability Testing Equipment Entry | Leverages precision temperature control expertise from adjacent laboratory segments. |
| Smart Oven Firmware Redesign | Pre-empts FTC standby power limit compliance ahead of anticipated rule amendments. |
| District Heating Interface Integration | Aligns electric configurations with EU residential decarbonization mandates. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to construct segment-level demand estimates. Primary engagement with thermal equipment procurement managers at commercial bakeries, restaurant chain operations directors, pharmaceutical facility engineers, and laboratory equipment specialists informed installation cycle dynamics and replacement timing. Secondary validation drew from SEC filings of diversified industrial manufacturers, EU Ecodesign regulatory impact assessments, utility rebate program disclosures, and customs data for thermal equipment trade flows. Bottom-up equipment shipment analysis and top-down construction spending allocation models were cross-referenced to anchor volume estimates.
Segment-weighting approaches applied differential growth assumptions across product type, end user, installation configuration, and energy source dimensions. The analytical framework modeled convection, wall, conventional, and toaster oven categories separately, with further disaggregation by commercial, restaurant, residential, and hospitality end users. CAGRs were derived from fitted trend lines applied to historical shipment data and adjusted for regulatory phase-in schedules. Induction penetration rates in EU commercial foodservice and smart connectivity adoption in North American residential replacement cycles served as key forecast inputs.
Caveats apply where steel and copper commodity volatility, EU regulatory enforcement variance across member states, or FTC rulemaking delays could materially shift the outlook. Forecasts reflect assumptions about utility rebate program continuity and district heating infrastructure buildout rates that remain contingent on public funding commitments. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Deep Fryer Market
Food Processing Equipment
Food Waste Composting Machine Market
Food Processing Equipment
Commercial Tunnel Oven Market
Food Processing Equipment
Food Disinfection Equipment Market
Food Processing Equipment
Commercial Kettles and Braising Pans Market
Food Processing Equipment
Griddle Market
Food Processing Equipment
Homogenizers Market
Food Processing Equipment
Global Commercial Food Dehydrators Market
Food Processing Equipment
Automatic Evisceration System Market
Food Processing Equipment
Global Non Thermal Processing Market
Food Processing Equipment
Electric Chicken Scalder Market
Food Processing Equipment
Brining Systems Market
Food Processing Equipment
Vacuum Frying Machine Market
Food Processing Equipment
Freeze-Drying Market
Food Processing Equipment
Ice Maker Machines Market
Food Processing Equipment
Commercial Wood Fired Pizza Oven Market