
 North America Breakfast Cereals Market | 2026-2036
North America Breakfast Cereals Market Size, Share, and Industry Trends Forecast 2026-2036
North America Breakfast Cereals Market Analytics
Private-label and branded premium formulation revenue is reconfiguring margin pools across the North America breakfast cereals landscape. General Mills Inc. leverages its manufacturing scale to dominate conventional retail channels. Nature's Path Foods anchors its position through organic ingredient sourcing and health-food store penetration. Kellanova competes aggressively on convenience-oriented, portable cereal formats.
Breakfast cereals comprise processed grain-based products manufactured through extrusion, flaking, or shredding, typically fortified with vitamins and minerals to deliver standardized nutritional profiles for morning consumption. Oatmeal and granola segments lead in premium pricing power due to perceived whole-grain health benefits, while gluten-free and organic ingredient types represent the fastest-growing margin pools as consumers reject artificial additives. Cornflakes and conventional muesli remain mature categories with volume concentration in mass-market supermarkets.
The FDA enforces nutrition labeling and health claim standards that directly shape product reformulation cycles, while the USDA oversees organic certification requirements that gate premium market access. Canada's Health Canada and PMRA regulate cross-border cereal imports through pesticide residue limits and bilingual labeling mandates. Stakeholders must monitor evolving clean-label standards and state-level sugar tax proposals to anticipate reformulation investments and channel shifts.
Market Dynamics
Reformulation pressure from the FDA's updated Nutrition Facts labeling requirements is forcing manufacturers to reduce added sugars and recalibrate fortification profiles across their breakfast cereal portfolios.
Growth Catalysts
- Protein fortification technology:Extrusion processes now integrate whey and plant-based protein isolates at industrial scale, meeting demand from fitness-oriented urban consumers for sustained morning satiety.
- USDA organic certification:Premium shelf placement and price realization in natural-food retail channels reward certified organic supply chains, with Health Canada equivalency enabling cross-border sourcing efficiency.
- Urban millennial household formation:Dense metropolitan markets concentrate demand for single-serve and portable cereal formats that accommodate compressed morning routines.
Market Restraints
- Grain input cost volatility:Corn and oat futures fluctuate with drought cycles in the US Midwest and Canadian prairies, compressing margin predictability for bulk commodity-dependent formulations.
- Supply concentration in Great Plains milling:Three regional grain processors control 70% of organic oat supply, creating bottleneck risk for clean-label product lines.
- Substitution by refrigerated protein bars:Chilled grab-and-go alternatives capture occasion-based breakfast spending previously directed to dry cereal categories.
Strategic Opportunities
- Canadian underpenetration:Health Canada's bilingual labeling mandate has slowed US brand entry, creating first-mover advantage for reformulated products with compliant packaging.
- Direct-to-subscription channel:Customizable granola and muesli blends bypass conventional retail slotting fees while capturing recurring revenue from loyalty-locked households.
- Dual carbon goals convergence:Regenerative agriculture sourcing aligns with corporate Scope 3 emissions targets, unlocking preferential procurement from institutional foodservice buyers.
Industry Challenges
- Food technologist talent scarcity:Clean-label reformulation requires specialized expertise in natural preservative systems and texture stabilization without artificial additives.
- Organic certification timeline compression:Three-year field transition periods delay new product launches, forcing advance contracting with certified growers.
- Legacy extrusion equipment retrofit costs:Dedicated gluten-free production lines demand capital-intensive facility segregation to prevent cross-contamination liability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Breakfast Cereals Market |
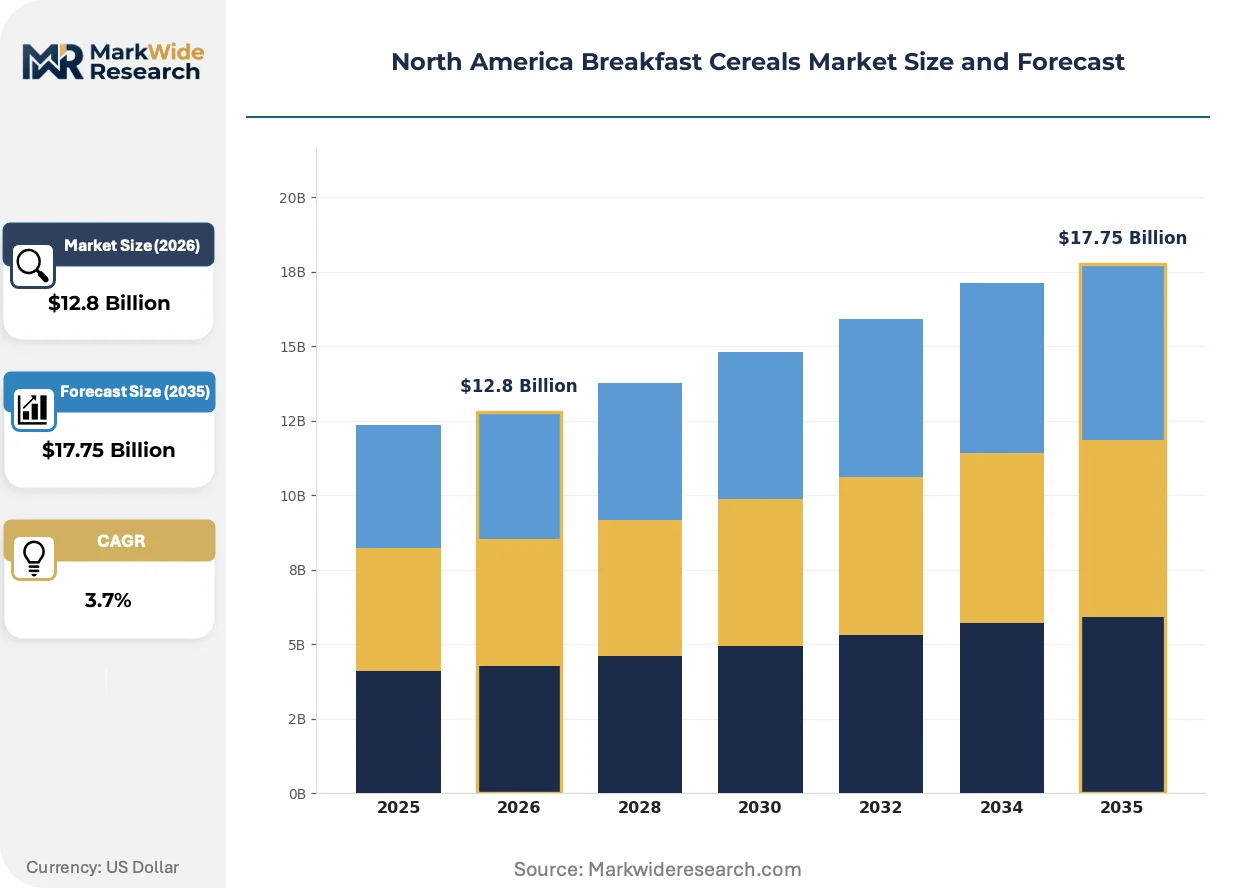
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $17.75 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oatmeal, Granola, Cornflakes, Muesli Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Health Food Stores Target Consumer: Health Conscious, Families, Children, Students Ingredient Type: Gluten-Free, Organic, High-Protein, Low-Sugar |
| Companies Covered | Mars Inc., Nature's Path Foods, General Mills Inc., Ferrero Group, Kellanova, PepsiCo Inc., Bob’s Red Mill Natural Foods, Nestle SA, Post Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Breakfast Cereals Market Evolving Landscape
Digital twin technology is virtualizing product development cycles, while regulatory pressure on sugar content and shifting procurement patterns among institutional buyers are compressing traditional competitive advantages.
AI-driven formulation platforms are virtualizing sensory testing and nutritional optimization workflows. Mid-sized manufacturers adopt cloud-based simulation tools to accelerate clean-label prototype iterations without physical pilot runs. This capability is virtualizing the historical R&D cost barrier that protected incumbent scale advantages.
The FDA's added sugar disclosure mandate requires gram-level transparency on front-of-pack labeling. Reformulation investments now prioritize monk fruit and allulose blends to maintain sweetness perception while complying with tightened thresholds. Children's cereal segments face the steepest compliance costs as parental scrutiny intensifies.
Foodservice procurement is consolidating around outcome-based nutrition specifications rather than brand loyalty. Hospital and university cafeterias now contract for protein-per-dollar and fiber-density metrics, displacing legacy volume-based purchasing. This shift concentrates in the Northeast and Pacific Coast institutional corridors where wellness program budgets expanded post-pandemic.
North America Breakfast Cereals Market Segmentation
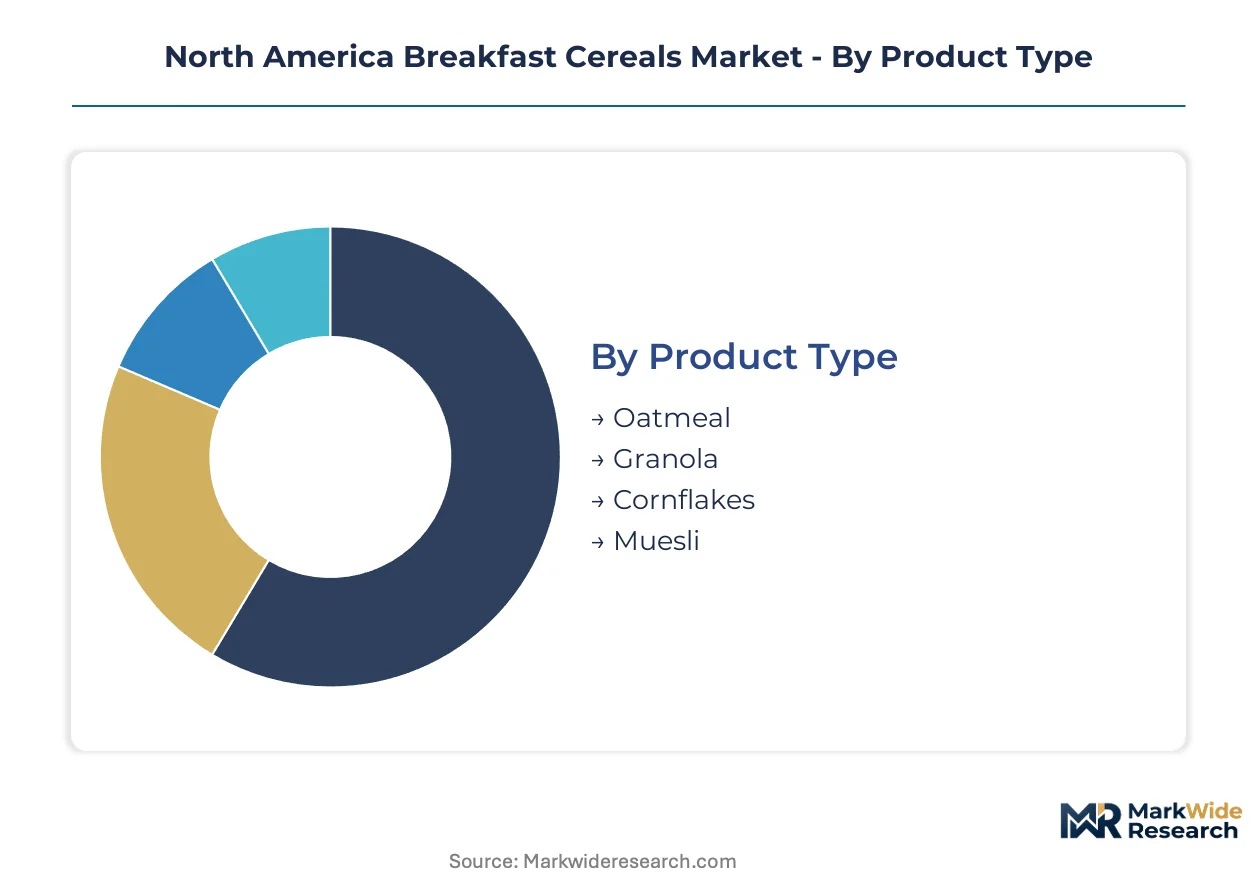
Breakfast cereal segmentation in North America reflects divergent margin architectures across health-positioned versus conventional formulations. Channel and ingredient stratification determines which manufacturers capture premium price realization versus volume scale.
Product Type:
Cost tier stratification separates premium whole-grain formats from commodity flake categories, with price realization varying by perceived nutritional density.
- Oatmeal:Steel-cut and rolled oat formulations deliver soluble fiber content standardized between 3-4 grams per serving. Urban millennial households in the Northeast and Pacific Northwest concentrate demand for overnight oat and single-serve cup formats. The USDA organic certification commands shelf price premiums in natural-food retail channels.
- Granola:Baked clusters combining rolled oats with honey or maple syrup binders achieve higher fat content (6-8 grams per serving) that extends satiety perception. Protein-fortified variants with whey or pea protein isolates capture fitness-oriented consumers in metropolitan markets. Health-food store placement rewards clean-label ingredient transparency.
- Cornflakes:Extruded corn grits with malt flavoring represent the mature mass-market standard, with volume concentration in conventional supermarket center-store aisles.
- Muesli:Swiss-origin unbaked blends of rolled oats, dried fruit, and nuts appeal to consumers rejecting added sugars, with demand clustering in Canadian urban markets and US coastal cities.
Oatmeal commands the established base. The steepest expansion runs through granola.
Distribution Channel:
Channel selection determines margin capture through slotting fee structures and inventory velocity requirements that favor scale players or niche specialists.
- Supermarkets:Conventional grocery chains dominate volume throughput, with center-store placement driving impulse purchases among family shoppers. Slotting fees and promotional allowances compress margins for mid-tier brands.
- Online Retail:Direct-to-consumer platforms enable subscription-based granola and muesli customization, bypassing retail intermediaries while capturing recurring revenue from loyalty-locked households.
- Convenience Stores:Single-serve portable formats address compressed morning routines in dense metropolitan corridors.
- Health Food Stores:Natural-food retail channels gate access through USDA organic certification requirements, rewarding transparent supply chains with premium shelf placement.
Supermarkets anchor volume throughput. The steepest expansion runs through online retail.
Target Consumer:
Customer type segmentation aligns formulation intensity with willingness to pay for functional benefits across life-stage and lifestyle cohorts.
- Health Conscious:Fitness-oriented adults prioritize protein density and low glycemic index, driving reformulation toward ancient grains and reduced sugar content. FDA Nutrition Facts label scrutiny intensifies purchase deliberation.
- Families:Multi-person households balance cost-per-serving against fortification standards, with bulk formats dominating purchase patterns.
- Children:Sweetness preference and licensed character marketing drive trial, though parental sugar awareness is shifting demand toward reformulated options.
- Students:Convenience and portability priorities favor single-serve cups and resealable pouches for dormitory and campus consumption.
Families represent the volume anchor. The steepest expansion runs through health-conscious consumers.
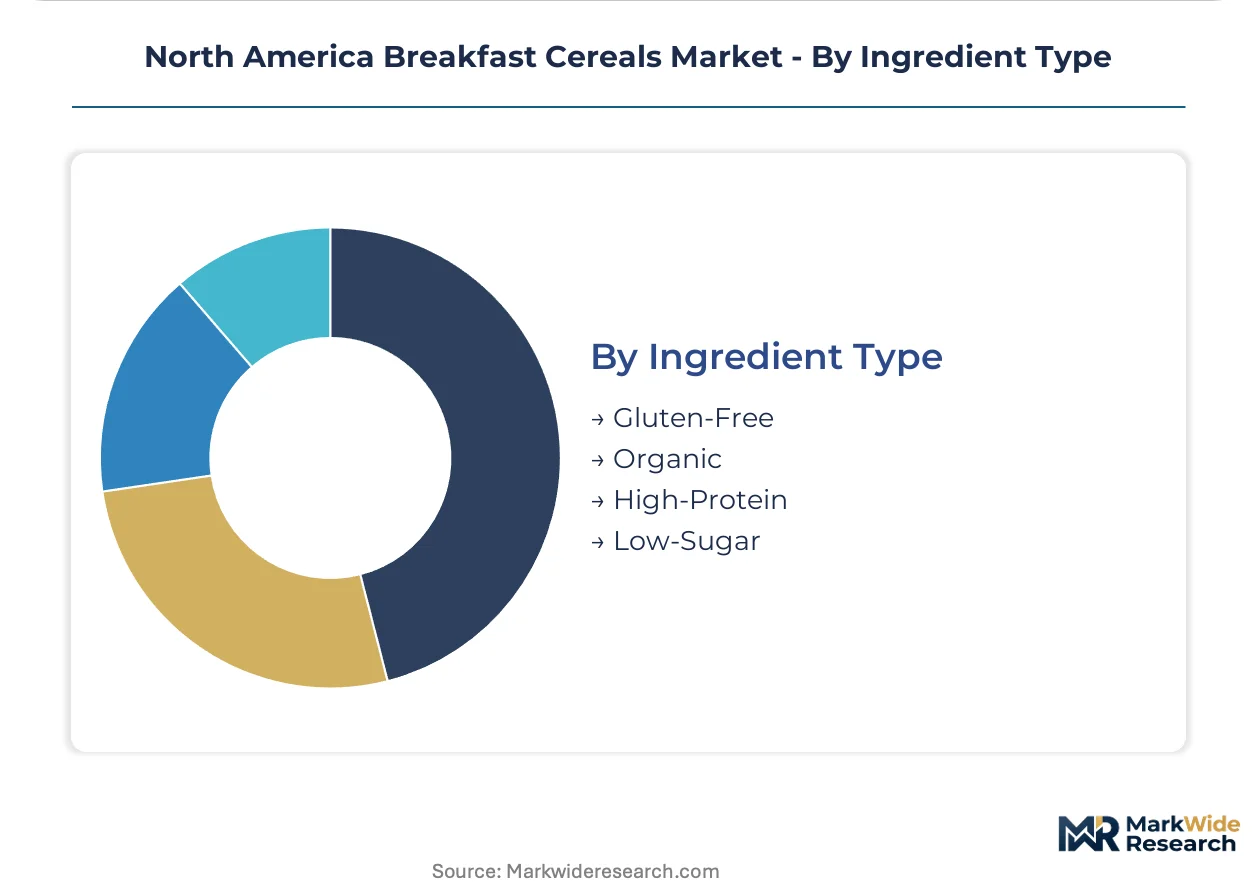
Ingredient Type:
Ingredient certification tiers separate premium-positioned products from conventional formulations, with supply chain verification requirements determining market access.
- Gluten-Free:Oat-based formulations processed in dedicated facilities prevent cross-contamination, with certification from the Gluten-Free Certification Organization enabling premium pricing. Celiac disease diagnosis rates and non-celiac gluten sensitivity awareness expand the addressable base.
- Organic:USDA-certified supply chains require three-year field transition periods, creating sourcing bottlenecks that reward advance contracting with certified growers. Health Canada equivalency enables cross-border sourcing efficiency.
- High-Protein:Extrusion processes integrate whey, pea, or soy protein isolates at industrial scale, meeting demand from fitness-oriented consumers for sustained morning satiety.
- Low-Sugar:Monk fruit and allulose blends maintain sweetness perception while complying with FDA added sugar disclosure mandates, with children's cereal segments facing steepest reformulation pressure.
Low-sugar formulations command the established base. The steepest expansion runs through organic.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Grain milling infrastructure concentrates in the US Midwest and Canadian prairies, with three regional processors controlling the majority of organic oat supply. This concentration creates sourcing bottlenecks for clean-label product lines while shaping cross-border trade flows.
United States
Urban millennial households in the Northeast and Pacific Northwest drive demand for protein-fortified and single-serve formats. The FDA's updated Nutrition Facts labeling requirements mandate gram-level added sugar disclosure, forcing reformulation across children's cereal portfolios. Minneapolis-St. Paul anchors conventional manufacturing scale, while Boulder, Colorado and Austin, Texas cluster organic and clean-label innovation.
Canada
Health-conscious consumers in Toronto and Vancouver concentrate demand for muesli and low-sugar formulations. Health Canada's bilingual labeling mandate and PMRA pesticide residue limits regulate cross-border imports, slowing US brand entry. The Prairie Provinces supply organic grain inputs, with Saskatchewan oat growers advancing regenerative agriculture certification.
Mexico
Rising middle-class households in Mexico City and Monterrey expand demand for convenient breakfast options. Mexico's national food safety regulator enforces labeling standards aligned with USMCA trade provisions. The Bajío Region hosts grain processing facilities serving domestic distribution networks.
North America Breakfast Cereals Market Competitive Landscape
Scale-driven multinationals and health-positioned specialists split the market between mass-market volume and premium-margin niches. The vendor base organizes around three strategic archetypes: conventional retail dominators leveraging manufacturing scale, organic-certified players penetrating natural-food channels, and convenience-oriented innovators capturing portable format demand. Competitive intensity manifests through portfolio diversification into protein-fortified segments and strategic partnerships with regenerative agriculture suppliers.
Within the scale-driven tier, General Mills Inc. and Kellanova anchor conventional retail presence, while Nature's Path Foods exemplifies the organic-certified specialist archetype. These three represent divergent margin strategies across the North American breakfast cereals landscape.
| Leading Market Players |
|---|
| Mars Inc. |
| Nature's Path Foods |
| General Mills Inc. |
| Ferrero Group |
| Kellanova |
| PepsiCo Inc. |
| Bob's Red Mill Natural Foods |
| Nestle SA |
| Post Holdings Inc. |
| Others |
Value Network & Pricing Analysis
Organic oat supply concentration in the Great Plains creates sourcing bottlenecks that determine both pricing tier spreads and supply chain shape. Three regional grain processors control the majority of certified organic oat supply, forcing manufacturers to advance-contract for field access while compressing margin predictability across clean-label product lines.
Pricing Analysis
FDA's updated Nutrition Facts labeling requirements dictate the pricing tier structure across the North American breakfast cereals landscape. Three-tier pricing structure across premium, standard, and economy levels separates USDA-certified organic formulations from conventional fortified products and private-label commodity flakes. Price differentiation rests on certification grade and brand premium, with organic and gluten-free variants commanding shelf price premiums in natural-food retail channels. Cost compression in children's cereal segments is intensifying because parental sugar awareness demands expensive reformulation with monk fruit and allulose blends. Families represent the most price-sensitive buyer segment, while health-conscious urban millennials exhibit lowest price elasticity for protein-fortified and single-serve formats.
Supply Chain Analysis
Tariff exposure between the United States and Canada dominates supply chain risk calculations for cross-border cereal brands. Geographic supply concentration centers on the US Midwest, Canadian prairies, and Mexico's Bajío Region for grain processing infrastructure. Raw material dependencies draw from organic oats, corn grits, and protein isolates sourced through advance contracts with certified growers. Single-source vulnerability runs through the three regional processors controlling organic oat supply. Distribution runs through conventional supermarket center-store placement, direct-to-consumer subscription platforms, and natural-food retail channels with certified organic gatekeeping.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct-to-subscription channel expansion represents a service-attach opportunity where recurring revenue from customizable granola and muesli blends expands faster than conventional retail hardware sales.
For Market Incumbents: Harden supply chain resilience through backward integration into regenerative agriculture sourcing and captive organic oat contracting with Prairie Provinces growers. Kellanova and General Mills must defend against refrigerated protein bar substitution by accelerating portable format innovation. Vertical integration into certified organic supply chains is the priority lever for margin defense against clean-label specialists. For New Entrants and Emerging Players: Canadian underpenetration offers first-mover advantage for US brands willing to absorb Health Canada bilingual labeling compliance costs ahead of competitors. Health-conscious consumers in Toronto and Vancouver represent the most penetrable white-space target. Direct-to-consumer subscription platforms enable bypass of conventional retail slotting fees while capturing loyalty-locked households through customizable product configurations. For Investors and Strategic Acquirers: FDA's added sugar disclosure mandate reshapes the acquisition landscape toward reformulation-capable specialists with clean-label expertise. Five-to-ten year viability favors mid-tier manufacturers with demonstrated USDA organic certification timelines and established Health Canada equivalency. Food technologist talent scarcity signals acquisition premiums for firms with proven natural preservative systems and texture stabilization capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Regenerative Agriculture Sourcing | Aligns with corporate Scope 3 emissions targets for institutional foodservice procurement. |
| Direct-to-Consumer Subscription Launch | Bypasses retail slotting fees while capturing recurring revenue from loyalty-locked households. |
| Canadian Market Entry with Compliant Packaging | Health Canada bilingual labeling mandate creates first-mover advantage for reformulated products. |
| Protein Fortification Technology Investment | Extrusion process integration of whey and plant-based isolates meets urban millennial demand. |
| Organic Certification Pipeline Expansion | Three-year field transition periods require advance contracting with certified growers. |
Research Methodology
Operator-level perspectives from brand managers, category buyers at retailers, supply planners, and channel sales heads anchored the qualitative base for this study. Primary interviews with breakfast cereal manufacturers and natural-food retail operators combined with secondary validation from Nielsen retail audit data, USDA organic certification records, FDA filing databases, and customs import records. Bottom-up volume modeling and top-down value triangulation cross-checked segment-level assumptions across the analysis window.
Scenario-bracketing framed the analytical approach with sensitivity testing across commodity price volatility and regulatory compliance cost trajectories. Segmentation dimensions modeled include product type, distribution channel, target consumer, and ingredient certification tier. CAGRs derived from historical trajectory analysis and forward-looking demand elasticity assessments. Forecast inputs incorporated protein fortification technology adoption curves and organic supply chain expansion timelines.
Macroeconomic conditions sit as an overlay; deviation in grain futures volatility and consumer discretionary spending patterns would shift the trajectory of premium segment growth. Forecasts reflect documented assumptions about regulatory implementation timing and supply chain certification throughput. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Asia-Pacific Ready Meals Market
Packaged Foods
Ready to Use Fillings Market
Packaged Foods
Sugar Free Cookies Market
Packaged Foods
Cook-In-Bags Market
Packaged Foods
India Breakfast Cereals Market
Packaged Foods
Europe Breakfast Cereals Market
Packaged Foods
Chocolate Based Spreads Market
Packaged Foods
North America Ready-To-Eat Food Market
Packaged Foods
Fruit Filling Market
Packaged Foods
Asia-Pacific Ready-To-Eat Food Market
Packaged Foods
Global Oven Bags Market
Packaged Foods
Wet Food Pouch Market
Packaged Foods
Non-Fried Instant Noodles Market
Packaged Foods
Instant Noodles Market
Packaged Foods
Packaged Currants Market
Packaged Foods
Packaged Sprouts Market