
 United States Biodegradable Food Service Disposables Market | 2026-2036
United States Biodegradable Food Service Disposables Market Size, Share, and Industry Trends Forecast 2026-2036
United States Biodegradable Food Service Disposables Market Intelligence
Domestic molded fiber production is consolidating across the Great Lakes and Southeast manufacturing belts as capacity scales to meet foodservice procurement mandates. Georgia-Pacific LLC leverages its integrated pulp supply chain to control raw material costs across plate and bowl lines. Eco-Products, Inc. anchors the premium PLA cup segment through direct partnerships with national coffeehouse distributors. Pactiv Evergreen Inc. competes on thermoformed sugarcane clamshell scale, serving regional quick-service chains with refrigerated takeaway formats.
United States biodegradable food service disposables comprise single-use articles engineered from plant-derived polymers, agricultural residues, or certified compostable paper substrates, typically meeting ASTM D6400 or D6868 standards for industrial composting breakdown within 180 days. These articles serve commercial food preparation, delivery, and consumption workflows where conventional petroleum-based plastics face regulatory phaseouts or corporate sustainability exclusions. Sugarcane bagasse plates dominate unit volume due to cost parity with conventional foam and broad industrial composting acceptance. PLA cups and lids command premium positioning in cold-beverage takeaway applications where optical clarity and printability differentiate brand presentation. Bamboo cutlery occupies a narrow but expanding niche in catering and corporate events where tactile quality signals environmental commitment.
FDA food contact substance notifications govern migration limits for biopolymer coatings, while EPA guidelines under the Food Recovery Hierarchy influence municipal composting infrastructure that underpins product end-of-life claims. California's SB 54 and New York's extended producer responsibility proposals tighten material recovery obligations, effectively mandating compostable formats for on-premise dining and event catering across the two largest state economies. Stakeholders must monitor municipal composting capacity buildout against product certification requirements, as infrastructure gaps in the Midwest and Mountain West threaten to strand compostable claims without operational processing facilities.
Market Dynamics
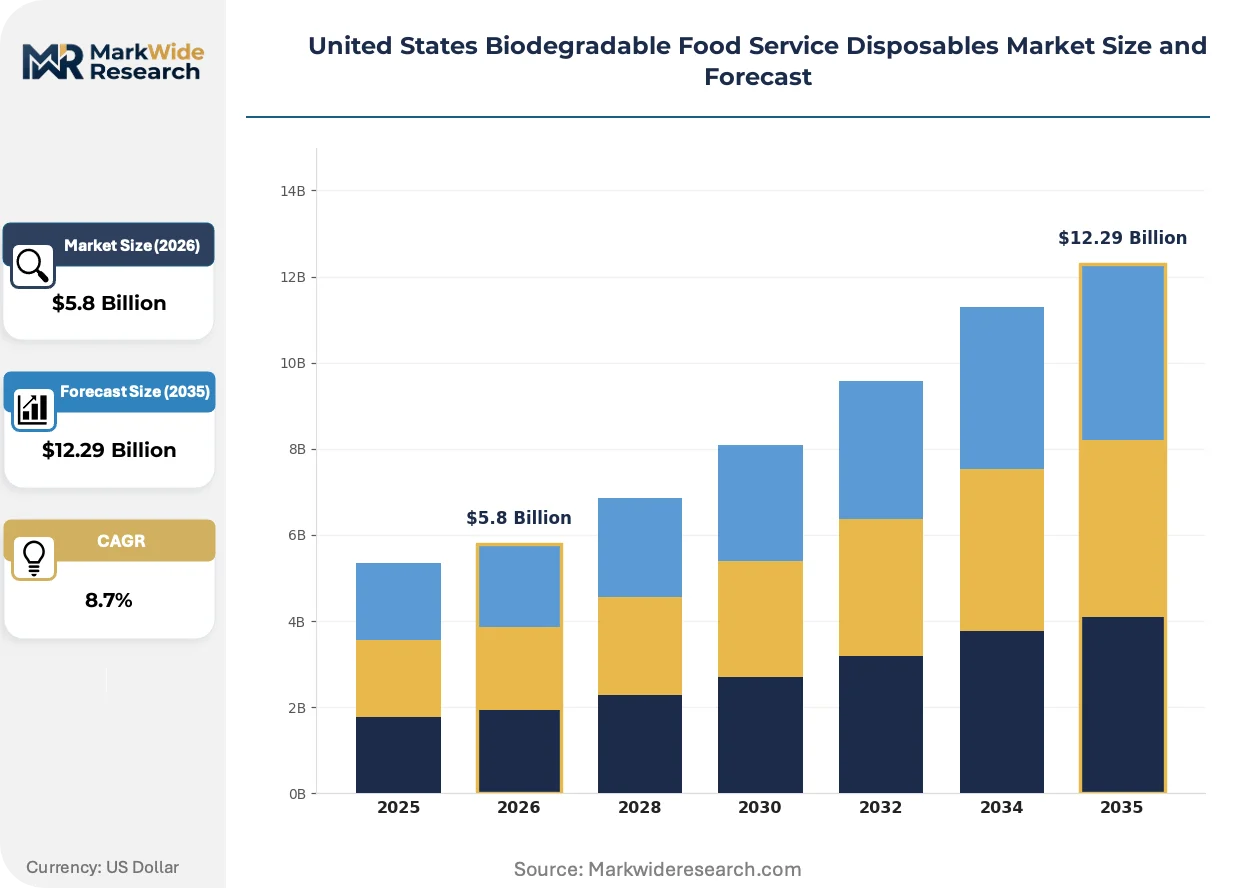
California's SB 54 extended producer responsibility law is compressing procurement timelines across quick-service restaurant supply chains, forcing national chains to requalify serviceware vendors before 2032 compliance deadlines.
Growth Catalysts
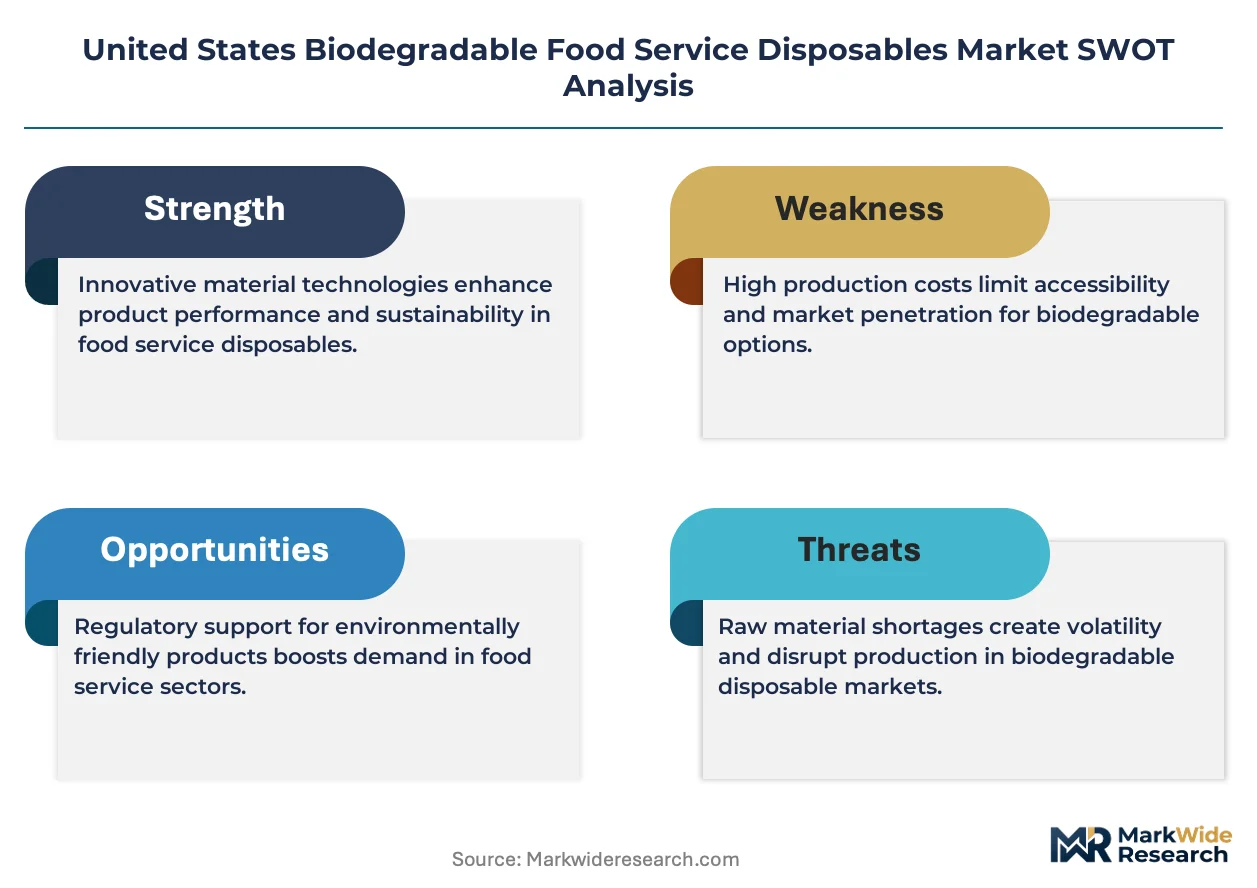
- Corporate cafeteria mandates:Fortune 500 campus procurement programs now require ASTM D6400-certified compostable serviceware for all on-premise dining contracts.
- Industrial composting buildout:Northeast corridor municipalities from Boston to Washington DC are expanding curbside organics collection that accepts bagasse and PLA waste streams.
- Sugarcane bagasse cost parity:Molded fiber production scaling across Georgia and Michigan manufacturing belts has eliminated the price premium versus conventional polystyrene foam.
Market Restraints
- PLA resin supply concentration:Domestic lactic acid fermentation capacity remains concentrated among three Midwest chemical processors, exposing converters to input volatility.
- Midwest composting infrastructure gaps:Industrial composting facilities in Ohio, Indiana, and Illinois lack the throughput to process certified disposables at claimed end-of-life specifications.
- Polystyrene substitution persistence:Foam clamshells retain cost advantages in rural quick-service markets where municipal composting mandates remain unenforced.
Strategic Opportunities
- Mountain West penetration:Colorado and Utah quick-service chains face pending state-level single-use plastic phaseouts without established local molded fiber suppliers.
- Hot-beverage lid innovation:CPLA and crystallized PLA formulations are opening certified compostable alternatives to conventional plastic lids in coffeehouse drive-thru formats.
- Event catering channel expansion:Stadium and arena concessionaires are sourcing bamboo cutlery and palm leaf plates for premium hospitality suites under LEED venue certification requirements.
Industry Challenges
- ASTM D6400 certification timeline:Third-party compostability testing requires 180-day industrial facility validation that delays new product launches by 8-12 months.
- Molded fiber tooling capex intensity:Bagasse plate and bowl production requires thermoforming equipment investments exceeding $4 million per production line.
- Food contact migration compliance:FDA notification submissions for novel biopolymer coatings demand extensive extractables testing that strains mid-cap converter resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Biodegradable Food Service Disposables Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $12.29 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plates, Cutlery, Bowls, Cups Material: PLA, Sugarcane, Bamboo, Paper Application: Catering, Restaurants, Events, Takeaway End User: Foodservice, Retail, Catering Companies, Consumers |
| Companies Covered | Georgia-Pacific LLC, Eco-Products, Inc., Dart Container Corporation, Genpak LLC, Pactiv Evergreen Inc., Anchor Packaging Inc., WestRock Company, Graphic Packaging International LLC, WorldCentric, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Biodegradable Food Service Disposables Market Strategic Shifts & Innovations
Material science breakthroughs and regulatory enforcement timelines are converging to reshape competitive positioning across cold-beverage, hot-food, and cutlery categories.
Barrier-coated molded fiber is electrifying the hot-food takeaway segment. Georgia-Pacific and regional converters are deploying aqueous and PLA-laminated formulations that replace polyethylene liners in soup bowls and grease-resistant clamshells. Quick-service chains in the Northeast corridor are qualifying these formats for fried chicken and noodle applications where oil resistance previously mandated plastic. The technology is electrifying category expansion by collapsing the performance gap between fiber and conventional plastic at unit economics viable for value-menu pricing.
EPA guidelines under the Food Recovery Hierarchy are accelerating municipal composting infrastructure investment. The agency's waste diversion prioritization is channeling federal grant funding toward industrial composting facility expansion in states with pending single-use plastic bans. California and New York municipal waste authorities are responding with procurement specifications that explicitly favor ASTM D6868-certified products, creating preferential vendor status for converters with established certification documentation.
Direct distributor partnerships are replacing traditional foodservice broker networks for premium PLA cup placement. National coffeehouse chains are consolidating cold-beverage serviceware procurement through exclusive supply agreements with certified converters, bypassing broadline distributors. This channel compression is most visible in the Pacific Northwest and Mid-Atlantic urban markets where sustainability scoring directly influences contract awards.
United States Biodegradable Food Service Disposables Market Segmentation
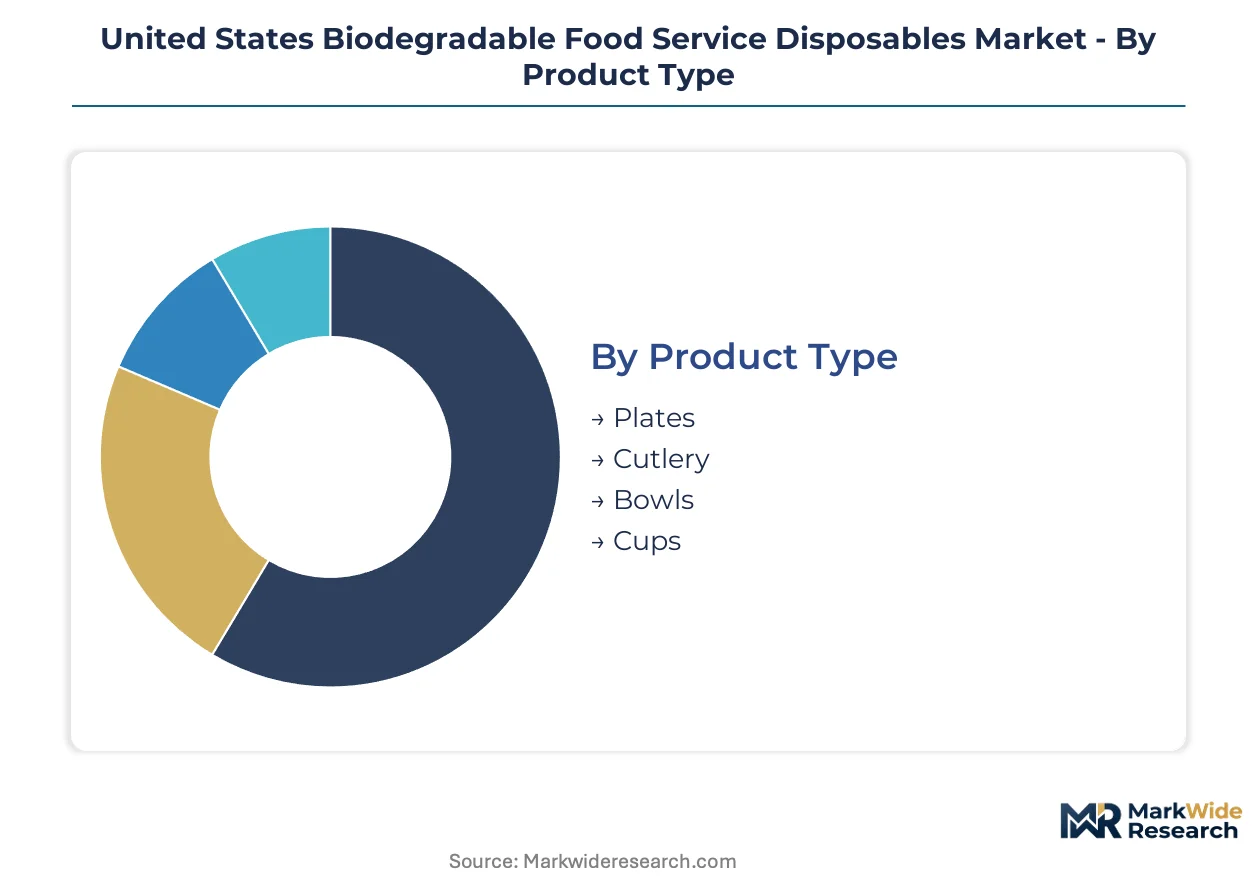
Segmentation reveals how procurement mandates and infrastructure availability concentrate demand across distinct product-material combinations. Each dimension exposes mismatches between certification requirements and operational composting capacity that shape vendor selection criteria.
Product Type:
Domestic manufacturing capacity clusters around molded fiber formats where thermoforming equipment amortizes across high-volume quick-service contracts.
- Plates:Molded sugarcane bagasse dominates this category with grease-resistant aqueous coatings replacing polyethylene liners. Northeast corridor quick-service chains from Boston to Washington DC specify these for fried chicken and burger formats under corporate sustainability mandates. Sugarcane plates absorb the bulk of installed capacity; cups are expanding most quickly.
- Cups:PLA cold-beverage formats with crystallized resin structures command premium positioning through optical clarity and direct-print branding. National coffeehouse distributors in the Pacific Northwest and Mid-Atlantic urban markets source these through exclusive supply agreements that bypass traditional broadline channels.
- Cutlery:Bamboo and CPLA alternatives serve catering and corporate events where tactile quality signals environmental commitment.
- Bowls:Barrier-coated molded fiber with PLA lamination handles soup and noodle applications where oil resistance previously mandated plastic.
Plates absorb the bulk of installed capacity; cups are expanding most quickly.
Material:
Raw material sourcing geography directly determines converter margin structures and supply security.
- Sugarcane:Bagasse pulp from Georgia-Pacific and regional converters leverages integrated supply chains across Georgia and Michigan manufacturing belts. Cost parity with conventional polystyrene foam has eliminated price premiums in quick-service procurement.
- PLA:Lactic acid fermentation capacity concentrates among three Midwest chemical processors, exposing converters to input volatility. Cold-beverage clarity and hot-beverage lid applications drive specification.
- Bamboo:Import-dependent supply serves premium catering and stadium hospitality suites under LEED venue certification requirements.
- Paper:Certified compostable substrates with aqueous barriers compete in cost-sensitive takeaway formats where industrial composting infrastructure is operational.
Sugarcane commands the greatest production volume; PLA claims the steepest expansion trajectory.
Application:
Regulatory enforcement intensity varies sharply across use cases, creating procurement timeline compression in mandated channels.
- Restaurants:Quick-service chains face California SB 54 requalification deadlines before 2032, forcing vendor consolidation. Molded fiber clamshells and bagasse plates dominate refrigerated takeaway formats.
- Catering:Corporate events and Fortune 500 campus dining specify ASTM D6400-certified serviceware for all on-premise contracts. Bamboo cutlery and palm leaf plates signal environmental commitment in hospitality suites.
- Takeaway:Cold-beverage cups and hot-food containers face municipal composting acceptance gaps in Midwest and Mountain West markets.
- Events:Stadium and arena concessionaires source premium formats under venue sustainability scoring systems.
Restaurants anchor procurement volume; catering is gaining share fastest.
End User:
Buyer sophistication around certification documentation and composting infrastructure access determines contract award criteria.
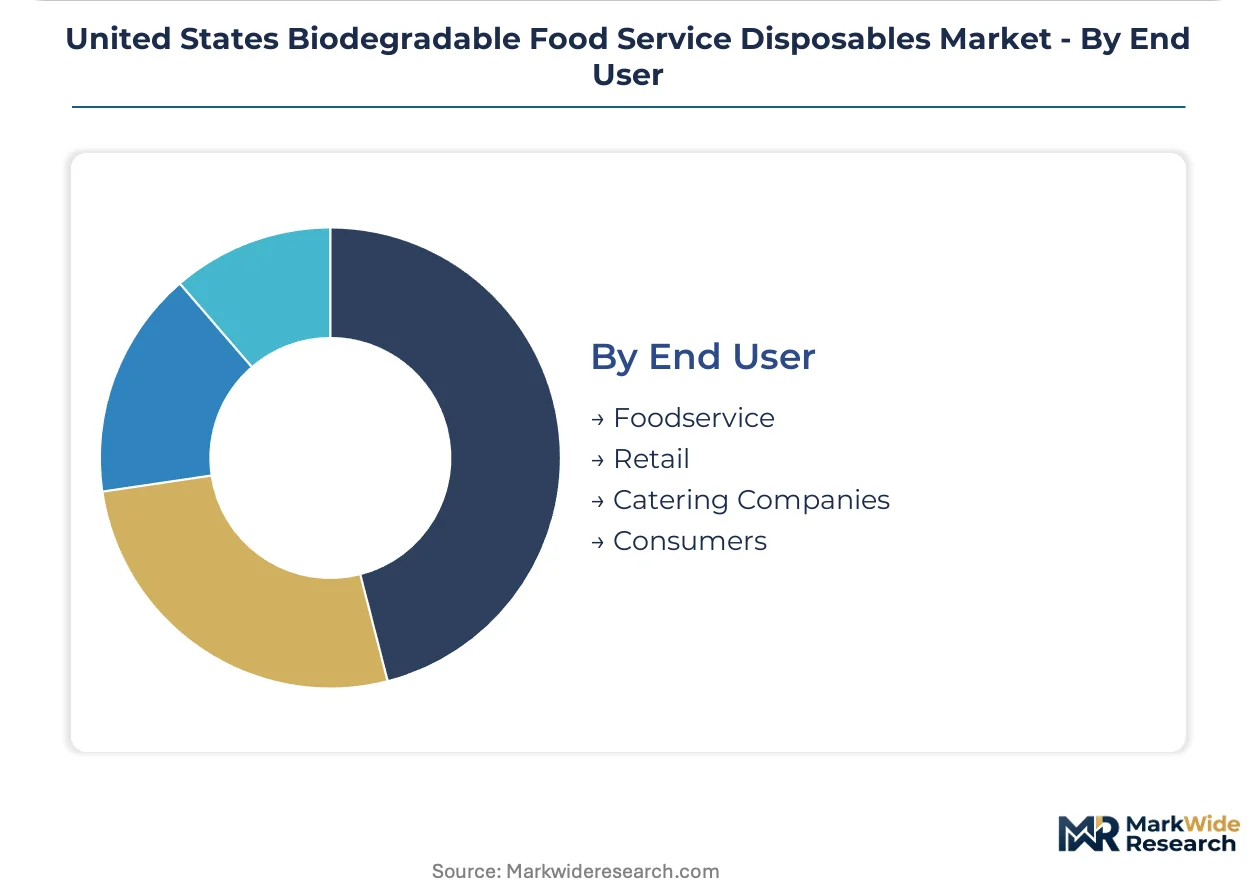
- Foodservice:National quick-service chains and corporate cafeteria operators mandate ASTM D6400 or D6868 certification with verified industrial composting pathways. Direct distributor partnerships are replacing traditional broker networks.
- Catering Companies:Event specialists source premium bamboo and palm leaf formats for client sustainability reporting requirements.
- Retail:Grocery prepared-food sections and convenience stores specify cost-optimized molded fiber where municipal organics collection is available.
- Consumers:Direct purchasing concentrates in Colorado and Utah markets facing pending state-level single-use plastic phaseouts.
Foodservice directs the majority of contract value; catering companies are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bagasse pulp mills in Georgia and Michigan anchor domestic molded fiber capacity, while PLA resin fermentation concentrates in Midwest chemical corridors. State-level extended producer responsibility laws are compressing procurement timelines across quick-service supply chains.
California
SB 54 mandates material recovery targets that force quick-service chains to requalify serviceware vendors before 2032. EPA guidelines under the Food Recovery Hierarchy channel federal grant funding toward industrial composting facility expansion in Los Angeles and San Francisco metro areas. Central Valley agricultural processors supply bagasse feedstock to converters serving West Coast coffeehouse distributors.
New York
Pending extended producer responsibility proposals tighten obligations for on-premise dining and event catering across the metropolitan region. State environmental regulators favor ASTM D6868-certified products in municipal procurement specifications. Hudson Valley composting facilities are expanding throughput to handle certified disposables from Manhattan corporate cafeteria contracts.
Georgia
Integrated pulp supply chains from Savannah forestry operations support cost-competitive bagasse plate and bowl production. State environmental regulations lag federal EPA guidelines, creating enforcement gaps in rural quick-service markets. Atlanta serves as the Southeast distribution hub for molded fiber clamshells serving regional refrigerated takeaway chains.
Michigan
Thermoforming equipment clusters in Detroit and Grand Rapids manufacturing belts scale capacity to meet Fortune 500 campus procurement mandates. State composting infrastructure remains underdeveloped relative to production capacity, threatening to strand compostable claims. Great Lakes shipping corridors connect Michigan converters to Northeast corridor quick-service distribution networks.
Colorado
Pending state-level single-use plastic phaseouts are driving quick-service chains to source molded fiber alternatives without established local supplier bases. Denver and Boulder municipal waste authorities are expanding curbside organics collection that accepts bagasse and PLA waste streams. Mountain West location creates freight cost disadvantages versus Great Lakes and Southeast manufacturing centers.
United States Biodegradable Food Service Disposables Market Key Industry Players
Global majors compete with regional champions across raw material integration and certification documentation capabilities. Market structure consolidates around pulp-integrated conglomerates and specialized PLA converters, with mid-cap molded fiber specialists occupying niche geographies. Three archetypes dominate: integrated pulp-to-converter operators, fermentation-dependent biopolymer specialists, and regional thermoforming scale players. Capacity expansion and direct distributor partnership formation represent the dominant competitive moves as procurement timelines compress.
Within the integrated pulp operator tier, Georgia-Pacific LLC exemplifies backward control over feedstock costs, while Eco-Products, Inc. and Pactiv Evergreen Inc. represent distinct positioning vectors in premium PLA cups and thermoformed sugarcane scale respectively. These three entities anchor the competitive structure by demonstrating how raw material access, certification depth, and channel relationships stratify vendor selection in national quick-service and corporate cafeteria procurement programs.
| Leading Market Players |
|---|
| Georgia-Pacific LLC |
| Eco-Products, Inc. |
| Dart Container Corporation |
| Genpak LLC |
| Pactiv Evergreen Inc. |
| Anchor Packaging Inc. |
| WestRock Company |
| Graphic Packaging International LLC |
| WorldCentric |
| Others |
Cost & Logistics Intelligence
Bagasse pulp price indices from Georgia-Pacific and Southeast regional mills cascade through converter pricing tiers, compressing margins for non-integrated processors while rewarding backward-linked operators with cost pass-through advantages in national quick-service procurement.
Pricing Analysis
Certification documentation bundling separates ASTM D6400-validated products from uncertified alternatives at the contract negotiation stage. Three-tier pricing structure across premium PLA cups, standard bagasse plates, and economy paper formats tracks raw material input volatility and composting infrastructure access. Cost compression in the PLA tier is intensifying because Midwest lactic acid fermentation capacity concentrates among three processors. Quick-service chains in the Northeast corridor exhibit least price sensitivity due to SB 54 compliance mandates; rural independent operators in Georgia and Michigan show highest sensitivity where polystyrene foam remains available.
Supply Chain Analysis
Single-source vulnerability sits with Midwest lactic acid fermentation clusters that feed PLA resin production for cold-beverage cup converters. Raw material sourcing draws from Georgia and Michigan bagasse pulp mills, imported bamboo fiber for premium cutlery, and Illinois-Indiana-Ohio chemical corridors for biopolymer feedstock. Tariff exposure on imported bamboo and palm leaf inputs threatens margin stability for catering-focused specialists. Distribution runs through direct partnerships with national coffeehouse distributors and broadline foodservice brokers serving regional quick-service chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
California's SB 54 extended producer responsibility law erects a compliance moat that favors ASTM D6400-certified incumbents while raising capital barriers for uncertified entrants lacking testing documentation and industrial composting partnerships.
For Market Incumbents: Deepen backward integration into bagasse pulp supply chains across Georgia and Michigan manufacturing belts to defend against resin price volatility from Midwest fermentation concentration. Fortify certification documentation capabilities to accelerate new product launches ahead of 2032 requalification deadlines. Prioritize direct distributor partnerships that disintermediate broadline brokers in premium PLA cup placement. For New Entrants and Emerging Players: National coffeehouse distributors represent the most penetrable channel wedge for certified converters lacking established quick-service relationships. Target Colorado and Utah quick-service markets facing pending single-use plastic phaseouts without local molded fiber supplier bases. Pursue white-label production partnerships with Great Lakes thermoforming specialists to bypass $4 million per-line capital requirements. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap molded fiber specialists with underutilized thermoforming capacity in Michigan and Georgia manufacturing belts. Long-term viability hinges on municipal composting infrastructure buildout keeping pace with product certification expansion. Monitor EPA grant funding disbursement velocity under Food Recovery Hierarchy guidelines as the signal for industrial composting capacity inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bagasse Pulp Supply | Georgia-Pacific's captive pulp sourcing controls raw material costs across plate and bowl lines. |
| ASTM D6400 Certification Investment | Third-party validation documentation accelerates vendor requalification under California SB 54 timelines. |
| Direct Distributor Partnership Formation | National coffeehouse exclusive supply agreements bypass broadline broker networks in premium PLA placement. |
| Mountain West Geographic Expansion | Colorado and Utah quick-service chains lack established local molded fiber suppliers pending plastic phaseouts. |
| Barrier-Coated Molded Fiber R&D | Aqueous and PLA-laminated formulations replace polyethylene liners in soup bowls and grease-resistant clamshells. |
Research Approach
Document review covered FDA food contact substance notifications, EPA Food Recovery Hierarchy guidelines, California SB 54 regulatory filings, and municipal composting infrastructure databases, complemented by interviews with thermoforming plant managers, quick-service procurement directors, national coffeehouse supply chain leads, and industrial composting facility operators. Secondary validation drew from SEC 10-K disclosures of publicly traded packaging converters, trade association production surveys, and customs data on bamboo fiber imports. Bottom-up capacity modeling and top-down procurement mandate tracking were triangulated against shipment data from Great Lakes and Southeast manufacturing belts.
Unit volume and value projections across the analysis window reflect segmentation by product type, material substrate, application channel, and end-user sophistication tier, with CAGRs derived from procurement timeline compression under state-level extended producer responsibility laws. The modeling framework incorporates industrial composting facility buildout schedules, lactic acid fermentation capacity expansion announcements, and quick-service chain vendor requalification deadlines as demand-side inputs.
Caveats apply where municipal composting infrastructure gaps in the Midwest and Mountain West could materially strand compostable product claims without operational processing facilities. Forecasts reflect assumptions about SB 54 enforcement intensity, EPA grant funding velocity, and resin supply concentration stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Personal Chef Services Market
Food Service
Halal Food and Beverages Market
Food Service
Philippines Foodservice Market
Food Service
Europe Online Grocery Market
Food Service
Global Sushi Restaurants Market
Food Service
Global Digital Food Delivery Market
Food Service
Online Grocery Market
Food Service
Clear Ice Maker Market
Food Service
United States Full Service Restaurants Market
Food Service
Latin America Biodegradable Food Service Disposables Market
Food Service
Air Fryer Market
Food Service
Restaurant Takeout Market
Food Service
Restaurants and Mobile Food Services Market
Food Service
Retail Bubble Tea Kits Market
Food Service
Smoker Grill Market
Food Service
Global Dark Store Market