
 Asia-Pacific Ready Meals Market | 2026-2036
Asia-Pacific Ready Meals Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Ready Meals Market Outlook
Thailand's ready-meal manufacturing corridor is reconfiguring supply dynamics across Southeast Asia. Ajinomoto Co., Inc. leverages its umami technology platform to dominate premium frozen rice and noodle segments. CJ CheilJedang Corporation anchors Korean-style ready meals through captive distribution in convenience-store networks. Nichirei Foods Inc. sustains margin leadership via backward integration into vegetable sourcing and blast-freezing infrastructure.
Ready meals comprise pre-cooked food formulations preserved through freezing, chilling, thermal processing, or dehydration to enable rapid consumption with minimal preparation, typically requiring reheating to core temperatures of 75°C or commercial equivalent. Frozen meals occupy the largest value pool due to extended shelf stability and established retail penetration, while chilled meals capture the fastest expansion as cold-chain reliability improves in urban China and India. Shelf-stable meals retain defensive demand in disaster-preparedness and military segments across Japan and Indonesia.
Japan's Consumer Affairs Agency enforces strict allergen labeling under Food Labeling Act amendments, compelling reformulation of multi-component tray meals. Australia's FSANZ mandates nutrition panel disclosure that shapes product development priorities for export-oriented manufacturers. China's SAMR oversees escalating food-safety audits that determine market-access eligibility for both domestic and imported brands. Stakeholders must monitor divergence between national labeling regimes as cross-border e-commerce channels expand regional product mobility.
Market Dynamics
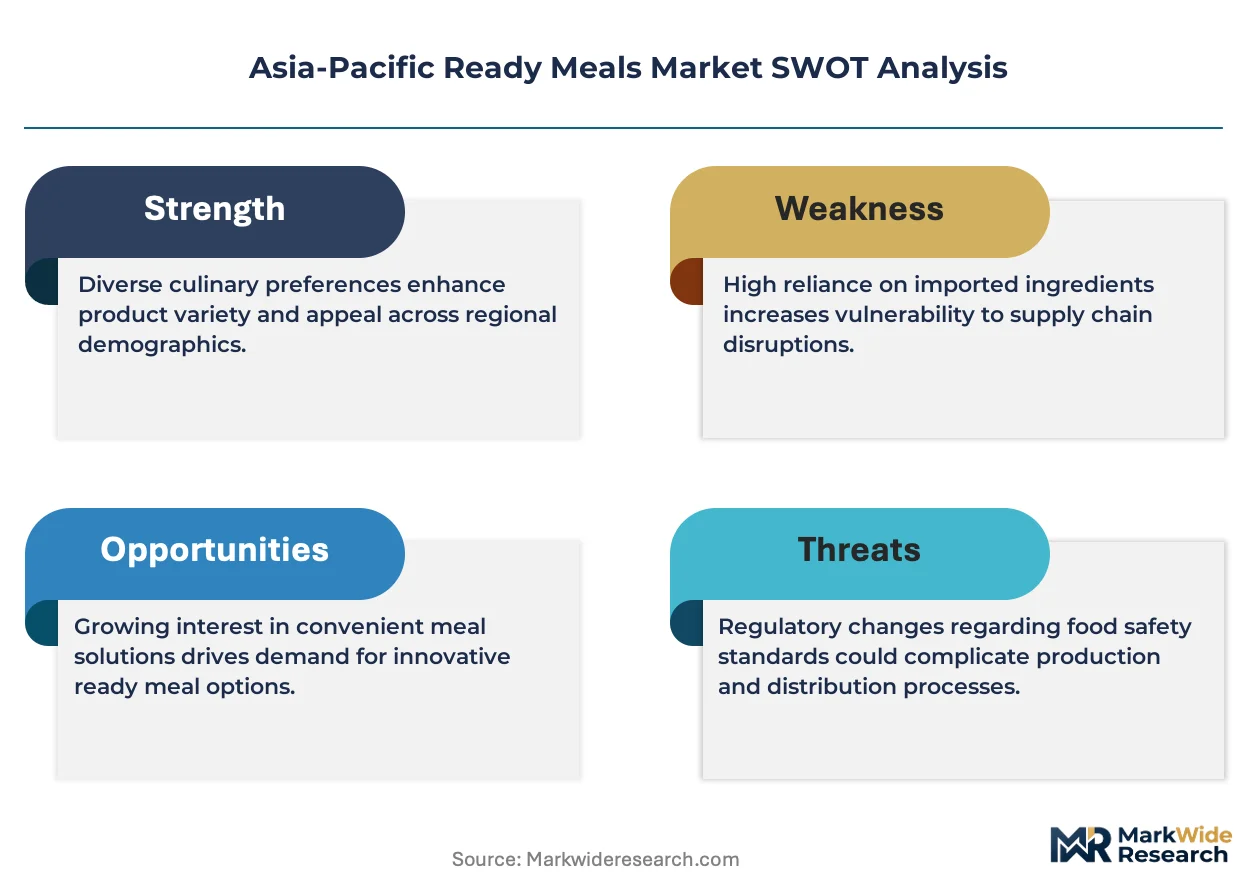
Cold-chain infrastructure compression is reshaping distribution economics across the Asia-Pacific ready meals sector, enabling apartment-level chilled delivery in dense megacities where freezer ownership remains limited.
Growth Catalysts
- Urban work-hour compression:Households in Shanghai, Tokyo, and Bangalore face shrinking discretionary time for meal preparation, creating structural demand for heat-and-eat solutions.
- METI food labeling standards:Japan's transparency mandates accelerate consumer trust formation, reducing information asymmetry that historically slowed premium ready meal adoption.
- Blast-freezing technology diffusion:Equipment cost curves enable mid-tier manufacturers to achieve texture parity with legacy producers, expanding competitive supply.
Market Restraints
- Input cost volatility:Wheat and rice price swings compress margin predictability for noodle and rice-based tray meal producers.
- Cold-chain capital intensity:Last-mile refrigeration requirements in tropical Southeast Asia limit viable distribution radius for chilled meal formats.
- SAMR audit escalation:China's food-safety inspection tightening creates market-access friction for smaller domestic manufacturers lacking compliance infrastructure.
Strategic Opportunities
- India tier-2 urban corridors:Cold-chain penetration in Pune, Hyderabad, and Chennai remains underdeveloped relative to demand potential.
- Convenience-store network densification:24-hour retail formats in South Korea and Taiwan create new impulse-purchase touchpoints for single-serve formats.
- Dual carbon goals alignment:China's emission-reduction mandates favor centralized meal production over dispersed home cooking energy use.
Industry Challenges
- Allergen management complexity:FSANZ and Japan's Consumer Affairs Agency impose divergent labeling thresholds, forcing SKU proliferation for export-oriented producers.
- Recipe-to-shelf timeline compression:Social media-driven flavor trends accelerate product obsolescence, demanding agile formulation pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Ready Meals Market |
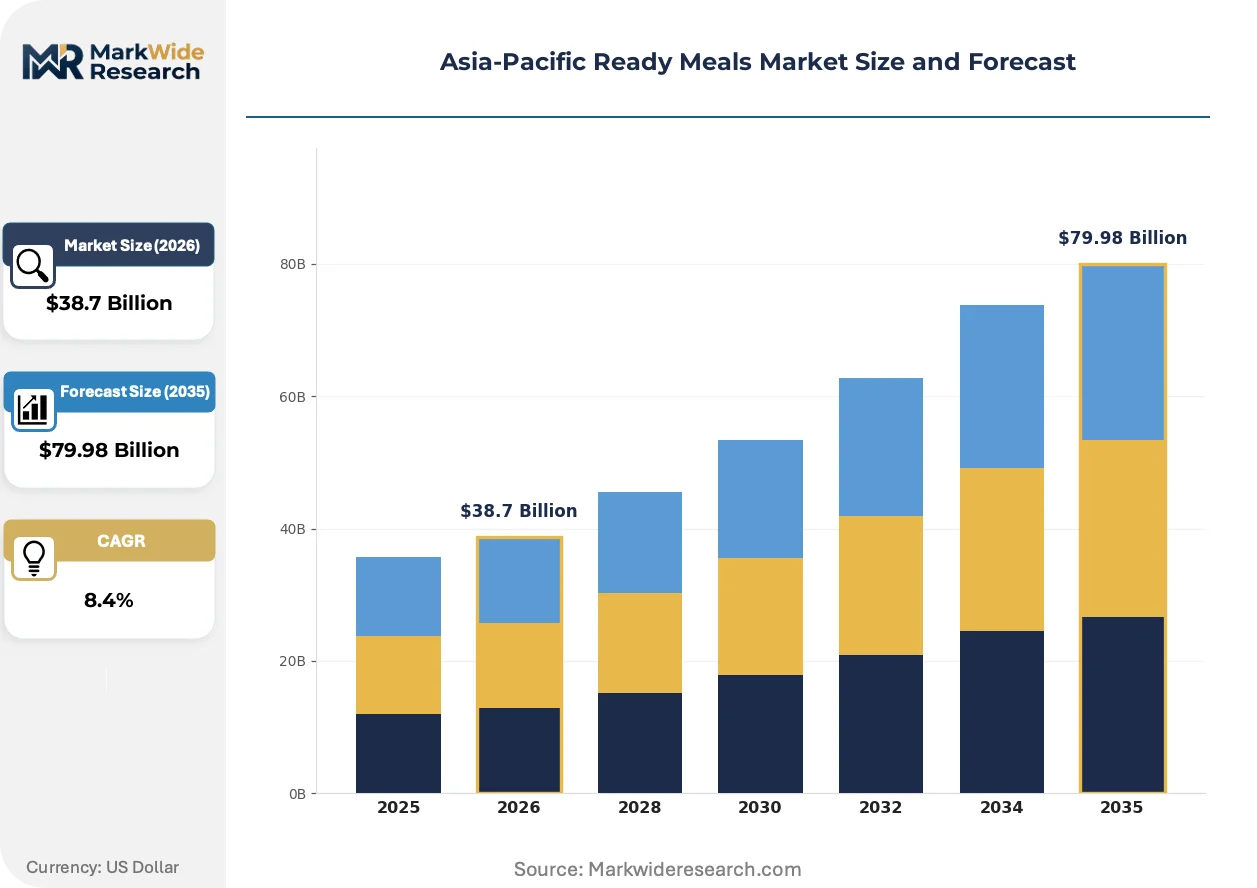
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Meals, Chilled Meals, Shelf-stable Meals, Dried Meals End User: Households, Food Service, Retail, Catering Services Packaging Type: Tray, Pouch, Box, Can Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Wholesalers |
| Companies Covered | Nestlé SA, Ajinomoto Co., Inc., McCain Foods Ltd, Conagra Brands Inc., Nichirei Foods Inc., CJ CheilJedang Corporation, Ting Hsin International Group, ITC Limited, MTR Foods Pvt Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Ready Meals Market Strategic Shifts
Active packaging technologies and regulatory transparency mandates are converging to redefine product integrity communication and shelf-life extension across the Asia-Pacific ready meals landscape.
Modified atmosphere packaging is hybridizing with time-temperature indicators to create self-monitoring meal trays. Premium convenience-store chains in Japan and South Korea are piloting these solutions for high-margin chilled bento formats. The technology is compressing quality-risk premiums and enabling direct-to-consumer subscription models previously vulnerable to cold-chain failure disputes.
Japan's Consumer Affairs Agency allergen labeling amendments now mandate component-level disclosure for multi-ingredient tray meals. Manufacturers serving export markets must maintain parallel formulation databases to satisfy both domestic and Australian FSANZ requirements. The regulation is forcing consolidation among small-scale producers lacking compliance infrastructure.
Meal-kit unbundling is disrupting traditional retail-ready meal relationships in urban China. Young professionals in Beijing and Shenzhen now subscribe to pre-portioned ingredient sets requiring 10-minute assembly rather than full heat-and-eat solutions. The shift is fragmenting demand between convenience absolutists and cooking-involvement seekers, creating format-specific channel strategies.
Asia-Pacific Ready Meals Market Segmentation
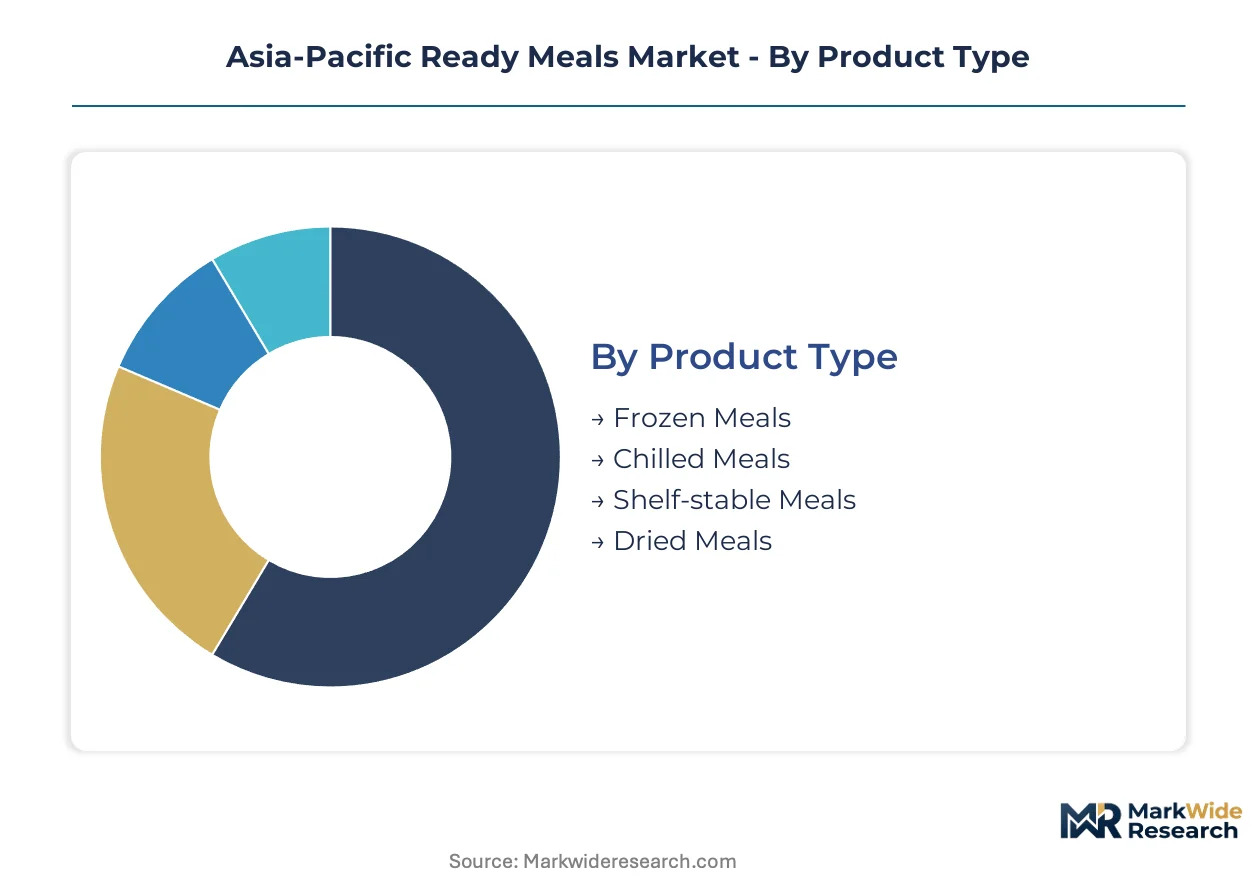
Segmentation in the Asia-Pacific ready meals sector reveals how preservation technology, consumption context, and channel infrastructure create distinct competitive arenas. Each dimension carries unique regulatory, logistical, and margin implications for manufacturers targeting urban consumers across divergent cold-chain maturity levels.
Product Type:
Use-case spectrum spans from freezer-dependent long-term storage to ambient pantry stocking, with each format demanding specialized production assets and distribution partnerships.
- Frozen Meals:Blast-frozen formulations preserved at -18°C deliver maximum shelf stability for protein-heavy rice and noodle combinations. Shanghai and Tokyo apartment households with limited freezer space drive demand for compact single-serve formats despite cold-chain dependency.
- Chilled Meals:Refrigerated products with 5-7 day shelf life capture heat-and-eat immediacy through modified atmosphere packaging. Urban China and South Korea lead adoption as last-mile refrigeration density enables apartment-level delivery without freezer ownership.
- Shelf-stable Meals:Retort-pouched or canned formulations withstand tropical storage without refrigeration. Japan's disaster-preparedness procurement and Indonesia's archipelago logistics create defensive demand for ambient formats.
- Dried Meals:Dehydrated noodle and rice products requiring hot water reconstitution serve backpacking, military, and budget segments across mountainous Southeast Asian markets.
The dominant share belongs to frozen meals, while chilled meals are closing the gap fastest.
End User:
Cost tier differentiation separates premium household convenience from high-volume institutional procurement with divergent price sensitivity and specification requirements.
- Households:Individual and family-size formats purchased through retail channels for home consumption. Dual-income households in Bangalore and Beijing prioritize time savings over per-meal cost minimization.
- Food Service:Restaurants, cafeterias, and quick-service operators sourcing bulk-prepared components. Australia's FSANZ compliance requirements shape procurement specifications for imported ready-to-heat bases.
- Retail:Private-label and branded products stocked for consumer self-selection. Convenience-store network densification in Taiwan and South Korea creates impulse-purchase touchpoints for single-serve formats.
- Catering Services:Event and institutional feeding operations requiring scalable portion consistency. Corporate catering in Singapore and Hong Kong demands allergen-labeled tray formats for liability management.
Households command the largest value pool, though food service is expanding most quickly as restaurant labor costs climb across the region.
Packaging Type:
Volume throughput and shelf-life extension requirements determine material selection, with regulatory labeling mandates forcing format-specific compliance investments.
- Tray:Rigid plastic or aluminum containers for multi-component meals with segregated compartments. Japan's Consumer Affairs Agency allergen disclosure rules favor transparent tray lids enabling visual component identification.
- Pouch:Flexible laminated films for soups, curries, and sauced proteins. Retort pouch adoption accelerates in Thailand's manufacturing corridor for export-oriented shelf-stable production.
- Box:Paperboard cartons for premium positioning and sustainability signaling. South Korean convenience stores deploy boxed bento formats for differentiated shelf presentation.
- Can:Metal containers for longest ambient shelf life in disaster stockpiling and military logistics. Indonesia's archipelago distribution favors canned formats for tropical climate resilience.
Tray formats retain the dominant position, while pouch packaging is gaining share fastest through retort technology cost reduction.
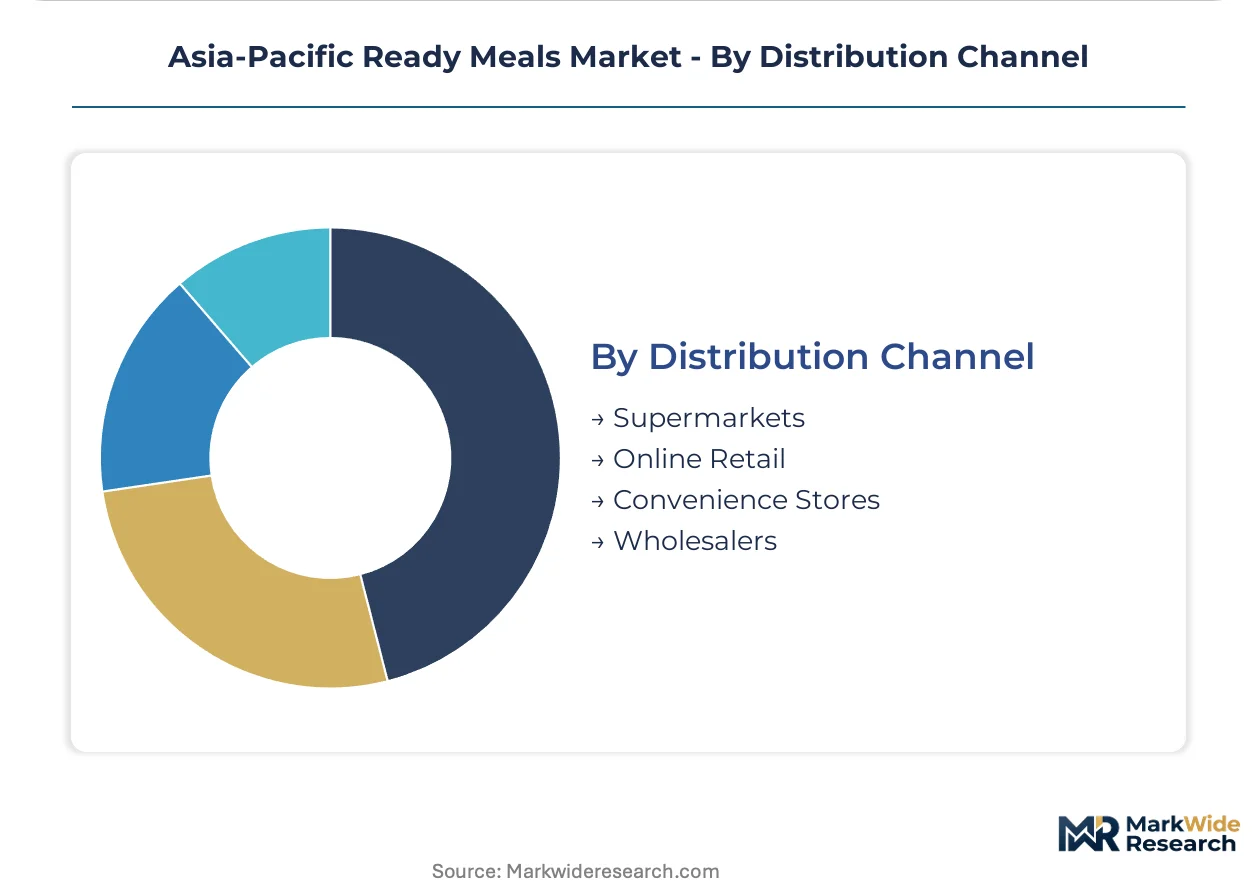
Distribution Channel:
Customer type and purchase occasion fragmentation requires parallel channel strategies, with cold-chain reliability determining viable format mixes per route.
- Supermarkets:Full-format retail with frozen, chilled, and ambient sections enabling complete category browsing. Australia's Coles and Woolworths chains enforce FSANZ-compliant nutrition panel standards for shelf placement.
- Online Retail:Direct-to-consumer platforms with cold-chain delivery promises. China's SAMR food-safety audit requirements determine platform eligibility for chilled meal vendors.
- Convenience Stores:24-hour urban outlets prioritizing immediate consumption and impulse purchase. South Korea's CU and GS25 networks create dedicated chilled meal sections for single professionals.
- Wholesalers:Bulk distribution to food service, catering, and institutional buyers. India's tier-2 urban corridors in Pune and Hyderabad remain underdeveloped for chilled format wholesale penetration.
Supermarkets anchor the largest volume flow, though online retail is climbing the fastest as cold-chain logistics mature in urban China.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across the Asia-Pacific ready meals landscape. Japanese households favor premium frozen bento formats with component-level transparency, while Indian consumers prioritize shelf-stable retort pouches for tropical storage resilience. Australia's FSANZ-mandated nutrition panels create export compliance gateways that reshape formulation priorities for regional manufacturers.
Japan
Tokyo and Osaka dual-income households drive demand for single-serve frozen rice and noodle combinations with sub-5-minute preparation. METI food labeling standards enforce allergen disclosure at the ingredient-component level, compelling reformulation of multi-layer tray meals. The Kanto manufacturing corridor around Chiba Prefecture hosts concentrated blast-freezing infrastructure serving premium convenience-store networks.
China
Shanghai and Beijing young professionals subscribe to chilled meal delivery platforms as apartment freezer ownership remains below 40% in dense urban cores. SAMR food-safety audit escalation determines market-access eligibility for both domestic and imported brands. The Yangtze River Delta cold-chain logistics hub enables same-day chilled distribution to apartment complexes across Suzhou and Hangzhou.
South Korea
Seoul Capital Area convenience-store densification creates 24-hour impulse-purchase touchpoints for single-serve formats targeting solo-dwelling professionals. MFDS nutrition labeling requirements shape product development priorities for export-oriented manufacturers. The Busan-Ulsan manufacturing belt supplies retort-pouch production capacity for both domestic consumption and regional export.
Australia
Sydney and Melbourne households demonstrate highest per-capita frozen meal consumption in the region, driven by dual-income time compression and established retail cold-chain penetration. FSANZ nutrition panel disclosure mandates determine shelf-placement eligibility for Coles and Woolworths chains. Queensland's food processing corridor concentrates private-label manufacturing for supermarket ready-meal ranges.
India
Mumbai and Delhi-NCR urban households adopt shelf-stable and dried meal formats as cold-chain infrastructure remains fragmented outside tier-1 metros. FSSAI packaging and labeling regulations create compliance thresholds that filter smaller domestic manufacturers from organized retail channels. Pune and Hyderabad tier-2 corridors remain underdeveloped for chilled format penetration despite latent demand potential.
Asia-Pacific Ready Meals Market Competitive Environment
Capability concentration sits with mid-tier specialists possessing captive umami technology and backward integration into vegetable sourcing; scale advantage sits with diversified food conglomerates leveraging cross-category distribution infrastructure. The vendor base organizes around three strategic archetypes: Japanese precision-format specialists, Korean convenience-channel anchors, and diversified multinational nutrition platforms. Competitive moves center on cold-chain partnership densification and regulatory compliance infrastructure acquisition to secure cross-border market access.
Among Japanese specialists, Ajinomoto Co., Inc. and Nichirei Foods Inc. exemplify the capability-driven tier through their positions in premium frozen format development. CJ CheilJedang Corporation represents the Korean convenience-channel archetype with captive distribution networks. Nestlé SA anchors the diversified multinational tier with cross-regional nutrition platform scale.
| Leading Market Players |
|---|
| Nestlé SA |
| Ajinomoto Co., Inc. |
| McCain Foods Ltd |
| Conagra Brands Inc. |
| Nichirei Foods Inc. |
| CJ CheilJedang Corporation |
| Ting Hsin International Group |
| ITC Limited |
| MTR Foods Pvt Ltd |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on Thailand's retort-pouch manufacturing corridor compresses margin predictability for Southeast Asian exporters while simultaneously widening price spreads between premium Japanese frozen formats and economy-grade Indian shelf-stable products. Wheat and rice commodity volatility feeds directly into formulation cost structures, forcing tiered pricing adjustments that track cold-chain infrastructure maturity rather than brand equity alone.
Pricing Analysis
Japanese premium frozen bento formats command three-to-four-fold premiums over Indian retort-pouch equivalents, with price spreads widening where METI-compliant allergen labeling adds compliance overhead. Three-tier pricing structure across premium, standard, and economy levels reflects cold-chain reliability gradients rather than ingredient quality alone. Pricing pressure stems from input cost volatility in grain and protein inputs, compressing margins for mid-tier noodle and rice-based tray producers. Food service procurement teams exhibit highest price sensitivity due to volume scale and specification standardization, while convenience-store impulse purchasers show lowest sensitivity for single-serve premium formats.
Supply Chain Analysis
Tariff exposure between Australia and Southeast Asian manufacturing hubs dominates supply chain risk calculus for export-oriented producers seeking FSANZ compliance. Production gravity centers on Thailand's retort-pouch corridor, Japan's Chiba Prefecture blast-freezing cluster, and South Korea's Busan-Ulsan manufacturing belt. Raw material dependencies include Australian wheat for noodle formulations, Thai jasmine rice for premium positioning, and domestic vegetable sourcing for Japanese umami-based recipes. Single-source vulnerability concentrates in modified atmosphere packaging film supply. Distribution runs through convenience-store network densification in Seoul and Tokyo, with online retail platforms capturing fastest channel expansion in urban China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into blast-freezing infrastructure and captive vegetable sourcing represents the scarce capability that separates margin leaders from commodity competitors in this market. Manufacturers lacking cold-chain partnership density face structural exclusion from premium tier positioning.
For Market Incumbents: Pre-empt meal-kit unbundling disruption in urban China by piloting hybrid formats that bridge heat-and-eat convenience with limited assembly involvement. Deepen backward integration into domestic vegetable sourcing to secure texture parity against Ajinomoto and Nichirei umami technology platforms. Defend convenience-store shelf presence in South Korea and Taiwan through exclusive chilled format development partnerships. For New Entrants and Emerging Players: Pursue tier-2 Indian urban corridors in Pune, Hyderabad, and Chennai where cold-chain penetration lags latent demand for chilled meal formats. Target shelf-stable retort-pouch white space in Indonesia's archipelago logistics environment where ambient storage resilience outweighs premium positioning. Anchor go-to-market strategy through direct-to-consumer subscription models leveraging time-temperature indicator packaging to compress quality-risk premiums. For Investors and Strategic Acquirers: The market sits at an infrastructure buildout phase that favors mid-tier specialists with captive compliance infrastructure over diversified conglomerates lacking regional regulatory depth. Long-term viability hinges on acquisition targets possessing parallel formulation databases for Japan's Consumer Affairs Agency and Australia's FSANZ requirements. Watch cold-chain logistics partnership announcements in India's tier-2 corridors as the signal indicating inflection toward chilled format penetration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Blast-Freezing Infrastructure | Captive freezing capacity enables texture parity with Nichirei and Ajinomoto premium formats. |
| Dual-Label Compliance Database Investment | Parallel METI and FSANZ formulation tracking secures cross-border market access eligibility. |
| Time-Temperature Indicator Packaging Pilot | Self-monitoring meal trays compress quality-risk premiums for direct-to-consumer subscription models. |
| Tier-2 Cold-Chain Partnership Densification | Last-mile refrigeration agreements in Pune and Chennai unlock latent chilled meal demand. |
| Convenience-Store Exclusive Format Development | Dedicated chilled sections in CU and GS25 networks create impulse-purchase capture points. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade records, and retail audit databases. Interviews with cold-chain logistics operators, convenience-store category buyers, ready-meal formulation scientists, and food-safety compliance officers anchored demand-side validation. Secondary sources included Japan's Consumer Affairs Agency allergen disclosure amendments, Australia's FSANZ nutrition panel standards, China's SAMR food-safety audit protocols, and Nielsen retail audit data across Shanghai, Tokyo, and Bangalore. Bottom-up channel volume estimates triangulated against top-down macro consumption indicators.
Forecast inputs span preservation technology adoption curves, cold-chain infrastructure deployment timelines, and regulatory amendment trajectories across the analysis window. Segmentation dimensions modeled include product type, end-user category, packaging format, and distribution channel, with additional granularity on urban density tiers and freezer ownership rates. CAGRs derived from regression against historical consumption patterns and infrastructure investment pipelines. Industry-specific inputs incorporate blast-freezing equipment cost curves and modified atmosphere packaging technology diffusion rates.
Sensitivities concentrate around SAMR audit escalation timelines, wheat and rice commodity price trajectories, and cold-chain partnership formation velocity in India's tier-2 corridors. Forecasts reflect assumptions on regulatory harmonization friction and infrastructure investment continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
North America Pasta and Noodles Market
Packaged Foods
Instant Rice Market
Packaged Foods
High-End Instant Noodles Market
Packaged Foods
Reduced Fat Packaged Food Market
Packaged Foods
Eco Bowls Market
Packaged Foods
North America Breakfast Cereals Market
Packaged Foods
North America Pasta Market
Packaged Foods
Cookie Butter Spread Market
Packaged Foods
North America Instant Noodles Market
Packaged Foods
Canned Fruits Market
Packaged Foods
Ready to Use Fillings Market
Packaged Foods
Canned Tropical Fruit Market
Packaged Foods
Europe Food Spread Market
Packaged Foods
Packaged Rice Market
Packaged Foods
United Arab Emirates Food Products Market
Packaged Foods
Morning Goods Market