
 Packaged Vegan Foods Market | 2026-2036
Packaged Vegan Foods Market Size, Share, and Industry Trends Forecast 2026-2036
Packaged Vegan Foods Market Outlook
European oat milk producers is repositioning capacity toward barista-grade formulations and ambient-stable cartons. Danone S.A. leverages its fermentation infrastructure to sustain dairy-alternative output across multiple continents. Beyond Meat, Inc. anchors its production footprint in domestic facilities with tight quality controls. Nestle S.A. competes through scaled ready-meal portfolios that integrate plant proteins into familiar formats.
Packaged vegan foods are commercially prepared plant-based products formulated without animal-derived ingredients, typically requiring controlled thermal processing, pH management, and modified-atmosphere packaging to achieve shelf stability and sensory parity with conventional equivalents. These products serve retail and foodservice channels seeking standardized, scalable alternatives to animal-based staples. Dairy alternatives currently lead volume contribution within product type segmentation, while meat substitutes represent the fastest-expanding margin pool as extrusion and fermentation technologies mature. Online retail channels are gaining structural share against supermarkets among younger demographics, though specialty stores still control premium-tier discovery and trial conversion.
The FDA governs allergen labeling and GRAS determinations for novel plant proteins in the United States, while the EFSA evaluates protein quality claims and additive approvals across European markets. REACH compliance shapes ingredient sourcing for emulsifiers and texturizers used in European-manufactured vegan products. Stakeholders must monitor evolving protein-quality scoring methodologies and front-of-pack labeling mandates that could recalibrate formulation priorities and regional competitiveness.
Market Dynamics
Retail shelf reallocation toward dedicated plant-based refrigerated sections is compressing product discovery timelines and forcing manufacturers to achieve sensory parity faster than historical norms.
Growth Catalysts
- EU Green Deal farm-to-fork targets:Sustainability mandates tighten ingredient sourcing requirements, creating compliant supply advantages for early-adopting European producers.
- Barista-grade oat milk formulations:Specialty coffee chains drive premium positioning for high-foam-stability dairy alternatives, expanding addressable occasions beyond home consumption.
- German discounter private-label expansion:Dedicated vegan lines at Aldi and Lidl normalize plant-based staples through aggressive price positioning and ubiquitous distribution.
Market Restraints
- Protein input cost volatility:Pea and fava bean isolate prices fluctuate with agricultural yields, compressing margin stability for extruded meat substitutes.
- Extrusion equipment supply concentration:High-shear texturization machinery relies on a limited supplier base in Germany and Italy, creating capacity bottlenecks during demand surges.
- EFSA novel protein approval timelines:Microbial fermentation-derived ingredients face extended safety evaluation periods, delaying commercialization of next-generation alternatives.
Strategic Opportunities
- Foodservice direct distribution:Bypassing retail markup through institutional contracts with university and corporate cafeteria operators unlocks volume scale at lower customer acquisition cost.
- Modified-atmosphere packaging convergence with active barrier films:Extended ambient shelf life without refrigeration opens convenience-store and vending-machine channels previously closed to fresh vegan products.
- REACH-compliant emulsifier localization:European producers who backward-integrate into domestic texturizer manufacturing reduce import dependency and accelerate formulation iteration cycles.
Industry Challenges
- Cross-contamination protocol certification:Third-party vegan verification audits require dedicated production lines, inflating capital requirements for multi-product facilities.
- Sensory scientist talent scarcity:Formulation expertise spanning protein chemistry, flavor masking, and texture engineering concentrates at a handful of research institutions in the Netherlands and Denmark.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaged Vegan Foods Market |
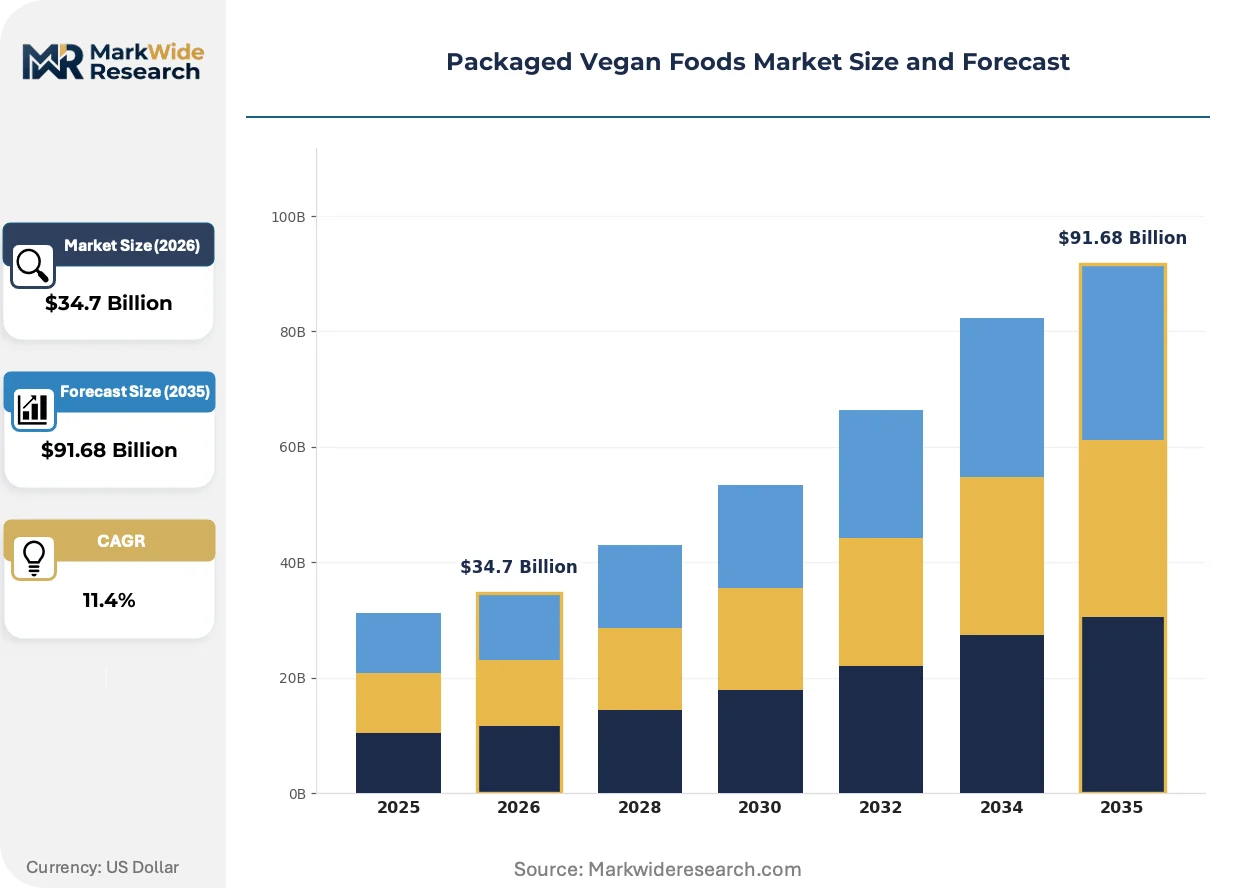
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $91.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Snacks, Dairy Alternatives, Meat Substitutes, Sauces End User: Individuals, Restaurants, Food Trucks, Retail Stores Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Health Food Shops Price Tier: Premium, Mid-Range, Budget, Discount |
| Companies Covered | Oatly Group AB, Amy's Kitchen Inc., Danone S.A., Nestle S.A., Tofutti Brands Inc., Beyond Meat, Inc., Kellanova, Maple Leaf Foods Inc., Impossible Foods Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaged Vegan Foods Market Strategic Shifts
Precision fermentation and advanced extrusion systems are collapsing the cost-performance gap between plant-based and conventional proteins, while regulatory clarity around novel ingredients accelerates commercialization timelines.
Precision fermentation of whey and casein proteins without animal agriculture is electrifying the dairy-alternative segment. Specialty ingredient buyers at premium ice cream and cheese manufacturers are integrating these recombinant proteins into hybrid formulations. This technology is compressing the premium tier's price elasticity, enabling parity positioning against conventional dairy in foodservice applications.
EFSA's evolving protein-quality scoring methodology is recalibrating formulation priorities across European manufacturers. The shift from single-metric evaluation to digestible indispensable amino acid scores favors multi-source protein blends over isolated soy or pea bases. Ready-meal producers in Germany and France are reformulating portfolios to achieve favorable front-of-pack ratings ahead of anticipated mandatory labeling expansions.
Direct-to-consumer subscription models for refrigerated vegan meal kits are displacing traditional supermarket trial among urban millennials. Specialty e-commerce platforms capture recurring revenue through personalized nutrition algorithms while specialty stores retain premium discovery functions. This bifurcation is most visible in London and Stockholm, where delivery density supports cold-chain economics unavailable in secondary cities.
Packaged Vegan Foods Market Segmentation
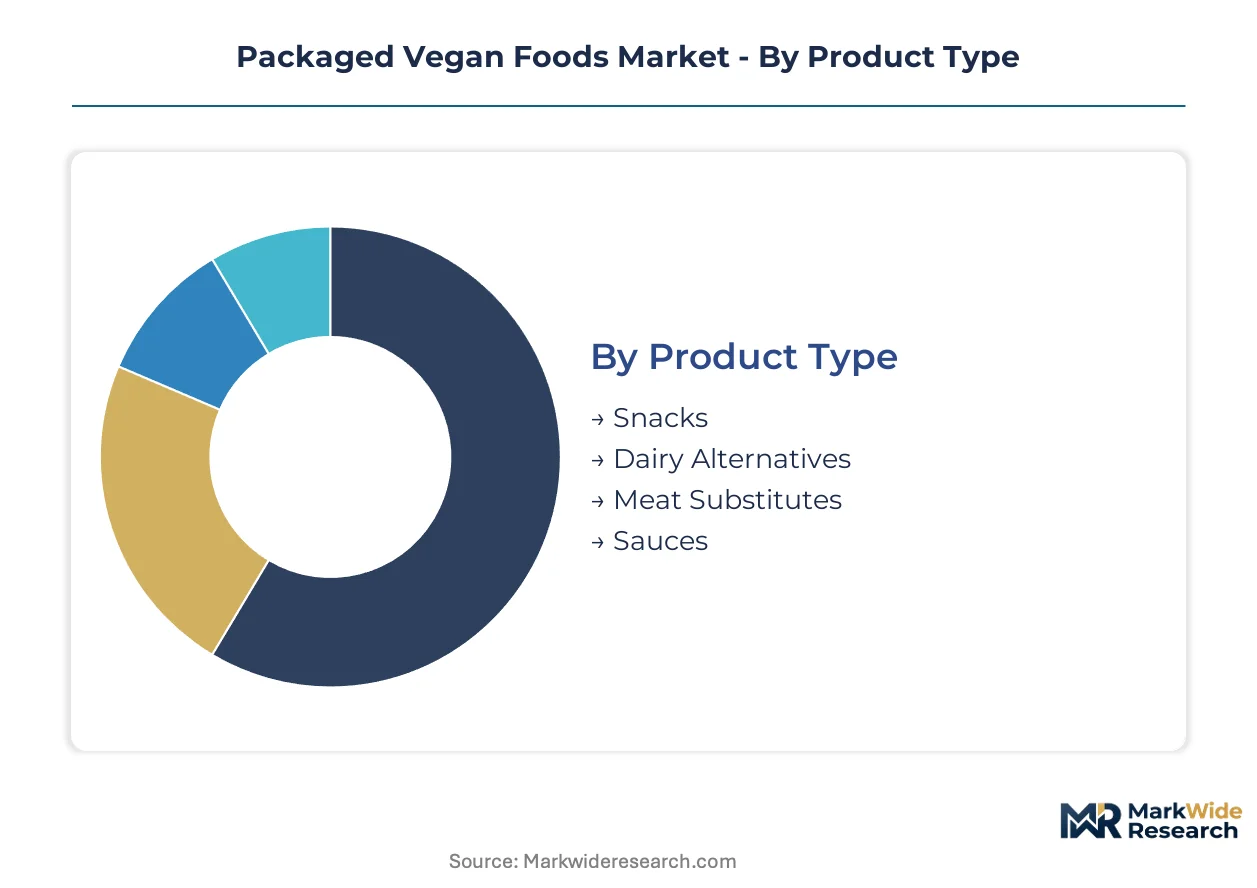
Segmentation in packaged vegan foods reveals how formulation complexity, channel economics, and certification requirements create distinct competitive arenas. Manufacturers must align R&D investment and packaging formats to the specific thermal stability and shelf-life demands of each product category.
Product Type:
Standalone packaged formats dominate refrigerated retail placement, while ingredient-system segments embed into foodservice and CPG manufacturing workflows with different margin profiles.
- Snacks:Shelf-stable formulations combining extruded proteins, legume flours, and oil-based coatings achieve ambient distribution without cold-chain dependency. German discounters and US convenience chains are expanding facings for puffed protein crisps and seitan jerky as impulse purchase drivers near checkout zones.
- Dairy Alternatives:Oat, almond, and soy-based milks, yogurts, and creams require UHT processing or refrigerated cold-chain logistics depending on pH and water activity targets. Barista-grade oat milk with specific foam-stability proteins commands placement in specialty coffee chains across Sweden and the United Kingdom, displacing conventional dairy in espresso-based beverages.
- Meat Substitutes:Extruded and fermented proteins with myofibrillar texture emulation.
- Sauces:Emulsified dressings and condiments using aquafaba or modified starches for viscosity.
Dairy alternatives lead volumes today; meat substitutes are gaining share fastest.
End User:
Customer archetypes span direct consumption through institutional procurement, with divergent requirements for portion sizing, nutritional labeling, and delivery frequency.
- Individuals:Single-serve and family-format retail packaging designed for home preparation with clear allergen callouts and reheating instructions. Subscription meal-kit platforms in London and Stockholm capture recurring revenue through personalized nutrition algorithms while displacing traditional supermarket trial.
- Restaurants:Bulk frozen formats with consistent cook yields and cross-contamination protocols for vegan menu certification. University and corporate cafeteria operators in the United States are negotiating direct distribution contracts to bypass retail markup and achieve volume scale.
- Food Trucks:Ambient-stable pouches and individually wrapped portions for limited refrigeration capacity.
- Retail Stores:Private-label and branded SKUs arranged for shelf-space optimization and turnover velocity.
Individuals dominate current offtake; restaurants show the steepest expansion trajectory.
Distribution Channel:
Channel selection determines packaging format, margin retention, and the speed of sensory feedback loops for formulation iteration.
- Online Retail:Direct-to-consumer platforms with cold-chain logistics and subscription mechanics. Urban millennial demand clusters in metropolitan delivery zones where density supports refrigerated last-mile economics unavailable in secondary cities.
- Supermarkets:Mass-market placement requiring modified-atmosphere packaging and competitive shelf-life positioning.
- Specialty Stores:Curated discovery environments with premium-tier positioning and staff-assisted trial conversion.
- Health Food Shops:Certified organic and clean-label focused outlets with educated consumer bases.
Supermarkets anchor volume today; online retail is climbing the fastest.
Price Tier:
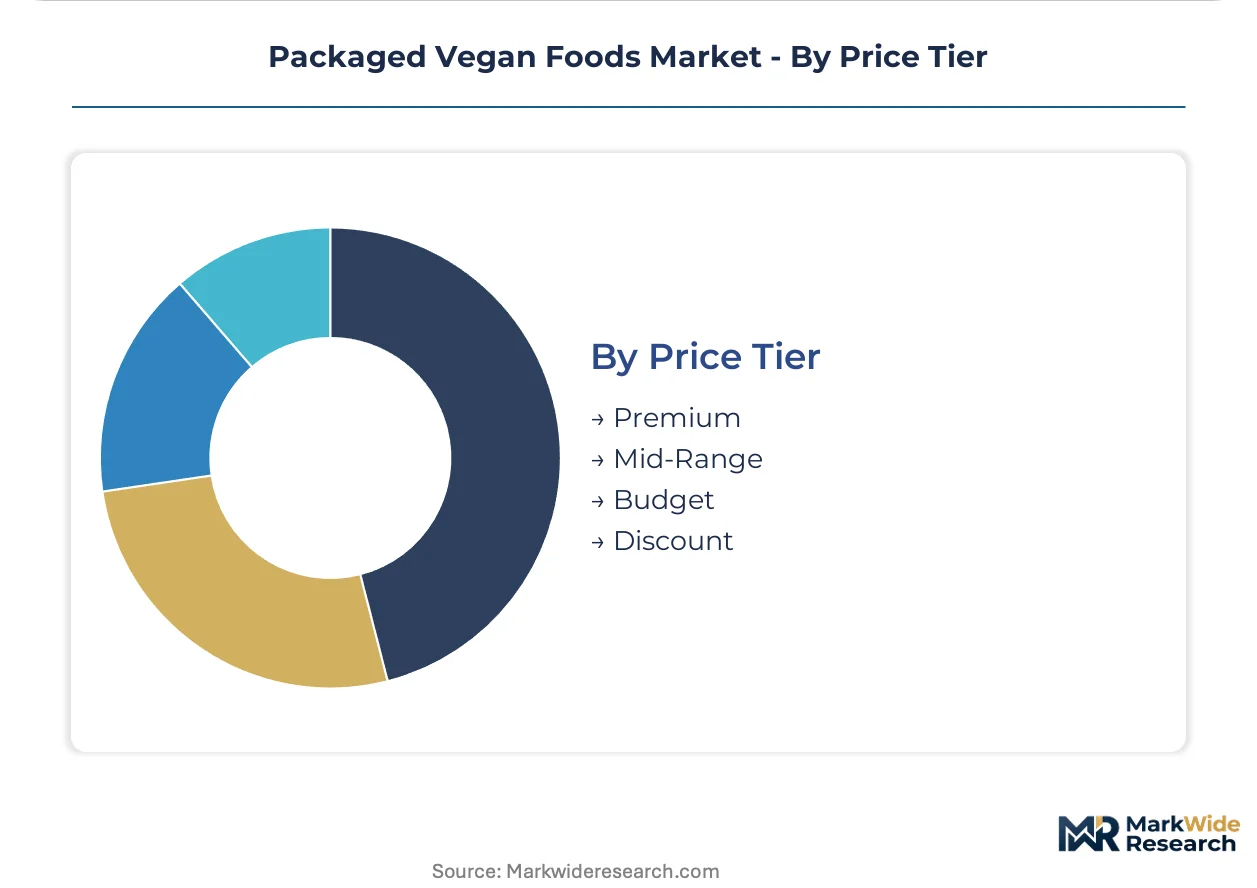
Cost positioning correlates with ingredient provenance, certification depth, and the capital intensity of dedicated production lines.
- Premium:Organic-certified, single-origin protein bases with third-party vegan verification and carbon-neutral claims. Precision fermentation-derived recombinant proteins in hybrid ice cream formulations compress price elasticity at the top tier.
- Mid-Range:Mainstream plant proteins with conventional emulsifiers and standard packaging formats.
- Budget:Private-label offerings at Aldi and Lidl in Germany normalizing plant-based staples through aggressive price positioning.
- Discount:Value-oriented formats with minimal processing and bulk sizing for price-sensitive volume buyers.
Budget tier leads unit volumes today; premium tier expands value contribution fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production geography as European sustainability mandates tighten faster than North American compliance costs, drawing fermentation capacity toward jurisdictions with clearer novel-protein approval pathways. Manufacturers migrate toward markets where REACH-compliant ingredient sourcing and EFSA protein-quality scoring create first-mover advantages in formulation flexibility.
Germany
Aldi and Lidl discounters drive private-label vegan line expansion through aggressive price positioning and ubiquitous distribution networks. The EU Green Deal's farm-to-fork sustainability targets tighten ingredient sourcing requirements, favoring domestic producers with compliant supply chains. Berlin and Hamburg anchor industrial clusters where oat milk producers reposition capacity toward barista-grade formulations and ambient-stable cartons.
United States
University and corporate cafeteria operators negotiate direct distribution contracts to bypass retail markup and achieve volume scale. FDA allergen labeling and GRAS determinations for novel plant proteins govern domestic commercialization timelines. Domestic facilities with tight quality controls anchor meat substitute production footprints, particularly in California and Illinois food manufacturing corridors.
Sweden
Specialty coffee chains across Stockholm and Gothenburg drive premium positioning for high-foam-stability dairy alternatives, expanding addressable occasions beyond home consumption. EFSA protein-quality scoring methodology shifts favor multi-source protein blends over isolated soy bases. Urban millennial demand clusters in metropolitan delivery zones where cold-chain economics support direct-to-consumer subscription models.
United Kingdom
London and Manchester delivery density supports cold-chain economics for refrigerated vegan meal kits unavailable in secondary cities. REACH compliance shapes ingredient sourcing for emulsifiers and texturizers used in domestic manufacturing. Specialty e-commerce platforms capture recurring revenue through personalized nutrition algorithms while specialty stores retain premium discovery functions.
Netherlands
Sensory scientist expertise spanning protein chemistry, flavor masking, and texture engineering concentrates at Wageningen research institutions, creating talent scarcity for multinational recruiters. EFSA additive approvals and evolving front-of-pack labeling mandates recalibrate formulation priorities for ready-meal producers. Rotterdam and Amsterdam logistics hubs facilitate modified-atmosphere packaging convergence with active barrier films for extended ambient shelf life.
Packaged Vegan Foods Market Competitive Environment
European producers anchor one tier through fermentation infrastructure and REACH-compliant supply chains; North American specialists hold another through scaled ready-meal portfolios and domestic quality-controlled facilities. The vendor base stratifies across three strategic archetypes: diversified food conglomerates leveraging existing distribution, pure-play plant-based innovators concentrating R&D spend, and private-label suppliers serving discounter channels. Dominant competitive moves include backward integration into domestic texturizer manufacturing and strategic partnerships with specialty coffee chains for barista-grade formulation placement.
Among diversified conglomerates, Danone S.A. and Nestle S.A. exemplify archetypes leveraging existing fermentation infrastructure and scaled ready-meal portfolios respectively. Beyond Meat, Inc. occupies a position within the pure-play innovation tier, representing domestic quality-controlled production footprints. These three entities illustrate how geographic origin and corporate structure shape competitive positioning without dictating specific strategic actions or market share claims.
| Leading Market Players |
|---|
| Oatly Group AB |
| Amy's Kitchen Inc. |
| Danone S.A. |
| Nestle S.A. |
| Tofutti Brands Inc. |
| Beyond Meat, Inc. |
| Kellanova |
| Maple Leaf Foods Inc. |
| Impossible Foods Inc. |
| Others |
Value Chain & Pricing Dynamics
The EU Green Deal's farm-to-fork sustainability targets gate qualified ingredient supply and premium-tier pricing access, forcing manufacturers to absorb compliance costs or surrender margin to discounters with compliant private-label networks.
Pricing Analysis
Retailer markup compression in German discounter channels is reshaping margin structures across the industry. Three-tier pricing structure across premium, standard, and economy levels separates precision fermentation-derived formulations from conventional extruded proteins and private-label staples. Pricing pressure stems from pea and fava bean isolate volatility, which squeezes mid-range meat substitute margins. Foodservice buyers exhibit lowest price sensitivity due to menu-premiumization potential, while budget-tier retail consumers drive aggressive sourcing negotiations.
Supply Chain Analysis
Domestic-content mandates under REACH compliance are reshaping European sourcing patterns for emulsifiers and texturizers. Manufacturing concentrates in Germany, Italy, and the Netherlands, with extrusion equipment supply anchored in German and Italian machinery specialists. Raw material dependencies include Nordic oat supplies, Canadian pea protein isolates, and Southeast Asian coconut derivatives. Single-source vulnerability in high-shear texturization machinery creates capacity bottlenecks during demand surges. Distribution runs through refrigerated logistics networks for fresh formats and ambient-stable channels for shelf-stable alternatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Packaged Vegan Foods Market operates as a regulatory compounder where EFSA protein-quality scoring methodology and front-of-pack labeling mandates are accelerating formulation investments and recalibrating competitive positioning.
For Market Incumbents: Deepen backward integration into domestic texturizer manufacturing to reduce REACH import dependency and accelerate iteration cycles. Incubate dedicated production lines for third-party vegan verification audits, insulating against cross-contamination protocol certification requirements that inflate capital requirements for multi-product facilities.
For New Entrants and Emerging Players: Begin with foodservice direct distribution contracts to university and corporate cafeteria operators, bypassing retail markup layers and capturing volume scale at lower customer acquisition cost. Target modified-atmosphere packaging convergence with active barrier films, opening convenience-store and vending-machine channels previously closed to fresh vegan products.
For Investors and Strategic Acquirers: Roll-up economics work for regional specialty ingredient platforms because EFSA novel protein approval timelines create extended moats for early-compliant domestic producers. Five-to-ten year viability favors fermentation infrastructure owners with REACH-compliant supply chains. Monitor EFSA additive approval velocity as the inflection signal for next-generation alternative commercialization.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Texturizer Manufacturing | REACH-compliant domestic sourcing reduces formulation iteration cycles for European producers. |
| Barista-Grade Formulation Partnerships | Specialty coffee chain placement in Sweden and the United Kingdom expands occasion-based consumption. |
| Modified-Atmosphere Packaging Convergence | Active barrier films unlock ambient distribution through convenience and vending channels. |
| Direct-to-Foodservice Distribution | Institutional contracts with US university and corporate cafeteria operators bypass retail markup layers. |
| Precision Fermentation Capacity Expansion | Recombinant protein production compresses premium-tier price elasticity against conventional dairy. |
Study Parameters
Direct dialogue with plant protein procurement directors, sensory science leads at research institutions, refrigerated logistics operators, and private-label category managers at German discounters grounded the qualitative foundation. Secondary validation drew from EFSA additive approval databases, EU Green Deal implementation trackers, customs records for pea and oat trade flows, and Nielsen retail audit data for plant-based shelf-space allocation. Bottom-up volume modeling triangulated against top-down macroeconomic scenario analysis.
Segment-level projections across product type, end user, distribution channel, and price tier dimensions fed into analytical framework outputs across the modeling period. CAGRs emerged from regression analysis against protein input cost indices and regulatory approval velocity metrics. Forecast inputs included EFSA protein-quality scoring adoption timelines and cold-chain logistics density thresholds for subscription model viability.
Several conditions sit outside the modeled scope, including unannounced novel protein safety evaluations, abrupt tariff shifts on legume imports, and breakthroughs in cell-cultured protein cost parity. Forecasts reflect documented assumptions about regulatory stability and agricultural yield patterns. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Air-Dried Food Market
Packaged Foods
Freekeh Market
Packaged Foods
North America Packaged Salad Market
Packaged Foods
Chewing Gum Market
Packaged Foods
Alginate Casings Market
Packaged Foods
Global Packed Food Market
Packaged Foods
Packaged Salad Market
Packaged Foods
Packaged Currants Market
Packaged Foods
Asia-Pacific Breakfast Cereals Market
Packaged Foods
Instant Rice Market
Packaged Foods
Burritos Market
Packaged Foods
South America Breakfast Cereals Market
Packaged Foods
Morning Goods Market
Packaged Foods
Cookie Pucks Market
Packaged Foods
Packaged Food Market
Packaged Foods
North America Pasta Market