
 United Kingdom Fruits and Vegetables Market | 2026-2036
United Kingdom Fruits and Vegetables Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Fruits and Vegetables Market Analytics
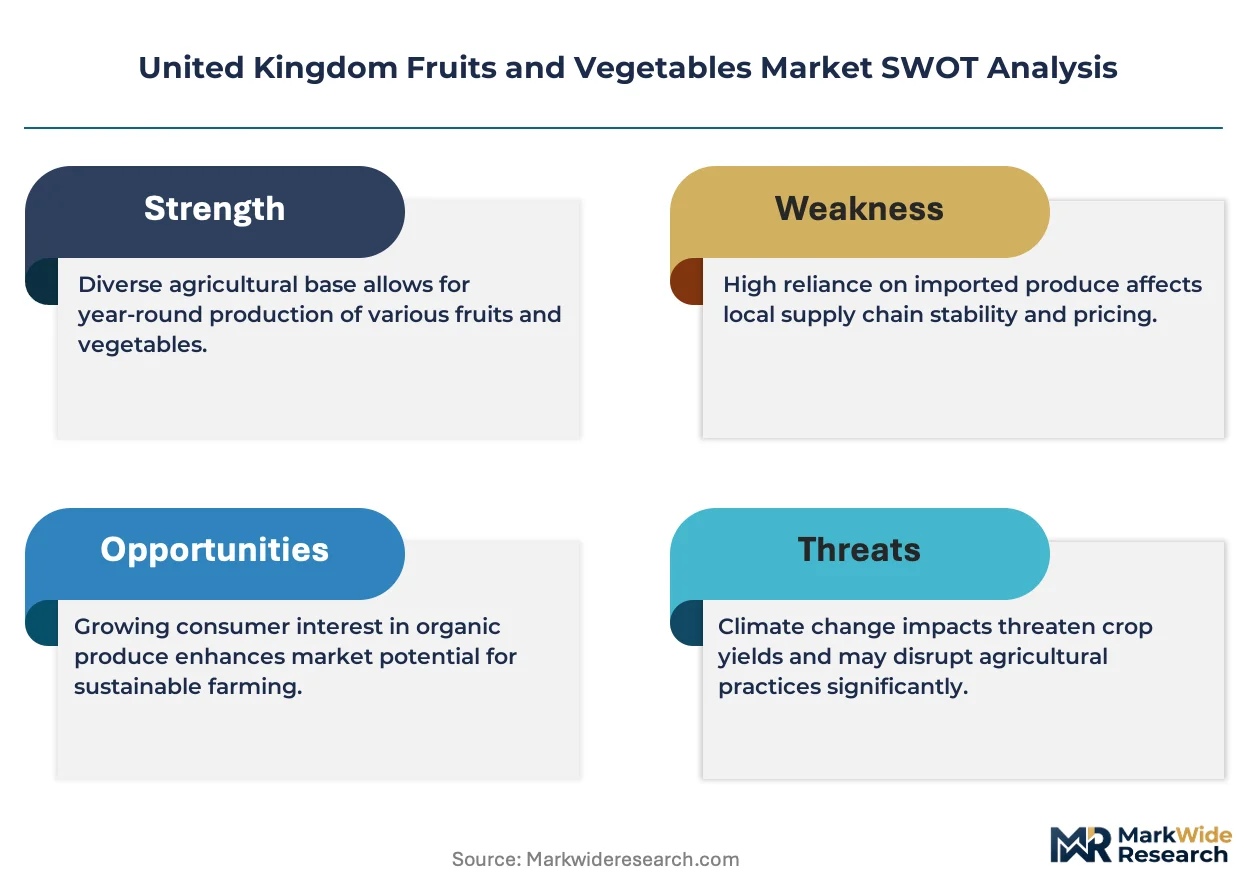
The gap between premium organic lines and commodity-grade produce is repositioning procurement strategies across British retail. Riverford Organic Farmers Ltd leverages its Devon-based grower network to sustain direct-to-consumer subscription volumes. A1 Veg Ltd anchors wholesale supply into London's restaurant and hotel sector through its New Covent Garden Market stall operation. Cains Farm differentiates via heritage variety specialization, commanding shelf-space premiums in Waitrose and Booths.
United Kingdom fruits and vegetables encompass fresh, minimally processed edible plant matter sold through commercial channels for human consumption, with shelf-life parameters typically spanning three to fourteen days post-harvest depending on cultivar, cold-chain integrity, and respiration rate. The primary commercial purpose centers on delivering micronutrient-dense foodstuffs to retail and institutional buyers while meeting stringent phytosanitary and residue thresholds. Supermarkets dominate volume throughput, though margin pools are migrating toward Online Retail as Ocado and Amazon Fresh expand automated fulfillment infrastructure for perishables. Farmers Markets capture disproportionate value per kilogram from affluent urban cohorts seeking provenance transparency, while the Exporter end-user segment faces structural pressure from post-Brexit phytosanitary certification requirements into EU27 destinations.
Defra enforces the Agricultural Transition Plan, reshaping land-use incentives away from area-based payments toward environmental outcomes. The Food Standards Agency administers pesticide residue monitoring through its Official Control Laboratory network, with maximum residue limits aligning with retained EU Regulation 396/2005. Retailers must monitor how the Groceries Code Adjudicator's strengthened enforcement powers alter supplier payment terms, as delayed settlements strain working capital across smallholder cooperatives supplying supermarket own-label programs.
Market Dynamics
Defra's Agricultural Transition Plan is redirecting farm subsidies from area-based payments toward environmental land management, fundamentally altering grower economics across England's horticultural belt. This subsidy restructuring is compressing margins for conventional producers while rewarding regenerative practices, forcing rapid operational recalibration throughout the supply base.
Growth Catalysts
- Clean-label procurement mandates:Food service operators are expanding fresh produce volumes to meet menu commitments for minimally processed ingredients. London's restaurant and hotel sector drives premium sourcing.
- Glasshouse technology diffusion:LED supplemental lighting and hydroponic systems enable year-round tomato and leafy green production in Kent and Sussex clusters.
- Environmental Land Management schemes:Defra's new subsidy framework incentivizes cover cropping and reduced tillage, improving soil health metrics that retailers now audit.
Market Restraints
- Post-Brexit phytosanitary friction:Exporters face structural certification requirements and border inspection delays for EU27 destinations, compressing shelf-life windows.
- Energy input cost volatility:Glasshouse operators depend on natural gas for heating; price spikes directly erode winter production economics.
- Labour supply concentration:Seasonal worker schemes rely on approved operator licenses; processing bottlenecks constrain harvest timing flexibility.
Strategic Opportunities
- Subscription direct-to-consumer channels:Regional grower networks can bypass wholesale terminals through weekly box schemes targeting affluent urban cohorts.
- Heritage variety specialization:Niche cultivars command shelf-space premiums in premium retail banners seeking provenance differentiation.
- Automated perishable fulfillment:Ocado and Amazon Fresh infrastructure investments create new listing pathways for accredited suppliers meeting cold-chain protocols.
Industry Challenges
- Residue monitoring compliance:The Food Standards Agency's Official Control Laboratory network enforces retained EU Regulation 396/2005 limits; testing failures trigger immediate delisting.
- Payment term compression:The Groceries Code Adjudicator's strengthened enforcement powers alter supplier settlement schedules, straining working capital across smallholder cooperatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Fruits and Vegetables Market |
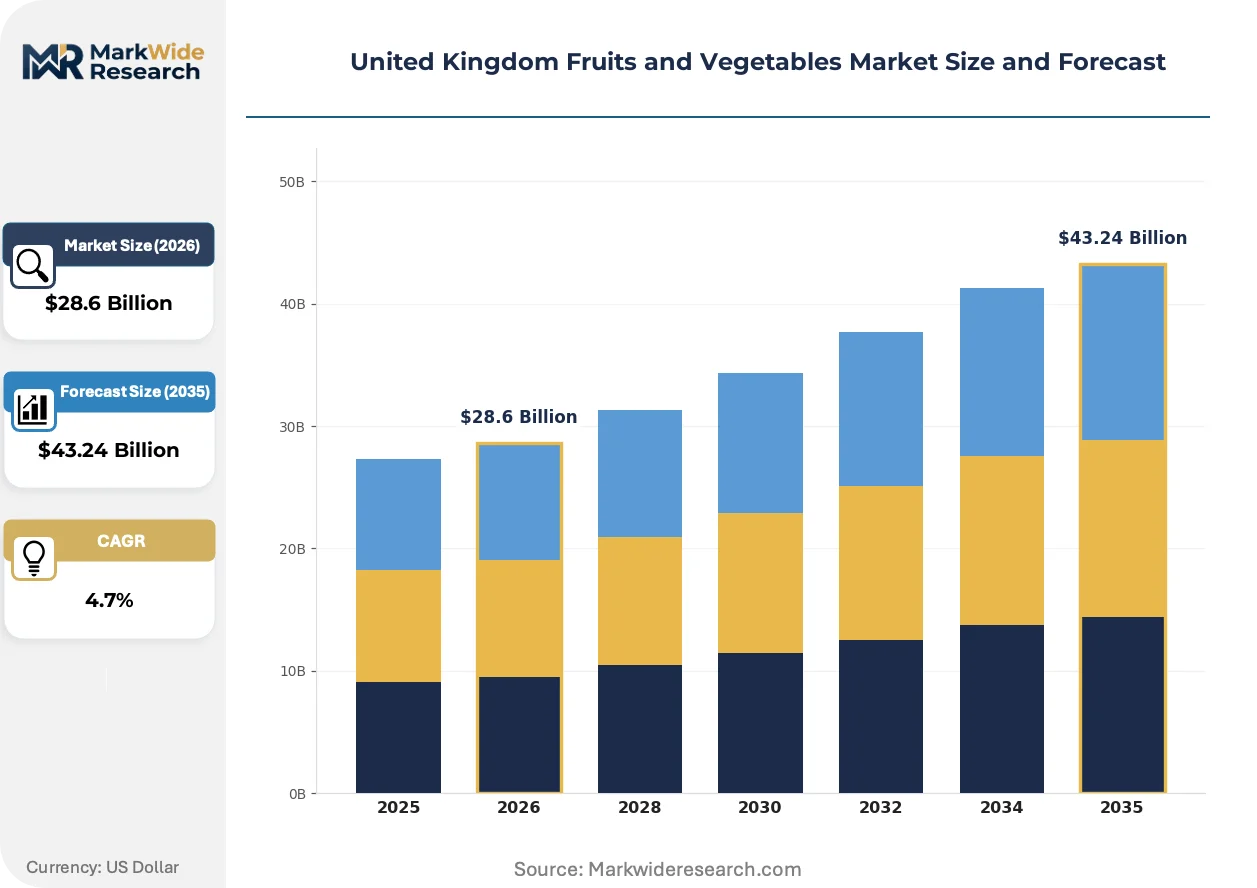
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.24 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Apples, Bananas, Carrots, Spinach Distribution Channel: Supermarkets, Wholesale, Farmers Markets, Online Retail End User: Households, Food Service, Retailers, Exporters Packaging Type: Bulk, Boxes, Baskets, Trays |
| Companies Covered | Riverford Organic Farmers Ltd, A1 Veg Ltd, Bus Station Fruiterers, Bidwalla Fruit & Veg Ltd, Cains Farm, C J B Fruit & Veg Wholesalers, Bitaal, Axton, A David & Co Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Fruits and Vegetables Market Evolving Landscape
Technological integration, regulatory tightening, and channel fragmentation are simultaneously reshaping how fresh produce moves from field to consumer. These forces are compressing traditional intermediaries while elevating traceability and automation requirements.
Controlled-environment agriculture is converging with renewable energy microgrids. Glasshouse operators in the Lea Valley are installing solar-plus-battery systems to buffer heating costs. This convergence is enabling 24-hour climate control independent of grid volatility, stabilizing winter production yields.
Defra's Agricultural Transition Plan mandates progressive subsidy reduction through 2027. Growers must document environmental outcomes to access replacement payments. The horticultural sector is responding through accelerated agroforestry adoption and precision irrigation investments to meet soil health metrics.
Urban consumers are consolidating purchases through rapid-delivery platforms. Amazon Fresh and Ocado's automated warehouses now capture margin pools that previously accrued to wholesale terminals. This channel rotation is most visible in Greater London, where same-day delivery slots command premium pricing for organic lines.
United Kingdom Fruits and Vegetables Market Segmentation
Segmentation in the United Kingdom fruits and vegetables market reveals how procurement priorities diverge across channel structures and end-use requirements. Understanding these divides exposes where margin pools concentrate and where operational complexity escalates.
Product Type:
Standalone produce categories command dedicated shelf-space negotiations, while bundled offerings integrate into private-label programs with stricter specification requirements.
- Apples:Cox and Braeburn cultivars dominate domestic procurement, with Kent and Herefordshire orchards supplying year-round cold-stored inventory. Waitrose and Tesco specifications on sugar-acid ratios filter supply base eligibility.
- Bananas:Cavendish imports from Costa Rica and Colombia move through ripening facilities at Portsmouth and Liverpool before distribution. Retailers audit ethylene management protocols to control shelf-life variance.
- Carrots:East Anglia's sandy loam belt produces 40% of national volume, with washing and grading operations concentrated near Peterborough.
- Spinach:Perpetual spinach and true spinach varieties cycle through rapid-turnover bagged salad programs, with shelf-life compression driving just-in-time harvest scheduling.
Volume placements concentrate in apples and bananas; the faster expansion belongs to spinach as bagged salad penetration deepens.
Distribution Channel:
Channel selection determines cold-chain investment intensity and margin capture potential, with direct-to-consumer models requiring fundamentally different logistics architecture than terminal-based distribution.
- Supermarkets:Tesco, Sainsbury's, and Morrisons operate consolidated national distribution centres with temperature-controlled cross-dock facilities. Own-label specifications on residue limits and cosmetic grading exclude smaller growers lacking certification capacity.
- Wholesale:New Covent Garden Market and Birmingham Wholesale Market aggregate supply from multiple countries for redistribution to independent retailers and restaurants. Early-morning auction dynamics set daily price benchmarks.
- Farmers Markets:Direct producer-to-consumer transactions at Marylebone, Borough, and regional weekend markets capture premium pricing through provenance storytelling.
- Online Retail:Ocado's automated warehouses and Amazon Fresh's rapid-delivery slots demand modified-atmosphere packaging and precise inventory positioning to prevent spoilage in automated picking environments.
Supermarkets absorb the largest volume throughput; online retail is climbing the fastest as automated fulfillment infrastructure scales.
End User:
End-user segmentation separates price-sensitive institutional procurement from specification-intensive retail programs, with each segment imposing distinct phytosanitary and traceability burdens.
- Households:Domestic consumption concentrates on convenience-oriented formats — pre-cut, washed, and bagged produce commanding per-kilogram premiums over loose alternatives.
- Food Service:London's restaurant and hotel sector sources through dedicated produce wholesalers, with clean-label menu commitments driving demand for heritage varieties and organic certification.
- Retailers:Supermarket buying offices negotiate annual contracts with fixed-volume commitments, transferring demand volatility risk upstream to grower cooperatives.
- Exporters:Post-Brexit phytosanitary certification requirements for EU27 destinations have compressed this segment's viability, with Rotterdam and Calais border inspections adding transit time.
Households generate the largest absolute demand; food service is gaining share fastest as out-of-home dining expenditure recovers.
Packaging Type:
Packaging configuration directly influences shelf-life extension, handling efficiency, and retail presentation requirements across the distribution chain.
- Bulk:Loose produce in returnable crates serves wholesale terminals and food service operators with rapid turnover, minimizing packaging cost but requiring immediate cold-chain insertion.
- Boxes:Standardised cardboard containers facilitate palletisation for supermarket distribution centre intake, with barcode traceability enabling lot-recall procedures.
- Baskets:Woven or plastic baskets support farmers market aesthetics and gift-oriented retail formats, though unit economics limit scale.
- Trays:Modified-atmosphere trays extend shelf-life for pre-cut salad lines and berry categories, with film permeability specifications calibrated to respiration rates.
Bulk and box formats handle the greatest tonnage; tray packaging shows the steepest expansion trajectory as value-added produce lines multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
London anchors United Kingdom fruits and vegetables distribution through its wholesale terminals and rapid-delivery infrastructure. The Southeast horticultural belt feeds this concentration with year-round glasshouse production. Regional variation across England, Scotland, Wales, and Northern Ireland reflects climate constraints, subsidy access, and channel specialization.
Southeast England
Food service procurement and premium retail sourcing concentrate demand in Kent and Sussex glasshouse clusters. Defra's Agricultural Transition Plan redirects area-based payments toward environmental land management, compressing conventional grower margins. LED supplemental lighting installations in Thanet Valley enable winter tomato production independent of Spanish import cycles.
East Anglia
Root vegetable volume production dominates sandy loam belts around Peterborough and Cambridgeshire. The Food Standards Agency's Official Control Laboratory network enforces retained EU Regulation 396/2005 residue limits across washing and grading facilities. Norfolk's carrot cooperatives supply supermarket own-label programs with fixed-volume annual contracts.
Scotland
Soft fruit cultivation concentrates in Tayside and Angus, with raspberry and strawberry harvests timed for English market windows. Seasonal worker scheme licensing bottlenecks constrain harvest flexibility across Perthshire farms. Aberdeenshire's potato sector supplies processing contracts for frozen chip lines.
Wales
Pembrokeshire early potato harvests command premium positioning before English maincrop availability. Welsh Government rural development programs supplement Defra payments for agroforestry adoption. Conwy Valley lettuce production serves North West England wholesale terminals through Holyhead port logistics.
West Midlands
Traditional market gardening persists in Worcestershire's Vale of Evesham, with asparagus and plum specialization. Birmingham Wholesale Market aggregates supply for independent retailers across the urban West Midlands conurbation. Heritage variety producers in Herefordshire supply Waitrose and Booths provenance-differentiated lines.
United Kingdom Fruits and Vegetables Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification and channel access dimensions. Supermarket own-label programs consolidate volume through accredited grower cooperatives, while independent wholesalers fragment across terminal auction dynamics. Three archetypes dominate: direct-to-consumer subscription networks, wholesale terminal stall operators, and heritage variety specialists. Competitive moves concentrate on backward integration into grower networks and automated fulfillment partnerships with online retail platforms.
Within the subscription network tier, Riverford Organic Farmers Ltd exemplifies Devon-based grower aggregation for weekly box schemes. A1 Veg Ltd occupies a position among New Covent Garden Market stall operators supplying London's restaurant and hotel sector. Cains Farm represents heritage variety specialization commanding shelf-space premiums in premium retail banners. These three entities anchor distinct margin pools without overlapping channel strategies.
| Leading Market Players |
|---|
| Riverford Organic Farmers Ltd |
| A1 Veg Ltd |
| Bus Station Fruiterers |
| Bidwalla Fruit & Veg Ltd |
| Cains Farm |
| C J B Fruit & Veg Wholesalers |
| Bitaal |
| Axton |
| A David & Co Ltd |
| Others |
Value Network & Pricing Analysis
Clean-label procurement mandates from London's restaurant and hotel sector are compressing supplier margins and forcing glasshouse operators toward LED-hydroponic systems to meet year-round volume commitments at fixed contract rates.
Pricing Analysis
Value-based pricing anchored to soil health metrics and environmental outcome documentation shapes Defra's Agricultural Transition Plan reimbursement structures. Three-tier pricing structure across premium organic, certified sustainable, and commodity conventional levels reflects certification grade and provenance transparency. Pricing pressure stems from supermarket own-label programs transferring demand volatility risk upstream to grower cooperatives. Food service operators show least price sensitivity, while bulk wholesale terminals face acute margin compression.
Supply Chain Analysis
Dual-sourcing requirements from Tesco and Sainsbury's buying offices mandate multi-supplier qualification across Kent glasshouse clusters and Spanish import channels. Geographic supply concentrates in Spain, the Netherlands, and domestic East Anglia root vegetable belts. Raw material dependencies center on natural gas for heating, seasonal labor licenses, and peat-reduced growing media. Single-source vulnerability runs through approved operator licensing for harvest timing flexibility. Distribution runs through New Covent Garden Market aggregation for food service and automated Ocado fulfillment for online retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into grower networks has become the defining competitive race, with subscription box operators and wholesale stall holders alike pursuing captive supply to secure residue-compliant volume.
For Market Incumbents: Deploy LED supplemental lighting infrastructure to buffer energy input cost volatility and stabilize winter tomato yields. Lock multi-year contracts with seasonal worker scheme licensees to preempt harvest timing bottlenecks. Ocado and Amazon Fresh automated fulfillment partnerships represent the critical channel control lever against wholesale terminal margin erosion. For New Entrants and Emerging Players: Farmers market direct-to-consumer transactions offer the most penetrable white-space target, capturing premium pricing through provenance storytelling at Marylebone and Borough Market locations. Heritage variety specialization commands shelf-space premiums in Waitrose and Booths. Weekly subscription box schemes targeting affluent urban cohorts provide the strongest go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors accredited grower cooperatives with environmental land management scheme documentation. Long-term viability hinges on soil health metric auditability and cold-chain certification capacity. Watch Defra's subsidy reduction trajectory as the inflection indicator for conventional producer distress opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grower Networks | Riverford Organic Farmers' Devon-based aggregation secures residue-compliant supply for subscription volumes. |
| LED-Hydroponic Glasshouse Expansion | Thanet Valley installations enable year-round production independent of Spanish import price cycles. |
| Environmental Land Management Certification | Defra's subsidy redirection rewards documented cover cropping and reduced tillage adoption. |
| Automated Fulfillment Partnership | Ocado's warehouse accreditation creates listing pathways meeting modified-atmosphere packaging protocols. |
| Heritage Variety Specialization | Cains Farm's provenance-differentiated lines command premiums in premium retail banners. |
Research Methodology
Document review covered Defra Agricultural Transition Plan filings, Food Standards Agency residue monitoring reports, and Groceries Code Adjudicator enforcement records, complemented by interviews with supermarket category buyers, glasshouse operations managers, New Covent Garden Market stall holders, and seasonal worker scheme licensees. Secondary validation drew from UK customs trade data, horticultural cooperative financial disclosures, and automated warehouse infrastructure investment announcements. Bottom-up grower volume estimates and top-down channel throughput analysis were triangulated.
Cross-referencing historical subsidy payment trajectories against panel input from procurement directors established the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, distribution channel, end-user category, and packaging format. CAGRs were derived through trend extrapolation of glasshouse technology diffusion rates and channel migration patterns toward online retail.
Caveats apply where Defra subsidy reduction schedules or post-Brexit phytosanitary certification requirements could materially shift the outlook. Deviation in seasonal worker scheme licensing throughput would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Guava Puree Market
Fruits and Vegetables
Avocado-Based Products Market
Fruits and Vegetables
Pomegranate Market
Fruits and Vegetables
Global Organic Fruits and Vegetables Market
Fruits and Vegetables
Europe Orange Market
Fruits and Vegetables
Global Pickle Market
Fruits and Vegetables
Dry Beans Market
Fruits and Vegetables
Organic Bananas Market
Fruits and Vegetables
North America Canned Fruits Market
Fruits and Vegetables
Arecanut Market
Fruits and Vegetables
Europe Stone Fruits Market
Fruits and Vegetables
Europe Freeze-Dried Fruits and Vegetable Market
Fruits and Vegetables
Edible Flowers Market
Fruits and Vegetables
Rubus Idaeus (Raspberry) Seed Oil Market
Fruits and Vegetables
Europe Frozen Fruits and Vegetables Market
Fruits and Vegetables
Cambodia Fruits and Vegetables Market