
 Ready to Use Fillings Market | 2026-2036
Ready to Use Fillings Market Size, Share, and Industry Trends Forecast 2026-2036
Ready to Use Fillings Market Analytics
China's ready-to-use fillings capacity expansion is narrowing the export surplus from Western suppliers. Nestlé leverages its dairy procurement network to sustain margin stability across cream-based formulations. Barry Callebaut anchors European chocolate and nut-based paste supply through integrated bean sourcing. Mondelez International competes in confectionery gels with proprietary stabilizer technology.
Ready to use fillings comprise pre-formulated, pumpable food matrices with controlled water activity between 0.85 and 0.92, designed for direct deposition into baked goods, confections, or savory applications without intermediate preparation. Creams dominate value contribution due to dairy fat volatility and cold-chain requirements, while gels represent the fastest-expanding category as Asian confectionery producers adopt Western-style layered desserts. Food service channels command premium pricing for aseptic pouch formats that reduce kitchen labor and waste.
The FDA's Food Safety Modernization Act preventive controls and the EU's EFSA additive re-evaluations compel manufacturers to reformulate with natural hydrocolloids and clean-label preservatives. China's SAMR enforces stricter GB standards for imported fillings, raising compliance costs for non-domestic suppliers. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether localized production or reformulation investments offer lower total compliance burden.
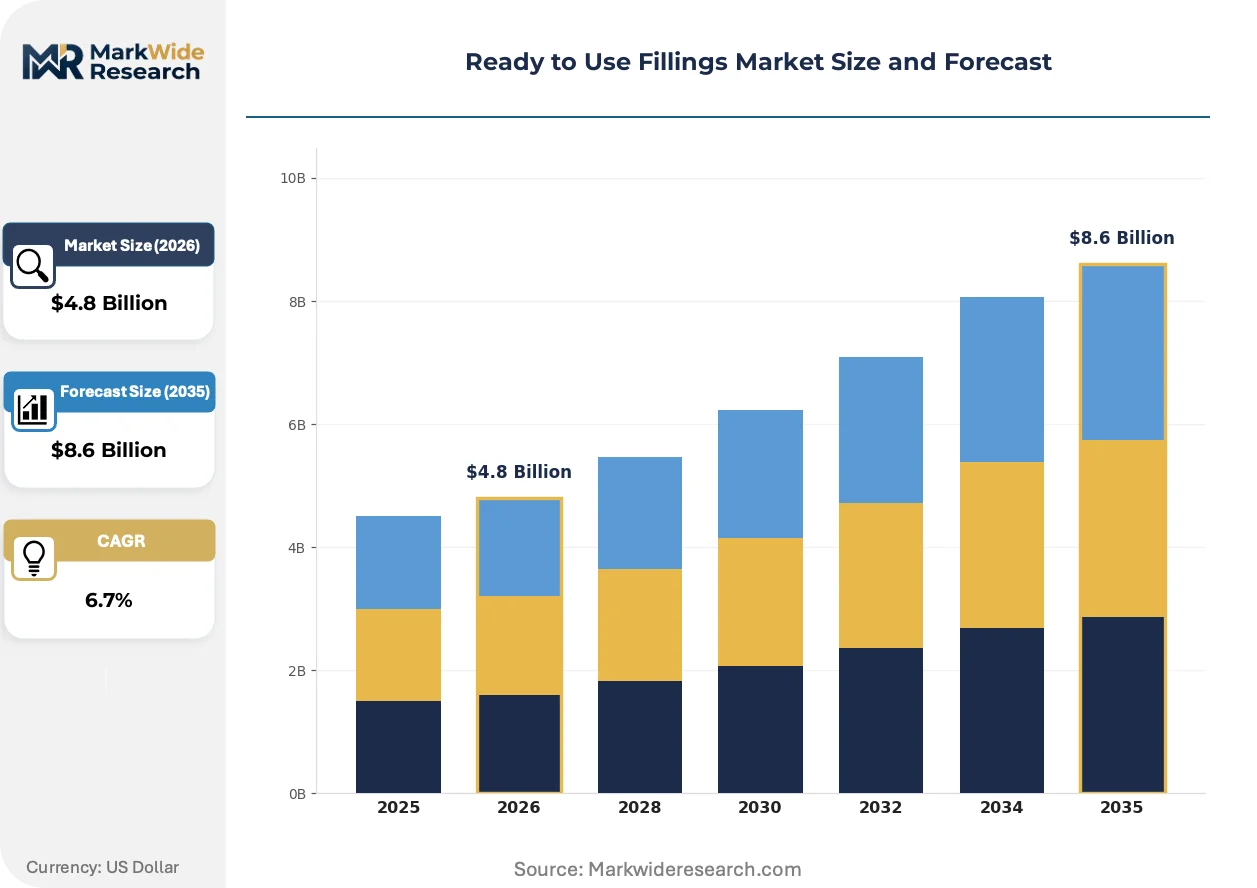
Market Dynamics
Food service labor inflation and Europe's F-Gas Regulation are forcing simultaneous reformulation of cream-based matrices and cold-chain infrastructure redesign across industrial bakery networks.
Growth Catalysts
- Automated Deposition Systems:Industrial bakeries in Germany's Ruhr cluster now require pumpable fillings with viscosity tolerances under 5% variance to maintain line speeds above 200 units per minute.
- EFSA Additive Re-evaluations:Clean-label mandates are accelerating replacement of synthetic stabilizers with citrus fiber and native starch blends in premium confectionery tiers.
- Aseptic Pouch Formats:Food service operators in France and Italy are adopting shelf-stable creams that eliminate kitchen reconstitution labor and reduce waste by enabling precise portion control.
Market Restraints
- Dairy Fat Volatility:Cream-based formulations remain exposed to butterfat price swings that compress margin stability for European manufacturers without backward integration into dairy processing.
- GB Standards Compliance:China's SAMR enforcement of stricter microbiological limits on imported fillings raises testing costs and extends customs clearance timelines for Western suppliers.
- Gelatin Substitution Pressure:Plant-based hydrocolloids in Asian confectionery are displacing animal-derived gels in layered dessert applications, forcing reformulation investments.
Strategic Opportunities
- Underpenetrated Indian Bakery Sector:Organized retail expansion in Mumbai and Bangalore creates demand for standardized fillings that local unbranded suppliers cannot match on consistency.
- Dual Carbon Goals Alignment:China's MEE carbon intensity targets favor domestic producers with localized supply chains over import-dependent competitors facing Scope 3 emissions scrutiny.
- Clean-Label Preservative Convergence:Fermented wheat flour and cultured sugar combinations are emerging as viable clean-label alternatives to potassium sorbate in ambient-stable pastes.
Industry Challenges
- Refrigerated Logistics Reconfiguration:Cold-chain operators must retrofit fleets to handle F-Gas phasedown refrigerants while maintaining 2-4°C stability for dairy-fat creams across extended distribution radii.
- Cross-Functional Formulation Expertise:Shortage of technologists fluent in both hydrocolloid rheology and industrial-scale thermal processing limits speed-to-market for texture-modified launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ready to Use Fillings Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Creams, Pastes, Gels, Sauces Application: Baking, Confectionery, Desserts, Savory Dishes End User: Food Service, Retail, Bakeries, Caterers Packaging Type: Tubs, Pouches, Jars, Sachets |
| Companies Covered | Nestlé, Kraft Heinz, Unilever, Cargill, General Mills, Mondelez International, Barry Callebaut, Archer Daniels Midland Company, Rich Products Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ready to Use Fillings Market Evolving Landscape
Formulation science and regulatory chemistry are converging to reshape viscosity control, preservation systems, and packaging formats across ready-to-use filling categories.
High-pressure processing is hybridizing with traditional thermal treatment to extend ambient shelf life of dairy creams without the cooked flavor profiles that degrade premium positioning. European industrial bakeries in the Netherlands and Belgium are piloting HPP-treated vanilla and chocolate creams at 600 MPa for 60-day stability. This hybridizing approach compresses the trade-off between clean-label claims and distribution radius that has constrained fresh cream penetration into convenience retail.
Europe's F-Gas Regulation is mandating refrigerant transitions that cascade into cold-chain cost structures for temperature-sensitive fillings. Manufacturers serving German and French food service channels must now validate product stability under wider temperature excursion windows to accommodate fleet retrofitting delays. Cream-based categories face the steepest compliance burden, driving accelerated investment in water activity reduction and modified atmosphere packaging.
Buyer concentration among multinational bakery chains is compressing supplier negotiation cycles and unbundling technical service from base product pricing. Industrial procurement teams in Spain and Poland now issue quarterly tenders with viscosity and microbiological specifications that disqualify regional specialists lacking certified laboratory infrastructure. This consolidation favors filling suppliers with captive R&D facilities capable of rapid reformulation response to specification changes.
Ready to Use Fillings Market Segmentation
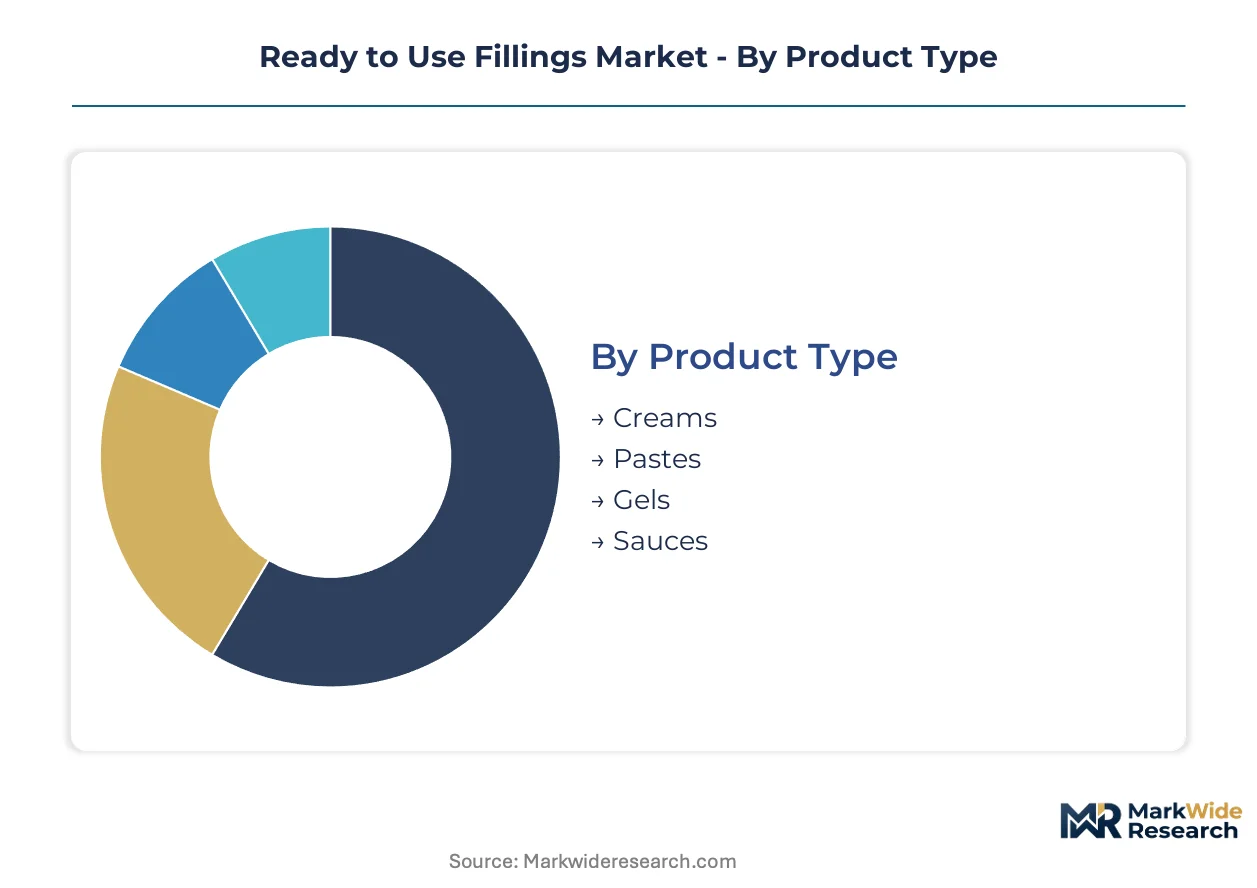
Segmentation in ready-to-use fillings determines technical service intensity, formulation complexity, and margin structure. Product viscosity requirements and cold-chain dependencies vary sharply across categories, forcing suppliers to maintain distinct R&D and application engineering capabilities for each segment cluster.
Product Type:
After-sales technical support intensity escalates with formulation complexity and stability requirements, with dairy-fat matrices demanding the most intensive customer service.
- Creams:Dairy-fat emulsions with controlled water activity between 0.85 and 0.92 require precise cold-chain maintenance. Germany's industrial bakery cluster drives specification intensity, where automated lines demand viscosity variance under 5% to sustain speeds above 200 units per minute. EFSA additive re-evaluations are accelerating reformulation toward citrus fiber and native starch stabilizers.
- Gels:Hydrocolloid matrices with controlled elastic modulus dominate Asian confectionery applications. Layered dessert adoption in China and Japan is climbing fastest as producers adopt Western-style visual differentiation, though plant-based hydrocolloid substitution is displacing traditional animal-derived formulations.
- Pastes:Nut and chocolate-based matrices with reduced water activity for ambient stability.
- Sauces:Fluid savory formulations with acidified pH control for extended shelf life.
By volume, creams lead. By expansion trajectory, gels are climbing fastest.
Application:
Application segmentation tracks directly to processing equipment investment and thermal treatment requirements, with baking commanding the most standardized specifications.
- Baking:Pumpable matrices designed for direct deposition into croissants, Danish pastries, and laminated doughs. France and Italy's food service channels specify aseptic pouch formats that eliminate kitchen reconstitution labor.
- Confectionery:Viscosity-controlled fillings for enrobing and molding operations. India's organized retail expansion in Mumbai and Bangalore is creating demand for standardized products that local unbranded suppliers cannot match on consistency.
- Desserts:Layered and mousse applications requiring freeze-thaw stability.
- Savory Dishes:Acidified cream and cheese matrices for ready-meal integration.
Baking generates the highest volume throughput. Dessert applications are expanding most quickly.
End User:
End-user segmentation determines packaging format preferences and price sensitivity, with food service operators prioritizing labor reduction over unit cost.
- Food Service:Hotels, restaurants, and institutional kitchens purchasing aseptic pouches and portion-controlled sachets. Labor inflation across France and Italy is accelerating adoption of shelf-stable formats that reduce kitchen preparation time and waste.
- Retail:Supermarkets and convenience stores stocking consumer-format tubs and jars. Germany's retail consolidation is compressing supplier negotiation cycles and unbundling technical service from base product pricing.
- Bakeries:Industrial and artisanal producers requiring bulk formats with consistent viscosity for automated deposition.
- Caterers:Event and contract food service operators prioritizing ambient stability for logistical flexibility.
Food service commands premium pricing. Retail channels are gaining share fastest in emerging markets.
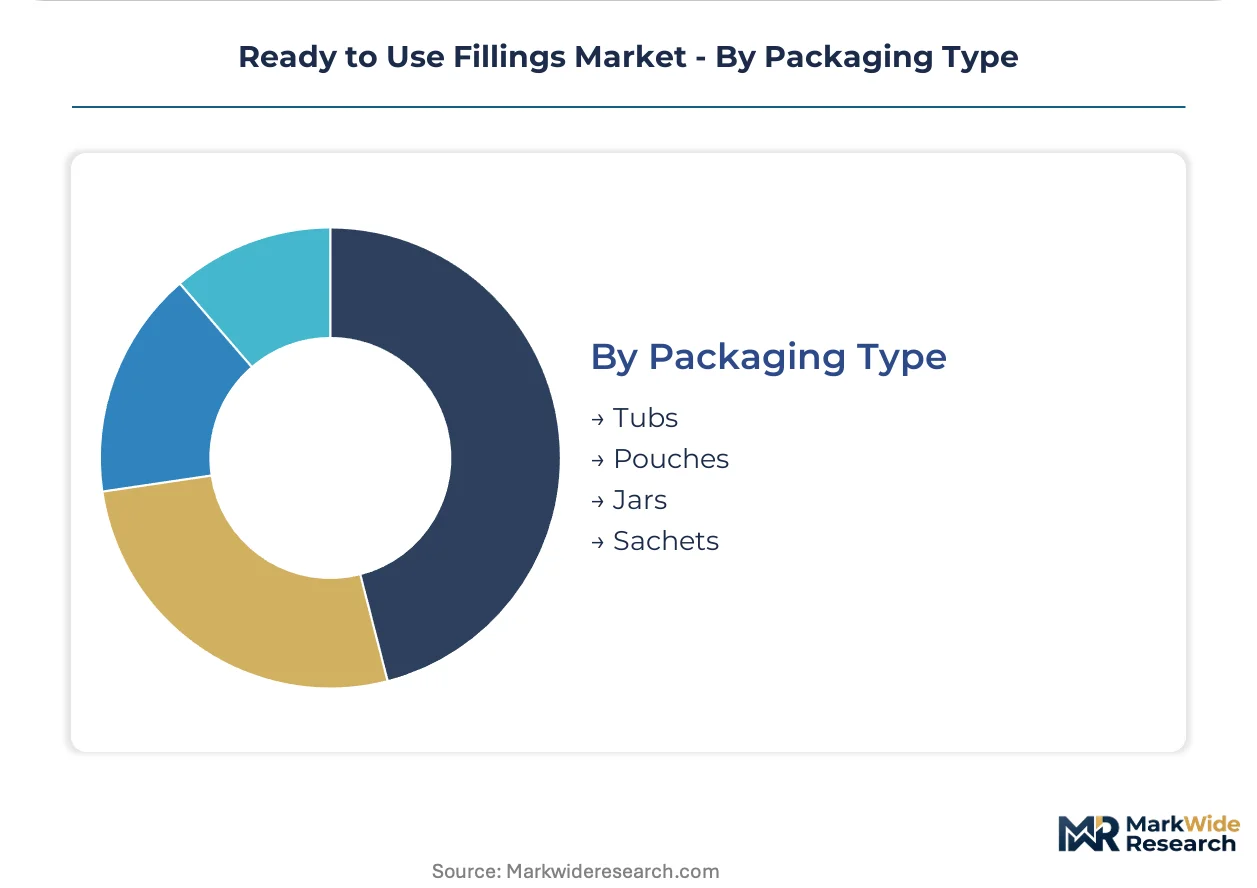
Packaging Type:
Packaging segmentation aligns with distribution radius requirements and sustainability mandates, with pouch formats benefiting from F-Gas Regulation compliance pressures.
- Pouches:Flexible aseptic formats enabling precise portion control and extended ambient shelf life. Netherlands and Belgium industrial bakeries are piloting high-pressure processed creams in pouch formats for 60-day stability without cooked flavor degradation.
- Tubs:Rigid containers for food service bulk purchasing and retail multi-serve applications.
- Jars:Glass and PET formats for premium retail positioning with resealability.
- Sachets:Single-serve portions for hospitality and airline catering channels.
Tubs dominate current volume. Pouch formats are climbing fastest as food service labor costs rise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA's additive re-evaluations and Europe's F-Gas Regulation anchor the most stringent compliance environment, forcing simultaneous reformulation of dairy-fat matrices and cold-chain infrastructure redesign across industrial bakery networks.
Germany
Industrial bakeries in the Ruhr cluster demand pumpable fillings with viscosity variance under 5% to sustain automated line speeds above 200 units per minute. The F-Gas Regulation mandates refrigerant transitions that cascade into fleet retrofitting costs for temperature-sensitive cream distribution. Bavaria's dairy processing concentration enables backward integration strategies that buffer butterfat price volatility for domestic manufacturers.
China
Layered dessert adoption in Shanghai and Guangzhou is climbing fastest as confectionery producers adopt Western-style visual differentiation. SAMR's stricter GB standards enforcement on imported fillings raises testing costs and extends customs clearance timelines for Western suppliers. The Yangtze River Delta's industrial bakery expansion is narrowing the export surplus from European cream suppliers.
France
Food service operators in Paris and Lyon specify aseptic pouch formats that eliminate kitchen reconstitution labor and reduce waste through precise portion control. EFSA clean-label mandates accelerate replacement of synthetic stabilizers with citrus fiber and native starch blends in premium confectionery tiers. Île-de-France's procurement consolidation compresses supplier negotiation cycles and unbundles technical service from base product pricing.
India
Organized retail expansion in Mumbai and Bangalore creates demand for standardized fillings that local unbranded suppliers cannot match on consistency. FSSAI's evolving food safety standards raise compliance barriers for imported formulations while favoring domestic production investments. Maharashtra's emerging industrial bakery sector lacks sufficient technologists fluent in hydrocolloid rheology and thermal processing.
United States
Food service labor inflation accelerates adoption of shelf-stable creams that reduce kitchen preparation time across hotel and institutional channels. FDA's Food Safety Modernization Act preventive controls compel manufacturers to reformulate with natural hydrocolloids and clean-label preservatives. The Midwest dairy belt's processing concentration supports margin stability for cream-based formulations through captive supply relationships.
Ready to Use Fillings Market Competitive Landscape
Multinational ingredient conglomerates and specialized dairy processors split the market between scale-driven procurement leverage and formulation technical service. The vendor base concentrates around three strategic archetypes: diversified food conglomerates with backward integration into dairy procurement, cocoa and nut-based specialists with integrated bean sourcing, and regional dairy processors with captive cream supply. Competitive moves center on M&A to secure hydrocolloid technology assets and capacity expansion in underpenetrated Asian markets.
Among diversified food conglomerates, Nestlé and Kraft Heinz exemplify archetypes anchored by dairy procurement networks that sustain margin stability across cream-based formulations. Barry Callebaut occupies a position representing cocoa and nut-based paste specialists with integrated bean sourcing that anchors European supply. These three entities sit within distinct competitive vectors—dairy procurement leverage, integrated commodity sourcing, and global distribution scale—rather than direct product overlap.
| Leading Market Players |
|---|
| Nestlé |
| Kraft Heinz |
| Unilever |
| Cargill |
| General Mills |
| Mondelez International |
| Barry Callebaut |
| Archer Daniels Midland Company |
| Rich Products Corporation |
| Others |
Value Network & Pricing Analysis
Germany's dairy processing concentration anchors butterfat supply for European cream-based formulations, concentrating margin pools with manufacturers possessing backward integration into fluid milk procurement. Food service operators absorbing cold-chain retrofit costs from F-Gas Regulation compliance now demand price stability clauses in quarterly procurement tenders.
Pricing Analysis
Geographic price spreads between Western European and Asian industrial bakery markets exceed transport-cost differentials due to EFSA-mandated reformulation expenses and extended customs clearance timelines under China's SAMR enforcement. Three-tier pricing structure across premium clean-label, standard stabilized, and economy synthetic-stabilizer tiers dominates contract negotiations. Price differentiation hinges on certification tier and volume scale, with industrial procurement teams in Spain and Poland extracting steep discounts for multi-year offtake commitments. Pricing pressure stems from dairy fat volatility compressing margins for non-integrated manufacturers, while food service channels show least price sensitivity due to labor-cost reduction priorities.
Supply Chain Analysis
Upstream feedstock dependence on New Zealand butterfat, German fluid milk, and West African cocoa butter concentrates supply risk in dairy-fat and chocolate-based matrices. Raw material sourcing draws from dairy cooperatives in Bavaria, cocoa processors in Belgium and the Netherlands, and hydrocolloid suppliers in China and Japan. Single-source vulnerability in citrus fiber and native starch stabilizers intensifies as EFSA additive re-evaluations accelerate synthetic replacement. Distribution runs through cold-chain operators retrofitting fleets for F-Gas compliance, with ambient-stable pouch formats bypassing refrigerated logistics for food service channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-pressure processing hybridization with thermal treatment represents a technological inflection disrupting the clean-label versus shelf-life trade-off that has constrained cream-based category expansion.
For Market Incumbents: Entrench procurement leverage through captive dairy supply relationships in Germany's Bavaria cluster and accelerated HPP capacity installation in Netherlands and Belgium pilot facilities. EFSA's additive re-evaluations threaten synthetic stabilizer portfolios, requiring rapid citrus fiber and native starch formulation expertise acquisition through targeted hydrocolloid technology hires. For New Entrants and Emerging Players: Build out localized production footprints in India's Maharashtra and Karnataka states to bypass FSSAI import compliance barriers while supplying Mumbai and Bangalore's organized retail expansion. India's industrial bakery sector lacks technologists fluent in hydrocolloid rheology, creating service-intensive entry angles through application engineering partnerships with European equipment suppliers. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap specialists with integrated hydrocolloid formulation capabilities and established SAMR registration pathways for GB standards compliance. Long-term viability across the projection horizon favors targets with HPP processing assets and clean-label preservative fermentation technology. Monitor EFSA's additive re-evaluation timeline as the signal indicating acceleration windows for citrus fiber and native starch substitution demand.| Strategic Initiative | Industry Significance |
|---|---|
| HPP-Thermal Hybrid Processing Investment | Extends ambient shelf life of dairy creams without cooked flavor degradation for premium positioning. |
| Backward Integration into Dairy Procurement | Buffers margin stability against butterfat price volatility in Germany's industrial bakery supply base. |
| SAMR Registration and Localized Production | Reduces customs clearance timelines and testing costs under China's stricter GB standards enforcement. |
| Clean-Label Preservative Fermentation Capacity | Replaces potassium sorbate with fermented wheat flour and cultured sugar combinations for ambient-stable pastes. |
| Hydrocolloid Technology Acquisition | Secures citrus fiber and native starch formulation expertise for EFSA-compliant premium confectionery tiers. |
Research Methodology
A standing panel of industrial bakery procurement directors, food service operations managers, hydrocolloid R&D technologists, and cold-chain logistics coordinators provided ongoing calibration across primary interview rounds. Secondary validation drew from EFSA additive re-evaluation documentation, SAMR GB standards filings, customs trade data for dairy and cocoa derivatives, and SEC 10-K disclosures from diversified food conglomerates. Bottom-up volume modeling triangulated against top-down category spend estimates from food service channel audits.
Scenario-bracketing around F-Gas Regulation implementation pace and EFSA re-evaluation timelines framed the analytical approach across the analysis window. Segmentation dimensions modeled include product viscosity tier, thermal treatment requirement, packaging format, and regional regulatory cluster. CAGRs were derived from curve-fitting against historical dairy fat price cycles and industrial bakery automation adoption rates, with specific inputs from HPP processing capacity expansion announcements and SAMR enforcement intensity indicators.
Sensitivities concentrate around EFSA's synthetic stabilizer ban timeline, China's GB standards microbiological limit adjustments, and F-Gas refrigerant transition cost pass-through rates. Cross-checking against IHS Markit food processing equipment installation data and Cefic hydrocolloid trade flows is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
US Canned Foods Market
Packaged Foods
Plant Focused Dips Market
Packaged Foods
Asia-Pacific Ready Meals Market
Packaged Foods
Packaged Vegan Foods Market
Packaged Foods
Australia Food Cans Market
Packaged Foods
Jams and Spreads Market
Packaged Foods
Packaged Corn on the Cob Market
Packaged Foods
Hummus Market
Packaged Foods
South America Breakfast Cereals Market
Packaged Foods
Canned Legumes Market
Packaged Foods
Asia-Pacific Breakfast Cereals Market
Packaged Foods
Pre-Packaged Food Market
Packaged Foods
Instant Soup Market
Packaged Foods
Fat Free Pasta Market
Packaged Foods
North America Pasta Market
Packaged Foods
Canned Soup Market