
 Brio Bowls Market | 2026-2036
Brio Bowls Market Size, Share, and Industry Trends Forecast 2026-2036
Brio Bowls Market Analytics
Artisan ceramic craftsmanship availability is redrawing competitive boundaries across the Brio Bowls landscape. HUHTAMAKI GROUP leverages industrial-scale molded fiber capabilities to supply high-volume foodservice contracts. Be Green Packaging anchors its position through proprietary plant-fiber forming technology for compostable bowl lines. CHINRIU HONTEN specializes in traditional Japanese lacquerware-influenced designs that command premium placement in specialty retail channels.
Brio Bowls comprise rigid foodservice and tableware vessels engineered for single or repeated use, typically ranging from 12 to 40 ounces in fluid capacity, formed through slip-casting, thermoforming, or pressed-fiber processes to serve salads, pasta, soups, and shared dishes. Salad Bowls and Serving Bowls dominate commercial procurement due to their centrality in fast-casual assembly-line formats and family-style dining presentations. Bamboo and molded fiber segments are expanding fastest as operators replace conventional plastic under extended producer responsibility mandates, while Ceramic retains the deepest margin pools through limited-batch artisan positioning.
The EU PPWR and FDA food-contact substance regulations jointly determine material permissibility and labeling requirements for cross-border bowl shipments. Japan's METI enforces stringent JIS standards for bamboo and wood-product treatments that govern import eligibility for traditional-format Brio Bowls. Stakeholders must monitor evolving state-level packaging bans in California and New York alongside pending federal rulemakings to anticipate forced material transitions and inventory obsolescence risks.
Market Dynamics
The EU Packaging and Packaging Waste Regulation (PPWR) is forcing immediate material transitions across the Brio Bowls supply base, compelling manufacturers to certify compostable and recycled-content formulations before 2030 enforcement deadlines.
Growth Catalysts
- Extended Producer Responsibility Mandates:Germany's Verpackungsgesetz and California's SB 54 require foodservice operators to source certified compostable serveware, accelerating procurement of molded fiber and bamboo alternatives.
- Fast-Casual Assembly-Line Expansion:Premium casual dining chains in the United States are refreshing tableware programs to differentiate customer experience, driving bulk orders for artisan-crafted ceramic and pressed-fiber salad bowls.
- Japan's Traditional Aesthetic Premiumization:METI-certified JIS-compliant bamboo and lacquerware-influenced designs command placement in specialty retail channels, capturing hospitality procurement budgets focused on cultural authenticity.
Market Restraints
- Raw Material Concentration Risk:Molded fiber pulp supply concentrates in Nordic and Southeast Asian timber regions, exposing bowl manufacturers to freight volatility and harvest-cycle disruptions.
- Ceramic Firing Energy Costs:Natural gas price fluctuations directly compress margins for slip-casting artisans operating batch kilns, particularly in Italy and Portugal production clusters.
- Cross-Border Certification Friction:Divergent FDA food-contact substance approvals and EU REACH compliance timelines create inventory stranding risks for exporters serving both North American and European hospitality buyers.
Strategic Opportunities
- Underpenetrated German Foodservice:System gastronomy chains in Germany lag Nordic counterparts in compostable bowl adoption, presenting first-mover advantage for certified suppliers meeting EU Green Deal procurement criteria.
- Smart Packaging Convergence:Integration of molded fiber forming with embedded RFID traceability enables premium casual operators to track bowl lifecycle and demonstrate circularity claims to ESG-focused investors.
- Direct-to-Operator Digital Channels:Bypassing traditional foodservice distributors, bowl manufacturers are building proprietary B2B platforms to capture margin and capture demand signals from independent restaurant groups.
Industry Challenges
- Artisan Capacity Scaling:Limited-batch ceramic craftsmanship requires multi-year apprenticeship pipelines that cannot expand quickly enough to meet hospitality procurement volume surges.
- Composting Infrastructure Mismatch:Industrial compostable bowl certification outruns municipal composting facility availability in most United States metropolitan areas, creating performance credibility gaps with sustainability-marketing claims.
- Legacy Plastic Inventory Obsolescence:Foodservice distributors face write-down pressure from state-level packaging bans in New York and pending federal rulemakings, complicating procurement planning for multi-site operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brio Bowls Market |
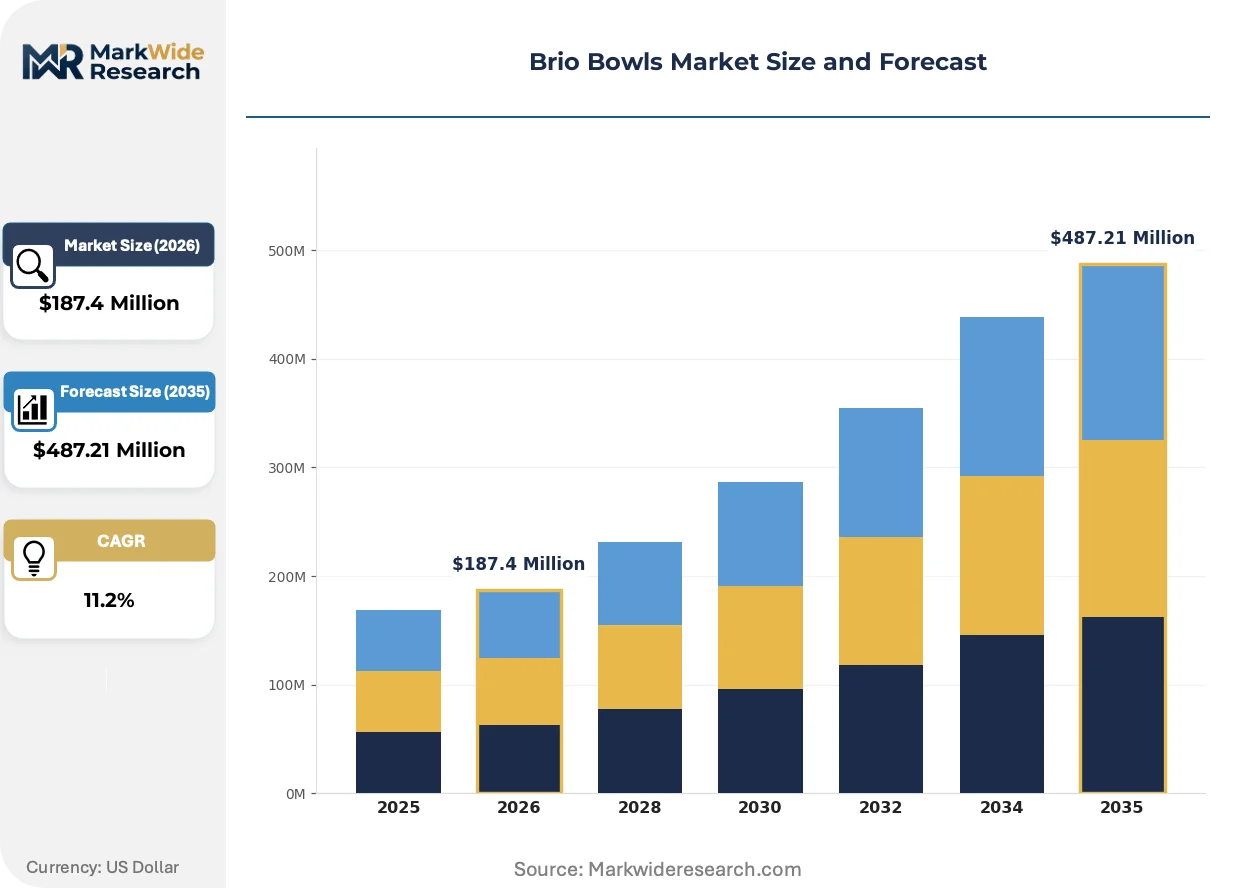
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $487.21 Million |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Salad Bowls, Pasta Bowls, Serving Bowls, Soup Bowls Material: Ceramic, Glass, Plastic, Bamboo Size: Small, Medium, Large, Extra Large Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesalers |
| Companies Covered | HUHTAMAKI GROUP, All Florida Paper, Mansfield Paper Company, Birsch Industries, Teigen Paper Supply, Lotus Pack, Be Green Packaging, CHINRIU HONTEN, Brio Bowls by Keiko, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brio Bowls Market Evolving Landscape
Material science advances and regulatory compliance automation are converging to reshape competitive positioning across rigid serveware categories, with sustainability certification becoming the primary procurement filter.
Pressed-fiber thermoforming with proprietary plant-fiber blends is displacing conventional polypropylene in high-volume fast-casual applications. Chains with 500-plus locations are mandating compostable alternatives in refresh programs. The technology is compressing price premiums between molded fiber and plastic to under fifteen percent at scale.
REACH substance restrictions and the EU PPWR's recycled-content quotas are rewriting material permissibility for cross-border bowl shipments. Manufacturers must maintain dual certification stacks for FDA and EFSA compliance. Ceramic and bamboo segments face the steepest documentation burdens under the new harmonized standards.
Buyer consolidation among hospitality procurement groups is compressing vendor counts and extending contract durations. Independent restaurant cooperatives are pooling purchasing power through group purchasing organizations. The United States and Germany exhibit the most pronounced concentration, with three buying groups controlling majority share of premium casual bowl procurement.
Brio Bowls Market Segmentation
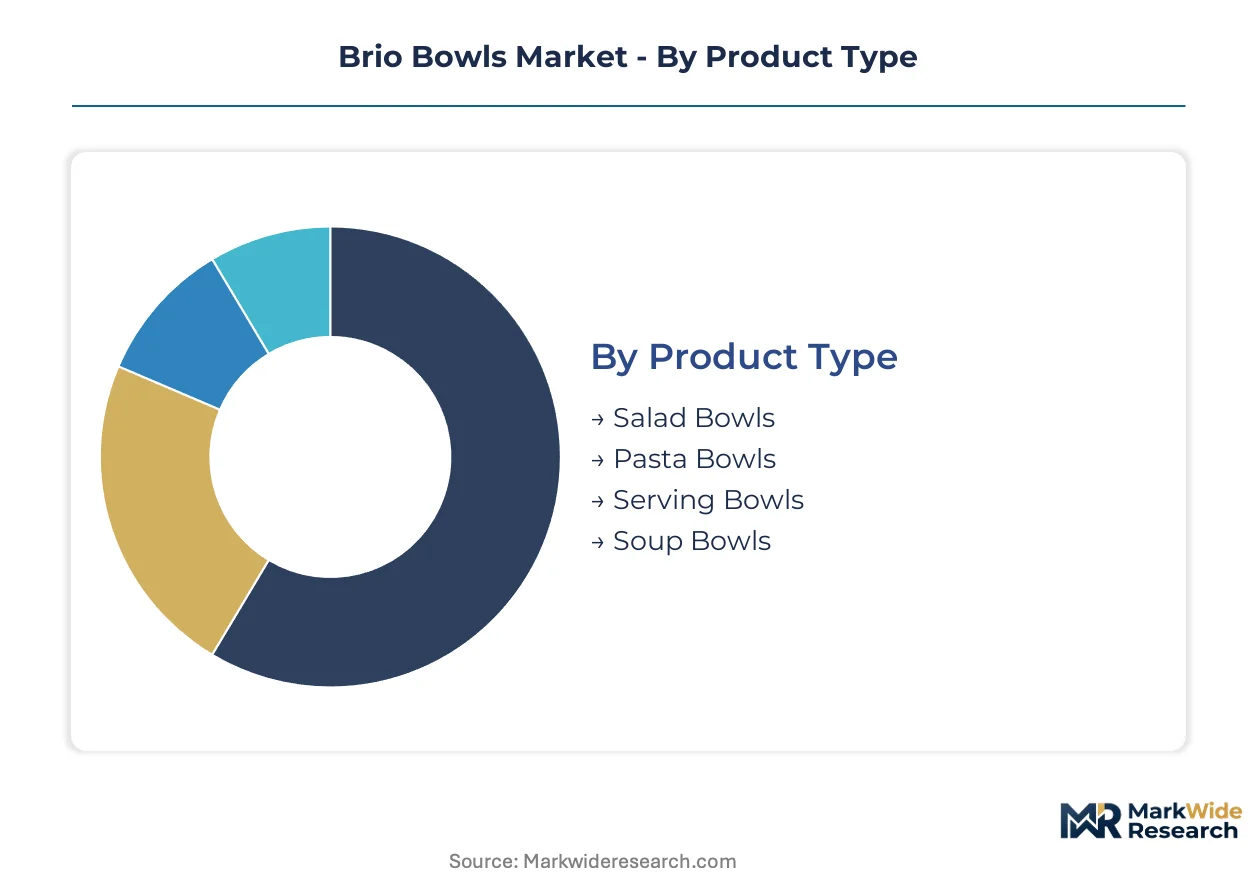
Procurement managers in foodservice and hospitality channels filter bowl purchases through material compliance, capacity specifications, and channel accessibility. Segmentation clarity enables suppliers to align certification investments with buyer decision hierarchies.
Product Type:
Salad Bowls face the most intense substitution pressure from disposable alternatives in fast-casual assembly formats, while Serving Bowls command durable investment cycles in full-service dining.
- Salad Bowls:Wide-rimmed vessels optimized for cold ingredient visibility and dressing containment. Fast-casual chains in the United States favor pressed-fiber and bamboo formats to meet California SB 54 mandates, though ceramic retains placement in premium positioning.
- Serving Bowls:High-capacity vessels engineered for shared-table presentation and family-style service. Hospitality procurement in Germany concentrates here for system gastronomy tableware refresh programs under EU Green Deal criteria.
- Pasta Bowls:Shallow, wide-profile designs with heat-retention properties for sauced preparations.
- Soup Bowls:Deep-walled vessels with thermal insulation requirements for hot liquid service.
Salad Bowls anchors the volume base while Serving Bowls gains share at the steepest rate.
Material:
Cost tier stratification separates artisan-fired ceramics from commodity molded fiber, with mid-tier bamboo capturing regulatory-driven substitution demand.
- Ceramic:Slip-cast or wheel-thrown clay bodies fired at 1,200°C-plus temperatures, glazed for food-contact safety and aesthetic differentiation. Italian and Portuguese production clusters supply limited-batch artisan lines to specialty retail channels in Japan and the United States where provenance commands premium placement.
- Bamboo:Laminated or pressed grass-fiber composites treated for moisture resistance and JIS compliance. Germany's Verpackungsgesetz and California's extended producer responsibility frameworks are accelerating procurement of METI-certified bamboo alternatives for compostable serveware mandates.
- Molded Fiber:Thermoformed plant-pulp vessels engineered for single-use foodservice applications.
- Glass:Tempered or soda-lime silicate vessels offering visual transparency and chemical inertness.
- Plastic:Polypropylene and PET formulations facing inventory obsolescence pressure from state-level packaging bans.
Ceramic commands the deepest margin pools while bamboo climbs the fastest under regulatory substitution pressure.
Size:
Volume concentration in mid-range capacities reflects standardization across fast-casual assembly-line equipment and family dining portion norms.
- Medium:20-28 ounce capacities matching fast-casual protein-plus-base bowl builds. United States quick-service operators standardize here for cross-menu flexibility, with procurement specifications tightening around stackability and dishmachine compatibility.
- Large:32-40 ounce formats for shared dishes and elevated presentation. German foodservice distributors favor this tier for system gastronomy contracts requiring family-style serving capability alongside individual portion alternatives.
- Small:12-16 ounce capacities for appetizer and side-dish applications.
- Extra Large:48-plus ounce vessels for catering and buffet service.
Medium anchors procurement volumes while Large expands most quickly in hospitality tableware refresh cycles.
Distribution Channel:
Customer type fragmentation splits between consolidated group purchasing organizations and fragmented independent operator access routes.
- Wholesalers:Broadline foodservice distributors managing inventory and logistics for multi-site operators. Three buying groups in the United States and Germany control majority share of premium casual bowl procurement, compressing vendor counts and extending contract durations.
- Online Retail:Direct-to-operator digital platforms enabling manufacturers to bypass distributor margins and capture demand signals from independent restaurant groups.
- Supermarkets:Mass retail channels for consumer tabletop and casual home entertaining segments.
- Specialty Stores:Curated retail environments emphasizing artisan provenance and cultural authenticity.
Wholesalers retain volume dominance while Online Retail gains share at the steepest rate through disintermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospitality procurement commands price premiums that German system gastronomy buyers resist, creating a transatlantic pricing-power asymmetry that shapes manufacturer portfolio priorities. Japan's specialty retail channels extract even steeper premiums for provenance-certified artisan lines. Regulatory divergence between FDA food-contact approvals and EU PPWR compliance timelines fragments supply chain economics across these three demand centers.
United States
Fast-casual assembly-line expansion and tableware refresh programs at premium casual chains drive molded fiber and ceramic procurement volumes. California's SB 54 extended producer responsibility mandate accelerates compostable bowl adoption ahead of federal rulemaking. Los Angeles and New York City procurement clusters concentrate demand for stackable, dishmachine-compatible formats across 500-plus location chains.
Germany
System gastronomy chains lag Nordic counterparts in compostable serveware adoption, creating first-mover openings for certified suppliers. The Verpackungsgesetz packaging law enforces strict recycled-content quotas that reshape distributor inventory requirements. North Rhine-Westphalia's foodservice distribution hubs channel procurement toward EU Green Deal-compliant ceramic and pressed-fiber alternatives.
Japan
Specialty retail and hospitality buyers prioritize METI-certified JIS-compliant bamboo and lacquerware-influenced designs for cultural authenticity positioning. METI enforces stringent treatment standards for imported wood and bamboo products that govern market eligibility. Tokyo's department store buyers and Osaka hospitality procurement groups anchor premium placement for limited-batch artisan lines.
Italy
Artisan ceramic production clusters face margin compression from natural gas price volatility affecting batch kiln operations. REACH substance restrictions and EU PPWR recycled-content mandates impose documentation burdens on slip-casting exporters. Tuscany and Emilia-Romagna craft workshops supply provenance-branded serveware to United States and Japanese specialty channels.
Portugal
Ceramic firing operations compete for export share against Italian clusters while navigating identical EU regulatory compliance costs. EFSA food-contact approvals and PPWR certification timelines determine cross-border shipment permissibility. Lisbon and Porto production zones target North American hospitality procurement with cost-advantaged artisan alternatives to Italian supply.
Brio Bowls Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Brio Bowls landscape. Industrial-scale molded fiber specialists compete on throughput and certification automation, while artisan ceramic workshops defend margin through limited-batch scarcity and provenance storytelling. The market structure separates into three strategic archetypes: high-volume foodservice contractors, compostable material technology specialists, and heritage craft positioning players. Competitive moves concentrate on backward integration into pulp supply and direct-to-operator digital channel development.
Among molded fiber and sustainable packaging specialists, HUHTAMAKI GROUP and Be Green Packaging occupy positions representing scale-driven and technology-differentiated archetypes respectively. CHINRIU HONTEN anchors the heritage craft tier through traditional Japanese design influence. These three company types exemplify how competitive positioning fragments across industrial efficiency, material innovation, and cultural authenticity vectors rather than consolidating around unified capabilities.
| Leading Market Players |
|---|
| HUHTAMAKI GROUP |
| All Florida Paper |
| Mansfield Paper Company |
| Birsch Industries |
| Teigen Paper Supply |
| Lotus Pack |
| Be Green Packaging |
| CHINRIU HONTEN |
| Brio Bowls by Keiko |
| Others |
Value Network & Pricing Analysis
Bamboo and molded fiber substitution for conventional plastic simultaneously redistributes supply geography toward Nordic pulp regions and Southeast Asian grass-fiber zones while compressing price premiums between compostable and legacy materials. California's SB 54 and Germany's Verpackungsgesetz accelerate this shift by mandating certified compostable procurement, forcing operators to absorb transitional cost premiums or redesign menu economics around new serveware specifications.
Pricing Analysis
The customization-premium spread separates limited-batch artisan ceramics from commodity molded fiber, with three-tier pricing structure across premium, standard, and economy levels. Certification grade under EU PPWR and FDA food-contact tiers drives price differentiation, while volume scale discounts compress margins for high-volume foodservice contracts. Cost compression in molded fiber is intensifying because Nordic pulp supply constraints and energy price volatility in ceramic firing clusters squeeze producer margins. Quick-service operators exhibit highest price sensitivity, whereas Japanese specialty retail buyers absorb premiums for provenance-certified artisan lines.
Supply Chain Analysis
Inventory lead times for METI-certified bamboo and JIS-compliant treatments extend procurement cycles by 8-12 weeks versus standard molded fiber alternatives. Supply concentrates in Italy and Portugal for artisan ceramic, Nordic regions for molded fiber pulp, and Southeast Asia for laminated bamboo composites. Raw material dependencies rest on timber harvest cycles, natural gas for batch kiln operations, and grass-fiber cultivation seasons. Single-source vulnerability in Nordic pulp supply exposes manufacturers to freight volatility and harvest disruptions. Distribution runs through broadline foodservice distributors in the United States and Germany, with direct-to-operator digital platforms gaining disintermediation share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Brio Bowls market sits at a platform-economics inflection where direct-to-operator digital channels and embedded RFID traceability converge to disintermediate traditional distributor relationships. Interoperability between compostability certification stacks and hospitality procurement software platforms will determine which suppliers capture group purchasing organization contract renewals.
For Market Incumbents: Consolidate backward integration into Nordic pulp supply and Portuguese ceramic firing capacity to defend against emerging compostable material specialists. Certification investment in dual FDA-EFSA compliance stacks protects against cross-border inventory stranding risks from divergent regulatory timelines. Channel control through proprietary B2B platforms captures margin and demand signals from independent restaurant groups bypassing traditional distributors. For New Entrants and Emerging Players: EU PPWR certification fast-track positions unlock first-mover advantage in underpenetrated German system gastronomy chains lagging Nordic compostable adoption curves. White-space targets include METI-certified bamboo supply for Japanese specialty retail and RFID-embedded molded fiber for United States premium casual chains with ESG reporting requirements. Direct-to-operator digital go-to-market angles bypass entrenched distributor relationships and capture procurement data for contract renewal negotiations. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors technology-differentiated compostable material specialists over undifferentiated molded fiber commodity producers. Long-term viability over the projection horizon hinges on backward integration into pulp supply and certification automation capabilities. Acquisition target archetypes include proprietary plant-fiber forming technology holders and METI-certified bamboo treatment specialists. The signal to watch is group purchasing organization vendor count compression extending contract durations toward multi-year exclusivity arrangements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Captive Nordic timber access insulates against harvest-cycle volatility and freight cost spikes. |
| Dual Certification Stack Investment | Simultaneous FDA and EFSA compliance enables cross-border shipment flexibility without inventory stranding. |
| Direct-to-Operator Platform Launch | Proprietary B2B channels capture margin and demand signals from independent restaurant cooperatives. |
| RFID Traceability Integration | Embedded molded fiber forming enables lifecycle tracking for ESG-focused hospitality investors. |
| Artisan Capacity Partnership | Multi-year apprenticeship pipelines with Italian and Portuguese craft workshops secure limited-batch ceramic supply. |
Research Methodology
Operator-level perspectives from fast-casual procurement directors, hospitality supply chain managers, ceramic craft workshop owners, and molded fiber plant engineers anchored the qualitative base. Primary interviews combined with secondary validation from EU PPWR implementation guidance, FDA food-contact substance databases, METI JIS standard publications, and California SB 54 rulemaking documents. Customs and trade data for pulp and ceramic shipments, foodservice distributor inventory disclosures, and hospitality group purchasing organization contract filings provided quantitative cross-checks. Bottom-up demand modeling and top-down supply capacity assessments triangulated volume and value estimates.
Sensitivity analysis tested forecast robustness across regulatory acceleration scenarios, natural gas price volatility bands, and pulp supply disruption assumptions. Segmentation dimensions modeled include product type, material composition, size capacity tier, and distribution channel structure alongside hospitality procurement certification grade. CAGRs derived from segment-level volume trajectories and price evolution assumptions across the analysis window. Industry-specific inputs incorporated extended producer responsibility mandate enforcement timelines and municipal composting infrastructure rollout patterns.
Decision-makers should treat outputs as directional under base assumptions of steady regulatory enforcement and stable pulp supply geography; material deviation in EU PPWR implementation speed or Nordic harvest conditions would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Canned Soup Market
Packaged Foods
North America Ready Meals Market
Packaged Foods
Instant Noodles Market
Packaged Foods
North America Pasta Market
Packaged Foods
Food and Beverages Market
Packaged Foods
Iran Breakfast Cereals Market
Packaged Foods
Global Popping Candy Market
Packaged Foods
Freekeh Market
Packaged Foods
Global Food Spread Market
Packaged Foods
Canned Fruits Market
Packaged Foods
Cookie Pucks Market
Packaged Foods
Breakfast Food Market
Packaged Foods
Condensed Canned Soups Market
Packaged Foods
Fat Free Pasta Market
Packaged Foods
Wet Pet Food Market
Packaged Foods
Europe Ready Meals Market