
 Global Optoelectronic Components Market | 2026-2036
Global Optoelectronic Components Market Size, Share, and Industry Trends Forecast 2026-2036
Global Optoelectronic Components Market Intelligence
South Korea's significant investment in semiconductor fabrication capacity is reconfiguring the supply base for high-performance optoelectronics. Hamamatsu Photonics K.K. leverages its specialization in high-sensitivity photodetectors for scientific and medical instruments. OSRAM Opto Semiconductors GmbH competes on the performance and efficiency of its LED and laser products for automotive and industrial lighting. ON Semiconductor positions itself with a broad portfolio catering to industrial automation and consumer electronics.
Optoelectronic components are devices that source, detect, or control light, fundamentally converting electrical energy into photons and vice versa. They operate across specific wavelengths, from ultraviolet to infrared, enabling applications in data transmission and environmental sensing. Light Emitting Diodes represent a mature, high-volume product category, while advanced Laser Diodes command higher margins. The telecommunication application segment continues to be a primary consumer, absorbing components for fiber optic networks and data centers.
Material composition is heavily scrutinized under frameworks like the European Union's RoHS directive, restricting hazardous substances like lead and cadmium. In parallel, China's GB standards and US EPA regulations create compliance hurdles for materials sourcing and fabrication waste streams. Success depends on balancing investments in compliant, sustainable materials against the escalating performance demands of new end-uses.
Market Dynamics
The central force shaping the optoelectronic components market is the escalating demand for data bandwidth from telecommunications and data centers. This relentless pull necessitates a fundamental shift toward smaller, more power-efficient, and highly integrated component designs like Photonic Integrated Circuits.
Growth Catalysts
- Photonic Integrated Circuits:The development of PICs allows for the consolidation of multiple optical functions onto a single chip, enabling the miniaturization and power reduction essential for next-generation data center interconnects and telecom networks.
- 5G Infrastructure Deployment:Government-backed initiatives, particularly in China, to build out national 5G networks create sustained, high-volume demand for fiber optic components, including transceivers, amplifiers, and modulators.
- Automotive LiDAR Systems:The push toward higher levels of vehicle autonomy in the automotive industry is creating a significant new demand stream for high-performance laser diodes and photodetectors used in LiDAR sensing technology.
Market Restraints
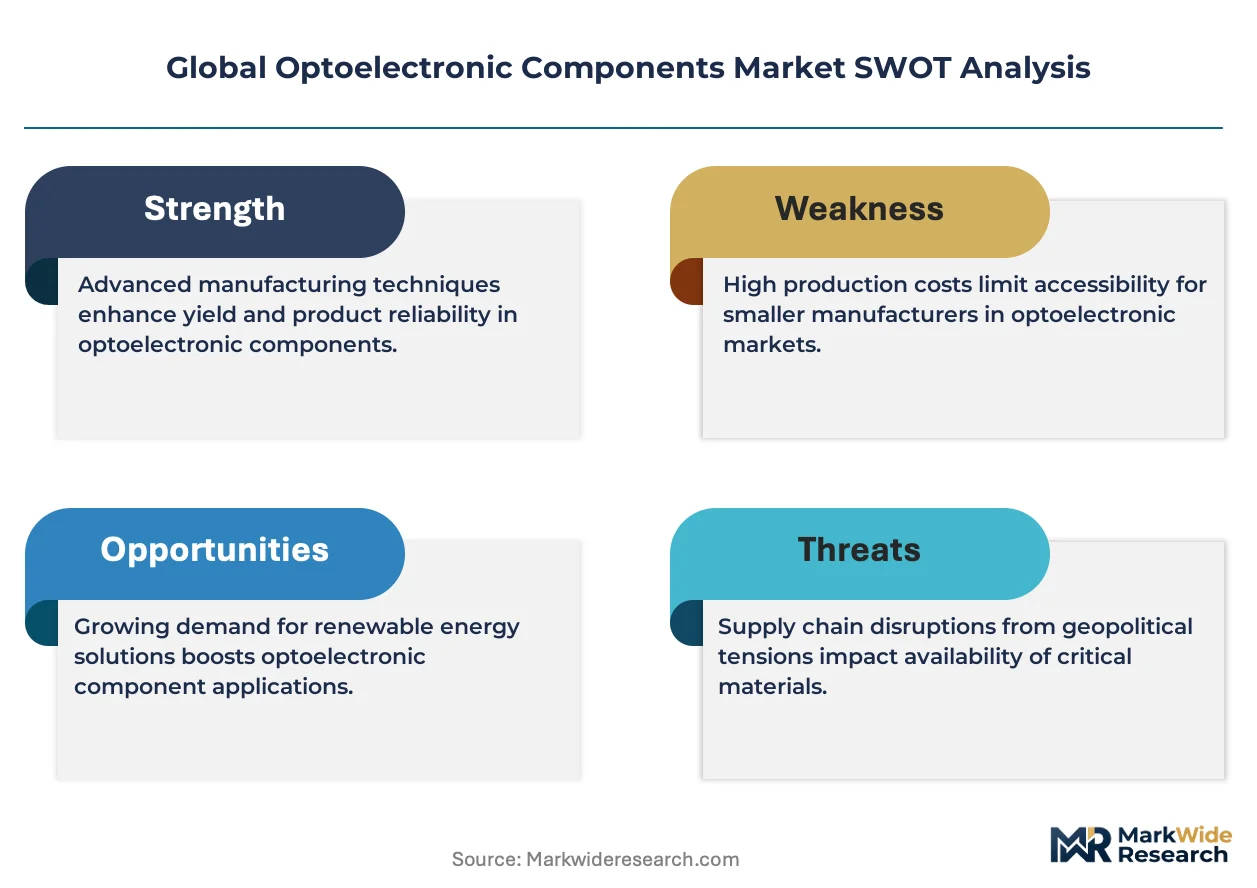
- High Material Costs:The reliance on expensive and difficult-to-process III-V compound semiconductor materials like Gallium Arsenide (GaAs) and Indium Phosphide (InP) creates a high-cost structure that can limit profitability and broader adoption.
- Hazardous Substance Regulations:Compliance with environmental mandates such as the European Union's RoHS directive restricts the use of materials like lead and cadmium, complicating manufacturing processes and requiring investment in alternative material science.
- Thermal Management Limitations:Increasing power density in smaller component packages presents a significant thermal dissipation challenge, acting as a structural bottleneck that can compromise performance, reliability, and operational lifespan.
Strategic Opportunities
- Quantum Information Systems:The emergence of quantum computing and communication creates a high-margin opportunity for specialized components, including single-photon sources and ultra-sensitive detectors, that operate at the quantum level.
- Advanced Agricultural Sensing:There is an underpenetrated opportunity in agricultural technology for infrared and multispectral sensors used in precision farming, crop health monitoring, and automated sorting, particularly in large agricultural economies.
- Micro-LED Display Technology:The transition to Micro-LEDs for next-generation displays in consumer electronics and automotive cockpits opens a vast, high-volume market for miniature, high-efficiency LED components.
Industry Challenges
- Photonic Engineering Talent Gap:A scarcity of engineers with specialized skills in compound semiconductor physics, epitaxial growth, and integrated photonics design creates an operational bottleneck for research, development, and manufacturing scale-up.
- Fragmented Compliance Pathways:Manufacturers face significant operational overhead in aligning product designs and manufacturing waste streams with disparate international standards, such as China's GB standards and US EPA regulations.
- System Integration Complexity:Integrating advanced optoelectronic devices into legacy industrial automation and medical equipment often requires extensive customization and specialized expertise, slowing adoption cycles for new technologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Optoelectronic Components Market |
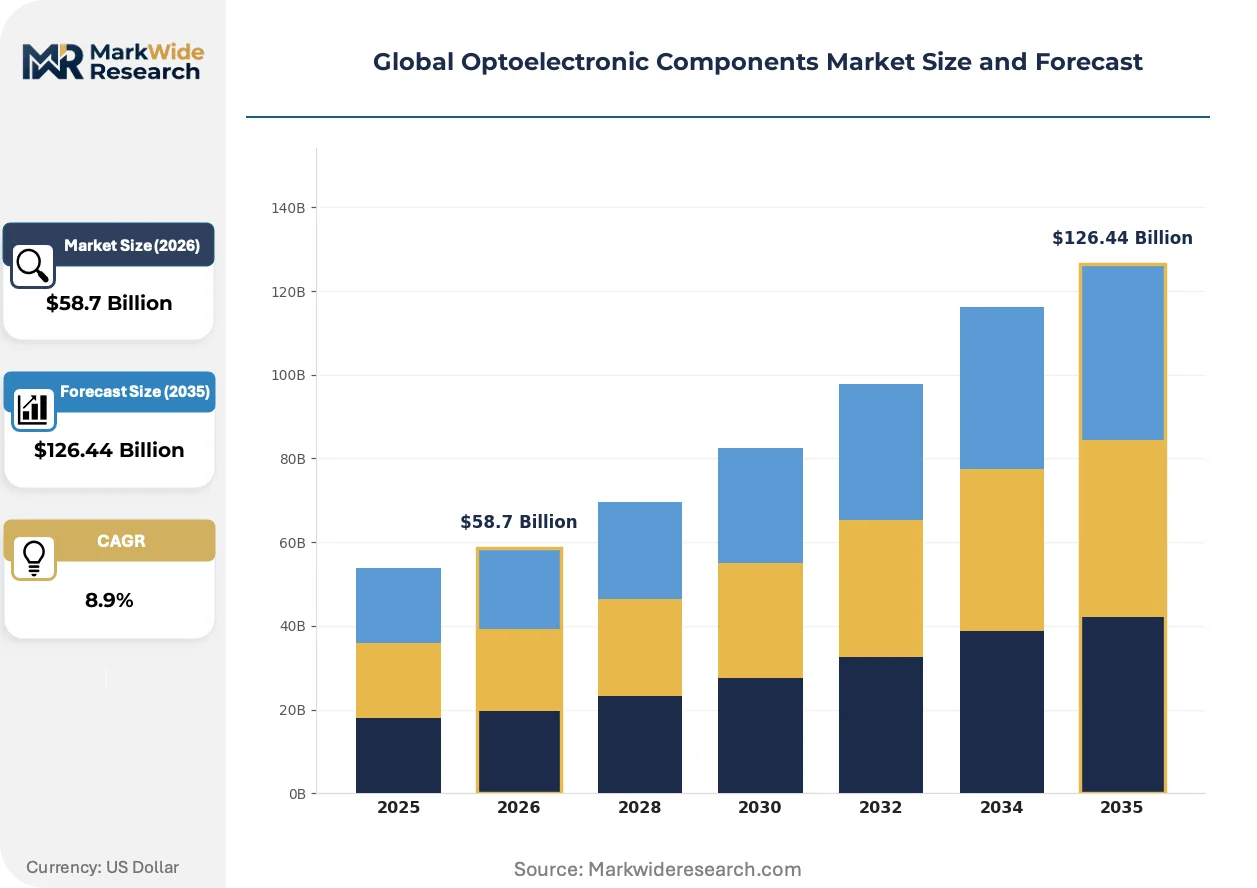
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $126.44 Billion |
| CAGR (2026 – 2036) | 8.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photodiodes, Lasers, Light Emitting Diodes, Optical Sensors, Phototransistors Technology: LED, Laser Diode, Photonic Integrated Circuits, Optical Fibers, Quantum Dots Application: Telecommunication, Consumer Electronics, Industrial Automation, Defense Systems, Scientific Research End User: Telecom Carriers, Electronics Manufacturers, Automation Providers, Military Units, Research Institutions |
| Companies Covered | Hamamatsu Photonics K.K., OSRAM Opto Semiconductors GmbH, TT Electronics, Vishay Intertechnology, ON Semiconductor, Cree, Samsung Electronics, Broadcom, ROHM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Optoelectronic Components Market Strategic Shifts & Innovations
Miniaturization and material science innovation are the defining themes in the optoelectronics sector. The push for smaller form factors with higher performance is compelling advancements in both component architecture and the underlying compound semiconductor substrates and fabrication techniques.
Silicon Photonics integrates complex optical functions directly onto silicon wafers, leveraging mature CMOS manufacturing infrastructure for cost-effective production. Data center operators and telecom equipment providers are rapidly adopting this technology for high-speed transceivers to manage exploding data traffic. This architectural shift is rendering obsolete many traditional, discrete component assemblies used in short-reach optical interconnects.
The European Union's RoHS directive imposes strict limits on hazardous materials like lead and mercury in electronic equipment. This regulation forces component manufacturers to re-engineer material compositions, particularly for solders and semiconductor substrates, to ensure compliance. The LED and laser diode segments are most affected, prompting significant R&D investment into compliant, lead-free materials to maintain access to the European market.
A notable behavioral shift is occurring as equipment manufacturers in sectors like industrial automation and automotive transition from buying individual components. These customers now increasingly prefer to procure pre-certified modules or complete subsystems that integrate optics, electronics, and the core optoelectronic device. This trend is most visible in machine vision and advanced driver-assistance systems, benefiting suppliers capable of delivering higher-level integrated solutions.
Global Optoelectronic Components Market Segmentation
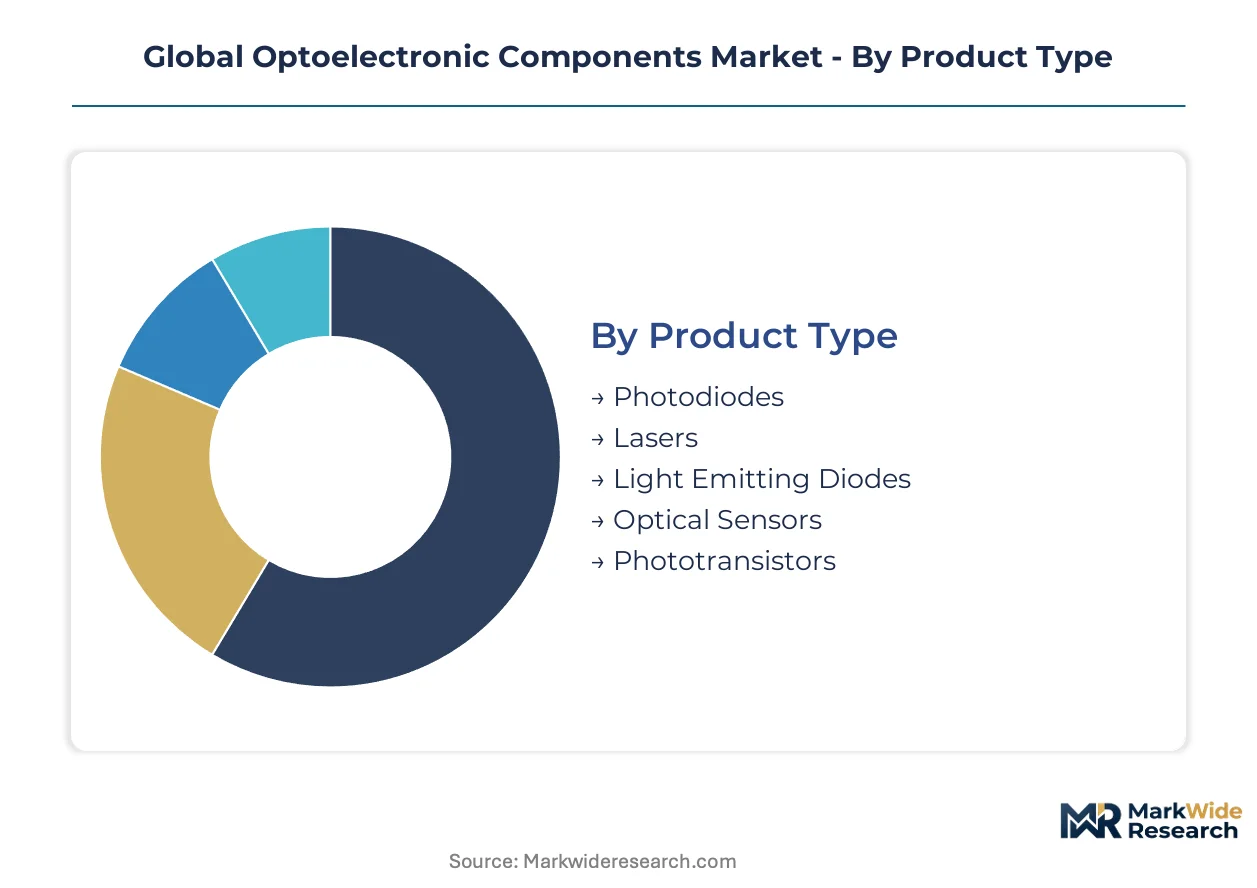
Understanding the diverse segments within the global optoelectronic components market is crucial for strategic planning. Distinct product types, technologies, applications, and end-users exhibit varied growth trajectories and demand patterns. This granular analysis reveals where innovation and investment are most impactful across the value chain.
Product Type:
The turnover rates for optoelectronic products vary significantly, from high-volume, short-lifecycle components to specialized devices with longer design cycles.
- Lasers:These devices generate coherent light through stimulated emission, offering high power density and precise wavelength control. Demand concentrates in telecommunication for high-speed data transmission and in automotive for LiDAR systems, driven by autonomous vehicle development.
- Light Emitting Diodes:LEDs convert electrical energy directly into light, known for their energy efficiency and long operational lifespan. Consumer electronics and general illumination drive significant volume, with continuous advancements in material science for improved performance.
- Photodiodes:These semiconductor devices convert light into an electrical current, finding widespread use in optical communication receivers.
- Optical Sensors:Optical sensors detect changes in light properties, enabling precise measurements in industrial automation and environmental monitoring.
- Phototransistors:Phototransistors amplify light-generated current, utilized in light-sensing applications requiring higher sensitivity than photodiodes.
Light Emitting Diodes dominates installed base. Lasers is where expansion concentrates.
Technology:
The technological maturity across optoelectronic components ranges from established, widely adopted platforms to nascent, high-potential innovations.
- Photonic Integrated Circuits:PICs integrate multiple optical functions onto a single chip, enabling miniaturization and power efficiency for data centers. The escalating demand for data bandwidth in telecommunication networks drives their rapid adoption for high-speed transceivers.
- Laser Diode:These semiconductor devices produce coherent light efficiently, critical for data communication, material processing, and sensing applications. Automotive LiDAR systems and advanced manufacturing processes represent significant growth areas for high-performance laser diodes.
- LED:Light Emitting Diode technology offers energy-efficient illumination and display solutions, widely adopted across consumer and industrial sectors.
- Optical Fibers:These hair-thin strands transmit light signals over long distances, forming the backbone of global telecommunication networks.
- Quantum Dots:Quantum dots are nanoscale semiconductor crystals emitting light at specific wavelengths, promising advances in display technology and biomedical imaging.
Established LED technology maintains a broad market presence. Photonic Integrated Circuits are gaining share fastest due to their disruptive integration capabilities.
Application:
The volume of optoelectronic component consumption varies dramatically across different application segments, from mass-market consumer devices to highly specialized industrial systems.
- Telecommunication:This segment requires high-speed, reliable optoelectronic components for fiber optic networks, data centers, and 5G infrastructure. The relentless pull for data bandwidth necessitates continuous innovation in transceivers and modulators.
- Industrial Automation:Optoelectronic devices are integral to machine vision, process control, and safety systems in manufacturing environments. Precision sensing and robust component designs are critical for enhancing efficiency and operational reliability.
- Consumer Electronics:Optoelectronic components enable displays, cameras, and sensors in smartphones, tablets, and smart home devices.
- Defense Systems:Military applications utilize optoelectronics for secure communication, targeting, and surveillance equipment, demanding high reliability.
- Scientific Research:Specialized optoelectronic devices are essential for spectroscopy, microscopy, and quantum experiments in academic and corporate laboratories.
Telecommunication applications represent the largest demand pool. Industrial Automation shows significant expansion potential driven by smart factory initiatives.
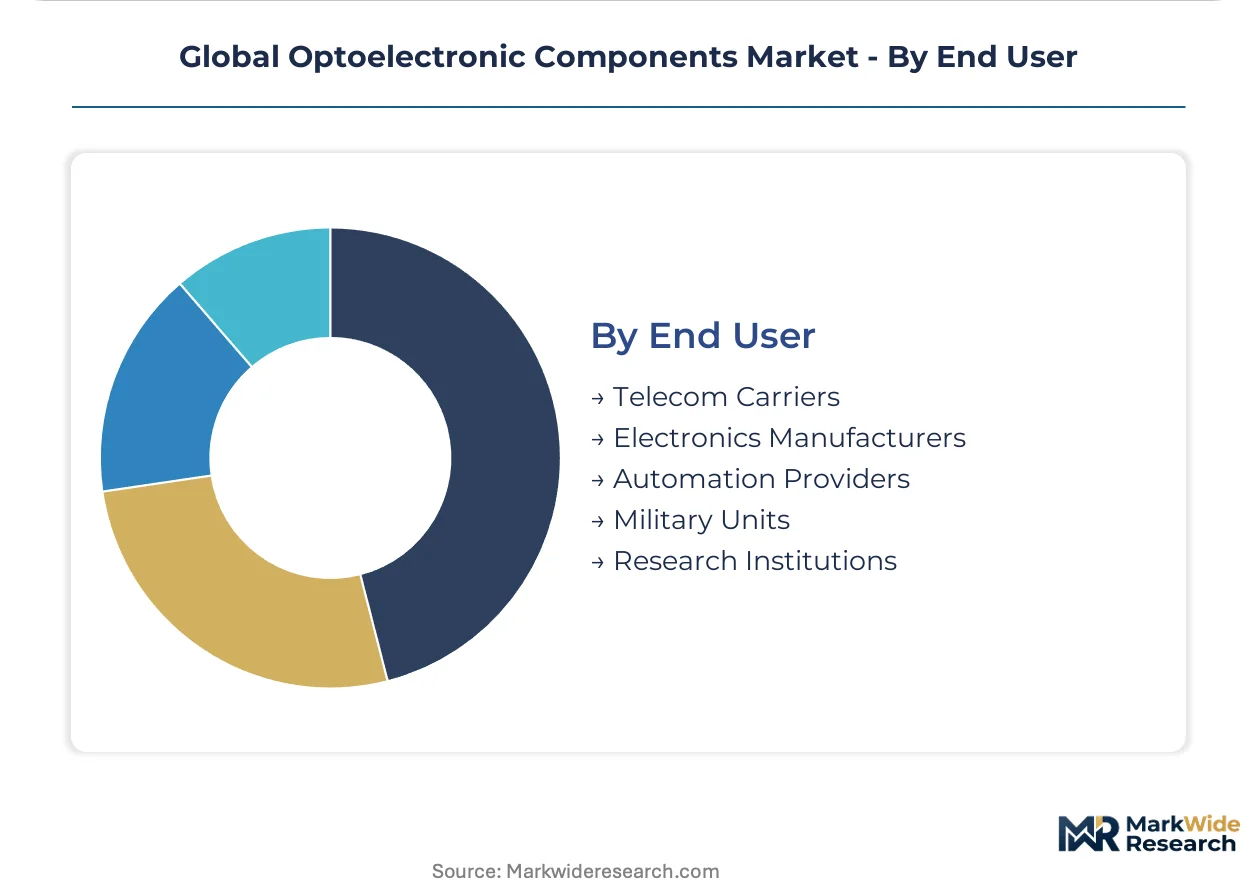
End User:
The purchasing behaviors and technical requirements of end-users shape the demand profile for optoelectronic components across various industries.
- Telecom Carriers:These operators deploy vast fiber optic networks and data centers, requiring high volumes of reliable transceivers, amplifiers, and modulators. Their procurement decisions are heavily influenced by bandwidth demand and infrastructure upgrade cycles for 5G.
- Electronics Manufacturers:Companies producing consumer electronics, automotive systems, and industrial equipment integrate optoelectronic components into their final products. Their demand focuses on miniaturization, cost-efficiency, and compliance with environmental regulations like RoHS.
- Automation Providers:These companies integrate optoelectronic sensors and vision systems into industrial robots and automated production lines.
- Military Units:Defense organizations procure optoelectronic components for secure communications, surveillance, and precision guidance systems.
- Research Institutions:Universities and private labs utilize advanced optoelectronic devices for experimental setups and scientific discovery.
Telecom Carriers remain the foundational customer segment. Electronics Manufacturers are rapidly diversifying their optoelectronic component sourcing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global supply base for optoelectronic components is concentrating in key manufacturing hubs, driven by specialized fabrication capabilities and robust domestic demand. These regions are actively shaping the industry's trajectory through strategic investments and regulatory frameworks. Market dynamics in these areas significantly influence global production and innovation.
China
China's robust domestic electronics manufacturing and extensive 5G infrastructure deployment generate substantial demand for optoelectronic components. The nation's GB standards for product quality and safety influence material sourcing and production processes. Manufacturing clusters in the Yangtze River Delta are expanding capacity for high-volume component fabrication.
South Korea
South Korea's substantial investments in semiconductor fabrication capacity drive demand for high-performance optoelectronics. Government-backed semiconductor initiatives foster advanced component development and manufacturing. The Seoul Capital Area hosts numerous R&D centers and production facilities specializing in integrated photonics.
Germany
Germany's advanced automotive industry creates significant demand for laser diodes in LiDAR systems, alongside industrial automation needs. Compliance with the European Union's RoHS directive necessitates material innovation in component manufacturing. Specialized optical engineering firms in Bavaria contribute to high-precision sensing technologies.
Japan
Japanese companies leverage specialization in high-sensitivity photodetectors for scientific and medical instruments, creating niche demand. METI policies support research and development in advanced optical materials and manufacturing processes. The Kanto region remains a hub for precision optoelectronics production and innovation.
United States
United States data centers and telecommunication networks are primary consumers of high-speed transceivers and modulators. US EPA regulations impact material sourcing and waste streams for optoelectronic component fabrication. Silicon Valley in California drives innovation in silicon photonics and integrated circuit design.
Global Optoelectronic Components Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, supplying critical optical devices. The optoelectronic components market exhibits a tiered structure, with a mix of large diversified players and niche specialists. Key strategic archetypes include integrated device manufacturers, pure-play component providers, and module assemblers. Companies pursue strategic partnerships and portfolio diversification to enhance their market reach.
Specialists in high-performance components include Hamamatsu Photonics K.K., a Japanese firm that exemplifies a pure-play provider focusing on scientific and medical instrumentation. OSRAM Opto Semiconductors GmbH, a German entity, represents an integrated device manufacturer competing on LED and laser product efficiency for diverse applications. ON Semiconductor, a US-based corporation, occupies a position with a broad portfolio catering to industrial automation and consumer electronics. These firms anchor specific segments through their distinct technological capabilities and market focus, influencing the supply dynamics across different tiers of the value chain.
| Leading Market Players |
|---|
| Hamamatsu Photonics K.K. |
| OSRAM Opto Semiconductors GmbH |
| TT Electronics |
| Vishay Intertechnology |
| ON Semiconductor |
| Cree |
| Samsung Electronics |
| Broadcom |
| ROHM |
| Others |
Cost & Logistics Intelligence
The Seoul Capital Area's advanced fabrication capacity significantly influences high-performance optoelectronics pricing. This concentration of specialized manufacturing capabilities creates a competitive environment for component suppliers, impacting margin structures for integrated circuits.
Pricing Analysis
The European Union's RoHS directive dictates the pricing tier structure for many optoelectronic components. Pricing models often involve contract-based long-term offtake agreements for high-volume components. Price differentiation stems from performance specifications and the level of customization required for specific applications. Pricing softness for commodity LEDs reflects intense competition and volume-driven manufacturing. Consumer electronics manufacturers exhibit high price sensitivity, while defense systems procurement shows lower sensitivity.
Supply Chain Analysis
Upstream feedstock sourcing for compound semiconductors like Gallium Arsenide and Indium Phosphide is critical. Geographic supply concentration centers in China, South Korea, and Japan for high-volume manufacturing. Regulatory restrictions on hazardous substances, such as those imposed by the US EPA, present a structural supply chain risk. Distribution typically involves direct sales to large telecom carriers and electronics manufacturers, supplemented by specialized distributors for niche industrial applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents an early-cycle expansion story, driven by the accelerating penetration of Photonic Integrated Circuits across data communication. Demand for high-speed data bandwidth continues to fuel this growth.
For Market Incumbents: Entrench existing market share by aggressively investing in Silicon Photonics research and development. Secure long-term supply contracts with major telecommunication carriers to stabilize volume. This strategy mitigates the threat from emerging PIC specialists and ensures access to critical sales channels. Focus on compliant material sourcing and advanced thermal management solutions.
For New Entrants and Emerging Players: Build out specialized capabilities in high-margin, niche segments like Quantum Information Systems. Target underpenetrated opportunities in advanced agricultural sensing, particularly in large agricultural economies. A focused go-to-market angle emphasizing rapid prototyping and specialized application engineering can establish early market presence. Leverage intellectual property in novel material science.
For Investors and Strategic Acquirers: Long-term, this sits as a technology-driven growth play because fundamental shifts in data infrastructure and sensing are ongoing. Identify pure-play component providers with strong intellectual property in Photonic Integrated Circuits or quantum dot technology. The commercialization milestones for Micro-LED display technology represent a key signal to watch for broader market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| PIC Design and Fabrication Investment | Accelerates miniaturization and power efficiency, essential for next-generation data center interconnects and telecom networks. |
| Sustainable Material R&D | Ensures compliance with evolving environmental regulations like RoHS, maintaining market access in key regions. |
| Specialized Photonic Engineering Talent Development | Addresses the critical talent gap, fostering innovation and enabling manufacturing scale-up for complex devices. |
| Integrated Module Offering Expansion | Meets customer demand for pre-certified subsystems, simplifying integration for industrial automation and automotive applications. |
| Quantum Component IP Acquisition | Positions firms for high-margin opportunities in emerging quantum computing and communication markets. |
Research Approach
Findings reconcile primary fieldwork against secondary review of industry association reports, patent databases, government technology roadmaps, and academic journals. This process involved extensive interviews with optoelectronic engineers, telecom network architects, automotive LiDAR developers, and material scientists. The analysis employed both bottom-up and top-down triangulation to ensure comprehensive data validation.
Forecast inputs considered demand-side drivers like 5G infrastructure deployment and supply-side capabilities across the analysis window. The analytical framework modeled segmentation dimensions including product type, technology, application, end-user, and specific wavelength range. Compound Annual Growth Rates were derived from historical growth trends and projected technology adoption curves, integrating inputs like autonomous vehicle penetration rates.
Stress conditions across global economic downturns, geopolitical trade tensions, and rapid shifts in material science were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding regulatory stability and technological evolution. Cross-checking against industry consortia reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optoelectronics
Laser Projection Market
Optoelectronics
Global Infrared Optoelectronics Market
Optoelectronics
Quantum Dot Solar Cell Market
Optoelectronics
Quantum Cascade Lasers Market
Optoelectronics
Infrared Emitter and Receiver Market
Optoelectronics
Taiwan Optoelectronics Market
Optoelectronics
Global Indium Phosphide (Inp) Wafers Market
Optoelectronics
Electro-Optical/Infrared (EO/IR) Systems Market
Optoelectronics
IT & Telecom Optoelectronics Market
Optoelectronics
Asia-Pacific Optoelectronics Market
Optoelectronics
Optoelectronic Transducers Market
Optoelectronics
Optical Emission Spectroscopy Market
Optoelectronics
Gallium Arsenide Gaas Wafer Market
Optoelectronics
Laser Diode Market
Optoelectronics
Vertical Cavity Surface Emitting Laser (Vcsels) Market
Optoelectronics
Quantum Dots Market