
 Electro-Optical/Infrared (EO/IR) Systems Market | 2026-2036
Electro-Optical/Infrared (EO/IR) Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Electro-Optical/Infrared (EO/IR) Systems Market Intelligence
A multi-sourcing approach for critical sensor components is hardening supply chain resilience for prime defense contractors. RTX Corporation leverages its extensive portfolio to offer integrated surveillance and targeting solutions. L3Harris Technologies specializes in networked systems, connecting disparate EO/IR assets across domains. Teledyne FLIR dominates the uncooled thermal imaging core segment for both military and commercial applications, demonstrating significant market control in that specific technology.
Electro-optical/infrared systems are devices that detect, process, and display energy from the visible to the infrared portions of the electromagnetic spectrum. Their primary function is to provide imaging and targeting capabilities in day, night, and adverse weather conditions. Within technology segments, uncooled detectors are expanding into new applications due to lower cost and size, while cooled detectors maintain dominance in high-performance targeting systems. Defense forces remain the principal end user sector, procuring systems for airborne, ground, and naval platforms.
Market access and technology transfer are heavily governed by national export control regimes, such as the United States' International Traffic in Arms Regulations (ITAR). Compliance with military standards (MIL-STD) in the US and NATO STANAG agreements in Europe dictates design and interoperability requirements for defense procurement. Future system viability will depend on the ability to integrate multi-spectral sensor data and counter emerging threats from sophisticated electronic warfare.
Market Dynamics
The central force shaping the EO/IR systems market is the integration of artificial intelligence with multi-domain sensor fusion. This shift transforms EO/IR devices from passive imaging tools into active, decision-making nodes within a networked defense architecture, driving new system requirements.
Growth Catalysts
- National Modernization Programs:Defense force modernization in countries like India, driven by national security mandates and border surveillance needs, creates sustained demand for advanced airborne and ground-based EO/IR platforms.
- Component Miniaturization:The decreasing size, weight, and cost of uncooled thermal imaging cores are enabling the expansion of EO/IR systems into new applications, including smaller unmanned aerial vehicles and individual soldier systems.
- Enhanced Situational Awareness:A persistent need among military end-users for superior intelligence, surveillance, and reconnaissance (ISR) capabilities in all weather conditions propels investment in next-generation, high-definition EO/IR sensors.
Market Restraints
- Export Control Regimes:Technology transfer is heavily restricted by regulations such as the United States' International Traffic in Arms Regulations (ITAR), which limits market access and complicates international co-development programs.
- High Input Costs:The production of high-performance cooled infrared detectors relies on expensive and supply-constrained materials, such as high-purity germanium and indium antimonide, creating a high cost floor for premium systems.
- Vulnerability to Countermeasures:The effectiveness of EO/IR systems can be degraded by emerging electronic warfare techniques and sophisticated obscurants, creating a constant need for costly counter-countermeasure development.
Strategic Opportunities
- Commercial Market Diversification:Adapting military-grade thermal imaging technology for commercial applications, such as industrial inspection, autonomous vehicle navigation, and public safety, opens significant new revenue streams.
- Multi-Spectral Sensor Fusion:There is a growing opportunity to develop systems that combine data from EO/IR, short-wave infrared (SWIR), and other sensor modalities to provide more complete and actionable intelligence.
- Unmanned Systems Integration:The proliferation of unmanned platforms across air, ground, and sea domains creates a vast addressable market for compact, lightweight, and power-efficient EO/IR payloads specifically designed for autonomous operation.
Industry Challenges
- Legacy System Integration:Integrating modern EO/IR pods with the avionics and power systems of older aircraft and vehicles presents significant engineering hurdles and unforeseen costs, slowing fleet-wide upgrades. *Interoperability Standards: Ensuring seamless data exchange between EO/IR systems from different manufacturers and across allied forces requires strict adherence to evolving NATO STANAG agreements, complicating system design.
- Specialized Talent Scarcity:A shortage of engineers with dual expertise in optical physics and machine learning algorithm development constrains the pace of innovation in AI-driven automated target recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electro-Optical/Infrared (EO/IR) Systems Market |
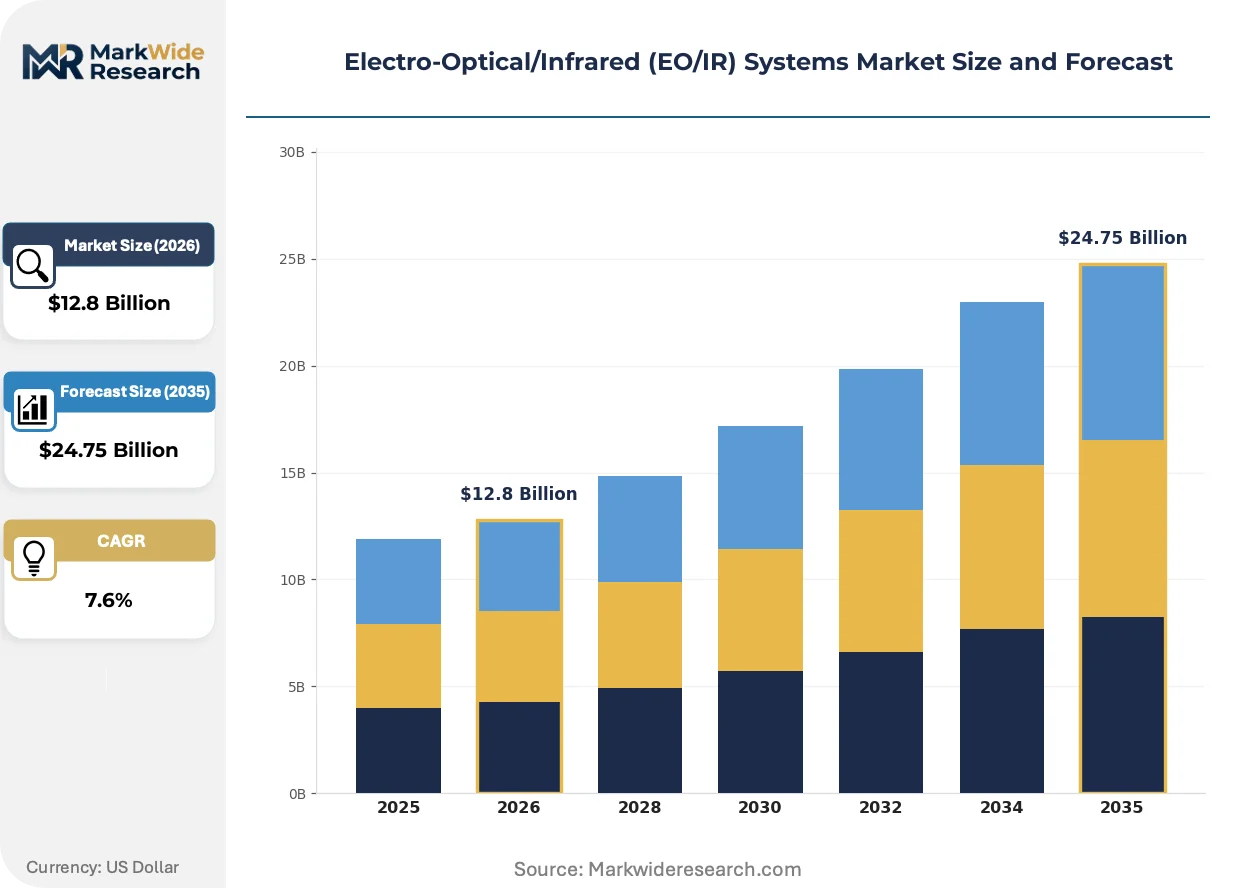
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $24.75 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Thermal Imaging, Night Vision, Laser Rangefinder, Targeting System, Surveillance Camera Technology: Cooled Detectors, Uncooled Detectors, Infrared Sensors, Image Intensifiers, Focal Plane Arrays Application: Border Security, Maritime Navigation, Firefighting Operations, Wildlife Monitoring, Search & Rescue End User Sector: Defense Forces, Aerospace Manufacturers, Environmental Agencies, Emergency Responders, Research Institutions |
| Companies Covered | Leonardo S.p.A., RTX Corporation, L3Harris Technologies, Elbit Systems, Lockheed Martin Corporation, Teledyne FLIR, Northrop Grumman, Excelitas Technologies, BAE Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electro-Optical/Infrared (EO/IR) Systems Market Strategic Shifts & Innovations
The functional role of electro-optical systems is evolving from mere data collection to automated information processing at the tactical edge. This evolution is driven by onboard computing and algorithmic advancements that enable new operational concepts. Systems are becoming key nodes in a wider network.
Onboard edge computing is a defining technological shift. These powerful, compact processors integrated directly within sensor turrets allow for real-time data analysis without reliance on a separate ground station. Defense operators of unmanned systems are rapidly adopting this for autonomous surveillance and targeting missions. The technology is automating target classification and threat prioritization, which significantly reduces the cognitive burden on human operators.
Regulatory frameworks like the EU AI Act are beginning to influence system design, even for defense-related technologies. The legislation establishes rules for AI systems based on risk, mandating transparency and human oversight for certain applications. This directly impacts the development of automatic target recognition algorithms, compelling manufacturers selling into or partnering with European nations to incorporate principles of explainability and ethical control.
A notable demand-side shift involves customers acquiring ISR capabilities as a managed service rather than just purchasing hardware. This model disrupts the traditional equipment sales cycle, with defense organizations contracting for guaranteed data delivery and system availability. The trend is most apparent in large-scale aerial surveillance programs in the United States and allied nations, where contractors are responsible for the entire operational lifecycle.
Electro-Optical/Infrared (EO/IR) Systems Market Segmentation
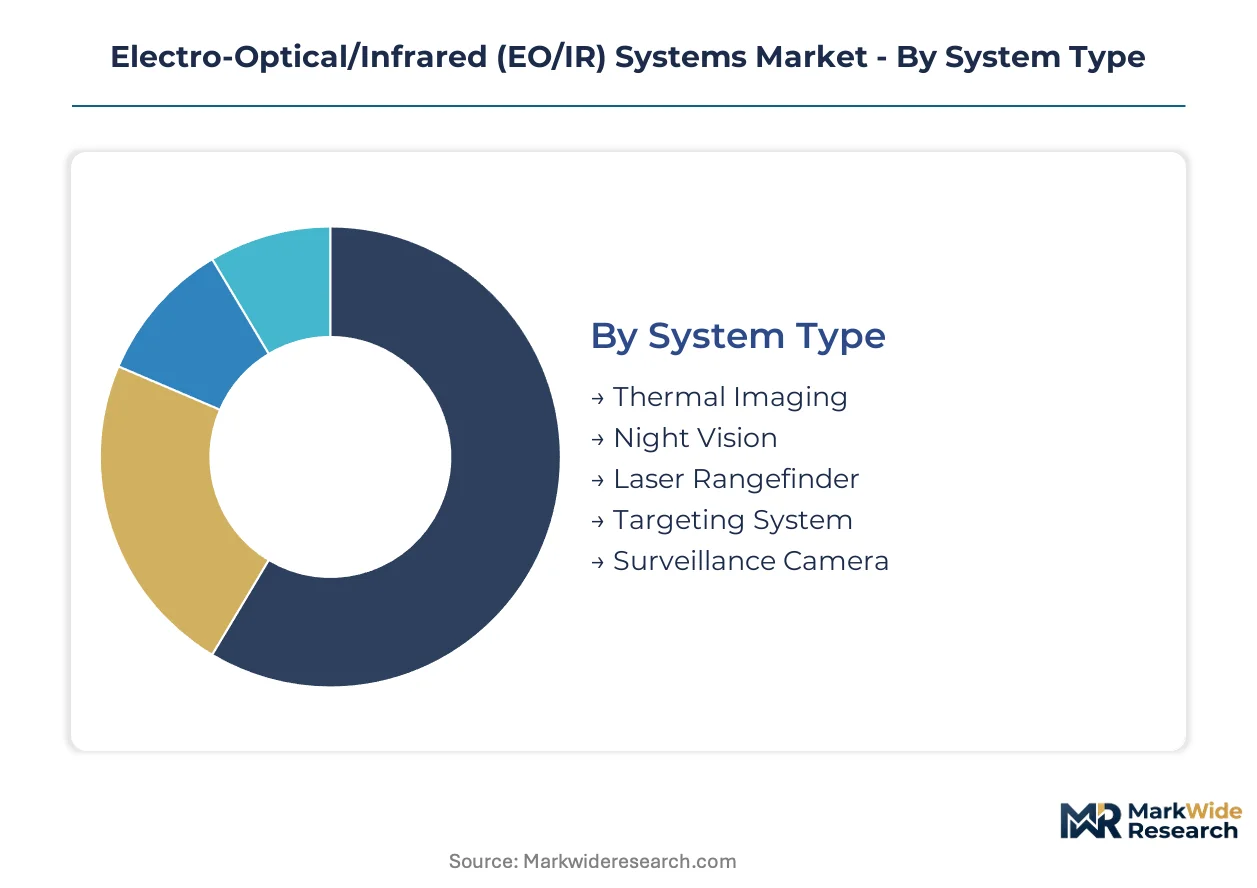
The Electro-Optical/Infrared (EO/IR) Systems market dissects into distinct segments, each driven by specific technological capabilities and end-user requirements. Understanding these classifications reveals where innovation is concentrating and where market opportunities are emerging. Performance demands and operational environments define the utility of each system type.
System Type:
Supply of advanced EO/IR systems is concentrating around specialized manufacturers capable of delivering integrated solutions across various system types. These manufacturers often control proprietary sensor designs and processing algorithms, influencing market availability.
- Thermal Imaging:These systems detect infrared radiation, forming images based on temperature differences, crucial for covert operations and adverse weather. Demand is robust in military intelligence, surveillance, and reconnaissance (ISR) applications.
- Targeting System:Integrating multiple sensors, these systems precisely identify, track, and designate targets for weapon engagement or intelligence gathering. National defense modernization programs in India drive demand for advanced solutions.
- Night Vision:These devices amplify ambient light or convert infrared energy into visible light for operation in low-light conditions.
- Laser Rangefinder:These systems accurately measure distances to targets using pulsed laser beams, critical for precision targeting and navigation.
- Surveillance Camera:High-resolution cameras, often with EO/IR capabilities, provide continuous monitoring for security and intelligence purposes.
Today's leader: Thermal Imaging. Tomorrow's challenger: Targeting System.
Technology:
The cost tier of EO/IR systems is heavily influenced by the underlying detector technology, with high-performance solutions commanding premium pricing due to complex manufacturing and specialized materials. This differentiation impacts accessibility and application scope.
- Cooled Detectors:These high-performance detectors operate at cryogenic temperatures, offering superior sensitivity, resolution, and detection range for long-range surveillance. Defense forces require these for high-end airborne and naval platforms.
- Uncooled Detectors:Operating at ambient temperatures, these detectors are smaller, lighter, and more cost-effective, expanding EO/IR into commercial and compact military applications. Demand is expanding rapidly for unmanned aerial vehicles.
- Infrared Sensors:These devices detect infrared radiation, forming the core component of thermal imaging and other heat-sensing systems.
- Image Intensifiers:These technologies amplify available light, enabling night vision capabilities primarily in the visible and near-infrared spectrum.
- Focal Plane Arrays:A matrix of individual detector elements, these arrays are crucial for capturing detailed thermal images across various EO/IR systems.
Uncooled Detectors are expanding most quickly, while Cooled Detectors maintain performance leadership.
Application:
The specific problem an EO/IR system is designed to solve dictates its configuration and performance requirements, influencing the integration of sensor modalities and processing capabilities. Diverse applications drive specialized product development.
- Border Security:EO/IR systems provide persistent surveillance and detection capabilities along national borders, identifying incursions in all weather conditions. National security priorities in the United States and India drive significant investment.
- Search & Rescue:These applications leverage thermal imaging to locate individuals in challenging environments, including smoke, darkness, or dense foliage. Emergency responders use these systems for rapid victim identification.
- Maritime Navigation:EO/IR systems enhance situational awareness for vessels, detecting obstacles, other ships, and hazards in low visibility conditions.
- Firefighting Operations:Thermal cameras assist firefighters by revealing heat sources, hot spots, and trapped individuals through smoke.
- Wildlife Monitoring:Researchers and conservationists use EO/IR for non-invasive animal observation, population counts, and anti-poaching efforts.
Border Security is gaining share fastest, propelled by geopolitical tensions and surveillance needs.
End User Sector:
The nature of the customer type significantly shapes procurement cycles, compliance requirements, and the demand for specific performance characteristics in EO/IR systems. Military standards and regulatory frameworks often dictate design and interoperability.
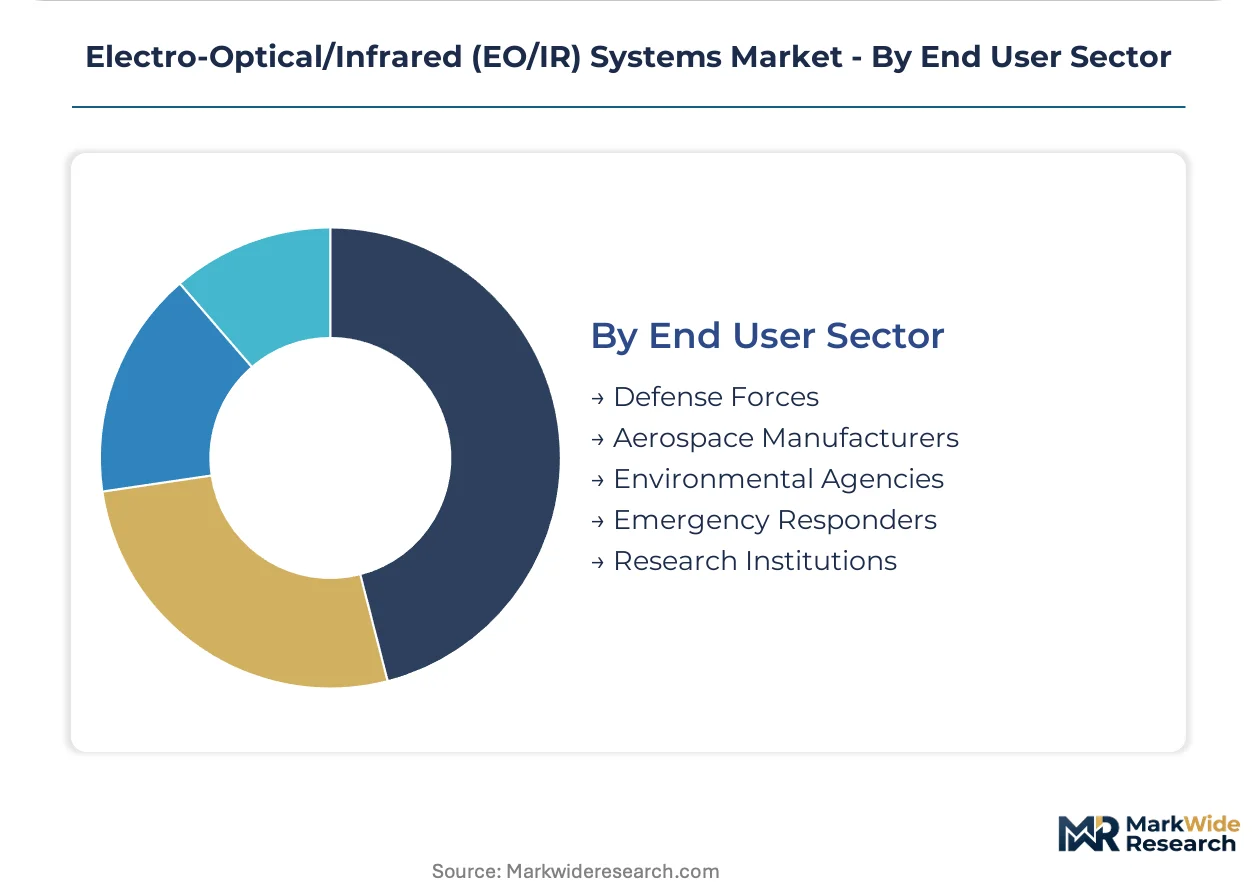
- Defense Forces:As the principal end-user, military organizations procure EO/IR systems for airborne, ground, and naval platforms to enhance intelligence, surveillance, and targeting capabilities. Modernization programs are a continuous demand driver.
- Emergency Responders:Police, fire departments, and search & rescue teams utilize EO/IR technology for situational awareness, evidence collection, and locating individuals in hazardous conditions. Public safety initiatives are expanding this segment.
- Aerospace Manufacturers:These companies integrate EO/IR systems into aircraft and unmanned platforms, often as prime contractors for defense programs.
- Environmental Agencies:Agencies use EO/IR for monitoring pollution, detecting wildfires, and tracking wildlife populations across vast areas.
- Research Institutions:Universities and government labs employ EO/IR systems for scientific study, technology development, and sensor testing.
Defense Forces maintain the largest share, while Emergency Responders are on the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of advanced EO/IR systems experiences regulatory arbitrage, with manufacturing often migrating to regions offering more favorable compliance landscapes. This dynamic influences investment decisions and supply chain configurations across the market. Global defense modernization efforts further shape regional demand.
United States
Demand for high-performance EO/IR systems in the United States is driven by national security priorities and ongoing defense modernization initiatives. The International Traffic in Arms Regulations (ITAR) strictly governs technology transfer and export controls. Major defense contractors in Southern California and the Washington D.C. metropolitan area innovate advanced sensor and targeting solutions.
India
India's significant defense modernization programs and critical border surveillance needs create sustained demand for advanced EO/IR platforms. The country's Defence Acquisition Procedure (DAP) promotes indigenous manufacturing and technology partnerships. Clusters in Bengaluru and Hyderabad are becoming hubs for defense electronics, fostering local development.
Germany
Modernization efforts within the Bundeswehr and NATO interoperability requirements drive demand for sophisticated EO/IR systems. Compliance with the EU AI Act influences ethical design and deployment of automated target recognition algorithms. Aerospace and defense firms in Bavaria and Baden-Württemberg focus on precision optics and integrated sensor suites.
France
French defense procurement emphasizes advanced intelligence, surveillance, and reconnaissance (ISR) capabilities for military operations. National export control regimes closely monitor the transfer of sensitive EO/IR technologies. Industrial zones around Toulouse and Paris host key players developing multi-spectral sensor fusion and targeting systems.
Japan
Japan's increasing focus on maritime security and air defense drives investment in high-definition EO/IR systems for surveillance. The country's export control regulations are evolving to support defense equipment transfers to allied nations. Major electronics and defense manufacturers in Tokyo and Nagoya contribute to domestic sensor technology advancements.
Electro-Optical/Infrared (EO/IR) Systems Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue niche applications and advanced AI-driven analytics. The market structure exhibits a blend of consolidation among prime contractors and fragmentation within specialized component suppliers. Strategic archetypes include integrated defense solution providers, sensor technology specialists, and software-centric analytics firms. Dominant competitive moves involve portfolio diversification and strategic partnerships to enhance system integration capabilities.
Companies like RTX Corporation and L3Harris Technologies exemplify the integrated defense solution provider archetype, offering comprehensive surveillance and targeting solutions across multiple domains. These entities leverage their broad capabilities to deliver networked systems, connecting disparate EO/IR assets for enhanced situational awareness. Teledyne FLIR, a prominent name, occupies a position as a specialist in thermal imaging technology, particularly dominating the uncooled detector segment. This firm's focus on specific sensor technology underpins its control in that particular niche for both military and commercial applications. These players anchor the market through their extensive product portfolios and established customer relationships across various defense and commercial sectors.
| Leading Market Players |
|---|
| Leonardo S.p.A. |
| RTX Corporation |
| L3Harris Technologies |
| Elbit Systems |
| Lockheed Martin Corporation |
| Teledyne FLIR |
| Northrop Grumman |
| Excelitas Technologies |
| BAE Systems |
| Others |
Cost & Logistics Intelligence
Defense forces, as the primary buyer archetype, drive a project-based pricing model for complex EO/IR systems, where custom integration and long-term support contracts are standard.
Pricing Analysis
Original equipment manufacturer (OEM) discounts significantly influence the final system cost for prime contractors. Project-based pricing dominates for high-performance EO/IR systems, reflecting extensive customization and integration efforts. Performance tier and compliance with MIL-STD or NATO STANAG agreements are key price differentiation drivers. Pricing softness affects the uncooled detector segment due to component miniaturization and increasing competition, while defense forces remain less price-sensitive for mission-critical cooled systems.
Supply Chain Analysis
High-value component logistics costs significantly impact the final price of EO/IR systems, particularly for specialized optics and detectors. Geographic supply concentration for critical materials like high-purity germanium and indium antimonide centers in countries like China and Australia. Single-source vulnerability for cooled detector components presents a significant supply chain risk. Distribution runs through direct sales channels to defense ministries and aerospace manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EO/IR systems market acts as a regulatory compounder, with the EU AI Act driving demand for ethical design and explainability in automated target recognition algorithms.
For Market Incumbents: Cement leadership through continuous investment in multi-spectral sensor fusion R&D to counter emerging electronic warfare techniques. Pursue backward integration into critical material supply chains to mitigate single-source vulnerability, leveraging extensive portfolios like RTX Corporation. Expand capabilities in edge computing for autonomous systems, addressing the threat from specialized software-centric analytics firms. Focus on MIL-STD and NATO STANAG compliance to reinforce interoperability across allied forces.
For New Entrants and Emerging Players: Individual soldier systems represent an underserved buyer archetype for compact, low-cost EO/IR solutions. Target commercial market diversification in industrial inspection and autonomous vehicle navigation to establish new revenue streams. Focus on uncooled detector technology for smaller unmanned aerial vehicles in emerging markets like India. A direct-to-developer go-to-market angle for AI-powered analytics can capture early adopters.
For Investors and Strategic Acquirers: Aerospace manufacturers are the most active acquirers in this space, seeking to integrate advanced EO/IR capabilities into their platforms. Long-term viability rests on the ability to deliver multi-domain networked systems over the next decade. Acquisition targets include specialized firms in AI-driven analytics and compact, power-efficient sensor payloads. The signal to watch is successful integration of multi-spectral data fusion into operational defense programs.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-spectral Sensor Fusion Development | Enhances intelligence, surveillance, and reconnaissance capabilities for defense forces in complex environments. |
| Edge AI Processor Integration | Enables real-time data analysis and automated target recognition directly on unmanned platforms. |
| Critical Material Supply Chain Control | Hardens resilience against single-source vulnerabilities for high-performance cooled detectors. |
| Commercial Thermal Imaging Adaptation | Diversifies revenue streams by applying military-grade technology to industrial and public safety applications. |
| NATO STANAG Interoperability Certification | Ensures seamless data exchange and operational compatibility across allied defense systems. |
Research Approach
Direct dialogue with defense procurement officers, aerospace engineers, sensor technology developers, and commercial application specialists informed primary research. This qualitative grounding combined with extensive secondary validation, including military procurement reports, technology whitepapers, and corporate financial filings. Bottom-up and top-down triangulation ensured robust data points for market sizing and trend analysis.
Market volume and value projections emerged from a comprehensive analytical framework applied over the projection horizon. Segmentation dimensions modeled included system type, technology, application, and end user sector, alongside regional demand patterns. Compound annual growth rates were derived from historical data analysis and future trend projections. National defense budgets and technology roadmap investments served as key industry-specific forecast inputs.
Underlying measurement precision varies by segment; Cooled Detectors and Defense Forces carry tighter precision than others. Forecasts reflect assumptions regarding geopolitical stability and technological advancements. Geopolitical shifts or unforeseen regulatory changes could revise projections. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optoelectronics
Gaas Photodiode Market
Optoelectronics
Americas Optoelectronics Market
Optoelectronics
Thermophotovoltaics Market
Optoelectronics
Global Infrared Optoelectronics Market
Optoelectronics
EPON ONU Market
Optoelectronics
3D Projector Market
Optoelectronics
Vertical Cavity Surface Emitting Laser (Vcsels) Market
Optoelectronics
Europe Optoelectronics Market
Optoelectronics
Gallium Arsenide Gaas Wafer Market
Optoelectronics
Quantum Dots Market
Optoelectronics
Global Opto-Isolator Market
Optoelectronics
Light Projector Market
Optoelectronics
Integrated Circuit Optocouplers Market
Optoelectronics
China Optical Detector Market
Optoelectronics
Optical Pulse Sensor Market
Optoelectronics
Optoelectronic Development Tools Market