
 Global Infrared Optoelectronics Market | 2026-2036
Global Infrared Optoelectronics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Infrared Optoelectronics Market Foresight
Aftermarket service revenue for infrared sensor calibration and detector replacement is tilting toward original equipment manufacturers with captive service networks. Hamamatsu Photonics leverages its vertically integrated photodetector fabrication to capture recurring maintenance contracts across Japanese and European research laboratories. Vishay Intertechnology anchors its position through broad distribution control over standard infrared emitters used in consumer proximity sensing. ROHM Co., Ltd. specializes in compact infrared laser diodes for automotive LiDAR, competing against larger compound semiconductor foundries.
Infrared optoelectronics encompasses semiconductor devices that generate, detect, or manipulate electromagnetic radiation in wavelengths from 700 nanometers to 1 millimeter, typically fabricated from III-V compounds such as indium gallium arsenide or mercury cadmium telluride operating at cryogenic or ambient temperatures. These components serve as the sensory and signaling backbone for thermal imaging, spectroscopic gas analysis, optical communications, and autonomous navigation systems where visible-light performance fails. Photodetectors and infrared lasers command the dominant share of product-type revenue, driven by defense imaging contracts and automotive LiDAR adoption, while microbolometer arrays within the technology dimension are displacing cooled alternatives in commercial thermal cameras due to lower unit cost and reduced power budgets. The surveillance and industrial automation application segments exhibit the steepest growth trajectories, though fire detection retains mature, replacement-driven demand patterns with compressed margins.
The U.S. FDA regulates infrared therapeutic devices under 21 CFR 890, while the EPA enforces emissions-monitoring standards that mandate infrared gas analyzers for continuous compliance reporting at petrochemical facilities. EASA and FAA certification requirements for airborne infrared collision-avoidance and enhanced vision systems shape product development roadmaps and testing protocols for aerospace suppliers. Stakeholders must monitor how evolving automotive safety regulations in Germany and Japan redefine detector sensitivity thresholds before committing to next-generation wafer process designs.
Market Dynamics
Defense procurement cycles in the United States are compressing development timelines for cryogenically cooled infrared detectors, forcing foundries to reconfigure wafer capacity before next-generation targeting systems reach field deployment.
Growth Catalysts
- Automotive LiDAR mandates:Germany's KBA is tightening pedestrian-detection requirements for Level 3 autonomy, compelling OEMs to source 1550-nanometer infrared laser diodes from qualified compound semiconductor suppliers.
- EPA emissions monitoring:Continuous compliance reporting at Texas and Louisiana petrochemical corridors is mandating infrared gas analyzers for methane leak detection, creating installed-base expansion.
- Microbolometer cost curves:Uncooled focal plane arrays fabricated on 12-inch CMOS lines are penetrating commercial thermal imaging, displacing legacy pyroelectric sensors in building automation.
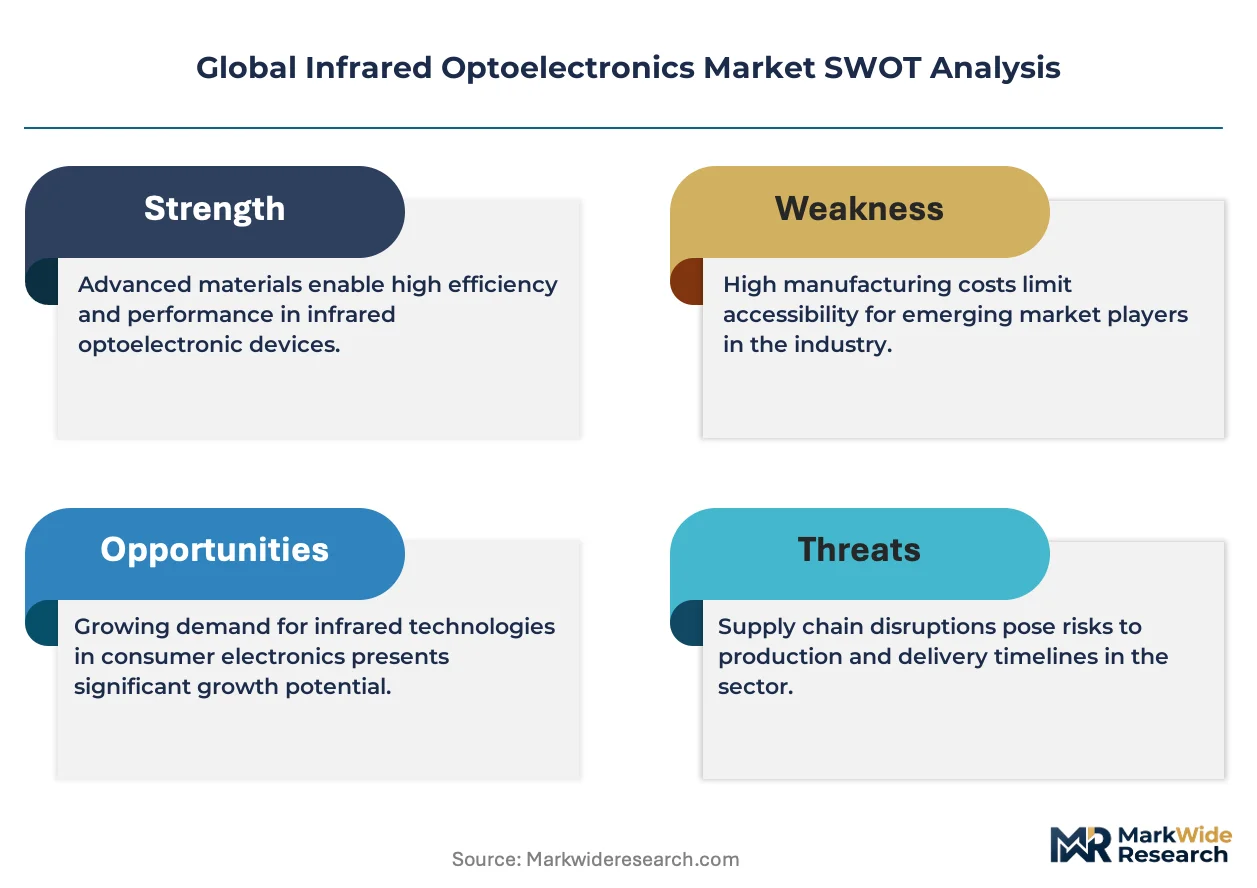
Market Restraints
- Mercury cadmium telluride supply concentration:Epitaxial growth of MCT wafers for long-wave detection remains concentrated among three qualified foundries, exposing defense contractors to single-source risk.
- Indium price volatility:The critical dopant for InGaAs photodetectors fluctuates with solar panel manufacturing demand, compressing margins on short-wave infrared components.
- RoHS substance restrictions:European REACH annex revisions are phasing out lead-based solder alternatives for high-reliability optoelectronic packaging, forcing qualification of new interconnect materials.
Strategic Opportunities
- India industrial automation:PLI scheme incentives for electronics manufacturing are attracting infrared sensor packaging investments to serve domestic steel and cement process-control demand.
- EU AI Act compliance:Safety-critical optoelectronic subsystems for autonomous systems must demonstrate traceable performance data, creating service revenue around calibration documentation.
- Spectroscopy-communication convergence:Tunable quantum cascade lasers are bridging gas-sensing and free-space optical links, opening dual-use architectures for oilfield and datacenter applications.
Industry Challenges
- Cryogenic engineering talent scarcity:Design of Stirling-cycle coolers for cooled detectors requires specialized thermodynamic expertise concentrated among retiring defense-sector engineers.
- EASA certification timelines:Airborne enhanced vision systems face 18-24 month qualification cycles for infrared imagers, delaying revenue recognition on aerospace contracts.
- Legacy system integration friction:Modern uncooled arrays output digital video streams incompatible with analog-architecture thermal cameras in installed security infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Infrared Optoelectronics Market |
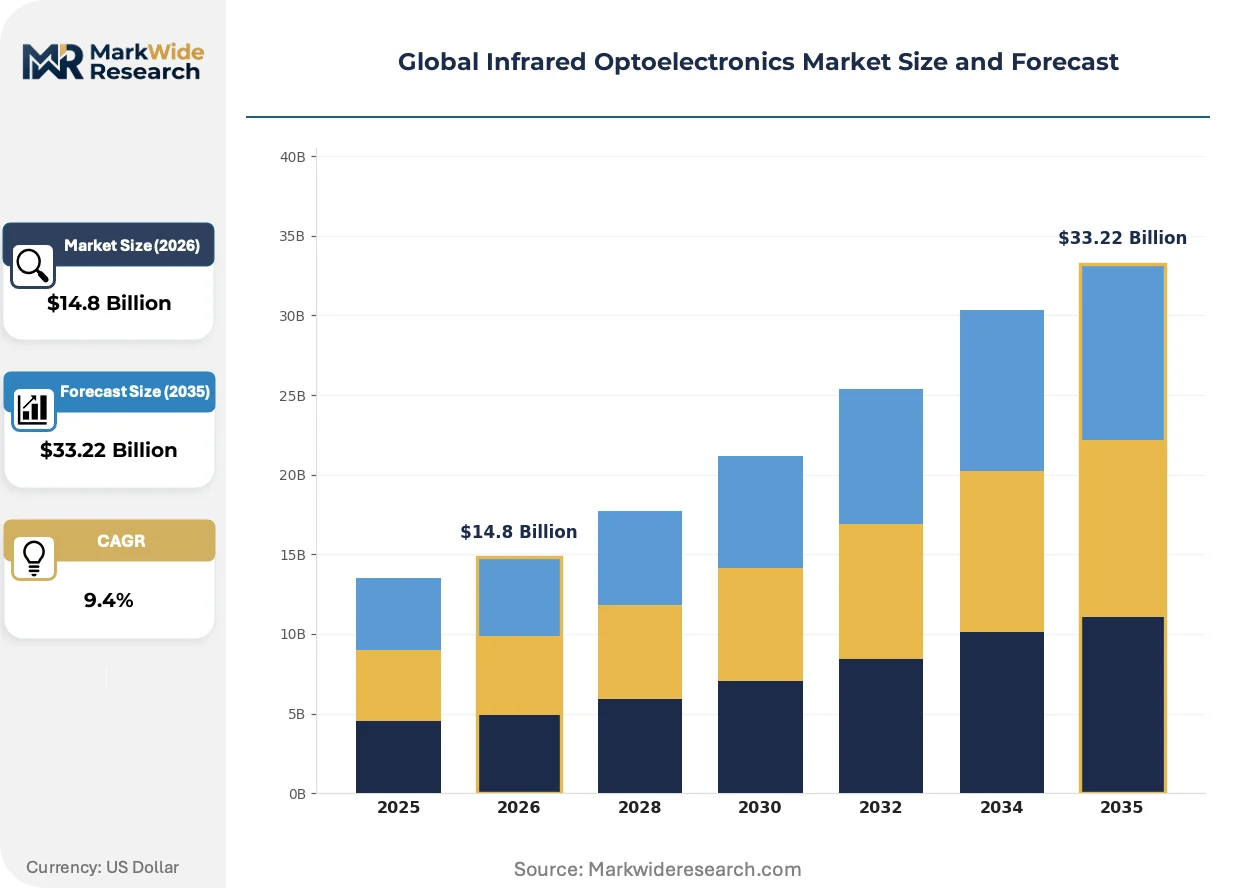
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $33.22 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photodetectors, Infrared Lasers, Sensors, Emitters, Optical Fiber Components Technology: Quantum Well, Quantum Cascade, Thermopile, Pyroelectric, Bolometer, Microbolometer Application: Surveillance, Gas Analysis, Fire Detection, Industrial Automation, Environmental Monitoring End User: Defense Contractors, Telecommunications Providers, Research Laboratories, Consumer Electronics, Aerospace Firms |
| Companies Covered | Sharp Corporation, Umicore, Vishay Intertechnology, Ophir Optronics Solutions, TAMRON, OSRAM International GmbH, ROHM Co., Ltd., Hamamatsu Photonics, Omnivision Technologies Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Infrared Optoelectronics Market Shifts & Advancements
Computational imaging algorithms are compressing hardware requirements across infrared system architectures, enabling software-defined performance upgrades without detector replacement.
Quantum cascade lasers are digitizing molecular fingerprinting for industrial process control. Food safety inspectors and pharmaceutical manufacturers are adopting benchtop infrared spectrometers at three-year refresh cycles. This technology is digitizing quality-assurance workflows, collapsing analytical chemistry turnaround times from hours to minutes.
Japan's METI is tightening energy-efficiency standards for industrial thermal imagers, mandating standby power below 2 watts for equipment deployed in manufacturing facilities. Domestic OEMs are redesigning microbolometer readout circuits to comply. The industrial automation segment faces compressed development budgets as engineering resources redirect to certification documentation.
Defense contractors are unbundling sensor hardware from integrated system sales, offering infrared detector modules separately for foreign military end-users. This procurement pattern shift disrupts traditional prime-contractor capture of full-system revenue. The trend is most visible in Middle Eastern and Southeast Asian markets where domestic integration capabilities are maturing.
Global Infrared Optoelectronics Market Segmentation
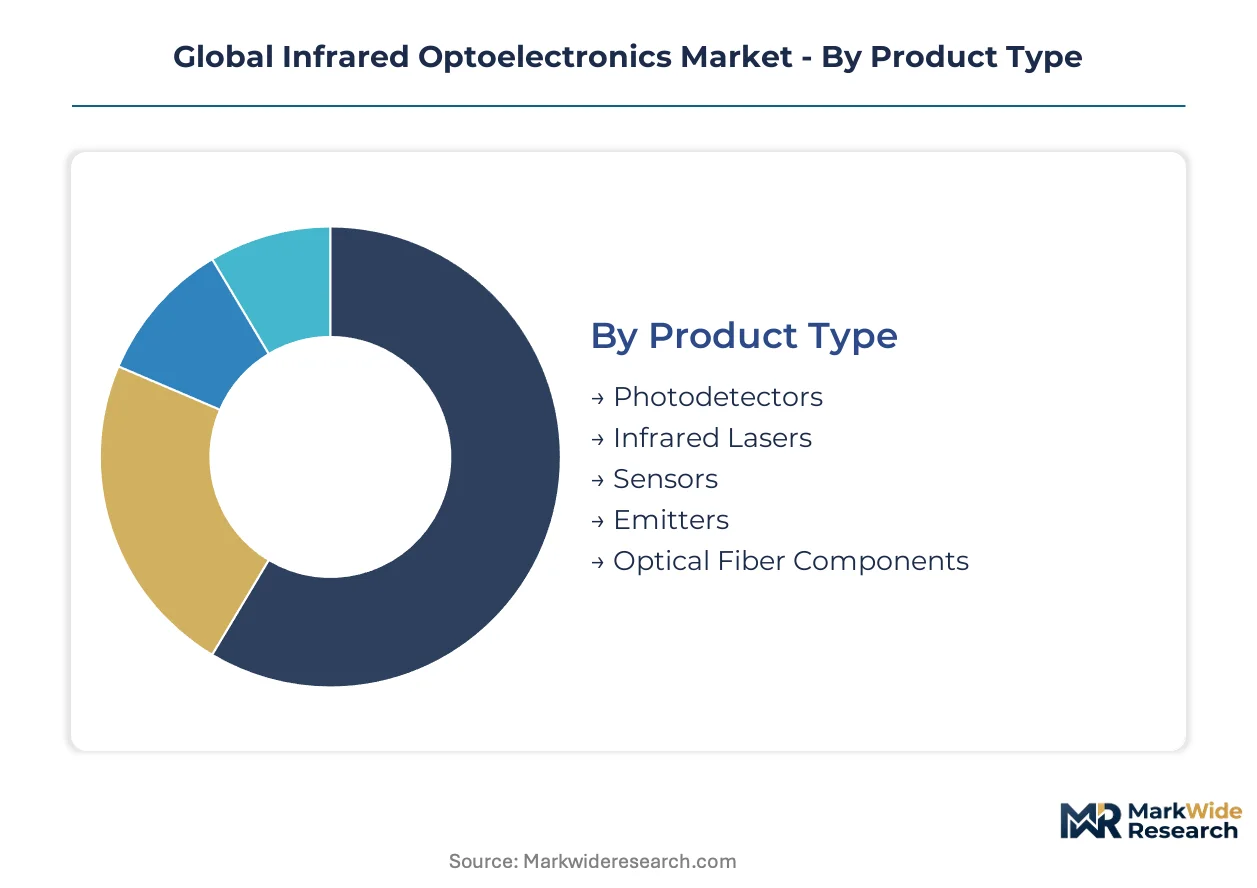
Infrared optoelectronics spans heterogeneous device physics and divergent procurement cycles. Component refresh rates range from three-year consumer proximity sensor cycles to fifteen-year defense detector programs. Understanding these temporal patterns shapes capacity planning and R&D allocation across the value chain.
Product Type:
Photodetectors and infrared lasers turn over fastest on automotive LiDAR roadmaps, while optical fiber components lock into decade-long telecommunications infrastructure commitments.
- Photodetectors:Indium gallium arsenide and mercury cadmium telluride architectures detect short-wave through long-wave infrared signatures. Defense imaging contracts in the United States and Germany concentrate demand, though indium price volatility compresses margins on InGaAs variants.
- Infrared Lasers:Edge-emitting and vertical-cavity surface-emitting structures generate coherent radiation at 905nm and 1550nm wavelengths. KBA pedestrian-detection mandates for Level 3 autonomy in Germany are accelerating 1550nm laser diode procurement from compound semiconductor foundries.
- Sensors:Integrated detector-cooler assemblies and uncooled focal plane arrays convert thermal radiation into electrical signals. Fire detection and building automation drive replacement demand with compressed pricing.
- Emitters:Light-emitting diodes and laser diodes produce incoherent and coherent infrared output for illumination and signaling. Consumer electronics proximity sensing in Japan and South Korea sustains volume production.
- Optical Fiber Components:Couplers, isolators, and amplifiers condition infrared signals in fiber-optic links. Telecommunications backbone upgrades in China and India anchor long-term supply agreements.
Photodetectors dominate installed base. Infrared lasers are where expansion concentrates.
Technology:
Cost tiers separate cryogenically cooled quantum well architectures from ambient-temperature microbolometer alternatives.
- Quantum Well:Epitaxial III-V heterostructures enable intersubband absorption for high-performance detection. Aerospace enhanced vision systems in the United States and Europe absorb premium-priced cooled arrays despite 18-24 month EASA certification timelines.
- Quantum Cascade:Unipolar intersubband lasers emit at mid-infrared wavelengths tunable across molecular absorption bands. Oilfield methane monitoring and pharmaceutical quality control are climbing the fastest for benchtop spectrometer deployment.
- Thermopile:Thermoelectric junction arrays generate voltage proportional to incident infrared flux. Non-contact temperature measurement in German automotive assembly lines sustains steady demand.
- Pyroelectric:Polarization changes in ferroelectric crystals detect thermal variation. Legacy security motion detectors face displacement by microbolometer alternatives.
- Bolometer:Temperature-dependent resistance changes in metal or semiconductor films measure radiant power. Scientific instrumentation retains niche applications despite higher noise floors.
- Microbolometer:CMOS-fabricated uncooled focal plane arrays achieve thermal sensitivity below 50 millikelvin. Commercial thermal imaging in Japan is gaining share fastest as METI standby power regulations below 2 watts reshape readout circuit designs.
Microbolometer volumes scale on consumer cost curves. Quantum cascade is where technology investment concentrates.
Application:
Customer maturity separates surveillance procurement with defined upgrade cycles from emerging environmental monitoring specifications still stabilizing.
- Surveillance:Thermal imaging and night-vision systems for perimeter security and law enforcement. Middle Eastern and Southeast Asian defense ministries are unbundling sensor hardware from integrated systems, shifting procurement toward standalone detector modules.
- Gas Analysis:Spectroscopic identification of molecular species through infrared absorption fingerprinting. EPA methane leak detection mandates at Texas and Louisiana petrochemical facilities are expanding installed base most rapidly.
- Fire Detection:Flame and hotspot sensing in industrial facilities and transportation infrastructure. Mature replacement markets in Europe operate on compressed margins with limited technology differentiation.
- Industrial Automation:Process monitoring, predictive maintenance, and robotic guidance through thermal signature analysis. Bavarian and Baden-Württemberg manufacturing clusters in Germany anchor component demand.
- Environmental Monitoring:Atmospheric sensing and emissions compliance verification. Continuous reporting requirements under EPA and EU F-Gas Regulation are standardizing analyzer specifications.
Fire detection dominates installed base. Gas analysis is where regulatory compliance concentrates expansion.
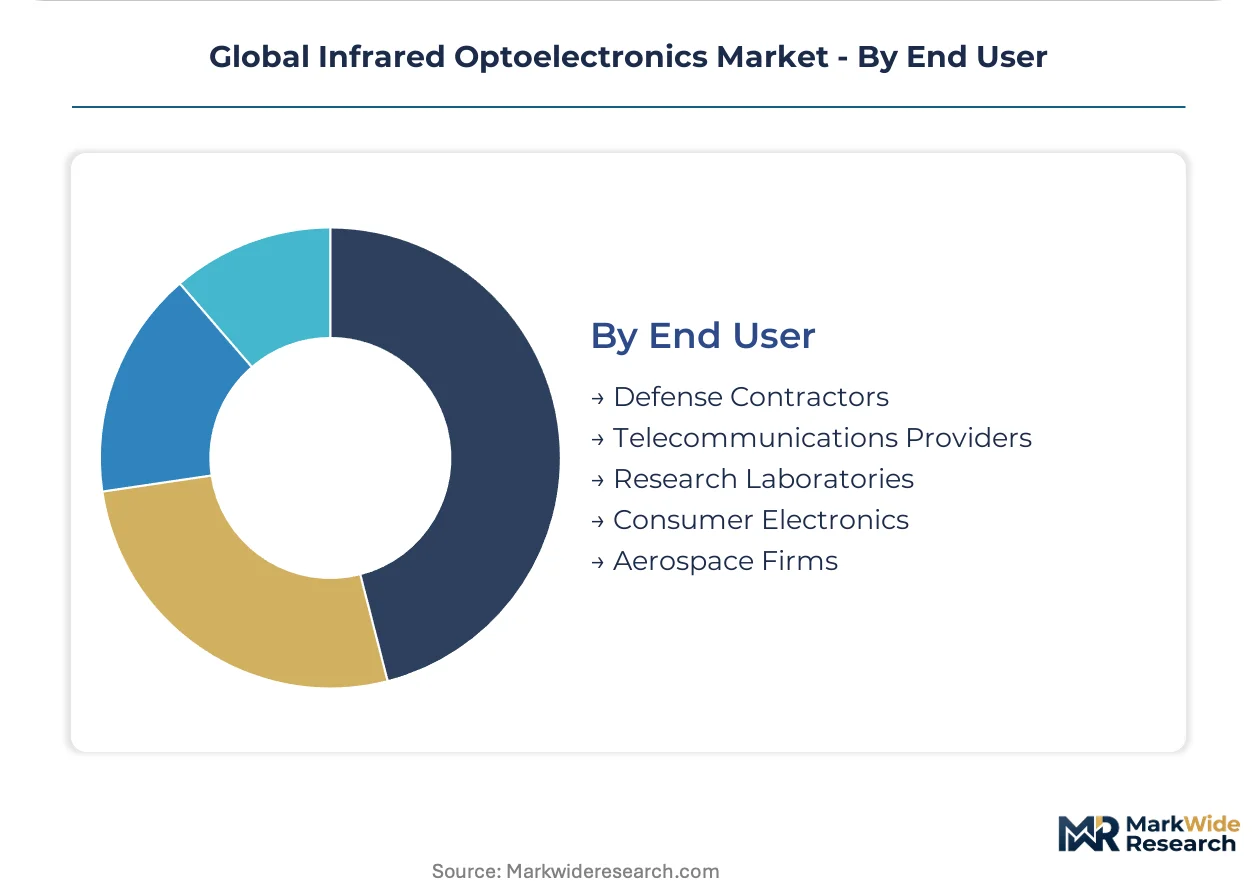
End User:
Volume concentration varies from fragmented consumer electronics to consolidated defense procurement with captive qualification requirements.
- Defense Contractors:Prime integrators and subsystem suppliers for military imaging and targeting. United States procurement cycles are compressing development timelines for cryogenically cooled detectors, forcing foundry reconfiguration ahead of field deployment.
- Telecommunications Providers:Fiber-optic network operators and equipment manufacturers. Long-haul and datacenter interconnect demand in China and India shapes optical component roadmaps.
- Research Laboratories:Academic and government facilities requiring calibrated photodetection for spectroscopy and imaging. Japanese and European facilities are tilting service revenue toward OEMs with captive calibration networks.
- Consumer Electronics:Smartphone, wearable, and home automation OEMs integrating proximity and gesture sensing. Standard infrared emitter procurement runs through broad distribution channels with limited supplier stickiness.
- Aerospace Firms:Commercial and military aircraft manufacturers certifying enhanced vision and collision-avoidance systems. EASA and FAA qualification protocols extend revenue recognition timelines.
Defense contractors dominate premium pricing. Industrial automation end-users are where volume expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wafer fabrication for cryogenically cooled detectors concentrates among qualified foundries in the United States, Germany, and Japan, while packaging and module assembly disperses toward lower-cost manufacturing zones in Southeast Asia and India. Defense procurement cycles and automotive safety mandates in specific national markets drive regional demand differentiation.
United States
Defense contractors in Texas and Arizona are compressing development timelines for next-generation targeting systems, forcing foundry reconfiguration ahead of field deployment. The EPA mandates continuous methane monitoring at petrochemical facilities along the Gulf Coast, expanding installed base for infrared gas analyzers. Boston-area research laboratories anchor service revenue for calibrated photodetection systems.
Germany
KBA pedestrian-detection requirements for Level 3 autonomy are accelerating orders for 1550-nanometer laser diodes from compound semiconductor suppliers. Bavarian and Baden-Württemberg manufacturing clusters drive component demand for industrial automation and robotic guidance systems. The EU AI Act and MDR CE marking requirements tighten performance standards for safety-critical optoelectronic subsystems.
Japan
METI energy-efficiency standards mandate standby power below 2 watts for industrial thermal imagers, reshaping microbolometer readout circuit designs. Consumer electronics manufacturers in Tokyo and Osaka sustain volume production of standard infrared emitters for proximity sensing. Hamamatsu Photonics leverages vertically integrated fabrication to capture recurring maintenance contracts across domestic and European research facilities.
China
Telecommunications backbone upgrades for long-haul fiber networks shape optical component roadmaps and supply agreements. MIIT industrial policy directs investment toward domestic compound semiconductor capacity for infrared laser diodes. Yangtze River Delta packaging houses are absorbing module assembly work previously concentrated in Japan and South Korea.
India
PLI scheme incentives for electronics manufacturing are attracting infrared sensor packaging investments to serve domestic steel and cement process-control demand. BIS standards alignment with international thermal imaging specifications is accelerating qualification timelines for imported detector modules. Gujarat and Maharashtra industrial corridors concentrate early deployment of predictive maintenance systems.
Global Infrared Optoelectronics Market Competitive Landscape
Vertically integrated photodetector specialists and broad-line component distributors split the market between premium calibrated systems and high-volume standard products. The vendor base organizes around three strategic archetypes: captive fabrication houses serving defense and research end-users, compound semiconductor foundries supplying automotive LiDAR roadmaps, and distribution-anchored players controlling consumer electronics procurement channels. Competitive moves concentrate on backward integration into epitaxial wafer growth and geographic expansion of captive calibration service networks.
Among Japanese fabricators, Hamamatsu Photonics and ROHM Co., Ltd. exemplify divergent strategic positions within the infrared component space. Hamamatsu represents the vertically integrated archetype with captive service networks, while ROHM occupies a specialization position in compact laser diode architectures. Vishay Intertechnology anchors the distribution-controlled segment for standard infrared emitters. These three companies illustrate how geographic origin and organizational structure map to distinct competitive vectors in detector, laser, and emitter product categories.
| Leading Market Players |
|---|
| Sharp Corporation |
| Umicore |
| Vishay Intertechnology |
| Ophir Optronics Solutions |
| TAMRON |
| OSRAM International GmbH |
| ROHM Co., Ltd. |
| Hamamatsu Photonics |
| Omnivision Technologies Inc |
| Others |
Supply & Pricing Matrix
Bavarian and Baden-Württemberg manufacturing clusters concentrate compound semiconductor foundry capacity for automotive LiDAR components, translating upstream wafer bottlenecks into pricing leverage for qualified 1550-nanometer laser diode suppliers serving German OEMs. This geographic concentration feeds downstream cost structures across defense imaging and industrial automation procurement channels.
Pricing Analysis
Aftermarket service contracts for detector calibration and cooler maintenance generate lifetime value multiples exceeding original hardware sales. Three-tier pricing structure across premium, standard, and economy levels separates cryogenically cooled defense arrays from uncooled commercial microbolometers and consumer-grade proximity emitters. Cost compression in standard infrared emitters intensifies because Vishay Intertechnology's distribution control forces volume competitors toward commodity margins. Consumer electronics OEMs exhibit highest price sensitivity, while defense contractors absorb premium pricing for qualified detector modules.
Supply Chain Analysis
Indium feedstock and mercury cadmium telluride epitaxial wafers anchor upstream material dependencies for high-performance photodetection. Taiwan, the United States, and Japan concentrate III-V compound semiconductor foundry capacity, while China and South Korea dominate optical fiber component fabrication. Single-source vulnerability in MCT wafer supply exposes defense contractors to foundry reconfiguration delays. Distribution runs through captive service networks for calibrated research systems and broad electronics distributors for consumer-grade emitters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in cyclical recovery as defense procurement cycles compress development timelines and automotive LiDAR mandates accelerate component qualification. The cyclical driver is the synchronization of military modernization programs with Level 3 autonomy deployment roadmaps.
For Market Incumbents: Entrench position through backward integration into epitaxial wafer growth and expansion of captive calibration service networks across European and Japanese research facilities. Indium price volatility and emerging compound semiconductor foundries in China threaten margin stability. Certification investment for EU AI Act compliance represents the critical defensive lever. For New Entrants and Emerging Players: Mid-tier industrial automation integrators in India and Southeast Asia represent the most penetrable entry point, as PLI scheme incentives attract packaging investment but domestic design capability remains limited. Gas analysis instrumentation for EPA methane compliance offers second white-space opportunity. Go-to-market through subsystem partnerships with established German automotive Tier 1s bypasses qualification barriers. For Investors and Strategic Acquirers: Long-term, this sits as a compound semiconductor consolidation play because defense and automotive demand curves are converging on identical 1550-nanometer laser diode and InGaAs photodetector technologies. Target acquisition archetype: mid-scale foundries with qualified MCT or InGaAs epitaxial capacity and existing EASA certification pathways. Monitor KBA pedestrian-detection mandate enforcement as inflection signal for automotive LiDAR procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Epitaxial Wafer Capacity Expansion | Captive MCT and InGaAs supply secures defense imaging contracts against single-source risk. |
| Calibration Service Network Extension | Recurring maintenance contracts at Japanese and European research laboratories lock in aftermarket revenue. |
| 1550nm Laser Diode Qualification | KBA compliance for German Level 3 autonomy opens automotive procurement to compound semiconductor suppliers. |
| Microbolometer Readout Redesign | METI standby power mandates below 2 watts reshape industrial thermal imager specifications. |
| Quantum Cascade Laser Platform Convergence | Dual-use architectures bridge oilfield methane sensing and datacenter free-space optical links. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with defense procurement officers, compound semiconductor foundry engineers, automotive Tier 1 supplier quality managers, and research laboratory instrumentation heads; and secondary validation through SEC filings, EPA emissions compliance databases, EASA certification registries, and customs trade records. Bottom-up and top-down triangulation cross-checked wafer capacity estimates against component shipment volumes.
Forecast inputs considered product type segmentation across photodetectors, infrared lasers, sensors, emitters, and optical fiber components; technology tiers separating cryogenic and ambient-temperature architectures; and application demand patterns in surveillance, gas analysis, fire detection, industrial automation, and environmental monitoring. CAGRs were derived from installed base expansion rates and replacement cycle compression across the projection horizon. Defense procurement cycle timing and automotive safety mandate enforcement schedules served as industry-specific demand inputs.
Practitioners should monitor indium price volatility, KBA enforcement discretion, and EASA certification timeline extensions for early signals of forecast revision. Quarterly review of defense budget appropriations, automotive LiDAR design win announcements, and REACH substance restriction proposals is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optoelectronics
Europe Wigig Market
Optoelectronics
Global Opto-Isolator Market
Optoelectronics
Gaas Epiwafer Market
Optoelectronics
Vertical Cavity Surface Emitting Laser (Vcsels) Market
Optoelectronics
Electro-Optical/Infrared (EO/IR) Systems Market
Optoelectronics
Asia-Pacific Optoelectronics Market
Optoelectronics
Taiwan Optoelectronics Market
Optoelectronics
Optoelectronic Transducers Market
Optoelectronics
Light Projector Market
Optoelectronics
Optoelectronic Development Tools Market
Optoelectronics
Ingaas Avalanche Photodiode Market
Optoelectronics
Green Laser Diode Market
Optoelectronics
Optocoupler IC Market
Optoelectronics
Europe Optoelectronics Market
Optoelectronics
Laser Projector Market
Optoelectronics
Global Optocoupler Market