
 Atomic Spectroscopy Market | 2026-2036
Atomic Spectroscopy Market Size, Share, and Industry Trends Forecast 2026-2036
Atomic Spectroscopy Market Analysis
ISO 17025 accreditation for analytical testing laboratories is collapsing the competitive field, forcing smaller instrument vendors to cede ground to certified specialists. Thermo Fisher Scientific leverages its integrated consumables-instrument-service model to sustain recurring revenue streams across installed bases. Agilent Technologies anchors its position through chromatography-spectroscopy workflow bundling that locks in pharmaceutical quality control contracts. PerkinElmer differentiates via dedicated food safety application packages aligned with evolving contaminant testing protocols.
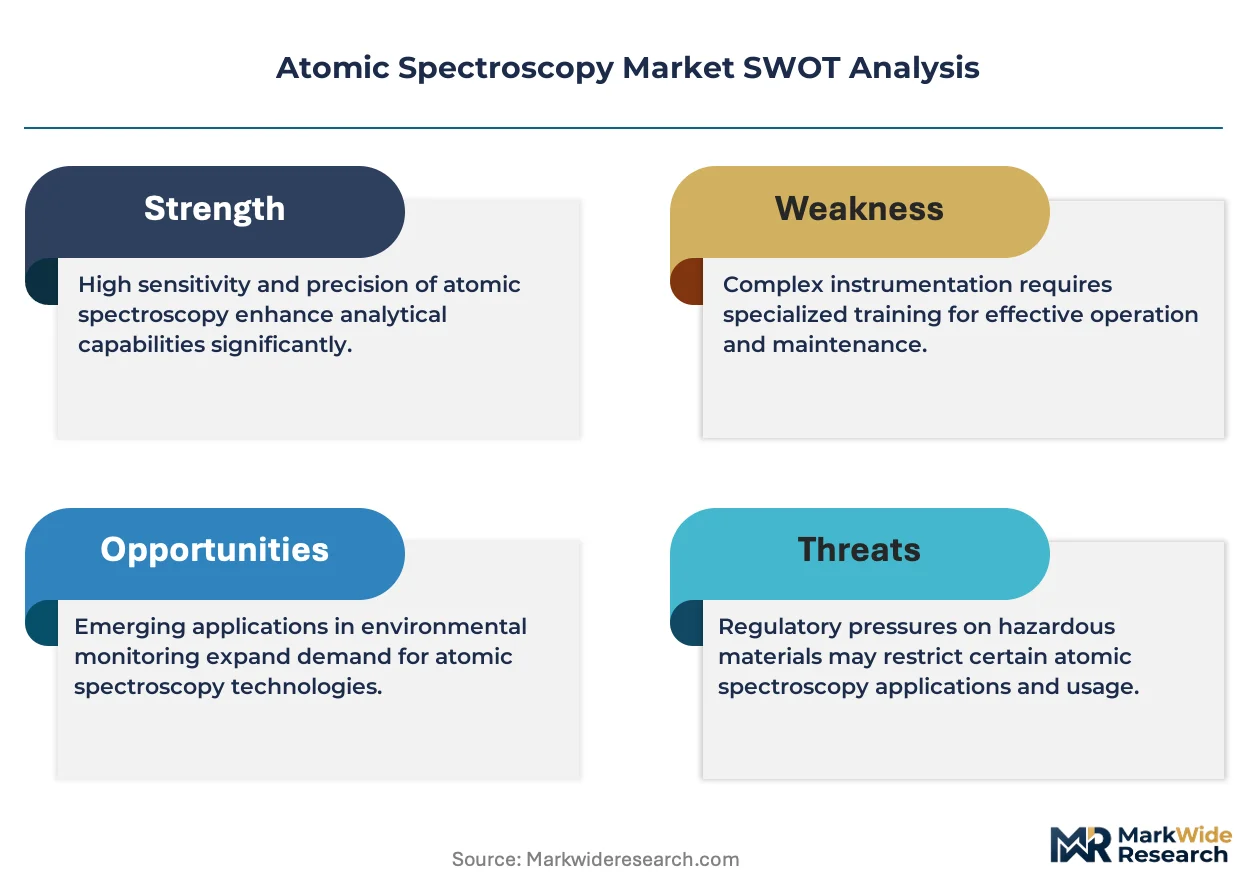
Atomic spectroscopy encompasses techniques that quantify elemental composition by measuring electromagnetic radiation absorbed or emitted by atoms in gaseous states, with detection limits reaching parts-per-billion depending on atomization method and optical path design. Its primary purpose spans regulatory compliance verification, raw material qualification, and trace contamination control across process industries. Inductively coupled plasma systems command premium positioning due to multi-element throughput advantages, while graphite furnace atomic absorption retains share in laboratories with concentrated heavy metal testing mandates. Flame spectroscopy occupies a mature, cost-driven tier serving educational institutions and routine industrial quality checks where sensitivity requirements remain modest.
US EPA methods 200.7 and 6020B, alongside FDA elemental impurity guidance per ICH Q3D, shape instrument specification requirements and validation documentation burdens for vendors seeking North American market access. Europe's REACH enforcement through ECHA and the EU Water Framework Directive establish comparable compliance thresholds that drive parallel demand for certified analytical platforms. China's MEE environmental monitoring standards and GB methods for food safety testing expand the addressable base for inductively coupled plasma configurations. Stakeholders must weigh capital deployment timing against pending revisions to pharmacopeial monographs and emerging per- and polyfluoroalkyl substance testing protocols that will redefine instrument performance specifications.
Market Dynamics
The transition from flame atomic absorption to inductively coupled plasma mass spectrometry is compressing replacement cycles while elevating validation documentation burdens for analytical laboratories across pharmaceutical and environmental testing verticals.
Growth Catalysts
- ICH Q3D Implementation:FDA enforcement of elemental impurity limits in drug products mandates multi-element screening capabilities that flame systems cannot deliver, forcing upgrade investments.
- China MEE Monitoring Mandates:Expanded environmental testing protocols for heavy metals in water and soil samples drive procurement of certified inductively coupled plasma platforms in provincial laboratories.
- Per- and Polyfluoroalkyl Substance Protocols:Emerging testing requirements for PFAS contamination in food packaging and drinking water create demand for ultra-trace detection methods.
Market Restraints
- High-Purity Argon Supply Concentration:Russia and Qatar control over 60% of global noble gas production, creating input cost volatility for plasma-based systems.
- Technical Limitation at Single-Digit PPB:Graphite furnace atomic absorption faces fundamental interference challenges in complex matrices that mass spectrometry resolves.
- REACH Registration Burden:ECHA chemical inventory requirements impose documentation costs that disadvantage smaller European instrument vendors.
Strategic Opportunities
- India PLI Scheme for Pharma:Production-linked incentives for active pharmaceutical ingredient manufacturing create captive demand for in-house elemental analysis capabilities.
- Portable XRF Convergence:Handheld energy-dispersive systems merging with cloud data platforms enable field-based screening that reduces laboratory sample volumes.
- Food Safety Application Bundles:Pre-validated method packages for arsenic speciation in rice and seafood accelerate deployment in commercial testing laboratories.
Industry Challenges
- ISO 17025 Talent Scarcity:Accredited analytical chemists capable of method validation and uncertainty quantification command premium compensation that strains laboratory operating budgets.
- Legacy LIMS Integration Friction:Newer inductively coupled plasma software architectures require middleware development to connect with established laboratory information management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Atomic Spectroscopy Market |
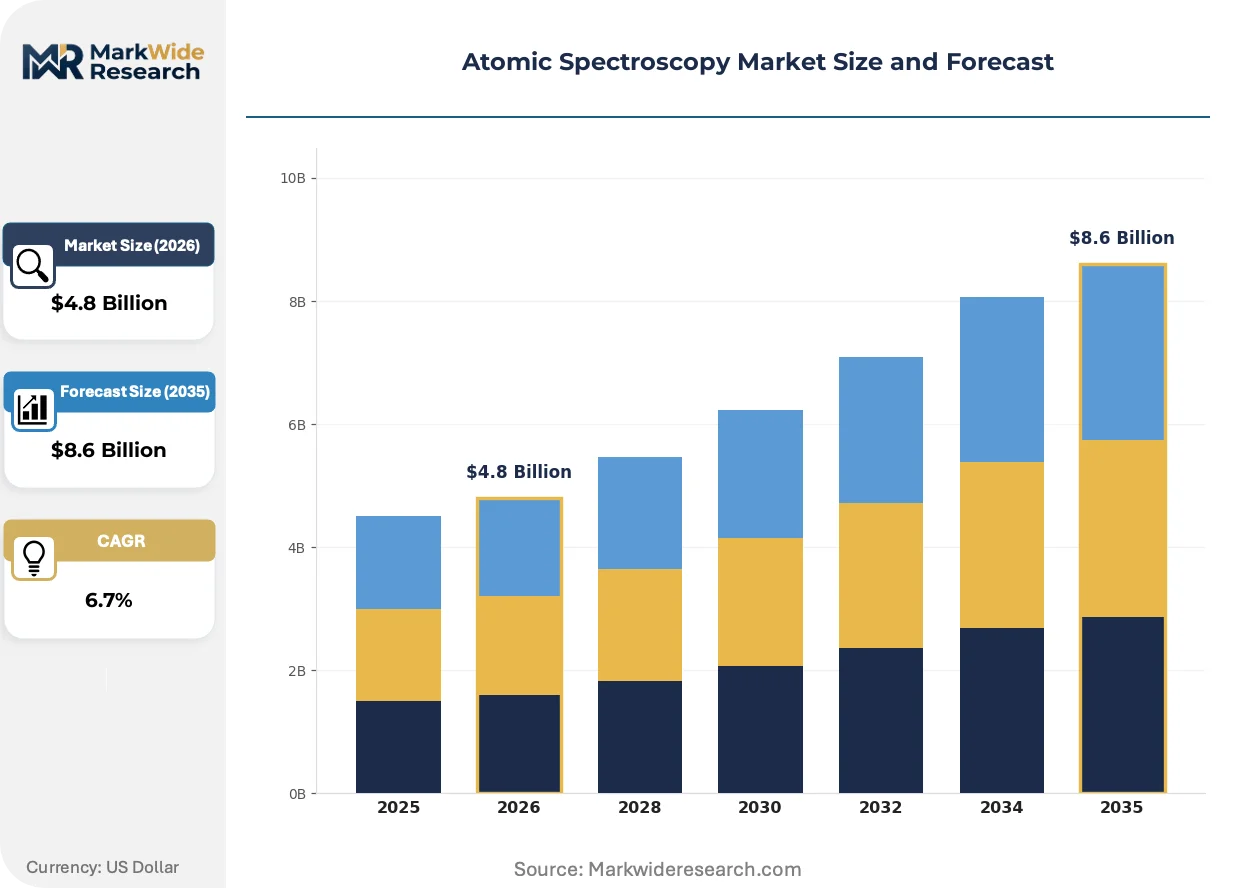
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flame Spectroscopy, Graphite Furnace, Inductively Coupled Plasma, Atomic Absorption Application: Environment Monitoring, Food Safety, Pharmaceutical Analysis, Material Testing End User: Academics, Research Institutions, Pharmaceuticals, Environmental Agencies Technology: Mass Spectrometry, Laser Ablation, Near-Infrared Spectroscopy, Others |
| Companies Covered | Agilent Technologies, Thermo Fisher Scientific, PerkinElmer, Bruker Corporation, Shimadzu Corporation, Rigaku Corporation, Analytik Jena, GBC Scientific Equipment, Aurora Biomed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Atomic Spectroscopy Market Emerging Trajectories
Instrument manufacturers are embedding artificial intelligence into spectral interpretation workflows while regulatory agencies tighten method validation requirements. These parallel developments are elevating both capability expectations and compliance complexity for end-users.
Triple quadrupole inductively coupled plasma mass spectrometry is displacing single-quadrupole configurations in pharmaceutical quality control laboratories. Large molecule and cell therapy manufacturers adopt these platforms to eliminate polyatomic interferences in complex biological matrices. The structural consequence is a bifurcation between premium multi-reaction-monitoring systems and commodity elemental screening instruments.
REACH authorization lists through ECHA now designate additional heavy metal compounds as substances of very high concern. Industrial users must demonstrate analytical capability to verify absence in supply chains or face use restrictions. Chemical manufacturers in Germany and the Netherlands are consolidating testing contracts with ISO 17025-accredited laboratories to satisfy downstream documentation demands.
Service unbundling is fragmenting traditional instrument procurement models. Pharmaceutical buyers now separate hardware acquisition from application support and consumables supply, soliciting competitive bids for each component. This pattern is most pronounced in the United States, where centralized procurement functions exploit vendor specialization to compress total cost of ownership.
Atomic Spectroscopy Market Segmentation
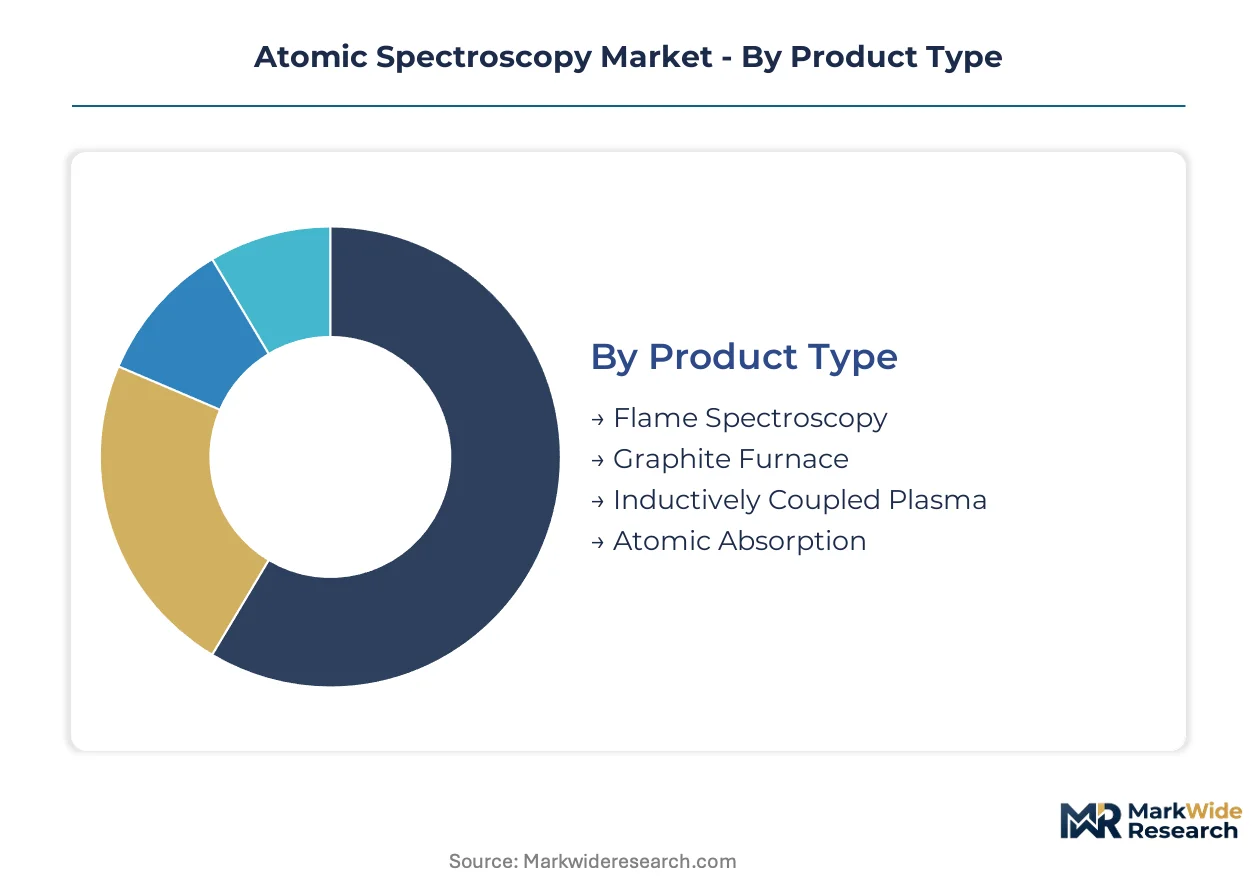
Segmentation in atomic spectroscopy reveals how instrument capabilities align with regulatory stringency and detection limit requirements across end-use verticals. Procurement patterns diverge sharply between laboratories seeking multi-element throughput and those prioritizing single-analyte cost efficiency.
Product Type:
Direct sales channels dominate high-value inductively coupled plasma installations, while distribution partnerships serve flame spectroscopy demand in educational markets.
- Inductively Coupled Plasma:These systems utilize argon plasma at temperatures exceeding 6,000K to atomize samples for simultaneous multi-element quantification. Pharmaceutical quality control laboratories in the United States and Germany are concentrating procurement here, driven by FDA and EMA enforcement of ICH Q3D elemental impurity limits that demand sub-ppb detection.
- Graphite Furnace:Electrothermal atomization confines samples within carbon tubes, enabling single-element analysis at detection limits rivaling mass spectrometry for concentrated heavy metal applications. Environmental agencies in China favor this technology for MEE-mandated water monitoring where capital constraints preclude full ICP-MS deployment.
- Flame Spectroscopy:Aerosol sample introduction into air-acetylene flames provides economical elemental screening for sodium, potassium, and calcium determinations in routine industrial settings.
- Atomic Absorption:Hollow cathode lamp-based systems with pneumatic nebulization retain installed base in mining and metallurgical laboratories requiring robust, low-maintenance operation.
Inductively coupled plasma dominates installed base. Flame spectroscopy is where expansion concentrates in emerging market educational institutions.
Application:
Cost tiers separate applications by validation burden and certification requirements, with pharmaceutical analysis commanding premium pricing and food safety operating on compressed margins.
- Pharmaceutical Analysis:Elemental impurity screening of drug substances and excipients per USP chapters 232/233 and ICH Q3D guidelines requires validated methods with documented uncertainty budgets. CDSCO-registered facilities in India are expanding capabilities fastest under PLI scheme incentives for active pharmaceutical ingredient manufacturing.
- Environment Monitoring:EPA Method 200.7 and 6020B compliance for water, soil, and air matrices demands certified instrumentation with demonstrated interference resolution. Provincial laboratories across China's MEE network are upgrading from flame systems to meet tightened heavy metal discharge standards.
- Food Safety:Arsenic speciation in rice and seafood, cadmium in chocolate, and lead in spices drive method-specific consumables demand from commercial testing laboratories.
- Material Testing:Alloy verification and semiconductor-grade chemical qualification rely on spark optical emission or ICP-based platforms with matrix-matched calibration protocols.
Pharmaceutical analysis commands premium pricing tiers. Food safety applications are climbing the fastest as import testing mandates proliferate.
End User:
Customer type determines service bundling preferences, with pharmaceutical buyers unbundling hardware from consumables and academics accepting turnkey packages.
- Pharmaceuticals:Corporate analytical development and quality control departments require 21 CFR Part 11 compliant software, IQ/OQ/PQ documentation, and multi-year service contracts. These buyers in the United States and Switzerland are consolidating vendor relationships to reduce total cost of ownership.
- Environmental Agencies:Government laboratories operate under fixed capital budgets with extended replacement cycles, prioritizing instrument longevity and domestic service technician availability. Germany's UBA and Netherlands' RIVM are standardizing on ISO 17025-accredited platforms to satisfy REACH downstream documentation demands.
- Research Institutions:University core facilities balance multi-user accessibility with publication-grade performance specifications, often favoring flexible configurations supporting multiple atomization modes.
- Academics:Undergraduate teaching laboratories prioritize instrument durability and simplified operation over detection limits, sustaining demand for flame photometry and basic atomic absorption systems.
Environmental agencies anchor replacement demand volume. Pharmaceuticals are gaining share fastest through in-house captive laboratory expansion.
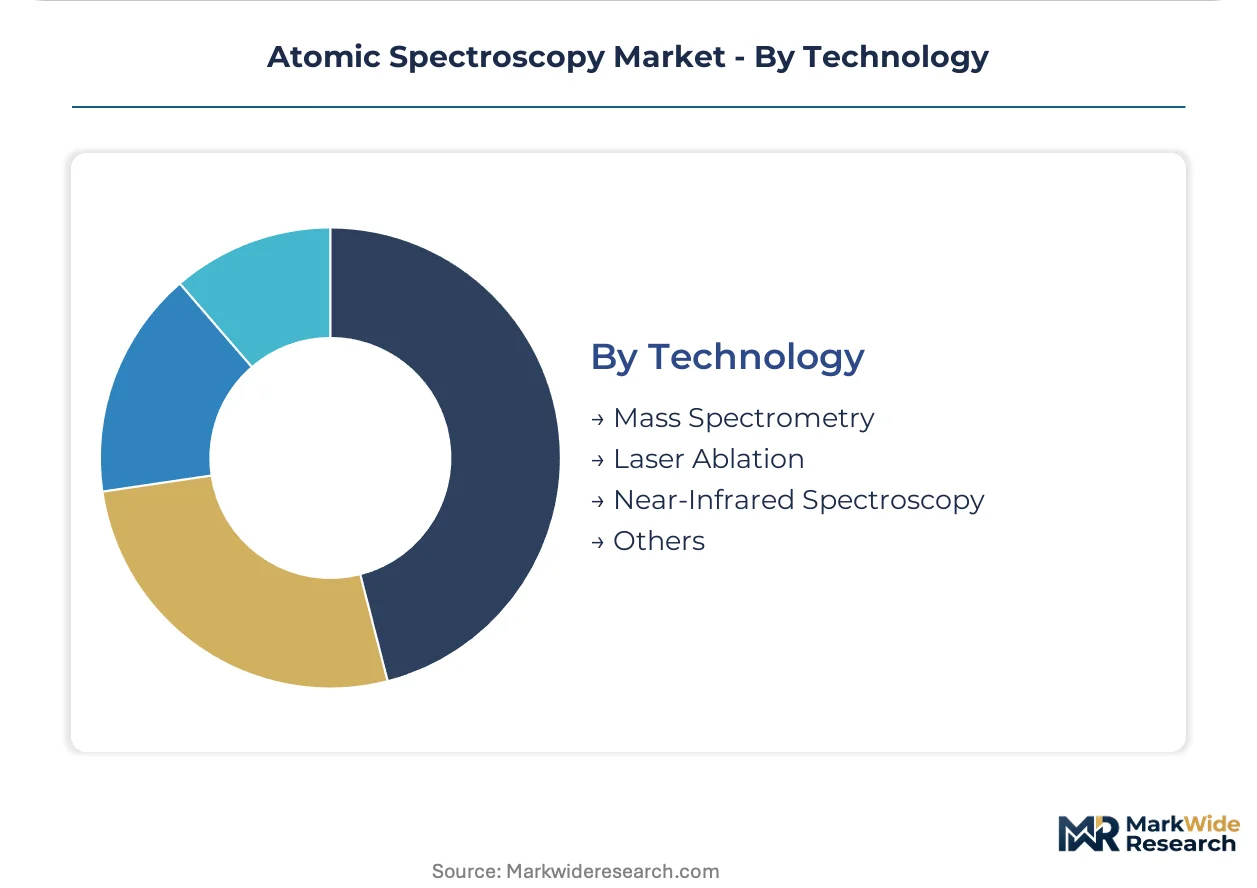
Technology:
Supply concentration in detector manufacturing and plasma torch fabrication shapes technology accessibility and upgrade pathways.
- Mass Spectrometry:Quadrupole and collision-reaction-cell configurations eliminate polyatomic interferences through mass resolution or gas-phase chemistry, enabling accurate trace analysis in complex biological matrices. Cell therapy manufacturers in Massachusetts and Basel are adopting triple quadrupole ICP-MS platforms fastest.
- Laser Ablation:Solid sample introduction bypasses dissolution steps, preserving spatial resolution for geological and forensic applications requiring microanalysis capabilities.
- Near-Infrared Spectroscopy:Molecular overtone absorption provides rapid screening complementary to atomic techniques, particularly for moisture and organic content determination in incoming raw materials.
- Others:X-ray fluorescence and arc/spark optical emission systems serve niche applications in alloy identification and high-throughput metal sorting operations.
Mass spectrometry dominates installed base. Laser ablation is where expansion concentrates in geological survey and materials science laboratories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production-linked incentives for pharmaceutical manufacturing in India and tightened environmental discharge standards across China's provincial laboratory networks are accelerating capital deployment in elemental analysis infrastructure. These policy instruments are compressing replacement cycles for legacy flame-based systems while elevating procurement specifications for certified inductively coupled plasma platforms.
United States
FDA enforcement of ICH Q3D elemental impurity limits drives multi-element screening upgrades at contract manufacturing organizations. EPA Methods 200.7 and 6020B compliance mandates shape instrument validation documentation for environmental testing laboratories. Massachusetts biotech clusters and New Jersey pharmaceutical corridors concentrate demand for triple quadrupole mass spectrometry configurations.
Germany
ECHA REACH authorization lists designate additional heavy metal compounds as substances of very high concern, forcing supply chain verification capabilities. The UBA standardizes on ISO 17025-accredited platforms to satisfy downstream documentation demands from chemical manufacturers. Industrial laboratories in North Rhine-Westphalia and Baden-Württemberg consolidate testing contracts with certified specialists.
China
MEE environmental monitoring standards for heavy metals in water and soil samples drive provincial laboratory procurement of certified inductively coupled plasma configurations. GB methods for food safety testing expand the addressable base for atomic spectroscopy platforms. Yangtze River Delta environmental agencies upgrade from flame systems to meet tightened discharge standards.
India
CDSCO-registered facilities expand capabilities fastest under PLI scheme incentives for active pharmaceutical ingredient manufacturing. Production-linked incentives create captive demand for in-house elemental analysis capabilities at contract research organizations. Maharashtra and Gujarat pharmaceutical manufacturing zones concentrate instrument deployment for raw material qualification.
Switzerland
Swissmedic pharmacopeial requirements align with EMA enforcement patterns, elevating validation documentation burdens for analytical laboratories. Large molecule and cell therapy manufacturers in Basel adopt premium multi-reaction-monitoring systems to eliminate polyatomic interferences. The country's precision manufacturing base sustains demand for semiconductor-grade chemical qualification platforms.
Atomic Spectroscopy Market Vendor Landscape
Listed leaders compete with private specialists across service bundling strategies and application-specific validation packages. The vendor base stratifies between integrated conglomerates sustaining recurring revenue through consumables-instrument-service models and focused specialists targeting discrete regulatory compliance verticals. Three archetypes dominate: full-workflow bundlers locking in pharmaceutical contracts, application-package differentiators aligned with food safety protocols, and technology-forward platforms embedding artificial intelligence into spectral interpretation. Consolidation pressure manifests through ISO 17025 accreditation requirements collapsing the competitive field, while service unbundling fragments traditional procurement models in North American markets.
Within the integrated conglomerate tier, Thermo Fisher Scientific and Agilent Technologies exemplify contrasting bundling philosophies. Thermo Fisher leverages its consumables-instrument-service integration to sustain recurring revenue streams across installed bases, while Agilent anchors positioning through chromatography-spectroscopy workflow bundling. PerkinElmer occupies a differentiated position through dedicated food safety application packages. These three entities represent the dominant competitive archetypes shaping procurement negotiations with pharmaceutical quality control departments and environmental testing laboratories.
| Leading Market Players |
|---|
| Agilent Technologies |
| Thermo Fisher Scientific |
| PerkinElmer |
| Bruker Corporation |
| Shimadzu Corporation |
| Rigaku Corporation |
| Analytik Jena |
| GBC Scientific Equipment |
| Aurora Biomed |
| Others |
Supply Flow & Price Mechanics
Argon plasma torch fabrication concentrates in high-capacity German and Japanese manufacturing hubs, creating scale advantages that compress unit economics for inductively coupled plasma systems while elevating price floors for smaller competitors lacking equivalent throughput. This concentration cascades into aftermarket consumables pricing, where certified plasma torches and detector arrays command premiums that sustain incumbent margin structures.
Pricing Analysis
Certification level (ISO 17025/FDA-grade) creates the primary spread between premium and standard instrument tiers. Three-tier pricing structure across pharmaceutical-grade, environmental-certified, and educational-economy levels dominates procurement negotiations. Cost compression in the economy tier intensifies because Chinese manufacturers are expanding flame spectroscopy production for emerging market educational institutions. Pharmaceutical quality control departments exhibit the lowest price sensitivity due to ICH Q3D compliance mandates, while undergraduate teaching laboratories negotiate aggressively on total cost of ownership.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes periodically disrupt detector module deliveries from Japanese fabrication facilities to German assembly plants. Manufacturing concentration centers on Germany, Japan, and the United States for precision optical components and mass spectrometer subassemblies. High-purity argon supply draws from concentrated Qatari and Russian extraction, creating commodity price volatility that plasma-based system vendors must absorb or pass through. Single-source vulnerability in collision-reaction-cell gas delivery systems represents the dominant structural risk. Distribution runs through direct sales for high-value pharmaceutical installations and authorized distributors for academic and routine industrial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Validated analytical chemists capable of uncertainty quantification and method development command compensation premiums that strain laboratory operating budgets, creating competitive moats around accredited service providers. This talent scarcity shapes strategic positioning for all market participants.
For Market Incumbents: Secure ISO 17025 accreditation expansion into emerging PFAS testing protocols before regulatory mandates formalize. Lock in multi-year consumables contracts with pharmaceutical quality control departments to defend against unbundling pressure. Vertical integration into high-purity argon recycling systems mitigates supply concentration risk from Qatari and Russian sources.
For New Entrants and Emerging Players: Anchor in India's PLI scheme-funded pharmaceutical manufacturing zones where captive laboratory demand outpaces established vendor service capacity. Target environmental testing laboratories in China's provincial MEE networks upgrading from flame systems. Position through application-specific method packages for arsenic speciation in food safety rather than competing head-to-head on instrument specifications.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors triple quadrupole ICP-MS specialists over single-quadrupole commodity producers. Long-term viability hinges on recurring revenue attachment rates from consumables and service contracts rather than hardware shipment volumes. Monitor ECHA REACH authorization list expansions as the inflection signal for downstream testing demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Application-Specific Method Package Development | Pre-validated arsenic speciation protocols accelerate deployment in FSSAI-regulated food testing laboratories. |
| Consumables-Instrument-Service Integration | Recurring revenue streams from plasma torches and detector arrays lock in pharmaceutical QC contract renewals. |
| ISO 17025 Accreditation Expansion | Certified capabilities satisfy ECHA REACH downstream documentation demands from German chemical manufacturers. |
| Backward Integration into Argon Supply | Captive high-purity gas production insulates margins from Qatari and Russian supply volatility. |
| Cloud-Connected Portable XRF Convergence | Field-based screening reduces laboratory sample volumes for EPA Method 200.7 compliance workflows. |
Methodological Framework
A spread of perspectives from pharmaceutical quality control managers, environmental laboratory directors, instrument vendor application specialists, and regulatory affairs consultants converged on the working assumptions shaping this analysis. Primary interviews with these stakeholders combined with secondary validation from FDA guidance documents, ECHA authorization lists, MEE monitoring standards, and CDSCO facility registration data. Bottom-up instrument shipment tracking and top-down end-use spending analysis provided triangulation across the modeling period.
Segmentation dimensions modeled include product type (inductively coupled plasma, graphite furnace, flame spectroscopy), application (pharmaceutical analysis, environment monitoring, food safety), end user (pharmaceuticals, environmental agencies, research institutions), and technology (mass spectrometry, laser ablation). CAGRs were derived from replacement cycle compression analysis and regulatory mandate timing across geographies. Forecast inputs incorporated ICH Q3D enforcement trajectories and PFAS protocol development timelines.
Decision-makers should treat outputs as directional under assumptions of sustained FDA and EMA enforcement of elemental impurity limits; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Micro Balances Market
Analytical Instruments
Portable Infrared Digital Thermometer Market
Analytical Instruments
Tunable Diode Laser Analyzer Market
Analytical Instruments
Electrochemistry Meters Market
Analytical Instruments
Portable Particle Counter Market
Analytical Instruments
Middle East and Africa Dissolved Gas Analyzer Market
Analytical Instruments
Global Particle Counters Market
Analytical Instruments
Bolometer Market
Analytical Instruments
Atomic Force Microscopes (AFM) Market
Analytical Instruments
Network Analyzers Market
Analytical Instruments
North America Surface Analysis Market
Analytical Instruments
Universal Probe Library Market
Analytical Instruments
Europe Mass Spectroscopy Market
Analytical Instruments
Global Mass Spectrometry Market
Analytical Instruments
Laser Scanning Microscopes Market
Analytical Instruments
TDLAS Moisture Analyzers Market