
 Air Circuit Breaker Market | 2026-2036
Air Circuit Breaker Market Size, Share, and Industry Trends Forecast 2026-2036
Air Circuit Breaker Market Analysis
Skilled relay-coordination engineers is bifurcating the competitive landscape into firms that can design selective protection schemes and those dependent on standardized configurations. ABB leverages its digital-twin software to embed arc-flash modeling into breaker specification workflows. Siemens sustains manufacturing depth across electromechanical and hybrid platforms. Schneider Electric anchors its position through channel control in European utility retrofit programs.
An air circuit breaker is a low-voltage switching device that extinguishes electric arcs using compressed air or arc chutes with rated breaking capacities typically exceeding 50 kA; it serves as the primary fault-protection element in main switchgear assemblies for commercial buildings and heavy industrial plants. Medium voltage breakers command the deepest margin pools where custom engineering and site-specific commissioning create pricing power. Smart technology is displacing electromechanical platforms fastest in utility-scale automation deployments where remote monitoring and predictive maintenance reduce outage duration. Miniature units occupy a mature, cost-driven segment concentrated in residential and light commercial distribution boards.
FDA oversight of electrical safety in healthcare facility infrastructure, EPA energy-efficiency mandates for federal buildings, and IEC 60947-2 product standards collectively shape breaker specification, testing protocols, and market access across North American and European procurement channels. India's CEA grid-code revisions and BIS certification requirements for short-circuit withstand ratings are tightening import conditions while accelerating domestic manufacturing scale. Stakeholders must decide whether to build captive arc-chamber production or source from consolidated Asian ceramic suppliers before supply commitments lock in for the next utility investment cycle.
Market Dynamics
Renewable integration timelines across Southeast Asian grids are compressing substation upgrade cycles, forcing utilities to specify breakers with higher interrupting ratings and faster reclosing capabilities than legacy electromechanical platforms can deliver.
Growth Catalysts
- CEA Grid-Code Revisions:India's Central Electricity Authority mandates stricter short-circuit withstand ratings for 765 kV substations, compelling domestic manufacturers to scale arc-chamber production capacity.
- Data Center Buildouts:Hyperscale facilities in Singapore and Johor Bahru require 50 kA+ rated ACBs with digital trip units for selective coordination in redundant bus configurations.
- Copper-Nickel Contact Alloys:Advanced metallurgy extends electrical endurance beyond 10,000 operations, reducing replacement frequency in steel mill power distribution.
Market Restraints
- Silver Oxide Price Volatility:Arc-chamber contact materials face input cost swings tied to precious metal commodity markets, squeezing margin on standard-duty units.
- Consolidated Asian Ceramic Supply:Arc chute manufacturing concentrates in Zhejiang and Jiangsu provinces, creating single-source risk for European and North American breaker assemblers.
- IEC 60947-2 Testing Bottlenecks:Certification backlog at accredited laboratories extends product launch timelines by 8-14 months for new platform introductions.
Strategic Opportunities
- Vietnam Industrial Zones:Underpenetrated manufacturing corridors near Hai Phong and Binh Duong lack qualified protection engineers, creating first-mover advantage for firms offering bundled engineering services.
- Digital Twin Integration:Convergence of breaker hardware with asset management software enables predictive maintenance contracts that lock in decade-long spare parts revenue streams.
- EU Green Deal Retrofit Mandates:Energy efficiency directives accelerate replacement of electromechanical breakers in German and French commercial building stock.
Industry Challenges
- Relay Coordination Talent Scarcity:Selective protection design requires engineers fluent in both electromechanical and microprocessor-based trip logic, a skill set concentrated among aging utility workforces.
- Legacy Switchgear Integration:Retrofitting smart breakers into 1980s-era MNS switchgear requires custom bus adapters and arc-flash containment engineering that extends project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Circuit Breaker Market |
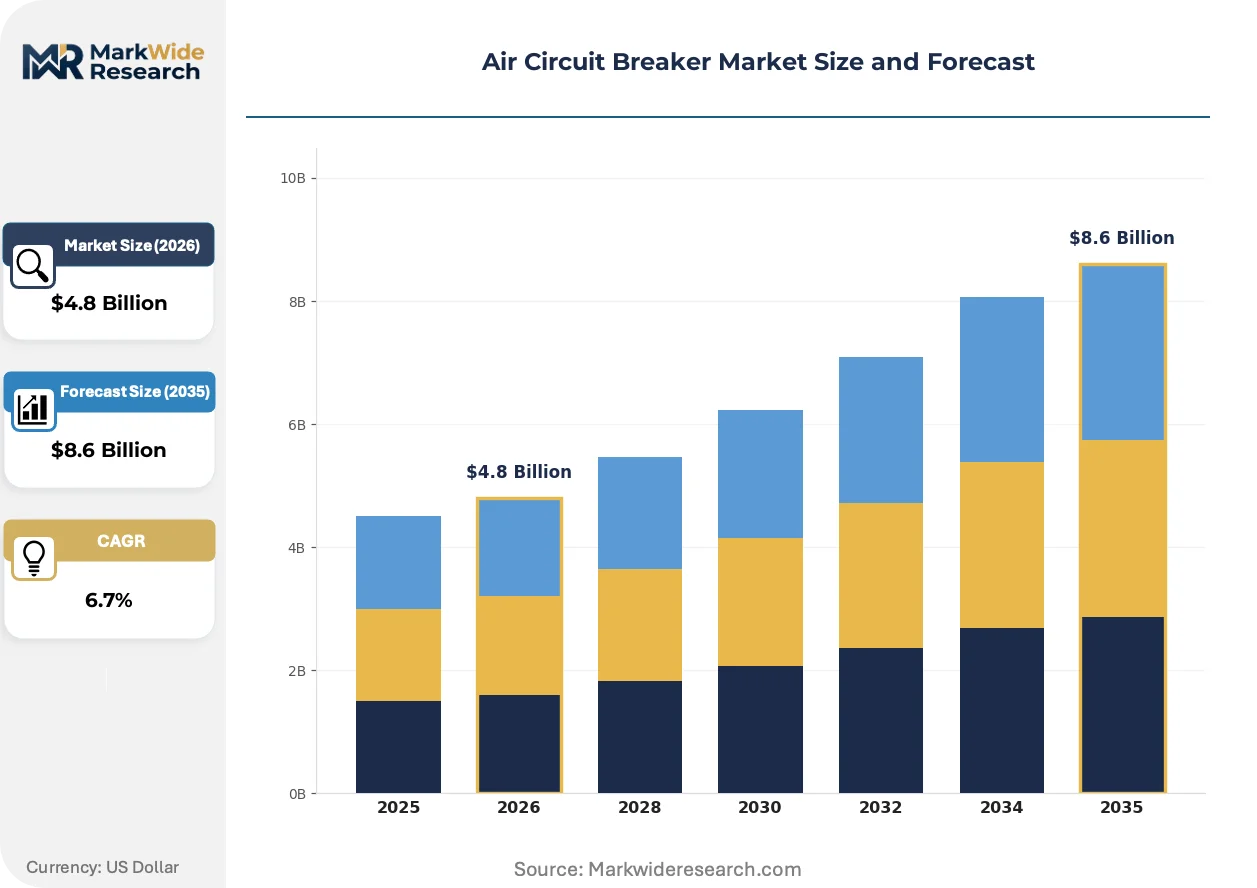
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Miniature, Standard, Low Voltage, Medium Voltage End User: Commercial, Industrial, Residential, Utilities Technology: Electromechanical, Digital, Hybrid, Smart Application: Power Distribution, Automation, Motor Control, Protection Systems |
| Companies Covered | Mitsubishi Electric, Hitachi, ABB, Larsen & Toubro, Fuji Electric, Schneider Electric, Siemens, CG Power and Industrial Solutions, Eaton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Circuit Breaker Market Emerging Trajectories
Breaker architecture is bifurcating between compact electronic platforms for new construction and ruggedized hybrid designs for harsh industrial retrofits, with specification software becoming the primary competitive battleground.
Hybrid trip units combining electromechanical energy storage with microprocessor-controlled release mechanisms are fragmenting the traditional split between purely electronic and purely thermal-magnetic platforms. Mining operators in Western Australia and Chilean copper belts specify these units for their immunity to electromagnetic interference in high-current fault conditions. The technology is fragmenting vendor R&D budgets across three parallel development tracks rather than consolidating on a single dominant architecture.
EPA energy-efficiency mandates for federal buildings now require circuit protection devices to demonstrate reduced electrical losses under partial-load conditions, affecting specification criteria for GSA procurement channels. This compresses demand toward breakers with low-resistance silver-tungsten contacts and optimized magnetic circuits. Manufacturers serving US federal contractors are responding by pre-certifying platforms to FEMP-qualified product lists before pursuing broader commercial distribution.
Asset owners in India's textile belt and Thailand's automotive parts clusters now unbundle breaker procurement from installation contracts, sourcing hardware through electrical distributors while engaging independent commissioning engineers for protection coordination. This disintermediates traditional turnkey switchgear vendors and shifts margin toward specialized service providers. The pattern is most visible in Gujarat and Tamil Nadu, where industrial associations have published standardized scope documents separating material from labor.
Air Circuit Breaker Market Segmentation
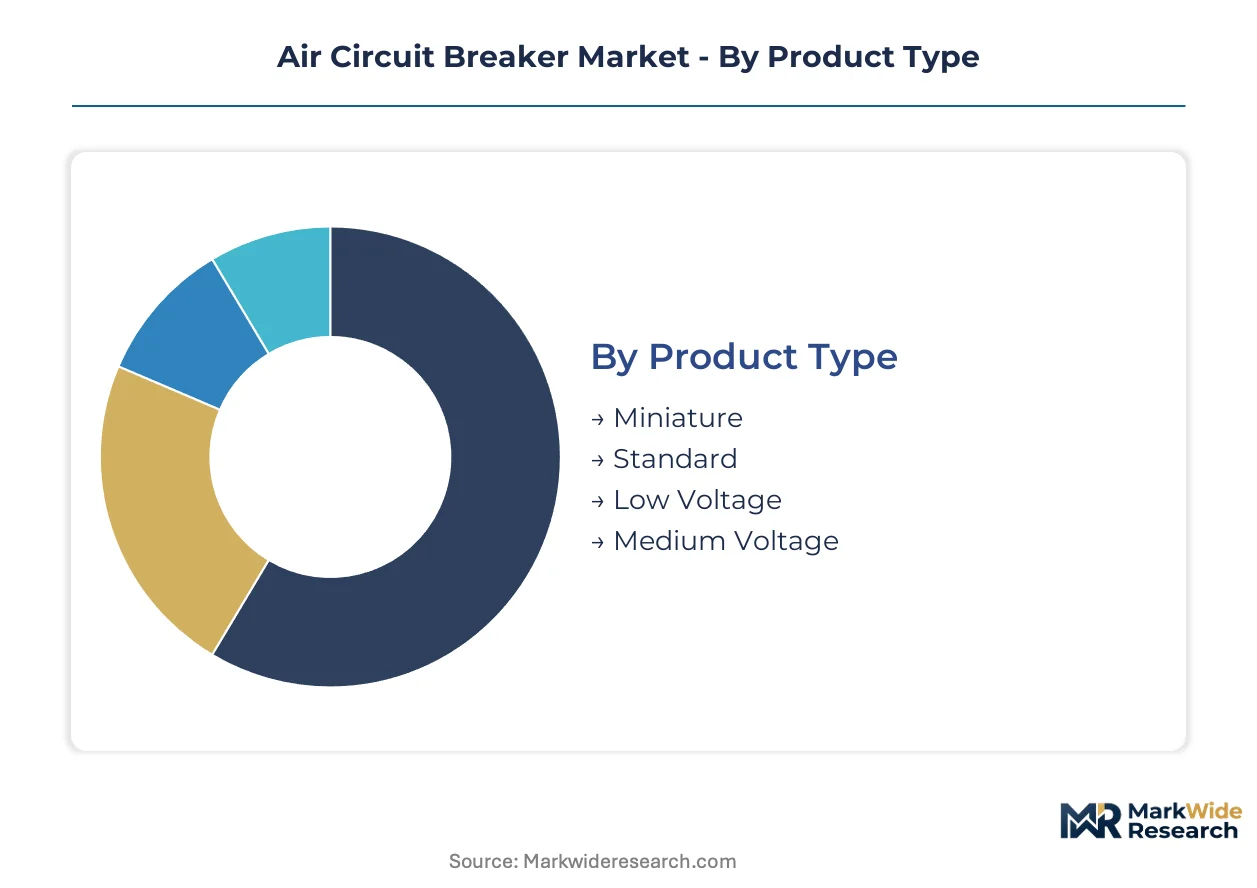
Air circuit breaker procurement bifurcates sharply between specification-driven utility contracts and price-sensitive commercial installations. Understanding segment-level margin distribution and technology migration patterns reveals where engineering investment yields sustainable pricing power.
Product Type:
Margin pools concentrate in medium voltage platforms where custom arc-chamber engineering and site-specific commissioning create defensible pricing. Low voltage units compete on manufacturing scale and channel efficiency.
- Miniature:Compact thermal-magnetic devices rated below 125A serve residential distribution boards and light commercial panels. Demand clusters in India's urban housing developments where BIS certification requirements filter import competition.
- Standard:Frame sizes from 250A to 1600A dominate commercial building switchgear. Procurement through electrical distributors in Vietnam's industrial zones is accelerating as foreign manufacturing tenants specify IEC-compliant platforms.
- Low Voltage:Modular designs rated up to 6300A protect heavy industrial bus systems. Steel mills in Gujarat and Tamil Nadu specify these units for their tolerance to dusty environments and high operation cycles.
- Medium Voltage:Custom-engineered platforms with vacuum or SF6 interruption mechanisms command the deepest margins. Utilities across Southeast Asia specify these for 765 kV substation upgrades under CEA grid-code revisions.
Medium voltage holds installed capacity. Low voltage is rotating up the share rankings.
End User:
Volume concentrates in industrial procurement where replacement cycles and capacity expansions generate recurring demand. Residential and commercial segments exhibit sharper price elasticity.
- Commercial:Office towers and retail complexes specify ACBs with electronic trip units for selective coordination. Singapore's Green Mark certification program is accelerating replacement of electromechanical breakers in existing building stock.
- Industrial:Manufacturing plants require ruggedized platforms with extended electrical endurance. Copper-nickel contact alloys rated beyond 10,000 operations reduce downtime in continuous-process industries like textiles and automotive components.
- Residential:Cost-driven demand for miniature breakers in multi-unit housing developments. India's Pradhan Mantri Awas Yojana urban housing mission is expanding distribution board volumes in tier-2 and tier-3 cities.
- Utilities:Grid-scale substation investments drive specification of high-interrupting-capacity units. State electricity boards in Maharashtra and Rajasthan are expanding 400 kV and 765 kV capacity to accommodate renewable integration timelines.
Industrial end users anchor replacement revenue. Utility procurement is climbing the fastest as grid modernization accelerates.
Technology:
Customer willingness to pay for diagnostic capability varies sharply by application criticality. Smart platforms capture premium in unmanned substations where remote monitoring reduces outage duration.
- Electromechanical:Thermal-magnetic mechanisms with mechanical energy storage dominate mature installed bases. Mining operators in Western Australia specify these for electromagnetic immunity in high-current fault conditions.
- Digital:Microprocessor-controlled trip units enable precise protection curves and event logging. Data center operators in Johor Bahru require these for selective coordination in redundant 2N bus configurations.
- Hybrid:Combines electromechanical energy storage with electronic release logic. Chilean copper belt mining operations favor this architecture for reliability in remote locations with limited technical support.
- Smart:Integrated communication protocols enable predictive maintenance and asset management software integration. European utility retrofit programs under EU Green Deal mandates are displacing legacy platforms fastest in this segment.
Electromechanical technology holds installed capacity. Smart platforms are gaining share fastest in utility automation deployments.
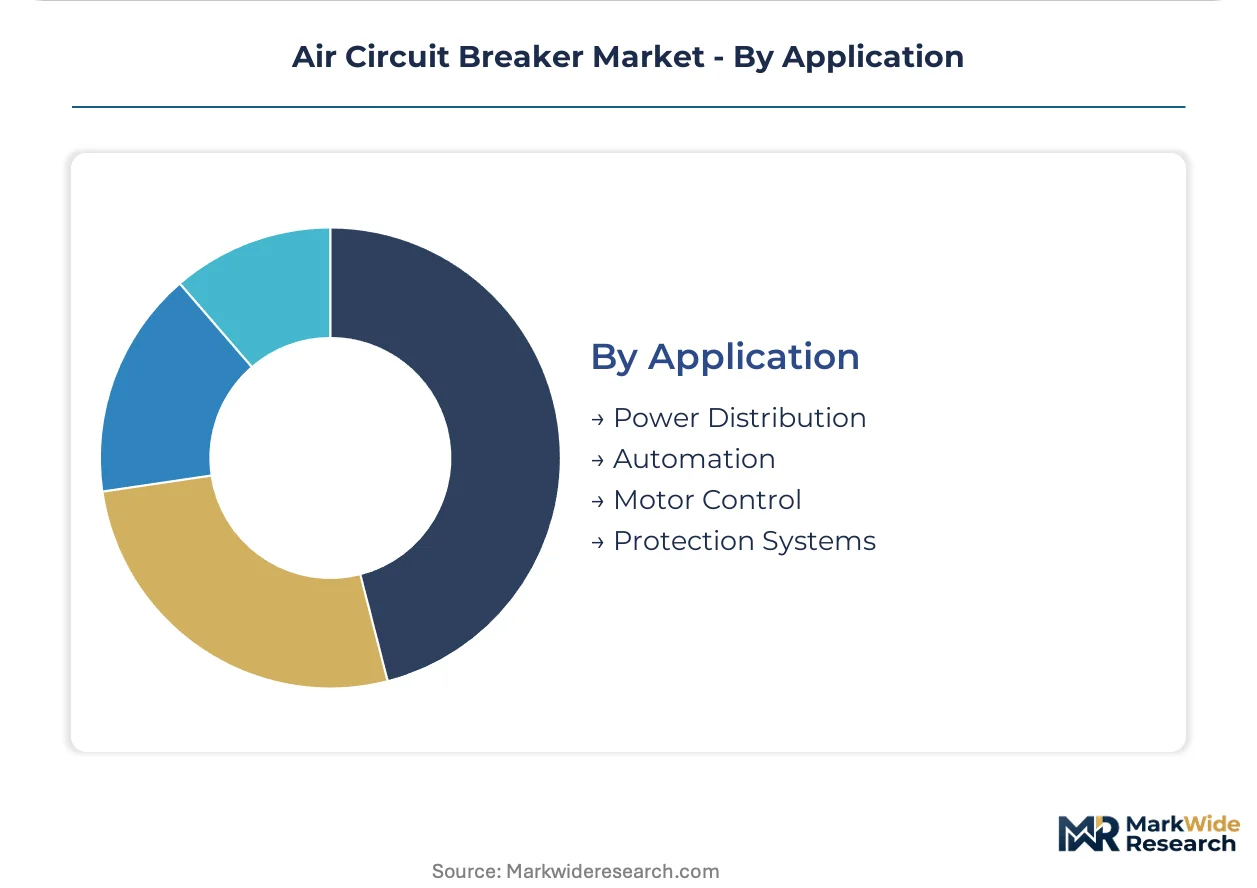
Application:
Specification complexity and engineering service intensity determine margin structure across application categories. Protection systems demand the most specialized commissioning expertise.
- Power Distribution:Main switchgear assemblies in commercial and industrial facilities. Thailand's Eastern Economic Corridor manufacturing investments are expanding demand for 50 kA+ rated units in heavy industrial parks.
- Automation:Integration with SCADA and building management systems requires communication-enabled breakers. Smart city infrastructure projects in Vietnam's Binh Duong province specify these for centralized grid monitoring.
- Motor Control:Coordination with motor protection relays in manufacturing processes. Automotive parts clusters in Tamil Nadu require precise trip curves to protect high-inertia machinery from damage.
- Protection Systems:Selective fault isolation schemes in critical infrastructure. India's CEA mandates for short-circuit withstand ratings are tightening specification requirements for 765 kV substation protection.
Power distribution holds installed capacity. Protection systems are expanding most quickly as grid-code compliance tightens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Japanese engineering corridors where custom arc-chamber fabrication commands 40-60% premiums over standard platforms. Cost leadership clusters in Chinese manufacturing basins where scale production of miniature and standard frame sizes dominates export volumes.
United States
Federal building retrofit mandates and data center expansion in Northern Virginia drive specification of low-resistance contact platforms. EPA FEMP qualification requirements filter procurement toward pre-certified breaker assemblies for GSA channels. Texas and Arizona utility-scale solar installations are accelerating demand for 50 kA+ interrupting capacity units in 345 kV collector substations.
Germany
EU Green Deal commercial building mandates are displacing electromechanical breakers in Frankfurt and Munich office stock. Ecodesign directives tighten energy-efficiency thresholds for distribution equipment in public procurement. Industrial clusters in North Rhine-Westphalia specify hybrid trip units for steel mill and chemical plant protection coordination.
India
CEA grid-code revisions for 765 kV substations are compelling domestic arc-chamber production scale-up. BIS certification requirements for short-circuit withstand ratings filter import competition in Maharashtra and Gujarat. The Mumbai-Delhi industrial corridor accounts for concentrated demand from textile belt and automotive parts clusters in Tamil Nadu.
China
State Grid Corporation substation automation investments are absorbing smart breaker platforms with integrated communication protocols. GB standards alignment with IEC 60947-2 is tightening testing protocols for export-oriented manufacturers. Zhejiang and Jiangsu provinces concentrate arc chute ceramic supply for both domestic consumption and European OEM sourcing.
Vietnam
Foreign manufacturing tenants in Hai Phong and Binh Duong industrial zones are specifying IEC-compliant low voltage platforms through electrical distributors. Underpenetrated protection engineering capacity creates service bundling opportunities for first-mover firms. Smart city infrastructure projects in Ho Chi Minh City are piloting SCADA-integrated breaker deployments for centralized grid monitoring.
Air Circuit Breaker Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with engineering-intensive medium voltage specialists commanding margin premiums while scale manufacturers dominate volume segments. The vendor base organizes into three tiers: integrated electromechanical-digital platforms, pure-play smart technology providers, and regional cost-optimized fabricators. Consolidation pressure concentrates in standard and miniature segments where manufacturing scale determines survival. Dominant competitive moves include backward integration into arc-chamber ceramics and predictive maintenance software licensing to capture recurring revenue.
Among European engineering groups, ABB and Siemens occupy positions spanning electromechanical heritage through digital platform migration. Japanese specialists including Mitsubishi Electric and Fuji Electric exemplify the hybrid-architecture approach favored in mining and heavy industrial applications. Schneider Electric anchors the premium service tier through channel control in utility retrofit programs. These three archetypes—European integrated platforms, Japanese hybrid specialists, and French service-anchored systems—collectively shape specification norms across procurement channels.
| Leading Market Players |
|---|
| Mitsubishi Electric |
| Hitachi |
| ABB |
| Larsen & Toubro |
| Fuji Electric |
| Schneider Electric |
| Siemens |
| CG Power and Industrial Solutions |
| Eaton |
| Others |
Supply Flow & Price Mechanics
IEC 60947-2 certification requirements gate both supplier qualification and price differentiation simultaneously, forcing manufacturers to absorb testing costs that standard-duty producers cannot pass through to price-sensitive buyers. This bifurcation rewards firms with captive arc-chamber production while squeezing margin on import-dependent assemblers.
Pricing Analysis
Configured-to-order pricing for medium voltage platforms commands 40-60% premiums over standard low voltage units due to site-specific arc-chamber engineering and commissioning services. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales bundling intensity. Cost compression in standard frame sizes is intensifying because Asian manufacturers are scaling export volumes into Southeast Asian industrial zones. Commercial building procurement teams exhibit highest price sensitivity, while utility protection engineers prioritize interrupting capacity over unit cost.
Supply Chain Analysis
Inbound logistics costs from Zhejiang and Jiangsu ceramic manufacturing clusters to European breaker assemblers have tightened margin on electromechanical platforms as container availability fluctuates on Asia-Europe trade lanes. Arc chute production draws from China, India, and Germany for ceramic substrates, silver-tungsten contact materials, and copper-nickel alloys. Single-source vulnerability concentrates in consolidated Asian ceramic supply for arc chamber fabrication. Distribution runs through electrical distributors in industrial corridors and direct specification channels for utility retrofit programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward industrial facility owners in India's textile belt and Thailand's automotive clusters as they unbundle hardware procurement from installation contracts. This fragmentation among end-users disintermediates traditional turnkey vendors and redistributes margin toward specialized commissioning engineers.
For Market Incumbents: Shield installed base revenue by embedding digital-twin software into breaker specification workflows before emerging pure-play smart technology providers capture utility automation contracts. Deepen backward integration into arc-chamber ceramics to offset silver oxide price volatility that squeezes standard-duty margins. Prioritize channel control in European utility retrofit programs where EU Green Deal mandates accelerate replacement cycles. For New Entrants and Emerging Players: Anchor in Vietnam's Hai Phong and Binh Duong industrial zones where underpenetrated protection engineering capacity creates first-mover advantage for firms offering bundled hardware-commissioning services. Target data center buildouts in Singapore and Johor Bahru requiring 50 kA+ rated units with digital trip units. Pursue distributor partnerships rather than direct specification channels to bypass incumbent relationships with state electricity boards. For Investors and Strategic Acquirers: Carve-out targets emerge from European engineering groups divesting electromechanical breaker divisions to focus on software-defined protection platforms. Long-term viability hinges on recurring revenue from predictive maintenance contracts and spare parts lock-in across decade-long utility asset lifecycles. Monitor CEA grid-code enforcement intensity in India as inflection indicator for domestic manufacturing scale-up versus import dependency.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Arc-Chamber Ceramics | Captive supply from Zhejiang ceramic clusters insulates margin from single-source risk. |
| Digital-Twin Software Licensing | ABB's arc-flash modeling embeds breaker specifications into utility engineering workflows. |
| Predictive Maintenance Contracting | Asset management software integration locks in decade-long spare parts revenue streams. |
| CEA Grid-Code Certification Investment | BIS-compliant short-circuit withstand ratings filter import competition in Maharashtra substations. |
| Vietnam Service Bundling Expansion | First-mover firms in Binh Duong industrial zones capture unmet protection engineering demand. |
Methodological Framework
Operator-level perspectives from utility protection engineers, switchgear OEM procurement directors, arc-chamber ceramic suppliers, and electrical distributor category managers anchored the qualitative base for this analysis. Primary interviews combined with secondary validation from IEC 60947-2 testing protocols, CEA grid-code filings, BIS certification registries, and customs trade data on silver-tungsten contact materials. Bottom-up segment sizing triangulated against top-down utility capital expenditure tracking across the analysis window.
Sensitivity analysis tested demand elasticity under varying renewable integration timelines and precious metal price scenarios. Segmentation dimensions modeled include product type, end user, technology platform, application criticality, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles and capacity expansion pipelines. Industry-specific forecast inputs incorporated CEA 765 kV substation upgrade schedules and data center power density specifications from Singapore and Johor Bahru developments.
Material uncertainties — silver oxide commodity volatility, IEC 60947-2 testing bottlenecks, and CEA enforcement consistency — sit outside the modeled envelope. Forecasts reflect documented assumptions about arc-chamber supply continuity and protection engineering labor availability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
High Voltage Switchboard Market
Electrical Equipment
North America Low Voltage Induction Motors Market
Electrical Equipment
Electric Motors for Conveyor System Market
Electrical Equipment
Smart Fan Market
Electrical Equipment
Vacuum Contactor Market
Electrical Equipment
South America High Voltage Switchgear Market
Electrical Equipment
Lighting Contactor Market
Electrical Equipment
Capacitor Bank Market
Electrical Equipment
United States Busbar Market
Electrical Equipment
Axial Fans Market
Electrical Equipment
Electric Enclosure Market
Electrical Equipment
Electrical Label Market
Electrical Equipment
Voltage Transformer Market
Electrical Equipment
Asia-Pacific Electrical Bushing Market
Electrical Equipment
Global Sealed DC Contactor Market
Electrical Equipment
Ultra High Voltage (UHV) Appliances Market