
 Asia-Pacific Optoelectronics Market | 2026-2036
Asia-Pacific Optoelectronics Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Optoelectronics Market Insights
Silicon photonics integration is rewriting how optical transceivers and sensing modules are architected for data centers and consumer devices. Samsung Electronics leverages its captive semiconductor fabrication to anchor display and image sensor supply chains across the region. Hamamatsu Photonics specializes in photodetector architectures for industrial automation and medical instrumentation. LG Innotek dominates camera module assembly for flagship smartphones, sustaining volume through tight integration with Korean handset OEMs.
Asia-Pacific optoelectronics encompasses devices that convert electrical signals into light or light into electrical signals, typically operating across ultraviolet through infrared wavelengths with semiconductor junctions or quantum structures as the active medium. These components enable optical communication, illumination, sensing, and imaging in systems where bandwidth, efficiency, or precision exceeds pure electronic alternatives. Light Emitting Diodes and Laser Diodes command the largest revenue pools due to their penetration in displays and fiber optic networks, while Quantum Dots represent the fastest-expanding technology segment as manufacturers pursue narrower emission spectra for premium displays. Consumer Electronics and Telecommunications absorb the majority of unit volume, though Automotive Lighting is widening as adaptive headlamp and LiDAR adoption spreads through Japanese and Korean vehicle programs.
Japan's METI enforces JIS standards for laser safety and optical component reliability, while China's MIIT administers GB standards and dual carbon targets that filter inefficient lighting products from domestic procurement. South Korea's MFDS and KATS frameworks regulate medical optoelectronic devices, creating compliance thresholds for phototherapy and diagnostic imaging exports. Stakeholders must track how divergent national efficiency mandates and substance restrictions across these three regulatory spheres reshape component sourcing and test certification burdens.
Market Dynamics
Silicon photonics integration is compressing component footprints and power budgets across Asia-Pacific data centers, forcing incumbent suppliers to retool fabrication lines or surrender optical transceiver sockets to vertically integrated semiconductor houses.
Growth Catalysts
- Automotive LiDAR mandates:Japanese and Korean OEMs are embedding solid-state scanning modules into Level 2+ ADAS platforms, pulling VCSEL and SPAD volumes from industrial sensing into vehicle programs.
- MIIT dual carbon enforcement:China's GB standards for luminous efficacy are phasing out legacy fluorescent and first-generation LED luminaires from government procurement, redirecting demand toward high-efficiency solid-state packages.
- Quantum dot display penetration:South Korean panel manufacturers are converting photolithography lines to inkjet-printed QD color conversion layers for premium television and monitor segments.
Market Restraints
- III-V epitaxy supply concentration:GaAs and InP wafer production clusters in Taiwan and Japan create single-source vulnerability for laser diode and photodetector foundries across the region.
- Dual-use export control friction:Japan's METI and South Korea's trade ministry maintain separate licensing regimes for high-power laser diodes above specified wattage thresholds, fragmenting cross-border component flows.
- Silicon carbide substrate cost:UV-C LED and power optoelectronic devices face margin compression from 6-inch SiC wafer pricing volatility tied to automotive power electronics demand.
Strategic Opportunities
- Vietnam and Indonesia manufacturing buildout:Display module assembly and camera module integration are migrating from coastal China to ASEAN industrial zones seeking tariff diversification and labor cost arbitrage.
- Photonic biosensor convergence:Integration of CMOS image sensors with microfluidic cartridges is opening diagnostic instrumentation markets regulated under South Korea's MFDS and Japan's PMDA frameworks.
- Smart city lighting retrofits:India's Smart Cities Mission and municipal procurement in Thailand are mandating networked solid-state streetlighting with embedded environmental sensing.
Industry Challenges
- Compound semiconductor process engineering shortage:MOCVD reactor operation and III-V device physics expertise concentrates in legacy Japanese and Korean fabs, constraining capacity expansion in newer manufacturing locations.
- Multi-jurisdiction certification stacking:Medical optoelectronic devices require sequential MFDS, PMDA, and NMPA approvals with non-harmonized test protocols, extending time-to-revenue for diagnostic imaging OEMs.
- Legacy automotive qualification timelines:LiDAR and adaptive headlamp modules face 24-36 month AEC-Q102 validation cycles that misalign with consumer electronics speed-to-market expectations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Optoelectronics Market |
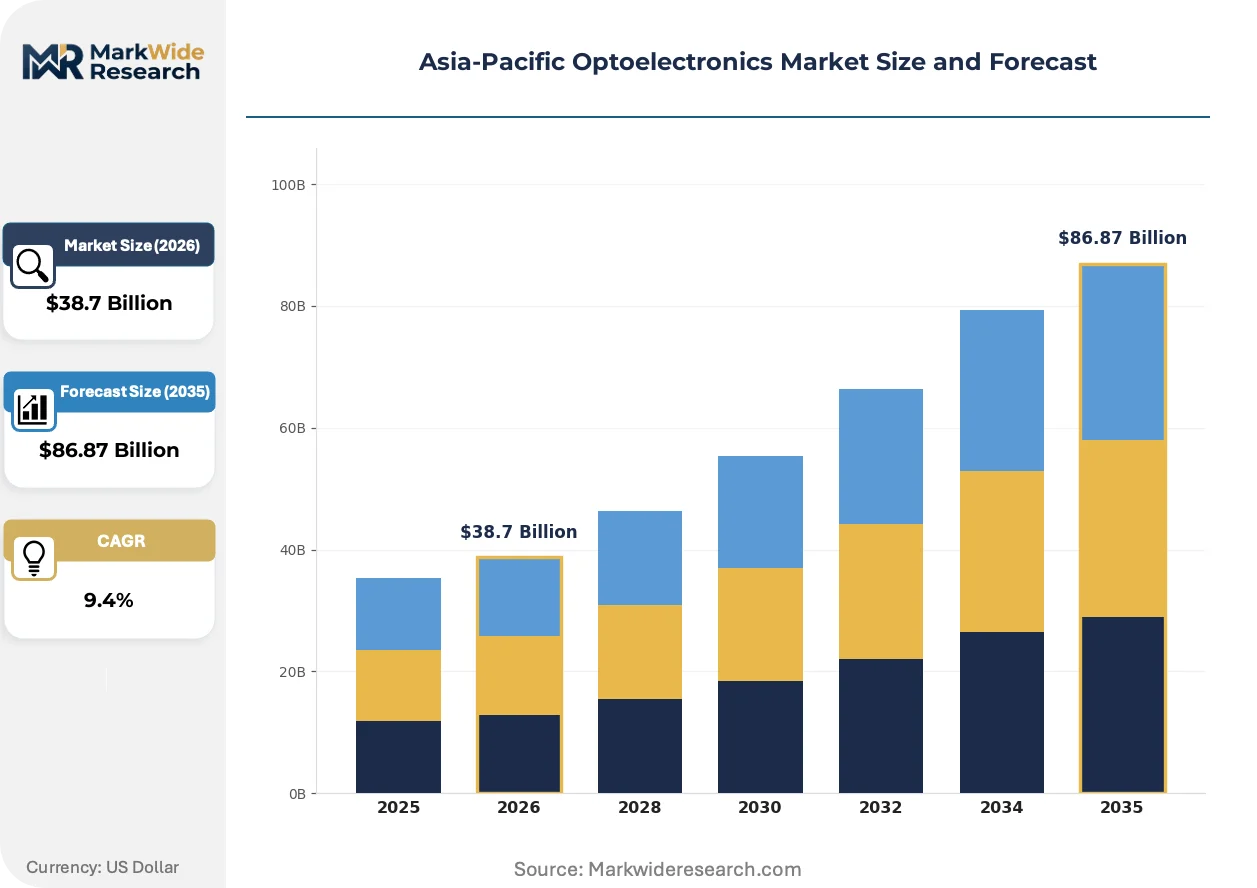
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $86.87 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Light Emitting Diodes, Photovoltaics, Laser Diodes, Solid State Lighting Technology: Fiber Optics, Quantum Dots, Organic Light Emitting Diodes, Photonic Crystals Application: Consumer Electronics, Telecommunications, Automotive Lighting, Medical Devices End User: Telecom Providers, Healthcare Institutions, Manufacturers, Retailers |
| Companies Covered | Omnivision Technologies Inc., Seoul Semiconductor, Samsung Electronics, Sharp Corporation, Hamamatsu Photonics, Panasonic Corporation, Nichia Corporation, LG Innotek, Sony Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Optoelectronics Market Trends and Innovations
Three simultaneous vectors are restructuring Asia-Pacific optoelectronics: photonic integration architectures, efficiency mandates tightening component specifications, and procurement consolidation among hyperscale data center operators.
Silicon photonics is digitizing optical interconnect layers by embedding modulators, waveguides, and photodetectors onto CMOS-compatible substrates. Cloud service providers in Singapore and Sydney are deploying 800G coherent transceivers at rack scale, compressing the addressable market for discrete component vendors and favoring foundries with in-house silicon photonics capability.
China's MIIT is accelerating solid-state lighting efficiency thresholds through successive GB standard revisions that phase out products below specified lumens-per-watt floors. Domestic lighting OEMs are responding by migrating from mid-power plastic packages to ceramic-substrate high-power LEDs, reshaping substrate and phosphor supply chains toward sapphire and nitride materials.
Hyperscale data center operators are consolidating optical component procurement through direct long-term agreements with Korean and Japanese transceiver manufacturers, bypassing traditional distribution layers. This concentration is visible most acutely in Singapore and Tokyo metro markets where submarine cable landings and cloud region buildouts coincide, compressing reseller margins and favoring vertically integrated suppliers with captive laser and detector fabrication.
Asia-Pacific Optoelectronics Market Segmentation
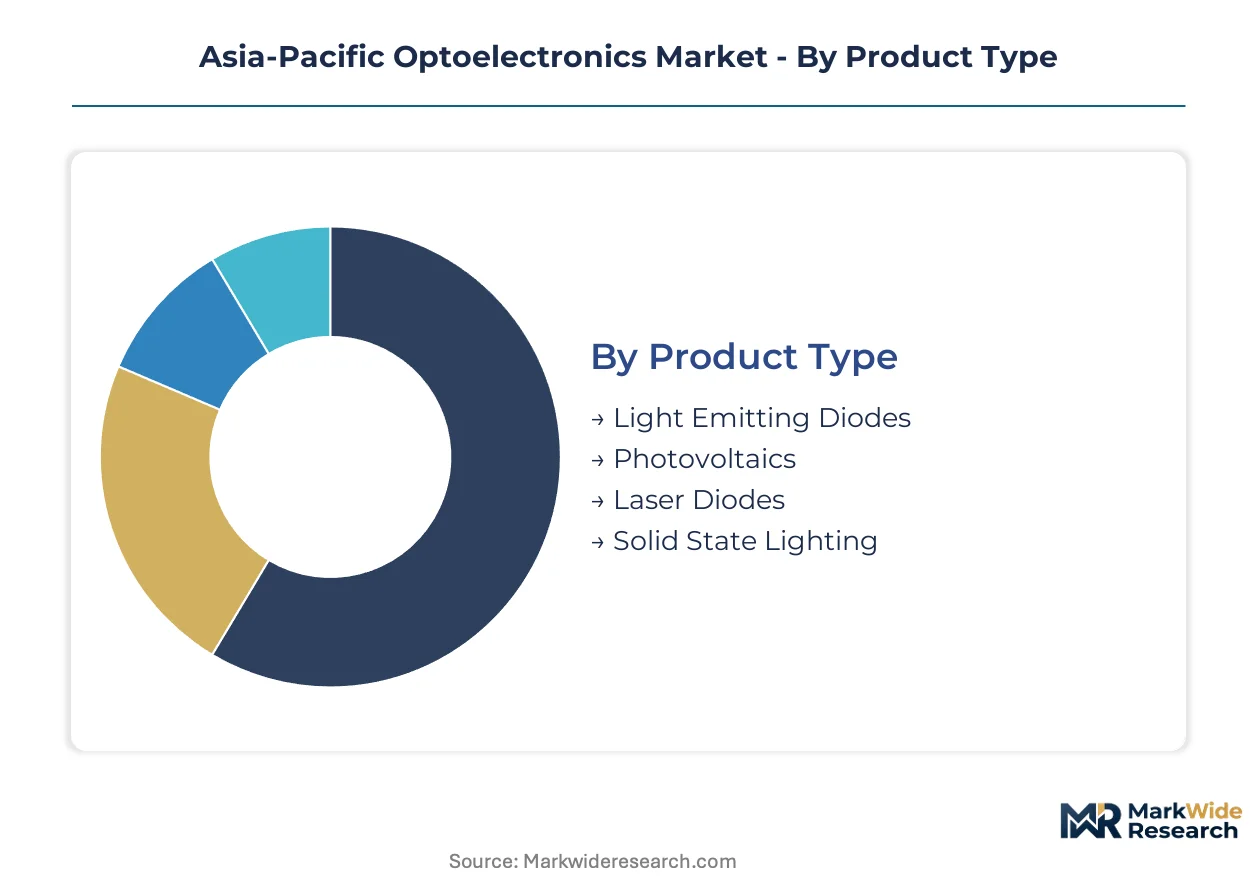
Optoelectronics procurement patterns diverge sharply across product architectures, fabrication technologies, and end-use qualification requirements. Understanding these segment boundaries clarifies where pricing power concentrates and which technology transitions threaten incumbent positions.
Product Type:
Cost tier determines package substrate selection, thermal management complexity, and phosphor formulation grade across solid-state emitters.
- Light Emitting Diodes:Mid-power plastic packages dominate volume shipments for general illumination, while ceramic-substrate high-power variants capture premium sockets in automotive headlamps and horticultural fixtures. China's MIIT GB efficiency mandates are accelerating migration toward the latter category in government procurement.
- Laser Diodes:Edge-emitting and VCSEL architectures span 780nm through 1550nm wavelengths, with GaAs epitaxy supply from Taiwanese foundries constraining available capacity. Japanese and Korean OEMs are pulling volumes into solid-state LiDAR modules for Level 2+ ADAS platforms.
- Photovoltaics:III-V multi-junction cells serve concentrated solar installations and satellite power systems.
- Solid State Lighting:Integrated luminaire assemblies combine emitter modules with driver electronics and thermal management for commercial and residential retrofit markets.
Light Emitting Diodes commands the established base. The steepest expansion runs through Laser Diodes.
Technology:
Application requirements for bandwidth, color purity, or mechanical flexibility dictate which material systems and fabrication approaches win design sockets.
- Quantum Dots:Colloidal semiconductor nanocrystals enable narrow emission spectra unattainable with phosphor-converted white LEDs, with inkjet-printed color conversion layers now penetrating premium television panels from South Korean manufacturers. The technology climbs fastest as display makers pursue Rec. 2020 color gamut coverage.
- Fiber Optics:Silica and plastic optical fiber infrastructure underpins submarine cable landings and intra-data-center interconnects across Singapore, Sydney, and Tokyo metro markets. Cloud operators are consolidating procurement through direct agreements with Japanese and Korean transceiver houses.
- Organic Light Emitting Diodes:Thin-film emissive layers enable flexible display form factors and area lighting sources.
- Photonic Crystals:Periodic dielectric structures manipulate light propagation for sensing and communication applications.
Fiber Optics anchors current infrastructure deployment. The steepest expansion trajectory belongs to Quantum Dots.
Application:
Volume concentration and qualification timelines separate consumer-facing deployments from industrial and regulated medical environments.
- Consumer Electronics:Camera modules, display backlights, and proximity sensors absorb the largest unit volumes, with LG Innotek and Korean handset OEMs sustaining tight integration for flagship smartphone programs. Product cycles measured in months contrast sharply with automotive validation timelines.
- Automotive Lighting:Adaptive headlamps and interior ambient systems are widening as electric vehicle production scales across the region, pulling optoelectronic content per vehicle upward through solid-state scanning modules and matrix LED configurations.
- Telecommunications:Optical transceivers and amplification stages serve fiber optic network infrastructure.
- Medical Devices:Phototherapy and diagnostic imaging equipment face multi-jurisdiction approval stacking under Japan's PMDA and South Korea's MFDS frameworks.
Consumer Electronics commands the established base. The steepest expansion runs through Automotive Lighting.
End User:
Procurement scale and technical specification authority determine whether component vendors sell direct or through distribution layers.
- Telecom Providers:Hyperscale cloud operators and national carriers in Singapore, Japan, and Australia are bypassing traditional distribution through long-term agreements with vertically integrated transceiver manufacturers, compressing reseller margins in submarine cable landing zones.
- Manufacturers:Tier-1 automotive suppliers and display panel makers purchase emitter and sensor components for integration into larger assemblies, with Vietnam and Indonesia emerging as alternative assembly locations for tariff diversification.
- Healthcare Institutions:Hospitals and clinics procure finished diagnostic and therapeutic equipment rather than discrete optoelectronic components.
- Retailers:Lighting OEMs and consumer electronics channels distribute finished products to commercial and residential end markets.
Manufacturers commands the established base. The steepest expansion runs through Telecom Providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Telecom providers and automotive OEMs concentrate procurement authority across four distinct national markets, each with divergent regulatory frameworks and manufacturing specializations.
China
MIIT dual carbon mandates are phasing inefficient luminaires from government procurement, redirecting demand toward ceramic-substrate high-power LEDs. GB standards revisions enforce successive lumens-per-watt floors that domestic lighting OEMs must meet. Yangtze River Delta fabrication clusters around Shanghai and Suzhou are retooling mid-power plastic package lines toward sapphire-substrate emitters.
Japan
METI enforces JIS standards for laser safety and optical component reliability that filter export-ready products from domestic consumption-grade alternatives. PMDA medical device frameworks create compliance thresholds for phototherapy equipment targeting regional hospital procurement. Chubu region industrial corridors around Hamamatsu sustain concentrated photodetector and sensor module fabrication.
South Korea
MFDS and KATS regulatory frameworks govern medical optoelectronic exports, creating sequential approval requirements for diagnostic imaging OEMs. Display panel manufacturers are converting photolithography capacity toward inkjet-printed quantum dot color conversion layers. Seoul Capital Area and Busan-Ulsan corridors anchor camera module assembly and image sensor supply chains.
Taiwan
GaAs and InP wafer foundries create single-source vulnerability for regional laser diode and photodetector supply. Trade ministry licensing maintains separate regimes for high-power laser diodes above specified wattage thresholds. Hsinchu Science Park clusters concentrate MOCVD reactor capacity and III-V epitaxy expertise.
Vietnam
Tariff diversification incentives are pulling display module assembly and camera module integration from coastal China. Municipal procurement programs under national smart city directives mandate networked solid-state streetlighting with embedded sensing. Northern industrial zones around Hanoi and Hai Phong are absorbing Korean and Japanese component vendor facility relocation.
Asia-Pacific Optoelectronics Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where scale-driven semiconductor houses and captive fabrication units hold pricing leverage over discrete component vendors. The vendor base separates into three strategic archetypes: vertically integrated electronics conglomerates with in-house emitter and sensor production, standalone optoelectronic component specialists with deep epitaxy expertise, and modular assembly houses serving handset and automotive programs. Dominant competitive moves include backward integration into III-V wafer supply and geographic expansion into ASEAN manufacturing zones.
Among Japanese and Korean fabricators, Hamamatsu Photonics, Samsung Electronics, and LG Innotek occupy distinct positions within the competitive matrix. Hamamatsu Photonics exemplifies the photodetector specialist archetype with concentrated industrial and medical instrumentation exposure. Samsung Electronics represents the vertically integrated conglomerate model with captive semiconductor fabrication anchoring regional display and image sensor supply. LG Innotek sits within the modular assembly tier, sustaining volume through tight integration with Korean handset OEMs for flagship smartphone camera programs.
| Leading Market Players |
|---|
| Omnivision Technologies Inc. |
| Seoul Semiconductor |
| Samsung Electronics |
| Sharp Corporation |
| Hamamatsu Photonics |
| Panasonic Corporation |
| Nichia Corporation |
| LG Innotek |
| Sony Corporation |
| Others |
Pricing and Supply Chain Analysis
The Shanghai-Singapore maritime corridor carries III-V epitaxy wafers and MOCVD reactor components from Yangtze River Delta fabrication clusters to ASEAN assembly zones, with freight cost volatility amplifying margin compression for ceramic-substrate LED packages and compressing price spreads between high-efficiency emitters and mid-power alternatives procured by Vietnamese display integrators.
Pricing Analysis
Cost-plus contracts for GaAs and InP wafers from Taiwanese foundries carry indexation to spot silicon carbide substrate pricing, anchoring laser diode component costs. Three-tier pricing structure across automotive-grade AEC-Q102 certified, industrial-grade, and consumer-grade photodetectors separates qualification-burdened products from commodity alternatives. Pricing pressure stems from hyperscale data center operators consolidating optical transceiver procurement through direct long-term agreements. Tier-1 automotive suppliers exhibit lowest price sensitivity due to 24-36 month validation lock-in, while municipal lighting procurement in Vietnam and Thailand shows highest sensitivity to luminaire unit economics.
Supply Chain Analysis
Japan's METI and South Korea's trade ministry maintain separate licensing regimes for high-power laser diodes above specified wattage thresholds, fragmenting cross-border component flows between Hsinchu Science Park epitaxy foundries and Busan-Ulsan camera module assembly corridors. Supply concentration rests on Taiwan for GaAs and InP wafer production, Japan for photodetector architectures, and South Korea for display panel and image sensor integration. Raw material dependencies center on sapphire substrates, rare-earth phosphors, and high-purity gallium. Single-source vulnerability in III-V epitaxy creates structural risk. Distribution runs through vertically integrated semiconductor houses and modular assembly partners serving Korean handset OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon photonics integration is transforming Asia-Pacific optoelectronics into a platform-economy structure where interoperability between CMOS-compatible optical interconnects and legacy III-V architectures determines competitive survival, with Samsung Electronics' captive fabrication ecosystem exemplifying the interoperability shift now forcing retooling decisions across regional foundries.
For Market Incumbents: Harden supply chain resilience through backward integration into sapphire and nitride substrate supply, insulating against silicon carbide pricing volatility driven by automotive power electronics demand. Secure AEC-Q102 certification pipelines for photodetector modules to defend against Chinese lighting OEMs migrating into automotive LiDAR component supply. Prioritize MOCVD reactor capacity expansion in Vietnam and Indonesia to offset tariff exposure from coastal China concentration. For New Entrants and Emerging Players: Build out photonic biosensor convergence capabilities targeting South Korea's MFDS and Japan's PMDA diagnostic imaging approval pathways, where multi-jurisdiction certification stacking creates incumbent fatigue. Target India's Smart Cities Mission networked streetlighting procurement as the most penetrable municipal infrastructure segment. Pursue joint development agreements with CMOS image sensor houses for microfluidic cartridge integration rather than discrete component sales. For Investors and Strategic Acquirers: China's MIIT dual carbon enforcement reshapes the acquisition landscape by filtering inefficient luminaire manufacturers from government procurement eligibility, concentrating viable targets among ceramic-substrate high-power LED specialists. Frame long-term viability around 5-10 year platform consolidation where silicon photonics capability separates surviving foundries from displaced discrete component vendors. Watch for Japanese METI export control expansion to high-power VCSEL arrays as the signal indicating regulatory-driven supply chain restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into III-V Epitaxy | Captive GaAs wafer supply from Hsinchu Science Park clusters insulates against single-source vulnerability. |
| Silicon Photonics Foundry Conversion | CMOS-compatible optical transceiver production captures hyperscale data center procurement consolidation. |
| ASEAN Manufacturing Footprint Expansion | Vietnam and Indonesia assembly zones absorb tariff diversification migration from coastal China. |
| Multi-Jurisdiction Certification Pre-Positioning | Sequential MFDS, PMDA, and NMPA approval readiness accelerates diagnostic imaging time-to-revenue. |
| Quantum Dot Color Conversion Layer Investment | Inkjet-printed QD capacity aligns with South Korean panel manufacturer Rec. 2020 gamut pursuit. |
Research Methodology
The analysis maps LED package architectures, laser diode wavelength segments, and photodetector application tiers, each validated through procurement directors at hyperscale data center operators, MOCVD reactor engineers at Taiwanese foundries, and regulatory affairs specialists navigating Japan's METI licensing regimes. Primary interviews with automotive Tier 1 supplier quality engineers, display panel manufacturing heads in Seoul Capital Area corridors, and municipal lighting procurement officers in Vietnam combined with secondary validation from MIIT GB standard revision filings, Japan's JIS laser safety documentation, and hyperscaler capex disclosure trajectories. Bottom-up unit economics triangulated against top-down regional demand aggregation.
Assumptions held fixed include China's MIIT dual carbon enforcement trajectory, Japan's METI export control wattage thresholds, and South Korea's MFDS medical device approval timelines; varied assumptions encompass silicon carbide substrate pricing volatility and hyperscale data center buildout pacing across Singapore and Sydney metro markets. Segmentation dimensions modeled span product type, fabrication technology, application qualification requirements, and end-user procurement scale. CAGRs derived from installed base replacement cycles and content-per-unit expansion in automotive and display applications, with fiber optic infrastructure deployment and quantum dot display penetration as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated semiconductor houses or unexpected relaxation of Japan-South Korea export control friction would shift outcomes. Material shifts in China's GB efficiency mandate enforcement intensity or automotive LiDAR qualification timeline compression would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optoelectronics
Ingaas Avalanche Photodiode Market
Optoelectronics
IT & Telecom Optoelectronics Market
Optoelectronics
Smart Compact Projectors Market
Optoelectronics
Global Optoelectronic Components Market
Optoelectronics
Global Opto-Isolator Market
Optoelectronics
Laser Projector Market
Optoelectronics
Heterojunction Solar Cell Market
Optoelectronics
Quantum Dot Lasers Market
Optoelectronics
China Optical Detector Market
Optoelectronics
Europe Wigig Market
Optoelectronics
Cadmium Telluride Photovoltaic Market
Optoelectronics
2-Ethyl-3,4-Ethylenedioxythiophene Market
Optoelectronics
3D Projector Market
Optoelectronics
Quantum Cascade Lasers Market
Optoelectronics
Gunn Diode Market
Optoelectronics
Quantum Dot Solar Cell Market