
 Global Waveguide Components and Assemblies Market | 2026-2036
Global Waveguide Components and Assemblies Market Size, Share, and Industry Trends Forecast 2026-2036
Global Waveguide Components and Assemblies Market Outlook
Southeast Asia is fragmenting as a waveguide manufacturing corridor as Vietnam and Thailand attract precision metalworking investments from Japanese and Taiwanese suppliers. Northrop Grumman Corporation leverages captive semiconductor foundry relationships to secure gallium nitride substrates for high-power waveguide assemblies. L3Harris Technologies, Inc. anchors its position through long-term sustainment contracts with the US Department of Defense for shipboard radar waveguide networks. Cobham Limited specializes in hermetically sealed waveguide feeds for satellite payloads, competing against newer entrants from South Korea's defense industrial base.
Waveguide components and assemblies are hollow metallic or dielectric conduits engineered to propagate electromagnetic waves with minimal loss, typically fabricated from aluminum, brass, or silver-plated copper via CNC milling and electroforming processes. These structures channel microwave and millimeter-wave energy between transmitters, antennas, and receivers in systems where coaxial cable attenuation proves excessive. Passive waveguide terminations and bends dominate volume demand across telecommunications infrastructure, while hybrid active-passive assemblies command premium positioning in defense radar upgrades. Ceramic-based waveguide segments are gaining traction in medical imaging equipment where thermal stability and biocompatility intersect, though metal waveguides still occupy the bulk of aerospace and defense procurement specifications.
The US Federal Communications Commission spectrum reallocation mandates are forcing telecommunications equipment vendors to redesign waveguide paths for higher-frequency 5G millimeter-wave bands. Europe's REACH chemical regulations and RoHS directives constrain plating chemistries and solder compositions used in waveguide manufacturing, compelling suppliers to qualify alternative surface finishes. China's Ministry of Industry and Information Technology enforces domestic content ratios for critical communication infrastructure, reshaping supply access for foreign waveguide vendors. Stakeholders must monitor how national security classifications around microwave technology alter cross-border licensing requirements for precision waveguide exports.
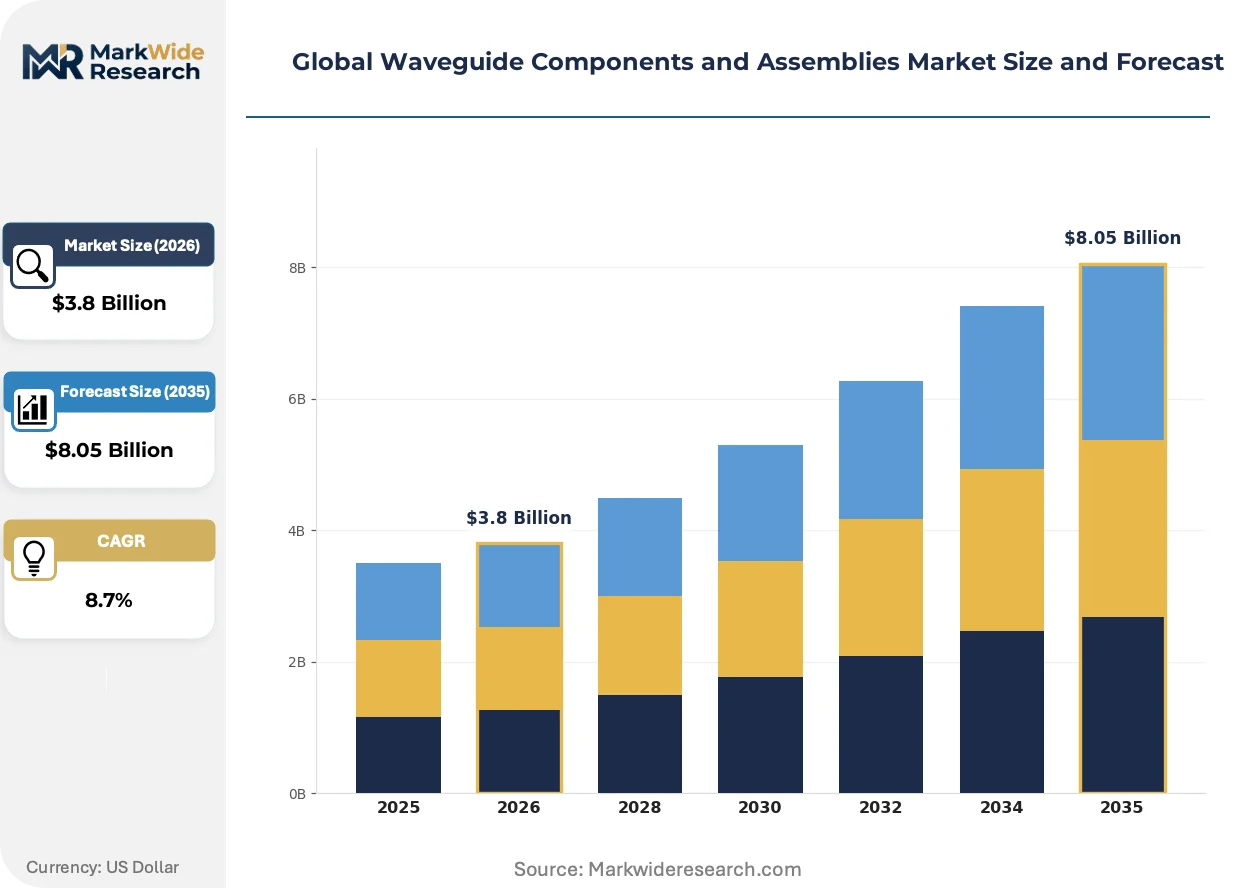
Market Dynamics
Defense procurement programs across NATO allies are concentrating demand for high-power waveguide assemblies in radar and electronic warfare systems, while telecommunications operators in Germany and South Korea are accelerating millimeter-wave backhaul deployments that favor low-loss metallic waveguides over coaxial alternatives.
Growth Catalysts
- REACH and RoHS Directives:Europe's chemical regulations are compelling suppliers to qualify alternative surface finishes and solder compositions, creating first-mover advantages for vendors with compliant plating chemistries.
- Millimeter-wave 5G Infrastructure:Telecommunications operators are deploying dense small-cell networks that require precision waveguide paths to minimize signal attenuation at frequencies above 24 GHz.
- Dual Carbon Goals:China's state-directed procurement for domestic 5G build-out is channeling waveguide demand toward local suppliers capable of meeting MIIT domestic content ratios.
Market Restraints
- Raw Material Volatility:Silver-plated copper substrates face price pressure from precious metal markets, compressing margins for electroformed waveguide manufacturers.
- Supply Concentration Risk:Gallium nitride substrate production for high-power assemblies concentrates among captive semiconductor foundries, limiting access for independent waveguide vendors.
- Technical Limitation:Ceramic-based waveguide segments remain niche due to brittleness in aerospace vibration environments, constraining penetration beyond medical imaging equipment.
Strategic Opportunities
- Thailand Precision Metalworking:Japanese and Taiwanese suppliers are establishing CNC milling capacity in Southeast Asia to serve regional telecommunications infrastructure projects.
- Satellite Payload Hermetic Sealing:Low-earth orbit constellation deployments are creating demand for vacuum-compatible waveguide feeds with space-qualified thermal cycling performance.
- Medical Imaging Convergence:Thermal stability requirements in MRI systems are opening applications for ceramic waveguide segments where biocompatibility intersects with electromagnetic performance.
Industry Challenges
- Electroforming Skill Shortage:Precision waveguide fabrication requires specialized technicians capable of controlling deposit thickness tolerances below 25 microns.
- Cross-border Licensing Complexity:National security classifications around microwave technology are altering export control requirements for precision waveguide assemblies with defense applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Waveguide Components and Assemblies Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Couplers, Adapters, Bends, Terminations Material: Metal, Plastic, Ceramic, Composite Technology: Passive, Active, Hybrid, Digital End User: Aerospace, Telecommunications, Defense, Medical |
| Companies Covered | Northrop Grumman Corporation, Teledyne Technologies Inc., L3Harris Technologies, Inc., Quantic Electronics, Millimeter Wave Products Inc., Cobham Limited, ETL Systems, Ducommun Incorporated, Amplitech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Waveguide Components and Assemblies Market Strategic Shifts
Active-passive hybrid architectures are compressing traditional boundaries between discrete waveguide components and integrated RF subsystems, while regulatory mandates on both sides of the Atlantic are rewriting material specifications and design rules.
Additive manufacturing of aluminum waveguide channels via laser powder bed fusion is collapsing lead times for complex bend geometries that previously required multi-axis CNC programming and fixture investment. Defense prime contractors are qualifying printed waveguide manifolds for low-volume radar prototypes, compressing the traditional electroforming-to-delivery cycle from weeks to days. This acceleration is collapsing the competitive advantage of established suppliers with sunk capital in conventional machining centers.
FCC spectrum reallocation mandates are forcing telecommunications equipment vendors to redesign waveguide paths for higher-frequency 5G millimeter-wave bands above 28 GHz. The industrial consequence is a qualification rush for low-loss aluminum alloys and novel plating chemistries that maintain conductivity at these frequencies. Equipment vendors in the United States are responding by consolidating supplier bases to vendors with demonstrated FCC pre-certification testing capabilities.
Buyer concentration among defense prime contractors is compressing procurement cycles and unbundling after-sales service from hardware supply. Long-term sustainment contracts for shipboard radar networks now specify performance-based logistics rather than discrete component orders. This shift is most visible in US Department of Defense procurement, where L3Harris Technologies and Northrop Grumman are negotiating decade-spanning agreements that internalize waveguide network maintenance within original equipment manufacturer responsibilities.
Global Waveguide Components and Assemblies Market Segmentation
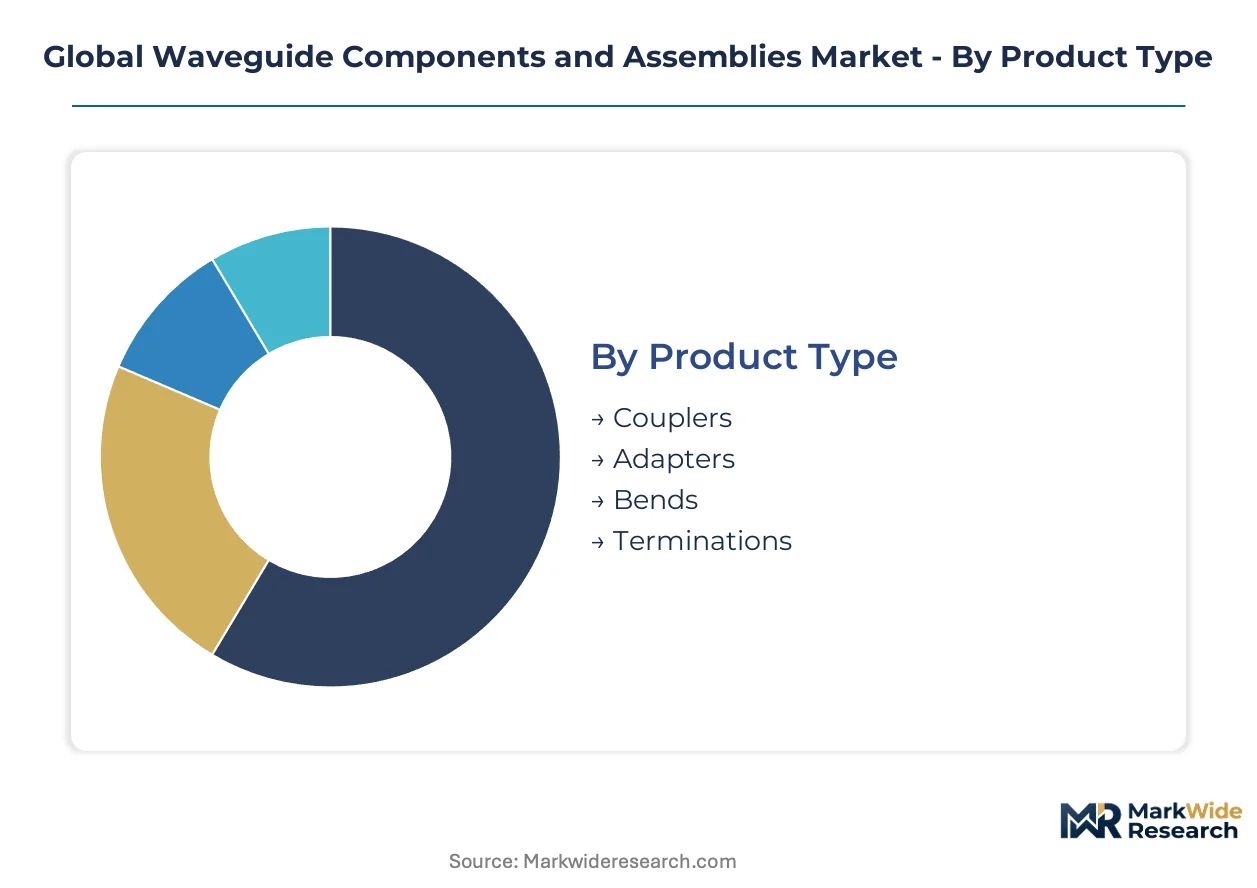
Waveguide component segmentation reveals how technical specifications, material constraints, and end-use requirements fragment procurement patterns across defense, telecommunications, and medical equipment supply chains. Each dimension carries distinct margin profiles and after-sales service intensities that reshape supplier economics.
Product Type:
After-sales service intensity varies sharply across product types, with complex assemblies demanding field calibration support while standard terminations require minimal technical intervention.
- Couplers:Directional and hybrid couplers split or combine microwave signals with defined coupling ratios, typically fabricated via precision machining of aluminum housings. NATO defense procurement programs in Germany and the United Kingdom are concentrating demand for high-power couplers in phased-array radar upgrades, where field failure carries mission-critical consequences. Service contracts for these units often span 15-20 years.
- Adapters:Waveguide-to-coaxial and inter-size adapters bridge impedance mismatches between transmission line types, demanding tight tolerances on flange alignment and surface finish. Telecommunications infrastructure build-outs in South Korea are accelerating adapter procurement for 5G millimeter-wave base stations, where rapid deployment cycles compress supplier response windows. Adapter replacement rates exceed other categories due to mechanical wear at connection points.
- Bends:E-plane and H-plane bends redirect waveguide paths with minimal reflection loss; compact geometries suit dense packaging in satellite payloads.
- Terminations:Matched loads absorb residual microwave energy to prevent standing waves; passive designs dominate volume demand with lowest service attachment rates.
Couplers hold the largest share; momentum sits with adapters as 5G deployment accelerates.
Material:
Cost tier differentiation separates premium substrates from commodity options, with precious metal plating chemistries commanding 3-5x raw material multiples over base aluminum.
- Metal:Aluminum, brass, and silver-plated copper constitute the dominant substrate class, with electroformed copper achieving conductivity benchmarks required for high-frequency defense applications. REACH and RoHS directives in Europe are compelling qualification of alternative plating chemistries, favoring suppliers with pre-certified surface finish portfolios. Metal waveguides retain specification dominance across aerospace and defense procurement.
- Ceramic:Alumina and aluminum nitride substrates deliver thermal stability and biocompatibility for medical imaging equipment, particularly MRI systems where patient proximity demands non-conductive, non-magnetic properties. Ceramic segments remain niche due to brittleness under aerospace vibration loads, constraining penetration beyond healthcare applications. Thermal cycling performance exceeds metal alternatives in controlled environments.
- Plastic:Injection-molded dielectric waveguides serve low-power consumer and automotive radar applications where cost minimization outweighs loss tolerance.
- Composite:Metal-polymer laminates and coated substrates target weight-sensitive satellite applications seeking electromagnetic performance with mass reduction.
Metal substrates dominate procurement volume; ceramic formulations are climbing the fastest as medical equipment specifications tighten.
Technology:
Application requirements determine technology selection, with defense radar systems tolerating no active component failure while telecommunications infrastructure prioritizes cost-optimized passive paths.
- Passive:Non-amplifying waveguide structures channel electromagnetic energy without powered components, occupying the bulk of telecommunications infrastructure demand for 5G backhaul networks. Germany's millimeter-wave deployment programs are concentrating procurement of passive aluminum waveguides for small-cell densification, where low insertion loss at 28 GHz frequencies determines link budgets. Passive architectures minimize field maintenance requirements and sustain 20+ year service lives.
- Active:Solid-state power amplifiers and low-noise amplifiers integrated into waveguide structures enable signal conditioning at the antenna interface. Gallium nitride substrate access through captive semiconductor foundries is limiting independent vendor participation in high-power active assemblies for electronic warfare systems. Active units carry 4-6x unit costs and elevated failure rates requiring swap-out logistics.
- Hybrid:Active-passive combinations compress discrete component boundaries into integrated RF subsystems for compact radar and communication payloads.
- Digital:Software-defined waveguide tuning and adaptive impedance matching represent emerging architectures for cognitive radio applications.
Passive technology holds the largest share; hybrid configurations are gaining share fastest as prime contractors consolidate subsystem suppliers.
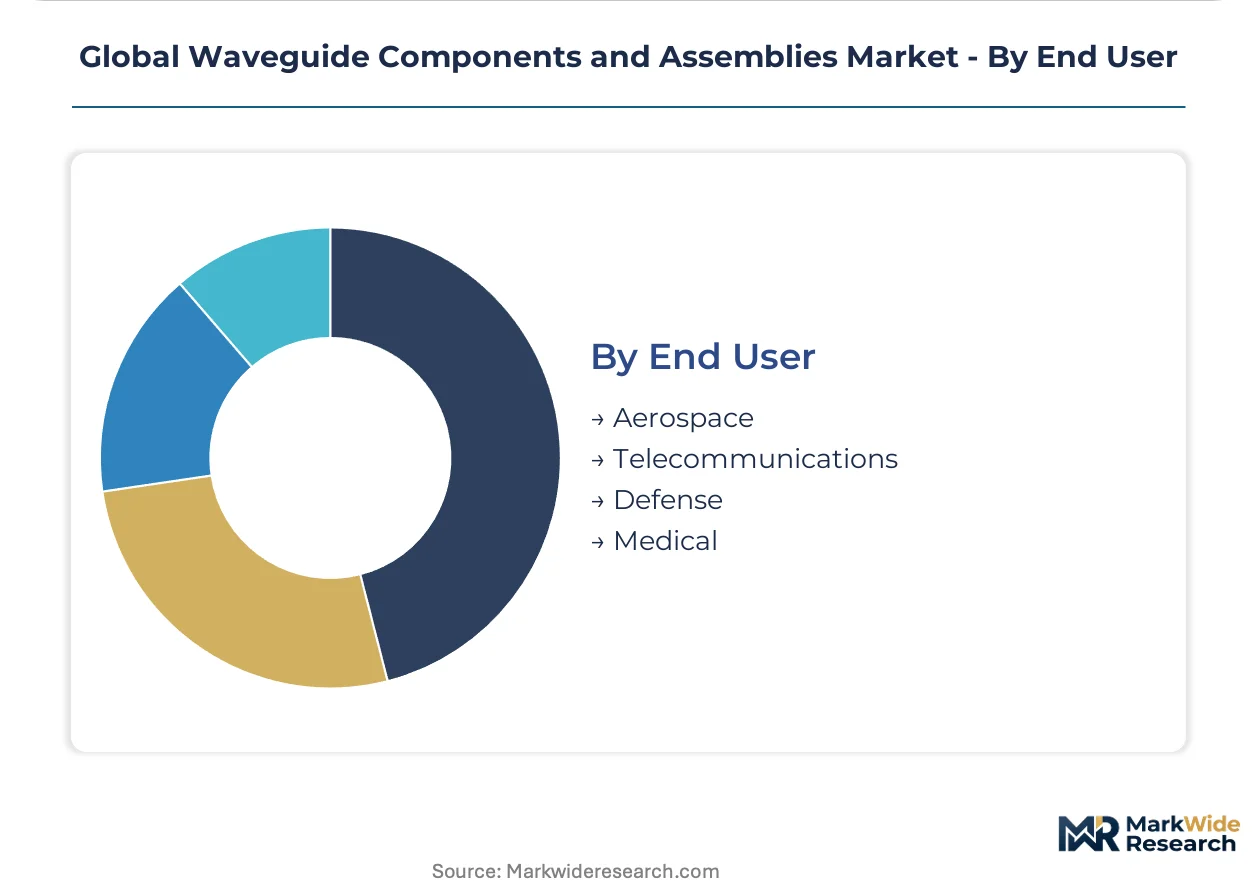
End User:
Customer type fragmentation concentrates procurement authority among defense prime contractors and telecommunications equipment vendors, with medical OEMs representing smaller but higher-margin demand pockets.
- Defense:Radar, electronic warfare, and satellite communication systems specify waveguide networks with military-grade environmental qualification and traceability documentation. The US Department of Defense is negotiating decade-spanning sustainment contracts that internalize waveguide network maintenance within original equipment manufacturer responsibilities, collapsing traditional component-aftermarket boundaries. Shipboard radar networks represent the most intensive service attachment segment.
- Telecommunications:Base station backhaul and fronthaul infrastructure drives volume demand for standardized waveguide assemblies, with FCC spectrum reallocation mandates forcing redesigns for millimeter-wave bands above 28 GHz. Equipment vendors are consolidating supplier bases to vendors with demonstrated FCC pre-certification testing capabilities, reducing qualified vendor counts by 30-40%.
- Aerospace:Commercial and military aircraft radar and communication systems demand lightweight, vibration-resistant waveguide routing with fire-resistant specifications.
- Medical:MRI and therapeutic equipment applications exploit ceramic waveguide biocompatibility where patient contact occurs, representing the highest margin-per-kilogram segment despite smaller volumes.
Defense end-use holds the largest share; telecommunications is expanding most quickly as 5G infrastructure investment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC spectrum reallocation mandates are forcing telecommunications equipment vendors across the United States to redesign waveguide paths for higher-frequency 5G millimeter-wave bands above 28 GHz. This regulatory pressure is cascading through allied defense procurement programs and commercial infrastructure deployments worldwide.
United States
Defense prime contractors are negotiating decade-spanning sustainment contracts with the Department of Defense for shipboard radar waveguide networks. FCC pre-certification testing capabilities are consolidating supplier bases by 30-40% as equipment vendors qualify vendors for millimeter-wave redesigns. Greater Boston and the Pacific Northwest host precision electroforming clusters serving satellite payload applications.
Germany
Telecommunications operators are accelerating millimeter-wave backhaul deployments that favor low-loss metallic waveguides over coaxial alternatives. REACH and RoHS directives are compelling suppliers to qualify alternative plating chemistries and solder compositions. Bavaria anchors precision machining capacity for regional 5G small-cell densification programs.
China
MIIT domestic content ratios for critical communication infrastructure are channeling waveguide demand toward state-directed local suppliers. Dual carbon goals are concentrating procurement within domestic supplier bases capable of meeting state-directed build-out timelines. Yangtze River Delta clusters are absorbing precision metalworking investments for 5G infrastructure.
South Korea
Telecommunications operators are deploying dense small-cell networks requiring precision waveguide paths to minimize signal attenuation above 24 GHz. The defense industrial base is producing newer entrants competing against established satellite payload specialists. Seoul Capital Area foundries are securing gallium nitride substrate access for high-power active assemblies.
Vietnam
Japanese and Taiwanese suppliers are establishing CNC milling capacity to serve regional telecommunications infrastructure projects. Precision metalworking investments are fragmenting Southeast Asia's manufacturing corridor as Thailand competes for similar foreign direct investment. Ho Chi Minh City industrial zones are absorbing waveguide component fabrication for export markets.
Global Waveguide Components and Assemblies Market Competitive Environment
Defense prime contractors and precision fabrication specialists split the market along capability-intensity lines. The vendor base concentrates among tier-one suppliers with captive semiconductor foundry relationships and long-term sustainment contract experience. Two strategic archetypes dominate: integrated defense primes with internal waveguide production and independent precision fabricators serving commercial telecommunications. Competitive moves center on M&A to secure electroforming skill bases and geographic expansion into Southeast Asian precision metalworking corridors.
Among US-based defense primes, Northrop Grumman Corporation and L3Harris Technologies, Inc. exemplify the integrated archetype through their positioning in long-term Department of Defense sustainment negotiations. Cobham Limited represents the hermetic sealing specialization tier for satellite payload applications. These three anchors demonstrate how captive supply relationships and performance-based logistics contracts are restructuring competitive boundaries between hardware supply and aftermarket service.
| Leading Market Players |
|---|
| Northrop Grumman Corporation |
| Teledyne Technologies Inc. |
| L3Harris Technologies, Inc. |
| Quantic Electronics |
| Millimeter Wave Products Inc. |
| Cobham Limited |
| ETL Systems |
| Ducommun Incorporated |
| Amplitech |
| Others |
Value Chain & Pricing Dynamics
Yangtze River Delta precision metalworking clusters are absorbing capacity investments from state-directed 5G infrastructure procurement, concentrating domestic supplier pricing power while foreign vendors face MIIT domestic content ratio barriers. This geographic supply concentration enables Chinese waveguide manufacturers to command premium positioning for high-frequency millimeter-wave assemblies, whereas electroformed copper specialists in Greater Boston and Bavaria compete on REACH-compliant plating certifications and FCC pre-certification testing capabilities.
Pricing Analysis
Asian-origin aluminum waveguide assemblies trade at 15-25% discounts to European equivalents, reflecting lower CNC milling labor costs and consolidated raw material sourcing. Three-tier pricing structure across defense-grade certified, telecommunications-standard, and industrial-economy levels separates procurement tiers by traceability documentation and thermal cycling test rigor. Cost compression in telecommunications-standard tiers is intensifying because equipment vendors are consolidating supplier bases by 30-40% to vendors with demonstrated FCC pre-certification capabilities. Defense prime contractors exhibit lowest price sensitivity due to decade-spanning sustainment contract structures that internalize lifecycle service costs.
Supply Chain Analysis
Silver-plated copper feedstock draws from precious metal markets in South Africa and Peru, while aluminum billet supplies concentrate in Chinese smelters and Russian export channels. Gallium nitride substrate access hinges on captive semiconductor foundry relationships in Taiwan and South Korea, constraining independent vendor participation in high-power active assemblies. Single-source vulnerability around electroforming chemical baths creates supply risk, as REACH and RoHS directives in Europe and MIIT environmental standards in China restrict qualified plating chemistry suppliers. Distribution runs through defense prime contractor direct procurement for military applications and telecommunications equipment vendor consolidated supplier bases for commercial infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Performance-based logistics contracts for shipboard radar networks are expanding faster than discrete component hardware supply, creating durable service-attach revenue streams that reshape supplier economics toward recurring-revenue models.
For Market Incumbents: Pre-empt additive manufacturing disruption by qualifying laser powder bed fusion capabilities for rapid prototype turnaround, collapsing the traditional electroforming-to-delivery cycle that currently protects established suppliers with sunk capital in conventional machining centers. Secure captive gallium nitride substrate access through semiconductor foundry partnerships or backward integration into substrate sourcing, as independent vendor participation in high-power active assemblies faces structural exclusion. Invest in REACH-compliant alternative plating chemistry qualification ahead of regulatory enforcement timelines to capture first-mover certification advantages in European defense procurement. For New Entrants and Emerging Players: Build out CNC milling capacity in Vietnam and Thailand to serve Japanese and Taiwanese supplier demand for regional telecommunications infrastructure projects, exploiting Southeast Asia's fragmenting manufacturing corridor. Target medical imaging equipment OEMs with ceramic waveguide segment specialization, as thermal stability and biocompatibility requirements in MRI systems create highest margin-per-kilogram demand pockets with limited incumbent penetration. Pursue satellite payload hermetic sealing qualifications for low-earth orbit constellation deployments, where vacuum-compatible thermal cycling performance specifications favor newer entrants unburdened by legacy aerospace program overhead. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among electroforming specialists with demonstrated long-term sustainment contract experience, as US Department of Defense procurement shifts from discrete component orders to performance-based logistics agreements spanning 15-20 years. Over the medium-term horizon, acquisition targets should prioritize precision fabrication specialists with captive semiconductor foundry relationships and pre-certified surface finish portfolios rather than commodity aluminum waveguide manufacturers facing telecommunications price compression. Monitor gallium nitride substrate allocation announcements from Taiwan and South Korea foundries as inflection indicators for high-power active assembly vendor viability.| Strategic Initiative | Industry Significance |
|---|---|
| Electroforming Skill Base Acquisition | Secures specialized technicians capable of controlling deposit thickness tolerances below 25 microns for defense radar applications. |
| REACH-Compliant Plating Chemistry Qualification | Enables European market access as ECHA restrictions constrain legacy chemistries used in waveguide manufacturing. |
| Additive Manufacturing Capability Buildout | Collapses lead times for complex bend geometries via laser powder bed fusion, displacing multi-axis CNC programming advantages. |
| Gallium Nitride Substrate Partnership | Resolves supply concentration risk among captive semiconductor foundries for high-power active waveguide assemblies. |
| Southeast Asian CNC Milling Expansion | Captures regional telecommunications infrastructure demand as Vietnam and Thailand attract Japanese and Taiwanese supplier investment. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of defense procurement databases, FCC spectrum allocation filings, trade customs records, and semiconductor foundry capacity disclosures. Primary interviews engaged radar systems engineers at defense prime contractors, telecommunications equipment vendor procurement directors, precision metalworking plant managers, and electroforming technical specialists. Secondary validation drew from SEC 10-K filings of listed defense contractors, MIIT infrastructure build-out announcements, REACH regulatory updates from ECHA, and customs data tracking aluminum and precious metal trade flows. Bottom-up demand modeling across product type, material, technology, and end-user segments triangulated against top-down market sizing from supply-side capacity assessments.
Forecast inputs include defense procurement program timelines, 5G millimeter-wave deployment schedules by telecommunications operators, and dual carbon goal implementation trajectories under MIIT direction. Segmentation dimensions modeled span product type complexity, substrate material tier, passive-active-hybrid technology architecture, and end-user sector with distinct margin profiles and service attachment rates. CAGRs were derived from regression analysis of historical procurement patterns against projected infrastructure investment cycles, with sensitivity testing around gallium nitride substrate availability and electroforming skill base expansion constraints.
The forecast holds incumbent behavior within observed patterns; aggressive moves by additive manufacturing specialists or gallium nitride substrate foundries would shift outcomes beyond modeled ranges. Forecasts reflect assumptions that REACH and RoHS regulatory trajectories proceed on announced timelines, that defense sustainment contract structures maintain current performance-based logistics specifications, and that FCC spectrum reallocation mandates enforce millimeter-wave redesign requirements without delay. Cross-checking against IHS Markit defense procurement tracking and telecommunications capex survey data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Data Bus Market
Electronic Components
Trackpad Market
Electronic Components
Passive Attenuator Market
Electronic Components
Battery Shunt Resistor Market
Electronic Components
Camera Battery Charger Market
Electronic Components
Motherboard Market
Electronic Components
Ceramic Capacitors Market
Electronic Components
Intel Motherboards Market
Electronic Components
US Frequency Control and Timing Devices Market
Electronic Components
Acoustic Diaphragm Market
Electronic Components
AC Adapter Market
Electronic Components
Electronic Wipe Market
Electronic Components
Audio Transistors Market
Electronic Components
Efuse Market
Electronic Components
Digital Audio Processor Market
Electronic Components
Asia-Pacific USB Retimer Market