
 Japan Outdoor LED Lighting Market | 2026-2036
Japan Outdoor LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Outdoor LED Lighting Market Insights
Municipal procurement is rotating toward networked, sensor-enabled street lighting as Japan's cities prioritize energy efficiency and remote management capabilities. Panasonic Holdings Corporation leverages its domestic manufacturing footprint and utility partnerships to anchor large-scale smart city deployments. Nichia Corporation dominates upstream LED chip supply, sustaining pricing power through proprietary phosphor technologies. Toshiba Corporation competes in the retrofit segment, extending its installed base relationships into LED conversion contracts.
Japan Outdoor LED Lighting comprises solid-state luminaires engineered with gallium nitride emitters, typically operating at correlated color temperatures between 2700K and 5000K, designed for exterior illumination of public thoroughfares, commercial facades, and recreational spaces. Street lights command the largest installed volume, though margin pools concentrate in smart lighting systems where software and controls generate recurring service revenue. Solar-powered installations represent the fastest-growing technology segment, driven by rural municipalities seeking grid-independent solutions for disaster resilience. Flood lights retain stable demand from industrial security applications, while decorative lights occupy a premium niche in tourism districts and heritage precincts.
METI enforces Top Runner standards that mandate progressive efficiency gains in LED luminaires, directly shaping product development roadmaps and factory certification requirements. JIS C 8105 governs photometric performance and durability testing, creating compliance barriers for non-domestic suppliers seeking public tenders. Local governments increasingly reference these frameworks in procurement specifications, elevating total cost-of-ownership calculations over upfront purchase price. Stakeholders must monitor evolving interoperability standards for smart city platforms, as proprietary control protocols risk fragmenting vendor selection and locking municipalities into single-supplier dependencies.
Market Dynamics
Japan's outdoor LED lighting sector is being restructured by METI's progressive efficiency mandates, which force manufacturers to redesign thermal management systems and optical engines ahead of each Top Runner compliance cycle. These regulatory ratchets compress product lifecycles while elevating technical barriers for non-domestic suppliers.
Growth Catalysts
- Top Runner Program:METI's efficiency benchmarks mandate continuous lumen-per-watt improvements, compelling domestic manufacturers to accelerate GaN-on-SiC chip development.
- Disaster-resilient infrastructure:Rural municipalities in Tohoku and Kyushu prioritize solar-integrated street lighting with battery backup for grid-independent operation during seismic events.
- Urban renewal zones:Tokyo's waterfront districts and Osaka's Umeda corridor drive concentrated demand for networked luminaires with embedded environmental sensors.
Market Restraints
- Upstream chip concentration:Nichia Corporation's dominance in phosphor-converted white LED emitters creates supply vulnerability for luminaire assemblers lacking captive chip capacity.
- JIS certification friction:Foreign manufacturers face 18-24 month approval timelines for JIS C 8105 photometric testing, excluding them from municipal tender windows.
- High-pressure sodium legacy:Existing HPS installations in industrial zones exhibit residual depreciation schedules that delay LED conversion decisions.
Strategic Opportunities
- Hokkaido and Okinawa prefectures:Remote island grids and harsh climate conditions create premium demand for hybrid solar-wind LED systems with extended temperature tolerances.
- Heritage precinct lighting:Kyoto's temple districts and Nara's UNESCO zones require tunable-CCT luminaires that preserve nocturnal aesthetics while meeting energy targets.
- LiDAR convergence:Integration of solid-state lighting with vehicle-to-infrastructure sensing creates new revenue pools in autonomous transport corridors.
Industry Challenges
- Optomechanical engineering shortage:Japanese universities produce insufficient thermal design specialists capable of optimizing heat sink geometry for high-lumen street luminaires.
- Legacy control protocol fragmentation:Proprietary smart city platforms from competing vendors prevent interoperability, forcing municipalities into single-supplier lock-in.
- Extended payback verification:Municipal auditors demand rigorous measurement and verification of energy savings claims, complicating performance-contracting structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Outdoor LED Lighting Market |
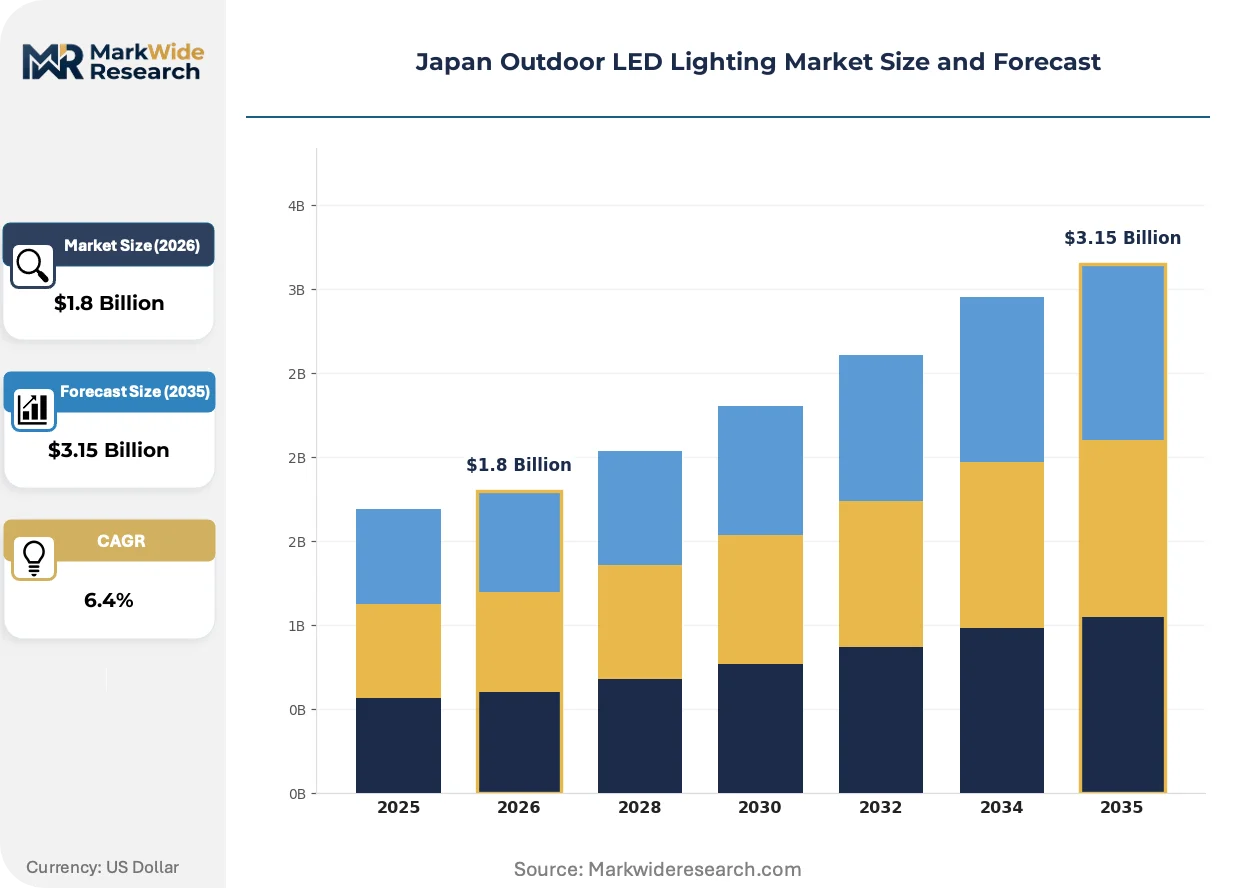
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Street Lights, Flood Lights, Garden Lights, Decorative Lights End User: Municipalities, Commercial Properties, Residential Areas, Parks Installation Type: New Installation, Retrofit, Upgrades, Custom Installations Technology: Smart Lighting, Solar-Powered, Wired Systems, Wireless Systems |
| Companies Covered | Panasonic Holdings Corporation, Nichia Corporation, Toshiba Corporation, Endo Lighting Corporation, ams-OSRAM AG, Mitsubishi Electric Corporation, Signify Holding (Philips), Japan Street Light Mfg Co Ltd, Takasho Digitec Co Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Outdoor LED Lighting Market Trends and Innovations
Photonic architectures and control intelligence are converging to redefine how exterior illumination systems generate value beyond basic visibility. The sector is pivoting from hardware-only transactions toward service-embedded deployments.
Silicon carbide substrate technology is displacing conventional sapphire-based LED chips in high-power street lighting applications. Tokyo Metropolitan Government's expressway authority specified SiC-GaN emitters for the Bayshore Route retrofit, citing superior thermal conductivity under enclosed luminaire conditions. This material transition is displacing legacy metal-halide and first-generation LED installations that fail to meet METI's 2027 lumen-maintenance thresholds.
METI's Top Runner standards now incorporate circadian lighting metrics for public spaces, mandating spectral power distribution reporting alongside efficacy data. Luminaire manufacturers must redesign phosphor formulations to demonstrate melanopic ratio compliance. Outdoor lighting procurement in Kanagawa and Aichi prefectures now weights these biological impact factors alongside energy performance.
Municipal buyers are consolidating vendor relationships around full-service performance contracts that bundle installation, maintenance, and energy management. Osaka's municipal corporation replaced transactional purchasing with decade-long availability agreements that transfer operational risk to suppliers. This contracting evolution concentrates procurement authority within prefectural purchasing cooperatives, marginalizing smaller luminaire vendors lacking balance sheet capacity for long-term service obligations.
Japan Outdoor LED Lighting Market Segmentation
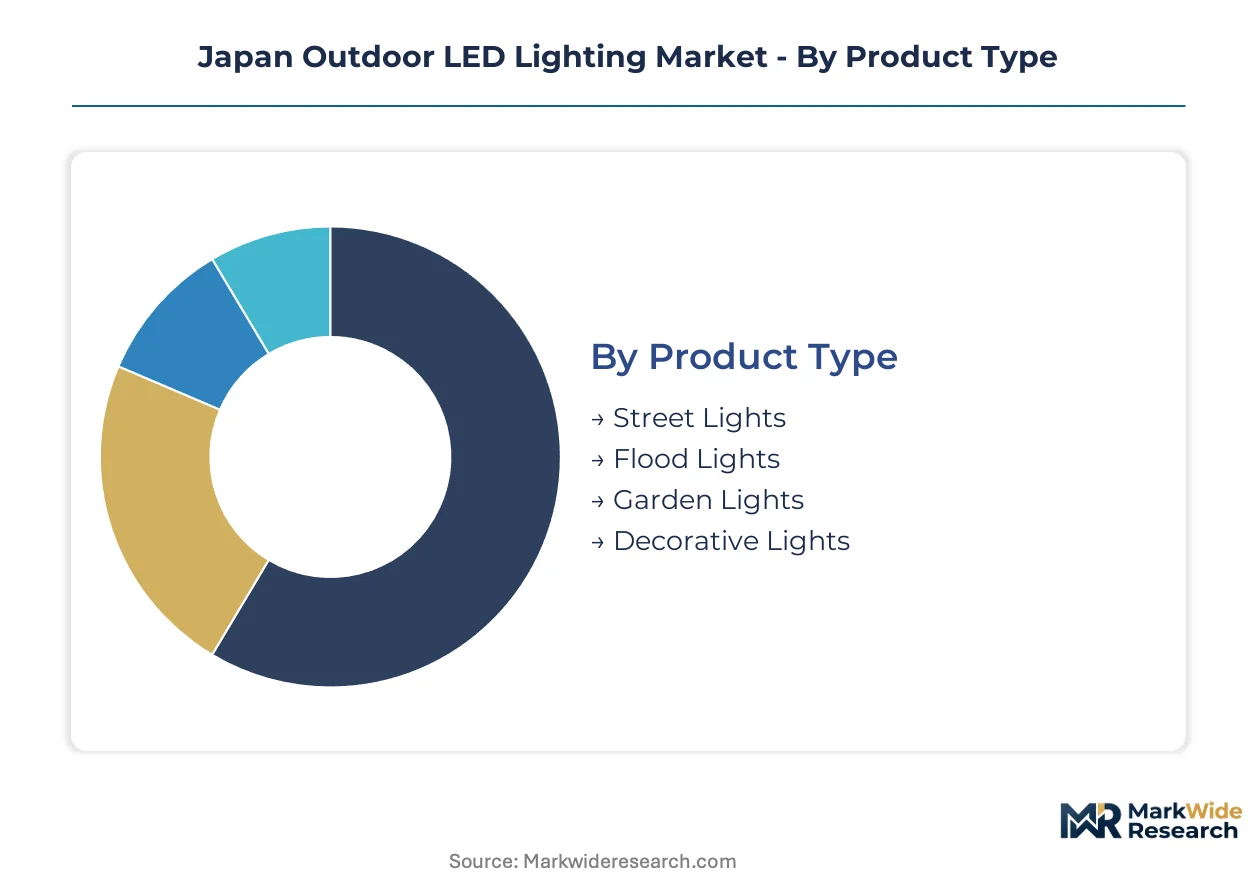
Segmentation reveals how METI efficiency mandates and disaster-resilience priorities reshape procurement patterns across Japan's outdoor LED landscape. Each dimension exposes distinct margin pressures and vendor positioning opportunities.
Product Type:
Street lights face the most acute substitution pressure as high-pressure sodium legacy installations approach end-of-life depreciation cycles, forcing rapid LED conversion decisions.
- Street Lights:High-power luminaires utilizing GaN-on-SiC chip architectures dominate municipal procurement volumes. Tokyo Metropolitan Government's expressway authority and Osaka's Umeda corridor drive concentrated demand for networked units with embedded environmental sensors.
- Flood Lights:Industrial security applications sustain stable replacement demand, particularly in manufacturing zones across Aichi and Kanagawa prefectures where 24-hour perimeter illumination remains mandatory.
- Garden Lights:Residential and hospitality sectors in Kyoto's temple districts prioritize low-glare, tunable-CCT designs that preserve nocturnal aesthetics.
- Decorative Lights:Tourism precincts and UNESCO heritage zones command premium pricing for custom spectral formulations.
Street lights anchor the volume base while solar-integrated garden lights gain share at the steepest rate in rural prefectures.
End User:
Cost-tier stratification separates specification-heavy municipal buyers from price-sensitive residential segments, with commercial properties occupying a contested middle ground demanding performance validation.
- Municipalities:Prefectural purchasing cooperatives consolidate authority around decade-long availability agreements that transfer operational risk to suppliers. METI's Top Runner compliance cycles dominate specification requirements.
- Commercial Properties:Osaka's commercial corridors and Tokyo's waterfront districts prioritize networked luminaires with energy management dashboards. Extended payback verification demands complicate performance contracting.
- Residential Areas:Suburban developments in Saitama and Chiba prefectures favor standardized retrofit packages with simplified installation protocols.
- Parks:Recreational spaces in Hokkaido and Okinawa require hybrid solar-wind systems with extended temperature tolerances for harsh climate resilience.
Municipalities concentrate procurement authority while commercial properties expand most quickly as performance contracting matures.
Installation Type:
Volume distribution tilts heavily toward retrofit as Japan's installed base of legacy metal-halide and first-generation LED systems reaches obsolescence thresholds.
- New Installation:Urban renewal zones in Tokyo and Osaka specify smart-ready infrastructure with embedded conduit for future sensor integration. Greenfield developments face stringent JIS C 8105 photometric certification timelines.
- Retrofit:Existing HPS installations in industrial zones exhibit residual depreciation schedules that delay conversion decisions, though METI mandates accelerate replacement timelines.
- Upgrades:First-generation LED retrofits from early adoption cycles now require chip-level replacement to meet 2027 lumen-maintenance thresholds.
- Custom Installations:Heritage precincts in Kyoto and Nara demand bespoke optomechanical engineering for aesthetic compliance.
Retrofit commands the dominant share while custom installations climb the fastest in premium tourism districts.
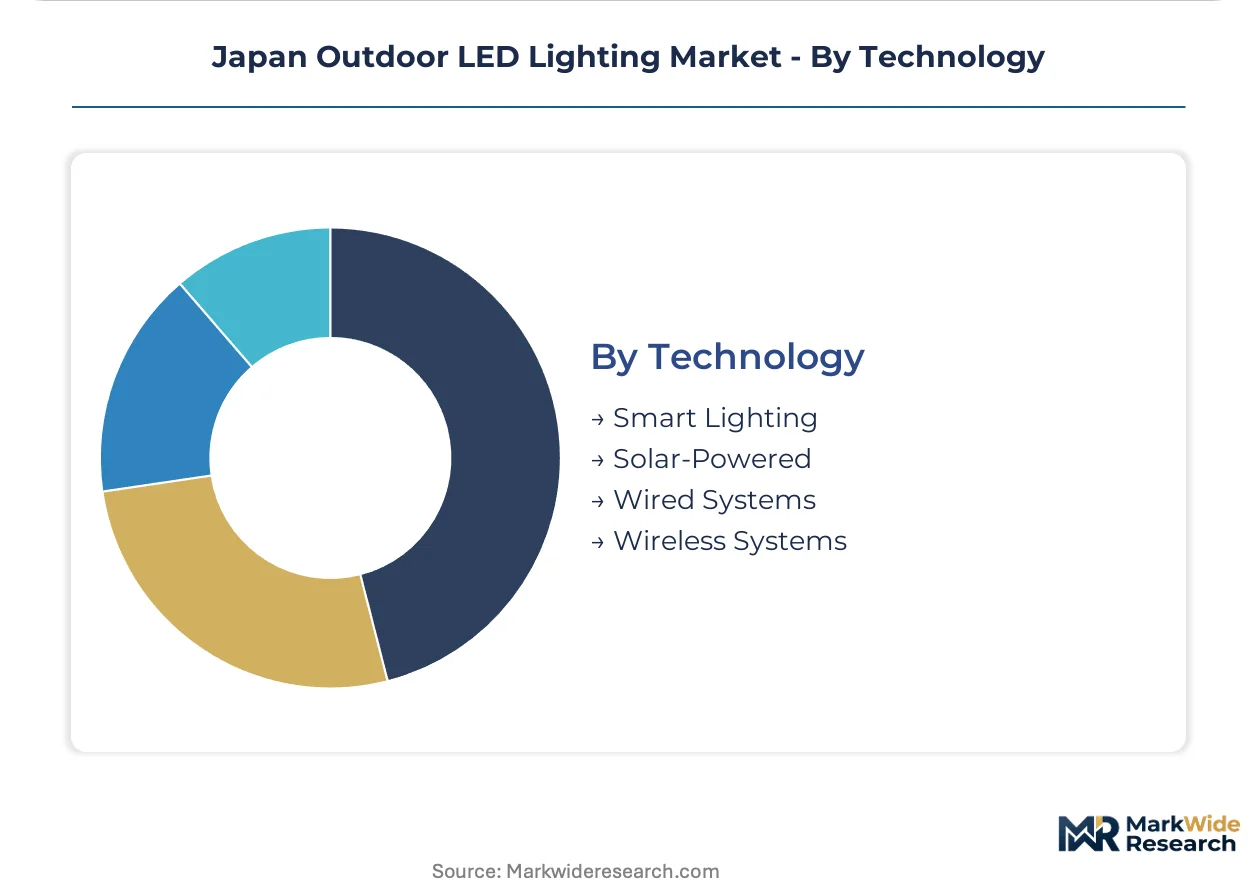
Technology:
Supply concentration in upstream phosphor-converted white LED emitters creates vulnerability for luminaire assemblers, privileging vendors with captive chip capacity or deep Nichia partnerships.
- Smart Lighting:Networked systems with embedded controls generate recurring service revenue and lock-in municipal relationships. Proprietary protocols from competing vendors prevent interoperability, forcing single-supplier dependencies.
- Solar-Powered:Rural municipalities in Tohoku and Kyushu prioritize battery-backed systems for grid-independent disaster resilience. Hokkaido's remote island grids create premium demand for hybrid configurations.
- Wired Systems:Legacy infrastructure in established commercial corridors sustains replacement demand despite higher installation costs.
- Wireless Systems:Reduced trenching requirements appeal to heritage districts where archaeological preservation limits excavation.
Wired systems retain the largest installed base while solar-powered technology expands most rapidly in disaster-preparedness applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese LED luminaire exports flow primarily toward Southeast Asian infrastructure projects, while domestic demand concentrates in metropolitan renewal corridors and disaster-resilient rural networks.
Kanto/Tokyo
Tokyo Metropolitan Government's expressway authority and waterfront districts drive concentrated demand for networked street luminaires with embedded environmental sensors. METI's Top Runner compliance cycles dominate municipal procurement specifications. The Bayshore Route retrofit exemplifies large-scale smart infrastructure deployment.
Kansai/Osaka
Osaka's Umeda commercial corridor and municipal corporation prioritize decade-long availability agreements that transfer operational risk to suppliers. Prefectural purchasing cooperatives consolidate authority around performance contracting. Urban renewal zones specify smart-ready infrastructure with embedded conduit for future sensor integration.
Chubu/Nagoya
Industrial security applications in Aichi and surrounding manufacturing zones sustain stable replacement demand for flood lighting systems. JIS C 8105 photometric certification requirements create compliance barriers for non-domestic suppliers. Manufacturing corridors require 24-hour perimeter illumination with high-pressure sodium legacy conversions accelerating.
Kyushu
Rural municipalities prioritize solar-integrated street lighting with battery backup for grid-independent operation during seismic events. Disaster-resilient infrastructure mandates from regional governments shape procurement patterns. Remote island grids create premium demand for hybrid solar-wind LED systems with extended temperature tolerances.
Hokkaido
Harsh climate conditions and remote island grid configurations generate specialized demand for hybrid renewable LED systems. Prefectural infrastructure budgets emphasize disaster preparedness and energy independence. Custom installations require extended temperature tolerances beyond standard product specifications.
Japan Outdoor LED Lighting Market Competitive Landscape
Listed leaders compete with private specialists across technology licensing and municipal service contracting, producing a tiered structure where scale advantages separate national champions from regional fabricators. The vendor base clusters around three strategic archetypes: integrated electronics conglomerates with captive chip capacity, specialized luminaire assemblers dependent on upstream supply partnerships, and international lighting majors leveraging global R&D platforms. Dominant competitive moves include strategic partnerships for smart city platform interoperability and backward integration into phosphor-converted emitter supply.
Among Japan-based electronics conglomerates, Panasonic Holdings Corporation and Toshiba Corporation exemplify the integrated archetype, leveraging domestic manufacturing footprints and utility partnerships to anchor large-scale deployments. Nichia Corporation occupies a distinct upstream position, representing phosphor-technology specialists that sustain pricing power through proprietary emitter formulations. These three entities illustrate how competitive positioning in Japanese outdoor LED lighting depends on control over critical technology layers rather than luminaire assembly scale alone.
| Leading Market Players |
|---|
| Panasonic Holdings Corporation |
| Nichia Corporation |
| Toshiba Corporation |
| Endo Lighting Corporation |
| ams-OSRAM AG |
| Mitsubishi Electric Corporation |
| Signify Holding (Philips) |
| Japan Street Light Mfg Co Ltd |
| Takasho Digitec Co Ltd |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at Nichia Corporation's phosphor-converted emitter fabs shapes price floors across Japan's luminaire assembly tier, concentrating margin capture upstream while compressing assembler profitability. This scale asymmetry forces domestic lighting manufacturers toward captive chip partnerships or decade-long service contracts to defend position.
Pricing Analysis
Technology-generation pricing gaps separate SiC-GaN street luminaires commanding premium positioning from sapphire-based legacy units facing accelerated depreciation. Three-tier pricing structure across premium smart-city systems, standard municipal retrofits, and economy-grade residential packages stratifies procurement. Cost compression in economy tiers intensifies because Chinese assembler competition floods standardized export markets. Municipal buyers exhibit lowest price sensitivity due to total-cost-of-ownership mandates, while suburban residential developers prioritize upfront capital minimization.
Supply Chain Analysis
Inventory lead times for GaN-on-SiC substrates extend 16-20 weeks, tethering luminaire production schedules to upstream wafer fab capacity allocation decisions. Japan, Taiwan, and South Korea concentrate critical LED chip and substrate supply. Raw material dependencies span high-purity gallium metal, rare-earth phosphor activators, and aluminum nitride ceramic submounts. Single-source vulnerability concentrates in Nichia Corporation's proprietary phosphor formulations. Distribution runs through prefectural purchasing cooperatives consolidating municipal procurement authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's outdoor LED market sits in early-cycle expansion as METI's Top Runner compliance deadlines force replacement waves across municipal infrastructure. Disaster-resilience mandates accelerate solar-integrated adoption beyond standard efficiency-driven retrofit timelines.
For Market Incumbents: Consolidate around captive phosphor technology or exclusive Nichia supply agreements to lock out assembler competitors. Extend balance sheet capacity for decade-long availability contracts transferring operational risk from municipalities. Prioritize backward integration into SiC substrate sourcing as foreign wafer suppliers expand capacity. For New Entrants and Emerging Players: Differentiate on hybrid solar-wind system engineering for Hokkaido and Okinawa prefectures where climate resilience commands pricing premiums. Target heritage district lighting in Kyoto and Nara requiring tunable-CCT aesthetic compliance. Pursue partnerships with regional electrical contractors bypassing consolidated prefectural purchasing cooperatives. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among smart-city platform vendors embedding energy-management software with municipal street lighting. Five-to-ten year viability favors vendors controlling proprietary control protocols despite current interoperability fragmentation. Acquisition targets should demonstrate JIS C 8105 certification capability and existing utility partnerships. Monitor METI's evolving circadian lighting metric adoption as inflection signal for phosphor formulation R&D valuation.| Strategic Initiative | Industry Significance |
|---|---|
| Smart City Platform Integration | Osaka's decade-long availability agreements demonstrate risk-transfer contracting concentrating procurement authority. |
| Backward Integration into SiC Substrates | Tokyo Metropolitan Government's Bayshore Route retrofit specifications favor thermal conductivity performance. |
| Phosphor Formulation R&D Investment | METI's melanopic ratio compliance mandates now weight biological impact factors in Kanagawa and Aichi tenders. |
| Hybrid Renewable System Development | Hokkaido's remote island grids and Kyushu seismic resilience priorities create premium demand segmentation. |
| JIS Certification Acceleration | Eighteen-month approval timelines exclude foreign competitors from municipal tender windows. |
Research Methodology
Cross-validation between municipal procurement database analysis and luminaire manufacturer technical documentation anchors the qualitative findings. Primary interviews with prefectural purchasing cooperative managers, METI efficiency standard officers, electrical contractor project directors, and Nichia Corporation distribution partners combine with secondary validation. Secondary sources include JIS C 8105 certification registries, METI Top Runner compliance filings, prefectural infrastructure budget appropriations, and customs trade records for LED component imports. Bottom-up unit economics triangulate against top-down municipal expenditure forecasts.
Sensitivity analysis around METI compliance timeline acceleration and substrate supply disruption scenarios tests forecast robustness across the projection horizon. Segmentation dimensions modeled include product architecture, end-user procurement authority tier, installation type, and technology integration level. CAGRs derive from replacement cycle timing, efficiency mandate phase-in schedules, and solar-integrated system penetration curves. Industry-specific inputs incorporate lumen-maintenance degradation curves and disaster-resilience infrastructure budget allocations.
The analysis sits within stated boundaries; outcomes outside sustained METI enforcement intensity or stable gallium supply conditions would require recalibration. Forecasts reflect documented assumptions regarding municipal budget continuity and technology substitution rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
LED Display Control Card Market
LED
US LED Downlight Market
LED
LED and OLED Display Market
LED
Asia Pacific Outdoor LED Lighting Market
LED
LED Tube Market
LED
Indonesia LED Market
LED
LED Light Bar Market
LED
India Indoor LED Lighting Market
LED
Global Outdoor LED Lighting Market
LED
China Outdoor LED Lighting Market
LED
Four-Digit 7 Segment LED Displays Market
LED
High-Intensity LED Logo and Livery Lighting Systems Market
LED
Africa LED Lighting Market
LED
LED Light Market
LED
US and Europe LED Lighting Market
LED
UK Outdoor LED Lighting Market