
 Global Ophthalmology Drugs and Devices Market | 2026-2036
Global Ophthalmology Drugs and Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ophthalmology Drugs and Devices Market Intelligence
Premium intraocular lens specifications is bifurcating the competitive landscape between commodified monofocal platforms and advanced toric-multifocal systems. Novartis AG leverages its sustained-release implant portfolio to anchor positions in retinal therapy segments. Alcon Vision LLC dominates manufacturing scale across phacoemulsification platforms and consumable surgical packs. Regeneron Pharmaceuticals Inc. competes through antibody engineering depth in anti-VEGF drug development.
Ophthalmology drugs and devices comprise pharmaceutical formulations, surgical instrumentation, diagnostic imaging systems, and corrective optical products engineered to treat disorders of the visual system, with specifications ranging from 10-micron precision in femtosecond laser capsulotomy to sustained-release intravitreal implants achieving therapeutic drug levels for six months. Anti-VEGF agents command concentrated margin pools due to recurring injection protocols and patent-protected biologic formulations, while diagnostic devices built on optical coherence tomography technology lead capital expenditure cycles in specialty eye hospitals. Contact lenses represent a mature volume segment where silicone hydrogel material innovation sustains replacement-schedule premiumization against private-label competition.
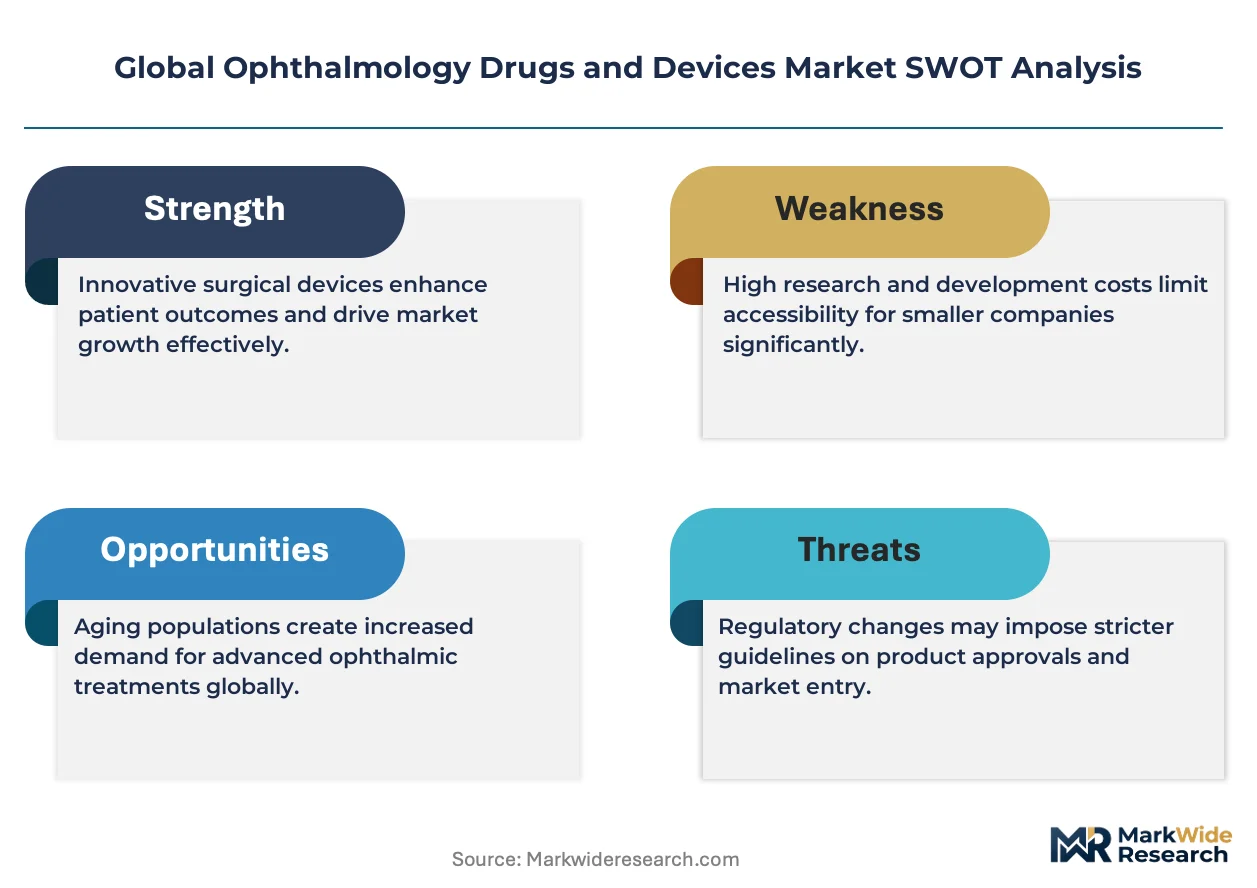
The FDA's Breakthrough Device Designation and the EU Medical Device Regulation reshape product development timelines, with the former compressing premarket review for novel diagnostic platforms and the latter imposing post-market surveillance obligations that favor established quality-management systems. Japan's PMDA accelerates approval harmonization through reliance pathways with FDA determinations, reducing redundant clinical trial requirements for multinational manufacturers. Stakeholders must monitor reimbursement threshold adjustments for sustained-release drug delivery systems versus conventional intravitreal injection protocols across the United States, Germany, and Japan to calibrate portfolio investment priorities.
Market Dynamics
The ophthalmology market pivots on sustained-release drug delivery systems that compress injection frequencies from monthly to biannual protocols, restructuring physician practice economics and patient compliance metrics across retinal therapy segments.
Growth Catalysts
- FDA Breakthrough Device Designation:The pathway compresses premarket review timelines for novel diagnostic platforms, accelerating commercialization of AI-integrated optical coherence tomography systems.
- Silicone hydrogel material platforms:Extended-wear contact lens specifications enable replacement-schedule premiumization against commodified hydrogel alternatives in specialty optical retail.
- Japan's aging demographic concentration:PMDA reliance pathways with FDA determinations reduce redundant clinical trial requirements, drawing multinational manufacturing investment into sustained-release implant production.
Market Restraints
- Biologic API supply concentration:Anti-VEGF antibody production depends on mammalian cell culture capacity concentrated in Swiss and Irish contract manufacturing facilities.
- EU MDR post-market surveillance obligations:The regulation imposes quality-management system burdens that disadvantage mid-scale diagnostic device manufacturers without established notified body relationships.
- Femtosecond laser platform capital intensity:Cataract surgery suites require seven-figure equipment investments that constrain penetration in reimbursment-constrained markets.
Strategic Opportunities
- Gene therapy vector manufacturing:Convergence of AAV production platforms with ophthalmic delivery routes opens inherited retinal disease segments previously unreachable by small-molecule or biologic approaches.
- Tele-ophthalmology screening networks:India's national blindness control program creates procurement scale for portable fundus cameras and AI-assisted diagnostic workflows in tier-2 and tier-3 cities.
- Home-based tonometry devices:Regulatory clearance for patient-operated intraocular pressure monitoring is displacing clinic-dependent glaucoma management in Germany's statutory insurance framework.
Industry Challenges
- Vitreoretinal surgeon training pipelines:Fellowship positions fail to match expansion of sustained-release implant administration capacity, creating procedural bottlenecks in academic medical centers.
- Legacy phacoemulsification platform integration:Femtosecond laser docking systems require surgical workflow reconfiguration that extends operating room turnover times during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ophthalmology Drugs and Devices Market |
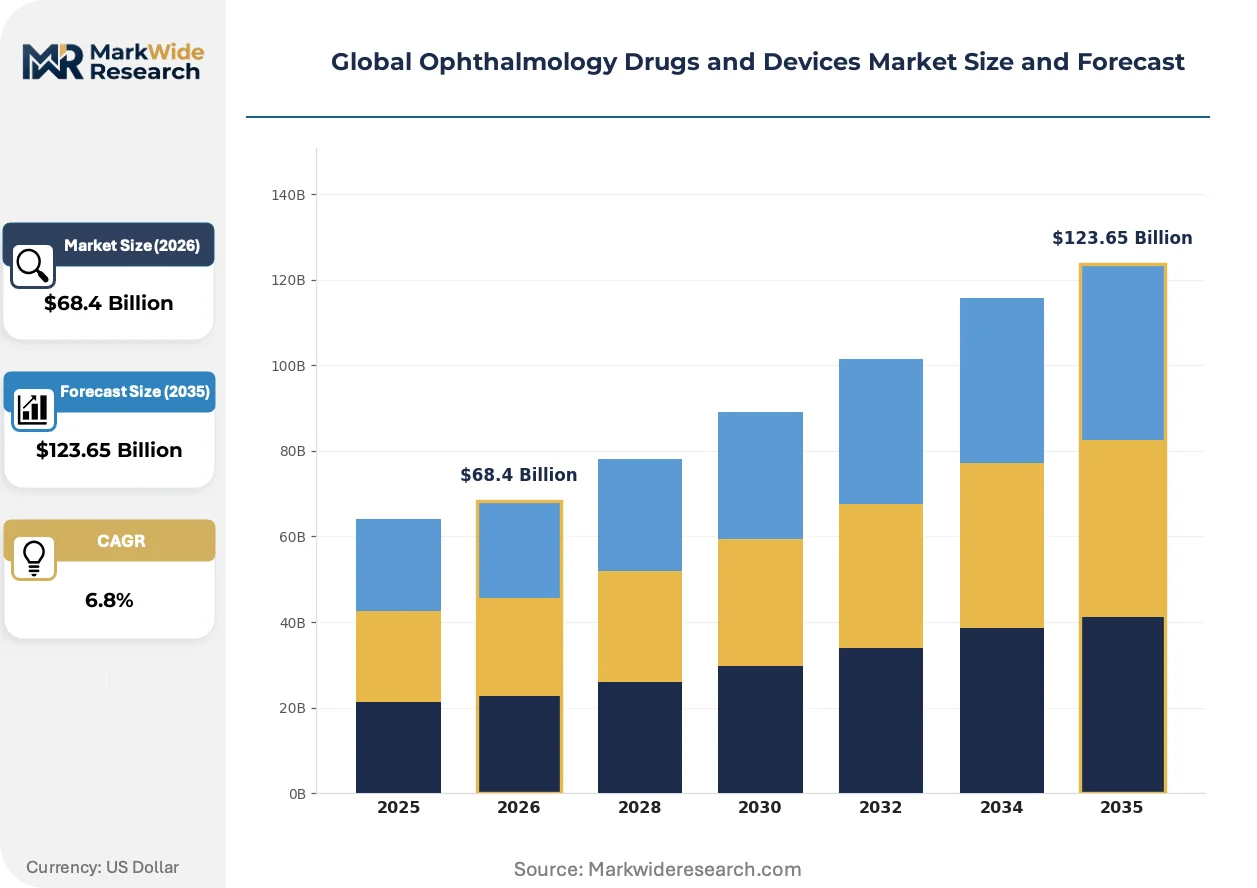
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anti-Glaucoma Drugs, Anti-VEGF Agents, Corticosteroids, Diagnostic Devices, Surgical Instruments, Contact Lenses Therapy Area: Glaucoma, Age-Related Macular Degeneration, Diabetic Retinopathy, Cataract, Dry Eye Syndrome, Uveitis End User: Ophthalmology Clinics, Specialty Eye Hospitals, Research Laboratories, Ambulatory Surgical Centers, Optical Retailers, Home Care Providers Technology: Optical Coherence Tomography, Fluorescein Angiography, Ultrasonography, Laser Photocoagulation, Phacoemulsification, Biometric Devices |
| Companies Covered | Novartis AG, Alcon Vision LLC, Regeneron Pharmaceuticals Inc., Abbott Laboratories, Allergan PLC by AbbVie Inc., F. Hoffmann-La Roche Ltd., Bausch + Lomb, Santen Pharmaceutical Co., Ltd., Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ophthalmology Drugs and Devices Market Strategic Shifts & Innovations
Digital biomarker extraction from optical coherence tomography angiography is restructuring clinical trial endpoints and reimbursement evidence requirements across retinal disease management protocols.
Extended-depth-of-focus intraocular lens designs are displacing traditional multifocal platforms in premium cataract surgery segments. Academic medical centers in the United States and Germany are prioritizing these specifications to reduce photic phenomenon complaints that drove multifocal explant rates. The technology is compressing market share available to conventional toric-multifocal combinations.
The EU Medical Device Regulation's classification rules for software-as-a-medical-device are redirecting development resources toward quality-management system documentation. Diagnostic platforms incorporating machine learning algorithms face heightened clinical validation requirements that extend time-to-market for OCT angiography systems. Manufacturers are responding by pre-submission engagement with notified bodies in Germany and the Netherlands.
Consolidated procurement by United States specialty eye hospital networks is compressing vendor margins on phacoemulsification consumables. Group purchasing organizations are unbundling surgical pack components and sourcing generic viscoelastic agents separately from capital equipment vendors. This pattern concentrates in the southeastern and southwestern states where hospital system consolidation has advanced furthest.
Global Ophthalmology Drugs and Devices Market Segmentation
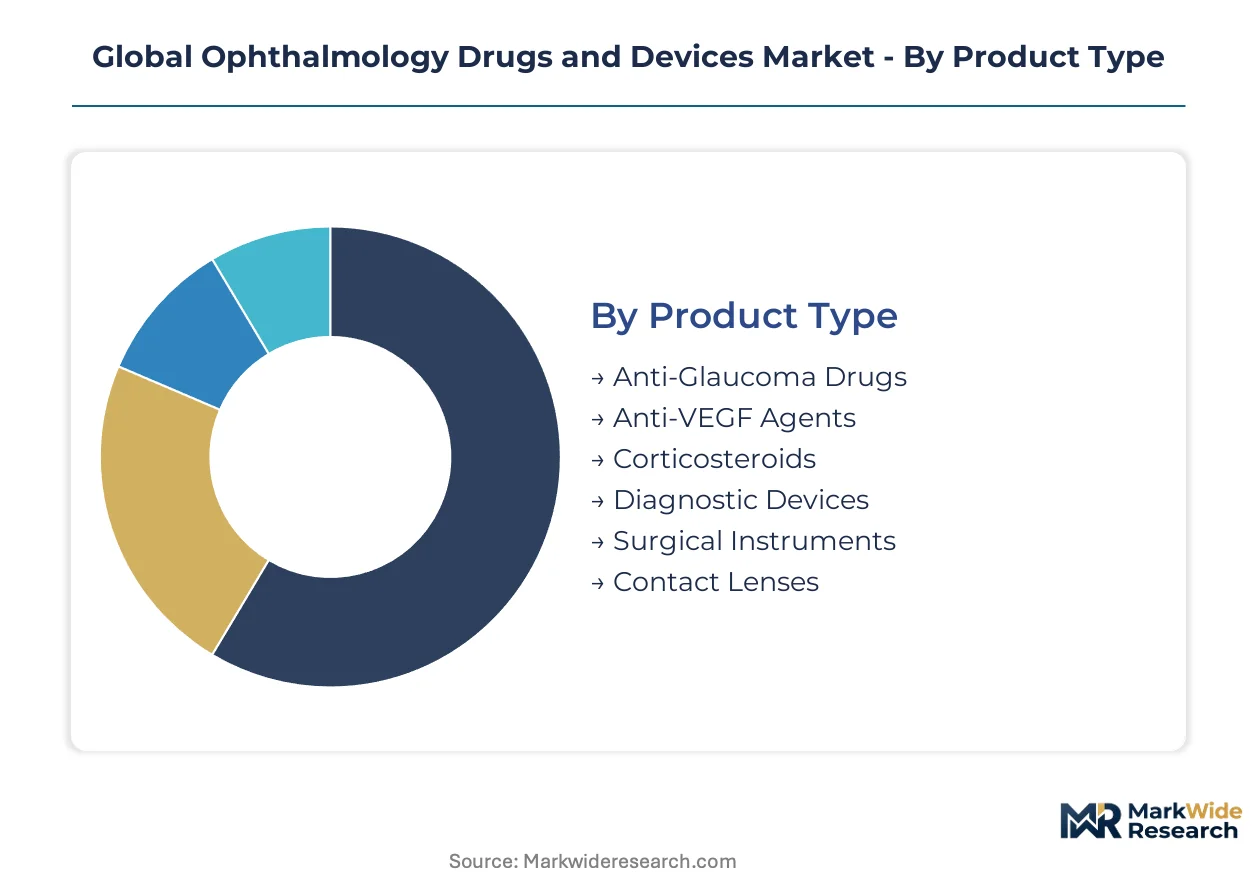
Ophthalmology market segmentation reveals divergent substitution pressures across therapeutic modalities. Sustained-release drug delivery systems and AI-integrated diagnostic platforms are displacing conventional monthly injection protocols and manual imaging workflows.
Product Type:
Anti-VEGF agents and sustained-release implants face intensifying substitution pressure from gene therapy vectors in inherited retinal disease segments.
- Anti-VEGF Agents:Ranibizumab and aflibercept formulations dominate recurring intravitreal injection protocols. Demand concentrates in United States specialty eye hospitals where reimbursement stability supports biologic premium pricing against biosimilar entrants.
- Surgical Instruments:Phacoemulsification platforms and femtosecond laser docking systems achieve 10-micron precision in capsulotomy. Procurement in Germany's statutory hospital networks favors modular upgrade paths over complete platform replacement.
- Anti-Glaucoma Drugs:Prostaglandin analogs and beta-blocker combinations manage intraocular pressure progression.
- Corticosteroids:Intravitreal and topical formulations address inflammatory posterior segment disorders.
- Diagnostic Devices:OCT and fundus imaging systems lead capital expenditure cycles in academic medical centers.
- Contact Lenses:Silicone hydrogel material innovation sustains replacement-schedule premiumization in optical retail channels.
Anti-VEGF agents retain volume leadership; sustained-release implant platforms hold the steepest expansion curve.
Therapy Area:
Cost tier stratification separates premium intervention segments from commodified chronic management categories.
- Age-Related Macular Degeneration:Wet AMD drives anti-VEGF injection volume with neovascularization requiring monthly monitoring. Japan's aging demographic concentration sustains demand for brolucizumab and faricimab in Tokyo-Osaka hospital corridors.
- Diabetic Retinopathy:Proliferative and non-proliferative forms create tiered treatment intensities from laser photocoagulation to anti-VEGF protocols. India's national blindness control program prioritizes screening infrastructure in tier-2 cities.
- Glaucoma:Open-angle and angle-closure variants require distinct surgical and pharmacological approaches.
- Cataract:Senile cataract prevalence scales directly with demographic aging across all developed markets.
- Dry Eye Syndrome:Evaporative and aqueous-deficient subtypes respond to distinct therapeutic mechanisms.
- Uveitis:Anterior, intermediate, and posterior classifications determine immunosuppressive intervention intensity.
Cataract surgery retains procedure volume leadership; diabetic retinopathy management holds the steepest expansion trajectory.
End User:
Customer type fragmentation creates distinct procurement specifications across institutional and retail channels.
- Specialty Eye Hospitals:Consolidated United States networks in southeastern states unbundle surgical pack components and source generic viscoelastic agents separately from capital equipment vendors. Group purchasing organization concentration compresses vendor margins on phacoemulsification consumables.
- Ophthalmology Clinics:Independent practice settings in Germany prioritize home-based tonometry integration within statutory insurance frameworks.
- Ambulatory Surgical Centers:Freestanding facilities optimize case throughput through streamlined phacoemulsification workflows.
- Research Laboratories:Academic medical centers in Boston and Heidelberg drive gene therapy vector manufacturing partnerships.
- Optical Retailers:Specialty chains and independent dispensaries differentiate on silicone hydrogel fitting expertise.
- Home Care Providers:Patient-operated pressure monitoring and drop adherence systems expand service boundaries.
Specialty eye hospitals retain capital expenditure leadership; home care providers hold the steepest expansion trajectory.
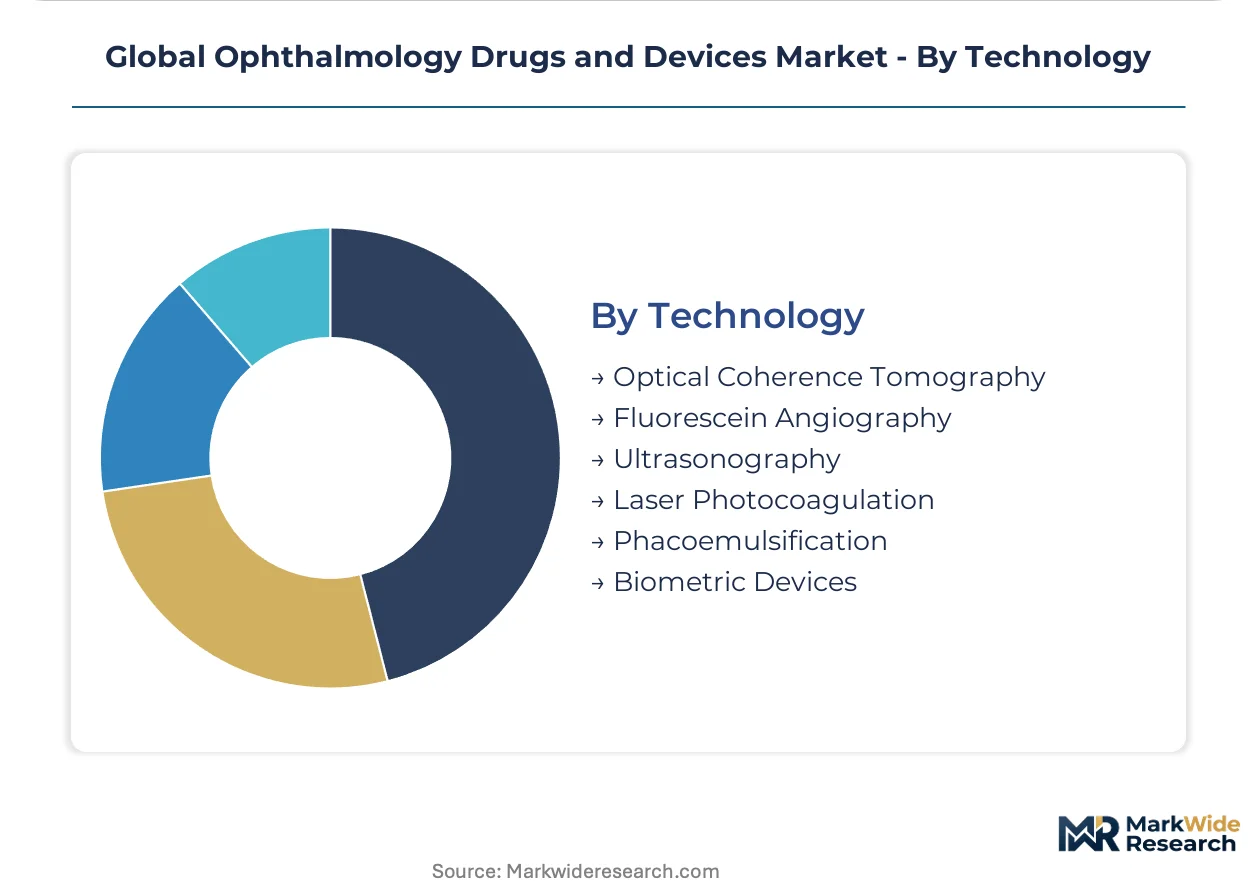
Technology:
Supply concentration in OCT componentry and laser source manufacturing shapes geographic deployment patterns.
- Optical Coherence Tomography:Spectral-domain and swept-source architectures achieve micron-level retinal layer resolution. FDA Breakthrough Device Designation accelerates AI-integrated angiography platforms in Palo Alto and Cambridge development clusters.
- Phacoemulsification:Torsional and longitudinal ultrasound modalities dominate lens fragmentation with thermal management specifications. Equipment manufacturers in Fort Worth and Geneva prioritize modular handpiece compatibility across platform generations.
- Fluorescein Angiography:Dye-based vascular imaging persists where OCT-A penetration remains cost-constrained.
- Ultrasonography:A-scan and B-scan modalities support biometric calculation in dense cataract cases.
- Laser Photocoagulation:Pattern scan and navigated systems optimize retinal treatment precision.
- Biometric Devices:Optical and partial coherence interferometry platforms calculate intraocular lens power.
Optical coherence tomography retains installed base leadership; biometric devices hold the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in ophthalmic biologics and precision surgical platforms tilt toward net-import status in aging economies while manufacturing capacity concentrates in Swiss, Irish, and Japanese production corridors. The United States, Germany, and Japan absorb the majority of sustained-release implant and premium IOL shipments, with regulatory harmonization compressing redundant clinical trial overhead.
United States
Specialty eye hospital networks in Florida and Texas drive capital expenditure cycles for femtosecond laser platforms and phacoemulsification consumables. FDA Breakthrough Device Designation accelerates commercialization timelines for AI-integrated OCT angiography systems developed in Palo Alto and Cambridge clusters. Group purchasing organization consolidation across southeastern states unbundles surgical pack components and sources generic viscoelastic agents separately from equipment vendors.
Germany
Statutory insurance frameworks in Bavaria and North Rhine-Westphalia sustain reimbursement stability for premium toric-multifocal intraocular lenses and home-based tonometry devices. EU MDR post-market surveillance obligations favor established diagnostic device manufacturers with notified body relationships in Berlin and Munich. Heidelberg academic medical centers anchor gene therapy vector manufacturing partnerships with multinational pharmaceutical sponsors.
Japan
Tokyo-Osaka hospital corridors concentrate demand for anti-VEGF agents and brolucizumab formulations serving wet age-related macular degeneration patients. PMDA reliance pathways with FDA determinations reduce redundant clinical trial requirements, drawing sustained-release implant production investment into Kansai manufacturing zones. METI industrial policy supports domestic ophthalmic device componentry supply chains in Nagoya precision optics clusters.
India
Tier-2 and tier-3 cities in Maharashtra and Tamil Nadu expand screening infrastructure under the national blindness control program, creating procurement scale for portable fundus cameras. CDSCO regulatory harmonization with WHO prequalification standards accelerates market entry for multinational sustained-release drug delivery systems. Bengaluru and Hyderabad host diagnostic device assembly operations serving South Asian export markets.
Switzerland
Basel and Zurich anchor mammalian cell culture capacity for anti-VEGF antibody production serving European and Asian markets. Swissmedic quality-management standards align with EU MDR requirements, facilitating seamless cross-border distribution into German and French hospital networks. Geneva-based contract manufacturing facilities concentrate biologic API supply for retinal therapy segments.
Global Ophthalmology Drugs and Devices Market Key Industry Players
Concentration sits with diversified pharmaceutical conglomerates and specialized ophthalmic device manufacturers that span biologic drug development, surgical platform engineering, and diagnostic imaging systems. The competitive structure tiers across three archetypes: integrated pharmaceutical-device hybrids, pure-play surgical instrument specialists, and biologic-focused retinal therapy developers. Strategic moves center on sustained-release implant portfolio expansion and AI-integrated diagnostic platform commercialization.
Within the integrated pharmaceutical tier, Novartis AG and Alcon Vision LLC occupy positions that span sustained-release drug delivery and surgical platform manufacturing. Regeneron Pharmaceuticals Inc. exemplifies the biologic-focused archetype through antibody engineering depth in anti-VEGF development. These three entities anchor competitive dynamics across retinal therapy, cataract surgery, and diagnostic imaging segments without exclusive territorial claims.
| Leading Market Players |
|---|
| Novartis AG |
| Alcon Vision LLC |
| Regeneron Pharmaceuticals Inc. |
| Abbott Laboratories |
| Allergan PLC by AbbVie Inc. |
| F. Hoffmann-La Roche Ltd. |
| Bausch + Lomb |
| Santen Pharmaceutical Co., Ltd. |
| Bayer AG |
| Others |
Cost & Logistics Intelligence
Silicone hydrogel material substitution for conventional hydrogel platforms redraws procurement geography toward East Asian polymer synthesis corridors while compressing replacement-schedule premiumization timelines in optical retail channels. This input transition simultaneously elevates raw material concentration risk and intensifies price competition at the standard-tier contact lens segment.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in surgical consumables and diagnostic platforms. Price differentiation hinges on FDA breakthrough designation status and volume scale commitments from United States specialty eye hospital networks. Pricing pressure stems from group purchasing organization unbundling of surgical pack components in southeastern states. Independent ophthalmology clinics in Germany exhibit highest price sensitivity due to statutory insurance reimbursement ceilings, while academic medical centers show lowest sensitivity given research funding offsets.
Supply Chain Analysis
Switzerland and Ireland anchor mammalian cell culture capacity for anti-VEGF antibody production serving retinal therapy segments worldwide. Biologic API manufacturing draws from Swiss contract manufacturing facilities and Irish fill-finish operations, with optical componentry sourcing from Japanese precision optics clusters in Nagoya. Single-source vulnerability concentrates in femtosecond laser source manufacturing. Distribution runs through consolidated specialty eye hospital networks and group purchasing organizations in the United States, supplemented by statutory hospital procurement frameworks in Germany and PMDA-designated distribution channels in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Ophthalmology Drugs and Devices Market sits at an early-cycle expansion phase where sustained-release implant adoption and AI-integrated diagnostic penetration create asymmetric returns for first movers.
For Market Incumbents: Secure captive supply of biologic API capacity through backward integration into mammalian cell culture facilities in Swiss and Irish manufacturing corridors. Fortify positions in retinal therapy segments against gene therapy vector substitution by accelerating sustained-release implant pipeline advancement and locking in exclusive hospital system partnerships across Tokyo-Osaka and Florida-Texas corridors.
For New Entrants and Emerging Players: Lead with tele-ophthalmology screening networks targeting tier-2 and tier-3 Indian cities under the national blindness control program, where portable fundus camera procurement scale outpaces established vendor presence. Capture white-space in home-based tonometry devices for Germany's statutory insurance framework, deploying direct-to-clinic sales models that bypass capital equipment vendor incumbency.
For Investors and Strategic Acquirers: The market sits at a platform consolidation phase that favors vertically integrated surgical device manufacturers with diagnostic imaging software capabilities. Long-term viability over the next decade rests on convergence of drug delivery and surgical platform ecosystems. Target acquisition archetypes include mid-scale OCT angiography developers with FDA breakthrough designation progress and gene therapy vector manufacturing specialists serving inherited retinal disease segments. Watch PMDA reliance pathway harmonization with FDA determinations as the signal for accelerated multinational manufacturing investment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation Pursuit | Compresses premarket review timelines for AI-integrated OCT angiography platforms in Palo Alto development clusters. |
| Sustained-Release Implant Manufacturing Scale-Up | Captures biannual injection protocol economics in retinal therapy segments across United States specialty eye hospitals. |
| Gene Therapy Vector Manufacturing Partnership | Opens inherited retinal disease segments previously unreachable by small-molecule or biologic approaches in Boston and Heidelberg. |
| Tele-Ophthalmology Platform Integration | Creates procurement scale for portable fundus cameras in India's tier-2 and tier-3 city screening networks. |
| Home-Based Tonometry Regulatory Clearance | Displaces clinic-dependent glaucoma management within Germany's statutory insurance reimbursement framework. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, PMDA approval summaries, ClinicalTrials.gov entries, and hospital procurement databases. Primary interviews engaged drug development executives at sustained-release implant manufacturers, regulatory affairs leads navigating EU MDR post-market surveillance obligations, formulary directors at United States specialty eye hospital networks, and GPO contracts managers in southeastern states. Secondary validation drew from SEC 10-K disclosures, Swissmedic quality-management filings, and CMS Medicare reimbursement data. Bottom-up demand modeling triangulated against top-down market sizing across therapeutic modality and technology platform dimensions.
Segmentation dimensions modeled include product type, therapy area, end user archetype, and technology platform across the projection horizon. CAGRs were derived from regression analysis of historical procedure volumes, pricing trajectories, and penetration rates by segment. Forecast inputs incorporated PMDA reliance pathway adoption curves, EU MDR transition timelines for diagnostic device reclassification, and silicone hydrogel material substitution elasticities in contact lens replacement schedules.
Forecasts assume regulatory continuity in FDA breakthrough designation pathways, EU MDR enforcement patterns, and PMDA reliance harmonization protocols; material policy shifts would require re-modeling. Specific risks include biologic API supply disruption from Swiss and Irish manufacturing concentration, femtosecond laser platform capital expenditure cyclicality, and vitreoretinal surgeon training pipeline bottlenecks constraining sustained-release implant administration capacity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Head Band Ophthalmoscopes Market
Ophthalmology
Global Therapeutic Lenses Market
Ophthalmology
Retinal Detachment Diagnostic Market
Ophthalmology
Ophthalmic Eye Shield Market
Ophthalmology
Usher Syndrome Market
Ophthalmology
Ophthalmic Clinical Trials Market
Ophthalmology
Europe Primary Angle-Closure Glaucoma Market
Ophthalmology
Vernal Keratoconjunctivitis Market
Ophthalmology
Ocular Pain Market
Ophthalmology
Astigmatism Market
Ophthalmology
Conjunctivitis Treatment Market
Ophthalmology
Global Hemianopsia Market
Ophthalmology
Extended and Continuous Wear Lenses Market
Ophthalmology
India Ophthalmic Clinical Trials Market
Ophthalmology
Ischemic Optic Neuropathy Treatment Market
Ophthalmology
Ophthalmic Lasers Market