
 Retinal Detachment Diagnostic Market | 2026-2036
Retinal Detachment Diagnostic Market Size, Share, and Industry Trends Forecast 2026-2036
Retinal Detachment Diagnostic Market Analytics
Market Context
A widening capability gap in R&D scale is bifurcating competitive positioning across the retinal detachment diagnostic landscape. Carl Zeiss Meditec AG leverages its integrated optics manufacturing base to dominate premium OCT system supply. Canon Medical Systems Corporation anchors its position through hospital network partnerships spanning multiple continents. Eyenuk Inc. differentiates via AI-enabled screening platforms that extend diagnostic access beyond specialist centers.
Technical Definition and Segments
Retinal detachment diagnostics encompass imaging and functional assessment technologies that detect separation of the neurosensory retina from the underlying retinal pigment epithelium, typically employing resolutions below 10 micrometers for cross-sectional tissue visualization. These systems serve the critical clinical purpose of enabling time-sensitive surgical intervention before macula-off progression causes irreversible vision loss. Optical coherence tomography leads product type revenue due to its established reimbursement and diagnostic specificity for subclinical detachments, while telemedicine delivery mode represents the fastest-expanding access channel as asynchronous image interpretation reduces specialist bottlenecks. Fluorescein angiography technology retains entrenched utility in vascular complication assessment despite competition from non-contrast alternatives.
Regulatory and Strategic Outlook
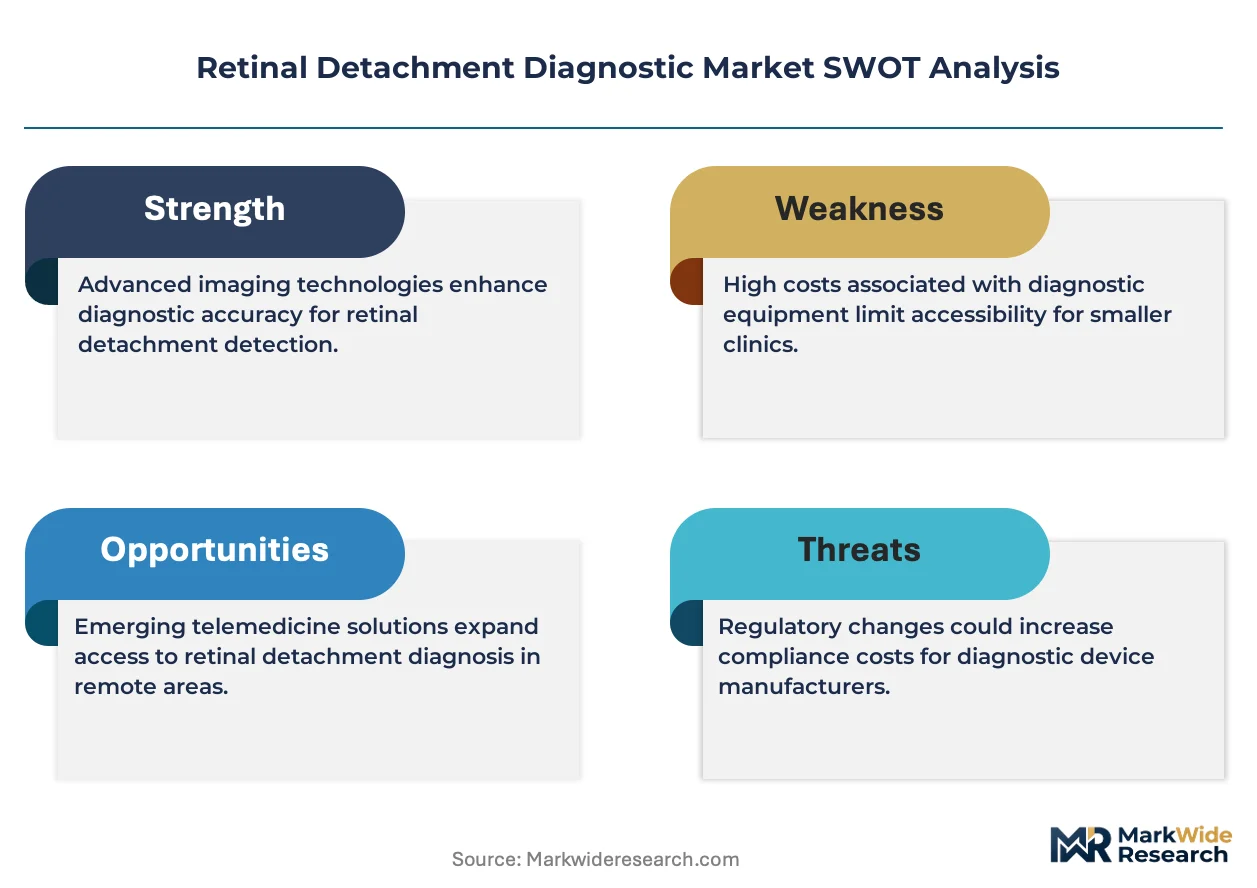
The FDA breakthrough device program and CE marking under the EU Medical Device Regulation shape product development timelines and market access requirements for manufacturers seeking multi-jurisdictional commercialization. ISO 13485 quality management standards and HIPAA privacy frameworks further constrain system design and data handling protocols across the United States and European markets. Stakeholders must monitor evolving AI diagnostic performance validation requirements as software-as-a-medical-device classifications proliferate.
Market Dynamics
The FDA breakthrough device designation pathway compresses commercialization timelines for AI-enabled retinal diagnostics, while hospital procurement consolidation concentrates purchasing power among integrated delivery networks. This dual pressure reshapes how manufacturers prioritize R&D investment and channel strategy.
Growth Catalysts
- Breakthrough Device Pathway:FDA's accelerated review mechanism reduces time-to-market for novel OCT algorithms and AI screening platforms. Manufacturers gain competitive advantage through earlier revenue recognition.
- Telemedicine Infrastructure:Asynchronous image interpretation protocols expand diagnostic access beyond metropolitan specialist centers. Rural and underserved populations gain screening coverage without physical referral.
- Diabetic Retinopathy Screening Mandates:CMS reimbursement policies for annual diabetic eye exams sustain volume demand across primary care integration points. Payers recognize cost savings from early intervention.
Market Restraints
- Capital Equipment Concentration:Premium OCT system manufacturing concentrates among German and Japanese optical conglomerates. Supply vulnerability emerges from single-source laser component dependencies.
- Specialist Workforce Scarcity:Fellowship-trained vitreoretinal surgeons remain concentrated in academic medical centers. Geographic maldistribution limits diagnostic interpretation capacity regardless of imaging availability.
- Reimbursement Compression:CMS physician fee schedule adjustments constrain margins for fluorescein angiography procedures. Hospital outpatient departments face site-of-service payment differentials.
Strategic Opportunities
- India Screening Expansion:CDSCO streamlined medical device registration opens pathways for handheld fundus camera deployment. Public-private partnerships target diabetic population screening at scale.
- AI Software-as-Medical-Device:Cloud-based diagnostic algorithms bypass hardware replacement cycles. Recurring revenue models displace capital-intensive equipment sales.
- EU AI Act Compliance:Conformity assessment frameworks for high-risk medical AI create first-mover advantage for validated retinal screening algorithms. CE marking under MDR Annex XVI extends addressable market.
Industry Challenges
- Interoperability Friction:DICOM standard implementation varies across PACS vendors. Image transfer failures between acquisition devices and cloud platforms delay diagnostic workflows.
- Validation Dataset Requirements:FDA demands for multi-site, demographically diverse training cohorts extend premarket submission preparation. Smaller developers face capital constraints for prospective clinical studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retinal Detachment Diagnostic Market |
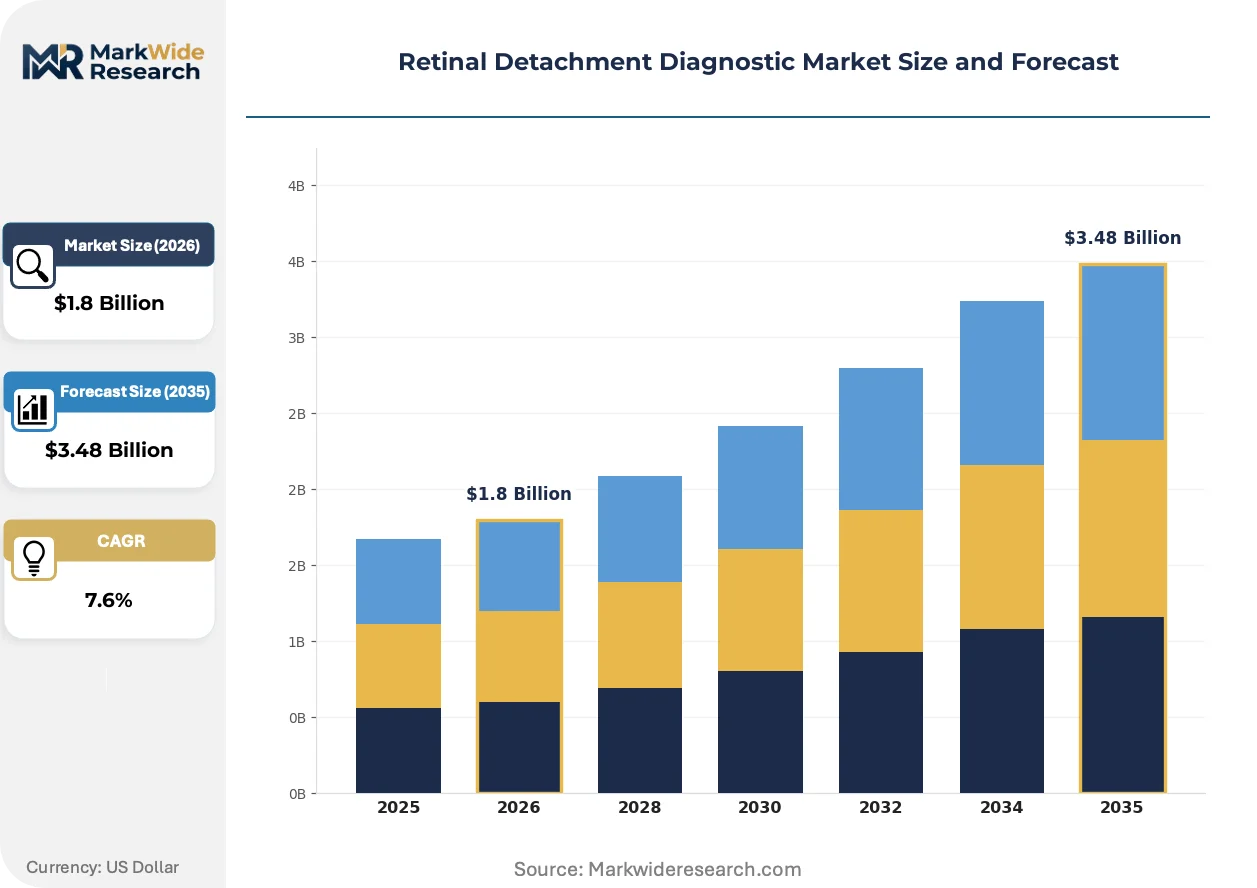
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: OCT, Fundus Camera, Ultrasound, Retinal Peripheral Devices Delivery Mode: In-Hospital, Outpatient Clinic, Home Care, Telemedicine End User: Ophthalmologists, Hospitals, Diagnostic Labs, Research Institutions Technology: Fluorescein Angiography, Optical Coherence Tomography, B-scan Ultrasound, Fundus Autofluorescence |
| Companies Covered | Canon Medical Systems Corporation, Carl Zeiss Meditec AG, Centervue SpA, Essilor International, Eyenuk Inc., HealPros LLC, Millennium Surgical Corp., ONL Therapeutics, Peek Vision Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retinal Detachment Diagnostic Market Evolving Landscape
Portable imaging hardware and cloud-native diagnostic algorithms are compressing the physical and temporal distance between image acquisition and specialist interpretation. These shifts enable point-of-care screening models that bypass traditional referral bottlenecks.
Handheld OCT systems are miniaturizing spectral-domain technology into battery-operated devices weighing under 500 grams. Community health centers and primary care clinics adopt these units for same-day screening decisions. The form factor reduction is miniaturizing the economic barrier to decentralized diagnostic access, enabling screening programs in mobile clinics and nursing facilities previously excluded from specialist proximity.
EU Medical Device Regulation Annex XVI expansions reclassify software-only diagnostic products as Class IIa or higher medical devices. Manufacturers face notified body conformity assessment for algorithms previously self-certified. Retinal screening AI platforms targeting European deployment accelerate clinical validation studies to meet 2026 transition deadlines.
Hospital purchasing committees now unbundle equipment acquisition from service contracts and software subscriptions. Integrated delivery networks negotiate multi-vendor maintenance agreements separately from capital purchases. This disaggregation is most visible in United States academic medical centers, where procurement teams centralize service spend across ophthalmology, radiology, and pathology imaging fleets.
Retinal Detachment Diagnostic Market Segmentation
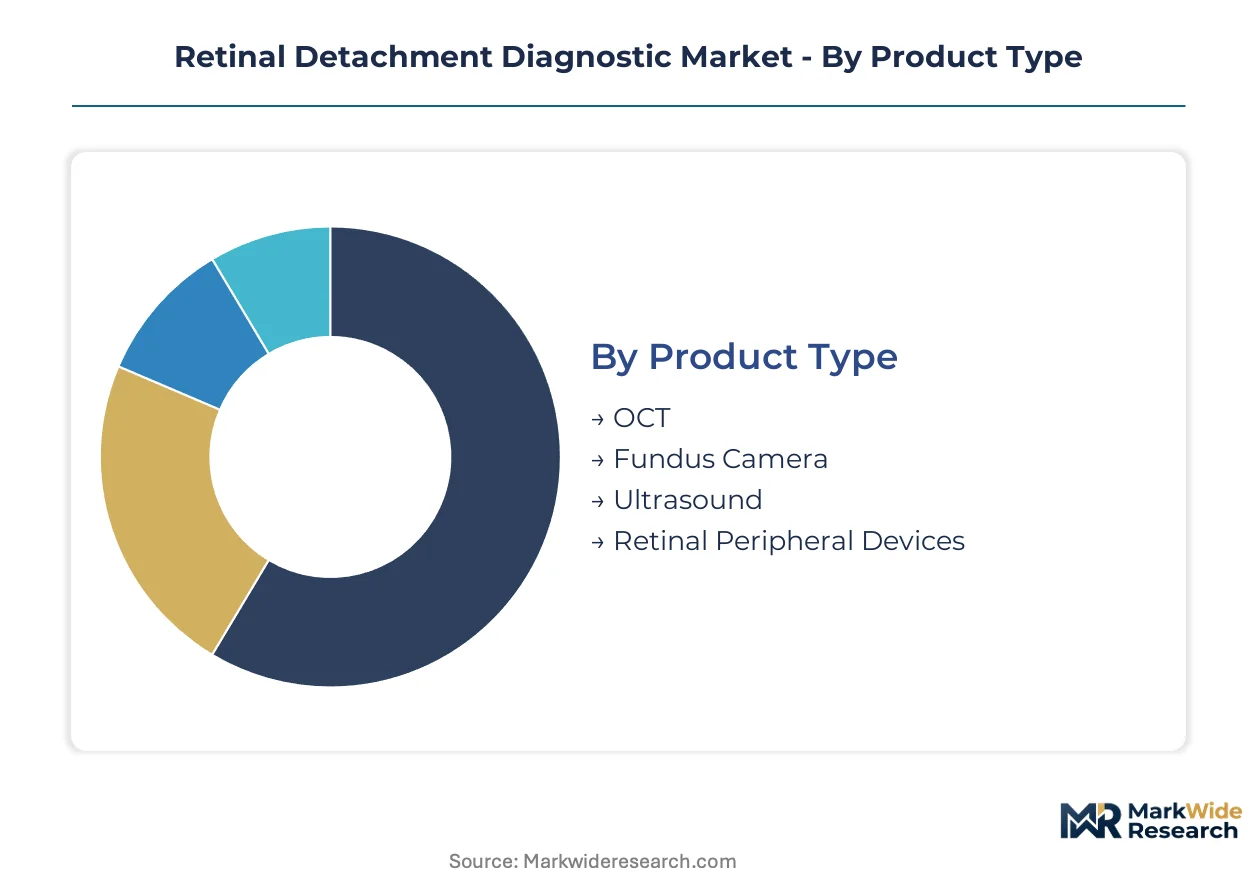
Retinal detachment diagnostics fragment across hardware platforms, care delivery settings, and user competencies. Each segmentation axis reveals distinct procurement patterns and reimbursement pathways that shape manufacturer strategy.
Product Type:
Domestic hospital procurement concentrates on high-resolution imaging systems, while export demand from emerging markets favors portable units for decentralized screening networks.
- OCT:Spectral-domain systems achieve sub-10 micrometer resolution for cross-sectional retinal visualization. United States academic medical centers drive replacement demand as reimbursement codes stabilize for anterior segment extensions.
- Fundus Camera:Non-mydriatic digital imaging systems capture wide-field retinal photography without pharmacologic dilation. Indian public health programs deploy handheld variants through CDSCO-registered distribution channels for diabetic retinopathy screening at scale.
- Ultrasound:B-mode acoustic imaging penetrates opaque media when optical methods fail.
- Retinal Peripheral Devices:Scleral depression accessories and indirect ophthalmoscopy lenses enable dynamic examination of the ora serrata.
OCT holds the largest share; momentum sits with fundus camera systems gaining share fastest through primary care integration.
Delivery Mode:
Cost tier stratification separates capital-intensive hospital installations from subscription-based remote interpretation services.
- In-Hospital:Integrated surgical suites combine diagnostic imaging with same-day vitrectomy capabilities. United States integrated delivery networks consolidate purchasing across ophthalmology and radiology departments to extract volume discounts.
- Outpatient Clinic:Standalone ophthalmology practices deploy compact OCT systems with cloud connectivity. Reimbursement site-of-service differentials constrain margin recovery for fluorescein angiography procedures.
- Home Care:Patient-operated fundus cameras transmit images for asynchronous specialist review.
- Telemedicine:Store-and-forward protocols bypass geographic specialist scarcity through HIPAA-compliant image exchange.
In-hospital delivery commands premium pricing; telemedicine infrastructure is expanding most quickly through CMS-supported diabetic screening mandates.
End User:
Customer type determines equipment specification complexity and service contract intensity.
- Ophthalmologists:Fellowship-trained vitreoretinal specialists demand spectral-domain OCT with angiography modules. Private practice groups in the United States negotiate multi-year service agreements separate from capital purchases.
- Hospitals:Academic medical centers require research-grade imaging with DICOM integration across PACS networks. Procurement committees unbundle hardware from software subscriptions to optimize total cost of ownership.
- Diagnostic Labs:Centralized interpretation services process outsourced fundus images from primary care sites.
- Research Institutions:NIH-funded clinical trials drive demand for adaptive optics OCT with cellular-resolution capabilities.
Hospitals represent the dominant installed base; diagnostic labs are climbing the fastest as payers consolidate interpretation services.
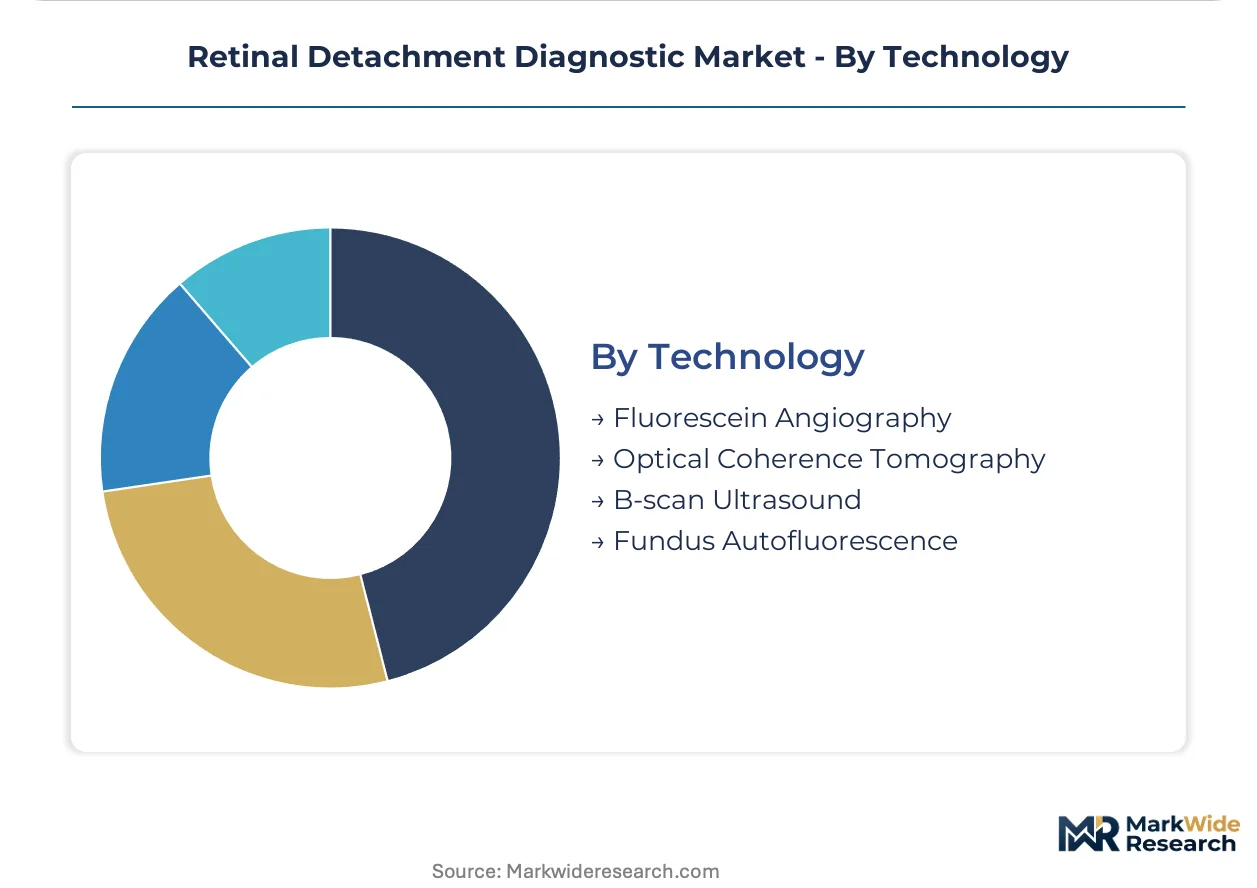
Technology:
Application maturity separates established contrast-dependent methods from non-invasive alternatives displacing them.
- Fluorescein Angiography:Intravenous sodium fluorescein dye enables dynamic vascular perfusion assessment. CMS reimbursement compression and anaphylaxis risk drive substitution toward non-contrast alternatives in United States outpatient settings.
- Optical Coherence Tomography:Interferometric depth-resolved imaging dominates macular pathology quantification. FDA breakthrough device designations accelerate commercialization for AI-enhanced segmentation algorithms.
- B-scan Ultrasound:Acoustic through-media imaging serves pre-surgical planning in dense cataract or vitreous hemorrhage.
- Fundus Autofluorescence:Lipofuscin excitation mapping reveals retinal pigment epithelium metabolic stress without exogenous dye.
Optical coherence tomography retains the dominant technology position; fundus autofluorescence is gaining share fastest through its non-contrast safety profile.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Germany while India and Brazil compete on access-cost efficiency. This asymmetry shapes where manufacturers deploy premium systems versus portable alternatives.
United States
Aging demographics and diabetic retinopathy prevalence sustain screening volumes across integrated delivery networks. FDA breakthrough device designations accelerate commercialization timelines for AI-enabled diagnostics. Academic medical centers in Boston and the San Francisco Bay Area drive adoption of research-grade OCT with cellular-resolution capabilities.
Germany
Carl Zeiss Meditec AG anchors premium OCT manufacturing through integrated optics production in Oberkochen. CE marking under EU Medical Device Regulation shapes product development timelines for multi-jurisdictional commercialization. The Munich-Stuttgart medical technology corridor concentrates R&D investment in spectral-domain imaging innovations.
Japan
Canon Medical Systems Corporation leverages hospital network partnerships spanning multiple continents from its domestic base. PMDA regulatory pathways align with FDA breakthrough mechanisms for synchronized market entry. Tokyo-Osaka metropolitan clusters concentrate fellowship-trained vitreoretinal specialists and diagnostic interpretation capacity.
India
CDSCO streamlined medical device registration opens pathways for handheld fundus camera deployment in public health programs. Public-private partnerships target diabetic population screening at scale. Maharashtra and Karnataka states concentrate manufacturing partnerships for cost-optimized imaging hardware serving South Asian markets.
United Kingdom
NHS diabetic eye screening mandates sustain volume demand through primary care integration points. MHRA post-Brexit regulatory frameworks diverge from EU MDR timelines, creating separate conformity assessment requirements. London and Manchester academic centers drive telemedicine infrastructure for asynchronous image interpretation.
Retinal Detachment Diagnostic Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the retinal detachment diagnostic landscape. Premium OCT system manufacturing concentrates among German and Japanese optical conglomerates with captive laser component supply. Three archetypes dominate: integrated optics conglomerates controlling upstream manufacturing, AI-native software vendors bypassing hardware cycles, and portable device specialists targeting decentralized screening networks. Competitive moves center on M&A for imaging algorithm portfolios and strategic partnerships with integrated delivery networks for multi-year service contracts.
Among integrated optics manufacturers, Carl Zeiss Meditec AG and Canon Medical Systems Corporation exemplify the premium-system archetype through their respective German and Japanese manufacturing bases. Eyenuk Inc. occupies a distinct position representing AI-native software vendors that extend diagnostic access beyond specialist centers through cloud-based screening platforms.
| Leading Market Players |
|---|
| Canon Medical Systems Corporation |
| Carl Zeiss Meditec AG |
| Centervue SpA |
| Essilor International |
| Eyenuk Inc. |
| HealPros LLC |
| Millennium Surgical Corp. |
| ONL Therapeutics |
| Peek Vision Ltd |
| Others |
Value Network & Pricing Analysis
Long-term service contracts between integrated delivery networks and OCT manufacturers lock in multi-year pricing visibility while securing priority component allocation. This arrangement binds hospital procurement committees to predictable maintenance spend and shields manufacturers from spot-market volatility in laser source supply.
Pricing Analysis
The customization-premium spread separates research-grade spectral-domain systems with angiography modules from standard diagnostic configurations. Subscription-based SaaS pricing for AI screening algorithms displaces capital-intensive equipment sales, compressing upfront revenue while extending recurring income streams. Price differentiation hinges on FDA breakthrough device designation status and ISO 13485 certification tier. Hospital outpatient departments exhibit acute price sensitivity due to CMS site-of-service payment differentials, whereas academic medical centers absorb premium pricing for cellular-resolution capabilities.
Supply Chain Analysis
Inventory lead times for superluminescent diode arrays stretch to six months, forcing manufacturers into advance purchase commitments. Laser component manufacturing concentrates in Germany and Japan, with final system assembly distributed across United States and Chinese facilities. German optical glass and Japanese precision motors constitute critical input dependencies. Single-source vulnerability in swept-source laser supply creates exposure to export control adjustments. Distribution runs through hospital purchasing committees and GPO contracts rather than direct OEM sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face sustained substitution pressure from AI-native software vendors bypassing hardware replacement cycles through cloud-based diagnostic algorithms.
For Market Incumbents: Shield installed base revenue by unbundling hardware sales from software subscriptions to match AI-native competitor pricing flexibility. Accelerate backward integration into superluminescent diode production to reduce single-source laser dependency. Prioritize FDA breakthrough pathway submissions for AI-enhanced segmentation modules to maintain technology leadership against software-only entrants.
For New Entrants and Emerging Players: Lead with handheld fundus camera deployment targeting Indian public health programs through CDSCO-registered channels. Penetrate diagnostic lab consolidation trends by offering centralized interpretation services to United States payers seeking to reduce specialist bottleneck costs. Position cloud-native platforms as HIPAA-compliant alternatives to capital-intensive hospital installations.
For Investors and Strategic Acquirers: AI-enabled screening platforms with validated European clinical datasets represent the most defensible acquisition archetype given EU AI Act conformity deadlines. Long-term viability rests on recurring revenue model transition completion and reimbursement code stability across major markets. Monitor FDA software-as-medical-device classification volume as inflection signal for platform valuation compression.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Accelerates commercialization timelines for novel OCT algorithms ahead of standard review pathways. |
| CE Marking Under MDR Annex XVI | Opens European market access for AI screening platforms previously self-certified as lower-risk devices. |
| Hospital System Partnership | Locks in multi-year service contracts with integrated delivery networks consolidating ophthalmology spend. |
| Software Companion Development | Extends hardware utility through cloud-based diagnostic algorithms generating recurring subscription revenue. |
| Reimbursement Strategy | Secures CMS coverage determination for telemedicine screening protocols expanding addressable patient base. |
Research Methodology
Operator-level perspectives from vitreoretinal surgeons, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers anchored the qualitative base for this analysis. Primary interview insights combined with secondary validation from FDA 510(k) filings, CMS physician fee schedule archives, hospital procurement databases, and CE marking registries. Bottom-up equipment shipment tracking and top-down healthcare expenditure modeling enabled triangulation across independent estimation approaches.
Sensitivity analysis tested forecast robustness across alternative reimbursement scenarios and AI adoption curve assumptions throughout the projection horizon. Segmentation modeling spanned product type, delivery mode, end user category, and technology platform dimensions. CAGRs derived from fitted growth curves applied to validated baseline estimates, with specific inputs including diabetic retinopathy screening mandate expansion rates and fellowship-trained specialist supply constraints.
The analysis sits within stated boundaries; outcomes outside stable FDA breakthrough pathway throughput or sustained CMS telemedicine reimbursement would require recalibration. Forecasts reflect documented assumptions regarding regulatory timeline continuity and hardware-software unbundling velocity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Japan Dry Eye Syndrome Market
Ophthalmology
Europe Ophthalmology Market
Ophthalmology
Age Related Vision Dysfunction Market
Ophthalmology
Ophthalmic Viscosurgical Devices Market
Ophthalmology
Presbyopia Treatment Market
Ophthalmology
Anterior Uveitis Market
Ophthalmology
Ophthalmic Clinical Trials Market
Ophthalmology
Pediatric Vitrectomy Market
Ophthalmology
Keratitis Treatment Market
Ophthalmology
Vernal Keratoconjunctivitis Treatment Market
Ophthalmology
Global Aphakia Market
Ophthalmology
Synoptophore Market
Ophthalmology
North America Ophthalmic Devices and Drugs Market
Ophthalmology
Global Retinal Detachment Treatment Market
Ophthalmology
Trachoma Treatment Market
Ophthalmology
Uveal Melanoma Treatment Market