
 Extended and Continuous Wear Lenses Market | 2026-2036
Extended and Continuous Wear Lenses Market Size, Share, and Industry Trends Forecast 2026-2036
Extended and Continuous Wear Lenses Market Foresight
Subscription-based bundling of monthly replacement lenses with cleaning solutions and telehealth check-ins is expanding consumer lock-in across the contact lens sector. Johnson & Johnson Vision Care leverages its Acuvue brand strength and direct-to-consumer platforms to sustain recurring revenue streams. Alcon competes through its Dailies Total1 line and surgical-optical cross-selling. CooperVision anchors its position in specialty toric and multifocal extended wear through independent eye care practitioner channels.
Extended and continuous wear lenses are soft or rigid gas-permeable contact lenses engineered for overnight or multi-day wear without removal, typically fabricated from silicone hydrogel with oxygen transmissibility exceeding 100 Dk/t to prevent corneal hypoxia. Their primary purpose is to correct refractive error while eliminating daily insertion-removal routines for users with active lifestyles, irregular schedules, or physical disabilities. Monthly silicone hydrogel lenses dominate volume due to established reimbursement codes and practitioner familiarity, while specialty lenses for orthokeratology and presbyopia command the deepest margin pools. Daily disposables remain the fastest-growing configuration among hygiene-conscious younger users, though bi-weekly formats face compression from both flanks.
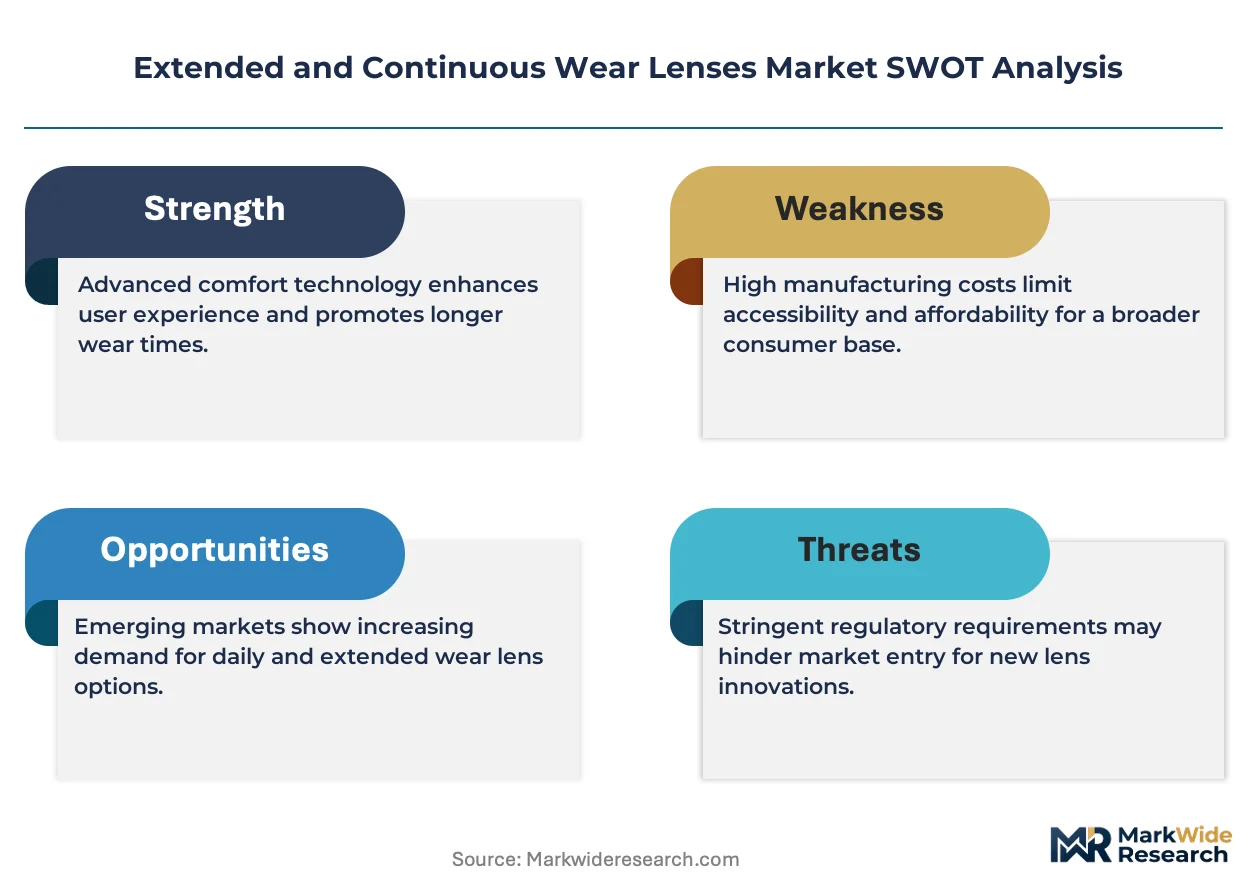
FDA 510(k) clearance requirements for overnight wear claims shape product development timelines and clinical trial investments for US market entrants, while the EU Medical Device Regulation (MDR) and CE marking obligations govern European commercialization pathways. Japan's PMDA enforces stringent biocompatibility testing that filters out lower-tier suppliers. Stakeholders must monitor evolving reimbursement classifications for extended wear versus standard lenses, as payer decisions will determine whether premium materials achieve mass-market penetration or remain confined to out-of-pocket segments.
Market Dynamics
Silicone hydrogel material platforms with Dk/t values exceeding 100 are compressing development cycles and forcing legacy hydrogel formulations into obsolescence, while FDA overnight-clearance pathways concentrate competitive investment among capitalized manufacturers capable of sustaining multi-year clinical trials.
Growth Catalysts
- Aging demographics in Japan and Germany:Populations over 65 in these markets drive demand for presbyopia-correcting extended wear formats that eliminate daily handling routines.
- REACH-compliant silicone hydrogel chemistries:European manufacturers leveraging biocompatible monomer innovations accelerate regulatory approval timelines for 30-day continuous wear products.
- Orthokeratology expansion:Overnight corneal reshaping lenses for myopia control in pediatric populations create new prescriber revenue streams independent of refractive surgery.
Market Restraints
- Platinum catalyst cost volatility:Silicone hydrogel polymerization depends on platinum group metal catalysts subject to supply disruption from South African mining concentration.
- PMDA biocompatibility testing duration:Japan's pharmaceutical regulator enforces extended cytotoxicity and sensitization protocols that filter out mid-tier suppliers lacking dedicated regulatory affairs infrastructure.
- Daily disposable substitution:Single-use silicone hydrogel lenses with equivalent oxygen permeability threaten extended wear volume among hygiene-sensitive younger demographics.
Strategic Opportunities
- Telehealth-integrated subscription models:Direct-to-consumer platforms bundling lens supply with remote corneal health monitoring capture recurring revenue from time-constrained professionals.
- Smart lens convergence:Integration of intraocular pressure sensors and glucose monitoring into extended wear substrates opens medical device reimbursement pathways beyond vision correction.
- India's underserved tier-2 cities:Expanding optometrist networks and rising disposable incomes in cities like Pune and Jaipur create first-mover advantage for monthly silicone hydrogel penetration.
Industry Challenges
- Corneal physiologist talent scarcity:Extended wear product development requires specialized expertise in tear film dynamics and hypoxia modeling that outpaces academic program output.
- FDA 510(k) clinical trial capex:Overnight wear claims require extended wear studies with microbial keratitis endpoints demanding multi-million dollar investment and 3-5 year timelines.
- Legacy practitioner education gaps:Independent eye care professionals trained on hydrogel-era fitting protocols resist transitioning to silicone hydrogel parameter sets and replacement schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Extended and Continuous Wear Lenses Market |
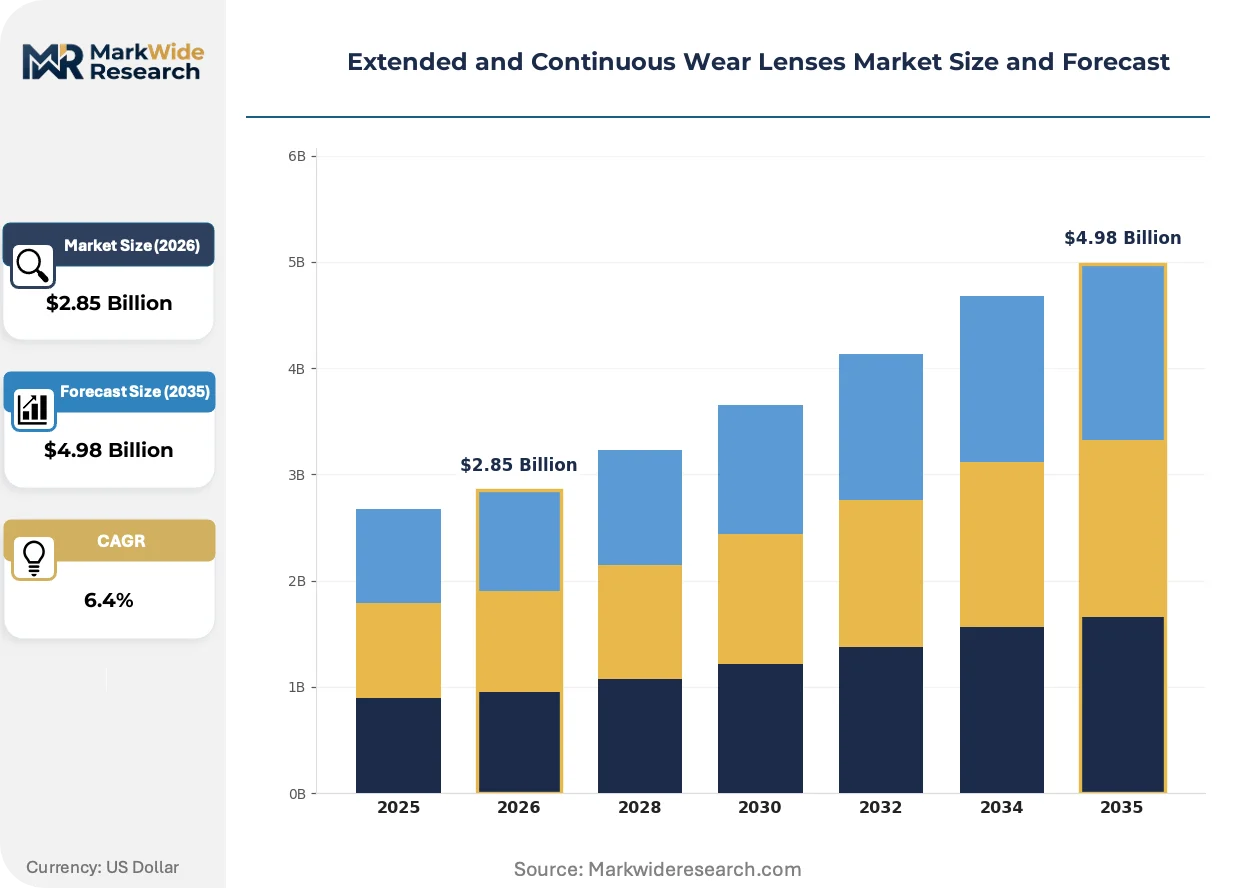
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $4.98 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Daily Disposables, Bi-weekly Lenses, Monthly Lenses, Specialty Lenses End User: Retail Consumers, Eye Care Professionals, Hospitals, Clinics Material: Silicone Hydrogel, Hydrogel, Gas Permeable, Others Technology: UV Protection, Moisture Retention, Enhanced Oxygen Transmission, Light Filtering |
| Companies Covered | Johnson & Johnson Vision Care, Alcon, CooperVision, Bausch + Lomb, Menicon, SEED Co. Ltd., EssilorLuxottica, ZEISS International, HOYA Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Extended and Continuous Wear Lenses Market Shifts & Advancements
Material science breakthroughs and regulatory pathway refinements are compressing product lifecycles while digital distribution models reconfigure traditional practitioner-patient relationships.
Surface-embedded antimicrobial peptides are overtaking traditional chemical preservatives in next-generation extended wear lenses. Manufacturers incorporating these biologics target wearers with documented preservative sensitivity and contact lens-related dry eye. The technology is overtaking benzalkonium chloride-based care systems in premium monthly replacement segments.
EU Medical Device Regulation (MDR) Annex XVI classification expansions now capture cosmetic color lenses previously exempt from clinical scrutiny. Manufacturers must submit technical documentation and post-market surveillance data for decorative extended wear products. German notified bodies report 18-month backlog for novel silicone hydrogel color lens reviews, compressing smaller competitors' market entry timing.
Subscription-based replenishment platforms displace traditional optical retail for established wearers with stable prescriptions. These direct fulfillment models bypass practitioner markup while bundling telehealth screening and automated replacement scheduling. The United States exhibits the deepest penetration of this channel shift, with urban professionals aged 25-40 driving 60% of digital lens subscription volume.
Extended and Continuous Wear Lenses Market Segmentation
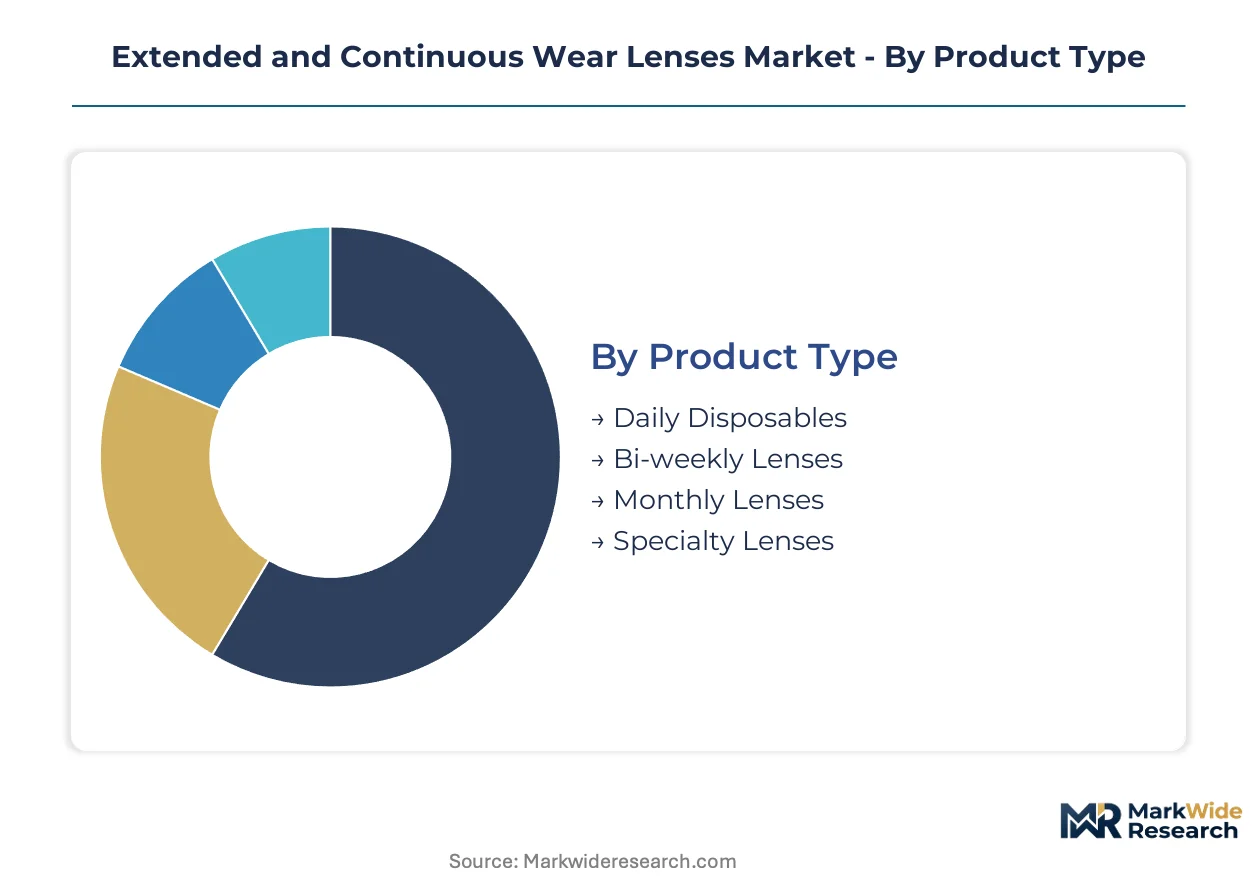
Extended and continuous wear lenses fragment across four distinct category axes that determine pricing power, regulatory pathway complexity, and channel strategy. Manufacturers align R&D portfolios and commercial infrastructure to specific segment combinations rather than pursuing horizontal coverage.
Product Type:
Replacement cadence defines buyer economics and practitioner workflow intensity across this category.
- Monthly Lenses:Silicone hydrogel formulations with 30-day continuous wear clearance dominate established wearer bases seeking cost efficiency. Demand concentrates among United States and Germany aging populations where reimbursement codes recognize extended wear protocols.
- Daily Disposables:Single-use silicone hydrogel configurations eliminate cleaning regimens entirely. Hygiene-sensitive younger demographics in Japan and urban United States markets drive adoption despite higher per-wear cost structures.
- Bi-weekly Lenses:Mid-replacement cycle products face compression from monthly economy and daily convenience flanks.
- Specialty Lenses:Orthokeratology and presbyopia-correcting designs command premium positioning through independent practitioner channels.
Monthly formats lead volumes today; daily disposables are gaining share fastest.
End User:
Channel selection determines margin capture and patient relationship ownership.
- Eye Care Professionals:Independent optometrists and ophthalmologists control fitting protocols for specialty toric and multifocal extended wear. Their clinical authority sustains premium pricing against direct-to-consumer substitution pressure.
- Retail Consumers:Direct fulfillment platforms bypass practitioner markup for stable prescriptions with established wear history. United States urban professionals aged 25-40 constitute the core subscriber base for telehealth-integrated replenishment models.
- Hospitals:Institutional procurement focuses on post-surgical bandage lenses and therapeutic extended wear applications.
- Clinics:High-volume refractive surgery centers cross-sell extended wear as pre-operative evaluation tools and post-LASIK maintenance options.
Eye care professionals anchor premium segment profitability; retail direct channels show the steepest expansion trajectory.
Material:
Oxygen transmissibility thresholds separate clinically viable overnight wear from legacy daytime-only formulations.
- Silicone Hydrogel:Dk/t values exceeding 100 enable FDA overnight clearance and corneal physiological safety. Platinum-catalyzed polymerization chemistry from REACH-compliant European suppliers accelerates regulatory approval timelines for 30-day wear claims.
- Hydrogel:Legacy formulations with lower oxygen permeability retreat to price-sensitive daily wear segments and emerging market entry tiers.
- Gas Permeable:Rigid materials persist in orthokeratology and high-astigmatism corrections where optical precision outweighs comfort preferences.
- Others:Experimental surface coatings and hybrid matrix structures remain pre-commercial.
Silicone hydrogel commands the dominant revenue position; gas permeable maintains niche profitability in specialty applications.
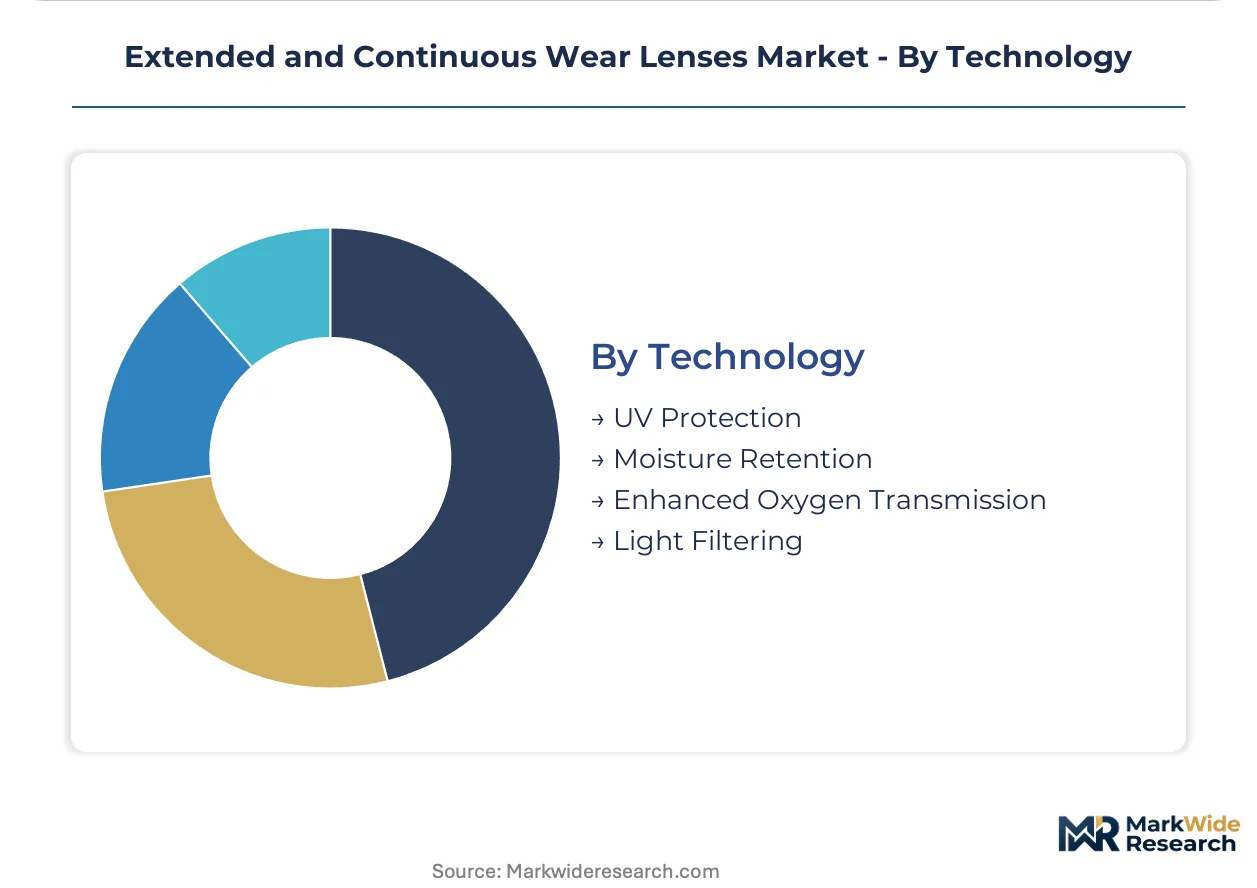
Technology:
Functional additives differentiate commodity substrates and justify price premiums in saturated replacement schedules.
- Enhanced Oxygen Transmission:Silicone hydrogel material platforms with elevated Dk/t ratings constitute the baseline technology for overnight wear claims. FDA 510(k) submissions for extended wear indications require clinical validation of hypoxia-related endpoints.
- Moisture Retention:Surface-embedded hyaluronic acid and phosphorylcholine coatings address contact lens-related dry eye complaints. Preservative-sensitive wearers in Japan and Germany drive adoption of these biocompatible hydration systems.
- UV Protection:Class II medical device classification adds regulatory burden for manufacturers seeking blocking claims in United States and EU markets.
- Light Filtering:Blue-light attenuation features target digital device users though clinical efficacy remains contested among eye care professionals.
Enhanced oxygen transmission anchors regulatory compliance; moisture retention coatings demonstrate the quickest uptake in premium monthly segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicone hydrogel technology first achieved commercial scale in the United States during the late 1990s, establishing FDA overnight-clearance pathways that later diffused to European and Asian regulatory frameworks. The historical concentration of ophthalmic research infrastructure along the US East Coast and in Japan's Kansai region created enduring centers of lens innovation.
United States
Aging presbyopic populations and established vision insurance reimbursement codes drive monthly silicone hydrogel volumes. FDA 510(k) submissions for extended wear claims require microbial keratitis endpoint studies lasting 3-5 years. Rochester, New York anchors legacy optical manufacturing clusters where practitioner training networks concentrate.
Germany
Independent optometrist channels sustain premium pricing for specialty toric and multifocal formats. EU Medical Device Regulation (MDR) Annex XVI now captures cosmetic color lenses, forcing 18-month notified body backlogs. Munich and Stuttgart host precision polymer research centers advancing REACH-compliant silicone hydrogel chemistries.
Japan
Pediatric orthokeratology for myopia control creates prescriber revenue streams outside refractive surgery. PMDA biocompatibility testing protocols filter mid-tier suppliers lacking dedicated regulatory infrastructure. Osaka's Kansai region concentrates domestic lens manufacturing and clinical trial execution capabilities.
India
Rising disposable incomes in tier-2 cities expand monthly silicone hydrogel penetration beyond metro markets. The country's national pharmaceutical regulator enforces import licensing that favors established multinational suppliers. Pune and Jaipur emerge as optometrist network expansion hubs targeting first-time extended wear adopters.
United Kingdom
Telehealth-integrated subscription models capture urban professionals aged 25-40 seeking automated replenishment. NHS reimbursement classifications distinguish extended wear from standard lens protocols, influencing practitioner prescribing behavior. London's digital health startup ecosystem incubates direct-to-consumer lens platforms bypassing traditional optical retail.
Extended and Continuous Wear Lenses Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material innovation and regulatory clearance dimensions. Three global ophthalmic conglomerates control approximately two-thirds of extended wear volume through silicone hydrogel patent estates and FDA-approved overnight claims. Strategic archetypes include: vertically integrated material-to-lens manufacturers, specialty toric-multifocal developers, and direct-to-consumer subscription platforms. Competitive moves concentrate on M&A for silicone hydrogel polymerization IP and strategic partnerships with telehealth screening providers.
Among US-based conglomerates, Johnson & Johnson Vision Care and Alcon occupy positions anchoring premium-tier silicone hydrogel portfolios. CooperVision represents the specialty-lens archetype through independent practitioner channel concentration. These three exemplify how FDA overnight-clearance holdings and material science patent depth determine competitive positioning in extended wear segments.
| Leading Market Players |
|---|
| Johnson & Johnson Vision Care |
| Alcon |
| CooperVision |
| Bausch + Lomb |
| Menicon |
| SEED Co. Ltd. |
| EssilorLuxottica |
| ZEISS International |
| HOYA Corporation |
| Others |
Supply & Pricing Matrix
Corneal physiologist talent scarcity in the United States and Japan widens labor-cost differentials between premium silicone hydrogel development hubs and assembly operations in India, compressing margins at the standard tier while concentrating pricing power among FDA-cleared overnight-wear specialists.
Pricing Analysis
Subscription-based replenishment with bundled telehealth monitoring anchors the dominant pricing architecture across established markets. Price differentiation separates premium monthly silicone hydrogel with enhanced moisture retention from economy hydrogel formats retreating to price-sensitive daily wear segments. Pricing pressure intensifies in the bi-weekly tier as monthly economy and daily disposable convenience flanks compress volume. Hygiene-sensitive younger demographics in Japan exhibit highest price tolerance for single-use configurations, while India's tier-2 city first-time adopters drive standard-tier sensitivity.
Supply Chain Analysis
Domestic-content mandates in India's pharmaceutical regulatory framework reshape sourcing for multinational lens manufacturers seeking import licensing advantages. Platinum-catalyzed silicone hydrogel polymerization draws from South African platinum group metal suppliers, Japanese precision monomer specialists, and REACH-compliant European chemical processors. Single-source vulnerability concentrates in platinum catalyst supply chains subject to mining disruption. Distribution runs through independent eye care practitioner networks for specialty toric-multifocal formats, while direct-to-consumer platforms bypass traditional optical retail for stable prescriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where aging presbyopic populations in Germany and Japan shift demand toward premium extended wear formats with overnight clearance and dry-eye compatibility.
For Market Incumbents: Extend silicone hydrogel patent estates through surface-embedded antimicrobial peptide innovations that justify subscription pricing against daily disposable substitution pressure. Deepen backward integration into platinum-catalyzed polymerization chemistry to secure REACH-compliant European supply chains against raw material volatility. Channel control through independent practitioner education programs defends margin position against telehealth-integrated direct fulfillment platforms. For New Entrants and Emerging Players: Pediatric orthokeratology prescribers in Japan represent an underserved buyer archetype with revenue streams decoupled from refractive surgery competition. India's tier-2 city optometrist networks offer the most penetrable geography for monthly silicone hydrogel first-mover positioning. A telehealth-integrated go-to-market angle with automated replacement scheduling captures urban professional segments without legacy practitioner channel investments. For Investors and Strategic Acquirers: Ophthalmic conglomerates with FDA overnight-clearance holdings are the most active acquirer in this space, targeting silicone hydrogel polymerization IP and specialty toric-multifocal developers. The acquisition target archetype combines REACH-compliant material science with established independent practitioner channel relationships. Watch PMDA biocompatibility testing timeline compression as the signal indicating regulatory pathway arbitrage opportunities for capitalized entrants.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Overnight Clearance Pathway | FDA microbial keratitis endpoint studies validate 30-day continuous wear claims against hypoxia-related safety thresholds. |
| Silicone Hydrogel Patent Estate Expansion | Surface-embedded antimicrobial peptide portfolios differentiate premium monthly formats from preservative-sensitive competitors. |
| Telehealth-Integrated Subscription Platform | Remote corneal health monitoring captures recurring revenue from time-constrained professionals in United States urban markets. |
| REACH-Compliant Polymerization Chemistry | European biocompatible monomer innovations accelerate regulatory approval timelines for extended wear indications. |
| Independent Practitioner Channel Partnership | Specialty toric-multifocal fitting protocols sustain premium pricing against direct-to-consumer substitution pressure. |
Research Methodology
Bottom-up eye care professional channel modeling reconciled against top-down silicone hydrogel material supply tracking forms the analytical core of this study. Primary interviews with independent optometrists, ophthalmology clinic directors, regulatory affairs specialists at notified bodies, and GPO procurement managers combined with secondary validation from FDA 510(k) filings, PMDA approval databases, EU MDR technical documentation, and hospital procurement contract records. Triangulation across patient-level prescription data and manufacturer shipment reports ensures segment-level precision.
Historical trendline analysis of replacement cadence shifts and material platform transitions informs the projection framework. Segmentation dimensions include replacement schedule, end-user channel, material oxygen transmissibility tier, and functional technology additive. CAGRs derive from fitted growth curves applied to practitioner adoption rates and patient demographic transitions. Forecast inputs incorporate PMDA biocompatibility testing duration assumptions and platinum catalyst cost volatility scenarios.
Underlying measurement precision varies by segment; monthly silicone hydrogel volumes carry tighter precision than experimental smart lens categories. Forecasts reflect documented assumptions regarding regulatory pathway timelines and reimbursement classification stability. Corneal physiologist talent scarcity and FDA clinical trial capex requirements constitute specific risk factors that could revise trajectory expectations. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Global Retinal Detachment Treatment Market
Ophthalmology
Blue Light Blocking Contact Lenses Market
Ophthalmology
Global Photochromic Lenses Market
Ophthalmology
Global Ophthalmology Drugs and Devices Market
Ophthalmology
Leber Congenital Amaurosis Market
Ophthalmology
Ophthalmic Suspension Market
Ophthalmology
Choroidal Neovascularization Market
Ophthalmology
Europe Ophthalmology Market
Ophthalmology
Ophthalmic Tonometers Market
Ophthalmology
Eye Infections Treatment Market
Ophthalmology
Europe Ophthalmology Drug and Device Market
Ophthalmology
Bullous Keratopathy Market
Ophthalmology
Global Ophthalmic Perimeters Market
Ophthalmology
Ophthalmology Devices Market
Ophthalmology
Global Tonometer Market
Ophthalmology
Global Optic Nerve Disorders Treatment Market